
 Clinical Laboratory Tests Market | 2026-2036
Clinical Laboratory Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Laboratory Tests Market Intelligence
Project finance for regional laboratory networks is reconfiguring capital deployment across the clinical testing landscape. Quest Diagnostics Incorporated leverages its national logistics infrastructure to sustain specimen throughput advantages. Laboratory Corporation of America anchors its competitiveness through in-house esoteric test development. Siemens Healthineers differentiates via integrated analyzer-to-informatics platforms that tighten workflow control.
Clinical laboratory tests comprise analytical procedures performed on biological specimens to detect disease markers, therapeutic drug levels, or physiological status, typically requiring controlled temperature handling, certified reagent lots, and turnaround windows under 24 hours for stat orders. Their primary purpose is informing clinical decision-making across diagnosis, treatment monitoring, and preventive screening. Molecular diagnostics represents the fastest-expanding test type as precision medicine protocols penetrate oncology and infectious disease workflows. Automated analyzers still occupy the dominant technology position by installed base, though point-of-care testing is capturing margin pools in emergency and perioperative settings where speed commands premium pricing.
The FDA maintains evolving jurisdiction over laboratory-developed tests while the Centers for Medicare and Medicaid Services governs reimbursement through the Clinical Laboratory Fee Schedule, creating dual compliance pressure on operational economics. ISO 15189 accreditation requirements from the College of American Pathologists shape quality benchmarks that determine institutional purchasing criteria. Stakeholders must monitor how reimbursement compression interacts with capital-intensive automation decisions to determine sustainable service line expansion.
Market Dynamics
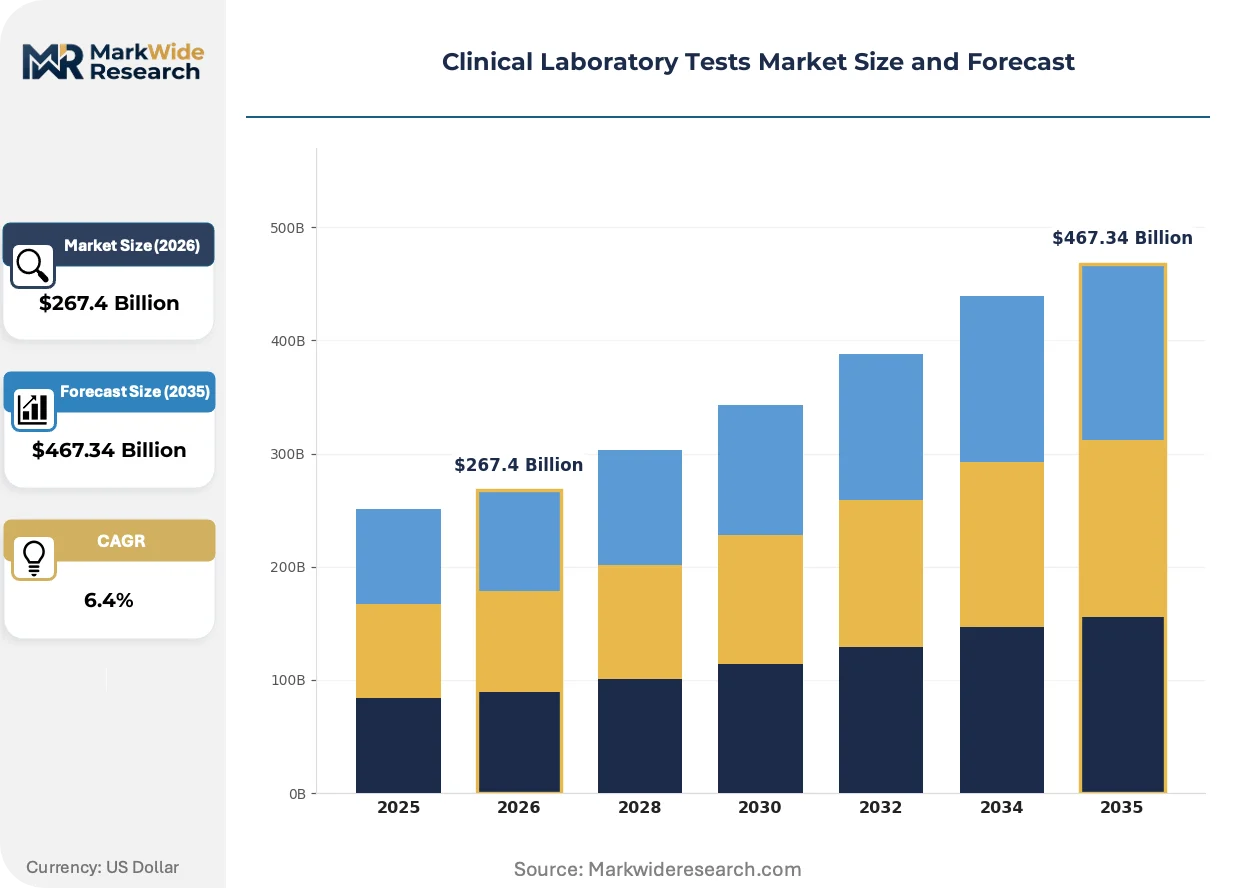
Reimbursement compression from the Clinical Laboratory Fee Schedule is forcing laboratories to restructure cost models while molecular diagnostics capabilities expand test complexity. This tension between declining unit economics and rising technical sophistication defines current strategic positioning.
Growth Catalysts
- Precision medicine protocols:Oncology and infectious disease workflows now mandate companion diagnostic testing, pulling molecular assays into standard care pathways and expanding reimbursable indications.
- CLIA certification expansion:The Centers for Medicare and Medicaid Services continues approving high-complexity laboratory licenses, enabling hospital systems to bring esoteric testing in-house rather than outsourcing.
- Point-of-care testing platforms:Emergency departments and perioperative suites now deploy cartridge-based analyzers that deliver results within minutes, capturing volume previously routed to central laboratories.
Market Restraints
- Reagent supply concentration:Three manufacturers control over 60 percent of immunoassay reagent production, creating vulnerability to lot-to-lot variability and force majeure disruptions.
- FDA LDT oversight uncertainty:Proposed rulemaking for laboratory-developed test premarket review threatens validation timelines and retrospective compliance costs for existing assays.
- Phlebotomy workforce constraints:Certified specimen collection personnel shortages in rural United States counties limit network expansion regardless of capital availability.
Strategic Opportunities
- India's diagnostic network gaps:Tier-2 and Tier-3 cities remain underserved by organized laboratory chains, creating whitespace for hub-and-spoke collection center models.
- AI-augmented pathology:Machine learning algorithms trained on digital slide archives are collapsing diagnostic turnaround times for histopathology, enabling same-day reporting in cancer centers.
- At-home sample collection:Dried blood spot and saliva kits distributed through e-commerce channels are bypassing traditional phlebotomy infrastructure for wellness screening panels.
Industry Challenges
- ISO 15189 accreditation timelines:College of American Pathologists inspection backlogs now extend 14-18 months, delaying new laboratory launches and limiting service line expansion.
- Legacy analyzer integration:Hospital information systems require costly middleware development to connect decades-old chemistry analyzers with modern laboratory information management platforms.
- Molecular technologist scarcity:Polymerase chain reaction and next-generation sequencing expertise concentrates in academic medical centers, constraining community laboratory test menu expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Laboratory Tests Market |
| Market Size in 2026 | $267.4 Billion |
| Market Size in 2035 | $467.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Immunoassays, Clinical Chemistry, Hematology, Molecular Diagnostics Application: Infectious Diseases, Oncology, Metabolic Disorders, Cardiovascular Diseases End User: Hospitals, Diagnostic Centers, Home Care, Research Laboratories Technology: Automated Analyzers, Point of Care Testing, Microfluidics, Next-Generation Sequencing |
| Companies Covered | Quest Diagnostics Incorporated, Laboratory Corporation of America, Siemens Healthineers, Sonic Healthcare Limited, OPKO Health, Inc., ARUP Laboratories, Eurofins Scientific, Mayo Clinic Laboratories, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Laboratory Tests Market Strategic Shifts & Innovations
Digital pathology and liquid biopsy platforms are collapsing traditional specimen processing workflows while regulatory frameworks scramble to validate algorithmic diagnostics. These shifts are redistributing value capture from hardware manufacturers to data analytics providers.
Next-generation sequencing panels for minimal residual disease monitoring are collapsing the distinction between treatment response assessment and recurrence surveillance. Oncology practices in the United States now order these assays quarterly rather than annually, compressing revenue per test while expanding total addressable volume. The technology is collapsing traditional anatomic pathology billing codes into molecular diagnostic reimbursement categories.
Europe's In Vitro Diagnostic Regulation (IVDR) is reclassifying companion diagnostics as Class C devices, requiring notified body involvement for conformity assessment. Manufacturers serving the European Union market must now submit clinical evidence packages that demonstrate analytical and clinical validity against defined performance criteria. Small-to-mid-sized assay developers are responding by withdrawing lower-volume products from the European market rather than absorbing compliance costs.
Health system procurement departments now unbundle analyzer placement contracts from reagent supply agreements, reversing decades of razor-and-blade commercial models. Integrated delivery networks in Texas and Florida negotiate instrument leases separately from per-test consumable pricing, pressuring manufacturers to disclose true equipment costs. This behavioral shift is most visible among systems operating more than 15 hospitals, where procurement consolidation creates sufficient volume leverage.
Clinical Laboratory Tests Market Segmentation
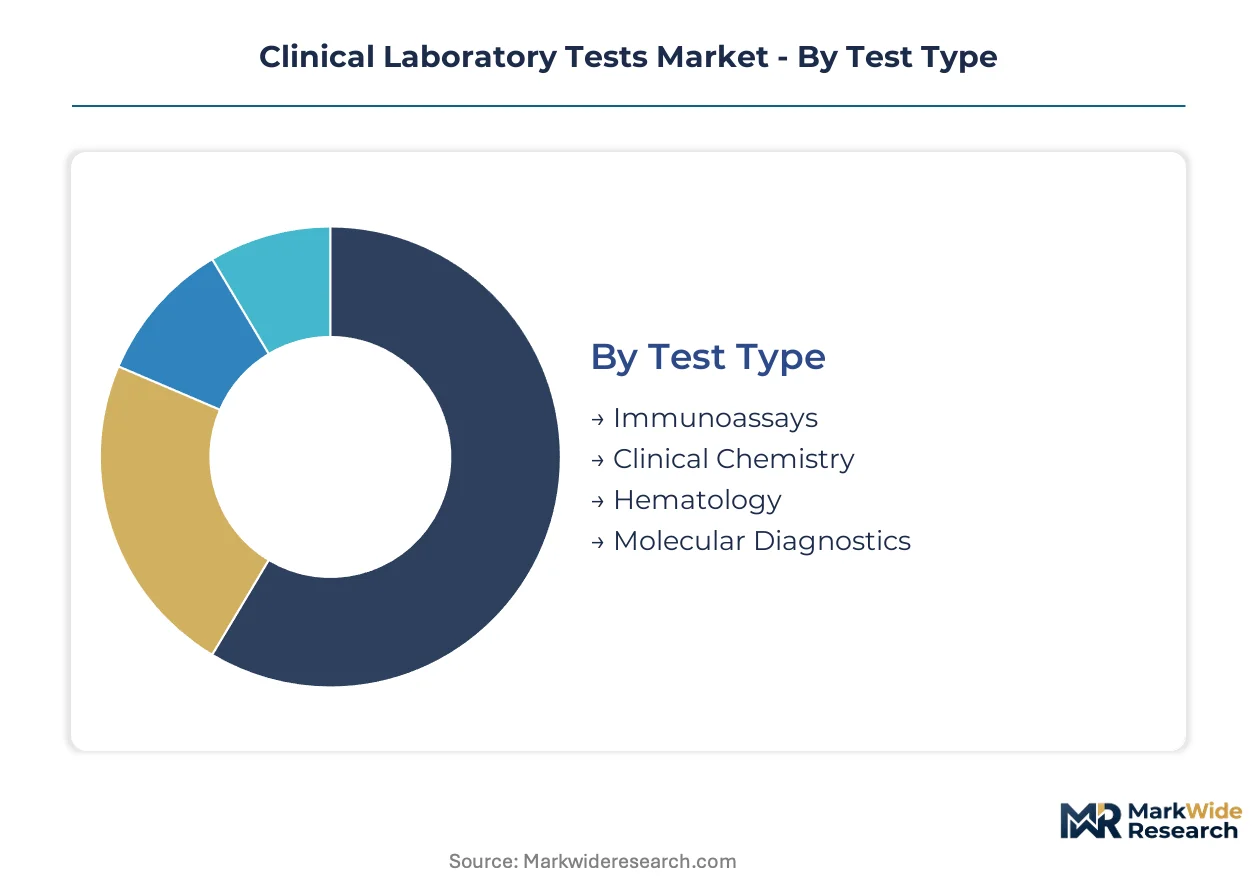
Clinical laboratory tests fragment across multiple technical and operational dimensions, each carrying distinct margin profiles and capital requirements. Understanding these partitions reveals where service intensity concentrates and where automation can displace labor costs.
Test Type:
After-sales service intensity varies sharply across test categories, with complex platforms demanding multi-year maintenance contracts and field engineering support while simpler chemistries run on break-fix models.
- Immunoassays:Antibody-antigen binding reactions detect hormones, tumor markers, and infectious agents with femtomolar sensitivity. Hospital laboratories in the United States anchor demand as therapeutic drug monitoring protocols expand post-discharge surveillance requirements.
- Clinical Chemistry:Enzymatic and spectrophotometric methods quantify electrolytes, enzymes, and metabolites in serum or plasma. High-throughput hospital core laboratories concentrate volume here, though reimbursement compression from Medicare's Clinical Laboratory Fee Schedule constrains menu expansion.
- Hematology:Automated cell counting and differential analysis characterizes blood cell populations for anemia, infection, and malignancy screening.
- Molecular Diagnostics:Nucleic acid amplification and hybridization techniques enable pathogen detection and genetic variant identification.
By volume, Clinical Chemistry leads. By growth pace, Molecular Diagnostics is ahead.
Application:
Application segmentation tracks how disease burden translates into test ordering patterns, with oncology and infectious disease workflows commanding premium pricing due to clinical urgency.
- Infectious Diseases:Culture, PCR, and serological methods identify bacterial, viral, and fungal pathogens. Emergency departments and intensive care units drive stat ordering patterns where turnaround time determines antibiotic stewardship decisions.
- Oncology:Tumor marker quantification, circulating tumor DNA detection, and minimal residual disease monitoring guide treatment selection and response assessment. Academic medical centers in the United States concentrate demand as precision medicine protocols mandate companion diagnostic testing.
- Metabolic Disorders:Glucose, lipid, and thyroid panels screen for diabetes, dyslipidemia, and endocrine dysfunction.
- Cardiovascular Diseases:Troponin, BNP, and lipid profiles stratify acute coronary syndrome risk and chronic management.
Infectious Diseases captures the highest test frequency. Oncology generates the steepest revenue per specimen.
End User:
End user configuration determines capital deployment models, with hospital systems favoring integrated analyzer networks while independent diagnostic centers pursue hub-and-spoke collection strategies.
- Hospitals:Inpatient and emergency settings demand 24-hour stat capabilities with sub-hour turnaround windows. Integrated delivery networks in Texas and Florida consolidate purchasing across multiple facilities to extract volume discounts from manufacturers.
- Diagnostic Centers:Outpatient-focused chains process routine wellness panels and employer health screenings. India's tier-2 and tier-3 cities present whitespace for organized chains to displace fragmented standalone laboratories.
- Home Care:Dried blood spot and saliva collection kits enable remote specimen acquisition for wellness screening.
- Research Laboratories:Investigational use assays and clinical trial support services operate outside standard reimbursement frameworks.
Hospitals dominate absolute test volume. Home Care is expanding most quickly as direct-to-consumer channels mature.
Technology:
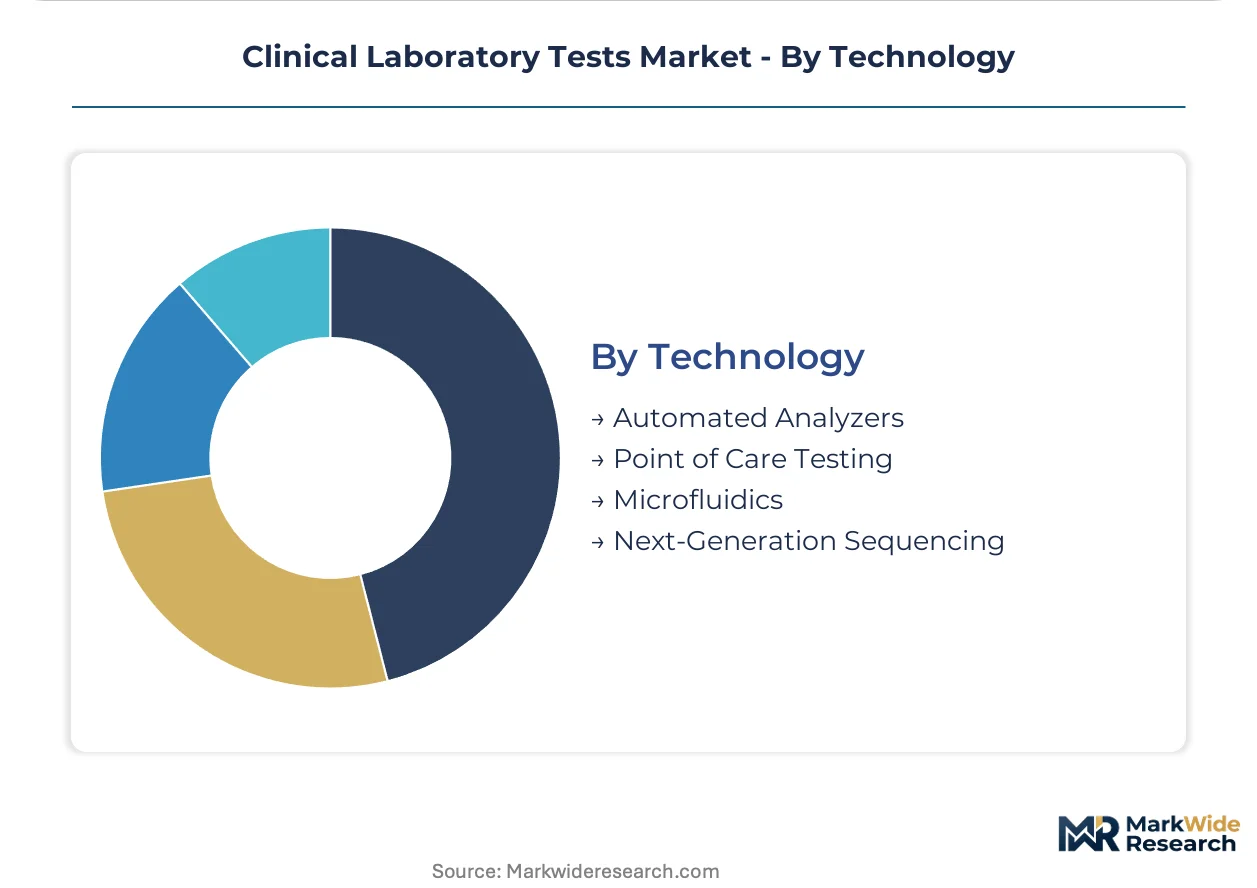
Technology segmentation separates capital-intensive central laboratory automation from distributed point-of-care platforms, with microfluidics and sequencing collapsing traditional workflow boundaries.
- Automated Analyzers:Random-access chemistry and immunoassay systems process hundreds of tests hourly with minimal technologist intervention. Siemens Healthineers and Roche Diagnostics anchor installed base concentration in the United States through long-term reagent supply contracts.
- Point of Care Testing:Cartridge-based and handheld devices deliver results at the bedside or in ambulatory settings within minutes. Emergency departments and perioperative suites capture volume here, commanding premium pricing for speed-critical decisions.
- Microfluidics:Lab-on-chip architectures miniaturize multi-step analytical workflows onto disposable cartridges.
- Next-Generation Sequencing:Massively parallel DNA sequencing enables comprehensive genomic profiling for oncology and rare disease applications.
Automated Analyzers retain the largest installed base. Next-Generation Sequencing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement policies through the Clinical Laboratory Fee Schedule directly shape laboratory economics in the United States. Germany's In Vitro Diagnostic Regulation implementation creates compliance templates that laboratories across Europe must adopt. India's hub-and-spoke collection models are penetrating tier-2 and tier-3 cities where organized chains displace fragmented standalone operators.
United States
Integrated delivery networks in Texas and Florida consolidate purchasing across multiple facilities to extract volume discounts from manufacturers. The FDA's evolving jurisdiction over laboratory-developed tests alters validation requirements for assay developers. Academic medical centers in Boston and the Research Triangle concentrate molecular diagnostics expertise where precision medicine protocols mandate companion diagnostic testing.
Germany
Hospital laboratories anchor demand for automated analyzers as therapeutic drug monitoring protocols expand post-discharge surveillance requirements. The In Vitro Diagnostic Regulation reclassifies companion diagnostics as Class C devices, requiring notified body involvement for conformity assessment. Industrial clusters in Baden-Württemberg and Bavaria host analyzer manufacturers that supply integrated platforms tightening workflow control.
India
Tier-2 and tier-3 cities present whitespace for organized diagnostic chains to displace fragmented standalone laboratories. The Central Drugs Standard Control Organization governs import licensing for reagents and analyzers entering the domestic market. Maharashtra and Karnataka host hub-and-spoke collection center models where logistics infrastructure enables specimen routing to centralized processing facilities.
Japan
Point-of-care testing platforms capture volume in emergency departments where speed commands premium pricing for critical decisions. The Ministry of Health, Labour and Welfare sets reimbursement rates that influence hospital laboratory capital deployment decisions. The Kanto region around Tokyo concentrates installed base density for automated chemistry and immunoassay systems serving aging population screening programs.
China
Independent diagnostic laboratories expand service menus to capture ambulatory volume shifting from hospital inpatient settings. The National Medical Products Administration governs registration requirements for in vitro diagnostic reagents and instruments. The Yangtze River Delta and Pearl River Delta clusters host domestic analyzer manufacturers competing with multinational suppliers on cost-adjusted performance metrics.
Clinical Laboratory Tests Market Key Industry Players
Channel-controlling players compete with product-specialist players across distinct value capture vectors. National laboratory networks leverage logistics infrastructure to sustain specimen throughput advantages, while esoteric test developers anchor competitiveness through proprietary assay portfolios. Three archetypes dominate: integrated diagnostic networks, specialized esoteric laboratories, and analyzer-to-informatics platform providers. Consolidation through acquisition of regional laboratory chains and vertical integration into reagent manufacturing represent the dominant competitive moves reshaping market structure.
Within the integrated network tier, Quest Diagnostics Incorporated and Laboratory Corporation of America exemplify channel-controlling archetypes that consolidate specimen volume across geographic footprints. Siemens Healthineers occupies a position representing analyzer-to-informatics platform providers that tighten workflow control through integrated hardware-software architectures. These three entities anchor the competitive landscape by representing distinct strategic positions: logistics-dominated scale, esoteric capability concentration, and vertical technology integration.
| Leading Market Players |
|---|
| Quest Diagnostics Incorporated |
| Laboratory Corporation of America |
| Siemens Healthineers |
| Sonic Healthcare Limited |
| OPKO Health, Inc. |
| ARUP Laboratories |
| Eurofins Scientific |
| Mayo Clinic Laboratories |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Cold-chain freight corridors connecting reagent manufacturing clusters in Germany to diagnostic laboratories across the United States impose cost dynamics that amplify both supply concentration effects and downstream price stratification. The interplay between temperature-controlled logistics expenses and reagent lot certification requirements creates differentiation pressure across buyer segments.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 15189-accredited laboratories commanding 15-25% price premiums over non-accredited counterparts. Per-test transactional pricing dominates, though integrated delivery networks increasingly negotiate multi-year reagent supply contracts with inflation-linked escalators. Price differentiation hinges on after-sales service intensity and field engineering support bundled with analyzer placements. Hospital systems demonstrate lowest price sensitivity due to stat turnaround requirements, while independent diagnostic centers face acute margin compression from Medicare reimbursement compression.
Supply Chain Analysis
Export-control restrictions on nucleic acid amplification technologies limit flows from the United States to certain jurisdictions, constraining molecular diagnostics supply chains. Reagent production concentrates in Germany, the United States, and Japan, with immunoassay raw materials drawing from specialized antibody production facilities in Switzerland and the Netherlands. Single-source vulnerability characterizes polymerase chain reaction enzyme supply, where three manufacturers control critical production capacity. Distribution runs through manufacturer-direct field service organizations for high-complexity platforms, while routine chemistries flow through regional distribution partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including multi-year maintenance contracts and field engineering support are expanding faster than hardware placements, repositioning capital equipment as a recurring-revenue anchor rather than a transactional sale.
For Market Incumbents: Insulate core analyzer placements by locking in exclusive reagent supply agreements with penalty clauses for early termination. Consolidate regional laboratory networks to capture ambulatory volume shifting from hospital inpatient settings. The FDA's evolving laboratory-developed test oversight threatens validation timelines for existing assay portfolios; preemptive investment in ISO 15189 accreditation across all processing facilities creates defensive moats against compliance disruption. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 cities where organized diagnostic chains displace fragmented standalone operators with hub-and-spoke collection models. Target point-of-care testing platforms for emergency departments where speed commands premium pricing and incumbent presence remains thin. Pursue direct-to-consumer channels for wellness screening panels using dried blood spot kits distributed through e-commerce platforms, bypassing traditional phlebotomy infrastructure requirements. For Investors and Strategic Acquirers: Esoteric test developers with proprietary companion diagnostic portfolios represent the most defensible acquisition archetype as precision medicine protocols mandate oncology assay integration. Long-term viability rests on reimbursement pathway durability rather than volume scale alone. Watch for inflection signals in Medicare Clinical Laboratory Fee Schedule rulemaking that would compress molecular diagnostics margins and force portfolio restructuring across the sector.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Supply Agreement Restructuring | Unbundling analyzer leases from consumable pricing pressures manufacturers to disclose true equipment costs. |
| AI-Augmented Pathology Platform Launch | Machine learning algorithms trained on digital slide archives collapse diagnostic turnaround times for cancer centers. |
| Hub-and-Spoke Collection Network Expansion | Logistics infrastructure enables specimen routing from tier-2 Indian cities to centralized processing facilities. |
| ISO 15189 Accreditation Pre-Investment | Preemptive quality certification insulates against College of American Pathologists inspection backlogs extending 14-18 months. |
| Liquid Biopsy Companion Diagnostic Development | Minimal residual disease monitoring panels compress revenue per test while expanding total addressable oncology volume. |
Research Approach
Initial hypotheses were tested against primary input from laboratory operations directors, hospital purchasing committee members, GPO contracts managers, and biomedical engineers, then refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and College of American Pathologists accreditation directories. Bottom-up test volume modeling triangulated against top-down market sizing across geographic clusters and end-user configurations.
Demand-supply balance framing anchored the forecast architecture, with segmentation dimensions spanning test type, application, end-user configuration, and technology platform across the analysis window. CAGRs derived from weighted average of historical trajectory and forward-looking reimbursement policy impacts. Molecular diagnostics expansion rates and point-of-care testing penetration curves served as primary forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates or FDA premarket review timelines would shift the trajectory. Forecasts reflect assumptions on regulatory stability and cold-chain logistics cost continuity. Material shifts in laboratory-developed test oversight enforcement or companion diagnostic reclassification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Assessment Services Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Histopathology Services Market
Laboratory Services
Central Lab Market