
 Veterinary Active Pharmaceutical Ingredients Manufacturing Market | 2026-2036
Veterinary Active Pharmaceutical Ingredients Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Active Pharmaceutical Ingredients Manufacturing Market Intelligence
The veterinary active pharmaceutical ingredients manufacturing sector is restructuring around a sharp divergence between premium biological APIs and commodity small-molecule chemistry. Zoetis leverages its vertical integration across biologics development to command premium positioning in vaccine-grade APIs. Alivira Animal Health Limited anchors its competitive stance through backward integration into fermentation-based antibiotic production. FIS - Fabbrica Italiana Sintetici S.p.A. differentiates via specialized synthetic routes for antiparasitic actives.
Veterinary active pharmaceutical ingredients are biologically or synthetically derived substances used as the pharmacologically active components in animal health formulations, typically requiring purity thresholds above 98% and compliance with species-specific toxicological profiles to ensure therapeutic efficacy in target animals. Antibiotics and antiparasitics remain the mature revenue base, while vaccines represent the fastest-expanding margin pool as companion animal owners shift toward preventive care. The injectables form dominates livestock applications due to dosing reliability in herd settings, whereas tablets concentrate in companion animal channels where owner compliance drives formulation preference.
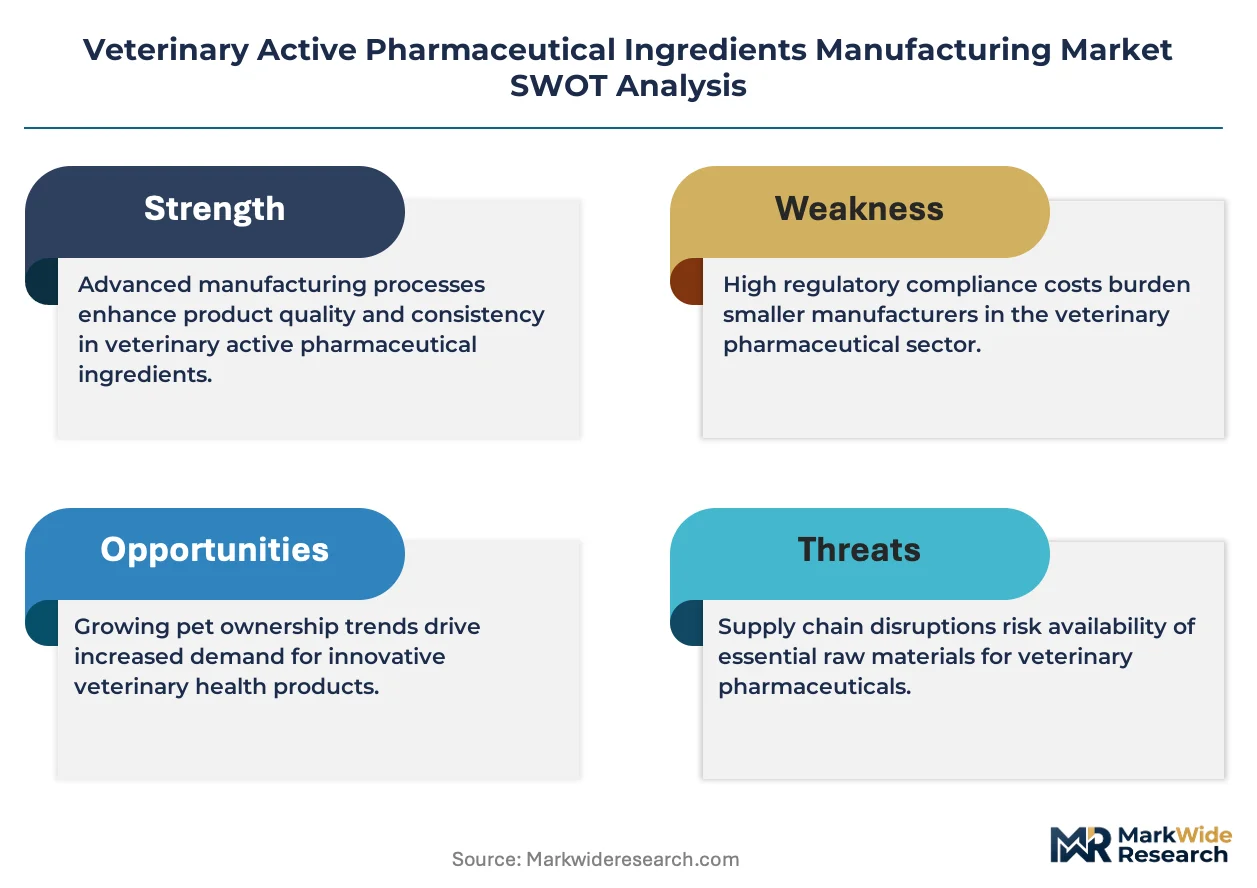
The FDA Center for Veterinary Medicine enforces strict bioequivalence and residue monitoring standards that elevate compliance costs for API suppliers seeking US market access, while the EMA's veterinary medicines regulation harmonizes quality benchmarks across EU member states. India's CDSCO and BIS frameworks govern domestic manufacturing standards while enabling export-oriented production through WHO-GMP alignment. Stakeholders must monitor evolving regulatory divergence between major markets to optimize facility certification strategies and avoid redundant compliance investments.
Market Dynamics
The FDA's veterinary feed directive and EU antibiotic stewardship rules are forcing manufacturers to restructure product portfolios around reduced-residue actives and alternative therapeutic modalities, compressing legacy chemistry margins while elevating biologics investment.
Growth Catalysts
- Regulatory Mandate Convergence:The FDA Center for Veterinary Medicine and EMA's veterinary medicines regulation are harmonizing residue monitoring standards, creating cross-certification efficiencies for compliant API suppliers.
- Companion Animal Preventive Care:Pet owners in developed markets are expanding vaccine-grade API procurement volumes as veterinary clinics shift toward wellness protocols.
- India's Contract Manufacturing Scale:WHO-GMP-aligned facilities in Hyderabad and Ahmedabad are capturing export demand from price-sensitive livestock producers across Southeast Asia and Africa.
Market Restraints
- Key Starting Material Volatility:Fermentation-derived antibiotic precursors face input cost swings from agricultural commodity markets, squeezing margin predictability for fermentation-based producers.
- Single-Source Supply Risk:Synthetic antiparasitic intermediates concentrate in Chinese specialty chemical hubs, exposing formulators to geopolitical disruption and logistics bottlenecks.
- Biologics Manufacturing Complexity:Cell culture and recombinant protein production require sterile facility investments that exceed small-molecule chemistry capex by orders of magnitude, limiting supplier entry.
Strategic Opportunities
- Brazilian Livestock Export Compliance:ANVISA's alignment with Codex Alimentarius standards creates demand for certified residue-free APIs among Brazilian beef integrators supplying EU and Middle Eastern markets.
- Phage Therapy Convergence:Bacteriophage technology combined with precision fermentation is opening alternative antibacterial pathways as antibiotic restrictions tighten in poultry and aquaculture.
- Direct-to-Formulator Platforms:Digital procurement channels are disintermediating traditional distributor networks for standard-grade small-molecule APIs, reducing working capital cycles for mid-size veterinary pharmaceutical manufacturers.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Vaccine-grade API facilities require staff trained in cell line development and aseptic processing, competencies concentrated in human biologics hubs with limited veterinary crossover.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, EMA, and BIS facility approvals extend qualification periods to 18-24 months, delaying revenue recognition for greenfield investments.
- Legacy Equipment Integration:Synthetic route optimization for antiparasitic actives demands continuous processing retrofit, straining capital allocation for multi-product facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Active Pharmaceutical Ingredients Manufacturing Market |
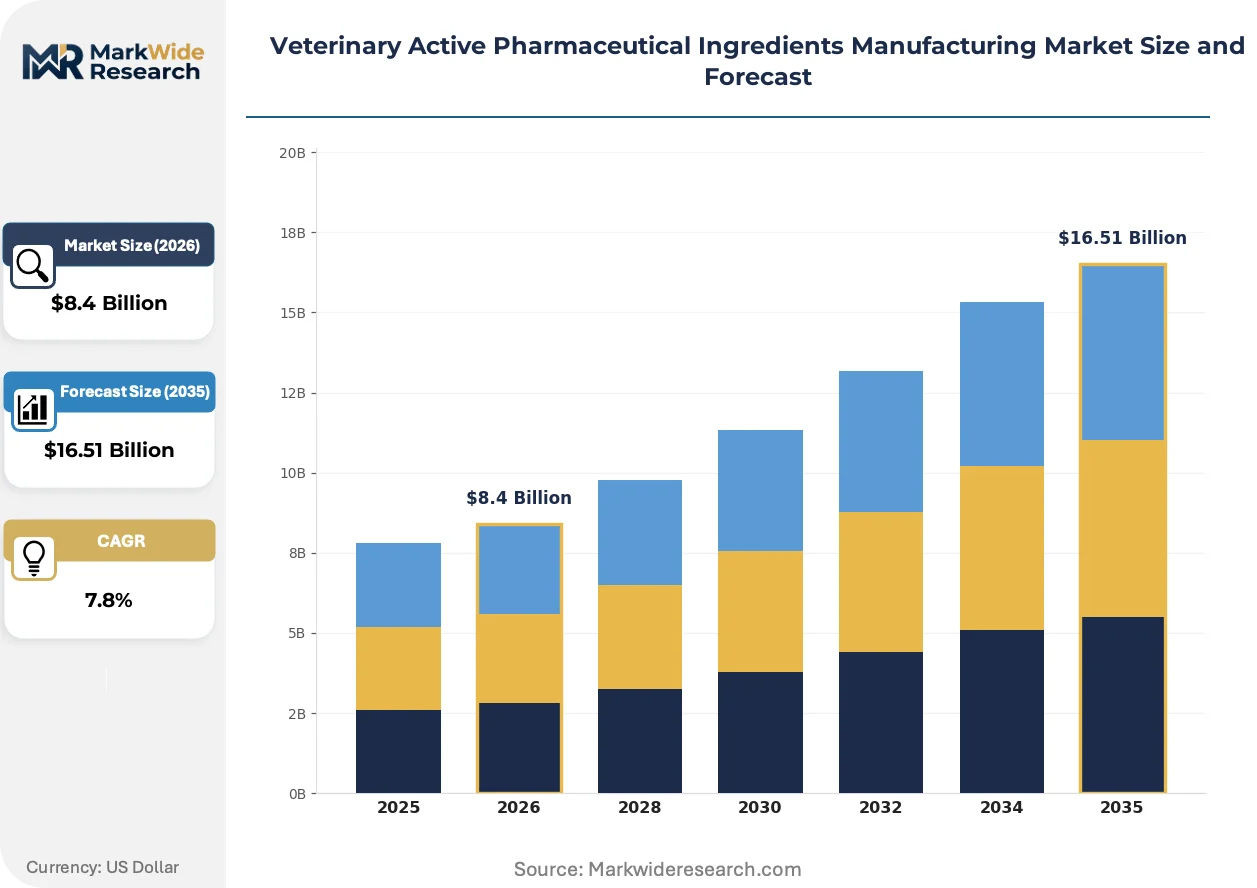
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Hormones, Antiparasitics, Vaccines End User: Veterinary Clinics, Research Laboratories, Pharmaceutical Companies, Animal Hospitals Form: Injectables, Tablets, Powders, Solutions Application: Companion Animals, Livestock, Aquaculture, Others |
| Companies Covered | Zoetis, Alivira Animal Health Limited, Ofichem Group, SUANFARMA, Excel Industries Limited, FIS - Fabbrica Italiana Sintetici S.p.A., Grupo Indukern S.L., Huvepharma, Menadiona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Active Pharmaceutical Ingredients Manufacturing Market Strategic Shifts & Innovations
Continuous processing technology and precision fermentation are displacing batch manufacturing paradigms, while regulatory pressure on antimicrobial resistance is redirecting R&D investment toward non-antibiotic therapeutic platforms.
Continuous flow chemistry for antiparasitic API synthesis is absorbing capital from traditional batch reactor investments as manufacturers seek yield improvements and solvent reduction. Mid-size veterinary pharmaceutical formulators in Europe and North America are adopting these systems at measured pace, constrained by technical revalidation requirements. The technology is absorbing engineering talent from human pharmaceutical contract manufacturing, tightening labor markets for specialized process design.
EMA's veterinary medicines regulation is compressing approval timelines for novel excipients while tightening environmental risk assessment requirements for manufacturing effluents. API suppliers must now submit extended aquatic toxicity data for parasiticide actives, elevating pre-registration costs. Aquaculture-focused manufacturers in Norway and Scotland are responding by partnering with specialized environmental consultancies to streamline dossier preparation.
Livestock integrators are consolidating API procurement under centralized veterinary services agreements, displacing decentralized purchasing by individual farm operators. This concentration is reshaping distributor economics as volume aggregates toward direct manufacturer relationships. The pattern is most visible in US broiler and swine production systems, where Tyson Foods and Smithfield Foods equivalents are negotiating multi-year API supply contracts with quality-tier specifications.
Veterinary Active Pharmaceutical Ingredients Manufacturing Market Segmentation
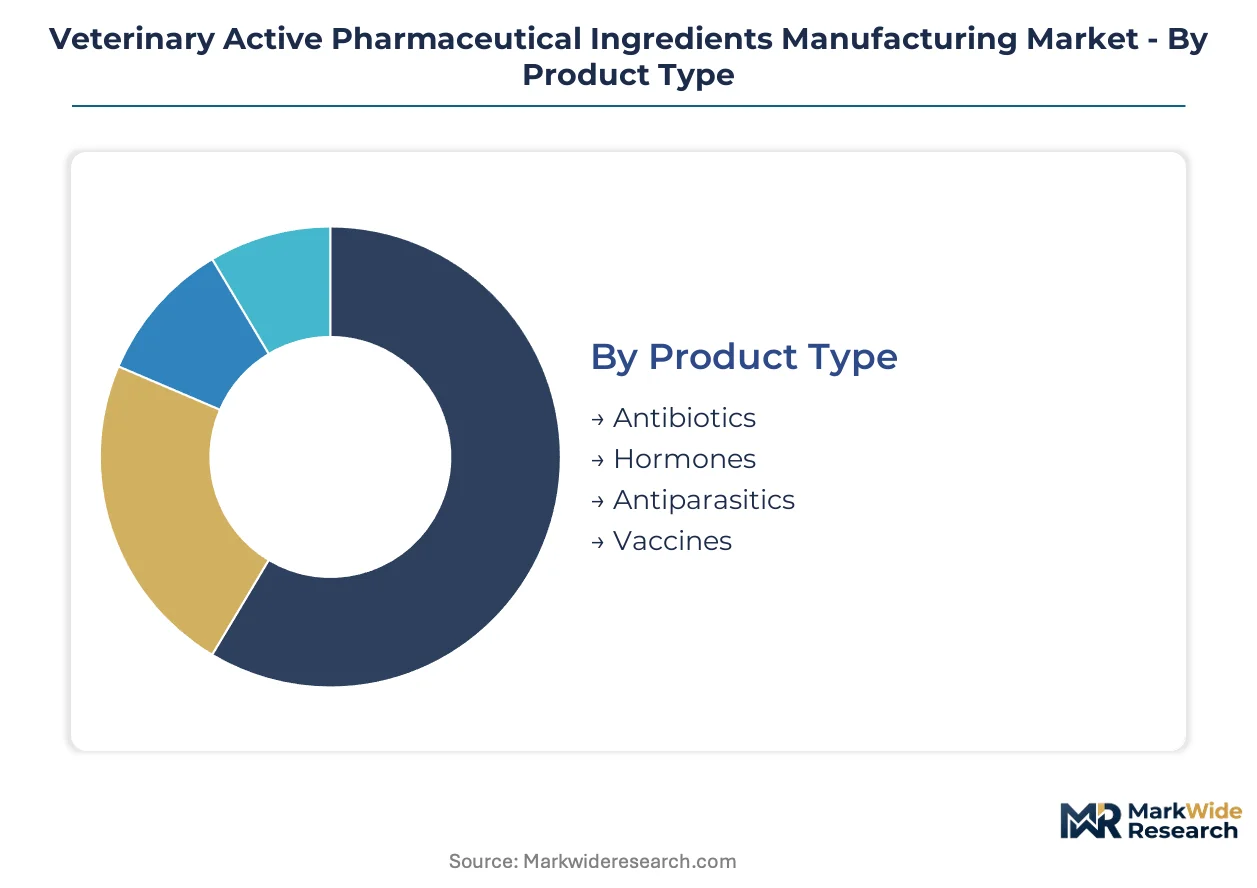
Segmentation in veterinary API manufacturing reveals divergent margin structures across therapeutic modalities and customer channels. Product type stratification separates commodity fermentation outputs from precision biologics, while end-user concentration determines certification requirements and commercial access models.
Product Type:
Customization intensity varies sharply across this category, from standardized fermentation batches to patient-specific biologic formulations requiring cell-line engineering.
- Antibiotics:Fermentation-derived beta-lactams and tetracyclines dominate livestock procurement volumes. Demand concentrates in India and China where backward-integrated producers supply price-sensitive poultry and swine integrators facing FDA veterinary feed directive compliance costs.
- Vaccines:Recombinant protein and viral vector platforms command premium positioning through sterile manufacturing requirements. Companion animal clinics in the US and Germany are expanding preventive care protocols, driving procurement of adjuvanted and modified-live antigen APIs with cold-chain specifications.
- Hormones:Synthetic steroid intermediates for reproductive synchronization in cattle and equine breeding programs.
- Antiparasitics:Macrocyclic lactones and benzimidazoles targeting endoparasite and ectoparasite control across grazing livestock and companion animals.
Leading the category by volume: Antibiotics. Expanding most quickly: Vaccines.
End User:
Customer sophistication determines API specification tiers, from research-grade analytical standards to commercial-scale GMP batches for finished dosage manufacturing.
- Pharmaceutical Companies:Integrated veterinary drug manufacturers and contract formulators procure multi-ton API quantities under long-term supply agreements with residue-grade and potency specifications. These buyers concentrate procurement authority in procurement departments that audit fermentation and synthetic facilities across India, Italy, and Spain.
- Veterinary Clinics:Small-volume purchasers of compounded APIs for individualized patient dosing, particularly in equine and exotic animal practice. US clinics operate under FDA Center for Veterinary Medicine compounding guidance, while German clinics reference EMA veterinary medicines regulation for API sourcing.
- Animal Hospitals:Emergency and referral centers requiring rapid-access injectable APIs for critical care.
- Research Laboratories:Preclinical and field trial sponsors sourcing reference standards and investigational APIs with certificate of analysis documentation.
Volume leadership sits with pharmaceutical companies. Fastest-climbing segment: veterinary clinics expanding in-house compounding capabilities.
Form:
Manufacturing complexity and stability requirements create distinct supply chain configurations across physical presentations.
- Injectables:Sterile solution and suspension APIs for parenteral administration dominate livestock herd health programs. Demand aggregates with Brazilian beef integrators and US swine producers requiring depot-formulation actives with extended release kinetics.
- Tablets:Compressed dosage form APIs concentrate in companion animal channels where owner compliance drives palatability-enhanced formulations. European and North American pet owners prefer chewable matrices, requiring excipient-compatible actives with taste-masking properties.
- Powders:Bulk active materials for medicated feed premix manufacturing and water-soluble administration in poultry houses.
- Solutions:Oral and topical liquid concentrates for pour-on antiparasitic delivery and drinking water medication.
Injectables capture the largest volume share. Tablets are gaining share fastest on companion animal preventive care expansion.
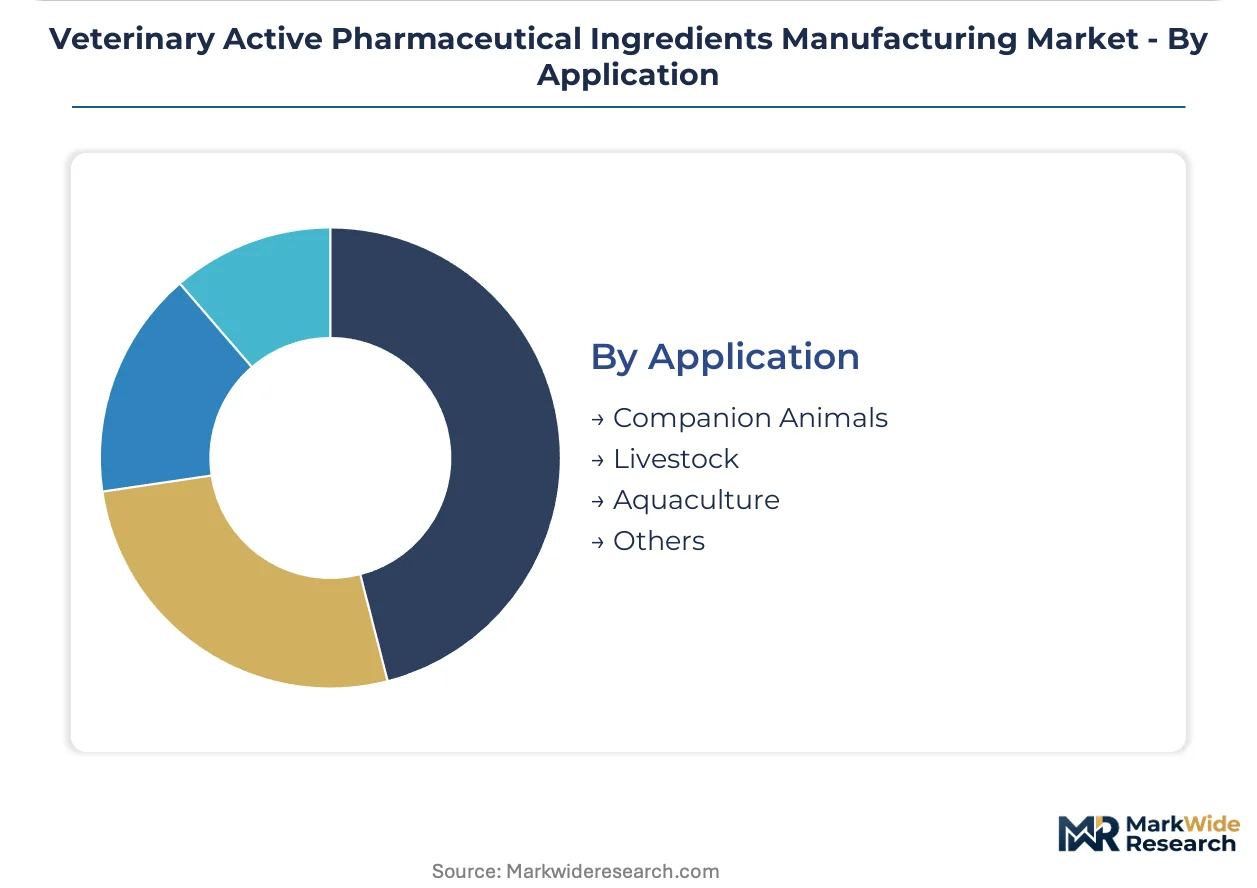
Application:
Species-specific toxicology and residue depletion profiles force API portfolio specialization across animal categories.
- Livestock:Cattle, swine, and poultry production systems consume tonnage-scale antibiotics and antiparasitics under withdrawal-period compliance protocols. Indian and Brazilian integrators are consolidating procurement under centralized veterinary services agreements with residue-free certification requirements.
- Companion Animals:Canine and feline therapeutic demand is shifting toward vaccine-grade biologics and chronic disease management APIs. US and German pet owners are expanding spending on oncology and dermatology actives with human-analog manufacturing standards.
- Aquaculture:Finfish and shellfish production in Norway and Scotland requires parasiticide and antibacterial APIs with extended aquatic toxicity dossiers under EMA environmental risk assessment rules.
- Others:Equine, ovine, and exotic species applications with specialized pharmacokinetic requirements.
Livestock maintains volume dominance. Companion animals show the steepest expansion trajectory on biologics premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors global contract manufacturing for veterinary APIs, with WHO-GMP-aligned facilities serving export markets across Southeast Asia, Africa, and Latin America. The city's fermentation corridor supplies price-sensitive livestock producers while maintaining compliance with multiple regulatory jurisdictions.
United States
Companion animal clinics in Texas and California are expanding vaccine-grade API procurement as preventive care protocols displace reactive treatment. The FDA Center for Veterinary Medicine enforces residue monitoring standards that elevate compliance costs for suppliers seeking market access. Indianapolis and Kansas City host formulation facilities that audit Indian and Italian API sources for GMP alignment.
Germany
EMA's veterinary medicines regulation harmonizes quality benchmarks across EU member states, creating cross-certification efficiencies for compliant suppliers. The country's national pharmaceutical regulator maintains strict bioequivalence standards for antiparasitic actives used in livestock export chains. Bavaria's chemical corridor near Leverkusen concentrates synthetic route development for macrocyclic lactone intermediates.
India
CDSCO and BIS frameworks govern domestic manufacturing standards while enabling export-oriented production through WHO-GMP alignment. Hyderabad and Ahmedabad facilities capture contract manufacturing demand from Brazilian beef integrators and Southeast Asian poultry producers. The country's fermentation base supplies beta-lactam and tetracycline precursors under price-competitive terms.
Brazil
ANVISA's alignment with Codex Alimentarius standards creates demand for certified residue-free APIs among beef integrators supplying EU and Middle Eastern markets. São Paulo state concentrates veterinary services agreements that consolidate API procurement under centralized purchasing. The southern livestock belt around Rio Grande do Sul drives antiparasitic active consumption for grazing cattle.
Italy
Synthetic antiparasitic production concentrates in the Lombardy-Veneto chemical corridor, where specialized routes for macrocyclic lactones and benzimidazoles serve European formulators. Swissmedic-aligned facilities near Milan supply cross-border demand from Swiss and German veterinary pharmaceutical manufacturers. The region's fine chemical heritage supports custom synthesis for novel therapeutic candidates.
Veterinary Active Pharmaceutical Ingredients Manufacturing Market Key Industry Players
Premium-margin players sit above commodity-margin players across therapeutic modality and manufacturing complexity, with biologics specialists commanding valuation multiples that exceed small-molecule fermentation operators by substantial margins. The market structures around three tiers: multinational integrators with captive biologics capacity, mid-size specialists with backward integration into fermentation or synthesis, and regional contract manufacturers serving price-sensitive livestock channels. Two competitive moves dominate: capacity expansion in India and Eastern Europe for cost-positioned supply, and strategic partnerships between synthetic chemistry houses and biologics developers to bridge modality gaps.
Within the multinational tier, Zoetis exemplifies vertical control across vaccine-grade biologics development, while Alivira Animal Health Limited occupies a position in fermentation-based antibiotic production with Indian manufacturing scale. FIS - Fabbrica Italiana Sintetici S.p.A. represents the specialized synthetic chemistry archetype, anchoring European supply for antiparasitic actives through custom route development.
| Leading Market Players |
|---|
| Zoetis |
| Alivira Animal Health Limited |
| Ofichem Group |
| SUANFARMA |
| Excel Industries Limited |
| FIS - Fabbrica Italiana Sintetici S.p.A. |
| Grupo Indukern S.L. |
| Huvepharma |
| Menadiona |
| Others |
Cost & Logistics Intelligence
Livestock integrator consolidation under centralized veterinary services agreements is forcing API suppliers to absorb certification and residue-testing costs, compressing margins for standard-grade fermentation outputs while elevating premiums for certified biologics. This procurement concentration rewards manufacturers with multi-jurisdiction GMP alignment and penalizes single-market operators.
Pricing Analysis
Yield-guarantee contracting anchors value-based pricing for vaccine-grade biologics, with companion animal clinics in Germany and Texas paying premiums for cold-chain-assured potency. Three-tier pricing structure across premium, standard, and economy levels separates WHO-GMP-certified biologics from domestic-grade fermentation outputs and non-certified commodity chemistry. Cost compression in standard-grade antibiotics is intensifying because Indian contract manufacturers are capturing Southeast Asian livestock demand at aggressive terms. Brazilian beef integrators exhibit highest price sensitivity due to Codex Alimentarius compliance burdens, while US companion animal channels remain least sensitive on preventive care biologics.
Supply Chain Analysis
Bioprocess engineering talent scarcity in Hyderabad and Ahmedabad strains fermentation capacity expansion despite robust facility investment. API supply concentrates in India, China, and Italy, with synthetic antiparasitic intermediates drawing from Chinese specialty chemical hubs and fermentation-derived antibiotics resting on Indian agricultural substrate markets. Single-source vulnerability runs through concentrated antiparasitic precursor production. Distribution runs through direct manufacturer relationships with consolidated livestock integrators and distributor networks serving fragmented veterinary clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary API sector is transitioning from batch chemical synthesis to continuous flow and precision fermentation platforms, with legacy small-molecule capacity facing stranded asset risk as biologics capture margin expansion.
For Market Incumbents: Acquire sterile biologics manufacturing capacity in WHO-GMP-aligned geographies to offset antibiotic margin erosion from FDA veterinary feed directive compliance costs. Consolidate synthetic route IP for antiparasitic actives before patent cliff exposure. Priority levers include backward integration into fermentation substrate supply and EMA veterinary medicines regulation pre-certification for cross-border EU access. For New Entrants and Emerging Players: Compounding-focused veterinary clinics in North American equine and exotic animal practice represent an underserved buyer archetype with fragmented procurement and limited manufacturer direct relationships. White-space targets include phage therapy APIs for poultry and aquaculture under antibiotic restriction regimes, and direct-to-formulator digital platforms disintermediating legacy distributor networks. A specialized environmental consultancy partnership streamlines EMA aquatic toxicity dossier preparation for aquaculture-focused entrants. For Investors and Strategic Acquirers: The window for entry favors mid-size fermentation specialists with CDSCO certification and established Brazilian beef integrator relationships. Long-term viability centers on modality diversification bridging small-molecule synthesis and biologics capacity. The signal to watch is ANVISA-Codex alignment enforcement tightening among Brazilian export-oriented livestock producers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Yield improvements and solvent reduction attract capital from batch reactor investments in European antiparasitic synthesis. |
| Precision Fermentation Scale-Up | Cell culture capacity expansion addresses vaccine-grade API demand from US and German companion animal preventive care protocols. |
| Multi-Jurisdiction GMP Certification | Simultaneous FDA, EMA, and CDSCO alignment reduces qualification timelines for Indian contract manufacturing facilities. |
| Phage Therapy Platform Development | Bacteriophage technology combined with precision fermentation opens alternative antibacterial pathways under tightening antibiotic restrictions. |
| Direct-to-Formulator Digital Procurement | Disintermediation of distributor networks reduces working capital cycles for mid-size veterinary pharmaceutical manufacturers. |
Research Approach
Regulatory filings with FDA Center for Veterinary Medicine, EMA veterinary medicines regulation submissions, and CDSCO manufacturing facility registrations formed the secondary backbone for supply-side capacity mapping. Primary interviews with fermentation plant managers, veterinary pharmaceutical procurement leads, regulatory affairs directors at contract manufacturing organizations, and companion animal clinic formulary decision-makers validated production cost structures and demand elasticity assumptions. Bottom-up facility capacity analysis triangulated against top-down therapeutic modality consumption estimates.
Historical trendline analysis of antibiotic and vaccine-grade API production volumes established baseline growth patterns across the analysis window. Segmentation modeling incorporated product type, end-user channel sophistication, physical form stability requirements, and species-specific application toxicology. CAGRs derived from regression-adjusted capacity utilization trajectories and regulatory approval pipeline velocity. Industry-specific forecast inputs included FDA veterinary feed directive compliance cost pass-through rates and EMA environmental risk assessment timeline compression.
Revisions become necessary when regulatory divergence between FDA and EMA intensifies, fermentation substrate commodity volatility exceeds historical bands, or bioprocess engineering talent migration from human to veterinary biologics accelerates. Forecasts reflect documented assumptions on facility certification timelines and livestock integrator procurement consolidation trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Critical Care Drugs Market