
 Short-Acting Insulin Market | 2026-2036
Short-Acting Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
Short-Acting Insulin Market Analytics
Type 1 diabetes patients requiring intensive insulin regimens is redrawing procurement patterns across the short-acting insulin landscape. Novo Nordisk leverages its analog manufacturing scale to dominate European hospital tenders. Eli Lilly and Company sustains R&D intensity around next-generation delivery formats. Sanofi anchors geographic reach through established distribution networks in emerging markets.
Short-acting insulin comprises rapid-acting analogs and regular human insulin formulated for subcutaneous injection with onset of action within 15-30 minutes, engineered through recombinant DNA technology to control postprandial glucose spikes in diabetic patients. Insulin Lispro and Insulin Aspart occupy the premium tier due to faster pharmacokinetic profiles and patent-protected formulations, while Insulin Regular remains the economy backbone in price-sensitive procurement environments. Delivery mode segmentation shows insulin pens capturing margin pools through convenience premiums, whereas vial and syringe formats persist in institutional settings where cost minimization governs purchasing decisions.
FDA bioequivalence pathways for biosimilar insulin and EMA's MDR quality system requirements shape product development timelines and market access conditions across major jurisdictions. WHO prequalification standards influence tender eligibility in low- and middle-income country procurement, creating a three-tier regulatory compliance burden for manufacturers. Stakeholders must monitor evolving interchangeability designations and their impact on pharmacy-level substitution policies.
Market Dynamics
Hospital procurement consolidation and homecare self-administration protocols are bifurcating distribution channels for short-acting insulin, forcing manufacturers to maintain dual supply chains with incompatible cost structures and service models.
Growth Catalysts
- FDA Interchangeability Designation Pathway:The accelerated biosimilar approval framework is expanding pharmacy-level substitution authority, unlocking volume access for follow-on rapid-acting analogs in US retail channels.
- Type 1 Diabetes Intensive Regimen Expansion:Endocrinology protocols emphasizing basal-bolus therapy are amplifying per-patient short-acting insulin consumption in tertiary care centers across Germany and Japan.
- Recombinant DNA Manufacturing Scale-Up:Single-use bioreactor adoption is compressing batch cycle times for insulin lispro and aspart production, improving yield economics for high-volume analog supply.
Market Restraints
- API Supply Concentration Risk:Bulk insulin crystal production concentrates among three specialized fermentation facilities in Denmark and China, creating single-source vulnerability for finished dose manufacturers.
- Cold Chain Cost Escalation:Temperature-controlled distribution requirements for unopened insulin vials and pens impose 15-25% logistics premiums that compress margins in emerging market tenders.
- Human Insulin Price Floor Competition:WHO Essential Medicines List procurement protocols in low-income countries favor regular human insulin, limiting rapid-acting analog penetration despite superior pharmacokinetics.
Strategic Opportunities
- Connected Pen Ecosystem Integration:Bluetooth-enabled dose capture devices paired with glucose monitoring apps are opening subscription revenue streams beyond drug sales in US and German reimbursement environments.
- EMA MDR Quality System Harmonization:Streamlined conformity assessment procedures for combination products are reducing time-to-market for pen-injector innovations across EU member states.
- Prefilled Syringe Format Expansion:Emergency department and inpatient settings are adopting ready-to-administer presentations to reduce nursing medication preparation time and dosing error rates.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Mammalian cell culture expertise for insulin analog production remains concentrated among a narrow cohort of specialists, constraining manufacturing expansion timelines.
- Biosimilar Immunogenicity Surveillance Burden:Post-market antibody monitoring requirements for follow-on products impose extended pharmacovigilance obligations that strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short-Acting Insulin Market |
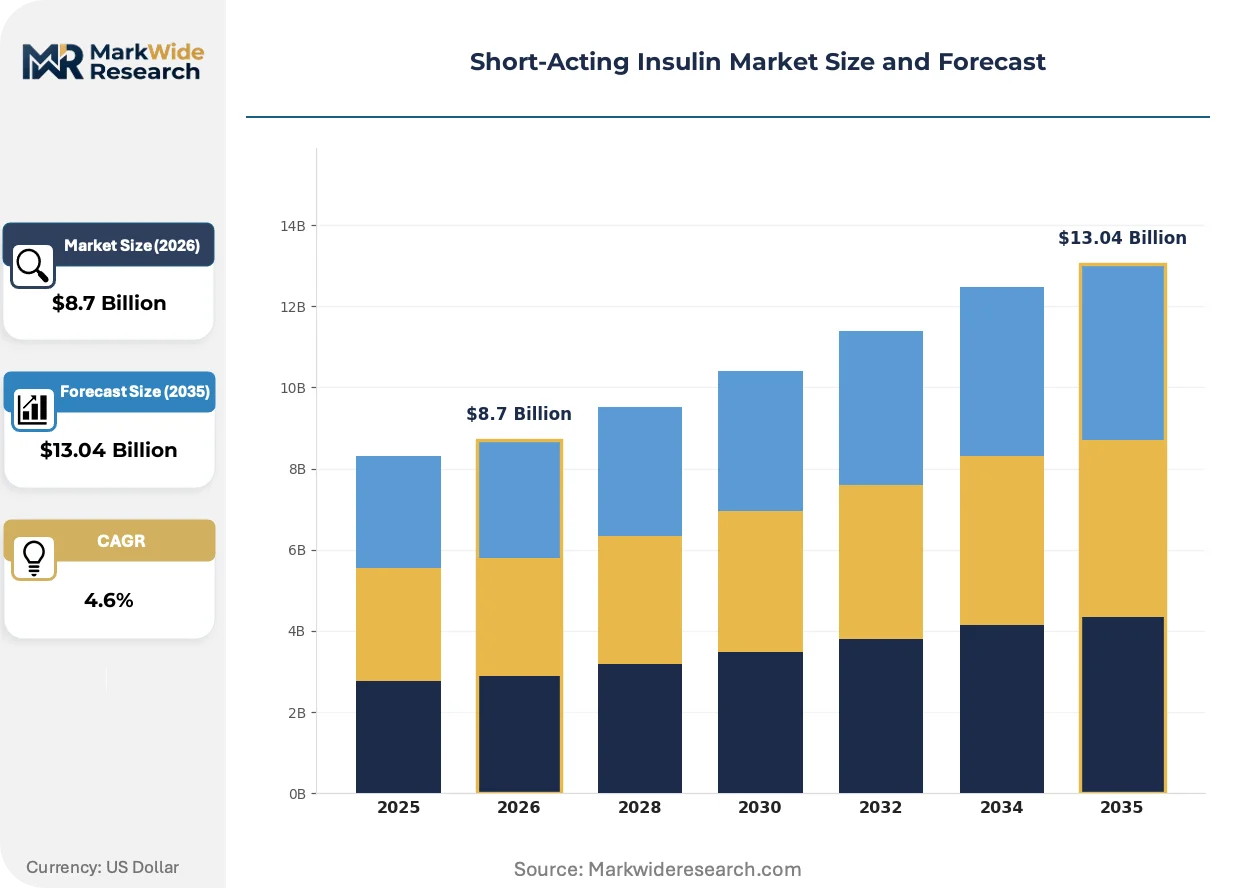
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Lispro, Insulin Aspart, Insulin Glulisine, Insulin Regular Delivery Mode: Vial & Syringe, Insulin Pen, Insulin Pump, Inhalable Insulin End User: Hospitals, Homecare Settings, Clinics, Pharmacies Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Others |
| Companies Covered | Sanofi, Novo Nordisk, Eli Lilly and Company, Biocon Limited, Pfizer, Wockhardt Ltd., Baxter International, Lupin Limited, MannKind Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short-Acting Insulin Market Evolving Landscape
Delivery device intelligence and real-world evidence generation are converging to transform short-acting insulin from a commodity injectable into a data-generating therapeutic system with sticky platform economics.
Ultra-rapid insulin formulations with accelerated absorption profiles are supplanting first-generation rapid-acting analogs in premium reimbursement tiers. Pediatric endocrinology practices and insulin pump users are migrating fastest to these next-generation candidates. The technology is compressing the postprandial glucose control window and enabling tighter closed-loop algorithm performance.
EMA's Medical Device Regulation (MDR) reclassification of insulin pen injectors as Class IIb products is imposing enhanced clinical evidence requirements on combination product submissions. Manufacturers must now generate usability validation data and human factors studies that extend development timelines by 12-18 months. Pen-injector suppliers serving the EU market are restructuring quality management systems to accommodate notified body scrutiny of software lifecycle processes.
Direct-to-patient pharmacy fulfillment models are disrupting traditional wholesale distribution for maintenance insulin prescriptions. Mail-order and specialty pharmacy channels are capturing chronic therapy volumes previously routed through retail storefronts, particularly in US Medicare Part D and commercial managed care plans. This channel rotation concentrates volume with pharmacy benefit managers possessing sophisticated cold chain infrastructure.
Short-Acting Insulin Market Segmentation
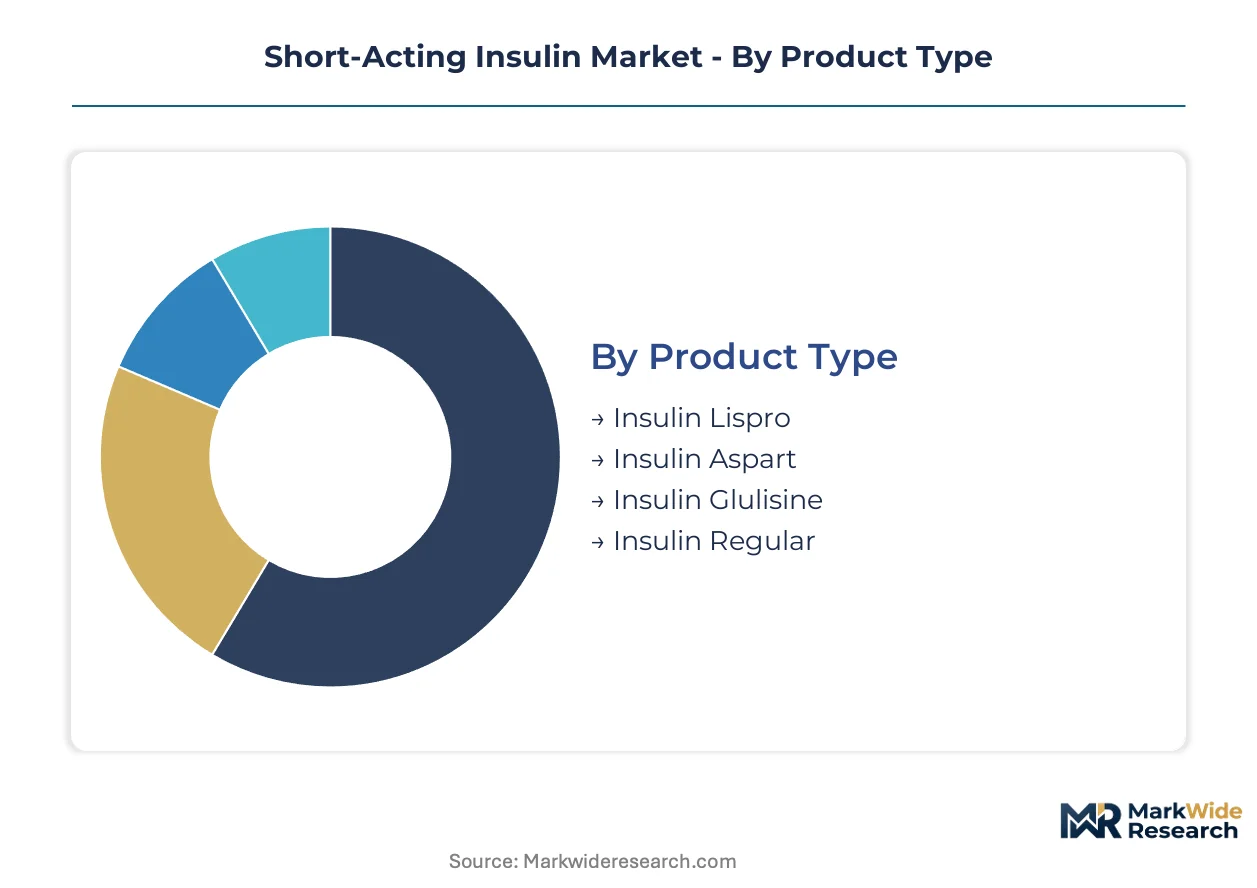
Segmentation in the short-acting insulin market reveals distinct procurement logics across therapeutic formulations, delivery technologies, care settings, and patient populations. Manufacturers must calibrate supply chain configurations and pricing architectures to serve these divergent demand profiles simultaneously.
Product Type:
Domestic manufacturing capacity for recombinant insulin analogs concentrates in Denmark, the United States, and France, while regular human insulin production serves export-heavy procurement in low- and middle-income markets through Indian and Chinese API suppliers.
- Insulin Lispro:Engineered through recombinant DNA technology with inverted amino acid sequence at B28-B29 positions to accelerate subcutaneous absorption. Demand clusters in US Medicare Part D and German statutory health insurance reimbursement tiers where rapid-acting analogs command premium formulary placement. FDA interchangeability designations for biosimilar versions are reshaping pharmacy substitution dynamics.
- Insulin Aspart:Aspartic acid substitution at B28 position enables faster onset than human insulin with 15-minute pre-meal dosing flexibility. Japanese PMDA-approved formulations and US hospital tender volumes drive concentrated procurement from Novo Nordisk's Danish manufacturing base. Cold chain distribution requirements limit penetration in tropical climate markets lacking refrigerated logistics infrastructure.
- Insulin Glulisine:Lysine and glutamic acid substitutions at B3 and B29 positions deliver rapid absorption profile with reduced intra-patient variability. Compact production scale relative to lispro and aspart analogs.
- Insulin Regular:Native human insulin sequence produced via recombinant technology in yeast or E. coli hosts. WHO Essential Medicines List procurement and emerging market government tenders anchor volume demand despite slower pharmacokinetic profile.
Insulin Lispro holds the largest share; momentum sits with Insulin Aspart in closed-loop pump integration.
Delivery Mode:
Cost tier differentiation separates premium pen formats from economy vial-syringe combinations, with reimbursement generosity determining format penetration across national health systems.
- Insulin Pen:Disposable and reusable cartridge systems with dose dialing mechanisms enable patient self-administration with reduced dosing error rates. German and Japanese reimbursement frameworks favor pen coverage for Type 1 diabetes intensive regimens. Bluetooth-enabled connected pens are capturing data subscription revenue in US commercial insurance plans.
- Vial & Syringe:Glass vial presentations with U-100 concentration require manual dose measurement and injection technique training. Hospital inpatient settings and US 340B drug pricing program procurement sustain volume despite patient convenience disadvantages.
- Insulin Pump:Continuous subcutaneous infusion devices with rapid-acting insulin reservoirs enable basal-bolus automation. US pediatric endocrinology practices and adult Type 1 diabetes populations with intensive glucose control targets drive adoption.
- Inhalable Insulin:Pulmonary delivery of powdered insulin formulations bypasses injection requirements. Restricted to US market following FDA approval with Risk Evaluation and Mitigation Strategy due to pulmonary safety surveillance requirements.
Insulin Pen dominates value capture; Vial & Syringe maintains volume leadership in institutional procurement.
End User:
Patient acuity and reimbursement structure create divergent service requirements across care settings, with homecare expansion forcing manufacturers to develop direct-to-patient fulfillment capabilities.
- Homecare Settings:Patient self-administration of basal-bolus regimens with pen or syringe formats. US mail-order pharmacy channels and German apotheken network direct distribution are displacing traditional wholesale models.
- Hospitals:Inpatient glycemic management protocols require rapid-acting insulin for sliding scale and correctional dosing. Consolidated procurement through group purchasing organizations concentrates volume with price-sensitive tender terms.
- Clinics:Outpatient endocrinology practices manage insulin initiation and dose titration. US Federally Qualified Health Centers and Japanese clinic-based diabetes care models anchor regional demand.
- Pharmacies:Retail dispensing of maintenance prescriptions with pharmacist counseling on storage and injection technique. US independent pharmacies and European pharmacy chains serve chronic therapy refill demand.
Hospitals command the largest procurement volumes; homecare settings are climbing the fastest as self-administration protocols expand.
Application:
Disease severity and treatment intensity determine per-patient insulin consumption rates, with Type 1 diabetes requiring comprehensive exogenous replacement driving highest annual volumes.
- Type 1 Diabetes:Absolute insulin deficiency requires intensive basal-bolus therapy with rapid-acting analogs for meal coverage. US, Germany, and Japan pediatric and adult populations with intensive glucose control targets concentrate premium product demand.
- Type 2 Diabetes:Progressive insulin deficiency managed with escalating therapy intensity. US Medicare population and emerging market urban diabetes burdens sustain human insulin volume despite analog penetration limits.
- Gestational Diabetes:Pregnancy-specific glucose management requiring rapid-acting insulin when dietary control fails. Maternal-fetal medicine protocols in US academic medical centers and European obstetric services drive limited but high-compliance demand.
- Others:Steroid-induced hyperglycemia, postsurgical glycemic control, and rare genetic diabetes forms requiring insulin therapy.
Type 1 Diabetes holds the largest share; Type 2 Diabetes represents the fastest-growing trajectory as disease prevalence expands and treatment intensification protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish fermentation facilities export rapid-acting insulin analogs to US Medicare channels and Japanese hospital systems, establishing a trans-Atlantic-Pacific trade corridor that concentrates finished dose supply among three manufacturing origins.
United States
Medicare Part D reimbursement tiers and commercial managed care formularies drive rapid-acting analog penetration above human insulin volumes. FDA interchangeability designations for biosimilar lispro products are reshaping pharmacy substitution authority across retail and mail-order channels. Indianapolis anchors domestic manufacturing scale for insulin lispro production serving North American demand.
Germany
Statutory health insurance coverage for pen-based intensive regimens amplifies per-patient consumption among Type 1 diabetes populations. EMA MDR quality system requirements for combination products extend development timelines for connected pen submissions. North Rhine-Westphalia hosts distribution hubs serving hospital tender consolidation across federal state procurement pools.
Japan
PMDA-approved insulin aspart formulations and pediatric endocrinology protocol intensification concentrate premium product demand. Ministry of Health, Labour and Welfare reimbursement frameworks favor rapid-acting analogs over human insulin in outpatient settings. Osaka-Kansai manufacturing clusters supply domestic hospital and clinic channels with cold chain distribution reach.
India
Government tender procurement for regular human insulin through WHO prequalification pathways sustains volume manufacturing for export to low-income markets. CDSCO manufacturing license requirements and PLI scheme incentives for biosimilar production are expanding domestic recombinant insulin capacity. Karnataka biotechnology corridors near Bangalore host fermentation facilities serving African and Southeast Asian procurement.
China
NMPA centralized procurement volume-based purchasing compresses rapid-acting analog pricing while expanding access coverage. Dual carbon goals and green manufacturing standards are reshaping bioprocess energy requirements for insulin crystal production. Yangtze River Delta pharmaceutical clusters concentrate API fermentation and finished dose formulation for domestic and export supply.
Short-Acting Insulin Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and regulatory dossier depth, creating a tiered structure where public company R&D intensity contrasts with private label cost positioning. The vendor base stratifies around three strategic archetypes: integrated fermentation-to-finished-dose operators, API-focused bulk suppliers, and delivery device specialists. Capacity expansion in single-use bioreactor infrastructure and strategic partnerships for cold chain distribution represent the dominant competitive moves reshaping supply security.
Within the integrated manufacturing tier, Novo Nordisk and Eli Lilly and Company exemplify archetypes of fermentation-scale dominance and delivery format innovation respectively. Sanofi occupies a position bridging European hospital tender access with emerging market distribution reach. Biocon Limited represents the biosimilar-focused specialist archetype, anchoring cost-competitive supply for price-sensitive procurement environments.
| Leading Market Players |
|---|
| Sanofi |
| Novo Nordisk |
| Eli Lilly and Company |
| Biocon Limited |
| Pfizer |
| Wockhardt Ltd. |
| Baxter International |
| Lupin Limited |
| MannKind Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day cold chain inventory cycles anchor insulin pricing power to refrigerated logistics capacity rather than manufacturing cost alone, concentrating margin capture with operators possessing multi-temperature-zone distribution networks across Denmark, the United States, and Japan.
Pricing Analysis
Next-generation ultra-rapid formulations command reimbursement premiums over first-generation rapid-acting analogs, while regular human insulin occupies the economy tier in WHO Essential Medicines List procurement. Three-tier pricing structure across premium analog, standard rapid-acting, and economy human insulin levels reflects pharmacokinetic performance differentiation and patent status. Cost compression in the human insulin tier intensifies because Indian and Chinese API suppliers compete on volume tenders for African and Southeast Asian markets. Government procurement offices in low-income countries exhibit highest price sensitivity, while US commercial insurance plans and German statutory health insurance demonstrate lowest sensitivity due to bundled device coverage.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore hubs elevates inbound logistics costs for temperature-sensitive insulin API shipments originating from Danish and Chinese fermentation facilities. Manufacturing concentrates in Denmark, the United States, and China, with formulation finishing distributed across France, India, and Japan. Bulk insulin crystal production draws from recombinant DNA fermentation in yeast or E. coli hosts, with single-use bioreactor adoption compressing batch timelines. Single-source vulnerability permeates the API tier where three specialized fermentation facilities supply global finished dose manufacturers. Distribution runs through cold chain logistics providers serving hospital GPOs, retail pharmacy networks, and direct-to-patient mail-order channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as post-pandemic hospital procurement normalization restores tender volumes and patient visit rates rebound to pre-disruption baselines.
For Market Incumbents: Secure fermentation capacity expansion in single-use bioreactor infrastructure to capture biosimilar substitution volumes as FDA interchangeability designations accelerate pharmacy-level switching. Anchor backward integration into API crystal production to reduce exposure to Danish and Chinese bulk supply concentration. Defend against connected pen ecosystem disruption by accelerating Bluetooth-enabled device submissions under EMA MDR quality system pathways.
For New Entrants and Emerging Players: Lead with biosimilar rapid-acting analog filings targeting US Medicare Part D and German statutory health insurance reimbursement tiers where reference product pricing creates accessible entry points. Penetrate the prefilled syringe format segment for emergency department and inpatient settings where nursing time reduction drives procurement preference. Pursue hospital system partnership models with ready-to-administer presentations to bypass established pen-format incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting diabetes portfolios amid strategic refocusing toward oncology and immunology assets. Long-term viability centers on manufacturing scale and regulatory dossier depth rather than single-product innovation cycles. Watch for FDA interchangeability designation velocity as the inflection signal determining biosimilar volume capture rates and incumbent pricing defense effectiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Connected Pen Ecosystem Development | Bluetooth-enabled dose capture paired with glucose monitoring apps opens subscription revenue streams beyond drug sales in US and German reimbursement environments. |
| EMA MDR Quality System Harmonization | Streamlined conformity assessment procedures for combination products reduce time-to-market for pen-injector innovations across EU member states. |
| Prefilled Syringe Format Expansion | Ready-to-administer presentations reduce nursing medication preparation time and dosing error rates in emergency department and inpatient settings. |
| Single-Use Bioreactor Scale-Up | Adoption compresses batch cycle times for insulin lispro and aspart production, improving yield economics for high-volume analog supply. |
| Direct-to-Patient Pharmacy Fulfillment | Mail-order and specialty pharmacy channels capture chronic therapy volumes previously routed through retail storefronts in US Medicare Part D plans. |
Research Methodology
A spread of perspectives from endocrinology practice directors, hospital procurement managers, regulatory affairs specialists, and pharmacy benefit managers converged on the working assumptions driving volume and value estimates. Primary field engagement with formulary directors and GPO contract administrators combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored the analytical framework.
Segmentation dimensions modeled span insulin analog type, delivery device format, care setting, and patient population severity across the projection horizon. Analytical framework approach incorporates treatment line progression, dosage intensity by diabetes type, administration route preference, and regional regulatory cluster differentiation. CAGRs were derived from patient volume growth trajectories and per-patient consumption intensity trends. Forecast inputs include biosimilar substitution elasticity coefficients and cold chain logistics cost escalation assumptions.
The analysis sits within stated boundaries; outcomes outside stable FDA interchangeability designation velocity, sustained cold chain infrastructure investment, and consistent WHO prequalification pathway access would require recalibration. Forecasts reflect documented assumptions regarding patient population growth, treatment intensification protocol adoption, and reimbursement framework stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Motilium Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
Congestive Heart Failure Drugs Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market