
 Betahistine Mesilate Market | 2026-2036
Betahistine Mesilate Market Size, Share, and Industry Trends Forecast 2026-2036
Betahistine Mesilate Market Insights
Hospital procurement consolidation is expanding across European and Asian healthcare systems, concentrating purchasing power among integrated delivery networks. Sandoz International GmbH leverages its generic manufacturing scale to serve these consolidated buyers across Germany and France. Cipla Limited anchors its position through cost-efficient tablet production targeting price-sensitive hospital formularies in emerging markets. Wockhardt Ltd. specializes in injectable formats that differentiate its portfolio for acute vertigo episodes in emergency departments.
Betahistine mesilate, the dimethanesulfonate salt of betahistine with molecular formula C8H12N2·2CH4O3S, functions as a histamine H1-receptor agonist and H3-receptor antagonist that improves cochlear microcirculation. Manufacturers synthesize it through controlled salt formation of the free base with methanesulfonic acid, yielding a crystalline solid with superior stability over the dihydrochloride form. Tablet formulations dominate current revenue pools due to established oral bioavailability and decades of clinical familiarity in Meniere's disease management, while injectable delivery modes capture premium positioning for acute vestibular crisis intervention. Homecare end users represent the fastest-expanding channel as post-pandemic reimbursement frameworks extend supervised self-administration programs.
EMA's centralized marketing authorization procedures govern quality standards for betahistine mesilate products distributed across EU member states, while Japan's PMDA applies distinct pharmacovigilance requirements that shape post-approval study commitments. India's CDSCO mandates bioequivalence documentation for generic entrants that influences competitive timelines for domestic manufacturers. Stakeholders must monitor evolving histamine-receptor modulator guidelines from WHO expert committees that could recategorize therapeutic indications or dosing protocols.
Market Dynamics
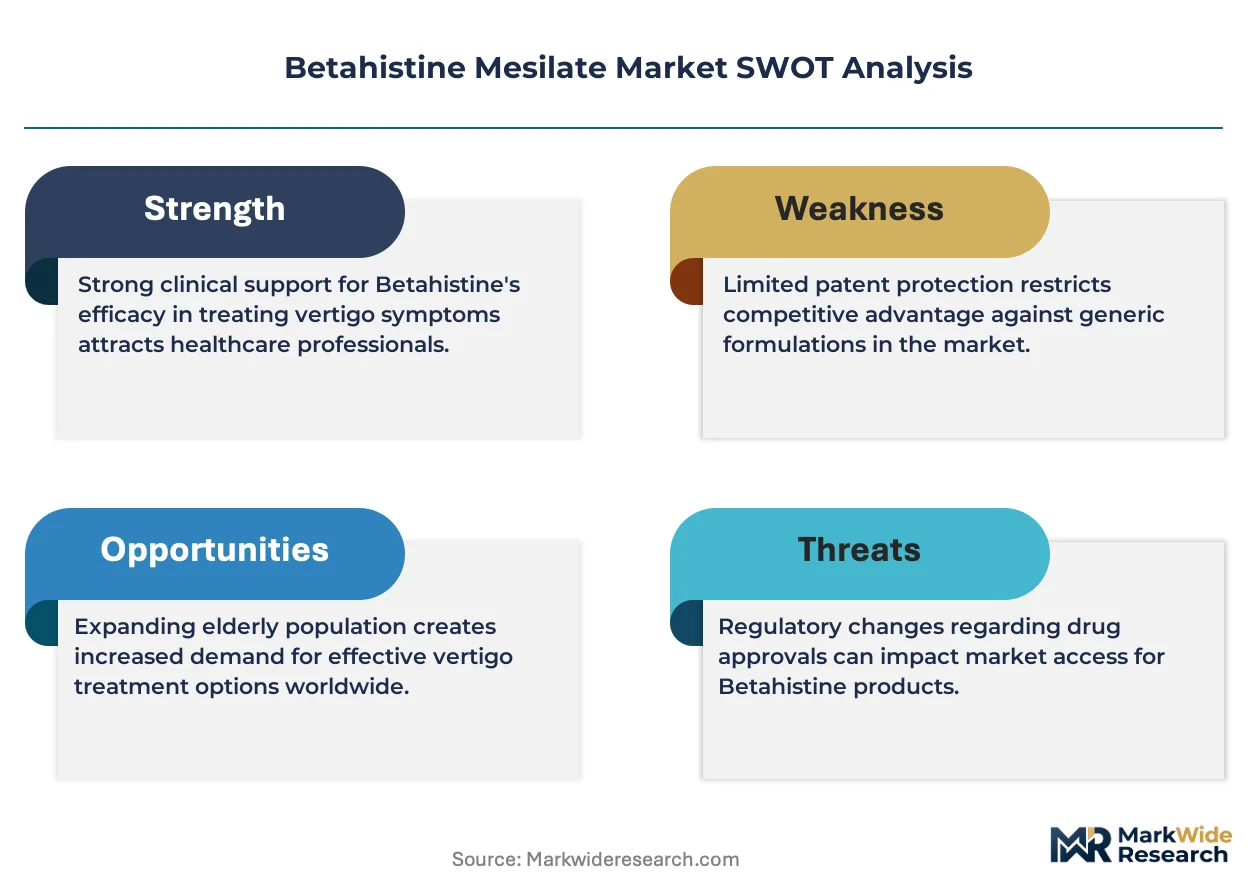
Hospital procurement consolidation across Germany, France, and Japan is compressing supplier margins while elevating quality and volume requirements for betahistine mesilate manufacturers serving integrated delivery networks.
Growth Catalysts
- EMA Centralized Authorization:Streamlined quality standards accelerate cross-border distribution for compliant manufacturers across EU member states.
- Japan PMDA Orphan Incentives:Extended exclusivity periods and tax credits stimulate domestic production investment for Meniere's disease therapeutics.
- Homecare Channel Expansion:Post-pandemic reimbursement frameworks in Germany extend supervised self-administration programs beyond hospital settings.
Market Restraints
- API Supply Concentration:Dependence on Indian and Chinese active pharmaceutical ingredient suppliers exposes formulators to geopolitical disruption and customs delays.
- Dihydrochloride Substitution:Generic betahistine dihydrochloride tablets at lower price points capture cost-sensitive hospital formulary slots.
- Bioequivalence Documentation Burden:India's CDSCO mandates extensive pharmacokinetic studies that extend generic entry timelines by 18-24 months.
Strategic Opportunities
- Emergency Department Injectable Demand:Acute vestibular crisis intervention protocols in French and Japanese hospitals favor rapid-onset parenteral formats.
- WHO Histamine Modulator Guidelines:Pending therapeutic recategorization could expand approved indications beyond Meniere's disease into broader vertigo classifications.
- Direct-to-Pharmacy Distribution:Bypassing wholesale intermediaries in Germany reduces margin leakage for manufacturers with cold-chain capabilities.
Industry Challenges
- Formulation Stability Expertise Gap:Methanesulfonate salt crystallization requires specialized process chemists scarce in emerging market manufacturing hubs.
- Cross-Border Pharmacovigilance Harmonization:Divergent adverse event reporting timelines between EMA and PMDA strain centralized safety database management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Betahistine Mesilate Market |
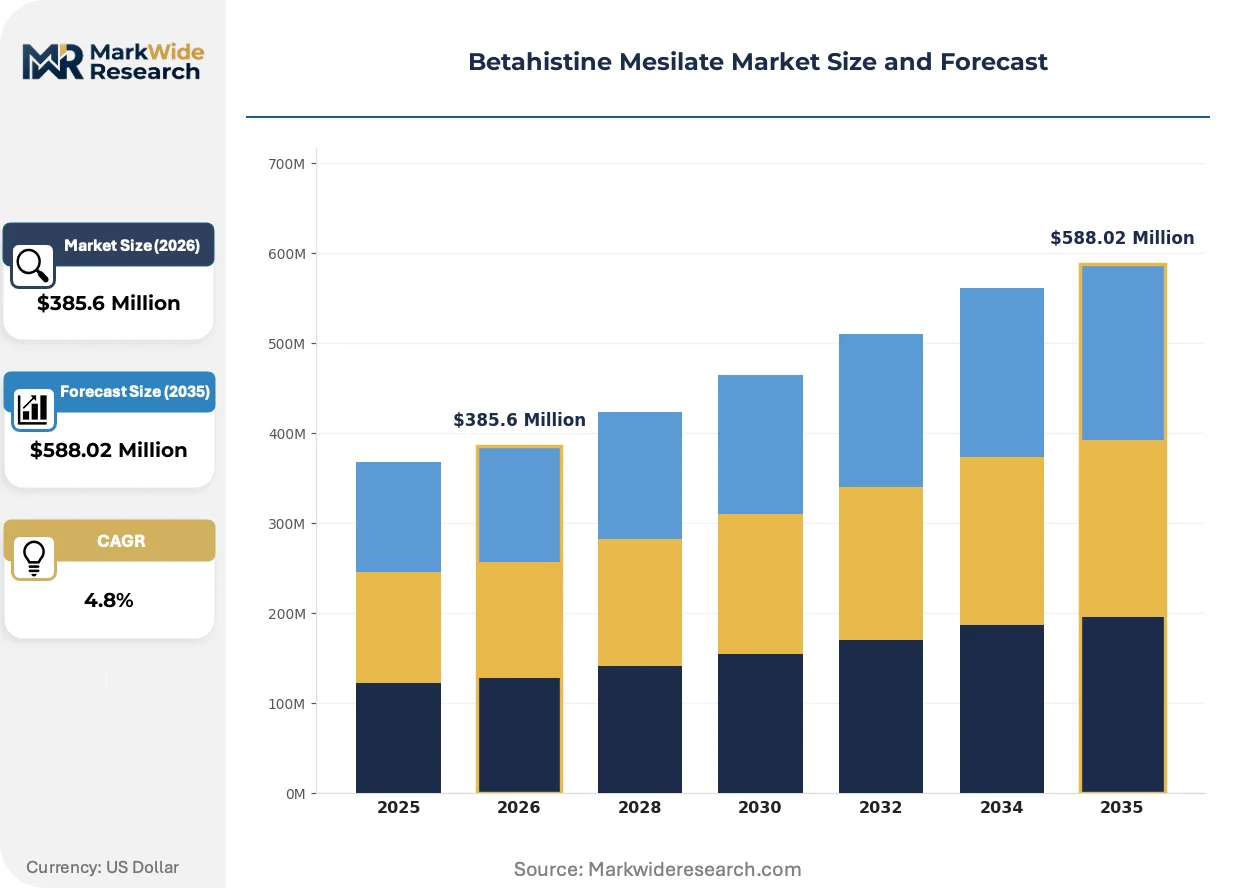
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Suspension, Injectable Therapy Area: Meniere's Disease, Vertigo, Tinnitus, Motion Sickness Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | Laboratoires KAD, Pfrimmer Nutra, Lannett Company, LGT Pharmaceutical, Lebsa, Apotex Inc., Sandoz International GmbH, Wockhardt Ltd., Cipla Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Betahistine Mesilate Market Trends and Innovations
Continuous manufacturing technologies and real-world evidence requirements are restructuring how betahistine mesilate suppliers validate quality, engage regulators, and capture hospital contracts across Europe and Asia-Pacific.
Controlled-release tablet matrices incorporating hydroxypropyl methylcellulose and polymethacrylate copolymers extend plasma concentration profiles from 3-4 hours to 8-12 hours. German hospital pharmacies are adopting these modified-release formats for outpatient vertigo management protocols. This extended-duration technology is unifying once-daily dosing convenience with established efficacy profiles, compressing the competitive advantage of twice-daily conventional tablets.
EMA's updated Good Manufacturing Practice Annex 1 requirements for sterile medicinal products impose enhanced environmental monitoring and barrier technology mandates on injectable betahistine mesilate production facilities. Manufacturers must retrofit filling lines with isolator technology or risk withdrawal of manufacturing authorizations. French and Italian contract development organizations are absorbing the capital burden through shared facility models, enabling mid-tier entrants to maintain compliance without captive infrastructure investment.
Hospital procurement committees in Japan are unbundling pharmaceutical purchasing from logistics services, awarding separate contracts to specialized cold-chain distributors with temperature-verified last-mile capabilities. This disintermediation separates product margin from distribution margin, forcing manufacturers to renegotiate net pricing with pharmacy benefit managers while ceding logistics relationships to third-party specialists. The restructuring is most visible in Tokyo and Osaka metropolitan hospital networks where consolidated purchasing volumes exceed regional tenders.
Betahistine Mesilate Market Segmentation
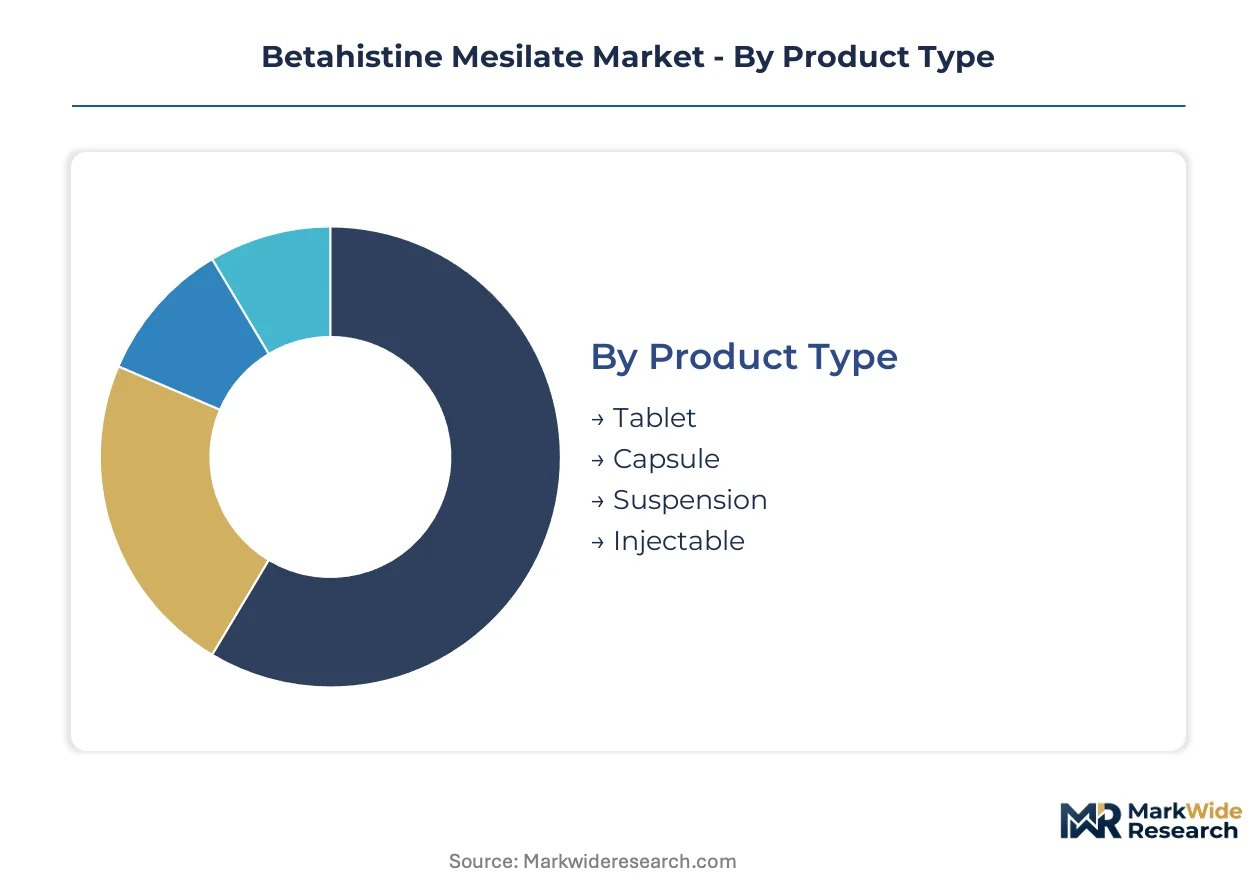
Betahistine mesilate formulations span distinct regulatory pathways and clinical settings. Each segment carries specific EMA, PMDA, or CDSCO documentation requirements that shape manufacturer investment priorities and competitive positioning.
Product Type:
Tablet formats require bioequivalence dossiers under EMA centralized procedures, while injectables demand sterile manufacturing annex compliance that extends approval timelines by 18-24 months.
- Tablet:Compressed solid dosage containing betahistine mesilate with established dissolution profiles. German hospital formularies in Bavaria and North Rhine-Westphalia prioritize these for outpatient Meniere's protocols due to reimbursement clarity.
- Injectable:Sterile parenteral solution for acute vestibular crisis intervention. French emergency departments in Paris and Lyon specify this format for rapid histamine receptor modulation in severe vertigo episodes.
- Capsule:Gelatin-encapsulated powder offering taste masking and modified release potential. Japanese geriatric clinics favor these for patients with tablet dysphagia.
- Suspension:Liquid oral formulation enabling dose titration in pediatric or elderly populations. Indian CDSCO requires additional stability data for these non-solid formats.
Leading the category by volume: Tablet. Growing fastest: Injectable.
Therapy Area:
Meniere's disease claims command premium reimbursement rates, while vertigo indications face tighter prior authorization requirements in Japanese metropolitan hospital networks.
- Meniere's Disease:Inner ear disorder characterized by episodic vertigo, tinnitus, and sensorineural hearing loss. EMA guidelines specifically endorse betahistine mesilate as first-line therapy, securing favorable formulary placement across EU member states.
- Vertigo:General vestibular dysfunction spanning peripheral and central etiologies. Acute intervention protocols in Osaka and Tokyo hospitals drive demand for rapid-onset formulations in this broader indication category.
- Tinnitus:Persistent auditory perception without external stimulus. Off-label utilization in German ENT clinics generates supplementary prescription volume beyond core vertigo indications.
- Motion Sickness:Vestibular disturbance triggered by movement. Maritime and aviation medicine specialists in Marseille and Hamburg prescribe for occupational prophylaxis in high-exposure professions.
Volume concentrates in Meniere's Disease. Steepest expansion trajectory: Vertigo applications in acute care settings.
Delivery Mode:
Oral administration dominates maintenance therapy, while parenteral routes capture crisis intervention premiums in tertiary hospital settings.
- Oral:Swallowed tablet or liquid formulations processed through hepatic first-pass metabolism. Homecare programs in Germany's Baden-Württemberg region extend supervised oral self-administration beyond traditional hospital boundaries.
- Intravenous:Direct vascular delivery achieving immediate systemic bioavailability. Japanese university hospitals in Kyoto and Kobe specify IV protocols for intractable vestibular episodes refractory to oral loading.
- Intramuscular:Depot injection into skeletal muscle for sustained absorption. French rural clinics utilize IM administration when vascular access proves difficult in elderly vertigo patients.
- Subcutaneous:Tissue plane delivery offering patient self-administration potential. Emerging format for outpatient vestibular rehabilitation programs in selected German pilot sites.
Oral delivery commands the largest prescription base. Intravenous formats are climbing the fastest as emergency department protocols expand.
End User:
Hospital procurement committees exert pricing leverage through volume consolidation, while homecare channels escape traditional wholesale markups.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees. Germany's Charité and France's AP-HP systems negotiate multi-year supply agreements that compress supplier margins in exchange for volume guarantees.
- Homecare:Supervised self-administration programs with remote monitoring components. Post-pandemic reimbursement frameworks in Japan's Kanto region accelerate this channel's displacement of institutional care.
- Clinics:Outpatient specialty practices in otolaryngology and neurology. Indian metro clinic chains in Mumbai and Delhi purchase through direct-manufacturer arrangements bypassing distributor tiers.
- Pharmacies:Community and hospital outpatient dispensaries. German Einzelhandel pharmacies face margin pressure from mail-order competitors in the vertigo therapeutic category.
Hospitals retain the dominant procurement position. Homecare is gaining share fastest as reimbursement shifts favor decentralized care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, France, and Japan concentrate the bulk of betahistine mesilate demand through multi-year supply agreements. EMA centralized authorization and Japan's PMDA orphan drug incentives reshape reimbursement pathways across these markets.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia sustain prescription volumes for Meniere's disease management. EMA centralized marketing authorization procedures govern quality standards for products distributed across EU member states. Charité Berlin and university hospitals in Munich negotiate consolidated purchasing agreements that compress supplier margins.
France
Emergency departments in Paris and Lyon specify injectable formats for acute vestibular crisis intervention protocols. ANSM pharmacovigilance requirements shape post-approval study commitments for manufacturers. Hospital procurement consolidation across AP-HP systems elevates volume requirements for integrated delivery networks.
Japan
PMDA orphan drug incentives including extended exclusivity periods stimulate domestic production investment. Tokyo and Osaka metropolitan hospital networks unbundle pharmaceutical purchasing from logistics services. Kanto region post-pandemic reimbursement frameworks accelerate homecare channel displacement of institutional care.
India
CDSCO bioequivalence documentation mandates extend generic entry timelines by 18-24 months for domestic manufacturers. Mumbai and Delhi metro clinic chains purchase through direct-manufacturer arrangements bypassing distributor tiers. API supply concentration exposes formulators to customs delays at major ports.
United Kingdom
NHS England integrated care systems consolidate vertigo therapeutic purchasing across regional pharmacy and therapeutics committees. MHRA recognition of EMA centralized procedures streamlines cross-border distribution for compliant suppliers. London and Southeast England otolaryngology clinics generate supplementary prescription volume for off-label tinnitus applications.
Betahistine Mesilate Market Competitive Landscape
European producers anchor one tier of the betahistine mesilate supply base; Indian specialists hold cost-efficient manufacturing positions for emerging market penetration. The market structure reflects moderate consolidation among generic pharmaceutical manufacturers with established histamine-receptor modulator portfolios. Three strategic archetypes dominate: multinational generics divisions with hospital contracting scale, mid-tier injectable specialists, and domestic API-integrated formulators. Competitive moves center on sterile manufacturing facility upgrades and direct-to-pharmacy distribution partnerships.
Within the multinational generics tier, Sandoz International GmbH and Cipla Limited exemplify manufacturers leveraging established regulatory dossiers across EMA and CDSCO jurisdictions. Wockhardt Ltd. occupies a position among injectable format specialists targeting emergency department procurement channels. These three anchors represent distinct geographic and format specializations without overlapping core positioning.
| Leading Market Players |
|---|
| Laboratoires KAD |
| Pfrimmer Nutra |
| Lannett Company |
| LGT Pharmaceutical |
| Lebsa |
| Apotex Inc. |
| Sandoz International GmbH |
| Wockhardt Ltd. |
| Cipla Limited |
| Others |
Pricing and Supply Chain Analysis
Controlled-release tablet matrices incorporating hydroxypropyl methylcellulose and polymethacrylate copolymers are simultaneously elevating manufacturing complexity and concentrating production among German and Japanese facilities with specialized coating capabilities. This technology transition compresses cost economics for conventional twice-daily formats while rewarding early movers with isolator-equipped sterile lines for injectable premium positioning.
Pricing Analysis
Volume concentrates in oral tablet formats while margins accrue to injectable presentations for emergency department procurement. Three-tier pricing structure across premium, standard, and economy levels separates isolator-certified sterile injectables from conventional tablets and commodity dihydrochloride substitutes. Cost compression in the tablet tier is intensifying because Indian and Chinese API suppliers face customs documentation burdens at European ports. Hospital procurement committees in Germany and France exhibit the highest price sensitivity, while Japanese emergency departments demonstrate lowest sensitivity due to protocol-driven formulary lock-in.
Supply Chain Analysis
Methanesulfonic acid feedstock rests on German and Japanese specialty chemical producers with batch-scale pharmaceutical-grade certification. Active pharmaceutical ingredient synthesis draws from Indian and Chinese contract manufacturers, while finished dose formulating concentrates in Germany, France, and Japan. Single-source vulnerability permeates the methanesulfonate salt crystallization step where specialized process chemists remain scarce. Distribution runs through hospital procurement committees in consolidated integrated delivery networks, with direct-to-pharmacy bypass emerging in Bavaria and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing technologies are displacing batch processing in betahistine mesilate production, rewarding capital-intensive facility upgrades while marginalizing legacy equipment operators.
For Market Incumbents: Cement formulary positioning through isolator technology retrofitting at sterile injectable lines, defending against mid-tier entrants utilizing shared French and Italian contract manufacturing facilities. Backward integration into methanesulfonic acid supply secures margin control against specialty chemical price volatility. For New Entrants and Emerging Players: Hospital pharmacy benefit managers represent the most accessible channel partnership for bypassing wholesale markups in Germany's direct-to-pharmacy pilot regions. White-space concentrates in subcutaneous formulations for outpatient vestibular rehabilitation and suspension formats for pediatric dose titration. Target acquisition of CDSCO-approved manufacturing assets to compress bioequivalence documentation timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational generics divisions seeking EMA centralized authorization dossiers. Long-term viability hinges on therapeutic expansion beyond Meniere's disease into broader vertigo classifications pending WHO histamine modulator guideline revision. Watch PMDA orphan drug exclusivity period announcements as inflection signals for Japanese domestic production valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Retrofit | EMA Annex 1 compliance secures manufacturing authorization for sterile injectable formats. |
| Direct-to-Pharmacy Distribution | Bypassing wholesale intermediaries in Germany recaptures margin leakage for cold-chain-capable manufacturers. |
| CDSCO Manufacturing Asset Acquisition | Approved facilities accelerate generic entry timelines by 18-24 months through existing bioequivalence dossiers. |
| Controlled-Release Formulation Development | Hydroxypropyl methylcellulose matrices extend plasma profiles to 8-12 hours for once-daily dosing convenience. |
| PMDA Orphan Drug Application | Extended exclusivity periods and tax credits stimulate domestic Japanese production investment. |
Research Methodology
Document review covered EMA centralized marketing authorization procedures, PMDA orphan drug incentive frameworks, and CDSCO bioequivalence guidelines, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from FDA filings, ClinicalTrials.gov protocol registries, hospital procurement databases, and GPO contract repositories. Bottom-up prescription volume modeling triangulated against top-down therapeutic category expenditure analysis.
Historical volume trajectories cross-referenced against expert panel input on reimbursement framework shifts across Germany, France, and Japan. Segmentation dimensions spanned product type, therapy area, delivery mode, and end-user channel across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating aging demographic projections and regulatory exclusivity period assumptions. Industry-specific inputs included EMA Good Manufacturing Practice Annex 1 compliance timelines and PMDA pharmacovigilance study commitments.
Caveats apply where WHO histamine-receptor modulator guideline revision or EMA therapeutic recategorization could materially shift the outlook beyond Meniere's disease indications. API supply disruption at Indian or Chinese ports, PMDA exclusivity period modifications, and hospital procurement consolidation acceleration represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Global Meningitis Vaccine Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Multiple Myeloma Drugs Market