
 Global Pharmaceutical Contract Manufacturing Market | 2026-2036
Global Pharmaceutical Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Contract Manufacturing Market Intelligence
Quality control and analytical testing as a bundled service layer is pivoting contract manufacturing relationships from transactional production runs toward integrated partnership models. Lonza leverages its biologics network to sustain long-term supply agreements with major drug developers. Catalent anchors North American capacity through multi-product facilities designed for complex sterile formulations. Samsung Biologics competes aggressively on manufacturing scale, positioning itself as the dominant mammalian cell culture provider in Asia.
Pharmaceutical contract manufacturing encompasses the outsourced production of drug substances and finished dosage forms under formal agreements between sponsors and specialized production entities, typically requiring aseptic processing capabilities, validated cleanroom environments, and batch release documentation compliant with pharmacopeial standards. The primary purpose centers on converting active pharmaceutical ingredients into market-ready therapeutics while transferring capital intensity and regulatory liability from sponsor to service provider. Biologics manufacturing commands premium pricing due to cell-line complexity and cold-chain requirements, while small molecule oral dosage forms represent the mature volume base where margin pools have compressed. Formulation development services attract growing investment as sponsors seek to accelerate preclinical-to-clinical transitions without building internal capabilities.
FDA inspections, EMA GMP certifications, and ISO 13485 quality management standards collectively determine market access and customer eligibility for contract manufacturers serving regulated markets. Compliance costs have risen substantially as both agencies intensify data integrity enforcement and demand continuous process verification for biologics. Stakeholders must monitor evolving biosimilar guidance from FDA and EMA, as these pathways will reshape capacity allocation decisions across mammalian and microbial expression systems.
Market Dynamics
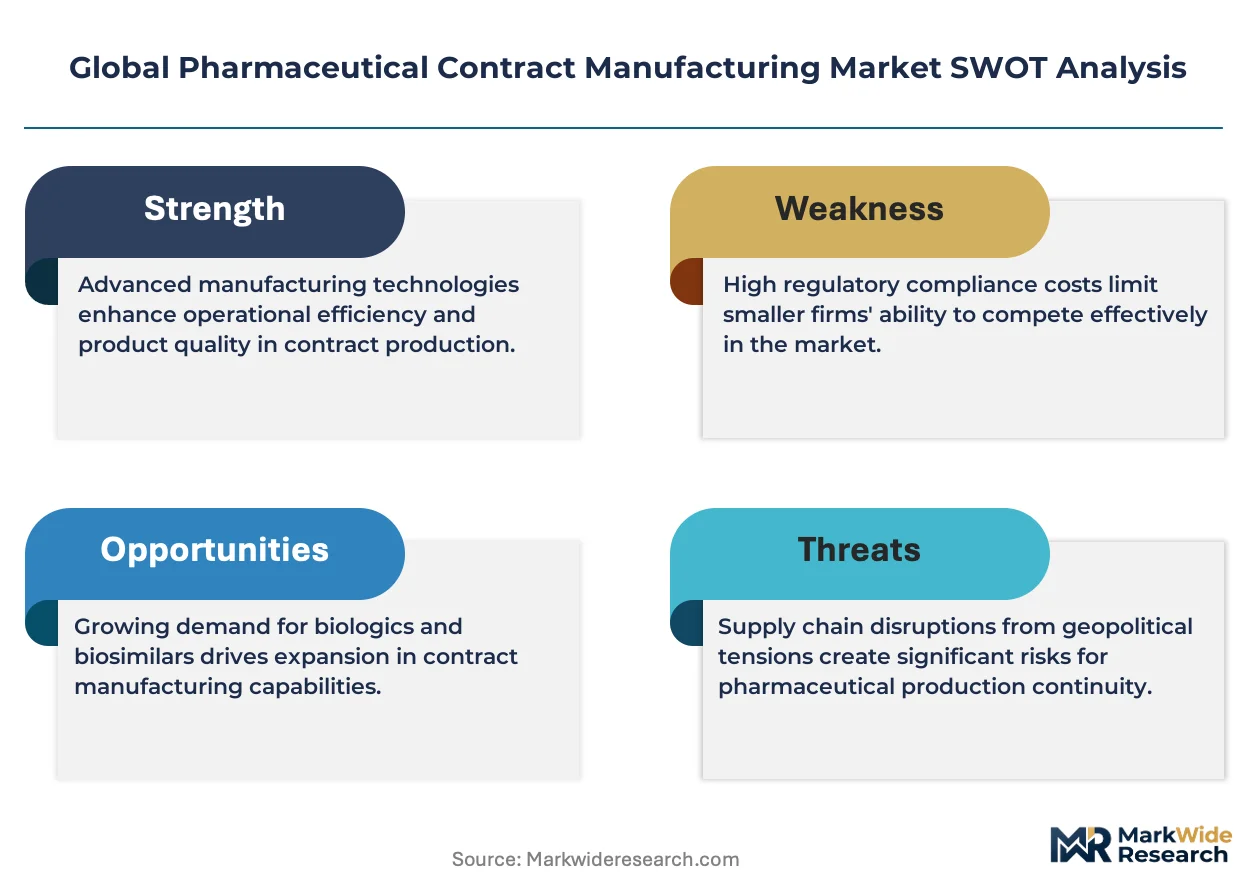
Biologics manufacturing complexity is forcing sponsors to externalize capacity investments, converting fixed-cost facilities into variable operating expenses while transferring regulatory liability to specialized operators.
Growth Catalysts
- FDA Quality-by-Design Framework:The agency's QbD mandate for continuous process verification drives sponsors toward contract partners with validated analytical platforms and established design-space documentation.
- Cell Therapy Commercialization:Autologous and allogeneic cell therapy developers lack scalable manufacturing infrastructure, creating pull for CDMOs with flexible cleanroom suites and cryogenic logistics capabilities.
- Switzerland Biologics Cluster:Concentration of Big Pharma headquarters and specialized manufacturing infrastructure in Basel-Zurich corridor attracts sponsor investment and talent migration.
Market Restraints
- Single-Use Component Supply:Reliance on specialized bioprocess bags and connectors from limited polymer suppliers creates input cost volatility and allocation risk during demand surges.
- EMA GMP Certification Backlogs:Extended inspection timelines for sterile injectable facilities delay facility qualification and revenue recognition for European-market-bound production.
- Plasmid DNA Bottlenecks:Viral vector manufacturing depends on scarce qualified plasmid suppliers, constraining gene therapy program expansion regardless of available bioreactor capacity.
Strategic Opportunities
- South Korea Regulatory Fast-Track:MFDS accelerated approval pathways for innovative biologics position Korean CDMOs as launch partners for Asia-Pacific market entry strategies.
- Integrated Drug-Device Combination:Convergence of prefilled syringe manufacturing with biologics fill-finish creates service bundling opportunities beyond standalone drug substance production.
- India Biosimilar Export:CDSCO streamlined biosimilar guidelines and WHO prequalification momentum open capacity for emerging market supply at cost-advantaged scale.
Industry Challenges
- Advanced Therapy Manufacturing Scientists:Shortage of professionals trained in cell culture, viral vector production, and aseptic processing limits facility utilization rates and batch success ratios.
- Multi-Product Facility Qualification:Campaign changeover validation and cleaning verification requirements extend downtime between biologics programs, compressing effective capacity yield.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Contract Manufacturing Market |
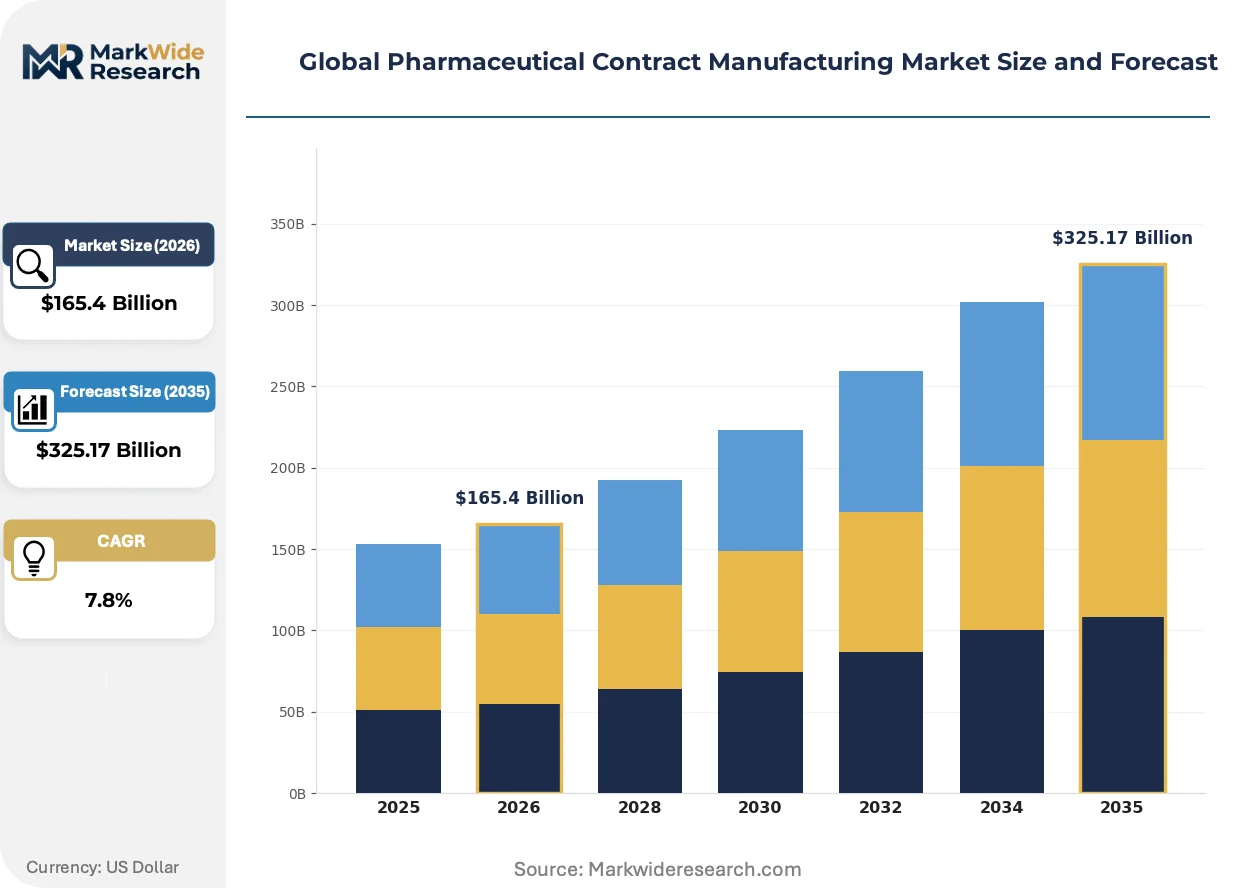
| Market Size in 2026 | $165.4 Billion |
| Market Size in 2035 | $325.17 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pharmaceutical Ingredients, Biologics, Small Molecules, Oral Dosage Forms Service Type: Formulation Development, Packaging Services, Quality Control, Analytical Testing End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases |
| Companies Covered | Lonza, Catalent, Thermo Fisher Scientific, Samsung Biologics, WuXi AppTec, Boehringer Ingelheim, Recipharm, Merck KGaA, CordenPharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Contract Manufacturing Market Strategic Shifts & Innovations
Continuous processing architectures and modular facility designs are compressing batch cycle times while enabling rapid product switches that static stainless-steel infrastructure cannot match.
Single-use bioreactor technology is absorbing capital deployment that previously flowed into fixed equipment installations. Mid-size biotechnology sponsors are adopting 2,000-liter disposable systems for Phase III commercial readiness without committing to dedicated facility construction. This absorption pattern is fragmenting large-scale capacity ownership across multiple regional operators rather than concentrating it with integrated pharmaceutical majors.
EMA's revised Annex 1 GMP guidelines for sterile medicinal products impose stricter environmental monitoring and contamination control requirements. Manufacturers must implement enhanced barrier technology and rapid microbial detection systems to maintain compliance. Fill-finish operators serving European markets are prioritizing isolator-based lines and closed-system processing to meet the 2023 implementation deadlines without production interruption.
Sponsor buying patterns are consolidating supplier relationships around full-service CDMOs capable of drug substance, drug product, and packaging within unified quality systems. Early-stage biotechnology companies are abandoning fragmented multi-vendor sourcing in favor of integrated program management from preclinical through commercial supply. This consolidation is most pronounced among US-based sponsors seeking to reduce regulatory interface complexity and accelerate IND-to-BLA timelines.
Global Pharmaceutical Contract Manufacturing Market Segmentation
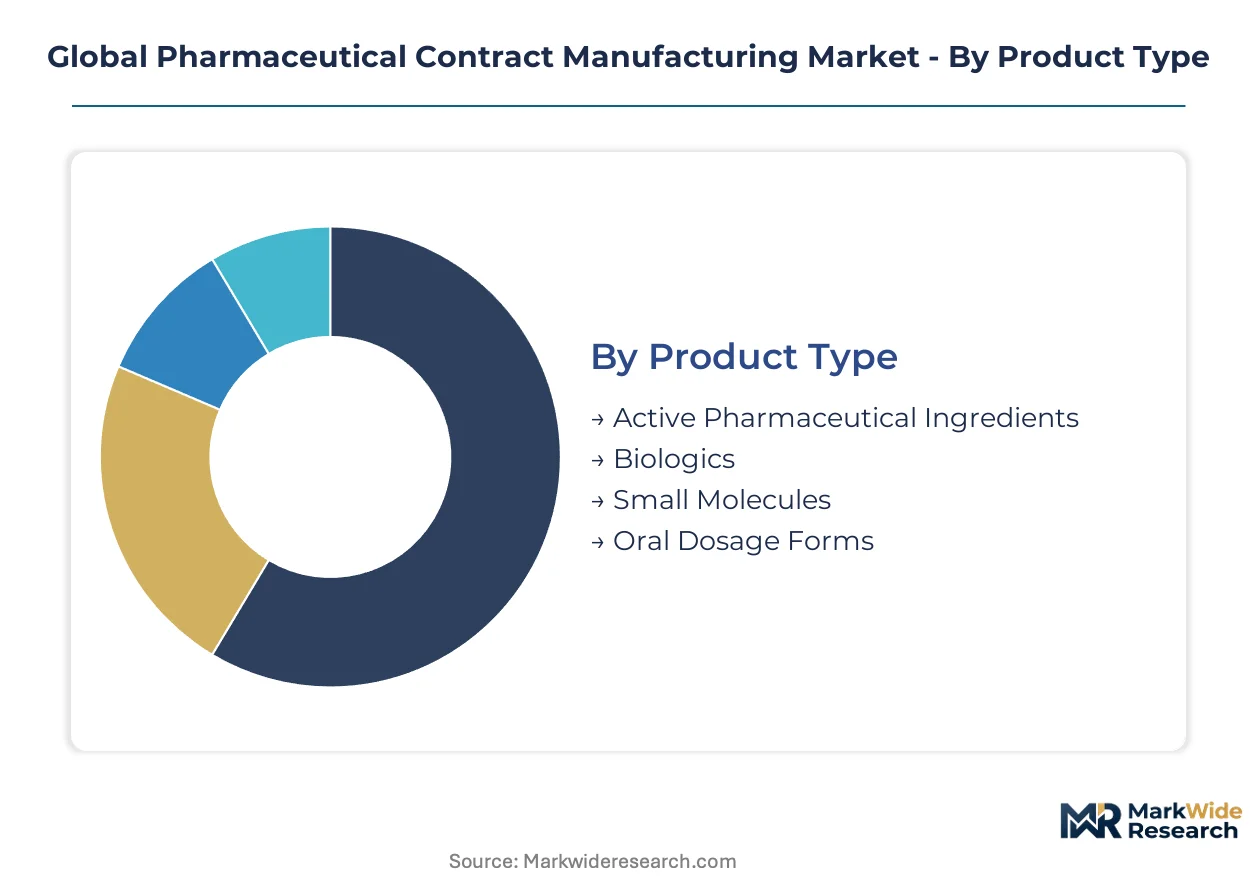
Segmentation in pharmaceutical contract manufacturing reveals how regulatory burden, technical complexity, and sponsor maturity stratify outsourcing decisions across distinct service layers. Each category maps to specific FDA, EMA, and MFDS certification requirements that determine market access eligibility.
Product Type:
Biologics demand FDA process validation and EMA Annex 1 compliance, while small molecules face abbreviated new drug application pathways with lighter ongoing inspection frequency.
- Active Pharmaceutical Ingredients:Chemical synthesis and fermentation-based production of drug substances requires dedicated containment infrastructure and occupational exposure band certification. Demand concentrates among US-based generics manufacturers seeking to offset capital intensity through toll manufacturing arrangements with Indian and Chinese suppliers.
- Biologics:Mammalian and microbial cell culture systems producing monoclonal antibodies, vaccines, and recombinant proteins command premium pricing due to cold-chain requirements and biosafety level containment. Switzerland and South Korea host the dominant manufacturing clusters as Big Pharma headquarters proximity and MFDS fast-track pathways attract sponsor investment.
- Small Molecules:Synthetic organic chemistry routes to oral and parenteral drugs represent the mature volume base with compressed margins.
- Oral Dosage Forms:Tablet and capsule manufacturing requires less specialized infrastructure than sterile injectables.
Small molecules sit at the top of the volume ranking, with biologics climbing the fastest.
Service Type:
Cost tier stratification separates high-investment analytical capabilities from commoditized packaging operations that compete on throughput efficiency.
- Formulation Development:Preclinical-to-clinical transition services including solubility enhancement, stability testing, and dosage form selection absorb growing sponsor investment as biotechnology firms seek to accelerate IND timelines without building internal capabilities. Demand concentrates among early-stage companies in Boston and San Francisco biotechnology corridors.
- Quality Control:Batch release testing, environmental monitoring, and method validation functions bundled with manufacturing contracts are pivoting relationships from transactional production runs toward integrated partnership models. FDA data integrity enforcement and continuous process verification mandates drive sponsors toward partners with validated analytical platforms.
- Packaging Services:Primary and secondary packaging with serialization for track-and-trace compliance operates at lower margin pools.
- Analytical Testing:Characterization services for identity, purity, and potency determination support regulatory submissions.
Packaging services occupy the lowest cost tier by unit operation, with quality control expanding most quickly as sponsors consolidate supplier relationships.
End User:
Customer type determines contract structure complexity, with pharmaceutical companies demanding multi-year supply agreements and academic institutions operating on project-based procurement.
- Pharmaceutical Companies:Large-cap sponsors with established product portfolios outsource mature products and capacity-constrained launches while retaining strategic manufacturing for blockbuster assets. FDA quality-by-design framework compliance and established design-space documentation requirements favor long-term partnerships with full-service CDMOs.
- Biotechnology Firms:Venture-backed developers lacking manufacturing infrastructure externalize entire supply chains from preclinical through commercial phases. Cell therapy commercialization creates pull for CDMOs with flexible cleanroom suites and cryogenic logistics capabilities.
- Contract Research Organizations:Clinical trial material supply demands rapid turnaround and adaptive batch sizing.
- Academic Institutions:Investigator-initiated studies and translational research programs require small-batch flexibility.
Pharmaceutical companies anchor contract value concentration, with biotechnology firms gaining share fastest as externalization accelerates across the development spectrum.
Therapy Area:
Application-driven segmentation aligns manufacturing capabilities with disease-specific regulatory pathways and dosing requirements.
- Oncology:Cytotoxic and biologic cancer therapeutics require containment infrastructure and handling protocols that limit facility flexibility. Demand concentrates in specialized CDMOs with isolator technology and potent compound expertise serving US and European markets.
- Neurology:Central nervous system drug delivery presents blood-brain barrier penetration challenges that drive formulation complexity. Sponsors seek partners with nanotechnology and lipid nanoparticle capabilities for gene therapy and small molecule programs.
- Cardiovascular:Large-volume oral solid dosage forms for chronic disease management compete on manufacturing scale and cost efficiency.
- Infectious Diseases:Antibiotic and antiviral production faces pricing pressure from generic competition and government procurement.
Cardiovascular maintains the largest installed base, with neurology exhibiting the steepest expansion trajectory as gene therapy pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland and South Korea have emerged as contrasting models of biologics manufacturing concentration, with the former leveraging pharmaceutical headquarters proximity and the latter exploiting regulatory acceleration, while the United States retains the largest absolute contract manufacturing spend.
United States
FDA quality-by-design mandates and cell therapy commercialization drive sponsor demand toward externalized capacity. The agency's continuous process verification requirements favor CDMOs with validated analytical platforms and established design-space documentation. Greater Boston and San Francisco biotechnology corridors concentrate early-stage outsourcing decisions, with multi-product facilities in Research Triangle Park and Puget Sound anchoring commercial-scale supply agreements.
Switzerland
Big Pharma headquarters proximity and specialized manufacturing infrastructure attract sustained sponsor investment. Swissmedic maintains stringent GMP certification standards that reinforce quality differentiation for export-bound production. The Basel-Zurich corridor hosts concentrated biologics manufacturing clusters where talent migration and facility co-location create network effects for complex sterile formulation programs.
South Korea
MFDS accelerated approval pathways for innovative biologics position Korean CDMOs as launch partners for Asia-Pacific market entry strategies. Government-backed biocluster development in Songdo and Incheon Free Economic Zone subsidizes facility construction and regulatory consulting infrastructure. Samsung Biologics anchors mammalian cell culture capacity expansion, with secondary operators scaling microbial expression systems for biosimilar export programs.
Germany
EMA Annex 1 compliance requirements and advanced therapy manufacturing expertise concentrate demand in specialized operators. The country's federal pharmaceutical regulator enforces strict environmental monitoring standards that drive investment in isolator-based fill-finish lines. North Rhine-Westphalia and Bavaria host integrated drug-device combination facilities serving European-market-bound biologics programs.
India
CDSCO streamlined biosimilar guidelines and WHO prequalification momentum open capacity for emerging market supply at cost-advantaged scale. The national pharmaceutical regulator has harmonized inspection protocols with FDA and EMA standards, reducing facility qualification timelines for export-oriented manufacturers. Maharashtra and Gujarat pharmaceutical corridors concentrate API synthesis and oral dosage form capacity, with Hyderabad emerging as a viral vector and plasmid DNA production hub for gene therapy sponsors.
Global Pharmaceutical Contract Manufacturing Market Key Industry Players
Top-tier vendors anchor integrated full-service platforms, while mid-scale specialists compete on therapeutic-area concentration or regional regulatory expertise. The vendor base stratifies across three capability tiers: mammalian cell culture dominants with multi-thousand-liter bioreactor networks, flexible cleanroom operators serving cell therapy and viral vector demand, and cost-optimized small-molecule API manufacturers in South Asia. Consolidation pressure intensifies as sponsor buying patterns favor unified quality systems spanning drug substance through commercial packaging.
Among Swiss- and German-based integrated operators, Lonza, Boehringer Ingelheim, and Merck KGaA exemplify the full-service archetype with mammalian and microbial expression capabilities spanning preclinical through commercial phases. These entities occupy positions where regulatory liability transfer and long-term supply agreements converge, representing the partnership model that biotechnology sponsors increasingly favor over fragmented multi-vendor sourcing. Their geographic anchoring in Basel and Darmstadt reinforces proximity to EMA regulatory interfaces and Big Pharma headquarters clusters.
| Leading Market Players |
|---|
| Lonza |
| Catalent |
| Thermo Fisher Scientific |
| Samsung Biologics |
| WuXi AppTec |
| Boehringer Ingelheim |
| Recipharm |
| Merck KGaA |
| CordenPharma |
| Others |
Cost & Logistics Intelligence
Biologics-versus-small-molecule manufacturing cost bifurcation separates premium cell-culture services from commodity oral dosage production, with this divergence manifesting in both contract pricing structures and raw material sourcing configurations across Switzerland, South Korea, and India. FDA quality-by-design compliance and EMA Annex 1 certification requirements anchor pricing premiums for sterile injectables, while single-use component dependencies and cold-chain logistics costs reshape supplier selection criteria for sponsors seeking variable-cost capacity.
Pricing Analysis
Capacity additions in South Korea and India are reshaping price floors for mammalian cell culture services as Samsung Biologics and regional operators expand bioreactor networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated biologics facilities from EMA-compliant standard operations and cost-optimized emerging market suppliers. Cost compression in small-molecule oral dosage forms is intensifying because Indian and Chinese API manufacturers compete on scale-driven unit economics. Biotechnology firms with venture-backed funding cycles prove most price-sensitive, while large-cap pharmaceutical companies prioritize quality system integration over unit cost minimization.
Supply Chain Analysis
Cold-chain logistics costs and cryogenic shipping requirements absorb disproportionate margin share for cell therapy and viral vector programs, forcing sponsors to co-locate manufacturing with patient populations. Bioprocess equipment concentrates in Germany, Switzerland, and the United States, while single-use consumables draw from specialized polymer suppliers in the United States and Europe. Single-source vulnerability for plasmid DNA and cell culture media creates allocation risk during demand surges regardless of available bioreactor capacity. Distribution runs through sponsor-directed logistics partnerships with qualified cold-chain operators rather than third-party wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where sponsor procurement decisions increasingly favor CDMOs with unified drug-substance-to-commercial-packaging capabilities and validated continuous process verification platforms. The demand shift toward premium specifications reflects biotechnology sponsors consolidating fragmented multi-vendor relationships to accelerate IND-to-BLA timelines.
For Market Incumbents: Lock in long-term supply agreements with cell therapy developers before viral vector capacity scarcity eases. Defend against emerging Korean and Indian scale competitors by embedding analytical testing and regulatory consulting into bundled service contracts. Backward integration into plasmid DNA production reduces single-source dependency risks that currently constrain gene therapy program expansion.
For New Entrants and Emerging Players: Direct-to-biotechnology-sponsor digital platforms for real-time batch tracking and regulatory document exchange offer lower customer acquisition costs than traditional field sales models. Cell therapy cleanroom services in secondary US markets present the most penetrable white space, as Boston and San Francisco corridor capacity saturates. Position initially through flexible single-use suite offerings that avoid capital-intensive stainless-steel infrastructure commitments.
For Investors and Strategic Acquirers: Consolidation pressure builds where sponsor buying patterns favor unified quality systems spanning drug substance through commercial packaging. Mid-scale CDMOs with mammalian cell culture capabilities and existing FDA warning letter clearance represent the most viable acquisition archetypes for platform roll-up strategies. Watch for MFDS accelerated approval pathway utilization rates as the signal indicating which Asia-Pacific operators will capture disproportionate sponsor partnership allocations.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Investment | EMA Annex 1 compliance and FDA QbD documentation accelerate sponsor partner selection decisions. |
| Manufacturing Scale-Up | Single-use bioreactor networks in South Korea and Switzerland fragment large-scale capacity ownership patterns. |
| Backward Integration | In-house plasmid DNA production reduces gene therapy program constraints from qualified supplier scarcity. |
| Long-term Supply Agreement | Multi-year contracts with biotechnology sponsors convert fixed facility costs into predictable revenue streams. |
| Geographic Expansion | MFDS fast-track pathway positioning captures Asia-Pacific market entry strategies for innovative biologics. |
Research Approach
Multiple input streams — executive interviews with drug development leaders, regulatory affairs directors, and CDMO procurement managers; FDA filings and EMA GMP inspection databases; and ClinicalTrials.gov protocol tracking — were reconciled through bottom-up facility capacity modeling and top-down sponsor spend allocation analysis. Primary fieldwork with biotechnology corridor operators in Greater Boston and San Francisco captured early-stage outsourcing decision criteria, while secondary validation drew from Swissmedic certification records and MFDS approval pathway documentation. Cross-referencing sponsor-reported manufacturing externalization rates against CDMO disclosed utilization metrics enabled triangulation of market size estimates.
Data-stream reconciliation across product type, service layer, end-user category, and regional regulatory cluster dimensions produced volume and value outputs across the analysis window. Modeled segmentation captured biologics versus small molecule splits, formulation development versus commercial manufacturing service tiers, and pharmaceutical company versus biotechnology firm customer archetypes. CAGRs were derived from facility investment pipelines, sponsor pipeline maturity curves, and regulatory approval velocity indicators without reliance on single-source projections.
Regulatory inspection backlog durations, single-use component supply disruptions, and cell therapy manufacturing scientist availability constraints are the dominant revision risks that could alter capacity utilization assumptions. Forecasts reflect documented sponsor externalization intentions and CDMO expansion commitments subject to these operational variables. Stakeholders should weight assumptions against their own operating context and facility qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market