
 Global Onychomycosis Treatment Market | 2026-2036
Global Onychomycosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Onychomycosis Treatment Market Foresight
Fixed-dose combination kits pairing topical antifungals with mechanical debridement tools is hardening as the default configuration for moderate-to-severe cases. Pfizer Inc leverages its oral antifungal heritage to sustain physician preference in hospital formularies. Galderma S.A. anchors its position through dermatology-specialist channel control in Western Europe. Moberg Pharma AB differentiates via innovative device platforms that occupy the premium homecare tier.
Onychomycosis treatment encompasses pharmacological and physical interventions targeting dermatophyte, yeast, and mold infections of the nail unit, with topical formulations typically achieving 5-10% ciclopirox or 8% efinaconazole concentrations in lacquer or solution vehicles designed for transungual penetration. Oral antifungals remain the structural backbone of severe-case management due to superior mycological cure rates, while laser therapy segments capture margin pools from aesthetic-conscious patients seeking drug-sparing alternatives. Prescription drugs dominate value generation, yet over-the-counter products expand volume through pharmacy self-selection channels where gels and solutions outsell creams in convenience-driven purchasing.
FDA bioequivalence standards and EMA quality guidelines shape formulation development costs and timeline risk for new entrants. The EU MDR and ISO 13485 frameworks govern device-drug combination submissions, tightening clinical evidence requirements for laser and phototherapy platforms. Stakeholders must monitor how payer formularies in Germany, Japan, and Brazil classify combination protocols versus monotherapy lines.
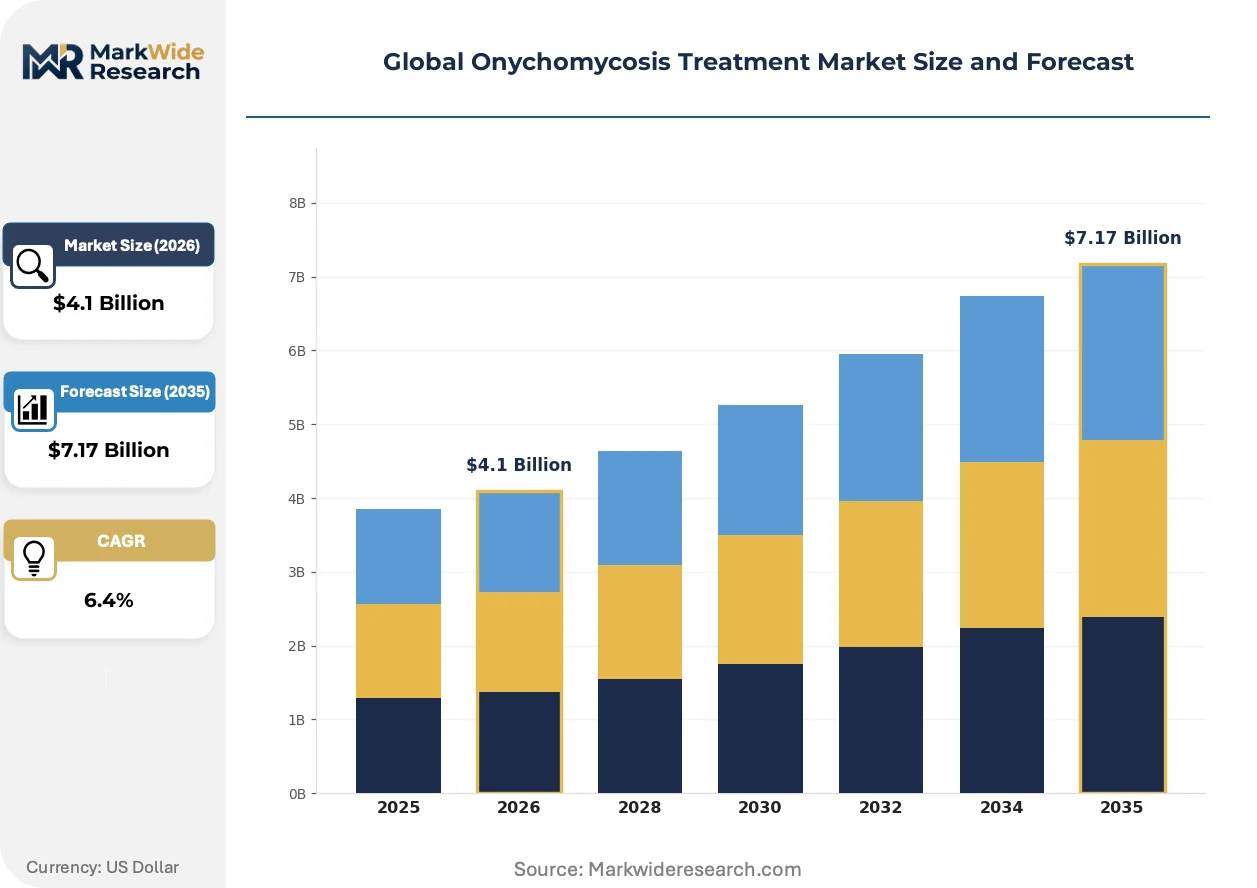
Market Dynamics
Fixed-dose combination protocols pairing topical antifungals with mechanical debridement tools are compressing treatment timelines and reshaping physician prescribing patterns across dermatology and podiatry channels.
Growth Catalysts
- FDA 505(b)(2) pathway:This regulatory route accelerates approval for topical-device hybrids by leveraging existing safety data, cutting development timelines for combination kits targeting moderate-to-severe onychomycosis cases.
- Podiatry network expansion:United States-based foot care clinics are extending direct-to-consumer access through telehealth-integrated prescription services, broadening patient reach beyond traditional dermatology referrals.
- Transungual penetration enhancers:Novel permeation technologies in lacquer vehicles are improving drug delivery through the nail plate, elevating mycological cure rates for topical formulations previously limited by bioavailability constraints.
Market Restraints
- Oral antifungal hepatotoxicity monitoring:Terbinafine and itraconazole require liver function surveillance, creating prescribing friction in hospital formularies and limiting first-line use in patients with comorbidities.
- API supply concentration:Active pharmaceutical ingredient production for azole antifungals clusters in China and India, exposing formulation sponsors to geopolitical disruption and quality variability risks.
- Laser device clinical evidence gaps:Phototherapy platforms lack standardized cure rate benchmarks comparable to pharmacological endpoints, constraining payer reimbursement and formulary placement in Germany and Japan.
Strategic Opportunities
- Brazil's unified health system:SUS formulary expansion for dermatological conditions creates procurement volume for combination protocols, particularly in São Paulo and Rio de Janeiro clinic networks.
- Homecare device convergence:Integration of cold plasma or photodynamic therapy modules with smartphone-guided treatment apps is opening premium self-administration segments.
- EU MDR transition window:Device-drug combination reclassification under the Medical Device Regulation creates first-mover advantage for sponsors with robust clinical evidence packages.
Industry Challenges
- Clinical trial recruitment:Mycological cure endpoints require 48-52 week follow-up periods, stretching study budgets and patient retention rates for topical formulation sponsors.
- ISO 13485 quality system implementation:Laser and phototherapy manufacturers face documentation intensity for design controls and post-market surveillance under harmonized device standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Onychomycosis Treatment Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Antifungals, Laser Therapy, Combination Therapy Delivery Mode: Prescription Drugs, Over-the-Counter Products, Herbal Remedies, Innovative Devices End User: Clinics, Hospitals, Homecare, Pharmacies Formulation: Gels, Solutions, Creams, Tablets |
| Companies Covered | Bausch Health Companies Inc, Pfizer Inc, Novartis AG, Galderma S.A., Moberg Pharma AB, Merck & Co., Inc., Johnson & Johnson Services Inc, Dr. Reddy's Laboratories, Cipla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Onychomycosis Treatment Market Shifts & Advancements
Transungual drug delivery systems are absorbing engineering investment previously directed toward oral antifungal reformulation, reflecting a strategic pivot toward localized therapy modalities with favorable safety profiles.
Cold plasma technology is absorbing development resources from traditional laser platforms in aesthetic-conscious patient segments. Dermatology clinics in Japan and South Korea are adopting these devices for drug-sparing protocols. The technology is absorbing margin pools from prescription pharmacotherapy by positioning nail rejuvenation as a cosmetic service outside pharmacy benefit management.
EMA quality guidelines for topical antifungal formulations are tightening impurity specification thresholds for ciclopirox and efinaconazole lacquers. Generic sponsors face elevated analytical validation costs for transungual penetration studies. Western European markets are responding with formulation differentiation strategies emphasizing vehicle composition rather than API concentration alone.
Direct-to-consumer pharmacy channels are displacing traditional prescriber-dependent distribution for mild-case topicals. United States retail chains and telehealth platforms are capturing self-diagnosing patients through over-the-counter efinaconazole and ciclopirox solutions. Brazil and Japan display comparable channel migration, though regulatory classification limits the scope of non-prescription availability in each market.
Global Onychomycosis Treatment Market Segmentation
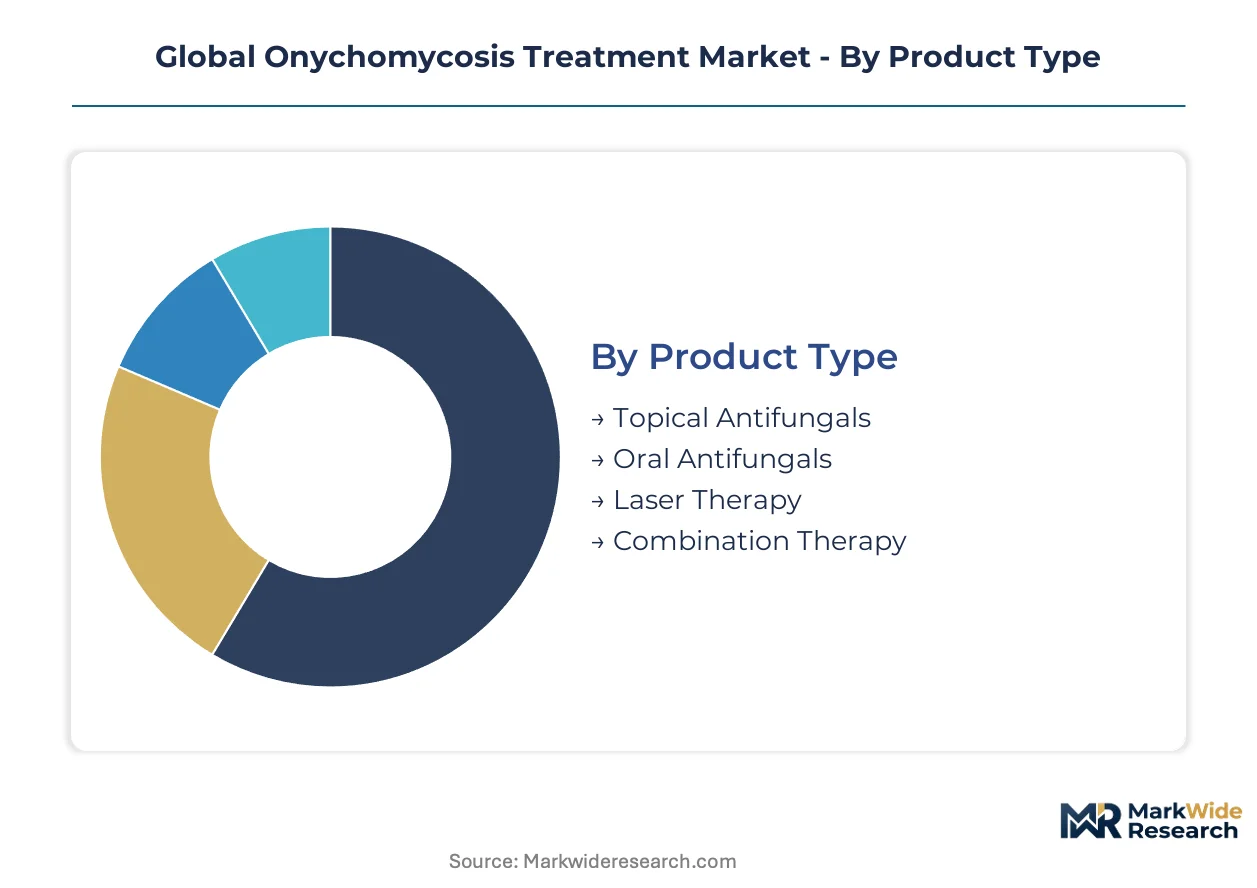
Onychomycosis treatment segmentation reveals distinct margin architectures across pharmacological and physical intervention modalities. Supply concentration in active pharmaceutical ingredient manufacturing and device component sourcing directly shapes competitive positioning within each category.
Product Type:
API production clusters in China and India concentrate supply risk for systemic formulations, while device manufacturing localizes differently across phototherapy platforms.
- Topical Antifungals:Ciclopirox and efinaconazole lacquers achieve 5-10% and 8% concentrations respectively in vehicles engineered for transungual penetration. Dermatology clinics in Germany and Japan favor these for mild-to-moderate cases where hepatotoxicity monitoring burdens oral alternatives.
- Oral Antifungals:Terbinafine and itraconazole tablets deliver superior mycological cure rates through systemic distribution. Hospital formularies in the United States retain these as structural backbones for severe infections despite liver function surveillance requirements.
- Laser Therapy:Phototherapy platforms target aesthetic-conscious patients seeking drug-sparing alternatives with margin extraction through cosmetic service positioning.
- Combination Therapy:Fixed-dose kits pairing topical antifungals with mechanical debridement tools compress treatment timelines and reshape prescribing patterns across podiatry networks.
Today's leader: Oral Antifungals. Tomorrow's challenger: Combination Therapy.
Delivery Mode:
Channel economics stratify sharply between prescriber-dependent distribution and self-selection retail, with regulatory classification determining accessibility ceilings in each national market.
- Prescription Drugs:Dominate value generation through dermatology and podiatry channel control. FDA bioequivalence standards and EMA quality guidelines elevate formulation development barriers for new entrants seeking formulary placement.
- Over-the-Counter Products:Expand volume through pharmacy self-selection where gels and solutions outsell creams in convenience-driven purchasing. United States retail chains and telehealth platforms capture self-diagnosing patients through direct-to-consumer channels.
- Herbal Remedies:Occupy fringe positioning with limited clinical evidence packages constraining reimbursement access.
- Innovative Devices:Cold plasma and photodynamic therapy modules integrate with smartphone-guided treatment apps, opening premium homecare segments outside pharmacy benefit management.
Prescription Drugs currently anchor revenue concentration. Over-the-Counter Products are climbing the fastest as channel migration accelerates.
End User:
Patient access patterns diverge between institutional settings with reimbursement infrastructure and emerging direct-to-consumer pathways.
- Clinics:Dermatology and podiatry networks in Germany, Japan, and Brazil are expanding patient access to combination protocols. São Paulo and Rio de Janeiro clinic networks drive procurement volume through SUS formulary expansion.
- Hospitals:Retain oral antifungal preference for severe-case management with embedded hepatotoxicity monitoring protocols.
- Homecare:Premium self-administration segments emerge through device-drug convergence with smartphone integration.
- Pharmacies:Capture mild-case volume through over-the-counter availability where regulatory classification permits.
Clinics dominate combination protocol adoption. Homecare represents the steepest expansion trajectory as device platforms mature.
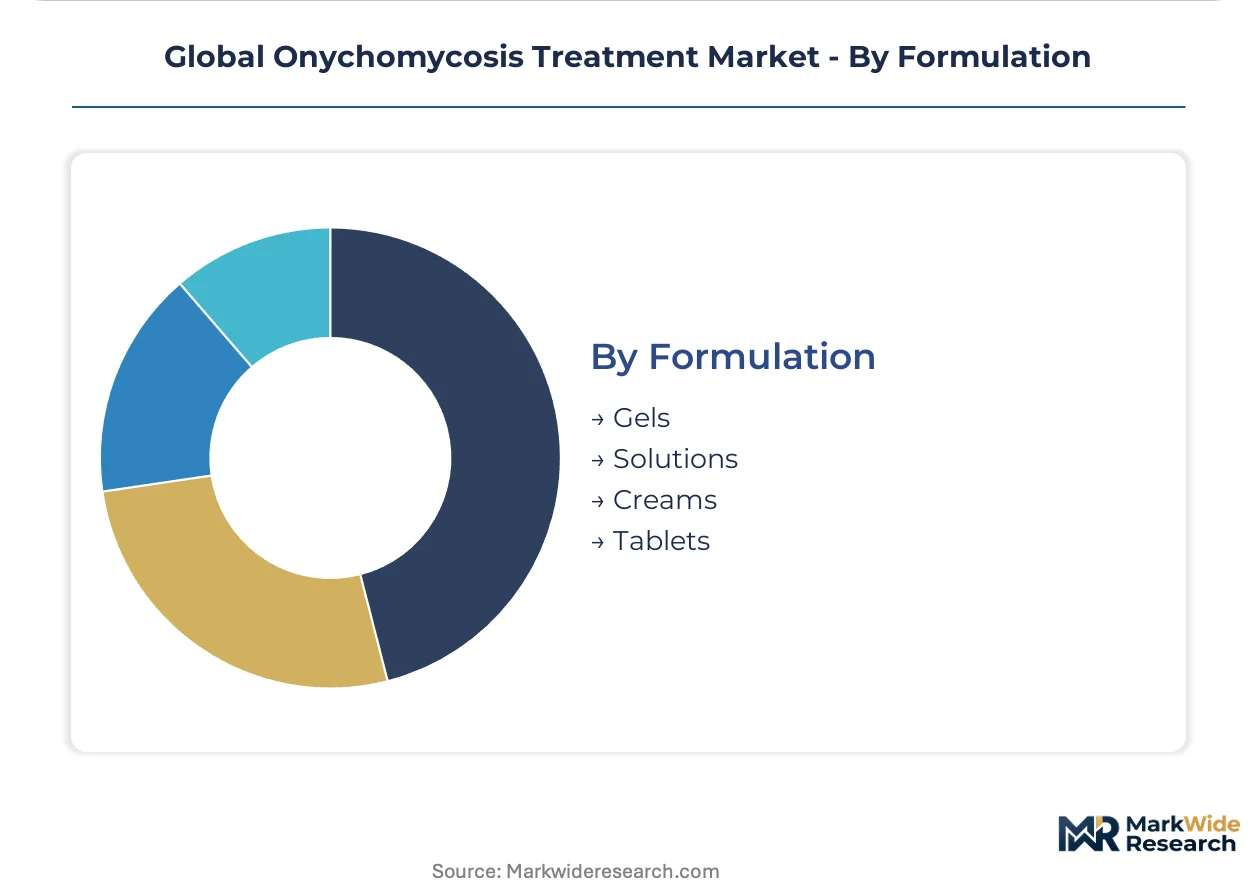
Formulation:
Vehicle engineering investment now exceeds API concentration optimization as transungual penetration becomes the primary efficacy differentiator.
- Gels:Favored in convenience-driven purchasing across pharmacy self-selection channels for ease of application and reduced mess.
- Solutions:Outsell creams in retail environments due to faster drying properties and compatibility with daily routines.
- Creams:Limited nail plate penetration constrains utility for onychomycosis despite broader dermatological application heritage.
- Tablets:Systemic delivery vehicles for oral antifungals with established pharmacokinetic profiles and liver metabolism surveillance requirements.
Solutions lead topical formulation preference. Gels are gaining share fastest as pharmacy channel migration continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Systemic antifungal therapy originated in Swiss and German pharmaceutical laboratories during the 1970s, establishing Central Europe as the foundational geography for onychomycosis drug development before manufacturing dispersion to North American and Asian markets.
United States
Podiatry network expansion and telehealth-integrated prescription services drive patient access beyond traditional dermatology referrals. FDA 505(b)(2) pathway accelerates approval timelines for topical-device hybrid kits targeting moderate-to-severe cases. Greater Boston and Pacific Northwest clusters host device startups developing smartphone-guided homecare platforms.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia favor combination protocols pairing topical antifungals with mechanical debridement for mild-to-moderate infections. EMA quality guidelines tighten impurity specifications for ciclopirox and efinaconazole lacquers, elevating analytical validation costs for generic sponsors. Frankfurt and Munich formularies classify combination therapies separately from monotherapy lines.
Japan
Aesthetic-conscious patient segments absorb cold plasma and photodynamic therapy devices for drug-sparing protocols. PMDA oversight governs device-drug combination submissions under harmonized standards. Tokyo and Osaka dermatology clinics position nail rejuvenation as cosmetic services outside pharmacy benefit management.
Brazil
SUS formulary expansion for dermatological conditions creates procurement volume in São Paulo and Rio de Janeiro clinic networks. ANVISA regulatory pathways shape market entry timelines for imported combination kits. Minas Gerais and Paraná secondary cities extend access through public health system dermatology units.
India
Active pharmaceutical ingredient production for azole antifungals clusters in Gujarat and Maharashtra, exposing formulation sponsors to quality variability risks. CDSCO bioequivalence standards govern generic oral antifungal approvals. Hyderabad and Bangalore analytical services laboratories support transungual penetration studies for lacquer vehicle optimization.
Global Onychomycosis Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and channel control dimensions. The vendor base stratifies between multinational pharmaceutical incumbents with hospital formulary lock-in, dermatology-specialist firms with clinic network relationships, and device-platform innovators capturing homecare premiums. Three archetypes dominate: oral antifungal heritage houses, topical formulation specialists, and phototherapy device engineers. Competitive moves concentrate on M&A for transungual delivery technology and strategic partnerships for podiatry channel access.
Among heritage pharmaceutical houses, Pfizer Inc and Novartis AG exemplify the oral antifungal incumbent archetype with established hospital formulary presence. Galderma S.A. occupies the dermatology-specialist tier with Western European clinic network control. Moberg Pharma AB represents the device-platform innovator segment targeting premium homecare positioning.
| Leading Market Players |
|---|
| Bausch Health Companies Inc |
| Pfizer Inc |
| Novartis AG |
| Galderma S.A. |
| Moberg Pharma AB |
| Merck & Co., Inc. |
| Johnson & Johnson Services Inc |
| Dr. Reddy's Laboratories |
| Cipla Inc. |
| Others |
Supply & Pricing Matrix
Captive API production in Gujarat and Maharashtra anchors both supply security and pricing power for Indian formulation sponsors serving domestic and export markets. This backward integration into azole manufacturing buffers against quality variability risks while compressing procurement costs relative to sponsors dependent on spot-market sourcing from Chinese intermediaries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by clinical setting and reimbursement access. Premium tiers extract margin through device-drug combination kits with ISO 13485 certification, while economy positioning targets pharmacy self-selection channels where price sensitivity concentrates among self-diagnosing patients. Cost compression in standard oral antifungal tablets is intensifying because of generic terbinafine saturation in United States hospital formularies. Dermatology clinics display the least price sensitivity, prioritizing mycological cure rates over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese API intermediates for efinaconazole and ciclopirox active pharmaceutical ingredients. Active pharmaceutical ingredient production clusters in China, India, and Switzerland, with formulation finishing distributed across Germany, Japan, and Brazil. Raw material dependencies include azole chemical precursors, nail lacquer vehicle polymers, and laser diode components for phototherapy platforms. Tariff exposure runs through United States-China pharmaceutical ingredient trade flows. Distribution runs through dermatology-specialist wholesalers in Western Europe, podiatry group purchasing organizations in North America, and public health system tenders in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA 505(b)(2) pathway efficiency and EMA MDR compliance burdens creates geographic cost differentials for combination kit sponsors. Manufacturers can compress development spend by sequencing United States approval ahead of European device-drug reclassification.
For Market Incumbents: Extend formulary lock-in through hepatotoxicity monitoring service bundling with oral antifungal prescriptions, countering topical-device substitution threats from cold plasma entrants. Deepen backward integration into transungual penetration vehicle manufacturing to defend margin position against generic lacquer sponsors. Prioritize certification investment under EU MDR for first-mover advantage in combination therapy reclassification. For New Entrants and Emerging Players: Aesthetic-conscious homecare patients represent the most penetrable buyer archetype, underserved by incumbent pharmacy-channel dependence. Capture this segment through smartphone-guided photodynamic therapy platforms with direct-to-consumer positioning. Brazil's SUS formulary expansion offers white-space access through ANVISA-registered combination kits for São Paulo clinic networks. Deploy telehealth-integrated prescription services as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for transungual delivery technology specialists because formulation complexity creates defensible IP moats against commodity generic sponsors. Platform consolidation across device-platform innovators and topical formulation houses offers long-term viability through homecare premium extraction. Monitor PMDA device-drug combination submission volumes as the inflection indicator for Asia-Pacific regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 505(b)(2) Submission | Accelerates topical-device hybrid approval by leveraging existing oral antifungal safety databases. |
| EU MDR Certification Pathway | Positions combination kits for premium reimbursement under reclassified device-drug frameworks. |
| Podiatry Network Partnership | Secures channel control through telehealth-integrated prescription services beyond dermatology referrals. |
| Transungual Delivery Acquisition | Consolidates permeation technology IP against generic lacquer sponsors in Western Europe. |
| ANVISA Registration Strategy | Unlocks SUS formulary procurement volume in São Paulo and Rio de Janeiro public health networks. |
Research Methodology
Direct dialogue with dermatology clinic directors, podiatry network procurement officers, regulatory affairs leads at combination kit sponsors, and pharmaceutical formulary managers grounded qualitative findings. Secondary validation drew from FDA 505(b)(2) approval databases, EMA MDR submission trackers, ClinicalTrials.gov mycological cure endpoint records, and ANVISA registration filings. Bottom-up patient access modeling triangulated against top-down pharmaceutical expenditure forecasts across the analysis window.
Top-down macroeconomic filtering preceded bottom-up segmentation by treatment modality, delivery channel, and geographic regulatory cluster. The analytical framework modeled oral antifungal, topical antifungal, laser therapy, and combination therapy segments across prescription, over-the-counter, and device-distribution channels. CAGRs derived from regression against historical approval timelines and payer formulary placement velocities. Forecast inputs incorporated PMDA device-drug combination submission rates and SUS dermatological procurement auction volumes.
Underlying measurement precision varies by segment; oral antifungal volume estimates carry tighter precision than emerging cold plasma device adoption curves. Forecasts reflect assumptions regarding FDA pathway efficiency, EMA MDR transition timelines, and Brazilian public health budget continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Laxatives Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Anastrozole Tablets Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Global Neuroprotective Agents Market