
 Global Pharmaceutical Contract Manufacturing and Contract Research Market | 2026-2036
Global Pharmaceutical Contract Manufacturing and Contract Research Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Contract Manufacturing and Contract Research Market Foresight
Process analytical technology services is decoupling manufacturing contracts from traditional fee-for-service structures. Samsung Biologics anchors the biologics capacity race through its Songdo mega-facility. Lonza Group AG specializes in mammalian cell culture platforms for complex modalities. Thermo Fisher Scientific Inc. extends its dominance across clinical research and commercial manufacturing through integrated service architectures.
Pharmaceutical contract manufacturing and contract research encompasses the outsourced production of drug substances and drug products alongside delegated discovery, preclinical, and clinical development activities, typically governed by ICH Q7 GMP guidelines for APIs and ICH Q10 quality systems for biologics, serving to reduce fixed-asset burdens and accelerate time-to-market for drug sponsors. Contract manufacturing for biologics captures the steepest capacity premiums as single-use bioreactor adoption shifts batch economics. Contract research in oncology commands the deepest sponsor budgets due to protocol complexity and patient recruitment costs. Analytical services represent a mature margin pool where specialized capabilities in biosimilar comparability studies differentiate regional players.
FDA enforces Current Good Manufacturing Practice through risk-based inspection schedules that determine facility approval timelines for US-bound products. EMA coordinates GMP mutual recognition agreements that gate European market access for Asian and North American contract manufacturers. China's NMPA accelerates overseas facility inspections under revised Drug Administration Law provisions. Sponsors must monitor regulatory divergence between FDA's Quality Management Maturity ratings and EMA's strengthened Annex 1 sterile manufacturing requirements when qualifying multi-continental supply networks.
Market Dynamics
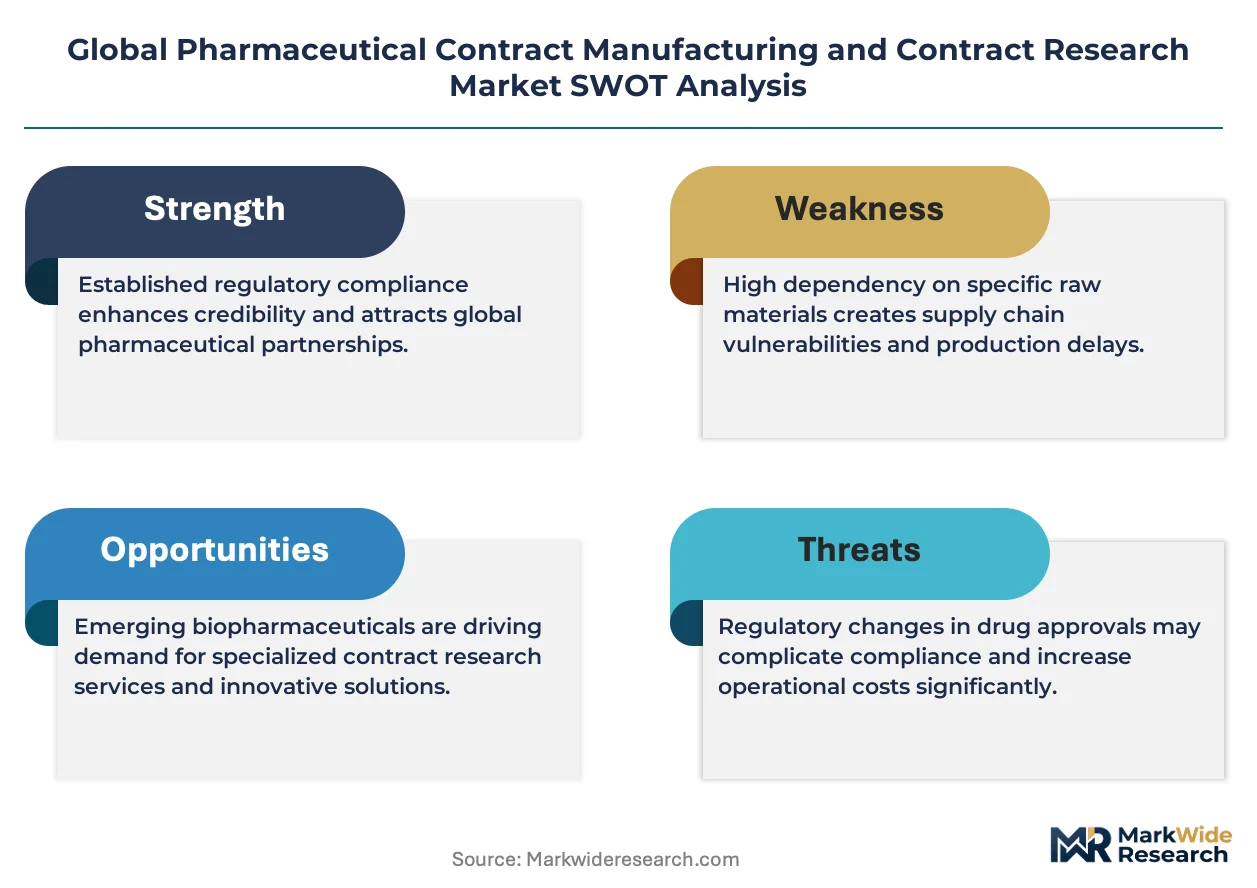
Biologics capacity scarcity is forcing sponsors into long-term exclusivity commitments with contract manufacturers, transforming transactional outsourcing into strategic partnerships anchored by dedicated facility investments and co-developed process platforms.
Growth Catalysts
- ICH Q10 Quality Systems:Harmonized biologics manufacturing standards reduce regulatory duplication across FDA and EMA jurisdictions, accelerating multi-regional product approvals for contract manufacturers.
- Cell and gene therapy pipelines:Viral vector production demands exceed in-house biopharma capabilities, pulling specialized CDMO capacity into early-phase development partnerships.
- South Korea biologics cluster:Government-backed tax incentives and streamlined MFDS inspections attract foreign sponsor investment into Korean mammalian cell culture facilities.
Market Restraints
- Single-use consumables concentration:Three suppliers control 70% of bioreactor bag and tubing supply, exposing contract manufacturers to resin and film raw material volatility.
- FDA Quality Management Maturity scoring:Sub-tier ratings trigger extended pre-approval inspection timelines, delaying revenue recognition for facilities awaiting commercial batch release.
- Plasmid DNA scarcity:mRNA and viral vector manufacturing compete for limited qualified GMP plasmid supply, constraining capacity expansion for gene therapy CDMOs.
Strategic Opportunities
- Swissmedic fast-track pathway:Switzerland's abbreviated inspection reciprocity with FDA and EMA positions Basel-Zurich corridor facilities for rapid global market entry.
- Continuous manufacturing convergence:Integration of process analytical technology with single-use bioreactors enables real-time release testing, compressing batch cycle times by 40%.
- India biosimilar analytical services:CDSCO's relaxed import testing requirements for reference biologics lower comparability study costs, attracting European sponsor outsourcing.
Industry Challenges
- Process development scientist scarcity:Mammalian cell line engineering and scale-up modeling expertise concentrates among tenured staff at legacy biologics facilities, constraining workforce expansion.
- Annex 1 compliance retrofit costs:EMA's 2022 sterile manufacturing overhaul requires isolator technology and facility redesign investments exceeding $50 million per legacy fill-finish site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Contract Manufacturing and Contract Research Market |
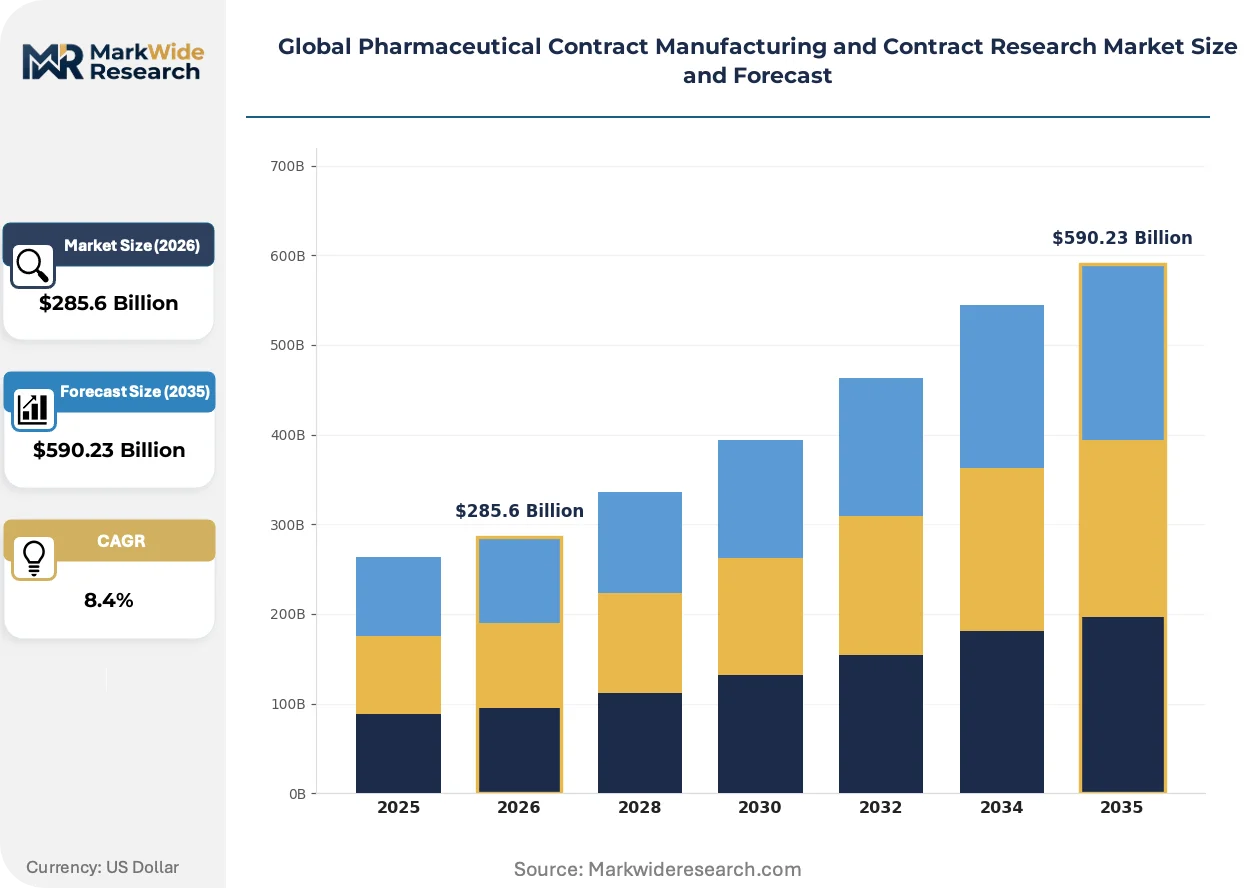
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $590.23 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Contract Manufacturing, Contract Research, Clinical Trial Management, Analytical Services, Regulatory Affairs Consulting Product Type: Active Pharmaceutical Ingredients, Biologics, Small Molecule Drugs, Biosimilars, Nutraceuticals Therapy Area: Oncology, Cardiovascular Disorders, Central Nervous System, Infectious Diseases, Rare Diseases End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Generic Drug Manufacturers |
| Companies Covered | Samsung Biologics Co., Ltd., Fujifilm Diosynth Biotechnologies, Lonza Group AG, Recipharm AB, Siegfried Holding AG, Thermo Fisher Scientific Inc., WuXi Biologics, PCI Pharma Services, Inc., Catalent, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Contract Manufacturing and Contract Research Market Shifts & Advancements
Process analytical technology is absorbing quality control functions into manufacturing execution systems, collapsing the traditional separation between production and release testing. This integration demands new data infrastructure and regulatory filing strategies.
Single-use bioreactor technology is absorbing stainless steel vessel demand across clinical-scale manufacturing. Mid-cap biotech sponsors now specify disposable platforms for Phase III campaigns, compressing facility qualification timelines from 18 months to 6 months. This shift is absorbing capital that previously flowed into fixed equipment, redirecting CDMO investment toward flexible multi-product suites.
EMA's strengthened Annex 1 sterile manufacturing requirements are forcing isolator adoption across European fill-finish networks. Facilities without barrier technology face inspection failure risk and sponsor disqualification. Aseptic processing for complex biologics is absorbing the highest compliance burden, with Swiss and Irish sites leading retrofit investment.
Sponsor procurement of integrated discovery-to-commercial packages is displacing fragmented vendor management. Large biopharma buyers now consolidate preclinical CRO, clinical manufacturing, and commercial supply under single accountability structures. This concentration is most visible in oncology programs, where timeline compression demands unified data handoffs between development phases.
Global Pharmaceutical Contract Manufacturing and Contract Research Market Segmentation
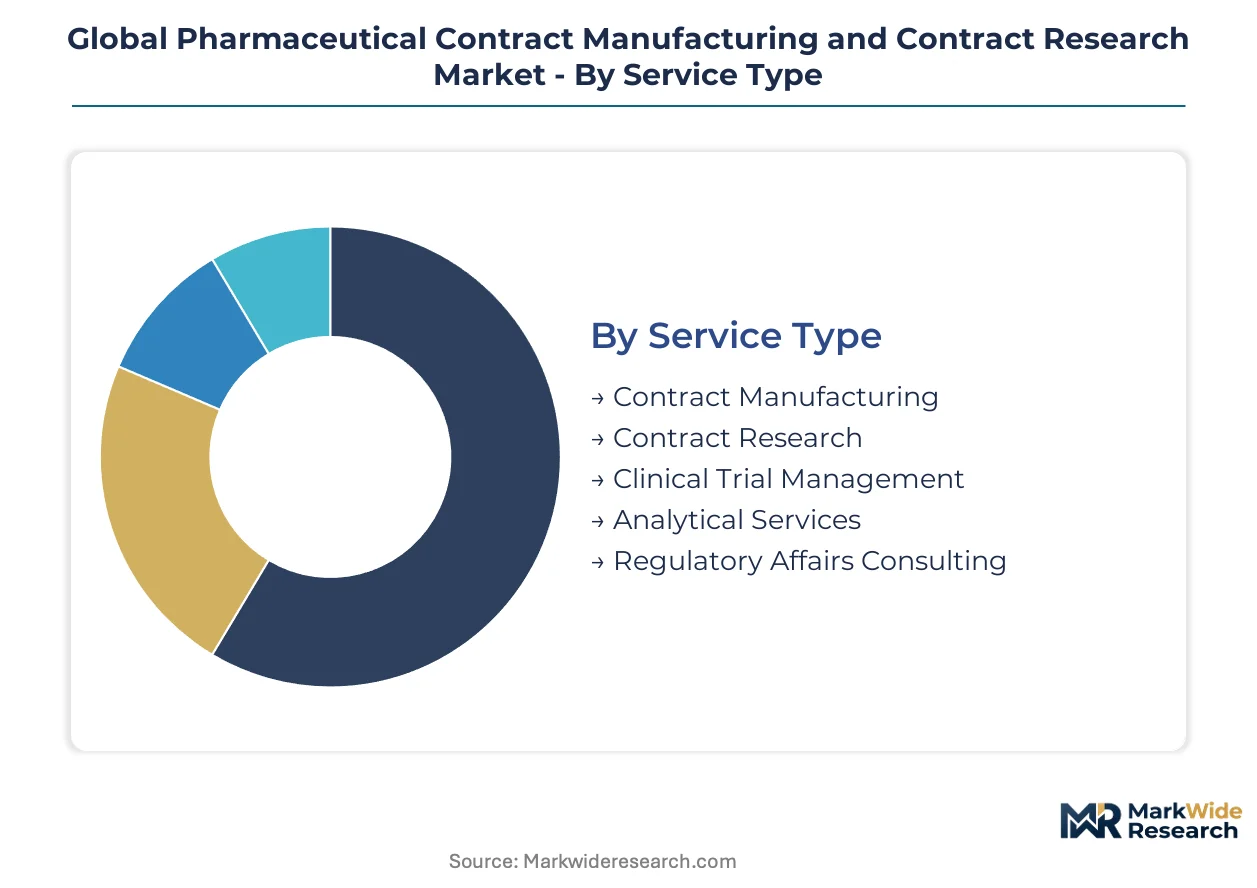
Pharmaceutical outsourcing contracts fragment across service depth, molecular complexity, therapeutic focus, and sponsor scale. Each segmentation axis carries distinct margin profiles, regulatory pathways, and capacity constraints that reshape vendor selection criteria.
Service Type:
Volume-driven manufacturing commands the base of contract value, while premium-margin advisory services capture expanding share as regulatory complexity intensifies.
- Contract Manufacturing:Commercial-scale drug substance and drug product production governed by ICH Q7 and Q10 standards. Demand concentrates in mammalian cell culture capacity across South Korea and Switzerland as biologics sponsors seek dedicated facility commitments. Single-use bioreactor adoption compresses batch turnaround timelines.
- Contract Research:Discovery through Phase I chemistry, biology, and pharmacology services. Oncology and rare disease pipelines in the United States and Germany pull specialized capabilities into long-term strategic partnerships with integrated data handoffs.
- Clinical Trial Management:Patient recruitment, site monitoring, and data management spanning Phase II-III execution.
- Analytical Services:Method development, stability testing, and biosimilar comparability studies.
- Regulatory Affairs Consulting:Submission strategy, FDA pre-IND meetings, and EMA scientific advice preparation.
Today's leader: Contract Manufacturing. Tomorrow's challenger: Regulatory Affairs Consulting.
Product Type:
Biologics manufacturing captures steepest capacity premiums as molecular complexity escalates, while small molecule commoditization pressures traditional API contract margins.
- Active Pharmaceutical Ingredients:Synthetic organic chemistry and fermentation-derived drug substances. Generic drug manufacturers in India drive volume demand as CDSCO import testing relaxation lowers comparability study barriers for European sponsor outsourcing.
- Biologics:Monoclonal antibodies, recombinant proteins, and fusion molecules produced via mammalian, microbial, or insect cell platforms. Capacity scarcity across the United States, Ireland, and Singapore forces sponsors into exclusivity commitments with dedicated facility investments.
- Small Molecule Drugs:Traditional chemical synthesis for oral solid dosage and parenteral formulations.
- Biosimilars:Follow-on biologics requiring extensive analytical characterization and clinical immunogenicity studies.
- Nutraceuticals:Dietary supplements and functional food ingredients with lighter GMP oversight.
Biologics anchors current profitability. Biosimilars represent the steepest expansion trajectory as patent cliffs accelerate sponsor investment.
Therapy Area:
Oncology commands the deepest sponsor budgets due to protocol complexity, while rare diseases attract premium pricing for specialized manufacturing runs.
- Oncology:Cytotoxic, biologic, and cell therapy candidates with complex handling requirements. CAR-T and bispecific antibody demand in the United States and Germany absorbs viral vector and mammalian cell culture capacity into integrated development partnerships.
- Cardiovascular Disorders:Established small molecule and biologic therapies with mature manufacturing processes.
- Central Nervous System:Blood-brain barrier penetration challenges and specialized formulation needs.
- Infectious Diseases:Antibiotics, antivirals, and vaccine production with pandemic surge capacity requirements.
- Rare Diseases:Orphan indications with small-batch production and accelerated regulatory pathways.
Oncology dominates contract value. Rare diseases are gaining share fastest as gene therapy modalities mature.
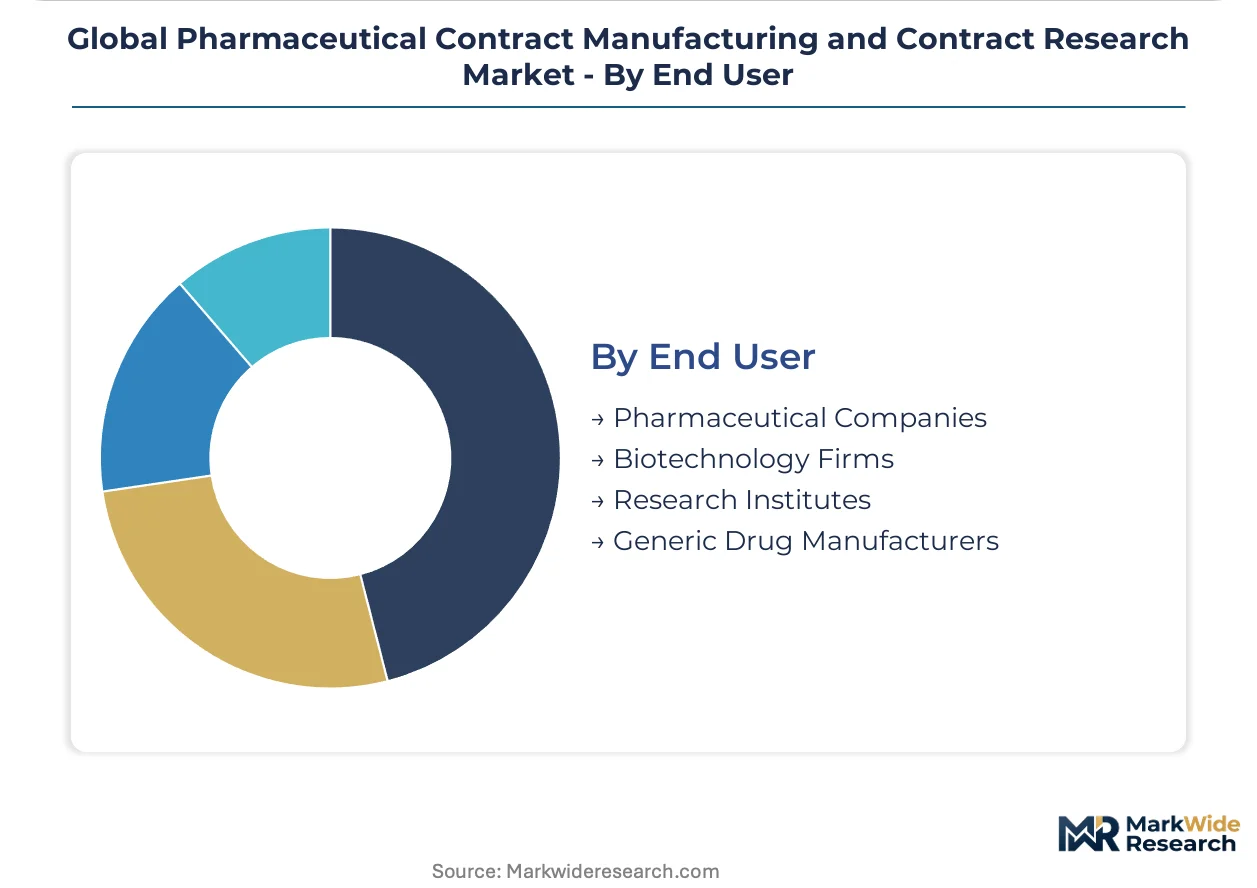
End User:
Large pharmaceutical sponsors consolidate vendor relationships under single accountability structures, while biotechnology firms drive demand for flexible, milestone-based engagement models.
- Pharmaceutical Companies:Multinational drug sponsors with global commercial portfolios. Procurement teams in Switzerland and the United Kingdom now specify integrated discovery-to-commercial packages that collapse traditional phase-boundary vendor fragmentation.
- Biotechnology Firms:Venture-backed and publicly traded development-stage companies. Cash runway constraints in Massachusetts and California biotech clusters favor fee-for-service structures with minimal upfront capital commitment.
- Research Institutes:Academic medical centers and government laboratories with grant-funded discovery programs.
- Generic Drug Manufacturers:Cost-competitive API and formulation sourcing for off-patent portfolios.
Pharmaceutical Companies anchor procurement volume. Biotechnology Firms represent the most dynamic demand source as cell and gene therapy pipelines expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland and South Korea command the steepest capacity premiums for mammalian cell culture, while India and Germany compete on analytical services and small molecule synthesis respectively. Regulatory reciprocity agreements and government-backed tax incentives are reshaping sponsor facility qualification decisions across these jurisdictions.
United States
Oncology and cell therapy pipelines in Massachusetts and California absorb viral vector manufacturing capacity into long-term partnerships. FDA's Quality Management Maturity scoring extends pre-approval inspection timelines for sub-tier rated facilities. The Greater Boston biotech cluster anchors integrated discovery-to-commercial service procurement.
Switzerland
Swissmedic's fast-track pathway leverages abbreviated inspection reciprocity with FDA and EMA to accelerate global market entry. The Basel-Zurich corridor concentrates biologics fill-finish capacity with isolator technology investments exceeding $50 million per site. Lonza Group AG anchors mammalian cell culture platform specialization in this jurisdiction.
South Korea
Government-backed tax incentives and streamlined MFDS inspections attract foreign sponsor investment into mammalian cell culture facilities. Samsung Biologics' Songdo mega-facility anchors the biologics capacity race with dedicated facility commitments. The Incheon Free Economic Zone clusters single-use bioreactor adoption for flexible multi-product suites.
Germany
Oncology and rare disease protocols in the United States and domestic markets pull specialized CRO capabilities into strategic partnerships. EMA's strengthened Annex 1 sterile manufacturing requirements force isolator adoption across European fill-finish networks. The Rhine-Main region concentrates process analytical technology integration with manufacturing execution systems.
India
CDSCO's relaxed import testing requirements for reference biologics lower biosimilar comparability study costs for European sponsor outsourcing. Generic drug manufacturers drive volume demand for API contract manufacturing. The Hyderabad-Bengaluru corridor clusters analytical services specialization with cost-competitive method development capabilities.
Global Pharmaceutical Contract Manufacturing and Contract Research Market Competitive Landscape
Top-tier vendors anchor integrated discovery-to-commercial platforms, while mid-cap specialists compete on cell and gene therapy modality expertise. The vendor base stratifies across mammalian cell culture capacity owners, viral vector production specialists, and analytical services providers. Three strategic archetypes dominate: biologics capacity aggregators, platform technology licensors, and regulatory advisory integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as sponsors seek dedicated facility commitments.
Within the biologics capacity tier, Samsung Biologics Co., Ltd. and Lonza Group AG exemplify dedicated facility investment archetypes. Thermo Fisher Scientific Inc. occupies a position spanning clinical research and commercial manufacturing through service architecture integration. WuXi Biologics represents the platform technology licensing model for mammalian cell culture scale-up. Fujifilm Diosynth Biotechnologies anchors viral vector production specialization for gene therapy pipelines.
| Leading Market Players |
|---|
| Samsung Biologics Co., Ltd. |
| Fujifilm Diosynth Biotechnologies |
| Lonza Group AG |
| Recipharm AB |
| Siegfried Holding AG |
| Thermo Fisher Scientific Inc. |
| WuXi Biologics |
| PCI Pharma Services, Inc. |
| Catalent, Inc. |
| Others |
Supply & Pricing Matrix
Vertical integration into single-use consumables anchors both supply security and pricing power for biologics contract manufacturers. CDMOs that control bioreactor bag and tubing supply chains command premium contract terms from sponsors facing raw material volatility.
Pricing Analysis
Capacity additions in South Korea and Switzerland are reshaping price floors for mammalian cell culture services. Project-based pricing with milestone payments dominates biologics manufacturing, with differentiation driven by FDA Quality Management Maturity tier and dedicated facility access. Cost compression in small molecule API services is intensifying because Indian generic manufacturers absorb volume demand. Biotechnology firms with cash runway constraints exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize quality tier over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from large pharmaceutical sponsors mandate multi-supplier qualification for critical inputs across India, China, and the United States. GMP-grade plasmid DNA, viral vectors, and single-use bioreactor components constitute essential dependencies. Single-source vulnerability concentrates in three suppliers controlling bioreactor bag and tubing supply. Distribution runs through sponsor-directed logistics with temperature-controlled custody chains from manufacturing site to clinical depot.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder. EMA's strengthened Annex 1 sterile manufacturing requirements drive demand for isolator technology investments exceeding legacy facility retrofit thresholds.
For Market Incumbents: Extend dedicated facility commitments into co-developed process platforms with top-tier biotechnology sponsors. Samsung Biologics and Lonza Group AG anchor this consolidation logic. Capacity scarcity in viral vector production threatens margin compression for mammalian cell culture specialists. Certification investment in FDA Quality Management Maturity Tier 3 ratings secures pre-approval inspection priority. For New Entrants and Emerging Players: The price-point gap between premium biologics capacity and economy small molecule API services opens white-space targeting. CDSCO's relaxed import testing requirements for reference biologics lower biosimilar comparability study barriers in India. Regulatory affairs consulting represents the most penetrable segment as sponsor procurement consolidates under integrated accountability structures. A go-to-market angle anchored in Swissmedic fast-track pathway expertise accelerates European sponsor acquisition. For Investors and Strategic Acquirers: Roll-up economics work for analytical services specialists because CDSCO regulatory relaxation fragments comparability study pricing across regional players. Platform consolidation across method development, stability testing, and biosimilar characterization captures sponsor procurement consolidation. The five-to-ten year viability window favors viral vector production specialists over commodity small molecule capacity. Watch FDA Quality Management Maturity scoring adoption rates as inflection indicator for facility valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Swissmedic fast-track reciprocity with FDA and EMA accelerates global market entry for Basel-Zurich corridor facilities. |
| Manufacturing Scale-Up | Samsung Biologics' Songdo mega-facility anchors dedicated facility commitments from foreign biotechnology sponsors. |
| Clinical Trial Advancement | Oncology and rare disease protocols in Massachusetts absorb viral vector capacity into integrated development partnerships. |
| Backward Integration | CDMO control over single-use consumables supply mitigates resin and film raw material volatility exposure. |
| Licensing Agreement | WuXi Biologics' platform technology licensing model for mammalian cell culture scale-up captures mid-cap biotechnology demand. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and CDMO procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across supply-side capacity announcements, sponsor pipeline disclosures, and regulatory inspection schedules informed the analytical framework. Segmentation dimensions modeled include service type, molecular complexity, therapeutic focus, and regional regulatory cluster. CAGRs were derived from facility investment trajectories and sponsor outsourcing penetration curves. Continuous manufacturing adoption rates and single-use bioreactor deployment timelines served as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for continuous manufacturing with real-time release testing would alter the outlook. Forecasts reflect assumptions regarding ICH Q10 harmonization persistence and MFDS inspection streamlining continuity. Deviation in FDA Quality Management Maturity scoring implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Radiosynthesis Equipment Market