
 Global Lifestyle Drugs Market | 2026-2036
Global Lifestyle Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lifestyle Drugs Market Foresight
The R&D spending gap between large-cap innovators and generic manufacturers is unwinding traditional competitive boundaries in lifestyle therapeutics. Pfizer leverages its global manufacturing footprint to sustain volume leadership in sexual health therapies. Eli Lilly and Company anchors its position through specialized obesity management pipelines that differentiate from commoditized antidepressant offerings.
Lifestyle drugs comprise prescription and over-the-counter pharmaceuticals formulated to enhance quality of life rather than treat acute disease, typically requiring chronic administration with bioavailability thresholds above 80 percent for oral formulations. These products serve commercial purposes spanning mental health stabilization, weight control, anxiety reduction, and sexual dysfunction correction. Antidepressants and weight loss medications occupy the deepest margin pools as chronic-use categories with high refill rates and limited generic erosion in novel formulations. The online platforms distribution channel represents the fastest-growing end user access point, while retail pharmacy channels still dominate total prescription volume for anti-anxiety and stimulant categories where controlled-substance regulations limit digital dispensing.
The FDA maintains strict labeling requirements for direct-to-consumer advertising of lifestyle medications, while the EMA's pharmacovigilance framework shapes post-market surveillance obligations across European markets. India's CDSCO and China's NMPA impose additional bioequivalence standards on imported lifestyle generics that filter market access for multinational portfolios. Stakeholders must monitor evolving digital therapeutics regulations that could reclassify app-integrated drug delivery systems under medical device frameworks.
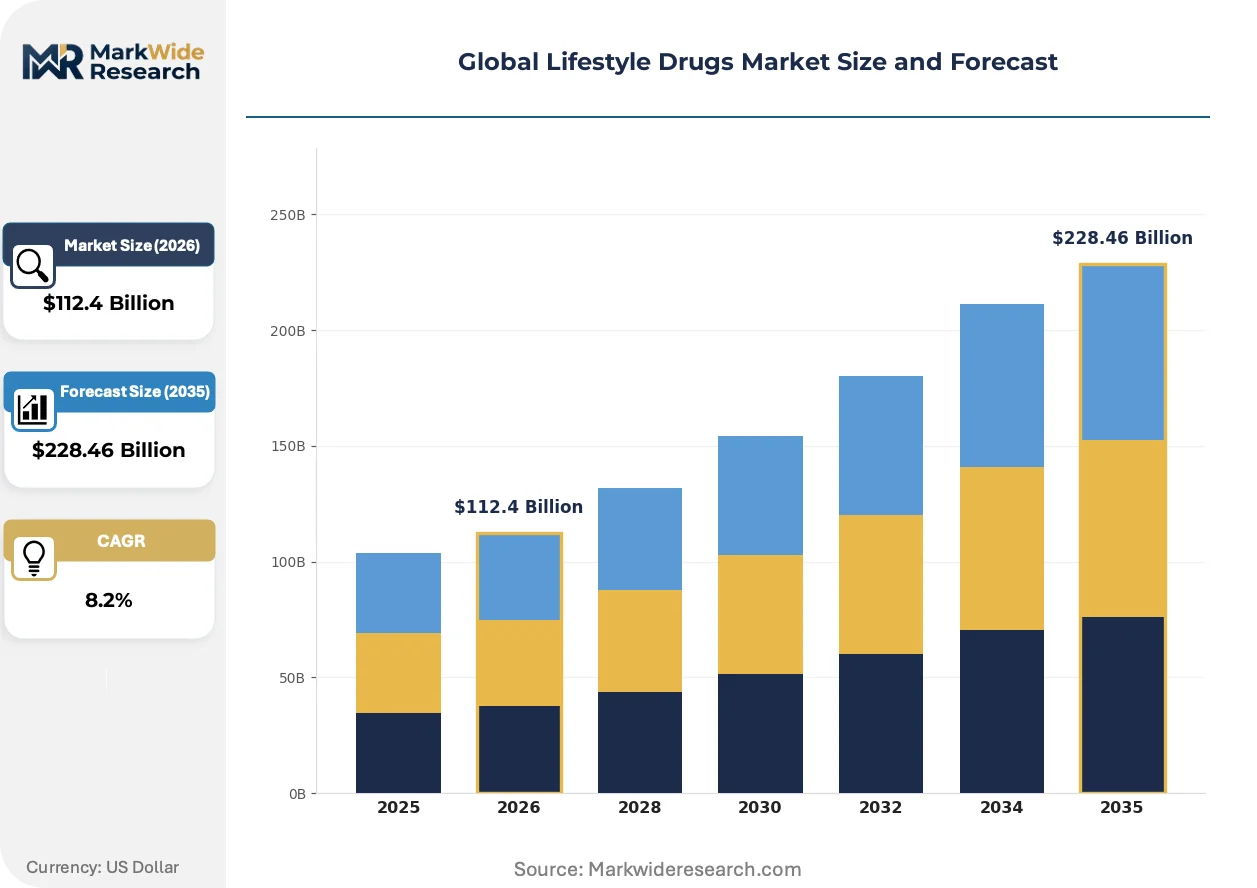
Market Dynamics
Direct-to-consumer digital distribution is compressing traditional pharmacy channels as FDA and EMA pharmacovigilance frameworks tighten advertising oversight for chronic-use lifestyle therapeutics.
Growth Catalysts
- EMA pharmacovigilance expansion:Post-market surveillance obligations for lifestyle medications in European markets are elevating product quality thresholds and filtering substandard competitors from reimbursement lists.
- Self-medication normalization:Aging populations in Germany and the United States are driving prescription refill automation through telehealth-integrated platforms for mental health and weight management therapies.
- Chronic-use bioavailability standards:Oral formulations exceeding 80 percent absorption thresholds are capturing preferential formulary placement in obesity and antidepressant categories.
Market Restraints
- API concentration in China and India:Active pharmaceutical ingredient sourcing for lifestyle generics remains concentrated in NMPA-regulated manufacturing zones, exposing supply chains to export licensing volatility.
- Controlled-substance dispensing limits:Anti-anxiety and stimulant categories face DEA scheduling restrictions that block full digital channel migration and preserve retail pharmacy gatekeeping.
- CDSCO bioequivalence barriers:India's import standards for lifestyle generics create extended regulatory timelines that delay multinational portfolio entry into high-volume domestic markets.
Strategic Opportunities
- Brazil ANVISA fast-track pathways:Emerging regulatory frameworks for novel obesity formulations offer accelerated market access for differentiated GLP-1 receptor agonist pipelines.
- Digital therapeutics reclassification:App-integrated drug delivery systems face potential medical device framework shifts under FDA software-as-medical-device guidance, creating first-mover positioning for compliant platforms.
- Saudi SFDA localization mandates:Domestic manufacturing incentives for imported lifestyle pharmaceuticals are pulling production investment toward Gulf distribution hubs serving Middle East demand concentration.
Industry Challenges
- Pharmacovigilance talent scarcity:Post-market surveillance expertise for lifestyle drug adverse event reporting remains concentrated among legacy regulatory affairs consultancies, inflating compliance staffing costs.
- Legacy pharmacy system integration:Controlled-substance tracking infrastructure in retail networks resists seamless connection with direct-to-consumer telehealth platforms, fragmenting patient data continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lifestyle Drugs Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $228.46 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Stimulants, Weight Loss Medications, Anti-Anxiety Drugs End User: Clinics, Pharmacies, Hospitals, Online Platforms Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale Therapy Area: Mental Health, Obesity Management, Substance Abuse, Sexual Health |
| Companies Covered | Pfizer, Eli Lilly and Company, Merck & Co., Johnson & Johnson, GlaxoSmithKline, Novartis, AstraZeneca, Teva Pharmaceutical Industries, Takeda Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lifestyle Drugs Market Shifts & Advancements
Continuous glucose monitoring integration with weight management therapies is redefining chronic disease boundaries and pulling metabolic health platforms into lifestyle drug adjacencies.
GLP-1 receptor agonist delivery mechanisms is bifurcating between subcutaneous injection devices and oral peptide formulations. Obesity management clinics in the United States are adopting dual-route prescribing protocols based on patient adherence profiles. This technology divergence is compressing market share for single-mode delivery incumbents while expanding addressable populations through preference-matched administration.
FDA software-as-medical-device guidance is reshaping approval pathways for app-integrated lifestyle drug delivery systems. Digital therapeutics combining antidepressant dosing with cognitive behavioral therapy modules now face combined pharmaceutical and device regulatory scrutiny. Mental health platforms incorporating drug adherence tracking are absorbing compliance costs that pure-play pharmaceutical distributors avoid.
Subscription-based prescription fulfillment is displacing per-transaction pharmacy dispensing for chronic lifestyle categories. Anti-anxiety and weight management therapies in Germany are migrating toward automated refill contracts with telehealth providers. This procurement evolution concentrates patient lifetime value with integrated platform operators and marginalizes standalone retail pharmacy relationships.
Global Lifestyle Drugs Market Segmentation
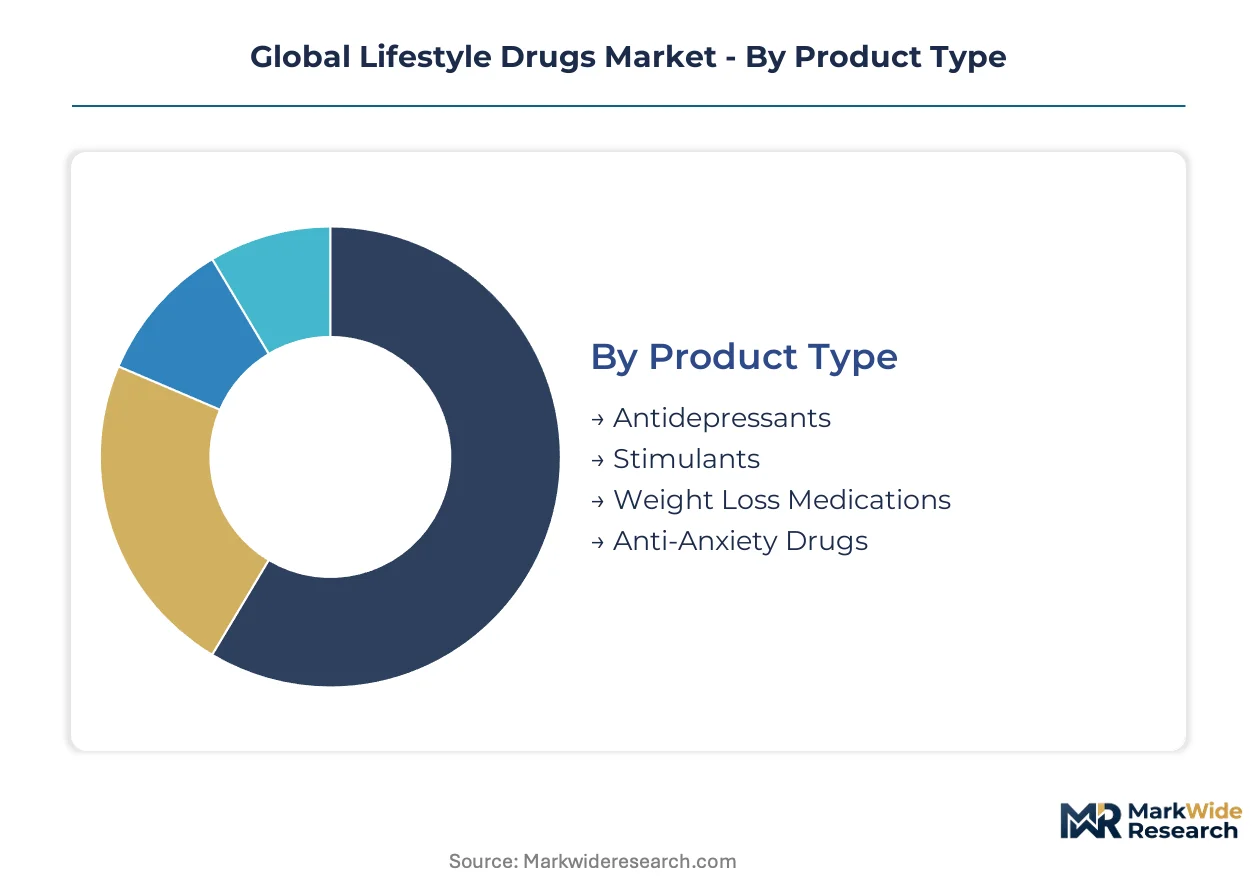
Lifestyle drug segmentation reveals how chronic-use categories command premium pricing while digital distribution channels erode traditional pharmacy gatekeeping. Substitution pressures vary sharply across therapy areas and access points, reshaping competitive boundaries between formulation innovators and platform operators.
Product Type:
Substitution pressure intensifies where generic bioequivalence thresholds exceed 80 percent absorption, commoditizing oral formulations faster than novel delivery mechanisms.
- Antidepressants:Chronic-use oral formulations with bioavailability above 80 percent dominate prescription volumes in Germany and the United States. Demand concentrates through telehealth-integrated platforms as self-medication normalization accelerates refill automation for selective serotonin reuptake inhibitors.
- Weight Loss Medications:GLP-1 receptor agonist pipelines differentiate through dual-route delivery protocols spanning subcutaneous injection devices and oral peptide formulations. United States obesity management clinics drive preference-matched prescribing based on patient adherence profiles.
- Stimulants:DEA scheduling restrictions preserve retail pharmacy gatekeeping for attention-deficit therapies despite digital channel expansion elsewhere.
- Anti-Anxiety Drugs:Controlled-substance dispensing limits fragment patient data continuity between legacy pharmacy systems and direct-to-consumer telehealth platforms.
Antidepressants retain volume leadership; weight loss medications hold the steepest expansion curve.
End User:
Cost tier stratification separates high-touch clinical settings from automated platform fulfillment, with reimbursement policies determining access point viability.
- Online Platforms:Telehealth-integrated prescription automation captures patient lifetime value through subscription-based fulfillment contracts in Germany. FDA and EMA pharmacovigilance frameworks tighten advertising oversight while platform operators absorb combined pharmaceutical and device regulatory scrutiny.
- Pharmacies:Retail networks retain controlled-substance dispensing dominance where DEA scheduling and state-level tracking infrastructure resist seamless digital migration.
- Clinics:Obesity management specialists in the United States adopt dual-route prescribing protocols for GLP-1 therapies based on patient adherence profiling.
- Hospitals:Acute care settings handle lifestyle drug initiation for complex comorbidities before transferring stable patients to outpatient channels.
Pharmacies retain prescription volume leadership; online platforms hold the steepest expansion trajectory.
Distribution Channel:
Geographic concentration of demand shapes channel viability, with aging populations in Germany and the United States pulling fulfillment automation toward integrated platform operators.
- E-commerce:Direct-to-consumer digital distribution compresses traditional pharmacy margins as FDA software-as-medical-device guidance reshapes approval pathways for app-integrated delivery systems.
- Retail:Brick-and-mortar networks preserve anti-anxiety and stimulant dispensing dominance where controlled-substance regulations limit digital channel migration.
- Wholesale:Volume aggregation serves institutional purchasers and pharmacy chains with inventory management for chronic-use categories.
- Direct Sales:Manufacturer-to-patient models face EMA pharmacovigilance expansion requirements for post-market surveillance obligations across European markets.
Retail retains transaction volume leadership; e-commerce holds the steepest expansion curve.
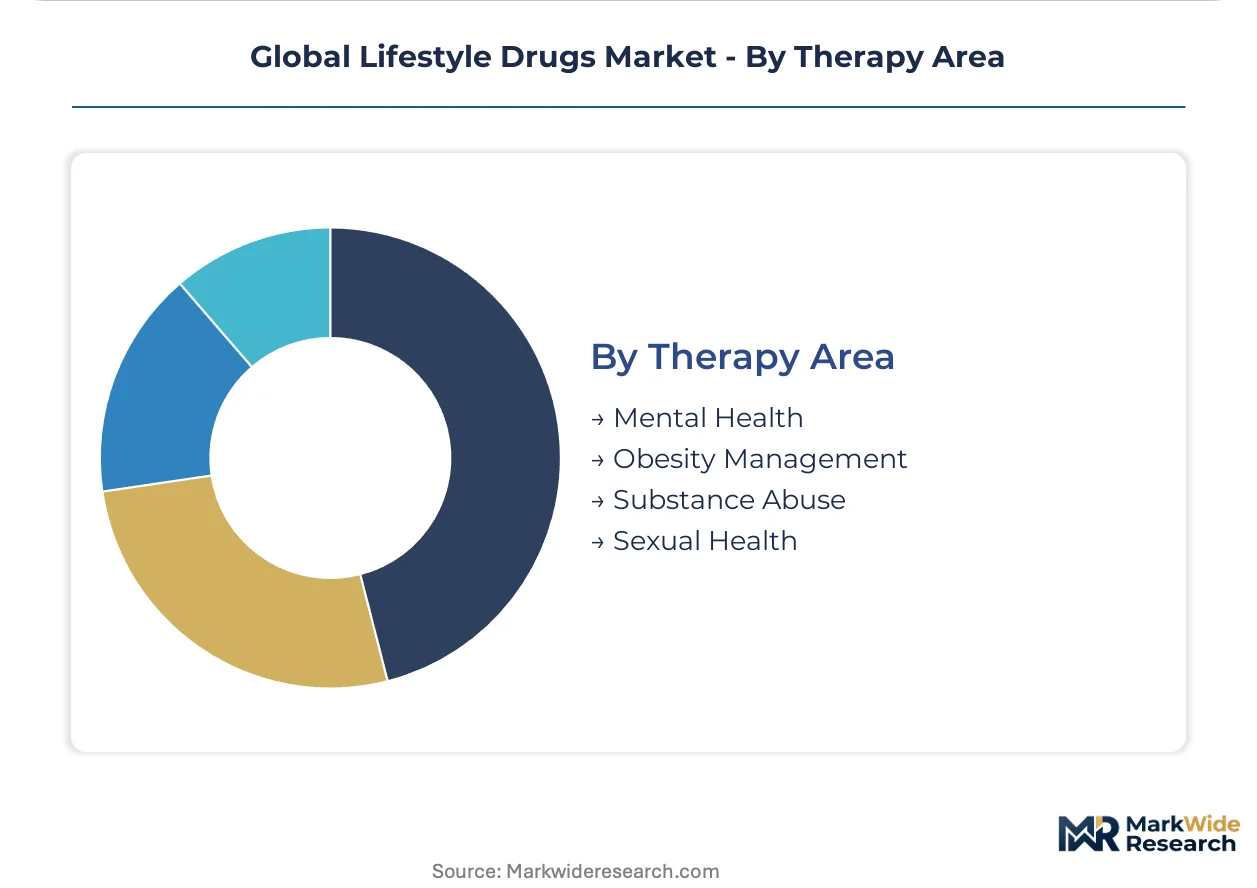
Therapy Area:
Margin concentration pools deepest where chronic administration meets limited generic erosion in novel formulations, separating mental health stabilization from commoditized metabolic interventions.
- Mental Health:Antidepressant and anti-anxiety categories generate high refill rates through subscription-based procurement evolution in Germany. Digital therapeutics combining pharmacological dosing with cognitive behavioral therapy modules face combined FDA pharmaceutical and device regulatory scrutiny.
- Obesity Management:GLP-1 receptor agonist pipelines command premium positioning as continuous glucose monitoring integration redefines chronic disease boundaries and pulls metabolic health platforms into lifestyle drug adjacencies.
- Sexual Health:Global manufacturing footprints sustain volume leadership for oral therapies with established bioequivalence profiles.
- Substance Abuse:Specialized dispensing protocols and DEA scheduling restrictions limit channel flexibility for addiction management therapies.
Mental health retains prescription volume leadership; obesity management holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where aging demographics sustain premium reimbursement rates, while India and China compete on volume through API manufacturing scale and domestic generics penetration.
United States
Self-medication normalization and telehealth platform expansion drive prescription automation for antidepressant and weight management categories. FDA pharmacovigilance frameworks tighten direct-to-consumer advertising oversight for chronic-use lifestyle therapeutics. Boston and San Francisco obesity management clinics adopt dual-route GLP-1 prescribing protocols based on patient adherence profiling.
Germany
Aging population density and subscription-based procurement evolution concentrate demand for mental health and anti-anxiety therapies. EMA pharmacovigilance expansion elevates post-market surveillance obligations and filters substandard competitors from reimbursement lists. Berlin and Munich telehealth platforms capture patient lifetime value through automated refill contracts for chronic lifestyle categories.
China
Domestic demand for weight management and metabolic health platforms accelerates as continuous glucose monitoring integration redefines chronic disease boundaries. NMPA bioequivalence standards on imported lifestyle generics filter market access for multinational portfolios. Shanghai and Beijing pharmaceutical clusters scale domestic GLP-1 receptor agonist manufacturing for regional distribution.
India
API sourcing concentration for lifestyle generics exposes supply chains to export licensing volatility under CDSCO regulatory timelines. CDSCO bioequivalence barriers create extended approval windows that delay multinational portfolio entry into high-volume domestic markets. Hyderabad and Mumbai manufacturing zones anchor active pharmaceutical ingredient production for global lifestyle drug supply chains.
Brazil
Emerging middle-class demand for obesity management and mental health stabilization pulls platform investment toward Latin American distribution hubs. ANVISA fast-track pathways for novel obesity formulations offer accelerated market access for differentiated GLP-1 receptor agonist pipelines. São Paulo and Rio de Janeiro telehealth operators build subscription-based fulfillment infrastructure for chronic lifestyle categories.
Global Lifestyle Drugs Market Competitive Landscape
Concentration sits with large-cap innovators possessing specialized obesity management pipelines and global manufacturing footprints for sexual health therapies. The competitive structure spans three tiers: formulation innovators with novel delivery mechanisms, generic manufacturers competing on bioequivalence certification, and integrated platform operators controlling patient data continuity. Dominant competitive moves include backward integration into API sourcing and strategic partnerships with telehealth platforms for direct-to-consumer channel access.
Among North American pharmaceutical incumbents, Pfizer and Eli Lilly and Company exemplify divergent strategic positioning within lifestyle therapeutics. Pfizer occupies a scale-driven position anchored by global manufacturing infrastructure, while Eli Lilly and Company represents the specialized innovation archetype through differentiated obesity management pipelines. European multinationals including Novartis and AstraZeneca sit within the diversified portfolio tier, balancing lifestyle drug exposure against broader therapeutic category breadth.
| Leading Market Players |
|---|
| Pfizer |
| Eli Lilly and Company |
| Merck & Co. |
| Johnson & Johnson |
| GlaxoSmithKline |
| Novartis |
| AstraZeneca |
| Teva Pharmaceutical Industries |
| Takeda Pharmaceutical |
| Others |
Supply & Pricing Matrix
FDA and EMA pharmacovigilance frameworks gate both supplier qualification and price differentiation simultaneously, elevating compliance costs that filter substandard competitors while sustaining premium tiers for novel formulations with bioavailability thresholds above 80 percent. Chronic-use categories concentrate pricing power with manufacturers possessing integrated platform partnerships, as subscription-based procurement compresses transactional margins for retail pharmacy incumbents.
Pricing Analysis
Customization-premium spreads separate subscription-based telehealth fulfillment from standard retail pharmacy dispensing, with automated refill contracts capturing patient lifetime value in Germany and the United States. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation novelty and delivery mechanism sophistication, while price differentiation hinges on bioequivalence certification and vertical integration into API sourcing. Cost compression in oral generic antidepressants is intensifying because Indian and Chinese manufacturers scale bioequivalent production, leaving obesity management clinics as the least price-sensitive segment due to preference-matched GLP-1 prescribing protocols.
Supply Chain Analysis
Inventory lead times for GLP-1 receptor agonist delivery devices extend where subcutaneous injection manufacturing concentrates in United States and German production clusters, while oral peptide formulations draw from Chinese and Indian API synthesis hubs. Active pharmaceutical ingredient sourcing rests on concentrated NMPA-regulated zones in China and CDSCO-monitored facilities in India, with single-source vulnerability exposing pipelines to export licensing volatility. Distribution runs through wholesale aggregation serving pharmacy chains, though direct-to-consumer e-commerce channels are displacing volume for non-controlled categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital therapeutics reclassification under FDA software-as-medical-device guidance presents a substitution defense imperative, as app-integrated drug delivery systems threaten to commoditize pure-play pharmaceutical distribution.
For Market Incumbents: Compound platform control through backward integration into telehealth subscription infrastructure and captive API sourcing from NMPA-certified Chinese manufacturing zones. GLP-1 delivery mechanism diversification defends against oral peptide formulation entrants, while pharmacovigilance talent acquisition locks in EMA compliance staffing as regulatory affairs consultancies inflate costs. For New Entrants and Emerging Players: Anchor in Brazil's ANVISA fast-track pathways for novel obesity formulations, where accelerated market access rewards differentiated GLP-1 pipelines with limited incumbent platform saturation. White-space concentration sits with mental health digital therapeutics combining antidepressant dosing with cognitive behavioral therapy modules, using hospital system partnerships as the go-to-market angle to bypass retail pharmacy gatekeeping. For Investors and Strategic Acquirers: FDA software-as-medical-device guidance reshapes the acquisition landscape toward platform operators with combined pharmaceutical and device regulatory capabilities. Long-term viability frames around integrated patient data continuity systems over pure formulation assets, with the signal to watch being DEA scheduling relaxation for anti-anxiety digital dispensing as telehealth penetration thresholds cross institutional adoption inflection points.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA pharmacovigilance expansion elevates post-market surveillance obligations for European market access. |
| Backward Integration | Captive API sourcing from NMPA-regulated Chinese zones reduces export licensing volatility exposure. |
| Platform Integration | Telehealth-embedded subscription fulfillment concentrates patient lifetime value away from retail pharmacies. |
| Pipeline Diversification | Dual-route GLP-1 delivery protocols match patient adherence profiles against single-mode incumbents. |
| Strategic Partnership | Hospital system alliances bypass DEA-controlled substance dispensing limits for digital therapeutics entry. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and telehealth platform operators anchored the qualitative base, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling triangulated with top-down reimbursement policy analysis across regional regulatory clusters.
Sensitivity analysis tested forecast robustness across patient adherence scenario variations, dosage form substitution elasticities, and digital channel penetration rates over the projection horizon. Segmentation dimensions spanned therapy area, delivery mechanism, distribution channel, and regional regulatory framework, with CAGRs derived from patient population demographics, refill automation adoption curves, and GLP-1 pipeline advancement timelines.
Decision-makers should treat outputs as directional under stable DEA scheduling and EMA pharmacovigilance enforcement assumptions; material deviation in digital therapeutics reclassification would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Global Eylea Market