
 Global Orally Disintegrating Tablet Market | 2026-2036
Global Orally Disintegrating Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orally Disintegrating Tablet Market Foresight
Modular packaging configurations that pair orally disintegrating tablets with single-dose blister cards is restructuring how hospitals and long-term care centers manage medication adherence and inventory. Pfizer Inc. leverages its manufacturing scale to supply institutional buyers with bundled ODT formats across multiple therapy areas. Teva Pharmaceutical Industries Ltd. competes through specialized fast-melting formulations that target neurology and psychiatric applications where swallowing difficulties are prevalent. Sun Pharmaceutical Industries Ltd. anchors its position in emerging markets with cost-controlled production of immediate-release ODT platforms.
An orally disintegrating tablet is a solid dosage form that disperses or dissolves in the oral cavity within seconds to minutes without requiring water, typically incorporating superdisintegrants such as crospovidone or sodium starch glycolate alongside taste-masking agents to achieve rapid disintegration and acceptable palatability. The primary commercial purpose is to improve medication compliance among patients with dysphagia, pediatric populations, and geriatric individuals who struggle with conventional swallowable tablets. Immediate-release ODTs dominate current volume due to their simpler manufacturing requirements and broader therapeutic applicability across cardiovascular and gastrointestinal indications. Fast-melting formulations represent the fastest-expanding category as neurology and psychiatry applications drive demand for rapid-onset therapeutic effects. Layered tablet configurations command premium positioning where sustained-release and immediate-release components must coexist in a single ODT unit.
The FDA enforces bioequivalence and dissolution standards that shape generic ODT approval pathways and manufacturing quality expectations in the United States. The EMA's MDR framework and REACH compliance requirements govern excipient safety and device-drug combination classifications for ODTs distributed across European markets. Japan's PMDA maintains distinct pharmacokinetic benchmarks for buccal and sublingual absorption profiles that influence formulation development priorities for manufacturers targeting that market. Stakeholders must monitor evolving regulator stances on excipient novelties and absorption standardization as these determinations will dictate which formulation platforms secure preferential market access across jurisdictions.
Market Dynamics
The FDA's tightening bioequivalence standards for generic ODT approvals are compressing formulation development timelines while elevating manufacturing quality thresholds, forcing manufacturers to retool disintegration testing protocols and superdisintegrant sourcing strategies.
Growth Catalysts
- EMA MDR framework:The European Medical Device Regulation's device-drug combination classifications are streamlining ODT excipient safety documentation, accelerating market entry for compliant manufacturers.
- Long-term care centers:Institutional medication adherence programs across Germany and Japan are standardizing single-dose blister card configurations that pair ODTs with compliance tracking.
- Layered tablet configurations:Sustained-release and immediate-release component integration is expanding therapeutic applicability into cardiovascular maintenance therapy.
Market Restraints
- Crospovidone supply concentration:Superdisintegrant production clusters in China create input cost volatility and qualification delays for Western manufacturers.
- PMDA buccal absorption benchmarks:Japan's distinct pharmacokinetic standards for sublingual profiles fragment formulation development priorities and duplicate clinical testing.
- Conventional swallowable tablets:Established dosage forms retain physician preference in adult populations without dysphagia, limiting ODT penetration in standard therapeutic areas.
Strategic Opportunities
- Home healthcare delivery networks:Specialty clinic expansion in the United States is creating direct-to-patient distribution channels that bypass traditional pharmacy intermediaries.
- REACH excipient novelties:The EU's chemical safety framework is incentivizing bio-based superdisintegrant alternatives that command premium positioning.
- Neurology applications:Parkinson's and epilepsy patient populations with swallowing difficulties represent underserved therapeutic segments for rapid-onset fast-melting formulations.
Industry Challenges
- Taste-masking formulation expertise:Shortages of flavor chemists with ODT-specific palatability optimization experience are extending product development cycles.
- Dissolution apparatus standardization:Inconsistent disintegration test methods across FDA, EMA, and PMDA protocols force redundant equipment validation and method transfer costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orally Disintegrating Tablet Market |
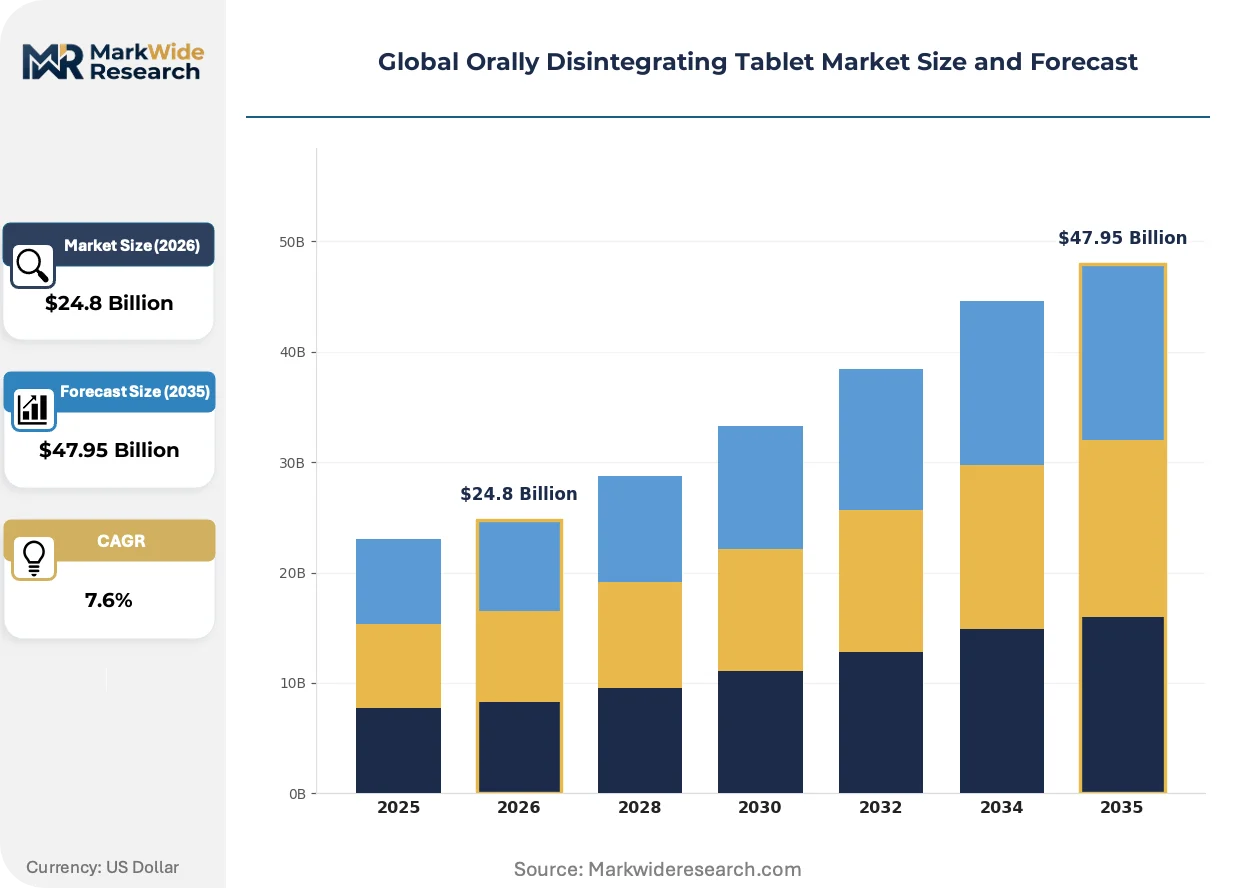
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immediate Release, Controlled Release, Sustained Release, Fast Melting, Layered Tablet Therapy Area: Neurology, Cardiovascular, Gastrointestinal, Respiratory, Endocrinology, Psychiatry End User: Hospitals, Retail Pharmacies, Specialty Clinics, Long-Term Care Centers, Home Healthcare Route of Administration: Buccal, Sublingual, Oral, Orodispersible, Chewable |
| Companies Covered | Pfizer Inc., Johnson & Johnson Services, Inc., Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Novartis AG, GlaxoSmithKline plc., AstraZeneca plc., Mylan N.V., Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orally Disintegrating Tablet Market Shifts & Advancements
Formulation science and regulatory harmonization pressures are converging to reshape how ODT manufacturers balance rapid disintegration performance with taste-masked palatability and manufacturing scale.
Multifunctional excipient platforms that combine superdisintegrant action with taste-masking and binding properties are unifying previously separate formulation steps. Contract development organizations serving institutional buyers in the United States and Germany are adopting these platforms to compress development timelines. The technology is unifying quality control protocols across multiple regulatory jurisdictions by reducing variable excipient interactions.
REACH compliance requirements for novel excipient safety documentation are elevating substitution thresholds for established superdisintegrants in European markets. Manufacturers targeting EMA approval pathways must now submit extended toxicological datasets for crospovidone alternatives. Pediatric and geriatric formulation specialists are responding by pre-qualifying excipient portfolios against both REACH and FDA inactive ingredient database standards.
Hospital procurement departments are consolidating ODT purchasing through centralized pharmacy and therapeutics committees that mandate bioequivalence documentation. This behavioral shift is displacing individual physician preference-based prescribing in long-term care and acute hospital settings. The concentration is most visible in Japan, where institutional formularies now require PMDA-approved dissolution profiles for all listed ODT products.
Global Orally Disintegrating Tablet Market Segmentation
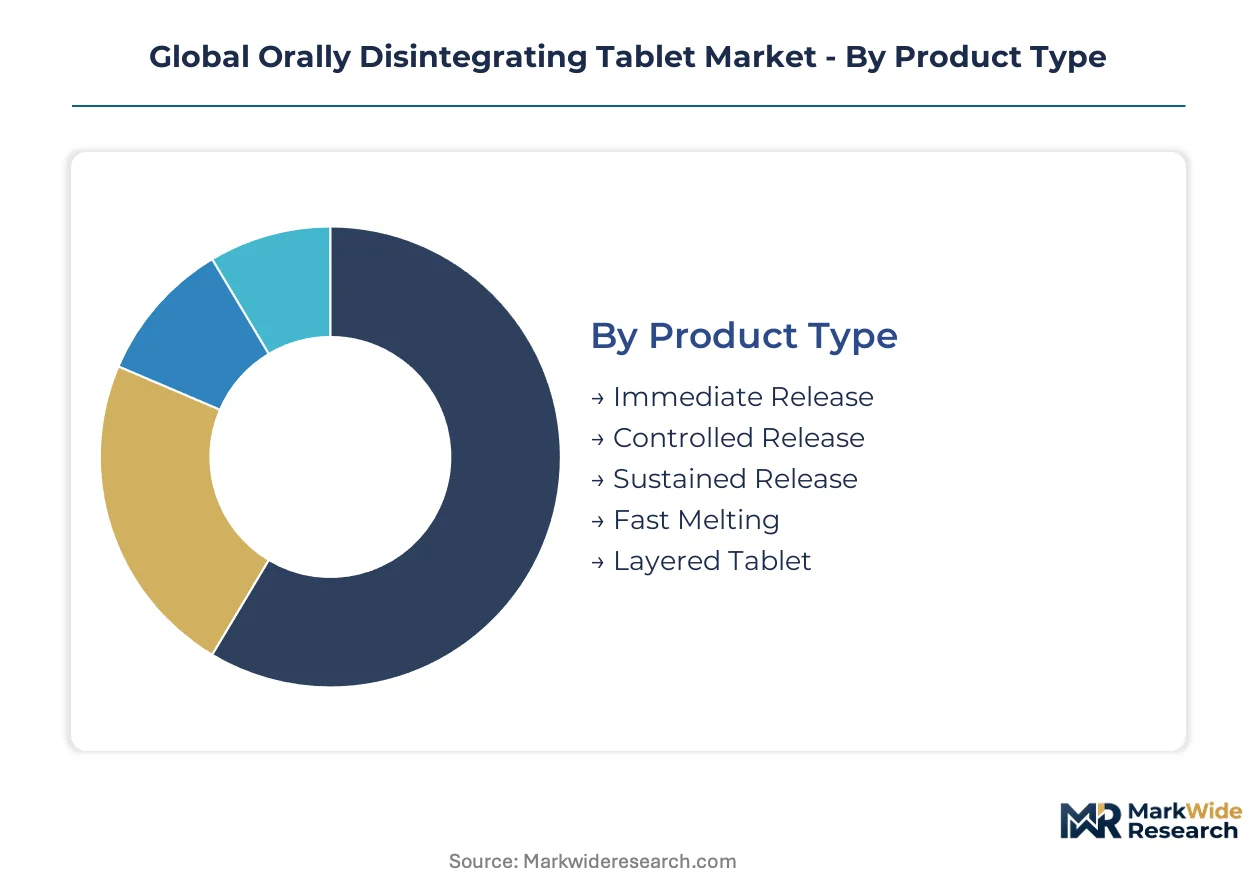
Orally disintegrating tablet manufacturers align R&D investments and manufacturing capacity against distinct formulation architectures, therapeutic applications, and institutional procurement channels. Segmentation clarity determines which superdisintegrant platforms, taste-masking technologies, and regulatory dossiers receive priority funding.
Product Type:
Formulation complexity and disintegration kinetics separate buyers seeking simple immediate-release platforms from those requiring sophisticated multi-layer architectures.
- Immediate Release:Single-layer matrices employing crospovidone or sodium starch glycolate achieve disintegration under 30 seconds without specialized equipment. Demand concentrates in cardiovascular and gastrointestinal applications across German hospital networks where formulary standardization favors proven, low-variability platforms.
- Fast Melting:Optimized particle size distribution and enhanced porosity drive sub-15-second disintegration for neurology and psychiatric indications. Japanese specialty clinics and long-term care centers in Osaka and Tokyo are expanding procurement of these formulations for Parkinson's and epilepsy patients with progressive dysphagia.
- Controlled Release:Matrix-forming polymers modulate active ingredient liberation over defined intervals.
- Sustained Release:Hydrophilic gel layers extend therapeutic windows for chronic conditions.
- Layered Tablet:Immediate-release and sustained-release strata coexist in single units for complex therapeutic regimens.
Volume sits with Immediate Release; growth tilts toward Fast Melting.
Therapy Area:
Patient population swallowing difficulties and acute-onset requirements determine which therapeutic categories justify ODT development costs.
- Neurology:Parkinson's disease, multiple sclerosis, and post-stroke dysphagia create non-negotiable demand for rapid-onset formulations. United States movement disorder clinics and Japanese geriatric hospitals are standardizing ODT protocols for levodopa and anti-epileptic delivery.
- Psychiatry:Acute agitation management and medication adherence in schizophrenia and bipolar disorder drive institutional preference. German psychiatric hospitals prioritize fast-melting antipsychotics that eliminate coercion risks associated with conventional tablet administration.
- Cardiovascular:Antihypertensive and anticoagulant ODTs serve aging populations with polypharmacy complexity.
- Gastrointestinal:Antiemetic and proton pump inhibitor applications leverage rapid buccal absorption.
- Respiratory:Acute bronchospasm and allergy management benefit from water-independent dosing.
- Endocrinology:Hypoglycemic and thyroid hormone formulations address swallowing difficulties in diabetic and elderly cohorts.
Neurology commands premium positioning; psychiatry is expanding most quickly.
End User:
Procurement centralization and patient acuity levels reshape channel economics for ODT suppliers.
- Hospitals:Pharmacy and therapeutics committees mandate bioequivalence documentation and dissolution profile standardization. Acute care facilities in the United States, Germany, and Japan are consolidating purchasing through group purchasing organizations that favor multi-therapy ODT contracts.
- Long-Term Care Centers:Medication adherence programs and nurse administration efficiency drive blister-card standardization. Institutional buyers across Japanese prefectures and German Länder are specifying single-dose packaging with compliance tracking integration.
- Retail Pharmacies:Patient-directed purchasing maintains preference for conventional tablets in non-dysphagia populations.
- Specialty Clinics:Direct-to-patient distribution models bypass traditional pharmacy intermediaries.
- Home Healthcare:Remote patient monitoring integration creates demand for connected packaging formats.
Hospitals dominate procurement volume; long-term care centers show steepest expansion trajectory.
Route of Administration:
Absorption kinetics and regulatory classification requirements fragment formulation development priorities.
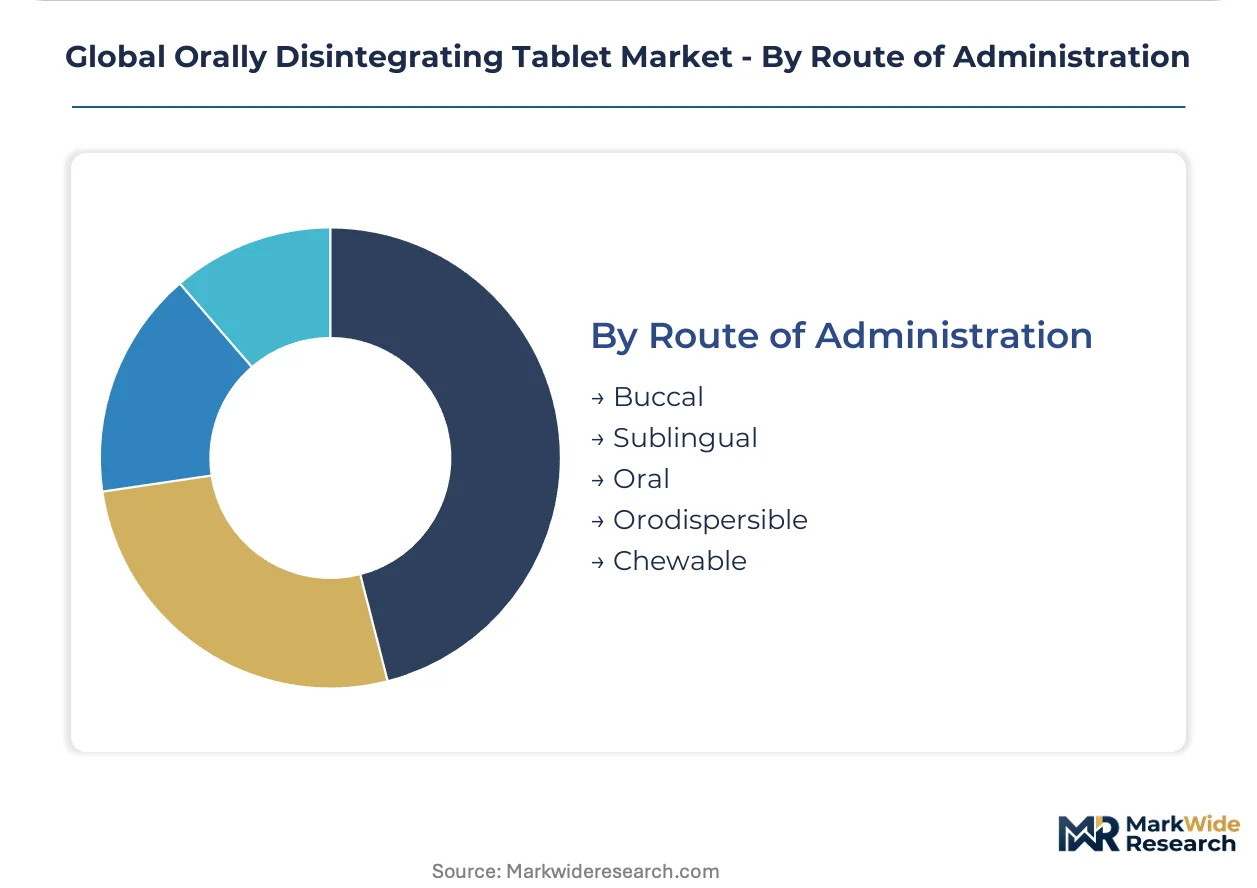
- Sublingual:Rich vascularization beneath the tongue enables rapid systemic absorption bypassing hepatic first-pass metabolism. PMDA maintains distinct pharmacokinetic benchmarks for sublingual profiles that Japanese manufacturers must satisfy for formulary inclusion.
- Buccal:Extended mucosal contact time suits sustained-release applications and local therapeutic effects. EMA device-drug combination classifications under the MDR framework govern excipient safety documentation for buccal systems distributed across European markets.
- Oral:Conventional disintegration without specific mucosal targeting.
- Orodispersible:Rapid dispersion across the entire oral cavity without water requirement.
- Chewable:Mastication-assisted breakdown for pediatric populations.
Sublingual platforms command technical investment; buccal applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for superdisintegrants and finished ODT dosage forms clusters in China and India, while consumption concentrates in aging Western markets with established institutional care infrastructure. The United States, Germany, and Japan absorb the majority of premium fast-melting and layered tablet volumes. Regulatory divergence across FDA, EMA, and PMDA jurisdictions fragments formulation standardization and shapes regional competitive positioning.
United States
Movement disorder clinics and long-term care networks in Florida and Arizona are expanding ODT protocols for Parkinson's and post-stroke dysphagia populations. The FDA's bioequivalence standards for generic ODT approvals are forcing manufacturers to retool dissolution testing protocols. Institutional buyers in Texas and California are consolidating procurement through group purchasing organizations that mandate bioequivalence documentation for formulary inclusion.
Germany
Psychiatric hospitals in Bavaria and North Rhine-Westphalia prioritize fast-melting antipsychotics that eliminate coercion risks associated with conventional tablet administration. The EMA's MDR framework streamlines excipient safety documentation for device-drug combination classifications. Manufacturing specialists in Baden-Württemberg are developing REACH-compliant bio-based superdisintegrant alternatives for premium European positioning.
Japan
Specialty clinics in Osaka and Tokyo are standardizing ODT procurement for epilepsy and geriatric dysphagia patients with progressive swallowing difficulties. The PMDA maintains distinct pharmacokinetic benchmarks for sublingual absorption profiles that fragment formulation development priorities. Institutional formularies in Kanagawa and Aichi prefectures now require PMDA-approved dissolution profiles for all listed ODT products.
India
Contract manufacturers in Gujarat and Maharashtra are scaling cost-controlled immediate-release ODT production for emerging market export. CDSCO alignment with FDA inactive ingredient database standards is accelerating dossier preparation for Western market entry. Hyderabad and Bangalore formulation hubs are specializing in taste-masking chemistry for pediatric and geriatric palatability optimization.
China
Superdisintegrant production concentrates in Jiangsu and Zhejiang provinces, creating input cost volatility for Western manufacturers dependent on crospovidone supply. The NMPA is tightening pharmacokinetic documentation requirements for ODT approvals as domestic geriatric populations expand. Shanghai and Beijing-based CDMOs are investing in multifunctional excipient platforms that unify disintegration and taste-masking properties.
Global Orally Disintegrating Tablet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation complexity tiers, with scale advantages concentrating in institutional supply contracts and technical differentiation residing in neurology and psychiatric applications. The vendor base organizes into three strategic archetypes: multinational pharmaceutical conglomerates leveraging manufacturing scale for bundled hospital contracts, mid-cap generic specialists optimizing cost structures for emerging market penetration, and regional CDMOs serving formulation development for niche therapeutic segments. Competitive moves center on superdisintegrant supply security through backward integration and regulatory dossier pre-qualification against multiple jurisdiction standards.
Within the multinational tier, Pfizer Inc. and Johnson & Johnson Services, Inc. anchor institutional procurement relationships across United States and European hospital networks. Teva Pharmaceutical Industries Ltd. exemplifies the mid-cap generic specialist archetype, occupying a position in fast-melting neurology and psychiatric formulations where swallowing difficulties drive non-negotiable demand. These three entities represent the dominant competitive anchors shaping pricing pressure and formulation innovation trajectories across the analysis window.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Novartis AG |
| GlaxoSmithKline plc. |
| AstraZeneca plc. |
| Mylan N.V. |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Fast-melting formulation premiums diverge sharply from immediate-release commodity pricing, with the former commanding institutional contract premiums in Japanese specialty clinics and German psychiatric hospitals while the latter faces procurement compression through United States group purchasing organizations. This tier bifurcation traces directly to superdisintegrant sourcing strategies, where crospovidone supply concentration in Chinese Jiangsu and Zhejiang provinces anchors input cost volatility for premium formulations while sodium starch glycolate availability supports cost-controlled immediate-release production.
Pricing Analysis
Cost-down pressure on immediate-release ODTs accelerates because United States hospital procurement committees are consolidating formulary contracts through group purchasing organizations that mandate bioequivalence documentation. Three-tier pricing structure across premium fast-melting, standard immediate-release, and economy contract-manufactured levels reflects certification grade differentiation and volume scale. Brand premiums attach to PMDA-approved dissolution profiles in Japan and REACH-compliant bio-based excipient portfolios in Germany. Long-term care centers in Japanese prefectures exhibit highest price sensitivity due to blister-card standardization mandates, while movement disorder clinics in Florida and Arizona maintain lowest sensitivity for rapid-onset neurology formulations.
Supply Chain Analysis
Superdisintegrant supply rests on Chinese specialty chemical producers in Jiangsu and Zhejiang provinces, with secondary sourcing from Indian Gujarat and Maharashtra contract manufacturers for cost-controlled immediate-release platforms. Raw material dependencies center on crospovidone, sodium starch glycolate, and multifunctional excipient platforms combining disintegration with taste-masking properties. Single-source vulnerability concentrates in crospovidone qualification delays for Western manufacturers facing FDA bioequivalence retooling. Distribution runs through institutional pharmacy and therapeutics committees in United States and German hospital networks, with direct-to-patient channels emerging through specialty clinic expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Superdisintegrant production bottlenecks in Chinese coastal provinces prop pricing premiums for fast-melting formulations, creating sustained margin protection for manufacturers with qualified alternative sourcing.
For Market Incumbents: Cement formulary positioning by securing PMDA dissolution profile pre-qualification for Japanese institutional contracts and REACH-compliant excipient portfolios for German psychiatric hospital procurement. Backward integration into bio-based superdisintegrant alternatives mitigates crospovidone supply concentration risk from Chinese producers. Capacity addition in Baden-Württemberg manufacturing clusters captures premium positioning under EMA MDR framework compliance. For New Entrants and Emerging Players: Launch via direct-to-patient distribution models targeting United States specialty clinics in Texas and California that bypass traditional pharmacy intermediaries. White-space concentration sits with fast-melting antipsychotics for German psychiatric hospitals and Parkinson's formulations for Japanese long-term care centers. Taste-masking chemistry expertise represents the most penetrable capability gap, with Hyderabad and Bangalore formulation hubs demonstrating viable specialization paths. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap generic specialists possessing PMDA-approved sublingual platforms given accelerating Japanese geriatric demand. Long-term viability over the five-to-ten year window favors manufacturers with dual-qualified excipient portfolios against FDA and REACH standards. The signal to watch is institutional formulary consolidation velocity in United States group purchasing organizations and Japanese prefectural hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| Superdisintegrant Backward Integration | Captive crospovidone sourcing insulates Western manufacturers from Jiangsu province supply volatility. |
| PMDA Dissolution Profile Pre-Qualification | Japanese institutional formulary mandates require approved pharmacokinetic benchmarks for market access. |
| REACH-Compliant Excipient Portfolio | Bio-based alternatives command premium positioning in German psychiatric hospital procurement. |
| Specialty Clinic Direct Distribution | Texas and California clinic networks bypass pharmacy intermediaries for Parkinson's patient populations. |
| Taste-Masking Chemistry Acquisition | Hyderabad formulation expertise addresses flavor chemist shortages extending product development cycles. |
Research Methodology
FDA filings, EMA MDR submissions, and PMDA pharmacokinetic benchmarks formed the secondary backbone, supplemented by ClinicalTrials.gov ODT protocol registrations and hospital procurement database analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States group purchasing organizations, and hospital procurement managers in German Länder and Japanese prefectures validated secondary findings. Bottom-up segmentation modeling across formulation type, therapy area, and end-user channel triangulated against top-down macroeconomic indicators to establish market sizing.
Historical trendline analysis of immediate-release and fast-melting formulation volumes informed projection modeling across the analysis window, with CAGR derivation incorporating regulatory approval velocity and institutional procurement centralization patterns. Segmentation dimensions encompassed product architecture complexity, patient population swallowing difficulty severity, regional regulatory cluster alignment, and distribution channel concentration. Forecast inputs integrated superdisintegrant supply qualification timelines and bioequivalence testing protocol evolution under FDA standards.
The model assumes a particular technology adoption path; alternative pathways for multifunctional excipient platforms would alter the outlook if REACH compliance timelines accelerate or PMDA sublingual benchmarks harmonize with FDA standards. Forecasts reflect assumptions regarding crospovidone supply stability and institutional formulary consolidation velocity. A small set of triggers—EMA MDR enforcement intensity, Japanese geriatric hospital expansion rates, and United States specialty clinic network growth—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
Global Genitourinary Drugs Market