
 Vitiligo Drugs Market | 2026-2036
Vitiligo Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Vitiligo Drugs Market Analysis
Multi-source API procurement is repositioning how developers secure active pharmaceutical ingredients for topical JAK inhibitors and calcineurin modulators. Incyte Corporation leverages its in-house kinase screening platforms to sustain pipeline momentum across dermatology indications. Pfizer anchors its position through manufacturing scale and broad regulatory dossier experience. LEO Pharma specializes in topical formulation science, competing on dermatology-specific delivery systems rather than systemic exposure profiles.
Vitiligo drugs encompass topical and systemic agents that modulate immune-mediated melanocyte destruction, including corticosteroids, calcineurin inhibitors, and Janus kinase inhibitors formulated for cutaneous application. These therapies aim to arrest depigmentation progression and stimulate repigmentation through localized immunosuppression or targeted cytokine pathway interruption. Janus kinase inhibitors represent the fastest-expanding product category as clinicians seek alternatives to prolonged corticosteroid exposure. Among treatment methods, phototherapy maintains the largest installed base of devices and reimbursement contracts, while combination therapy commands premium positioning where protocols layer topical immunomodulators with narrowband UVB delivery.
The FDA's dermatology and ophthalmology division shapes trial design requirements for novel topical agents, while the EMA's Committee for Medicinal Products for Human Use influences labeling standards that cascade into pricing and access negotiations across European markets. REACH compliance for excipient sourcing adds formulation complexity for manufacturers distributing into the European Union. Stakeholders must monitor how payer evidence requirements for repigmentation endpoints evolve alongside regulatory science discussions on patient-reported outcome measures.
Market Dynamics
The FDA's accelerated approval pathways for dermatology biologics are compressing development timelines and forcing competitors to front-load biomarker validation in Phase II trial designs. This regulatory velocity is reshaping how developers allocate capital across topical JAK inhibitors and calcineurin modulators.
Growth Catalysts
- Phototherapy service expansion:Dermatology clinics across the United States are adding narrowband UVB devices as patient referrals for combination protocols rise steadily.
- REACH compliance adaptation:European manufacturers are reformulating excipient sourcing strategies to maintain distribution access across EU member states.
- University hospital specialization:Germany's dedicated vitiligo centers of excellence are consolidating referral networks and standardizing repigmentation endpoint measurement.
Market Restraints
- Active pharmaceutical ingredient concentration:Multi-source API procurement for topical JAK inhibitors remains concentrated among specialized kinase production facilities in India and China.
- Prolonged corticosteroid exposure limitations:Safety profiles restrict chronic use of first-line topical corticosteroids, creating treatment gaps for maintenance therapy.
- Reimbursement evidence requirements:Payer demands for validated repigmentation endpoints exceed current clinical trial standardization across most European markets.
Strategic Opportunities
- Patient-reported outcome integration:Regulatory science discussions at the FDA and EMA are creating pathways for quality-of-life measures to supplement objective repigmentation metrics.
- Topical formulation convergence:Dermatology-specific delivery systems combining JAK inhibition with calcineurin modulation are opening combination product categories.
- Telemedicine channel development:Remote phototherapy monitoring and prescription management are expanding access in rural United States markets.
Industry Challenges
- Biomarker validation expertise:Clinical trial design for topical immunomodulators requires specialized dermatology biostatisticians familiar with localized pharmacodynamic assessment.
- Legacy phototherapy device integration:Narrowband UVB protocols must interface with electronic health record systems that lack standardized dermatology module configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitiligo Drugs Market |
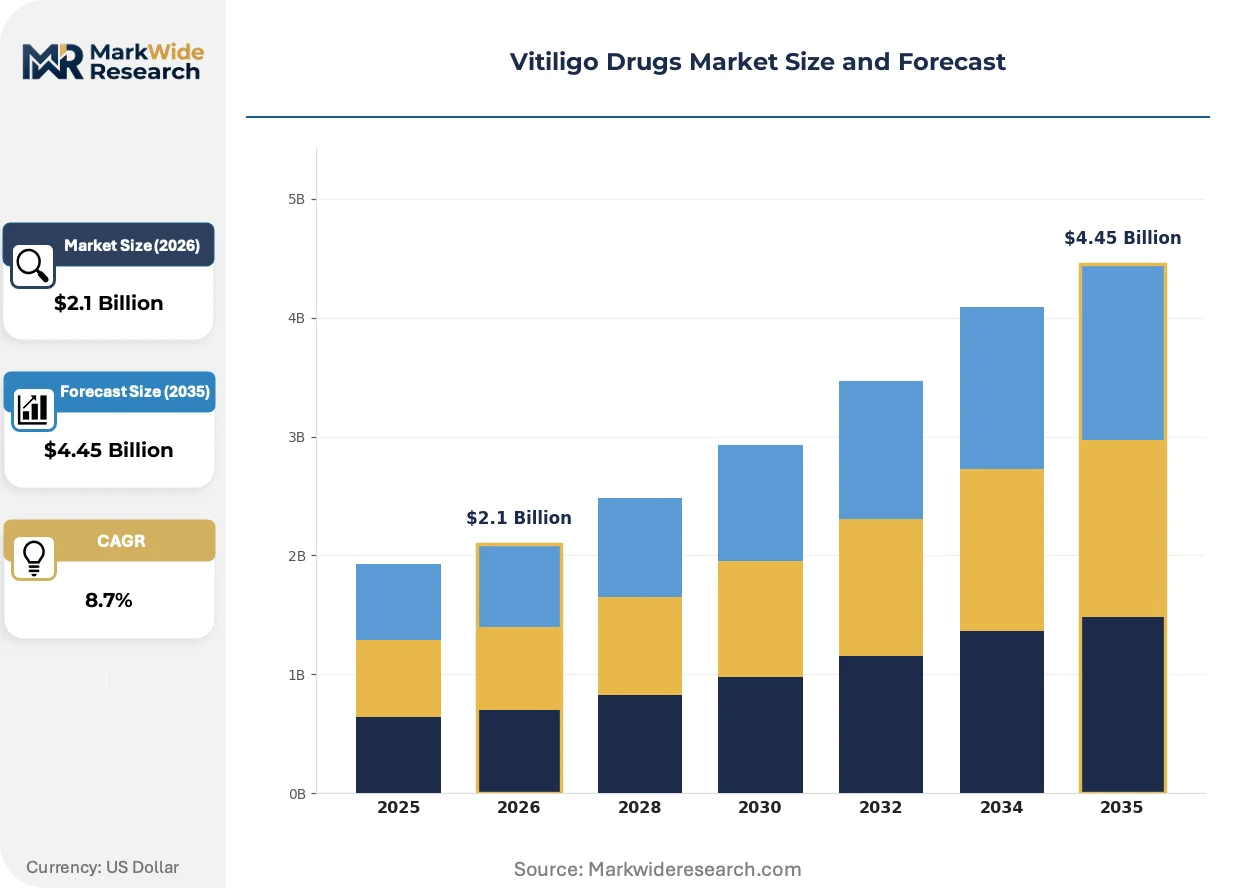
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Calcineurin Inhibitors, Janus Kinase Inhibitors, Excimer Laser Application: Topical Treatment, Light Therapy, Systemic Therapy, Surgical Procedures End User: Hospitals, Dermatology Clinics, Homecare Settings, Ambulatory Surgical Centers Treatment Method: Phototherapy, Immunotherapy, Combination Therapy, Depigmentation Therapy |
| Companies Covered | Teva Pharmaceuticals, STRATA Skin Sciences, Incyte Corporation, Astellas Pharma, LEO Pharma, AbbVie, China Medical System, Bausch Health Companies, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitiligo Drugs Market Emerging Trajectories
Topical Janus kinase inhibitors are absorbing development resources and clinical trial capacity across dermatology pipelines. Three interconnected developments are compressing traditional treatment hierarchies and reshaping competitive positioning.
Topical ruxolitinib formulations are absorbing physician preference in United States academic medical centers as clinicians seek alternatives to corticosteroid tapering protocols. Dermatology practices with established phototherapy infrastructure are adopting JAK inhibitor adjuncts at rates exceeding prior calcineurin inhibitor uptake curves. This absorption is compressing market access timelines for second-generation topical immunomodulators and forcing developers to demonstrate superior localized pharmacokinetic profiles.
The EMA's Committee for Medicinal Products for Human Use is tightening labeling standards for topical agents with systemic absorption potential. Manufacturers must now submit dermatopharmacokinetic data packages that demonstrate minimal percutaneous penetration before market authorization. European markets are responding by demanding excipient documentation that satisfies REACH compliance for novel penetration enhancers.
Patient advocacy networks are consolidating demand for repigmentation outcome transparency and accelerating switching behavior between treatment protocols. United States vitiligo support organizations are publishing treatment satisfaction benchmarks that influence dermatologist prescribing patterns. This behavioral shift is most visible in metropolitan markets with high specialist density where patients compare protocol options across multiple academic centers.
Vitiligo Drugs Market Segmentation
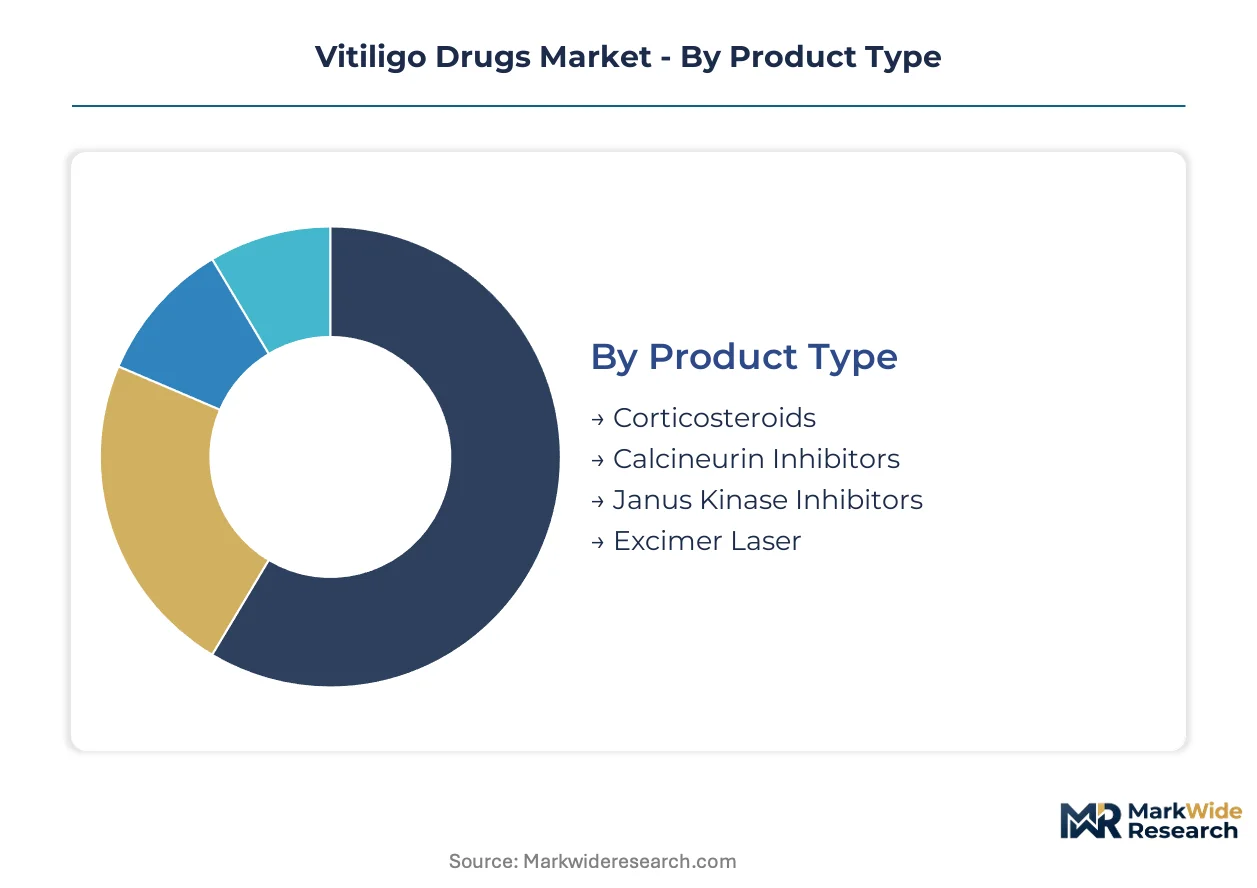
Segmentation in the vitiligo drugs market reveals how treatment hierarchies compress as novel immunomodulators displace legacy protocols. Each dimension exposes distinct procurement patterns, reimbursement pathways, and clinical adoption curves that shape competitive positioning.
Product Type:
The customization-vs-standardization spectrum runs from mass-manufactured corticosteroids to precision-formulated kinase inhibitors with dermatology-specific delivery requirements.
- Janus Kinase Inhibitors:Topical formulations interrupt cytokine signaling through localized JAK1/JAK2 inhibition, minimizing systemic exposure. Demand concentrates in United States academic medical centers where dermatologists seek alternatives to corticosteroid tapering protocols amid rising patient advocacy for maintenance therapy without atrophy risk.
- Calcineurin Inhibitors:Tacrolimus and pimecrolimus ointments suppress T-cell activation through calcineurin-NFAT pathway blockade. German university hospital networks favor these agents for facial and intertriginous lesions where corticosteroid potency restrictions apply, driving formulation innovation in lipophilic bases.
- Corticosteroids:First-line topical anti-inflammatories with established reimbursement but chronic use limitations.
- Excimer Laser:Targeted 308nm UVB delivery systems for localized lesions requiring precision dosing.
Most installed capacity flows through Corticosteroids. Expansion is steepest in Janus Kinase Inhibitors.
Application:
Cost tier stratification separates high-frequency topical dispensing from capital-intensive device-based protocols.
- Topical Treatment:Patient-administered creams and ointments for home-based maintenance. United States dermatology clinics are consolidating prescription volume through specialty pharmacy networks that manage prior authorization for high-cost immunomodulators.
- Light Therapy:Narrowband UVB and excimer laser protocols requiring clinic-based device infrastructure. German vitiligo centers of excellence standardize phototherapy regimens through university hospital networks, creating referral concentration that shapes device procurement cycles.
- Systemic Therapy:Oral immunosuppressants reserved for rapidly progressive or universal disease.
- Surgical Procedures:Melanocyte transplantation and grafting techniques for stable refractory patches.
Volume concentrates in Topical Treatment. Margin expansion tracks Light Therapy.
End User:
Customer type fragmentation reflects divergent reimbursement sophistication and protocol standardization capacity.
- Dermatology Clinics:Outpatient facilities with dedicated phototherapy suites and cosmetic procedure integration. United States private practice networks are acquiring narrowband UVB devices as patient referrals for combination JAK inhibitor-phototherapy protocols accelerate.
- Hospitals:Academic medical centers with clinical trial infrastructure and complex case referral patterns. India's tertiary dermatology departments manage severe vitiligo through systemic immunosuppression under CDSCO oversight.
- Homecare Settings:Patient-managed topical regimens with telemedicine monitoring support.
- Ambulatory Surgical Centers:Procedure-focused facilities for melanocyte transplantation and grafting.
Patient throughput peaks at Dermatology Clinics. Technology adoption velocity is highest at Hospitals.
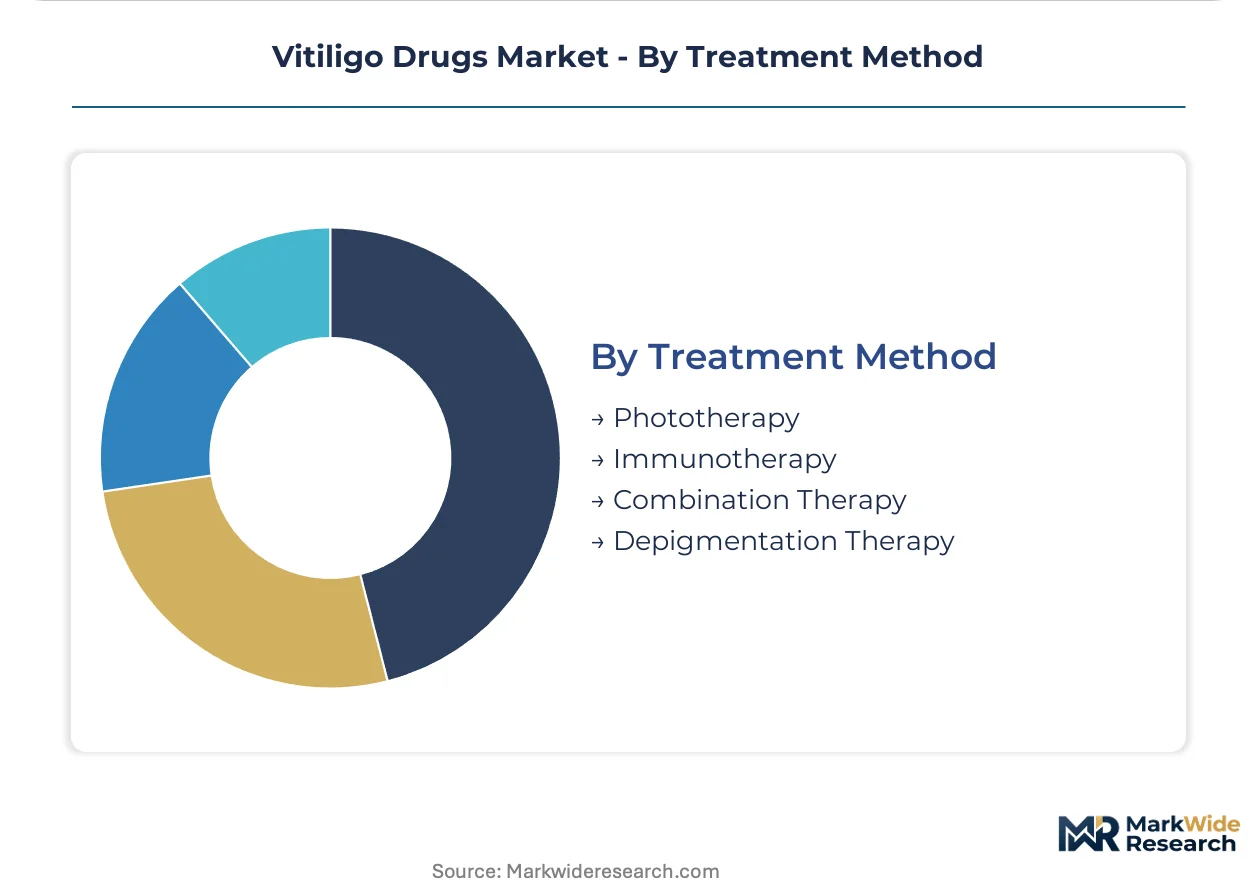
Treatment Method:
Maturity gradients separate established phototherapy protocols from emerging combination approaches still accumulating evidence packages.
- Combination Therapy:Layered topical immunomodulators with narrowband UVB delivery to enhance repigmentation kinetics. United States payers are demanding validated endpoint standardization before extending reimbursement, compressing access timelines for novel protocol iterations.
- Phototherapy:Narrowband UVB and excimer laser with the largest installed device base and established reimbursement contracts. German statutory health insurance funds maintain comprehensive coverage for twice-weekly clinic-based sessions.
- Immunotherapy:Targeted biologics and systemic immunomodulators for aggressive disease subtypes.
- Depigmentation Therapy:Monobenzone-based protocols for universal vitiligo seeking pigment elimination rather than restoration.
Reimbursement stability anchors Phototherapy. Evidence generation priorities center on Combination Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's university hospital networks anchor vitiligo drug demand through dedicated centers of excellence that standardize repigmentation protocols and consolidate referral flows across Central Europe.
United States
Dermatology clinics in metropolitan markets are expanding narrowband UVB device installations as patient referrals for combination therapy accelerate. FDA accelerated approval pathways for dermatology biologics are compressing Phase II trial timelines and reshaping developer capital allocation. Academic medical centers in Boston and New York are absorbing topical JAK inhibitor prescriptions at rates exceeding prior calcineurin inhibitor adoption curves.
Germany
Statutory health insurance funds maintain comprehensive reimbursement for twice-weekly phototherapy sessions, sustaining demand for clinic-based device infrastructure. EMA labeling standards for topical agents with systemic absorption potential are tightening dermatopharmacokinetic documentation requirements. University hospital networks in Munich and Heidelberg operate dedicated vitiligo centers that standardize endpoint measurement and consolidate referral networks.
India
Tertiary dermatology departments manage severe vitiligo cases through systemic immunosuppression protocols under CDSCO oversight. Multi-source API procurement for topical JAK inhibitors concentrates among specialized kinase production facilities in Hyderabad and Mumbai. Government hospital networks in Delhi and Maharashtra are expanding phototherapy access through centralized device procurement programs.
China
Domestic pharmaceutical manufacturers are reformulating excipient sourcing strategies to satisfy REACH-equivalent standards for European market access. NMPA review timelines for dermatology biologics are converging toward international norms, accelerating local developer pipeline progression. Shanghai and Beijing academic medical centers are adopting combination therapy protocols that layer topical immunomodulators with targeted UVB delivery.
Japan
PMDA consultation pathways for novel topical agents are incorporating patient-reported outcome measures alongside objective repigmentation metrics. Metropolitan dermatology clinics in Tokyo and Osaka are integrating excimer laser systems for localized lesion treatment. Domestic formulation specialists are developing lipophilic bases optimized for facial and intertriginous application sites.
Vitiligo Drugs Market Vendor Landscape
Global majors compete with regional champions across regulatory dossier capabilities and dermatology-specific formulation expertise. The market structure fragments across three tiers: multinational pharmaceutical conglomerates with manufacturing scale, mid-cap dermatology specialists with delivery system know-how, and emerging biotech developers with kinase platform technologies. Consolidation pressure concentrates among API procurement relationships and phototherapy device distribution networks. Dominant competitive moves include strategic partnerships for biomarker validation and geographic expansion through specialty pharmacy channel integration.
Within the dermatology specialist tier, LEO Pharma and STRATA Skin Sciences exemplify formulation-centric competitive positioning. Incyte Corporation anchors the kinase platform archetype with in-house screening infrastructure. Pfizer occupies a position at the scale-driven end, leveraging broad regulatory experience across dermatology indications. Teva Pharmaceuticals and Bausch Health Companies represent generic and branded portfolio diversification strategies respectively.
| Leading Market Players |
|---|
| Teva Pharmaceuticals |
| STRATA Skin Sciences |
| Incyte Corporation |
| Astellas Pharma |
| LEO Pharma |
| AbbVie |
| China Medical System |
| Bausch Health Companies |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
Kinase inhibitor API spot prices cascade through topical JAK inhibitor production into three-tier pricing structures across premium, standard, and economy levels, with REACH-compliant excipient costs further stratifying European market access tiers.
Pricing Analysis
Input-cost pass-through from specialized kinase production facilities in India and China compresses margins for mid-tier topical immunomodulator manufacturers. Pricing stratifies across premium, standard, and economy tiers based on dermatopharmacokinetic documentation depth and excipient sourcing geography. Cost compression in standard-tier corticosteroid alternatives is intensifying because multi-source API procurement has expanded supplier competition. Academic medical centers in the United States exhibit lowest price sensitivity due to formulary autonomy, while Indian government hospital networks face highest budget constraint pressure.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume institutional procurement for German university hospital networks, while specialty pharmacy networks manage prior authorization complexity for United States outpatient clinics. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland for kinase inhibitor precursors. Finished formulation draws from lipophilic base chemistries, narrowband UVB device components, and phototherapy maintenance contracts. Single-source vulnerability sits with specialized JAK1/JAK2 screening platforms controlled by limited platform holders. Distribution runs through dermatology-specific wholesalers with cold-chain capabilities for biologic adjuncts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
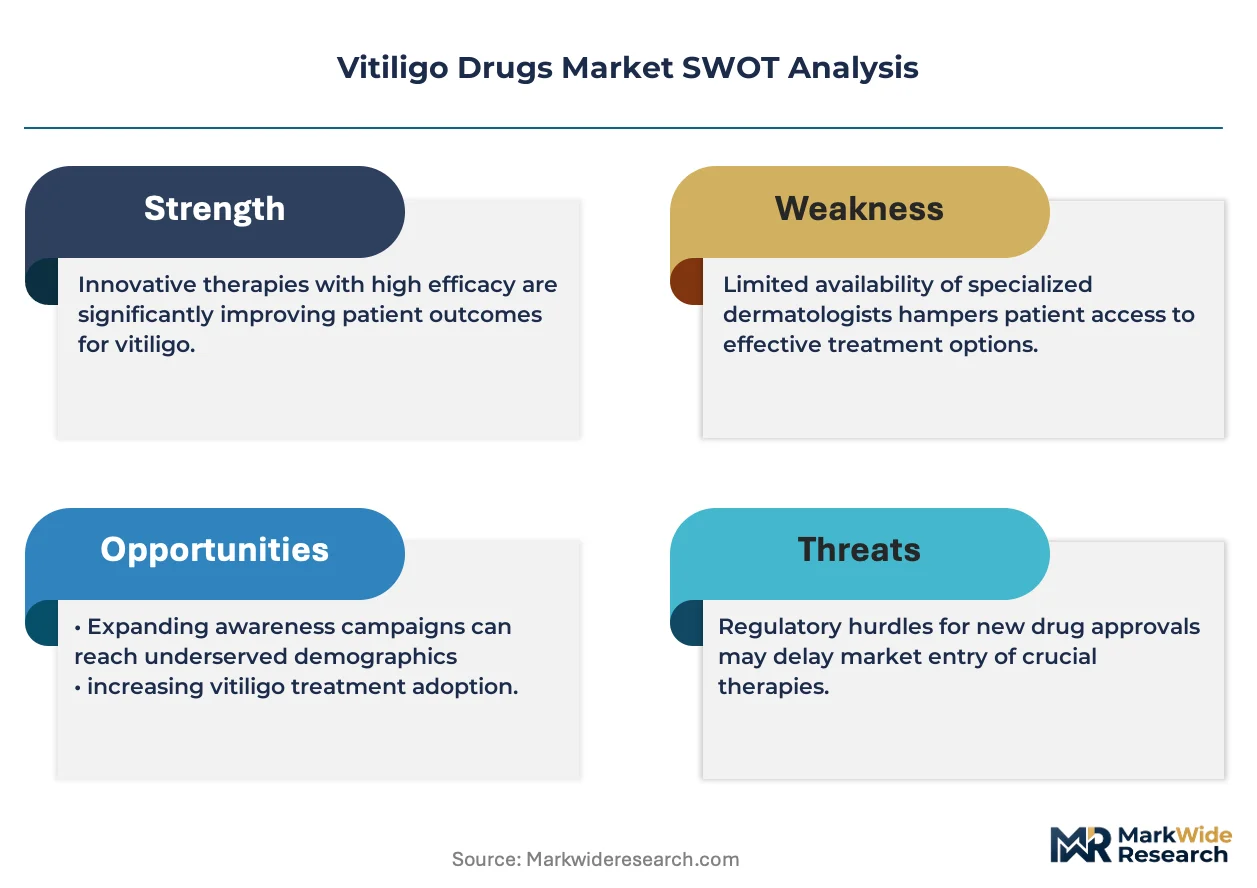
Margin expansion in vitiligo therapeutics rests on excipient cost-down initiatives and premium-tier JAK inhibitor uptake in United States academic centers, shifting value capture from commoditized corticosteroids toward precision immunomodulation.
For Market Incumbents: Anticipate biosimilar pressure on calcineurin inhibitor franchises by deepening backward integration into kinase production and securing captive supply of REACH-compliant penetration enhancers. Prioritize dermatopharmacokinetic data package investments that satisfy EMA labeling standards before competitor submissions. Defend channel position through specialty pharmacy network exclusivity arrangements for combination therapy protocols. For New Entrants and Emerging Players: Lipophilic base formulation innovation for facial and intertriginous application sites offers technology-first wedge into underserved lesion-specific segments. Target rural United States markets with telemedicine-enabled phototherapy monitoring platforms that bypass capital-intensive clinic infrastructure. Pursue white-label manufacturing partnerships with Indian API specialists to compress time-to-market for CDSCO-compliant systemic immunosuppression alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap dermatology specialists possessing in-house formulation science capabilities and established European regulatory dossiers. Long-term viability favors developers with integrated kinase screening infrastructure and phototherapy device distribution relationships. Monitor FDA dermatology and ophthalmology division guidance on patient-reported outcome measures as inflection indicator for quality-of-life-based reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II biomarker validation accelerates FDA accelerated approval pathway access for topical JAK inhibitors. |
| Regulatory Approval Pathway | EMA dermatopharmacokinetic submissions establish labeling precedence for systemic absorption minimization claims. |
| Licensing Agreement | API sourcing partnerships with Hyderabad kinase specialists secure supply continuity for European REACH compliance. |
| Manufacturing Scale-Up | Narrowband UVB device production expansion serves German statutory health insurance reimbursement volume. |
| Pipeline Diversification | Calcineurin-JAK combination formulations open new protocol categories beyond monotherapy standard of care. |
Methodological Framework
Bottom-up dermatology clinic prescribing modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Cross-referencing prescription volume data against manufacturing capacity disclosures enables triangulation between demand-side adoption curves and supply-side constraint identification.
Input-output matrix framing connects patient referral patterns through phototherapy service expansion to device procurement cycles and immunomodulator prescription volumes across the analysis window. Segmentation dimensions modeled include treatment line, dosage form, administration route, patient population, and regional regulatory cluster. CAGRs derive from slope analysis of adoption curve inflection points and reimbursement policy shift timelines. Forecast inputs incorporate EMA labeling standard evolution and payer evidence requirement trajectories for repigmentation endpoints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance on patient-reported outcome integration and REACH excipient restriction amendments. Forecasts reflect documented assumptions regarding phototherapy infrastructure investment continuity and JAK inhibitor safety profile durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Rheumatology Therapeutics Market