
 PD-1/PD-L1 Inhibitor Market | 2026-2036
PD-1/PD-L1 Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
PD-1/PD-L1 Inhibitor Market Insights
Hospital and specialty pharmacy procurement is tilting toward integrated delivery networks with centralized oncology formularies. Bristol-Myers Squibb anchors its position through deep vertical integration across clinical trial infrastructure and manufacturing scale. Merck & Co. dominates the PD-1 landscape with sustained investment in combination therapy pipelines. BeiGene competes aggressively on price while extending its geographic footprint across Asia-Pacific markets.
PD-1/PD-L1 inhibitors are engineered monoclonal antibodies or fusion proteins that block programmed cell death protein 1 or its ligand, restoring T-cell mediated anti-tumor immune response through interruption of immune checkpoint signaling. These agents require cold-chain distribution, sterile intravenous infusion protocols, and biomarker-guided patient selection to achieve therapeutic efficacy. Monoclonal antibodies command the largest revenue pool due to established manufacturing platforms and premium pricing, while biosimilars represent the fastest-growing product type as patent cliffs approach for originator molecules. Non-small cell carcinoma generates the dominant therapy area volume, though bladder carcinoma and renal carcinoma segments are deepening as biomarker testing expands.
The FDA, EMA, and China's NMPA collectively shape market access through divergent evidentiary standards for accelerated approval and post-marketing confirmatory trial requirements. The FDA's Project Optimus mandates dose-optimization studies that extend development timelines but improve long-term safety profiles, while China's NMPA reforms have compressed review periods for innovative biologics. Stakeholders must monitor evolving biomarker coverage policies by CMS and national health technology assessment bodies, as companion diagnostic reimbursement directly determines addressable patient populations for each indication expansion.
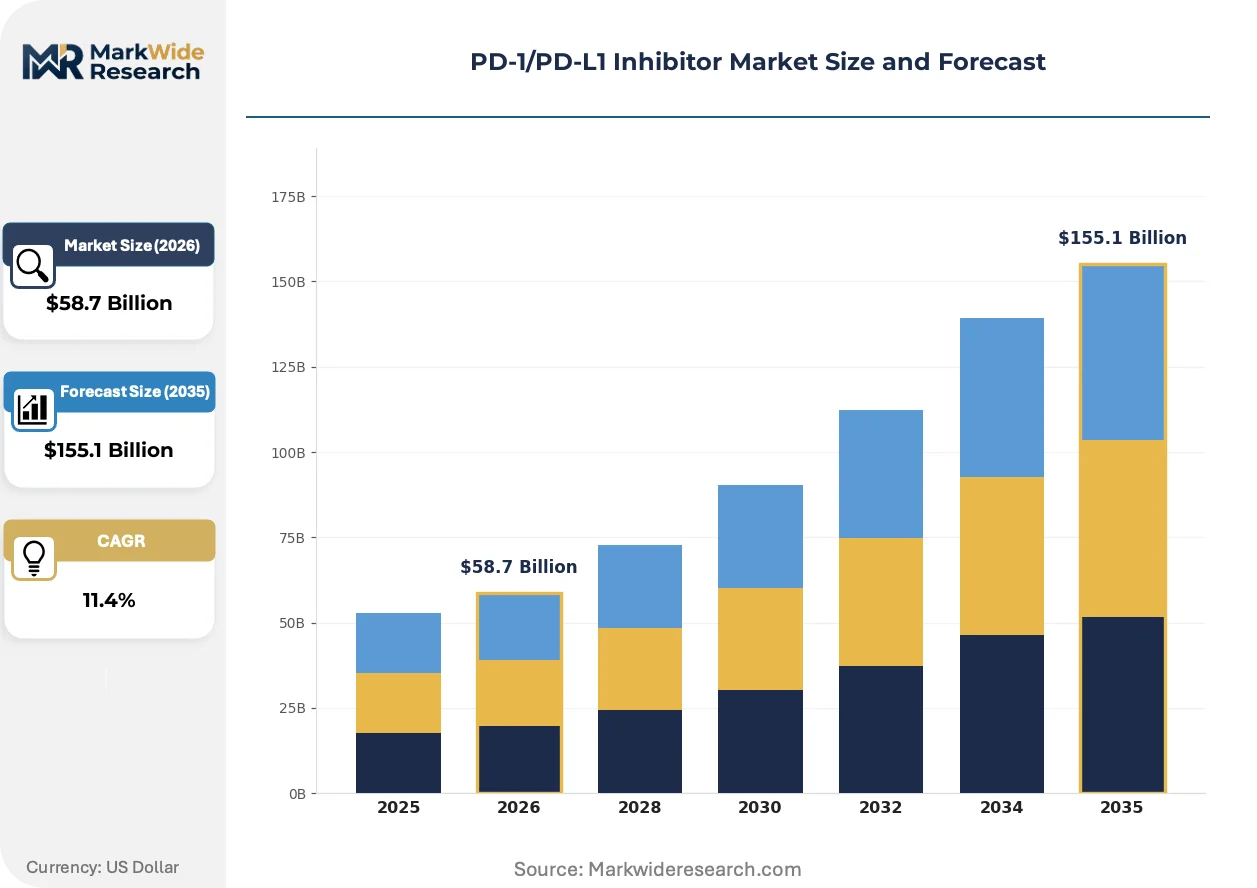
Market Dynamics
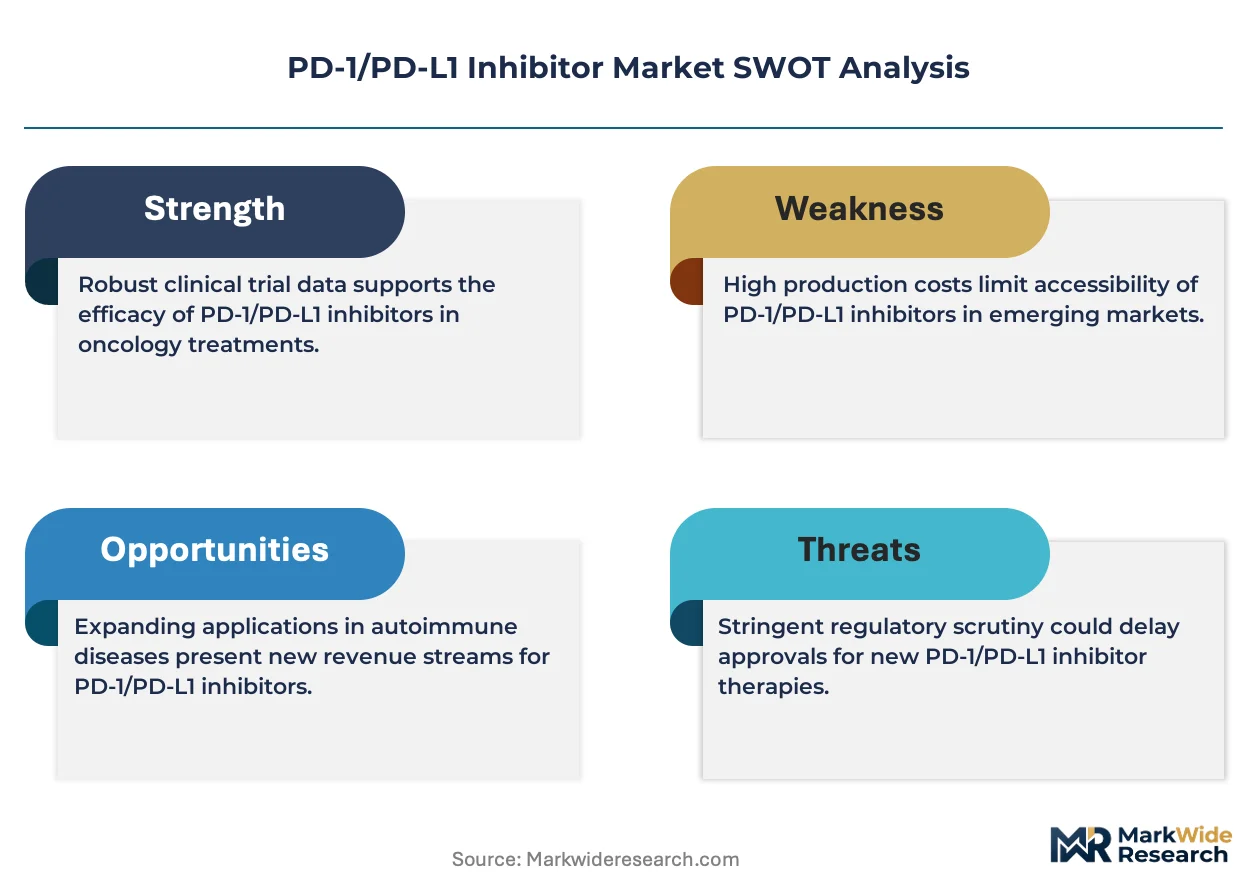
Biomarker-guided patient selection protocols are compressing clinical trial timelines while fragmenting addressable populations into molecularly-defined subsegments. This precision-medicine pivot is forcing manufacturers to build companion diagnostic partnerships alongside therapeutic development.
Growth Catalysts
- FDA Accelerated Approval Pathway:Breakthrough therapy designation compresses Phase II-to-market timelines for checkpoint inhibitors targeting unmet oncologic needs. Post-marketing confirmatory trial requirements sustain revenue protection through label expansion.
- Combination Therapy Pipelines:Pairing PD-1/PD-L1 agents with targeted small molecules or chemotherapy regimens expands addressable indications beyond monotherapy-responsive populations.
- China NMPA Reform:Streamlined review procedures for innovative biologics compress regulatory lag versus Western markets, accelerating commercial launch velocity for domestic and multinational sponsors.
Market Restraints
- Cold-Chain Distribution Concentration:Temperature-controlled logistics infrastructure clusters in the United States, Germany, and Japan, creating supply vulnerability for emerging market access.
- Biomarker Testing Reimbursement Gaps:CMS coverage variability for companion diagnostics restricts patient identification in community oncology settings outside academic medical centers.
- Patent Cliff Proximity:Originators face biosimilar entry pressure as manufacturing process patents expire, compressing pricing power ahead of molecule-specific exclusivity loss.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administration protocols reduce infusion center burden and expand community oncology penetration beyond hospital-based delivery.
- Bladder Carcinoma Biomarker Expansion:PD-L1 expression testing adoption in urothelial carcinoma creates new patient identification channels outside lung and melanoma dominance.
- Integrated Delivery Network Centralization:Hospital system formulary consolidation creates preferential access pathways for manufacturers with comprehensive evidence packages.
Industry Challenges
- Immuno-oncology Talent Scarcity:Translational medicine and biomarker strategy expertise concentrates among limited specialist pools, inflating compensation and extending hiring cycles.
- Confirmatory Trial Execution Risk:Accelerated approval contingent on post-marketing studies creates revenue volatility if endpoints fail, requiring proactive risk-sharing with contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PD-1/PD-L1 Inhibitor Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Biosimilars, Fusion Proteins Therapy Area: Non-Small Cell Carcinoma, Melanoma, Renal Carcinoma, Hodgkin’s Lymphoma, Bladder Carcinoma End User: Oncology Centers, Research Institutes, Specialty Clinics, Diagnostic Laboratories Delivery Mode: Intravenous Infusion, Subcutaneous Injection, Oral Administration, Combination Therapies |
| Companies Covered | Merck & Co., Bristol-Myers Squibb, F. Hoffmann-La Roche, AstraZeneca, Pfizer, Regeneron Pharmaceuticals, Sanofi, BeiGene, Jiangsu Hengrui Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PD-1/PD-L1 Inhibitor Market Trends and Innovations
Digital biomarker platforms and real-world evidence infrastructure are compressing traditional clinical development paradigms while enabling continuous label expansion through adaptive trial designs.
Artificial intelligence-driven patient stratification algorithms are digitizing biomarker interpretation workflows. Community oncology networks in the United States adopt these tools to replicate academic center precision-medicine capabilities. The technology is digitizing site selection and protocol amendment processes, compressing enrollment timelines for combination studies.
EMA's Clinical Trial Regulation harmonizes submission procedures across European member states, eliminating redundant national competent authority reviews. Multinational sponsors consolidate European trial operations into fewer countries with centralized ethics oversight. Oncology trials with EU primary endpoints now initiate faster than under the previous directive-based framework.
Integrated delivery networks are consolidating oncology formulary decision-making into centralized pharmacy and therapeutics committees. Community practices affiliate with hospital systems to secure 340B pricing access, displacing independent physician-owned infusion centers. This concentration is most visible in Texas, Florida, and California, where health system mergers have reduced independent oncology practice counts substantially.
PD-1/PD-L1 Inhibitor Market Segmentation
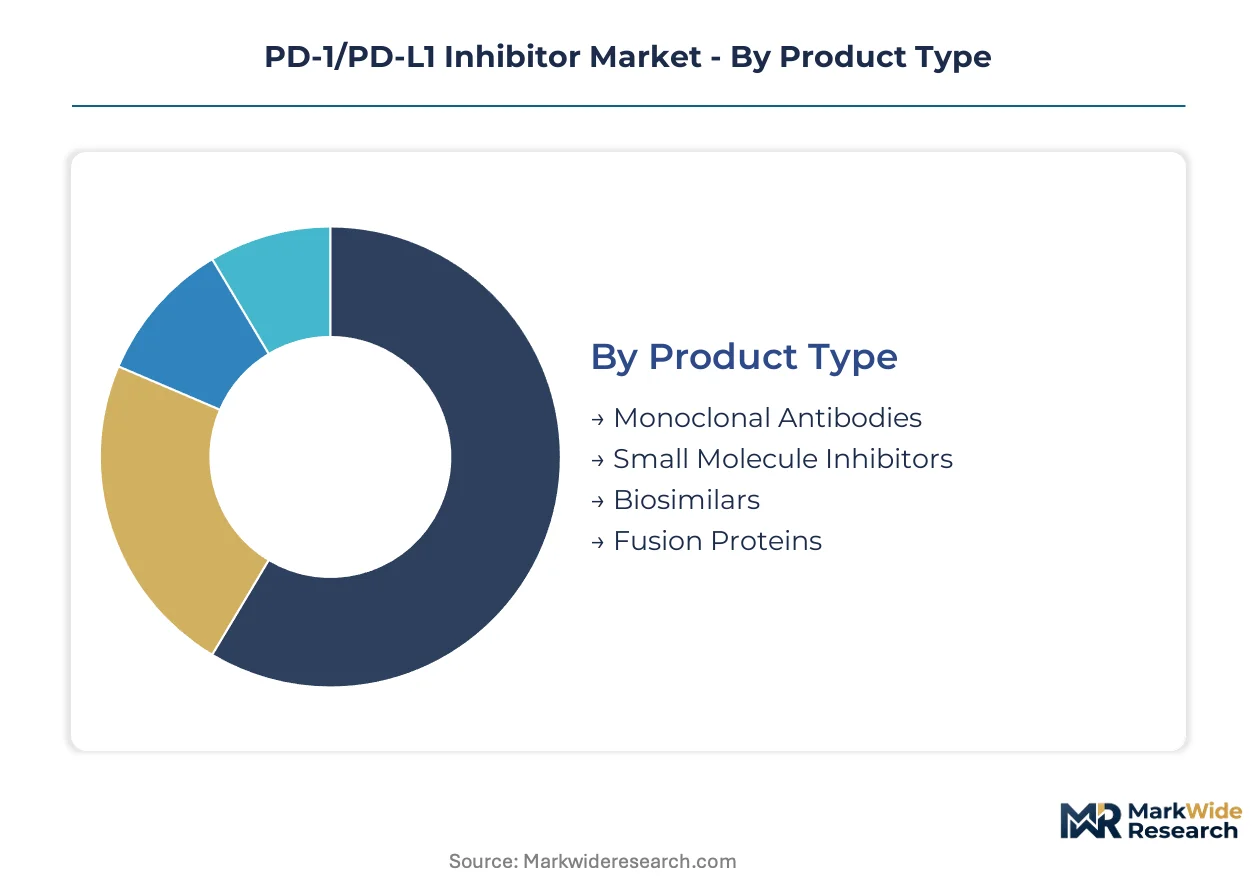
PD-1/PD-L1 inhibitor segmentation reveals how manufacturing complexity, clinical application breadth, and delivery infrastructure shape competitive positioning. Product type stratification exposes the tension between established biologic platforms and emerging biosimilar pressure, while therapy area fragmentation tracks biomarker-guided indication expansion.
Product Type:
Cost tier differentiation separates premium biologics from emerging alternatives, with manufacturing scale and patent status determining pricing power and market access trajectories.
- Monoclonal Antibodies:Engineered immunoglobulins with high binding specificity to PD-1 or PD-L1 epitopes dominate hospital formularies through established cold-chain infrastructure and infusion center workflows. United States oncology centers concentrate procurement of these agents for melanoma and non-small cell carcinoma first-line protocols.
- Biosimilars:Analytical and functional similarity to reference biologics enables abbreviated regulatory pathways, with China's NMPA reforms accelerating domestic manufacturer entry. The steepest expansion trajectory runs through Asia-Pacific markets where originator patent cliffs approach and national health systems prioritize cost containment.
- Small Molecule Inhibitors:Oral bioavailability and simpler synthesis routes offer distribution advantages but face efficacy limitations against large-molecule checkpoint blockade.
- Fusion Proteins:Engineered constructs combining immune checkpoint binding domains with effector moieties occupy niche development pipelines targeting combination therapy synergies.
Monoclonal antibodies command the established base. The steepest expansion runs through biosimilars.
Therapy Area:
Application breadth tracks biomarker validation maturity, with lung and melanoma indications providing commercial anchors while urologic and hematologic malignancies deepen addressable pools.
- Non-Small Cell Carcinoma:PD-L1 expression testing standardization in lung adenocarcinoma and squamous cell histologies creates the largest addressable patient population across United States, China, and Japan. CMS coverage determinations for companion diagnostics directly shape community oncology prescribing patterns.
- Bladder Carcinoma:Urothelial carcinoma biomarker adoption accelerates as FDA approvals expand beyond platinum-refractory settings into perioperative protocols. Academic medical centers in Germany and Japan lead protocol development for muscle-invasive disease neoadjuvant applications.
- Melanoma:First approved indication establishes durable market presence with mature reimbursement pathways and established patient identification infrastructure.
- Renal Carcinoma:Clear cell histology dominance and combination with tyrosine kinase inhibitors defines current utilization patterns.
- Hodgkin's Lymphoma:Relapsed/refractory positioning limits volume despite high response rates in checkpoint-naive populations.
Non-small cell carcinoma anchors revenue concentration. Bladder carcinoma gains share fastest through perioperative label expansion.
End User:
Customer type concentration reflects site-of-care economics, with infusion center consolidation and 340B pricing access determining procurement leverage.
- Oncology Centers:Hospital-based infusion units and affiliated community practices administer the majority of intravenous checkpoint inhibitors, with integrated delivery network formulary committees centralizing purchasing decisions in Texas, Florida, and California health systems.
- Research Institutes:Academic medical centers with early-phase trial infrastructure drive combination therapy protocol development and biomarker discovery programs.
- Specialty Clinics:Independent physician-owned practices face displacement as affiliation with hospital systems becomes necessary for 340B pricing access.
- Diagnostic Laboratories:Companion diagnostic testing providers enable patient selection but face reimbursement variability outside academic referral networks.
Oncology centers control the volume base. Research institutes concentrate the innovation pipeline.
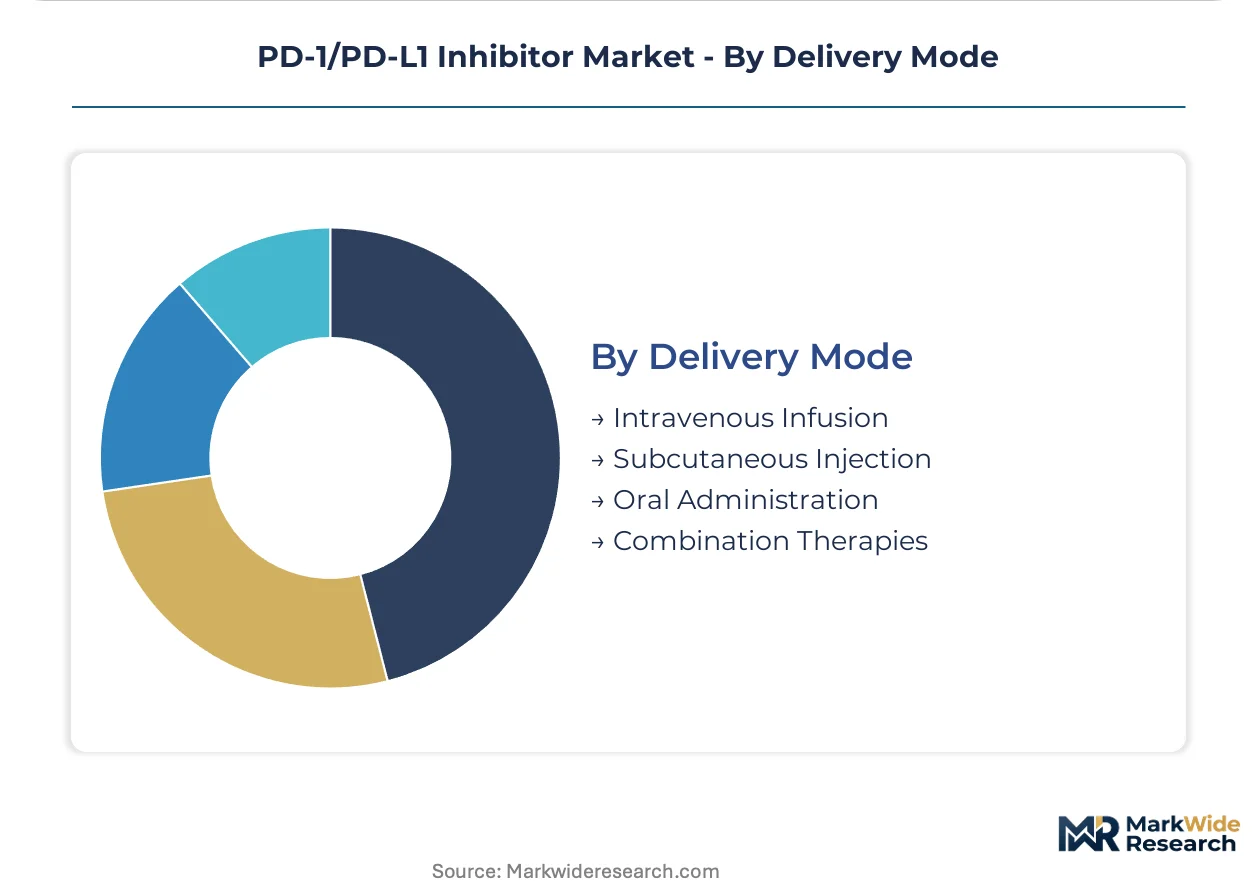
Delivery Mode:
Supply concentration in intravenous administration creates infrastructure dependencies, while subcutaneous development promises site-of-care flexibility.
- Intravenous Infusion:Sterile compounding requirements and cold-chain maintenance through infusion center workflows define current standard of care. United States hospital systems invest in centralized pharmacy operations to manage preparation volume and waste reduction.
- Subcutaneous Injection:Self-administration potential reduces infusion center burden and expands community oncology penetration, with formulation stability challenges driving device co-development partnerships.
- Oral Administration:Bioavailability limitations and first-pass metabolism constraints restrict small-molecule checkpoint approaches to investigational combinations.
- Combination Therapies:Sequential or concurrent administration with chemotherapy, targeted agents, or radiation requires protocol complexity management across multidisciplinary tumor boards.
Intravenous infusion maintains the infrastructure base. Subcutaneous injection climbs the fastest through patient convenience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-chain logistics networks anchor pharmaceutical distribution capacity for temperature-sensitive biologics. Major oncology hubs cluster near international airports with dedicated pharmaceutical cargo terminals. Regulatory harmonization initiatives compress cross-border approval timelines for checkpoint inhibitors.
United States
Integrated delivery networks in Texas, Florida, and California consolidate oncology formulary decisions through centralized pharmacy committees. The FDA's Project Optimus mandates dose-optimization studies that extend development timelines. Memorial Sloan Kettering Cancer Center in New York anchors combination therapy protocol development.
China
Domestic manufacturers exploit NMPA reform timelines to accelerate biosimilar entry against originator molecules. The National Reimbursement Drug List expansion prioritizes innovative biologics for cancer indications. Shanghai's Zhangjiang Hi-Tech Park concentrates monoclonal antibody manufacturing infrastructure.
Japan
PMDA's Sakigake designation system compresses review periods for breakthrough oncology therapies. National health insurance price premiums sustain reimbursement for novel immuno-oncology agents. The Kanto region around Tokyo hosts the highest density of academic medical center trial sites.
Germany
IQWiG health technology assessments determine companion diagnostic reimbursement at federal level. EMA centralized procedures enable simultaneous EU-wide market access from Frankfurt logistics hubs. Heidelberg and Munich academic clusters drive biomarker-guided neoadjuvant protocol development.
United Kingdom
NICE single technology appraisals create binary market access decisions with limited negotiation latitude. The Cancer Drugs Fund provides provisional reimbursement pending confirmatory trial outcomes. London's Royal Marsden Hospital anchors early-phase combination studies through its academic partnership network.
PD-1/PD-L1 Inhibitor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with manufacturing scale or biomarker expertise. The PD-1/PD-L1 inhibitor market consolidates around originator biologics with established infusion center relationships and biosimilar entrants exploiting patent cliffs. Three archetypes dominate: vertically integrated pharmaceutical conglomerates with clinical trial infrastructure, regional biotech specialists with price-competitive manufacturing, and emerging biosimilar pure-plays with abbreviated regulatory pathways. Competitive moves concentrate on companion diagnostic partnerships and subcutaneous formulation development to differentiate infusion center economics.
Among originator-tier anchors, Merck & Co., Bristol-Myers Squibb, and Roche occupy positions defined by first-mover indication approvals and combination therapy pipeline depth. BeiGene represents the Asia-Pacific specialist archetype with manufacturing scale advantages and NMPA regulatory familiarity. These named entities exemplify how geographic regulatory expertise and manufacturing platform control translate into formulary positioning rather than specific product-level claims.
| Leading Market Players |
|---|
| Merck & Co. |
| Bristol-Myers Squibb |
| F. Hoffmann-La Roche |
| AstraZeneca |
| Pfizer |
| Regeneron Pharmaceuticals |
| Sanofi |
| BeiGene |
| Jiangsu Hengrui Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Frankfurt-Rotterdam pharmaceutical cargo corridors anchor cold-chain cost dynamics for temperature-sensitive biologics, with freight concentration in these lanes amplifying pricing power for originator manufacturers while compressing margins for biosimilar entrants dependent on shared logistics infrastructure.
Pricing Analysis
Volume-discount tiering structures separate originator monoclonal antibodies from emerging biosimilars across hospital procurement negotiations. Three-tier pricing stratification across premium originators, mid-tier licensed products, and economy biosimilars reflects manufacturing scale and patent status. Pricing pressure stems from China's NMPA accelerating domestic biosimilar approvals ahead of Western patent cliffs. Community oncology centers exhibit highest price sensitivity due to 340B pricing dependency, while academic medical centers prioritize clinical evidence over cost.
Supply Chain Analysis
Supplier-financing facilities from contract manufacturing organizations extend payment terms for biologics producers managing working capital through lengthy regulatory review periods. Manufacturing concentration in the United States, Germany, and China creates dependencies on specialized single-use bioreactor systems and serum-free cell culture media. Single-source vulnerability for critical raw materials from limited qualified suppliers threatens production continuity. Distribution runs through integrated delivery network central pharmacies with formulary committee gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic service layers expand faster than therapeutic hardware, creating recurring revenue streams through biomarker testing protocols that outpace drug price erosion.
For Market Incumbents: Harden manufacturing scale advantages through captive bioreactor capacity in Singapore and Switzerland to offset biosimilar price competition. Secure exclusive companion diagnostic partnerships with Foundation Medicine and Guardant Health to lock formulary positioning before label expansion. Consolidate clinical trial infrastructure through preferred site networks in Texas and Florida health systems.
For New Entrants and Emerging Players: Establish a beachhead in subcutaneous formulation development for community oncology penetration outside hospital-based infusion centers. Target bladder carcinoma perioperative protocols where biomarker testing infrastructure remains underdeveloped relative to lung cancer. Pursue NMPA regulatory familiarity as the go-to-market angle for Asia-Pacific commercial velocity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform biotechs with manufacturing process patents and biomarker-guided indication pipelines. Long-term viability hinges on combination therapy optionality across five-to-ten year development horizons. Watch FDA confirmatory trial failure rates as the inflection indicator for accelerated approval revenue risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Foundation Medicine collaboration secures patient identification infrastructure for label expansion. |
| Subcutaneous Formulation Development | Halozyme-enabled delivery reduces infusion center burden and expands community oncology access. |
| Integrated Delivery Network Contracting | Texas and Florida health system formulary consolidation creates preferential procurement pathways. |
| Manufacturing Scale-Up | Singapore bioreactor clusters anchor supply security for Asia-Pacific commercial expansion. |
| Regulatory Approval Pathway | China NMPA reform exploitation compresses review timelines versus FDA and EMA procedures. |
Research Methodology
Cross-validation between formulary database analysis and clinical trial investigator interviews anchors the qualitative findings in this study. Primary fieldwork encompassed drug development executives at originator and biosimilar manufacturers, regulatory affairs leads navigating FDA Project Optimus and NMPA reform timelines, hospital formulary directors at integrated delivery networks, and payer access specialists managing CMS coverage determinations. Secondary sources triangulated against these interviews include FDA accelerated approval letters, EMA centralized procedure assessments, ClinicalTrials.gov protocol registrations, and hospital procurement databases tracking 340B pricing utilization. Bottom-up patient-flow modeling and top-down revenue reconciliation validated segment-level estimates.
Calibration against historical approval-to-launch intervals and price erosion curves from prior biologic patent cliffs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, therapy area, end user, and delivery mode, with regional regulatory cluster differentiation for United States, China, Japan, Germany, and United Kingdom markets. CAGRs derived from indication-specific patient population growth, biomarker testing penetration assumptions, and pricing trajectory scenarios. Forecast inputs included CMS companion diagnostic coverage policy evolution and NMPA biosimilar approval velocity.
Stress conditions across FDA confirmatory trial failure rates, China reimbursement list inclusion timing, and cold-chain logistics disruption severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about biomarker adoption curves and health system consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
United States Pharmaceutical 3PL Market