
 Antiviral Immunoglobulin Market | 2026-2036
Antiviral Immunoglobulin Market Size, Share, and Industry Trends Forecast 2026-2036
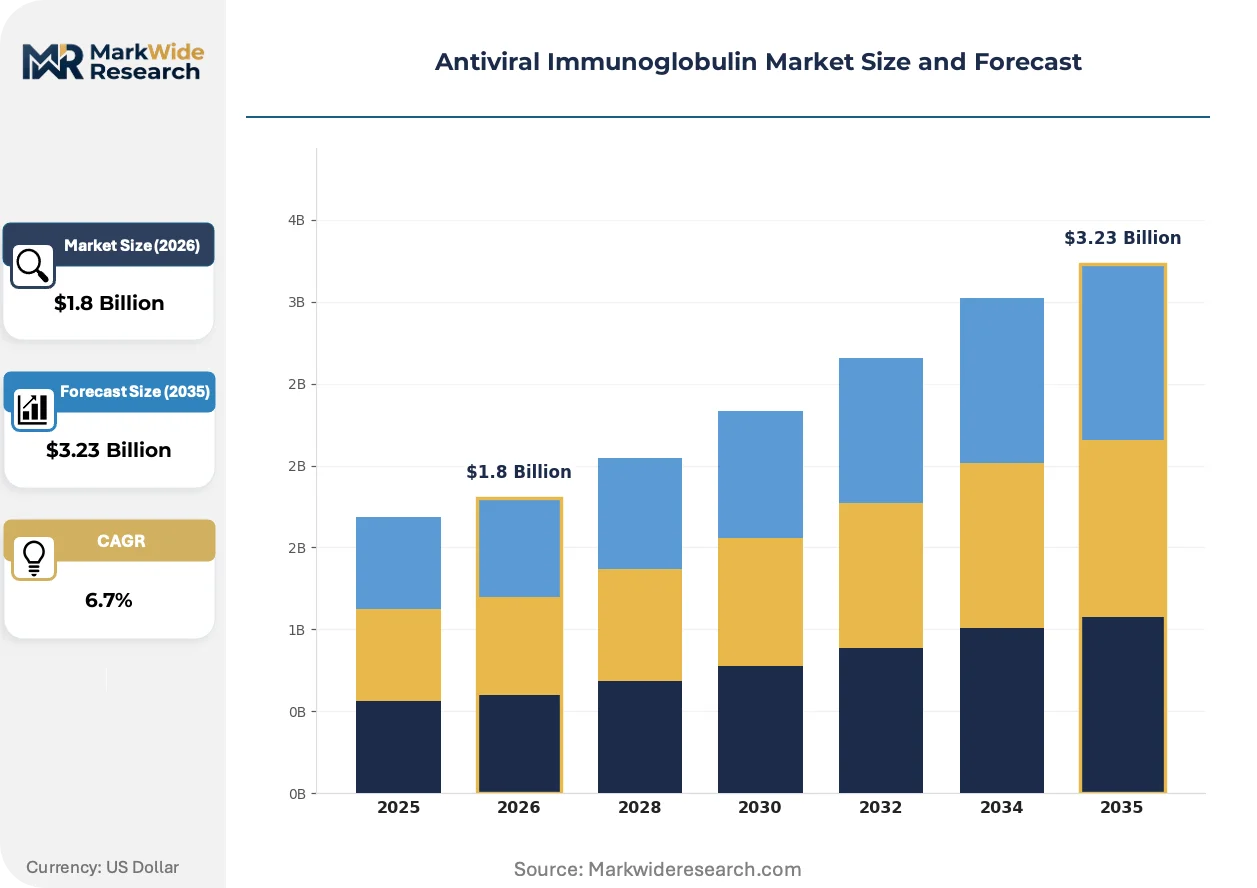
Antiviral Immunoglobulin Market Outlook
Project finance for plasma fractionation facilities is tilting competitive dynamics toward capital-rich operators. CSL Behring leverages its vertically integrated plasma collection network across multiple continents to sustain raw material security. Grifols anchors its position through one of the world's largest donor center footprints, while Kedrion Biopharma specializes in regional European distribution of hyperimmune products.
Antiviral immunoglobulin comprises pathogen-specific antibody preparations derived from human plasma, typically containing immunoglobulin G concentrations exceeding 95 percent with defined neutralizing titers against target viruses, manufactured through cold ethanol fractionation and viral inactivation steps to provide passive immunity in immunocompromised or exposed patients. Intravenous immunoglobulin dominates current volume due to established reimbursement pathways and broad off-label antiviral use, while subcutaneous immunoglobulin represents the fastest-expanding administration mode as homecare protocols reduce hospital dependency. Hyperimmune globulin commands premium positioning given its targeted pathogen specificity and constrained plasma donor pool requirements.
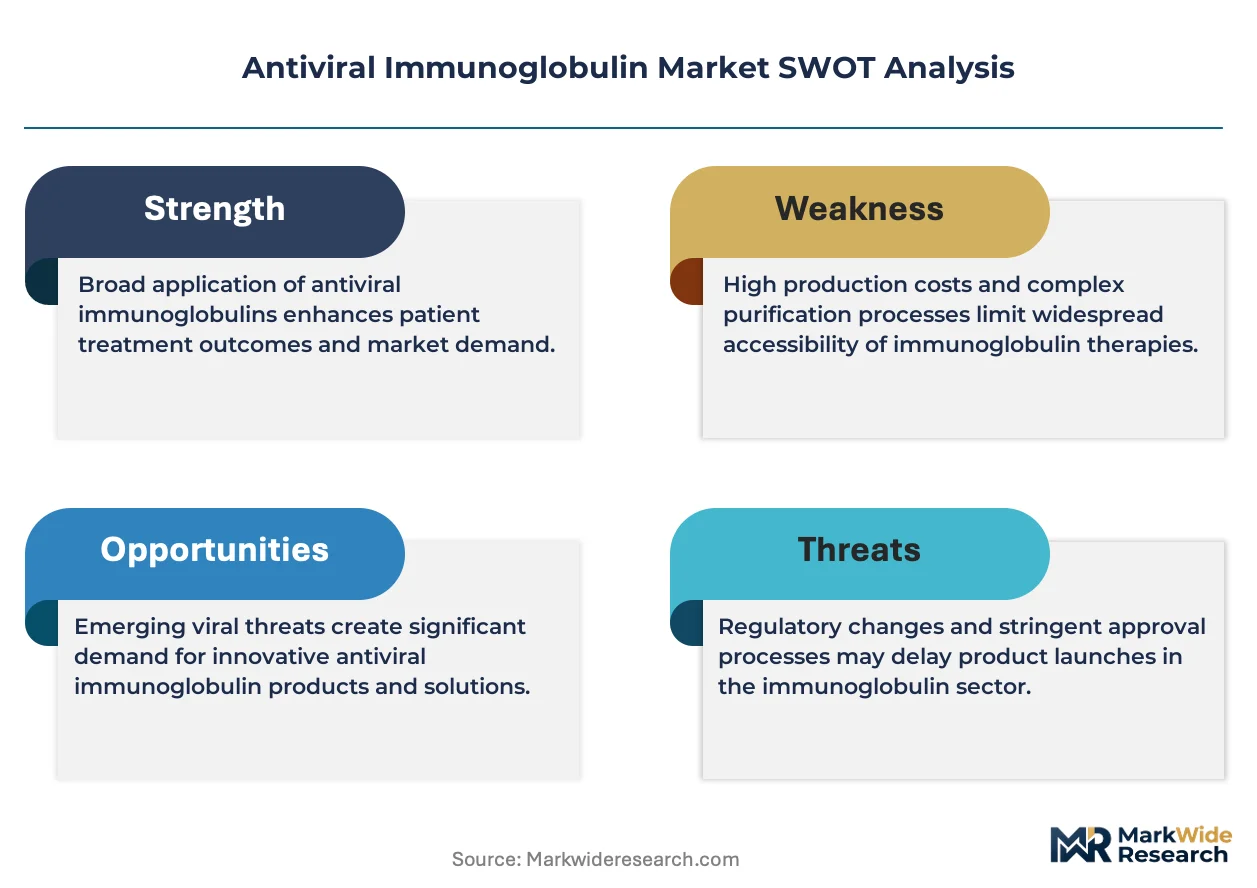
FDA plasma donor deferral policies and EMA's Biologicals Guideline on immunoglobulin quality standards shape product eligibility and batch release timelines, directly constraining which formulations reach clinical use. The EU F-Gas Regulation indirectly affects cold chain logistics for temperature-sensitive biologics, elevating infrastructure compliance costs for cross-border distribution. Stakeholders must monitor evolving plasma collection regulations and homecare reimbursement decisions to align capacity investments with shifting site-of-care preferences.
Market Dynamics
Plasma supply security now dominates strategic calculus as FDA donor deferral expansions and EMA quality standard revisions simultaneously constrain collection volumes and elongate batch release timelines, forcing fractionators to secure multi-continent sourcing networks.
Growth Catalysts
- Hospital-based infusion programs:Specialized immunology centers in the United States are scaling hyperimmune globulin administration through dedicated outpatient protocols, anchoring therapeutic consumption growth.
- F-Gas Regulation compliance infrastructure:Cold chain logistics investments across EU member states are elevating distribution capabilities for temperature-sensitive biologics, reducing spoilage rates in cross-border transit.
- Subcutaneous administration protocols:Homecare delivery models are displacing hospital dependency for maintenance immunoglobulin therapy, expanding addressable patient populations beyond institutional settings.
Market Restraints
- Plasma donor pool constraints:FDA's tightened eligibility criteria for hyperimmune donors are directly limiting pathogen-specific antibody collection volumes, creating raw material scarcity for targeted formulations.
- Fractionation capacity concentration:Production gravity centers on North American and European facilities with cold ethanol infrastructure, leaving emerging markets import-dependent and exposed to supply disruption.
- Reimbursement pathway rigidity:Intravenous immunoglobulin retains entrenched coding and payment structures that disadvantage newer administration modes despite clinical equivalence.
Strategic Opportunities
- European regional distribution specialization:Kedrion Biopharma's established hyperimmune product networks demonstrate scalable models for penetrating underserved Central and Eastern European markets.
- Homecare reimbursement expansion:Medicare and commercial payer policy evolution toward site-neutral payment creates tailwinds for subcutaneous protocol adoption in the United States.
- Pathogen-specific inventory pre-positioning:Pandemic preparedness frameworks are mandating strategic stockpiles of hyperimmune globulin against emerging viral threats, creating non-cyclical demand anchors.
Industry Challenges
- Plasma collection workforce scarcity:Phlebotomist and donor center technician shortages are constraining collection volume growth despite capital investment in new center openings.
- Viral inactivation validation timelines:EMA Biologicals Guideline compliance documentation requirements are extending batch release cycles, compressing working capital efficiency.
- Legacy hospital contracting integration:Institutional purchasing organizations resist protocol switching costs associated with transitioning from intravenous to subcutaneous administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiviral Immunoglobulin Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Immunoglobulin, Subcutaneous Immunoglobulin, Hyperimmune Globulin, Normal Immunoglobulin End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Administration Route: Intravenous, Subcutaneous, Intramuscular, Intra-articular Indication: Hepatitis, Measles, Varicella, Cytomegalovirus |
| Companies Covered | CSL Behring, Grifols, Kedrion Biopharma, Octapharma, Biotest, Takeda Pharmaceutical, Emergent BioSolutions, China Biologic Products, Kamada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiviral Immunoglobulin Market Strategic Shifts
Digital donor management platforms are virtualizing plasma collection logistics, while regulatory harmonization efforts and site-of-care migration are compressing traditional distribution hierarchies across all major markets.
Pathogen-reduction technologies utilizing solvent-detergent treatment and nanofiltration are virtualizing traditional viral inactivation assumptions by enabling broader donor pool utilization without compromising safety margins. Fractionators with validated platforms are expanding collection geography into previously deferred populations. This capability is compressing the competitive advantage of legacy cold ethanol-only operators who lack dual-inactivation infrastructure.
EMA's updated Biologicals Guideline on immunoglobulin quality standards is mandating enhanced impurity profiling and extended stability data packages for market authorization renewals. Manufacturers are restructuring quality systems and analytical method portfolios to meet stepped-up documentation requirements. Subcutaneous formulations with longer shelf-life claims are gaining accelerated assessment pathways as regulators prioritize patient convenience metrics.
Site-of-care purchasing decisions are migrating from centralized pharmacy committees to individual immunology practice units with direct budget authority. Hospital-based infusion centers are unbundling bundled payment contracts to separate drug acquisition from administration fees. This decentralization is most visible in United States academic medical centers where specialty pharmacy carve-outs are creating direct manufacturer-to-physician contracting channels.
Antiviral Immunoglobulin Market Segmentation
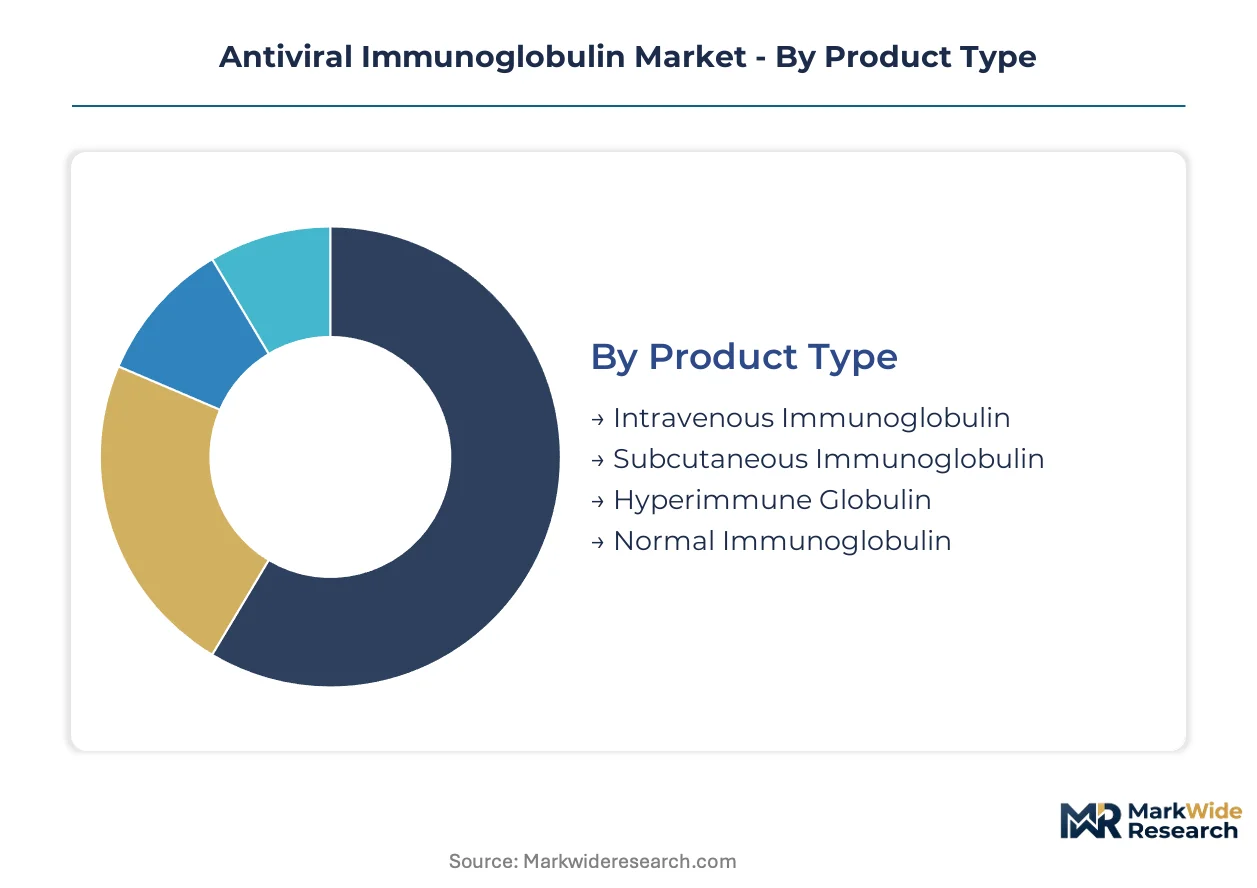
Antiviral immunoglobulin markets fragment across product formulation, delivery setting, and therapeutic target, with each axis demanding distinct manufacturing capabilities, regulatory pathways, and reimbursement negotiations. Understanding these segment boundaries reveals where capital deployment yields highest returns and where supply constraints create persistent margin pressure.
Product Type:
Formulation chemistry and antibody specificity define the use-case spectrum from broad-spectrum prophylaxis to targeted post-exposure intervention.
- Intravenous Immunoglobulin:Polyspecific IgG preparations exceeding 95% purity delivered through controlled infusion protocols. Demand concentrates in United States academic medical centers where established reimbursement codes and pharmacy committee familiarity sustain volume leadership despite longer administration times.
- Hyperimmune Globulin:Pathogen-specific antibody concentrates harvested from screened donors with documented high-titer serology. Supply concentrates against hepatitis and cytomegalovirus targets where donor pool scarcity and FDA deferral policies create persistent raw material bottlenecks.
- Subcutaneous Immunoglobulin:Concentrated formulations enabling patient-administered delivery through portable infusion pumps. Homecare protocols in Germany and France are displacing hospital dependency for maintenance therapy.
- Normal Immunoglobulin:Standard polyclonal preparations without targeted pathogen enrichment. Emerging market procurement programs in Brazil and India leverage this category for cost-constrained public health applications.
The dominant share belongs to intravenous formulations, while subcutaneous delivery is closing the gap fastest as site-of-care economics shift toward outpatient models.
End User:
Site-of-care migration from institutional settings to patient-controlled environments is redrawing distribution infrastructure requirements and contracting relationships.
- Hospitals:Inpatient and dedicated outpatient infusion centers with centralized pharmacy oversight. United States hospital purchasing organizations anchor the largest therapeutic consumption base through bundled payment contracts that separate drug acquisition from administration fees.
- Homecare Settings:Patient-administered therapy through specialty pharmacy networks with nursing support. Medicare site-neutral payment evolution and commercial payer policy shifts in the United States are accelerating addressable population expansion beyond institutional boundaries.
- Clinics:Community-based infusion centers with direct physician practice ownership. Regional European networks demonstrate scalable models for penetrating underserved Central and Eastern European markets.
- Research Laboratories:Investigational product access for clinical trial supply and reference standard preparation. EMA Biologicals Guideline compliance documentation requirements extend batch release timelines for this channel.
Hospital purchasing organizations still command the largest volume allocation, though homecare channels are expanding most quickly as reimbursement frameworks adapt to patient convenience metrics.
Administration Route:
Delivery mechanics determine staffing requirements, facility infrastructure, and patient compliance profiles across the therapeutic continuum.
- Intravenous:Infusion pump delivery through peripheral or central venous access requiring clinical monitoring. Established protocols dominate acute intervention scenarios where rapid antibody titers prove clinically necessary.
- Subcutaneous:Abdominal or thigh tissue deposition through butterfly needle sets enabling self-administration. Homecare training programs reduce hospital dependency for maintenance immunoglobulin therapy.
- Intramuscular:Depot injection for hyperimmune globulin post-exposure prophylaxis against hepatitis and measles. Public health emergency stockpiles mandate this route for field-deployable intervention capabilities.
- Intra-articular:Joint space delivery for localized immunomodulation in rare autoimmune complications. Specialist rheumatology practices in Switzerland and the United Kingdom maintain limited utilization for refractory cases.
Intravenous delivery retains entrenched volume leadership, yet subcutaneous protocols are gaining share most rapidly as specialty pharmacy carve-outs create direct manufacturer-to-physician contracting channels.
Indication:
Viral target specificity dictates donor screening protocols, regulatory filing strategies, and pandemic preparedness stockpiling mandates.
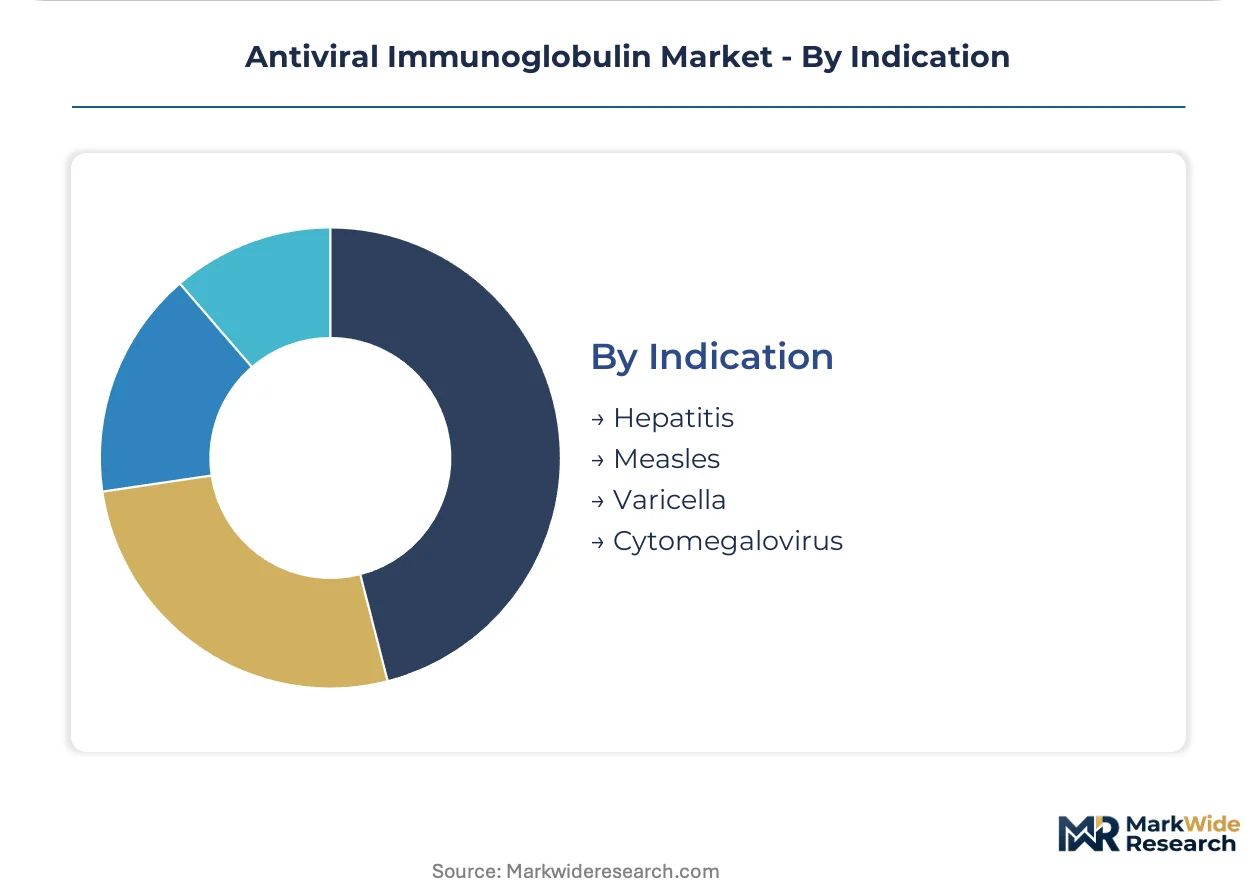
- Hepatitis:Hepatitis B immune globulin for post-exposure prophylaxis and liver transplant recipient prophylaxis. FDA donor deferral expansions for risk-factor history constrain collection geography for this high-titer requirement.
- Cytomegalovirus:CMV hyperimmune globulin for seronegative transplant recipient protection. Solid organ transplant center concentration in the United States, Germany, and Japan anchors demand concentration.
- Measles:Post-exposure prophylaxis for non-immune contacts in outbreak containment scenarios. Public health emergency frameworks mandate strategic inventory pre-positioning against resurgence events.
- Varicella:Zoster immune globulin for immunocompromised exposed patients and pregnant women without varicella immunity. Pediatric oncology centers and maternal-fetal medicine practices drive specialized demand.
Hepatitis applications command the largest indication share, while cytomegalovirus prophylaxis is climbing the fastest as transplant volumes expand and seronegative recipient protocols tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances define regional positioning as fractionation capacity concentrates in donor-rich Western markets while demand growth accelerates across transplant-heavy Asian economies. Plasma collection geography and regulatory stringency create divergent trade flows.
United States
Specialized immunology centers in academic medical centers anchor therapeutic consumption through dedicated outpatient infusion protocols. FDA donor deferral expansions for risk-factor history constrain hyperimmune donor pool expansion, tightening pathogen-specific antibody collection volumes. The Research Triangle and Greater Boston clusters concentrate transplant center density and fractionation R&D coordination.
Germany
Homecare delivery models in Bavaria and North Rhine-Westphalia displace hospital dependency for maintenance immunoglobulin therapy through specialty pharmacy networks. EMA Biologicals Guideline compliance documentation requirements extend batch release timelines, compressing working capital efficiency. Frankfurt and Munich anchor cold chain logistics investments for cross-border EU distribution.
Japan
Solid organ transplant center concentration in Tokyo and Osaka drives cytomegalovirus prophylaxis demand as seronegative recipient protocols tighten. PMDA quality standard revisions align with EMA impurity profiling requirements, elevating analytical method validation burdens. The Kansai region concentrates plasma fractionation partnerships with European suppliers.
China
Domestic plasma collection network expansion in Shandong and Henan provinces reduces import dependency for standard immunoglobulin formulations. NMPA viral inactivation validation timelines lag Western regulators, creating batch release cycle differentials. The Yangtze River Delta clusters transplant center construction and biologics cold chain infrastructure investment.
Australia
Public health emergency frameworks mandate strategic stockpiles of measles and varicella immune globulin against outbreak resurgence events. TGA alignment with EMA quality standards accelerates market authorization renewal requirements for imported products. Melbourne and Sydney concentrate specialized immunology practice units with direct budget authority over site-of-care purchasing.
Antiviral Immunoglobulin Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated plasma collection networks and cold ethanol fractionation infrastructure. Capital-rich operators with multi-continent donor center footprints outcompete regional specialists on raw material security. Two strategic archetypes dominate: integrated plasma-to-therapy pipeline operators and regional distribution specialists with hyperimmune product focus. Competitive moves center on plasma collection network expansion and pathogen-reduction technology licensing to broaden donor pool eligibility.
Within the integrated operator tier, CSL Behring and Grifols exemplify capital deployment strategies that anchor competitive positioning through captive plasma supply chains. Kedrion Biopharma occupies a position representing regional specialization archetypes, concentrating hyperimmune product distribution across European markets where transplant center density and public health procurement frameworks create distinct demand profiles. These three entities collectively illustrate how geographic footprint breadth and product specificity depth serve as alternative vectors for margin defense.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols |
| Kedrion Biopharma |
| Octapharma |
| Biotest |
| Takeda Pharmaceutical |
| Emergent BioSolutions |
| China Biologic Products |
| Kamada |
| Others |
Value Chain & Pricing Dynamics
Fractionation facility undercapacity in the United States is compelling capital-rich operators to secure multi-continent plasma sourcing networks while extracting premium positioning for hyperimmune formulations. This utilization squeeze simultaneously elevates raw material procurement costs and concentrates pricing power among integrated plasma-to-therapy pipeline operators with captive donor center footprints.
Pricing Analysis
Hospital purchasing organizations anchor contract-based long-term offtake structures for intravenous immunoglobulin, while hyperimmune globulin commands premium-mid-economy pricing differentiation based on pathogen specificity and donor pool scarcity. FDA donor deferral policies and EMA quality standard revisions are intensifying cost compression in standard polyclonal tiers as raw material constraints propagate downstream. Price sensitivity concentrates among emerging market procurement programs in Brazil and India, whereas United States transplant centers demonstrate low elasticity for CMV prophylaxis products.
Supply Chain Analysis
Plasma feedstock draws from donor center networks concentrated in the United States, Germany, and Austria where cold ethanol fractionation infrastructure anchors production gravity. The supply chain rests on pathogen-specific antibody concentrates, viral inactivation reagents, and temperature-controlled logistics assets. Single-source vulnerability permeates hyperimmune donor pool access as FDA eligibility criteria tighten. Distribution runs through hospital purchasing organizations in the United States and specialty pharmacy networks in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antiviral immunoglobulin sits in early-cycle expansion as subcutaneous homecare protocols penetrate maintenance therapy populations previously bound to hospital infusion centers. Medicare site-neutral payment evolution accelerates this site-of-care migration beyond institutional boundaries.
For Market Incumbents: Build captive plasma collection moats through multi-continent donor center expansion to defend against raw material scarcity threats from FDA deferral policy tightening. Secure pathogen-reduction technology licensing to broaden eligible donor pools without compromising EMA Biologicals Guideline compliance. Channel control through direct manufacturer-to-physician contracting in academic medical centers protects margin position against group purchasing organization consolidation. For New Entrants and Emerging Players: Establish a beachhead in Central and Eastern European hyperimmune distribution where Kedrion Biopharma's model demonstrates scalability and transplant center density lags Western penetration. Target pandemic preparedness procurement frameworks for strategic stockpile contracts as non-cyclical demand anchors. Go-to-market positioning around subcutaneous formulation convenience metrics captures site-of-care migration tailwinds. For Investors and Strategic Acquirers: Long-term, this sits as a supply-constrained biologics play because plasma donor pool expansion fundamentally limits fractionation capacity growth regardless of capital deployment. Acquisition targets with validated dual-inactivation infrastructure and established EMA quality systems command scarcity premia. Watch Medicare site-neutral payment implementation velocity as the inflection signal for homecare channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | CSL Behring's multi-continent donor center footprint secures raw material advantage against FDA deferral constraints. |
| Pathogen-Reduction Technology Licensing | Solvent-detergent validation enables broader donor pool utilization without EMA batch release timeline extension. |
| Homecare Reimbursement Strategy | Medicare site-neutral payment evolution accelerates subcutaneous protocol adoption beyond hospital dependency. |
| Regulatory Harmonization Investment | EMA Biologicals Guideline compliance documentation restructuring compresses competitive batch release cycles. |
| Pandemic Preparedness Contracting | Strategic stockpile mandates for measles and varicella immune globulin create non-cyclical demand anchors. |
Study Parameters
Initial hypotheses were tested against primary input from plasma collection center operators, fractionation facility managers, hospital pharmacy directors, and specialty pharmacy network executives and refined through secondary validation against FDA donor deferral policy documents, EMA Biologicals Guideline submissions, ClinicalTrials.gov immunoglobulin protocol registrations, and CMS Medicare reimbursement coding databases. Bottom-up demand modeling across administration routes and therapeutic targets was triangulated with top-down plasma collection volume assessments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value trajectories through product type segmentation by formulation chemistry, end user segmentation by site-of-care migration stage, and indication segmentation by transplant center density. CAGRs were derived from plasma donor pool growth constraints, fractionation capacity expansion schedules, and reimbursement policy evolution timelines. Forecast inputs incorporated FDA donor eligibility revision probabilities and EMA impurity profiling compliance cost trajectories.
Stress conditions across plasma collection workforce availability, viral inactivation validation timeline extension, and homecare reimbursement policy reversal were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding donor center opening rates and pathogen-reduction technology adoption curves. Cross-checking against hospital purchasing organization contract disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Anastrozole Tablets Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Normal Saline for Parenteral Use Market