
 South Korea Human Papillomavirus Vaccine Market | 2026-2036
South Korea Human Papillomavirus Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Human Papillomavirus Vaccine Market Insights
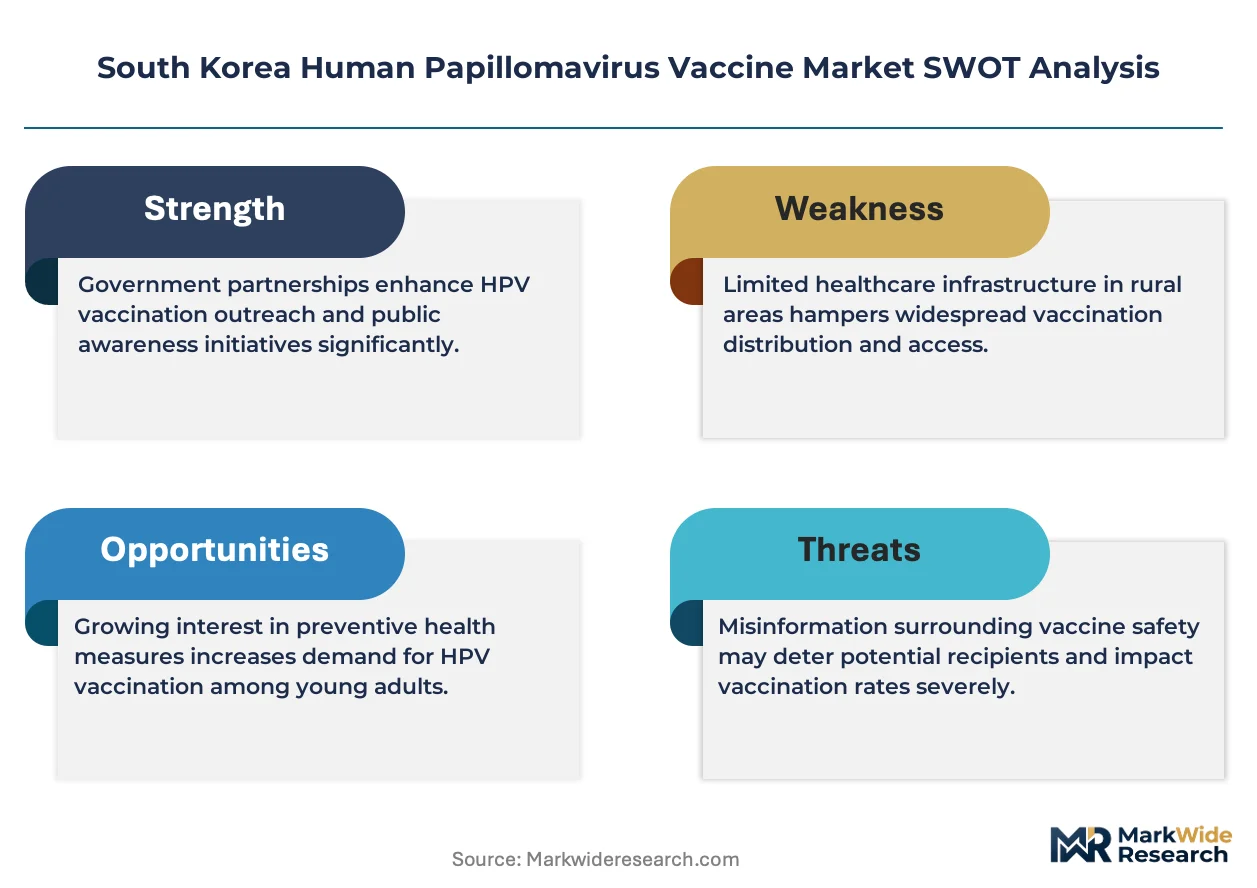
mRNA platform refinement and virus-like particle engineering is reshaping how South Korean manufacturers develop next-generation HPV immunogens. Merck & Co., Inc. leverages its established nonavalent franchise to sustain premium positioning across Seoul's tertiary hospitals. GSK plc anchors the bivalent segment through long-standing public procurement relationships. Wantai BioPharm competes on cost-engineered quadrivalent supply for provincial health departments.
The South Korea Human Papillomavirus Vaccine comprises prophylactic and therapeutic preparations targeting oncogenic HPV genotypes, formulated as recombinant virus-like particles or nucleic acid constructs administered via intramuscular injection to induce neutralizing antibodies. Nonavalent formulations dominate value capture due to broader genotype coverage, while therapeutic candidates represent the fastest-evolving pipeline segment with novel immunotherapy mechanisms. Adolescent vaccination through school health departments generates the highest volume throughput, though adult catch-up programs in private clinics command superior per-dose margins.
MFDS maintains stringent lot-release protocols and cold-chain verification standards that shape manufacturer compliance costs and distribution infrastructure requirements. The Korean Centers for Disease Control and Prevention sets national immunization schedule inclusion criteria that directly determine reimbursed demand pools. Stakeholders must monitor MFDS biosimilar guidance evolution and KCDC gender-neutral vaccination policy deliberations to anticipate reimbursement expansion and competitive entry dynamics.
Market Dynamics
MFDS accelerated approval pathways are compressing development timelines for novel immunogens while school-based immunization programs expand adolescent coverage, creating dual pressure on manufacturers to scale production capacity faster than clinical validation cycles.
Growth Catalysts
- School-Based Immunization Mandates:Korean Centers for Disease Control and Prevention inclusion of nonavalent vaccines in national health schedules drives volume throughput through organized adolescent health departments.
- mRNA Platform Migration:Domestic manufacturers are engineering nucleic acid constructs to bypass traditional virus-like particle manufacturing bottlenecks and accelerate lot-release timelines.
- Seoul Metropolitan Hospital Networks:Tertiary referral centers concentrate catch-up vaccination demand among adult women seeking broader genotype coverage.
Market Restraints
- Cold-Chain Infrastructure Costs:MFDS lot-release protocols require verified 2-8°C distribution from manufacturing through point-of-administration, elevating logistics expenditure for provincial clinics.
- Serotype Replacement Uncertainty:Broader nonavalent coverage may induce competitive displacement of bivalent formulations without proportional demand expansion.
- Domestic Manufacturing Concentration:Production gravity centers on Gyeonggi-do bioclusters, creating geographic vulnerability to localized supply disruptions.
Strategic Opportunities
- Gender-Neutral Vaccination Policy:KCDC deliberations on expanding reimbursement to adolescent boys would open an underpenetrated demographic segment equivalent in size to current female cohorts.
- Therapeutic Pipeline Candidates:Novel immunotherapy mechanisms targeting established infections represent white-space development outside crowded prophylactic segments.
- Telehealth-Integrated Scheduling:Digital platforms connecting regional clinics to Seoul referral networks are streamlining appointment allocation and reducing dose wastage.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:mRNA platform refinement requires specialized expertise in lipid nanoparticle formulation that outpaces domestic training pipeline output.
- MFDS Biosimilar Guidance Uncertainty:Evolving regulatory frameworks for follow-on vaccines complicate portfolio planning and investment timelines for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Human Papillomavirus Vaccine Market |
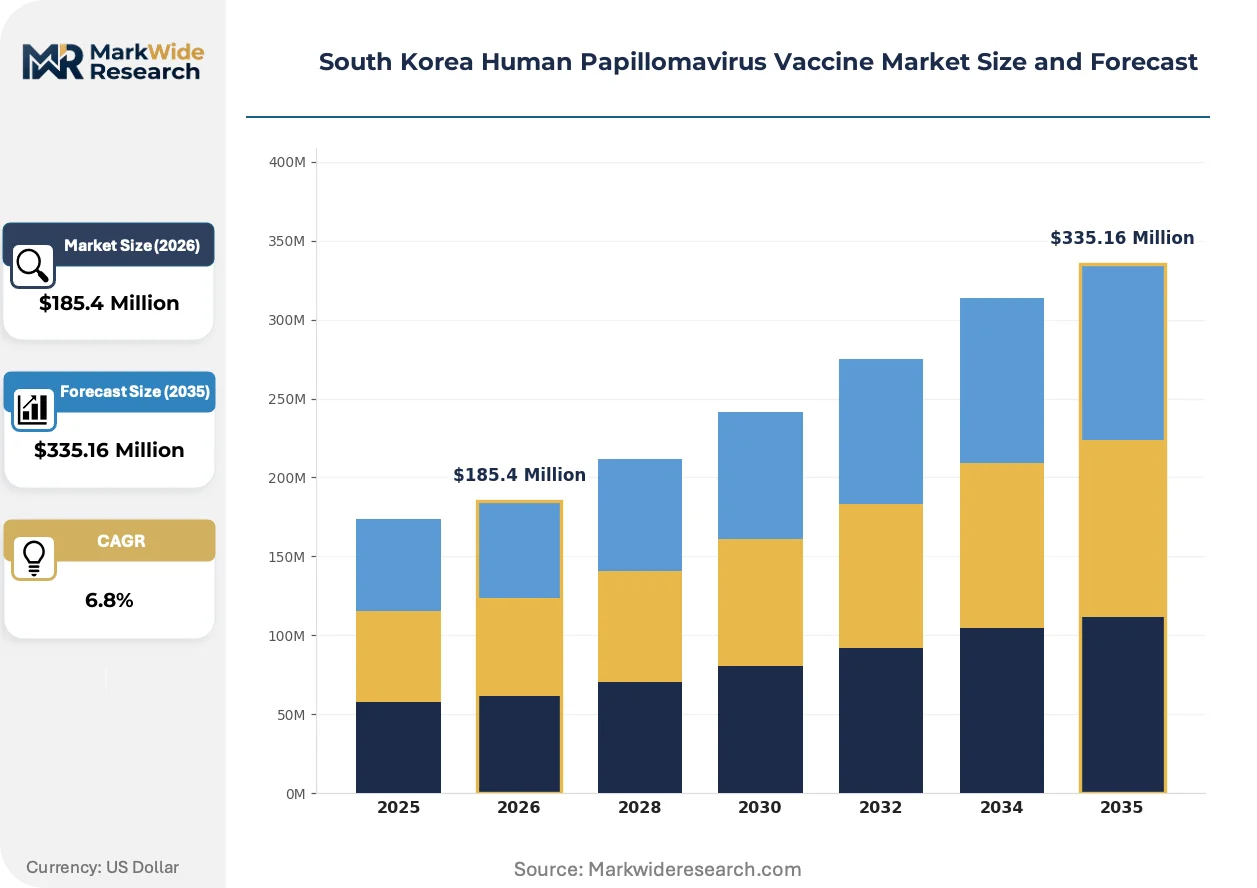
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadrivalent, Bivalent, Nonavalent, Therapeutic End User: Hospitals, Clinics, Pharmacies, Health Departments Age Group: Adolescents, Adults, Children, Seniors Administration Route: Intramuscular, Subcutaneous, Oral, Transdermal |
| Companies Covered | Wantai BioPharm, Xiamen Innovax Biotech Co., Ltd., Merck & Co., Inc., INOVIO Pharmaceuticals, Shenzhen Kangtai Biological Products Co., Ltd., GSK plc, Shanghai Zerun Biotech Co., Ltd., Sanofi SA, Serum Institute of India Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Human Papillomavirus Vaccine Market Trends and Innovations
Platform technology migration and regulatory pathway acceleration are restructuring how South Korean developers prioritize immunogen design, with digitized manufacturing controls emerging as the critical differentiator for commercial scale-up.
Automated bioreactor monitoring systems equipped with real-time analytics are digitizing quality assurance workflows for virus-like particle production. Seoul-based contract manufacturers are deploying these platforms to compress batch release timelines from weeks to days. The structural consequence is digitizing compliance documentation, enabling MFDS auditors to verify cold-chain integrity through distributed ledger records rather than physical inspection.
MFDS pilot programs for rolling review of mRNA vaccine submissions are compressing pre-market authorization timelines for domestic applicants. This regulatory innovation permits iterative data submission during Phase III execution rather than sequential dossier compilation. Domestic biotech firms with Gyeonggi-do manufacturing footprints are prioritizing these pathways to outpace foreign competitors in the nonavalent segment.
Regional health departments are consolidating procurement through centralized tender platforms that aggregate demand across multiple provinces. These digital marketplaces displace bilateral negotiations between individual clinics and distributors, compressing price discovery cycles and favoring manufacturers with verified scale-up capacity. The shift is most visible in Busan and Daegu metropolitan areas where hospital networks are piloting pooled purchasing agreements.
South Korea Human Papillomavirus Vaccine Market Segmentation
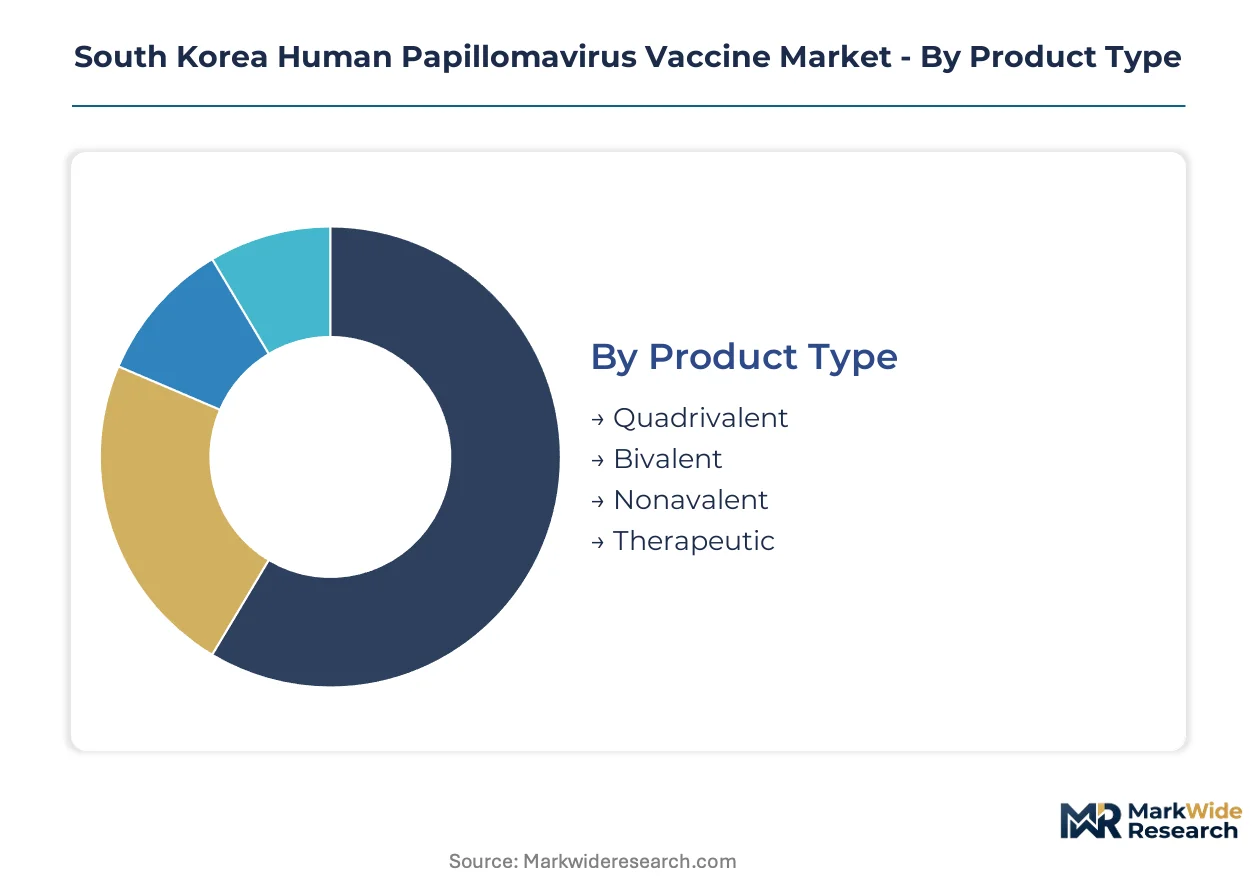
HPV vaccine segmentation in South Korea reveals how formulation breadth, delivery setting, and patient demographics create distinct commercial pockets. Each dimension carries unique MFDS compliance requirements and reimbursement pathways that shape manufacturer resource allocation.
Product Type:
Mature prophylactic formulations dominate revenue capture while therapeutic candidates occupy emerging pipeline territory.
- Nonavalent:Recombinant virus-like particles targeting nine oncogenic genotypes command premium positioning across Seoul's tertiary hospital networks. Broader serotype coverage drives preference among adult women seeking catch-up vaccination.
- Quadrivalent:Cost-engineered formulations maintain provincial health department procurement relationships through established cold-chain distribution. Wantai BioPharm anchors this segment with scaled manufacturing from Gyeonggi-do bioclusters.
- Bivalent:GSK plc sustains long-standing public supply contracts through streamlined lot-release protocols with MFDS.
- Therapeutic:Novel immunotherapy mechanisms targeting established infections represent pipeline white-space outside crowded prophylactic competition.
Nonavalent formulations retain volume leadership; therapeutic candidates hold the steepest expansion curve.
End User:
Institutional scale and reimbursement access separate high-throughput channels from margin-focused private settings.
- Health Departments:School-based immunization programs generate the highest dose throughput through organized adolescent cohorts. KCDC national schedule inclusion creates predictable demand pools with centralized procurement.
- Hospitals:Seoul metropolitan referral centers concentrate adult catch-up vaccination with superior per-dose margins. Tertiary networks leverage broader genotype coverage to differentiate from provincial alternatives.
- Clinics:Regional private practices serve residual demand outside organized programs with flexible scheduling.
- Pharmacies:Retail channels remain limited by intramuscular administration requirements and cold-chain verification needs.
Health departments retain volume leadership; hospitals hold the steepest margin expansion trajectory.
Age Group:
Vaccination timing relative to exposure risk creates distinct immunological and commercial profiles.
- Adolescents:School health departments target females prior to sexual debut with optimal immunogenic response. KCDC inclusion criteria prioritize this cohort for national schedule reimbursement.
- Adults:Catch-up programs in private clinics serve women beyond optimal vaccination windows with broader serotype demand.
- Children:Pre-adolescent dosing schedules remain under evaluation for expanded age indications.
- Seniors:Therapeutic applications for persistent infections represent exploratory clinical territory.
Adolescents retain volume leadership; adults hold the steepest margin expansion trajectory.
Administration Route:
Delivery mechanism determines cold-chain complexity and point-of-care infrastructure requirements.
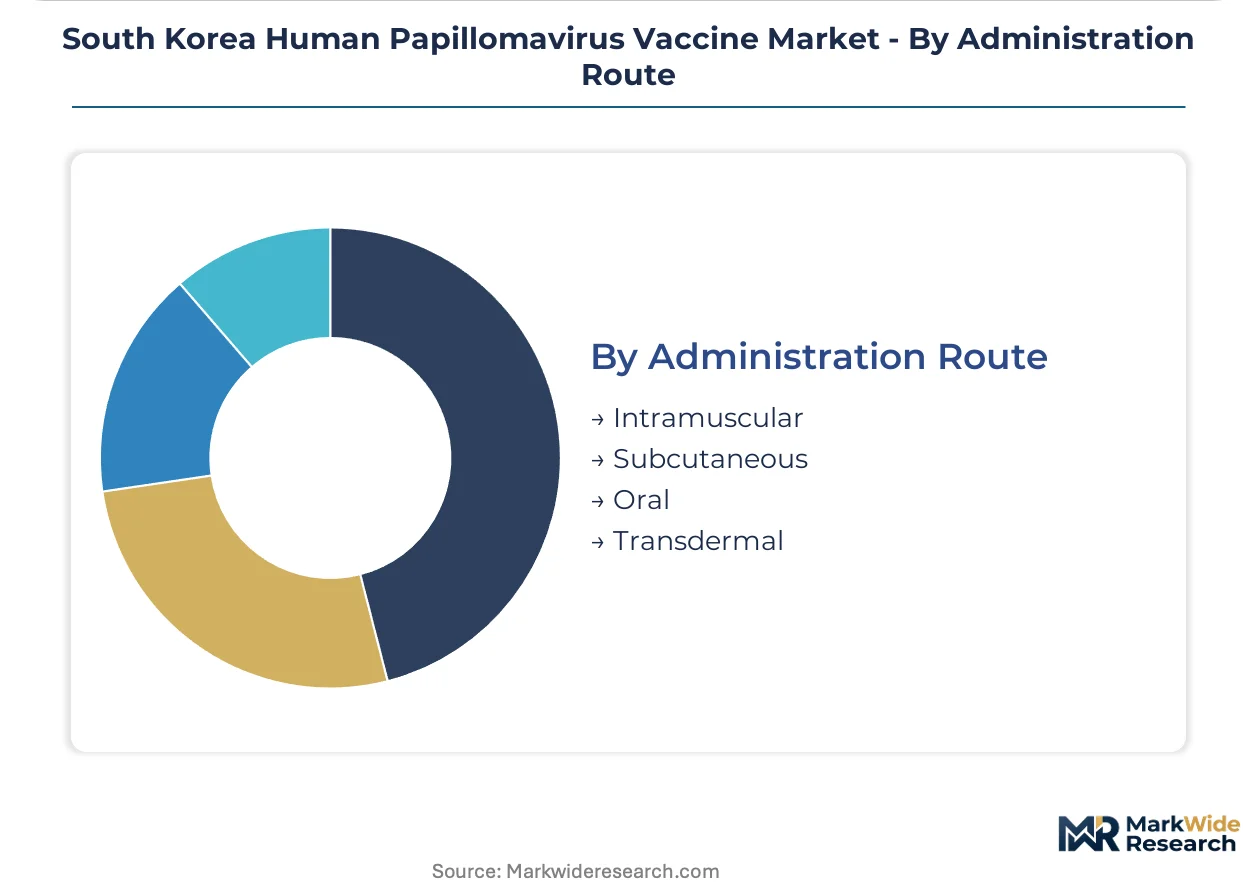
- Intramuscular:Deltoid or anterolateral thigh injection of virus-like particle suspensions requires trained healthcare administration. MFDS mandates verified 2-8°C storage through point-of-administration.
- Subcutaneous:Alternative delivery for specific formulations reduces muscle penetration requirements.
- Oral:No approved HPV vaccines utilize gastrointestinal delivery; experimental mucosal immunization remains preclinical.
- Transdermal:Microneedle patch technologies for nucleic acid constructs are under early-stage evaluation.
Intramuscular delivery retains volume leadership; transdermal platforms hold the steepest innovation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul metropolitan hospital networks concentrate the highest-value demand for nonavalent formulations, while provincial health departments in Gyeonggi-do and Busan drive volume throughput through school-based immunization programs. Buyer archetypes split between premium-seeking tertiary referral centers and cost-optimized public procurement channels.
Seoul Capital Area
Tertiary hospitals in Gangnam and Jongno districts command premium positioning for adult catch-up vaccination with broader genotype coverage. MFDS lot-release protocols require these facilities to maintain verified cold-chain infrastructure from manufacturer through point-of-administration. Bioclusters in Songdo and Pangyo anchor contract manufacturing operations for domestic mRNA platform developers.
Busan-Ulsan
Metropolitan hospital networks in Busan pilot pooled purchasing agreements that aggregate demand across Gyeongsang provinces. The Korean Centers for Disease Control and Prevention channels school-based immunization doses through this corridor to reach underserved adolescent cohorts. Cold-chain distribution hubs in Ulsan industrial complexes service regional clinics with compressed delivery timelines.
Daegu-Gyeongbuk
Provincial health departments here maintain established procurement relationships with cost-engineered quadrivalent suppliers. MFDS accelerated approval pathways attract domestic manufacturers seeking to outpace foreign competitors in nonavalent segments. Gyeongbuk's pharmaceutical manufacturing zones host virus-like particle production facilities with digitized quality assurance workflows.
Daejeon-Sejong
Government research institutes in this administrative hub shape national immunization schedule inclusion criteria that determine reimbursed demand pools. The Korea Disease Control and Prevention Agency headquarters coordinates gender-neutral vaccination policy deliberations that would expand reimbursement to adolescent boys. Clinical trial networks here accelerate therapeutic candidate evaluation through centralized data submission protocols.
Gwangju-Honam
Regional clinics in Jeolla provinces serve residual demand outside organized school programs with flexible scheduling for adult women. Telehealth-integrated platforms connecting these clinics to Seoul referral networks streamline appointment allocation and reduce dose wastage. Provincial tender platforms aggregate demand across multiple Honam jurisdictions, compressing price discovery cycles for manufacturers with verified scale-up capacity.
South Korea Human Papillomavirus Vaccine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent reimbursement pathways. Seoul metropolitan hospital networks grant preferential access to manufacturers with established tertiary relationships, while provincial health departments reward cost-engineered supply from scaled producers. Three archetypes dominate: multinational pharmaceutical incumbents with broad genotype portfolios, domestic biotech firms pursuing mRNA platform migration, and contract manufacturers with Gyeonggi-do production footprints. Competitive moves center on MFDS rolling review pathway access and backward integration into lipid nanoparticle formulation capacity.
Among multinational incumbents, Merck & Co., Inc. and GSK plc occupy positions representing established nonavalent and bivalent franchise holders respectively. Domestic specialists exemplified by Wantai BioPharm anchor cost-optimized supply for provincial procurement channels. These named entities serve as archetype anchors rather than exhaustive market coverage, with competitive dynamics further shaped by Chinese manufacturers including Xiamen Innovax Biotech Co., Ltd. and Shenzhen Kangtai Biological Products Co., Ltd. competing on scaled virus-like particle production.
| Leading Market Players |
|---|
| Wantai BioPharm |
| Xiamen Innovax Biotech Co., Ltd. |
| Merck & Co., Inc. |
| INOVIO Pharmaceuticals |
| Shenzhen Kangtai Biological Products Co., Ltd. |
| GSK plc |
| Shanghai Zerun Biotech Co., Ltd. |
| Sanofi SA |
| Serum Institute of India Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Gyeonggi-do biocluster concentration in virus-like particle manufacturing anchors margin capture downstream at Seoul's tertiary hospital networks, where nonavalent formulations command premium positioning against provincial cost-optimized alternatives.
Pricing Analysis
Cost-plus contracts with MFDS lot-release fee indexation structure procurement relationships between provincial health departments and scaled manufacturers. Pricing stratifies across premium nonavalent, standard quadrivalent, and economy bivalent tiers based on genotype breadth and cold-chain certification grade. Pricing pressure stems from centralized tender platforms aggregating multi-province demand and compressing price discovery cycles. Provincial health departments exhibit highest price sensitivity; Seoul metropolitan hospitals prioritize serotype coverage over unit cost.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms from Gyeonggi-do contract manufacturers stabilize working capital for regional clinic networks. Manufacturing concentrates in South Korea, China, and India for virus-like particle production and lipid nanoparticle formulation inputs. Raw material dependencies include recombinant yeast cultures, aluminum adjuvants, and specialized glass vials. Single-source vulnerability in lipid nanoparticle formulation expertise creates supply chain risk. Distribution runs through verified cold-chain logistics from Gyeonggi-do bioclusters to provincial health department hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against mRNA platform vaccines that could displace traditional virus-like particle formulations through accelerated MFDS approval timelines and simplified manufacturing economics.
For Market Incumbents: Build regulatory moat through backward integration into lipid nanoparticle formulation capacity within Gyeonggi-do bioclusters. Secure preferential access to MFDS rolling review pathways ahead of mRNA platform competitors. Deepen channel control through exclusive supply agreements with Seoul metropolitan hospital networks to lock in catch-up vaccination demand.
For New Entrants and Emerging Players: Build out therapeutic pipeline candidates targeting persistent HPV infections outside crowded prophylactic segments. Target gender-neutral adolescent vaccination policy expansion as the most penetrable reimbursement expansion opportunity. Pursue telehealth-integrated scheduling partnerships with regional clinics to streamline appointment allocation and reduce dose wastage.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic biotech firms pursuing mRNA platform migration that lack commercial scale-up infrastructure. Five-to-ten year viability hinges on successful navigation of MFDS biosimilar guidance evolution and KCDC reimbursement expansion deliberations. Watch MFDS gender-neutral vaccination policy announcements as the critical inflection signal for demand pool doubling.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Rolling Review Pathway Access | Accelerated pre-market authorization compresses development timelines for domestic mRNA applicants against foreign incumbents. |
| Backward Integration into Lipid Nanoparticle Formulation | In-house production of specialized delivery systems reduces dependency on scarce bioprocess engineering talent pools. |
| School-Based Immunization Program Expansion | KCDC national schedule inclusion creates predictable volume throughput through organized adolescent health departments. |
| Therapeutic Pipeline Diversification | Novel immunotherapy mechanisms for established infections open white-space development outside saturated prophylactic competition. |
| Telehealth-Integrated Distribution Partnerships | Digital platforms connecting regional clinics to Seoul referral networks reduce dose wastage and optimize appointment allocation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads at MFDS, hospital procurement managers in Seoul metropolitan networks, and formulary directors at KCDC; alongside secondary validation through MFDS submission databases, ClinicalTrials.gov records, Korean Centers for Disease Control and Prevention immunization schedule documentation, and hospital procurement contract filings. Bottom-up volume estimates from school-based program dose throughput and top-down value triangulation from manufacturer supply relationships were cross-referenced for convergence.
Forecast inputs considered patient population segmentation by age cohort, formulation type across nonavalent through therapeutic categories, administration route with cold-chain infrastructure requirements, and regional regulatory cluster alignment with MFDS approval pathways. CAGRs were derived from modeled demand expansion across the projection horizon, incorporating KCDC policy deliberation timelines and MFDS pathway evolution assumptions. Industry-specific inputs included serotype replacement dynamics and mRNA platform migration rates.
Stress conditions across MFDS regulatory timeline compression, KCDC reimbursement expansion decisions, and mRNA manufacturing scale-up feasibility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about policy trajectory and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Anticoagulants Market