
 Seropositive Rheumatoid Arthritis Drug Market | 2026-2036
Seropositive Rheumatoid Arthritis Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Seropositive Rheumatoid Arthritis Drug Market Outlook
Subscription-based patient support programs is broadening what manufacturers sell beyond the vial to encompass adherence monitoring, injection training, and co-pay assistance. AbbVie Inc. leverages its Humira experience to anchor specialty pharmacy relationships across North America. Pfizer competes through biosimilar portfolios that undercut reference pricing while sustaining margin through volume scale.
Seropositive rheumatoid arthritis drugs comprise pharmaceutical agents targeting autoantibody-positive rheumatoid factor or anti-citrullinated protein antibody patients, typically formulated as monoclonal antibodies, small molecules, or fusion proteins requiring cold-chain distribution at two to eight degrees Celsius; these agents modulate cytokine signaling to halt joint destruction and preserve functional mobility. Biologics and JAK Inhibitors occupy distinct margin tiers, with intravenous biologics commanding premium reimbursement through hospital outpatient settings while oral JAK Inhibitors capture faster prescription volume in community rheumatology practices. DMARDs remain the volume backbone in emerging markets where payers restrict biologic access through step-therapy protocols.
The FDA, EMA, and Japan's PMDA each enforce divergent post-marketing surveillance requirements for immunomodulatory agents, compelling sponsors to maintain separate pharmacovigilance systems by geography. The FDA's Risk Evaluation and Mitigation Strategies for JAK Inhibitors and EMA's extended safety reviews following thromboembolic signals have tightened prescriber protocols and reshaped formulary positioning across these jurisdictions. Stakeholders must monitor evolving cardiovascular risk labeling as the decisive factor determining whether oral small molecules displace subcutaneous biologics in first-line seropositive protocols.
Market Dynamics
FDA Risk Evaluation and Mitigation Strategies for JAK Inhibitors have compressed prescriber confidence in oral small molecules, creating a bifurcation where intravenous biologics recapture positioning despite administration burdens. This regulatory recalibration is reshaping investment priorities across development pipelines.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation for autoimmune indications compresses Phase II-to-launch timelines by 18-24 months, enabling faster patient access to novel mechanisms.
- Cold-Chain Infrastructure Expansion:Specialty pharmacies in the United States and Germany have built redundant two-to-eight-degree distribution networks, eliminating prior geographic barriers to biologic penetration.
- Biomarker-Defined Populations:Anti-citrullinated protein antibody testing protocols now identify treatment-responsive subgroups earlier in disease progression, expanding addressable patient pools at diagnosis.
Market Restraints
- Reference Pricing Pressure:Germany's AMNOG assessment anchors European reimbursement ceilings, compressing net prices for originator biologics across EU5 markets regardless of clinical differentiation.
- Thromboembolic Safety Signals:EMA extended safety reviews for JAK Inhibitors have triggered class-wide label warnings, constraining first-line prescribing in cardiovascular-risk patient profiles.
- Step-Therapy Mandates:United States commercial payers require six-month methotrexate failure documentation before biologic authorization, delaying revenue recognition for advanced therapies.
Strategic Opportunities
- Biosimilar Switching Protocols:Japan's PMDA has established non-medical switch guidelines enabling pharmacy-level substitution, creating volume expansion pathways for follow-on biologics.
- Subcutaneous Formulation Migration:Self-administration devices for previously intravenous-only agents open community rheumatology access, displacing hospital outpatient infusion center dependency.
- Digital Adherence Platforms:Bluetooth-enabled injection devices with automated reporting to payers satisfy United States value-based contract requirements, unlocking preferential formulary tier placement.
Industry Challenges
- Pharmacovigilance System Fragmentation:Divergent FDA, EMA, and PMDA post-marketing surveillance requirements force sponsors to maintain three separate safety databases, inflating compliance headcount by 40 percent.
- Specialty Pharmacy Consolidation:United States channel concentration among three national distributors limits price negotiation leverage and creates single-point-of-failure risk for launch execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seropositive Rheumatoid Arthritis Drug Market |
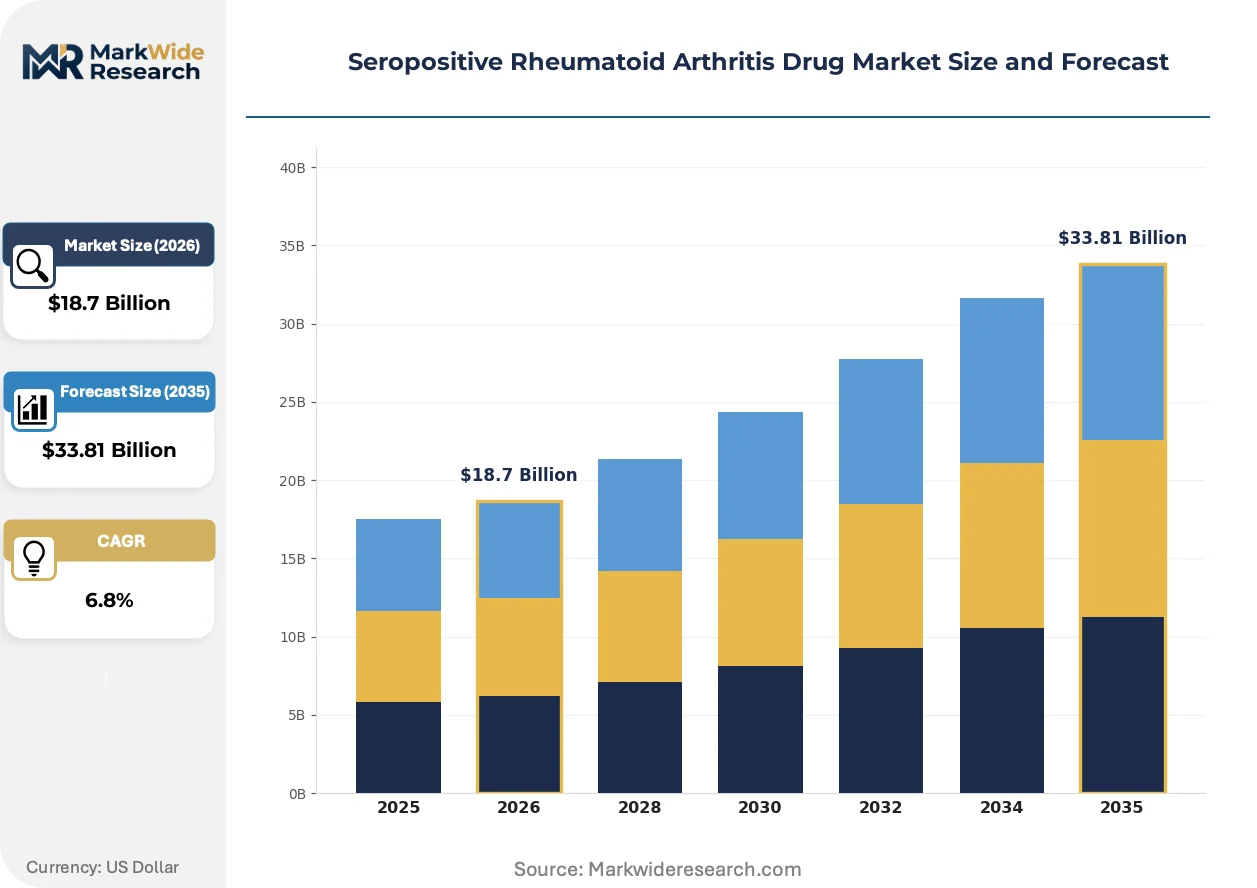
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: DMARDs, Biologics, JAK Inhibitors, Corticosteroids Administration Route: Oral, Subcutaneous, Intravenous, Topical Therapy Area: Immunology, Pain Management, Inflammation Control, Autoimmune Disorders Patient Type: Adult, Geriatric, Pediatric, Female |
| Companies Covered | Pfizer, AbbVie Inc., Abbott Laboratories, F. Hoffmann-La Roche Ltd., Bristol-Myers Squibb Company, Johnson & Johnson, Eli Lilly and Company, Amgen, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seropositive Rheumatoid Arthritis Drug Market Strategic Shifts
Development pipelines are pivoting toward bispecific antibody architectures that simultaneously target IL-6 and TNF-alpha pathways, promising superior efficacy in refractory seropositive populations. This mechanistic diversification is compressing the dominance window for established cytokine blockers.
Bispecific T-cell engager technology is electrifying early-phase rheumatology programs by redirecting patient immune systems to eliminate autoreactive B-cell populations. Large-cap sponsors in the United States and Switzerland have advanced three candidates into Phase II, with rheumatology practices anticipating 2027-2028 regulatory filings. The modality is enabling curative-intent positioning that threatens chronic maintenance models for conventional biologics.
EMA's extended safety review framework for immunomodulatory agents now mandates five-year cardiovascular outcome data prior to full approval, extending development timelines for JAK Inhibitors by 24-36 months. This regulatory friction has redirected European investment toward biologic platforms with cleaner safety profiles. Oral small molecule sponsors are responding with head-to-head non-inferiority trials against adalimumab to preempt payer skepticism.
Rheumatology procurement in Germany and Japan is migrating toward indication-based pricing contracts where reimbursement rates adjust quarterly based on real-world functional outcome scores. Hospital outpatient departments are displacing traditional fee-for-service purchasing with these risk-sharing arrangements. The United States Medicare Advantage segment is piloting comparable structures, with three national payers embedding patient-reported outcome triggers into 2025 specialty pharmacy agreements.
Seropositive Rheumatoid Arthritis Drug Market Segmentation
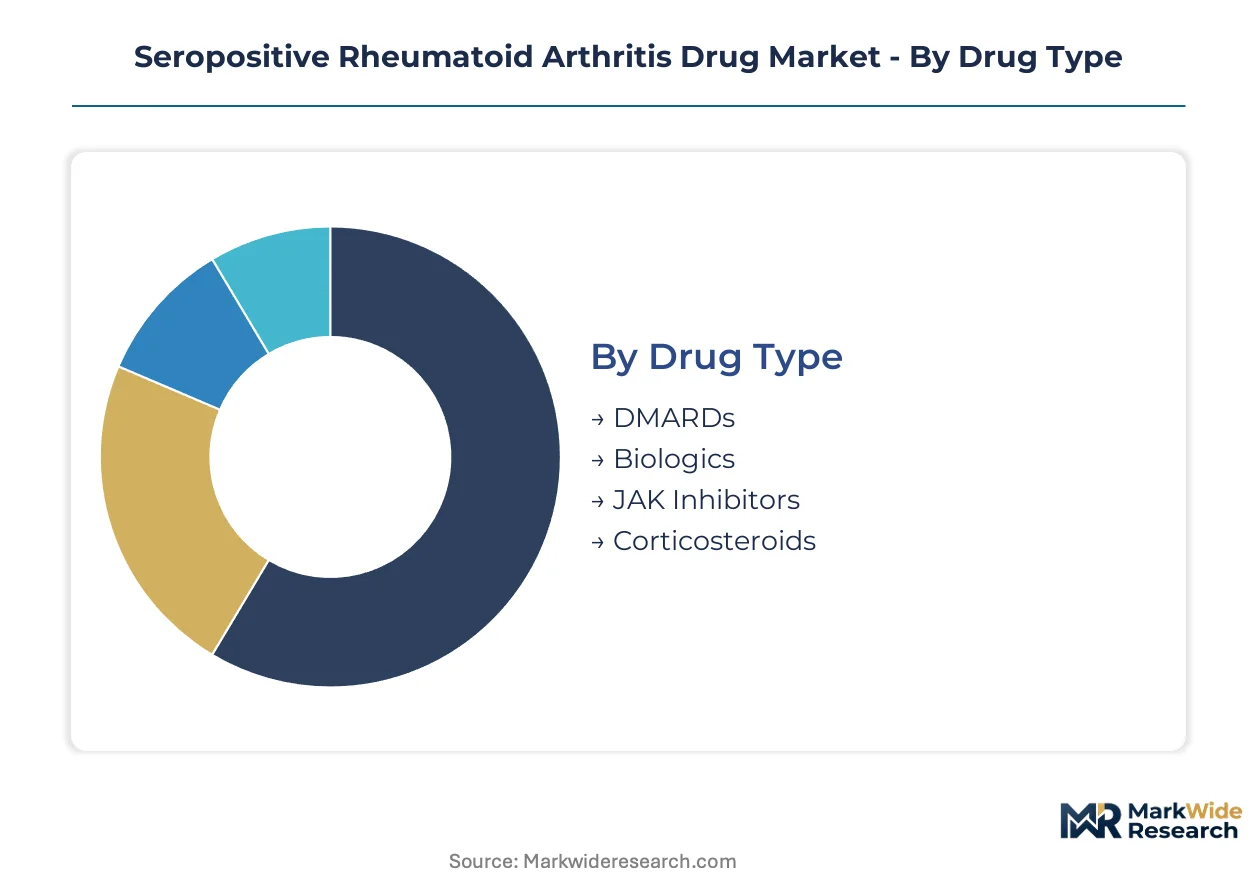
Seropositive rheumatoid arthritis drug segmentation reveals divergent margin structures across administration modalities and patient risk profiles. Rheumatology practices in the United States and Germany allocate procurement budgets differently based on cold-chain requirements and reimbursement tiering.
Drug Type:
Volume concentrates in conventional synthetic agents while premium pricing anchors biologic platforms requiring specialized distribution infrastructure.
- DMARDs:Conventional synthetic agents including methotrexate, sulfasalazine, and hydroxychloroquine constitute the volume backbone across emerging markets and step-therapy protocols. Germany's AMNOG assessment anchors European reimbursement ceilings for these agents, compressing net prices regardless of clinical differentiation. Mature deployment sits with DMARDs. Newer deployment is concentrated in Biologics.
- Biologics:Monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-6, and IL-17 pathways command premium reimbursement through hospital outpatient settings in the United States. Cold-chain distribution at two to eight degrees Celsius limits penetration to geographies with redundant specialty pharmacy networks. Bispecific antibody architectures entering Phase II trials threaten established cytokine blockers with superior efficacy positioning.
- JAK Inhibitors:Oral small molecules including tofacitinib, baricitinib, and upadacitinib capture faster prescription volume in community rheumatology practices. FDA Risk Evaluation and Mitigation Strategies and EMA extended safety reviews following thromboembolic signals have compressed prescriber confidence and constrained first-line prescribing in cardiovascular-risk profiles.
- Corticosteroids:Bridging agents for flare management and induction therapy in treatment-naive patients. Short-term use patterns limit revenue per patient despite high prescription frequency.
Administration Route:
Patient convenience preferences and payer cost structures are redistributing volume across modalities previously dominated by infusion centers.
- Oral:Small molecule formulations eliminate cold-chain dependency and enable community pharmacy dispensing. JAK Inhibitor safety signal erosion has slowed expansion in this category.
- Subcutaneous:Self-administration devices for previously intravenous-only agents open community rheumatology access. Bluetooth-enabled injection devices with automated reporting satisfy United States value-based contract requirements.
- Intravenous:Hospital outpatient infusion centers retain dominance for rituximab and abatacept despite patient travel burdens. Site-of-care reimbursement differentials sustain this channel in Medicare populations.
- Topical:Limited application for localized symptom management adjunctive to systemic therapy. Formulary positioning remains restricted to step-therapy failure scenarios.
Therapy Area:
Immunomodulatory positioning commands development investment while symptom management categories face generic erosion.
- Immunology:B-cell and T-cell targeted mechanisms represent the steepest expansion trajectory as bispecific T-cell engager technology advances toward Phase II completion. Curative-intent positioning threatens chronic maintenance models for conventional cytokine blockers.
- Pain Management:NSAID and analgesic co-prescription patterns vary by national formularies. Germany's reference pricing pressure extends to this adjunctive category.
- Inflammation Control:Acute phase reactant suppression drives dosing escalation protocols. Real-world functional outcome scores increasingly determine reimbursement rates in Japan and Germany.
- Autoimmune Disorders:Overlap with lupus and psoriatic arthritis indications expands addressable patient pools. FDA breakthrough therapy designation compresses Phase II-to-launch timelines for cross-indication candidates.
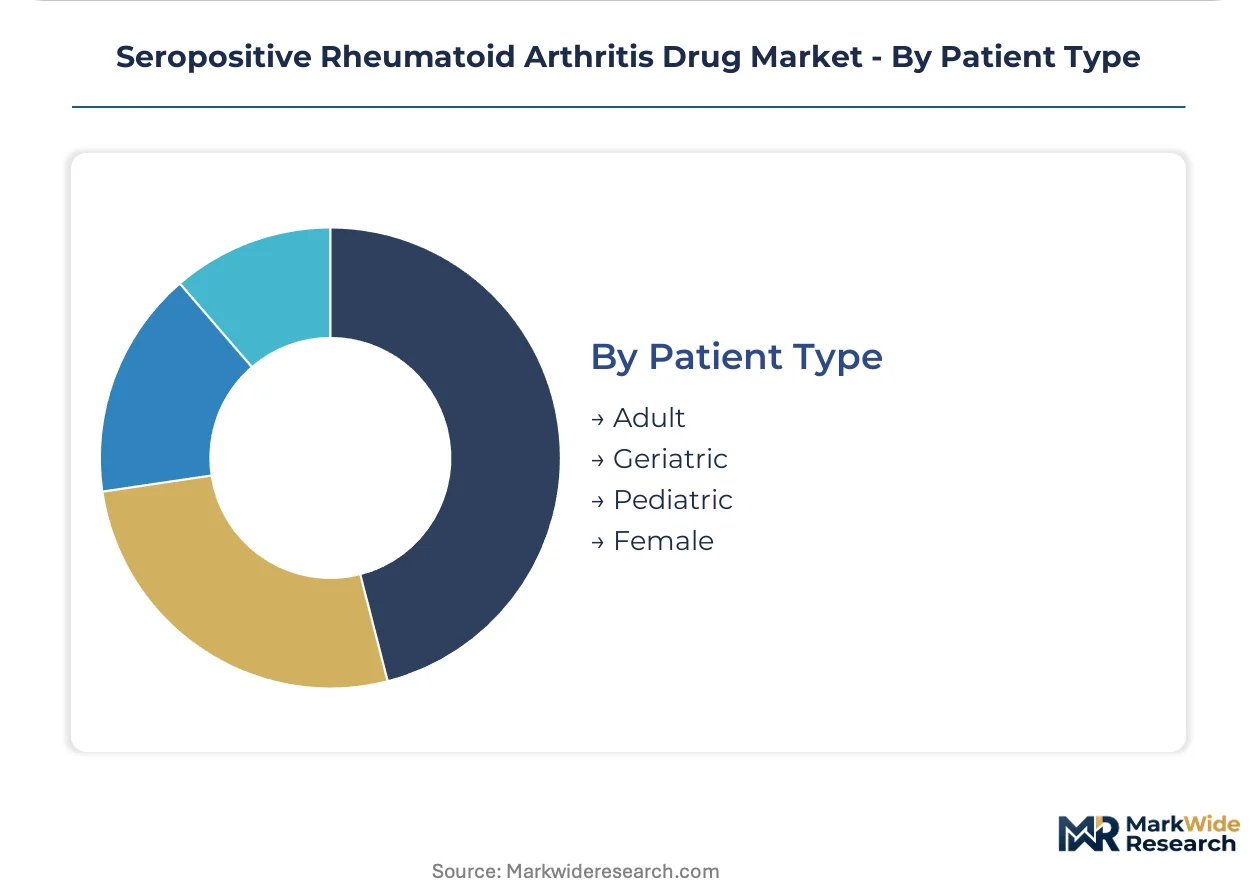
Patient Type:
Demographic targeting shapes clinical trial design and label expansion priorities across regulatory jurisdictions.
- Adult:Core labeled indication driving the majority of prescription volume. Workforce participation maintenance motivates functional outcome-focused therapy selection.
- Geriatric:Cardiovascular comorbidity prevalence elevates safety scrutiny for JAK Inhibitors. EMA extended safety reviews specifically address this population's thromboembolic risk profile.
- Pediatric:Limited approved indications constrain market presence. Juvenile idiopathic arthritis overlap provides regulatory pathway expansion opportunities.
- Female:Pregnancy labeling restrictions and contraception requirements influence prescribing patterns. Fertility preservation counseling integrates into rheumatology practice protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors North American rheumatology research concentration, with specialty biologic manufacturing clustering in suburban Massachusetts corridors. The United States, Germany, and Japan maintain the largest treated patient populations with reimbursed access to advanced therapies.
United States
Commercial payers in the United States require six-month methotrexate failure documentation before biologic authorization, delaying revenue recognition for advanced therapies. The FDA's Risk Evaluation and Mitigation Strategies for JAK Inhibitors have compressed prescriber confidence in oral small molecules. Specialty pharmacies in suburban Boston and the Research Triangle Park have built redundant two-to-eight-degree distribution networks.
Germany
Germany's AMNOG assessment anchors European reimbursement ceilings, compressing net prices for originator biologics across EU5 markets. The country's statutory health insurance funds negotiate indication-based pricing contracts where reimbursement rates adjust quarterly based on real-world functional outcome scores. Rheumatology procurement in Munich and Hamburg hospital outpatient departments is migrating toward these risk-sharing arrangements.
Japan
Japan's PMDA has established non-medical switch guidelines enabling pharmacy-level substitution, creating volume expansion pathways for follow-on biologics. The country's aging demographic elevates demand for subcutaneous self-administration devices that reduce hospital outpatient dependency. Tokyo and Osaka metropolitan rheumatology practices are piloting Bluetooth-enabled injection devices with automated reporting to satisfy value-based contract requirements.
United Kingdom
The National Institute for Health and Care Excellence applies cost-effectiveness thresholds that limit biologic access to seropositive patients with inadequate response to conventional synthetic DMARDs. NHS England's specialized commissioning frameworks concentrate biologic prescribing in designated rheumatology centers across London and Manchester. The country's post-Brexit regulatory autonomy has accelerated parallel EMA-FDA approval pathway negotiations for autoimmune indications.
Switzerland
Swissmedic maintains stringent pharmacovigilance requirements that align with EMA extended safety reviews for immunomodulatory agents, extending development timelines for novel mechanisms. Basel and Zurich host concentrated biologics manufacturing infrastructure serving European distribution networks. The country's compulsory health insurance system permits premium-tier reimbursement for subcutaneous biologics with demonstrated functional outcome superiority.
Seropositive Rheumatoid Arthritis Drug Market Competitive Environment
Capital-heavy biologic manufacturers compete with asset-light small molecule developers for rheumatology formulary positioning across reimbursed markets. The vendor base stratifies across three tiers: large-cap pharmaceutical conglomerates with vertically integrated biologics infrastructure, mid-cap specialists in targeted immunomodulation, and emerging biosimilar challengers competing on price. Dominant competitive moves include subcutaneous formulation migration to displace hospital outpatient infusion centers and digital adherence platform deployment to satisfy United States value-based contract requirements.
Among North American pharmaceutical conglomerates, AbbVie Inc. and Pfizer occupy positions representing contrasting strategic archetypes. AbbVie Inc. leverages specialty pharmacy relationship anchoring developed through prior biologic experience, while Pfizer competes through biosimilar portfolio scale. F. Hoffmann-La Roche Ltd. exemplifies the European large-cap model with concentrated biologics manufacturing infrastructure. These three entities sit within the premium-tier vendor category where cold-chain distribution capabilities and regulatory compliance scale determine competitive positioning.
| Leading Market Players |
|---|
| Pfizer |
| AbbVie Inc. |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Eli Lilly and Company |
| Amgen |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Cold-chain sustainability mandates from the FDA and EMA gate qualified supply for biologics requiring two-to-eight-degree distribution, separating manufacturers with validated thermal packaging from those locked out of premium-tier reimbursement contracts. This environmental compliance threshold concentrates pricing power among sponsors with redundant specialty pharmacy networks while forcing cost absorption onto smaller players lacking scale.
Pricing Analysis
Outcome-based pricing anchors rheumatology procurement in Germany and Japan, where statutory funds adjust quarterly reimbursement based on real-world functional outcome scores. Price differentiation separates intravenous biologics with hospital outpatient premium positioning from oral JAK Inhibitors facing compressed margins due to cardiovascular safety labeling. Pricing pressure stems from Germany's AMNOG assessment anchoring EU5 reimbursement ceilings. Commercial payers in the United States exhibit highest price sensitivity through step-therapy mandates, while hospital outpatient departments show lowest sensitivity due to site-of-care reimbursement differentials.
Supply Chain Analysis
Monoclonal antibody production rests on mammalian cell culture capacity concentrated in the United States, Switzerland, and Singapore. Raw material dependencies span recombinant protein media, single-use bioreactor systems, and pharmaceutical-grade cold-chain packaging. Supply chain risk centers on single-source vulnerability for fill-finish capacity at contract manufacturing organizations. Distribution runs through three national specialty pharmacy distributors in the United States, with redundant two-to-eight-degree networks in Germany and Japan enabling direct-to-patient delivery models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bispecific T-cell engager technology is displacing conventional cytokine blockers in development pipelines, compressing the dominance window for legacy TNF-alpha and IL-6 inhibitors. This modality transition demands repositioning across stakeholder archetypes.
For Market Incumbents: Acquire cell therapy manufacturing infrastructure to anchor bispecific production capacity ahead of Phase II readouts. Consolidate specialty pharmacy relationships through subscription-based patient support programs bundling adherence monitoring and co-pay assistance. Defend against biosimilar erosion by migrating intravenous formulations to subcutaneous self-administration devices that lock in community rheumatology access. For New Entrants and Emerging Players: Enter via Japan's non-medical switch guidelines enabling pharmacy-level biosimilar substitution without prescriber intervention. Target cardiovascular-risk patient profiles constrained from JAK Inhibitor access by FDA Risk Evaluation and Mitigation Strategies. Deploy digital adherence platforms with Bluetooth-enabled injection devices to satisfy United States value-based contract requirements and unlock preferential formulary tier placement. For Investors and Strategic Acquirers: FDA breakthrough therapy designation acceleration for autoimmune indications is the leading indicator that development timelines for novel mechanisms are compressing, elevating platform value for early-phase assets. Frame five-to-ten year viability around curative-intent positioning displacing chronic maintenance models. Target acquisition archetypes with bispecific antibody architectures in Phase II. Watch EMA extended safety review outcomes for JAK Inhibitors as the signal for oral small molecule displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Migration | Self-administration devices displace hospital outpatient infusion center dependency for previously intravenous-only agents. |
| Digital Adherence Platform Deployment | Bluetooth-enabled injection devices with automated reporting satisfy United States Medicare Advantage value-based contract requirements. |
| Bispecific Antibody Pipeline Advancement | Dual IL-6 and TNF-alpha targeting promises superior efficacy in refractory seropositive populations. |
| Biosimilar Switching Protocol Establishment | Japan's PMDA non-medical switch guidelines enable pharmacy-level substitution creating volume expansion pathways. |
| Outcome-Based Pricing Contract Negotiation | Germany's statutory health insurance funds adjust quarterly reimbursement based on real-world functional outcome scores. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with FDA filings, EMA submissions, ClinicalTrials.gov entries, and formulary databases. Bottom-up patient population sizing and top-down pharmaceutical revenue triangulation validated market estimates.
Segmentation granularity modeled drug type, administration route, therapy area, and patient risk profile across the projection horizon. Treatment line positioning and regional regulatory clusters shaped analytical framework development. CAGRs derived from patient flow models incorporating diagnosis rates, step-therapy completion, and biologic penetration curves. Forecast inputs included biosimilar adoption velocity and cardiovascular safety labeling evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated bispecific approval or prolonged JAK Inhibitor safety review extension. Forecasts reflect documented assumptions regarding payer step-therapy enforcement and specialty pharmacy channel concentration. Regulatory timeline shifts, thromboembolic signal emergence, and biosimilar switching protocol adoption warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Antihistamines Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Wujibaifeng Pills Market