
 Critical Care Drugs Market | 2026-2036
Critical Care Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Care Drugs Market Outlook
Biologics manufacturing is fragmenting across distributed production networks, complicating supply assurance for plasma-derived and recombinant critical care therapies. AstraZeneca leverages its respiratory portfolio to anchor positions in sedation and analgesia for ventilated patients. Johnson & Johnson sustains broad hospital formulary access through its diversified injectables infrastructure. Gilead Sciences specializes in antiviral and immunomodulatory agents used in sepsis and multi-organ failure protocols.
Critical care drugs comprise pharmacological agents administered to stabilize hemodynamics, maintain organ perfusion, and modulate pathological inflammatory responses in life-threatening conditions; these therapies typically require precise dosing titration, rapid onset of action, and compatibility with continuous infusion systems in monitored settings. The primary commercial purpose centers on reducing mortality and organ dysfunction in patients requiring mechanical ventilation, vasopressor support, or emergency intervention. Intravenous delivery dominates value capture due to the need for immediate bioavailability and dose adjustments in unstable patients, while inhalation routes are gaining structural importance for sedative-analgesic combinations in ventilator-synchronized protocols. Sedatives represent the most mature margin pool, whereas neuromuscular blockers are attracting renewed development interest for acute respiratory distress syndrome management.
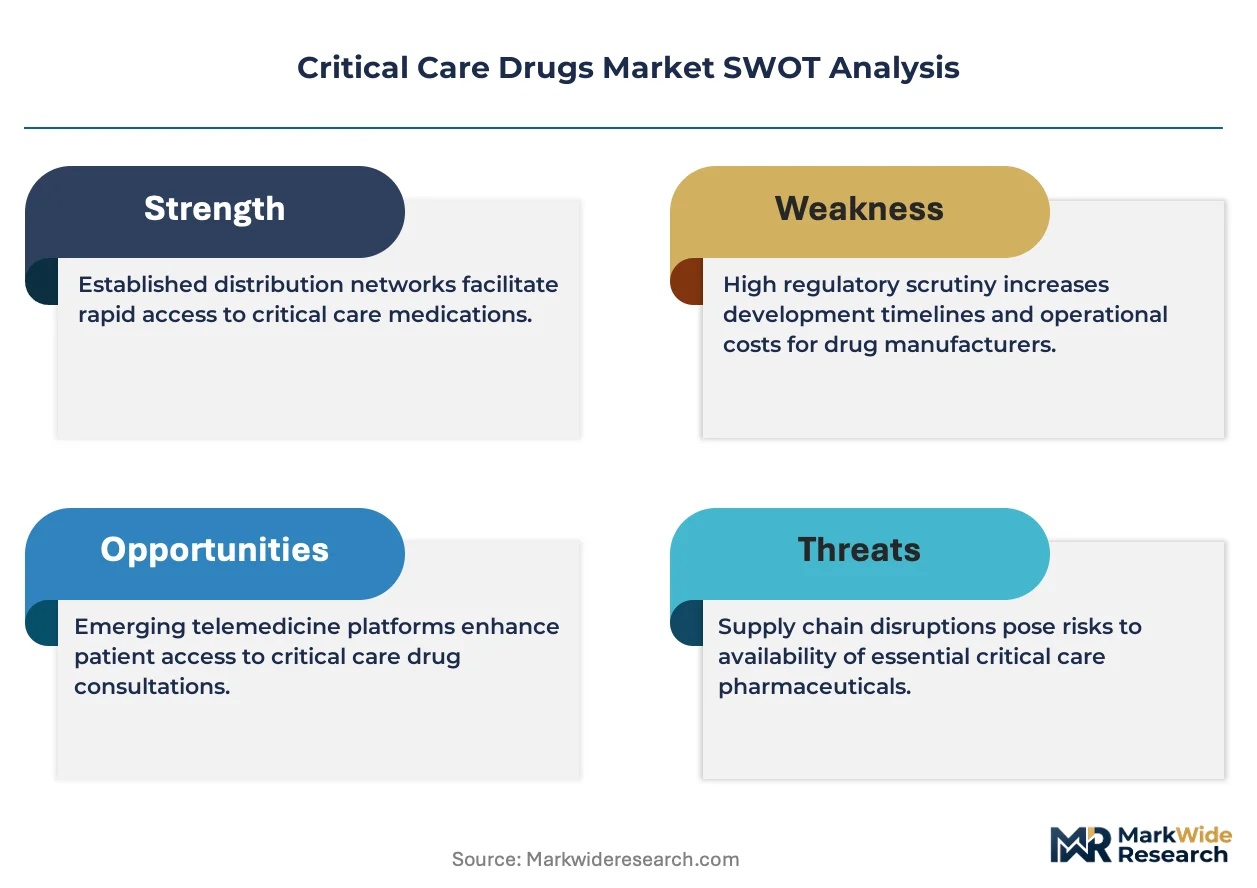
The FDA maintains stringent batch-release and current good manufacturing practice standards for injectable critical care products, while the EMA's Good Manufacturing Practice Annex 1 revisions for sterile medicinal products are raising compliance costs for European suppliers. The International Council for Harmonisation Q3D elemental impurity guidelines further constrain formulation choices for high-volume parenteral therapies. Stakeholders must monitor how regional divergence in biosimilar interchangeability rules will reshape competitive dynamics for biologic critical care agents across hospital purchasing consortia.
Market Dynamics
Hospital formulary consolidation is compressing vendor access channels as integrated delivery networks centralize purchasing authority across multi-state systems. This structural concentration forces manufacturers to defend positions through sole-source contracts and real-world evidence commitments rather than traditional sales force expansion.
Growth Catalysts
- ICU capacity expansion:Tertiary care networks in the United States are adding specialized cardiac and neurocritical care units, expanding the addressable patient base for continuous-infusion sedatives and vasopressors.
- FDA emergency-use authorization pathways:Streamlined review timelines for critical care therapies during public health emergencies have permanently shortened development-to-deployment cycles for manufacturers with established quality systems.
- Plasma fractionation technology:Advances in chromatographic purification methods are improving yield rates for albumin and immunoglobulin products used in sepsis protocols.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for high-volume injectables clusters in India and China, creating single-point-of-failure exposure for European and North American formulators.
- EMA Annex 1 compliance costs:Revised sterile manufacturing standards are forcing facility upgrades that disproportionately burden mid-scale parenteral producers.
- Biosimilar interchangeability uncertainty:Divergent state-level substitution rules in the United States fragment pricing power for reference biologics used in critical care.
Strategic Opportunities
- Home-based acute care:Hospital-at-home programs in Australia and the United Kingdom are creating demand for portable infusion pumps and pre-mixed critical care drug formulations.
- AI-driven dosing algorithms:Integration of machine learning with electronic health records is enabling personalized vasopressor titration protocols that reduce time-to-therapeutic effect.
- Modular manufacturing platforms:Single-use bioreactor systems are allowing distributed production of recombinant proteins closer to point-of-care consumption.
Industry Challenges
- Specialized compounding workforce:Shortages of pharmacy technicians certified in sterile hazardous drug handling are constraining 503B outsourcing facility capacity for patient-specific critical care preparations.
- Legacy EHR integration:Proprietary data architectures at major academic medical centers are blocking seamless interoperability with third-party clinical decision support tools for drug-dosing optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Care Drugs Market |
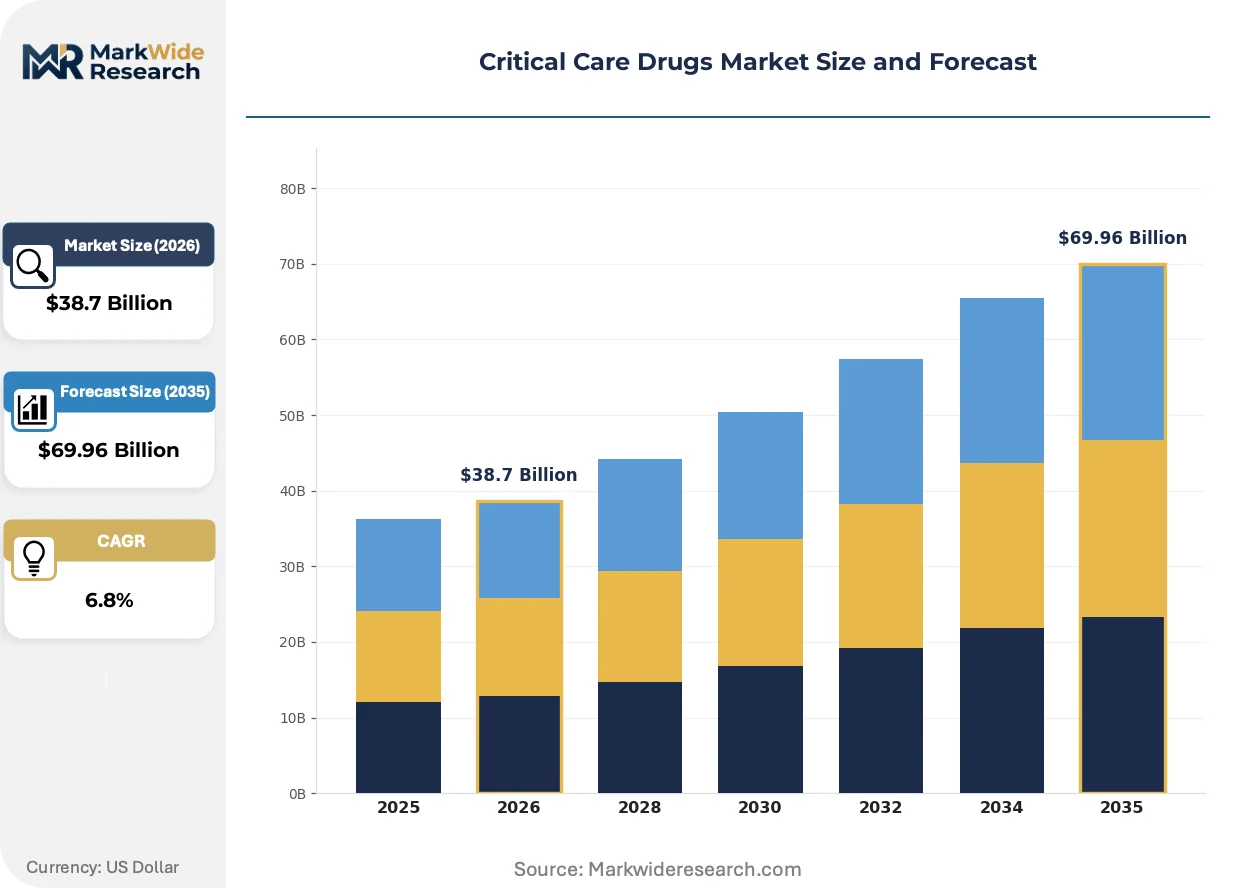
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Sedatives, Vasopressors, Neuromuscular Blockers Delivery Mode: Intravenous, Inhalation, Oral, Subcutaneous End User: Intensive Care Units, Emergency Departments, Surgical Centers, Hospitals Indication: Shock, Respiratory Failure, Cardiac Arrest, Sepsis |
| Companies Covered | AstraZeneca, Amgen, Johnson & Johnson, Regeneron Pharmaceuticals, Gilead Sciences, AbbVie, Novartis, CSL, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Care Drugs Market Strategic Shifts
Precision dosing technologies are displacing weight-based nomograms across mechanical ventilation protocols, while regulatory pressure on endotoxin thresholds is accelerating process analytical technology adoption in sterile manufacturing.
Closed-loop sedation systems is hybridizing pharmacokinetic modeling with real-time EEG monitoring to automate propofol and dexmedetomidine infusion rates. Academic medical centers in Germany and the Netherlands are piloting these platforms in neurocritical care units. The technology is hybridizing anesthesiologist workflow by reducing manual titration events while compressing time-to-adequate sedation targets.
REACH Annex XVII restrictions on residual solvents are forcing reformulation of liposomal and nanosuspension critical care products manufactured in European Union facilities. The EMA's tightened impurity specifications are triggering method-transfer campaigns at contract manufacturing organizations serving the injectables market. High-complexity oncology-supportive care agents face the steepest compliance cost escalation.
Consolidated procurement through group purchasing organizations is compressing supplier margins as contract terms extend to five-year commitments with inflation-capped escalators. Integrated delivery networks in the United States are unbundling clinical pharmacy services from drug distribution agreements. This restructuring is most visible in the southeastern states where hospital system mergers have created super-regional purchasing entities controlling over forty percent of ICU bed capacity.
Critical Care Drugs Market Segmentation
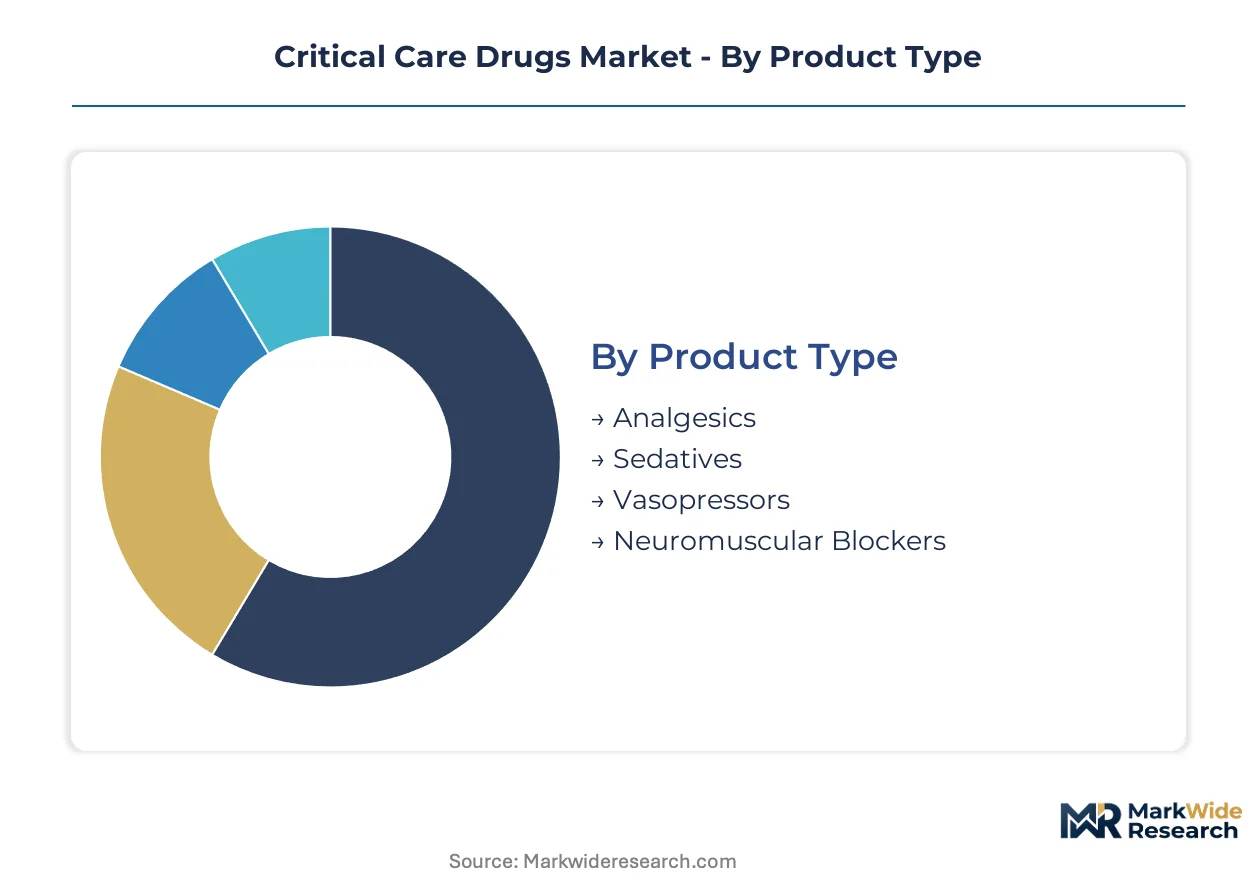
Segmentation in critical care drugs reveals how therapeutic maturity, delivery complexity, and clinical setting shape procurement patterns. Manufacturers align portfolio investments with the divergent technical and regulatory requirements across these dimensions.
Product Type:
Mature therapeutic categories dominate hospital formularies while emerging classes attract development capital for specialized indications.
- Sedatives:Propofol, dexmedetomidine, and benzodiazepine formulations constitute the largest revenue pool in mechanical ventilation protocols. Demand concentrates in United States academic medical centers where closed-loop infusion systems are displacing manual titration. FDA batch-release standards for lipid emulsion formulations maintain elevated manufacturing barriers.
- Vasopressors:Catecholamine and non-catecholamine pressor agents stabilize hemodynamics in septic and cardiogenic shock. European tertiary networks in Germany and the Netherlands drive utilization of norepinephrine-equivalent dosing standardization. EMA Annex 1 sterile manufacturing revisions are compressing supplier margins for high-volume injectables.
- Analgesics:Opioid and non-opioid parenteral analgesics manage pain in ventilated patients.
- Neuromuscular Blockers:Rocuronium, vecuronium, and cisatracurium enable lung-protective ventilation in ARDS protocols.
Sedatives retain volume leadership; neuromuscular blockers hold the steepest expansion curve.
Delivery Mode:
Route selection reflects the tension between immediate bioavailability requirements and patient stability considerations across care settings.
- Intravenous:Bolus and continuous-infusion delivery captures the majority of critical care drug value due to rapid onset and dose titration precision. United States integrated delivery networks specify pump-compatible formulations with standardized concentrations to reduce compounding errors. FDA current good manufacturing practice enforcement for high-volume parenterals sustains quality differentiation.
- Inhalation:Aerosolized sedative-analgesic combinations synchronize with ventilator breath cycles in neurocritical care. Australian hospital-at-home programs pilot portable nebulization systems for transitioning patients from ICU settings. TGA device-drug combination reviews create regulatory complexity for manufacturers.
- Oral:Enteral formulations serve step-down and transitional care populations with preserved gastrointestinal function.
- Subcutaneous:Depot and continuous micro-infusion methods support palliative and chronic critical care scenarios.
Intravenous delivery anchors revenue concentration; inhalation routes are climbing the fastest toward structural importance.
End User:
Facility type determines formulary breadth, purchasing authority concentration, and clinical decision-making workflows.
- Intensive Care Units:Specialized cardiac, neurocritical, and medical ICUs drive the most complex polypharmacy protocols. United States super-regional health systems in the Southeast consolidate purchasing across forty-plus percent of ICU bed capacity through five-year inflation-capped contracts. Clinical pharmacy services unbundling from distribution agreements reshapes vendor relationships.
- Hospitals:General medical-surgical units with step-down capabilities manage post-ICU stabilization and intermediate-acuity patients.
- Emergency Departments:Resuscitation bays and observation units require rapid-acting agents for hemodynamic emergencies.
- Surgical Centers:Ambulatory and short-stay facilities utilize abbreviated critical care drug formularies for perioperative stabilization.
Intensive Care Units command the deepest formulary penetration; Emergency Departments are expanding their addressable scope fastest.
Indication:
Disease-specific protocols create demand fragmentation across therapeutic areas with divergent mortality risk and treatment duration profiles.
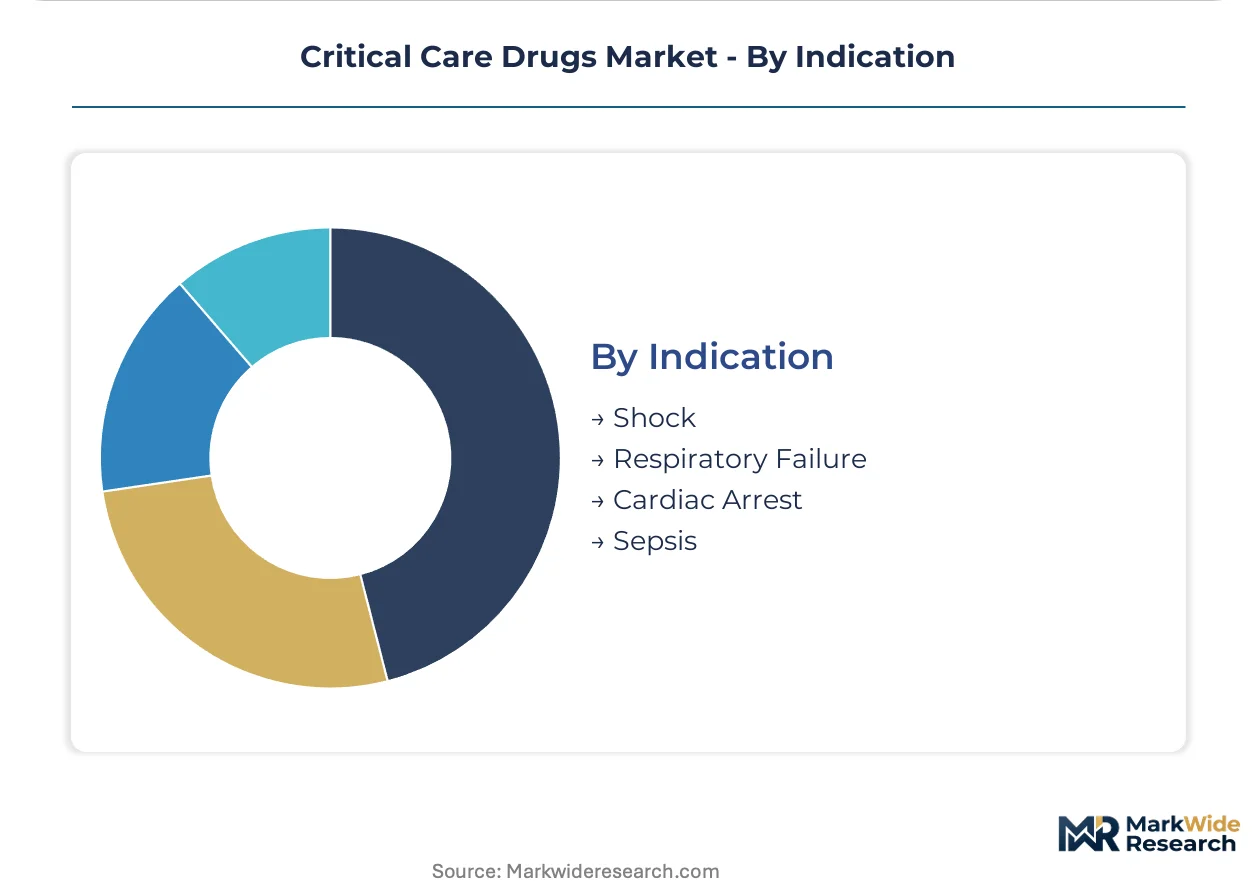
- Sepsis:Immunomodulatory agents, vasopressors, and source control antibiotics constitute multi-modal protocols with extended ICU stays. Plasma-derived albumin and immunoglobulin products face supply assurance challenges as biologics manufacturing fragments across distributed networks. Chromatographic purification advances are improving yield rates for these therapies.
- Shock:Cardiogenic, distributive, and hypovolemic shock subtypes require algorithm-driven pressor selection and titration.
- Respiratory Failure:Acute hypoxemic and hypercapnic failure drives neuromuscular blocker and sedative co-administration for lung-protective ventilation.
- Cardiac Arrest:Post-arrest targeted temperature management and hemodynamic optimization utilize concentrated vasopressor and sedative regimens.
Sepsis protocols retain the longest treatment duration; shock management is gaining algorithmic precision fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Super-regional health systems in the United States concentrate ICU purchasing authority through multi-state integrated delivery networks. Tertiary care networks in Germany and the Netherlands standardize vasopressor protocols. Australia's hospital-at-home programs pioneer portable infusion systems.
United States
Southeastern super-regional systems control over forty percent of ICU bed capacity through five-year inflation-capped procurement contracts. FDA emergency-use authorization pathways permanently shortened development cycles for established manufacturers. Academic medical centers in Boston and the Research Triangle pilot closed-loop sedation systems.
Germany
Neurocritical care units in Berlin and Munich drive demand for EEG-integrated infusion platforms. EMA Annex 1 sterile manufacturing revisions force facility upgrades among parenteral producers. The Rhine-Ruhr pharmaceutical cluster hosts chromatographic purification operations for plasma-derived therapies.
Netherlands
Academic hospitals in Amsterdam and Rotterdam standardize norepinephrine-equivalent dosing protocols across cardiac and medical ICUs. REACH Annex XVII residual solvent restrictions trigger reformulation campaigns for liposomal products. The Leiden biotech corridor concentrates contract manufacturing for high-complexity injectables.
Australia
Hospital-at-home programs in New South Wales and Victoria create demand for pre-mixed critical care formulations and portable nebulization systems. TGA device-drug combination reviews add regulatory complexity for inhalation route therapies. The Melbourne biomedical precinct anchors distributed production trials for recombinant proteins.
India
API production for high-volume injectables clusters in Hyderabad and Ahmedabad, creating supply assurance exposure for North American and European formulators. CDSCO manufacturing facility inspections intensify for sterile parenteral exporters. The Pune-Ahmedabad corridor expands contract manufacturing capacity for global critical care drug sponsors.
Critical Care Drugs Market Competitive Environment
Channel-controlling players compete with product-specialist players across hospital formulary access. Integrated delivery network consolidation compresses vendor margins while sole-source contracts defend incumbent positions. Three archetypes dominate: diversified pharmaceutical conglomerates with broad injectables infrastructure, respiratory-focused specialists leveraging sedation-analgesia adjacencies, and biologics manufacturers with plasma fractionation capabilities. Competitive moves center on real-world evidence commitments for formulary retention and modular manufacturing platform deployment for supply assurance.
Within the biologics-specialist tier, CSL exemplifies plasma-derived therapy concentration through chromatographic purification investments. Among diversified conglomerates, Johnson & Johnson occupies a position anchored by hospital formulary breadth and injectables distribution infrastructure. AstraZeneca represents respiratory-to-sedation portfolio extension, while Gilead Sciences sits within the antiviral-immunomodulatory niche for sepsis protocols.
| Leading Market Players |
|---|
| AstraZeneca |
| Amgen |
| Johnson & Johnson |
| Regeneron Pharmaceuticals |
| Gilead Sciences |
| AbbVie |
| Novartis |
| CSL |
| Merck |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient production for high-volume injectables clusters in Hyderabad and Ahmedabad, anchoring margin capture with North American and European formulators who face cost-plus contract renegotiations tied to Indian wholesale price index movements.
Pricing Analysis
Cost-plus contracts with inflation-capped escalators dominate procurement between United States integrated delivery networks and parenteral suppliers, with five-year terms standardizing price predictability. Price differentiation rests on FDA batch-release certification tiers and pump-compatible formulation concentrations. Cost compression in standard injectables intensifies as group purchasing organizations consolidate contract volumes. Academic medical centers exhibit lowest price sensitivity due to formulary unbundling, while mid-scale community hospitals face acute margin pressure.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk assessment for sterile parenteral manufacturers dependent on chromatographic purification resins. API production concentrates in India and China, with finished dose formulators in Germany and the Netherlands drawing from these sources. Single-source vulnerability pervades plasma fractionation feedstock for albumin and immunoglobulin products. Distribution runs through 503B outsourcing facilities and direct-to-hospital consignment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Critical care drug procurement is shifting toward service-attach models where clinical pharmacy consulting and real-time dosing algorithm subscriptions expand faster than commodity injectable volumes.
For Market Incumbents: Build formulary moats through sole-source contracts with embedded real-world evidence commitments. Johnson & Johnson and CSL should deepen backward integration into plasma collection networks to offset biosimilar interchangeability uncertainty. Defend against mid-scale parenteral producers upgrading EMA Annex 1 compliance capabilities by locking five-year inflation-capped agreements with southeastern super-regional systems. For New Entrants and Emerging Players: Hospital-at-home programs in Australia and the United Kingdom represent the most penetrable entry point for portable pre-mixed formulation specialists. AI-driven dosing algorithm developers should target academic medical centers in Germany and the Netherlands with closed-loop sedation pilot partnerships. Go-to-market execution requires TGA device-drug combination regulatory expertise for inhalation route therapies. For Investors and Strategic Acquirers: Capital is best deployed toward biologics manufacturers with chromatographic purification yield advantages and distributed production platform pilots. Long-term viability hinges on supply assurance capabilities rather than portfolio breadth alone. Watch FDA emergency-use authorization pathway expansion as signal for development-to-deployment cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Commitment | Formulary retention at United States academic medical centers depends on outcomes data contracts. |
| Modular Manufacturing Platform | Single-use bioreactor deployment near Melbourne and Leiden reduces plasma-derived therapy supply risk. |
| Clinical Pharmacy Service Unbundling | Integrated delivery networks in southeastern states separate dosing optimization from drug distribution. |
| EMA Annex 1 Compliance Upgrade | European sterile parenteral producers face forced facility investments that favor scaled incumbents. |
| Hospital-at-Home Formulation Development | Pre-mixed critical care drugs for portable infusion pumps address Australian transitional care demand. |
Study Parameters
Cross-validation between formulary database audits and FDA filing records anchors the qualitative findings on vendor access channels. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and GPO contracts managers combined with secondary validation against EMA submissions, ClinicalTrials.gov protocols, and CMS Medicare utilization data. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation ensure segmentation consistency.
Calibration against historical CAGRs from comparable therapeutic categories shapes the projection framework across the analysis window. Segmentation dimensions include delivery mode, end-user facility type, indication-specific protocol, and regional regulatory cluster. CAGRs derive from spline-interpolation of adoption curves and pricing trajectory assumptions. Forecast inputs incorporate ICU capacity expansion pipelines and biosimilar interchangeability rule evolution.
Practitioners should monitor FDA emergency-use authorization precedent expansion and EMA Annex 1 enforcement intensity for early signals of competitive timeline compression. Forecasts reflect assumptions about sterile manufacturing compliance cost trajectories and plasma fractionation yield improvement rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Contraceptive Pills Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Intranasal Corticosteroids Market