
 North America Veterinary Oncology Market | 2026-2036
North America Veterinary Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Veterinary Oncology Market Insights
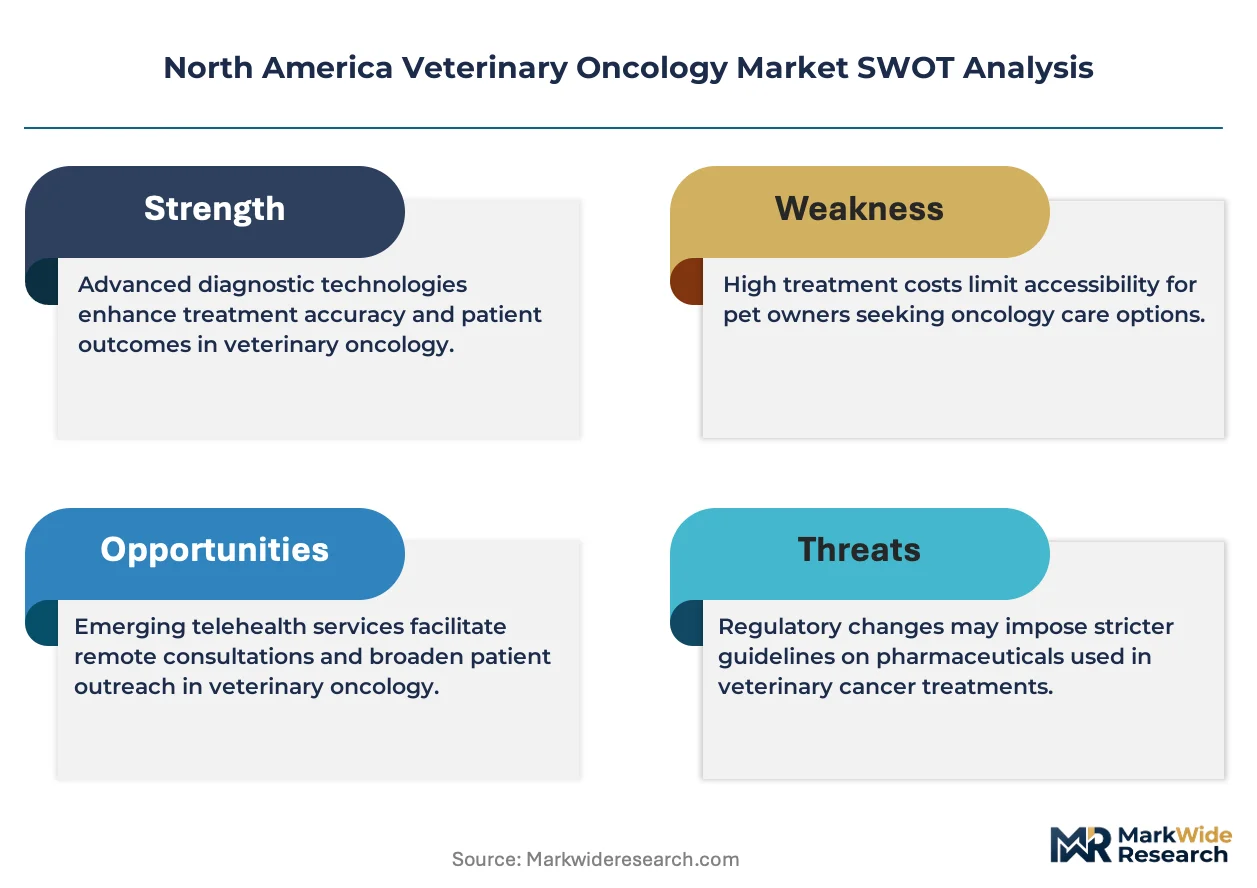
The FDA Center for Veterinary Medicine's streamlined approval framework for minor-use minor-species drugs is shifting the cost-of-entry calculus for novel oncology therapeutics in companion animals. Zoetis Inc. leverages its vertically integrated manufacturing network to sustain consistent supply of chemotherapy agents across the United States and Canada. Elanco Animal Health Inc. anchors its competitive position through deep R&D investment in targeted molecular therapies for canine lymphoma and mast cell tumors. IDEXX Laboratories, Inc. dominates the diagnostic layer, controlling proprietary immunohistochemistry platforms that precondition treatment selection.
North America veterinary oncology encompasses the clinical management of neoplastic diseases in companion and production animals through pharmacologic, radiologic, and surgical interventions, with chemotherapy protocols typically administered via standardized dose-intensity regimens calibrated to body surface area. Radiation therapy demands linear accelerator systems delivering 6–18 MV photon beams with sub-millimeter precision to spare adjacent healthy tissue. Immunotherapy represents the fastest-expanding product category as checkpoint inhibitors and autologous cancer vaccines attract venture funding, while molecular diagnostics within the technology segment captures disproportionate margin pools through next-generation sequencing panels that guide personalized treatment algorithms.
The United States Department of Agriculture and Health Canada jointly shape cross-border biologics standards, with USDA APHIS regulating veterinary biologics manufacture and the Canadian Food Inspection Agency enforcing parallel import controls. State veterinary medical boards in California, Texas, and New York impose continuing education mandates for oncology practitioners that elevate service quality thresholds. Stakeholders must monitor evolving reimbursement negotiations between pet insurance underwriters and specialty hospital networks, as coverage expansion will determine addressable market elasticity faster than therapeutic innovation alone.
Market Dynamics
Companion animal insurance penetration is compressing treatment abandonment rates and forcing specialty clinics to credential oncology specialists at scale. This financial intermediation is restructuring referral patterns across metropolitan veterinary networks.
Growth Catalysts
- FDA Center for Veterinary Medicine streamlined pathways:The MUMS framework accelerates approval timelines for novel therapeutics targeting narrow species indications, lowering development cost thresholds for innovators targeting canine lymphoma protocols.
- Linear accelerator precision upgrades:Sub-millimeter radiation delivery systems enable stereotactic treatments previously restricted to human oncology, expanding curative-intent case eligibility in specialty practices.
- Metropolitan corridor density:Pet ownership concentration across Southern California, Texas urban clusters, and the Northeast corridor aligns disposable income with specialty service accessibility, anchoring regional demand formation.
Market Restraints
- Isotope supply concentration:Radioactive sourcing for diagnostic imaging and therapeutic radiopharmaceuticals depends on limited North American cyclotron capacity, creating vulnerability to production interruptions.
- Veterinary specialist training bottlenecks:ACVIM board certification pathways require 4-year residency commitments that constrain annual diplomate output below clinic expansion rates.
- Biologic cold chain fragility:Autologous vaccine and cell therapy logistics demand continuous temperature monitoring that elevates distribution costs beyond general pharmaceutical handling standards.
Strategic Opportunities
- Canadian provincial coverage expansion:Pet insurance penetration in Ontario and British Columbia lags US benchmarks, presenting white-space acquisition potential for underwriters developing veterinary-specific products.
- Artificial intelligence histopathology:Machine learning algorithms trained on veterinary tumor atlases are converging with telemedicine platforms to extend diagnostic access into general practice settings lacking boarded pathologists.
- State-level continuing education mandates:California, Texas, and New York veterinary medical boards now require oncology-specific CE credits, creating institutional demand for accredited training programs and certification services.
Industry Challenges
- Radiation physics staffing scarcity:Board-certified veterinary radiation oncologists represent the smallest ACVIM subspecialty, forcing clinics to compete for talent against academic centers and human health systems.
- Next-generation sequencing integration:Multi-panel tumor profiling generates actionable data volumes that exceed current clinical decision-support infrastructure in most specialty practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Veterinary Oncology Market |
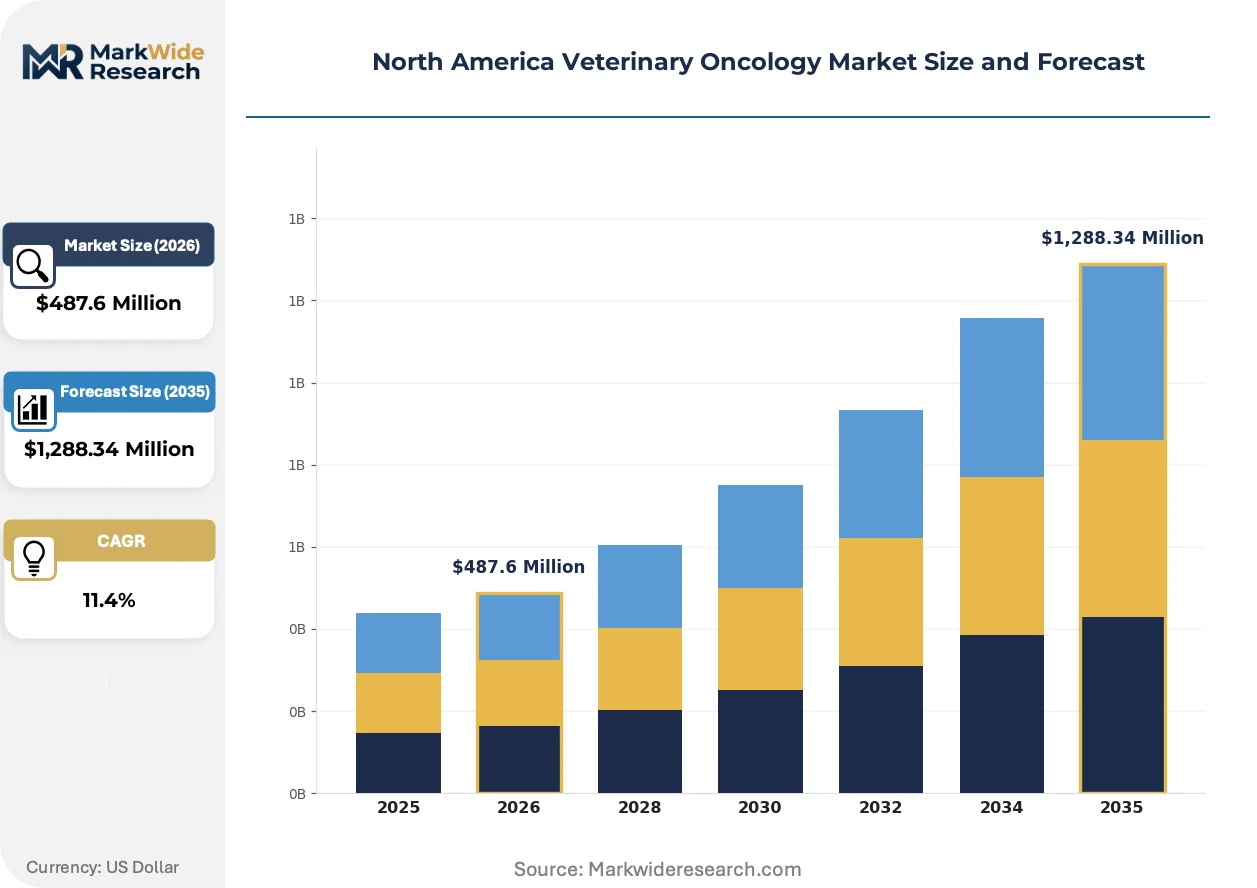
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Targeted Therapy End User: Veterinary Clinics, Research Institutions, Animal Hospitals, Home Care Delivery Mode: Intravenous, Oral, Topical, Subcutaneous Technology: Diagnostic Imaging, Biopsy, Molecular Diagnostics, Surgical Techniques |
| Companies Covered | Zoetis Inc., Elanco Animal Health Inc., Boehringer Ingelheim International GmbH, IDEXX Laboratories, Inc., Antech Diagnostics, Inc., PetCure Oncology, Karyopharm Therapeutics, Inc., Accuray Incorporated, Varian Medical Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Veterinary Oncology Market Trends and Innovations
Checkpoint inhibitor development and molecular diagnostics are compressing the timeline between diagnosis and personalized protocol selection. These advances are restructuring competitive advantage around data infrastructure rather than chemotherapy agent access alone.
Immunotherapy platforms targeting canine lymphoma and mast cell tumors are converging with real-world evidence registries that track long-term survival outcomes. Specialty hospital networks are adopting these systems to differentiate service quality and support insurance pre-authorization workflows. The technology is converging with payer requirements for documented efficacy, forcing manufacturers to invest in post-market surveillance infrastructure.
USDA APHIS and Health Canada are harmonizing veterinary biologics import documentation requirements under revised memoranda of understanding. This regulatory convergence reduces cross-border friction for autologous vaccine manufacturers seeking multi-country market access. Canadian Food Inspection Agency enforcement of parallel standards is accelerating product availability timelines in Ontario and Quebec specialty clinics.
Pet owners are demanding episode-based cost transparency before committing to multi-cycle chemotherapy protocols. Specialty practices are responding with bundled pricing models that separate diagnostic staging from treatment phases. This behavioral shift is most pronounced in Texas and California markets where insurance penetration exceeds 35 percent and pre-authorization workflows require documented cost estimates.
North America Veterinary Oncology Market Segmentation
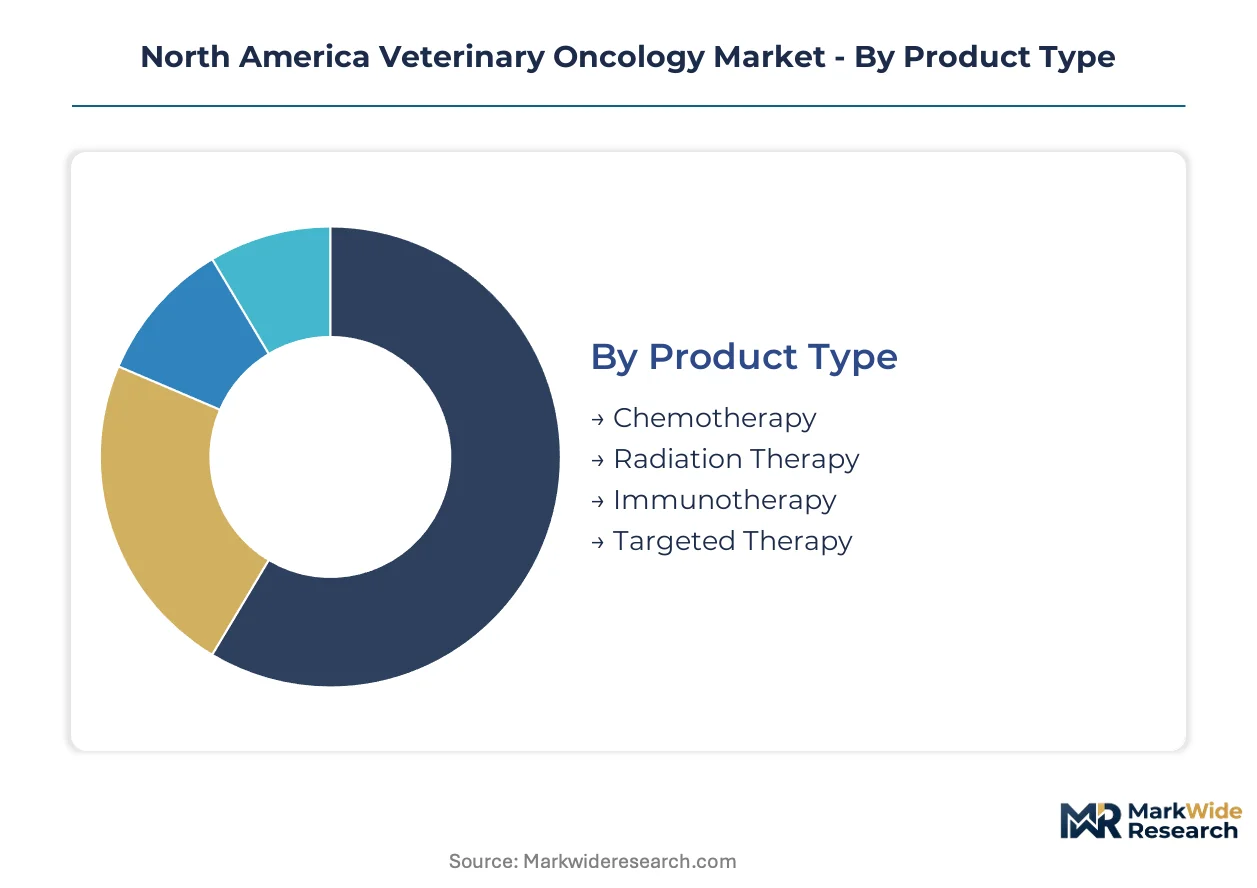
Veterinary oncology segmentation reveals how treatment modalities, care settings, and delivery infrastructure align with patient acuity and owner financial capacity. Understanding these boundaries helps stakeholders identify where capital deployment yields highest clinical and commercial returns.
Product Type:
Technology sophistication separates curative-intent interventions from palliative protocols across the treatment continuum.
- Chemotherapy:Alkylating agents, antimetabolites, and vinca alkaloids administered via standardized dose-intensity regimens calibrated to body surface area. Demand concentrates in metropolitan corridor specialty practices where insurance pre-authorization workflows support multi-cycle protocol completion.
- Immunotherapy:Checkpoint inhibitors and autologous cancer vaccines targeting canine lymphoma and mast cell tumors through immune system modulation. Texas and California specialty networks are expanding fastest here as venture funding flows into platform development.
- Radiation Therapy:Linear accelerator systems delivering 6–18 MV photon beams with sub-millimeter precision.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies directed at specific molecular pathways.
Mature deployment sits with Chemotherapy. Newer deployment is concentrated in Immunotherapy.
End User:
Credentialing requirements and capital intensity create sharp tiering in service delivery capacity.
- Animal Hospitals:Multi-specialty institutions with boarded oncologists, linear accelerators, and in-house pathology. Southern California and Northeast corridor facilities capture highest case volumes where pet density and disposable income align.
- Veterinary Clinics:General practice settings handling diagnosis, staging, and referral coordination. These gatekeepers are expanding fastest in Texas urban clusters as continuing education mandates elevate oncology literacy.
- Research Institutions:Academic veterinary medical centers conducting clinical trials and protocol development.
- Home Care:Subcutaneous chemotherapy administration and palliative monitoring delivered in residential settings.
Capital concentration favors Animal Hospitals. Accessibility expansion is concentrated in Veterinary Clinics.
Delivery Mode:
Route selection hinges on drug pharmacokinetics, tumor accessibility, and owner compliance capacity.
- Intravenous:Platinum compounds and anthracyclines requiring vascular access and cardiac monitoring. Specialty practices in New York and California maintain highest protocol adherence through nurse-led infusion coordination.
- Oral:Tyrosine kinase inhibitors and metronomic chemotherapy protocols enabling owner-administered dosing. Home administration is climbing fastest in insured populations where convenience drives compliance.
- Subcutaneous:Cytarabine and other agents suitable for depot formulation.
- Topical:Localized delivery for cutaneous mast cell tumors and superficial lesions.
Clinical standardization sits with Intravenous. Convenience-driven adoption is concentrated in Oral.
Technology:
Diagnostic precision determines treatment eligibility and protocol selection accuracy.
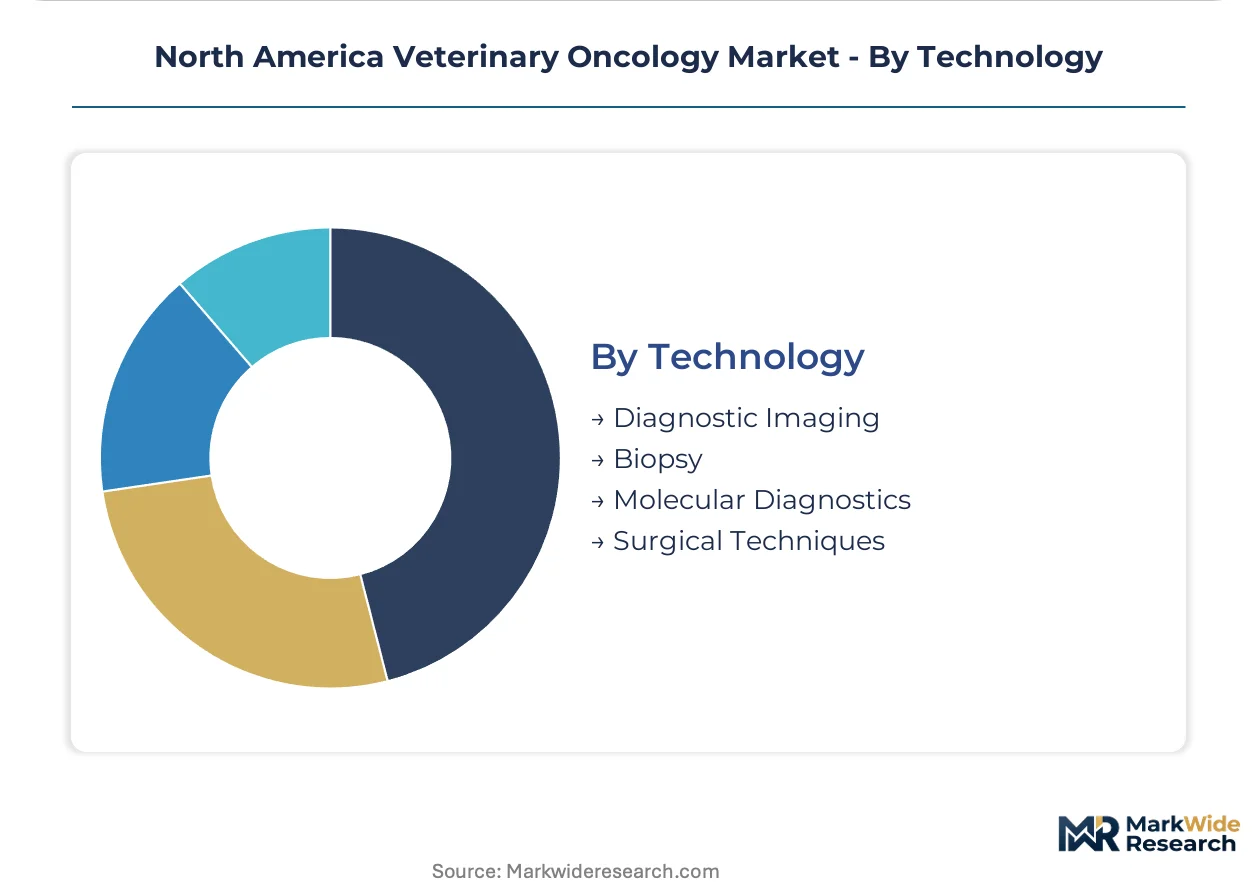
- Molecular Diagnostics:Next-generation sequencing panels and immunohistochemistry platforms guiding personalized therapy algorithms. IDEXX Laboratories' proprietary systems dominate throughput in high-volume reference laboratories.
- Diagnostic Imaging:CT, MRI, and PET-CT for staging and treatment planning. Linear accelerator-integrated imaging is expanding fastest in academic centers pursuing stereotactic radiation protocols.
- Biopsy:Fine-needle aspiration and histopathological confirmation.
- Surgical Techniques:Margin assessment and cytoreductive procedures.
Margin capture sits with Molecular Diagnostics. Capital deployment is concentrated in Diagnostic Imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Companion animal oncology demand concentrates in metropolitan corridors where pet insurance penetration exceeds national averages and specialty veterinary infrastructure has achieved critical mass. The United States dominates absolute spending, though Canadian provincial markets present underpenetrated expansion vectors. Mexico's emerging urban veterinary networks are beginning to stage complex cancer cases requiring cross-border referral coordination.
United States
FDA Center for Veterinary Medicine oversight shapes therapeutic commercialization timelines, with the MUMS framework accelerating approvals for narrow-species indications. Southern California, Texas urban clusters, and the Northeast corridor concentrate specialty practice density where disposable income and pet ownership rates align. California, Texas, and New York state veterinary medical boards impose oncology-specific continuing education mandates that elevate practitioner credentialing thresholds.
Canada
Pet insurance penetration in Ontario and British Columbia trails US benchmarks, creating white-space acquisition potential for veterinary-specific underwriters. Health Canada and the Canadian Food Inspection Agency enforce parallel import controls on veterinary biologics that align with USDA APHIS standards under revised memoranda of understanding. Quebec and Ontario specialty clinics benefit from harmonized cross-border documentation that accelerates autologous vaccine availability timelines.
Mexico
Growing metropolitan middle-class pet ownership in Mexico City and Monterrey is generating demand for advanced oncology services previously requiring US referral. The country's national pharmaceutical regulator maintains distinct approval pathways that create lag times for novel therapeutics available north of the border. Guadalajara and Mexico City veterinary teaching hospitals are developing clinical trial capacity to bridge this access gap.
North America Veterinary Oncology Market Competitive Landscape
United States producers anchor the therapeutics tier; Canadian diagnostic specialists hold regional reference laboratory positions. The market structure stratifies across vertically integrated pharmaceutical manufacturers, precision diagnostic platform controllers, and radiation therapy equipment fabricators. Three archetypes dominate: diversified animal health conglomerates with captive manufacturing networks, molecular diagnostics pure-plays with proprietary assay platforms, and radiation hardware specialists delivering linear accelerator precision upgrades. Competitive moves concentrate on strategic partnerships between diagnostic and therapeutic developers, plus geographic expansion of specialty hospital networks into underserved metropolitan corridors.
Within the diversified therapeutics tier, Zoetis Inc. and Elanco Animal Health Inc. occupy positions exemplifying vertically integrated supply chain control. IDEXX Laboratories, Inc. anchors the diagnostics archetype through reference laboratory infrastructure. Boehringer Ingelheim International GmbH represents the European-headquartered multinational with North American veterinary oncology exposure.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Elanco Animal Health Inc. |
| Boehringer Ingelheim International GmbH |
| IDEXX Laboratories, Inc. |
| Antech Diagnostics, Inc. |
| PetCure Oncology |
| Karyopharm Therapeutics, Inc. |
| Accuray Incorporated |
| Varian Medical Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Specialty veterinary hospital networks concentrate purchasing power across Southern California, Texas, and the Northeast corridor, anchoring a contract-based pricing model where multi-cycle chemotherapy protocol bundles secure volume discounts from distributors. Insurance pre-authorization workflows compress payment cycles, forcing manufacturers to absorb working capital costs in exchange for formulary placement.
Pricing Analysis
Short lead-time premiums dominate the biologics tier, where autologous vaccine manufacturers command 15-25 percent markups for expedited production slots versus standard 14-day turnaround schedules. Three-tier pricing structure across premium, standard, and economy levels separates board-certified academic centers from mid-tier specialty practices and general referral clinics. Cost compression in the chemotherapy generic segment is intensifying because Zoetis and Elanco have expanded captive manufacturing capacity. General practice clinics show highest price sensitivity, while university-affiliated hospitals prioritize clinical outcomes over per-dose economics.
Supply Chain Analysis
Regional distribution centers in Indianapolis, Dallas, and Ontario anchor a hub-and-spoke cold chain network that feeds last-mile veterinary clinics within 48-hour delivery windows. Active pharmaceutical ingredient sourcing draws from India, China, and Ireland for generic chemotherapy precursors, while isotope production for diagnostic imaging rests on limited cyclotron capacity in the United States and Canada. Single-source vulnerability concentrates in the radioactive sourcing tier, where production interruptions at Oak Ridge or Chalk River facilities cascade through PET-CT scheduling. Distribution runs through specialty veterinary distributors with temperature-validated logistics rather than general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary oncology is consolidating around diagnostic-therapeutic integration, with FDA MUMS pathway acceleration and insurance credentialing requirements forcing sub-scale competitors toward exit or acquisition.
For Market Incumbents: Cement diagnostic platform control by acquiring reference laboratories in Texas and California corridor markets where IDEXX maintains dominant throughput. Deepen backward integration into companion diagnostic development to capture margin pools currently flowing to human-health assay developers. Board certification bottlenecks for radiation oncologists represent the priority defensive moat. For New Entrants and Emerging Players: Specialty telemedicine platforms offer the most penetrable channel partnership for AI-enabled histopathology services targeting general practice clinics lacking boarded pathologists. Canadian provincial markets, particularly Ontario and British Columbia, present white-space acquisition potential where pet insurance penetration trails US benchmarks by 15-20 points. A veterinary-specific underwriter partnership model unlocks faster credentialing than direct hospital sales cycles. For Investors and Strategic Acquirers: The window for entry favors molecular diagnostics pure-plays with proprietary immunohistochemistry platforms and established reference laboratory infrastructure. Long-term viability hinges on data network effects that improve treatment algorithm accuracy and support payer pre-authorization workflows. Watch for ACVIM diplomate output expansion rates as the inflection signal determining whether specialty clinic growth outpaces qualified practitioner supply.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Real-world evidence registries tracking canine lymphoma outcomes satisfy FDA post-market surveillance and payer documentation requirements. |
| Regulatory Approval Pathway | MUMS framework exploitation for narrow-species indications compresses development timelines versus full NADA submissions. |
| Manufacturing Scale-Up | Captive production of chemotherapy agents insulates against API sourcing volatility from Indian and Chinese suppliers. |
| Strategic Partnership | Diagnostic-therapeutic developer alliances mirror human oncology models where companion tests gate treatment access. |
| Geographic Expansion | Specialty hospital network penetration into Texas urban clusters captures fastest-growing insured pet population density. |
Research Methodology
FDA Center for Veterinary Medicine approval databases, USDA APHIS biologics licensing records, and state veterinary medical board credentialing reports formed the secondary backbone. Primary interviews with veterinary oncologists, specialty hospital administrators, pet insurance underwriters, and reference laboratory executives validated demand assumptions. Bottom-up modeling of clinic-level case volumes and top-down reconciliation against manufacturer shipment data ensured cross-verification.
Bottom-up volume builds aggregated chemotherapy protocol cycles, radiation therapy fractions, and diagnostic test throughput across metropolitan corridor markets. Top-down reconciliation checked segment totals against disclosed manufacturer revenues and distributor shipment patterns. Segmentation dimensions included treatment modality, care setting credentialing tier, delivery route, and provincial regulatory cluster. CAGRs were derived from insurance penetration elasticity models and specialty clinic expansion pipelines.
Caveats apply where FDA approval timeline delays, cyclotron production interruptions, or ACVIM residency output constraints could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Radiation Oncology Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Glioblastoma Market
Oncology
South Korea Radiotherapy Market
Oncology
Colorectal Cancer Market
Oncology
Pharyngeal Neoplasm Market
Oncology
Gynecological Cancers Market
Oncology
Particle Therapy Systems Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
Esophageal Cancer Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Global Cancer Profiling Market
Oncology
Breast Cancer Brachytherapy Market