
 Global Sterile Injectable Drugs Market | 2026-2036
Global Sterile Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sterile Injectable Drugs Market Intelligence
Procurement focus within the sterile injectables supply chain is rotating from large hospital systems toward specialty clinics and ambulatory surgical centers. Pfizer Inc. leverages its extensive manufacturing network to supply a broad portfolio of essential injectable medicines across these channels. Sanofi specializes in high-value biologics and vaccines, often administered in specialized care settings. Novartis Pharmaceuticals Corporation, through its Sandoz division, competes on the strength of its biosimilar and generic injectable pipeline.
Sterile injectable drugs are pharmaceutical formulations administered parenterally, requiring absolute freedom from microbial contamination. These products, which must be isotonic and pyrogen-free, enable rapid therapeutic action and are essential for delivering biologics and other drugs degraded by the digestive system. Lyophilized powder formulations command higher margins due to complex manufacturing, while liquid injections represent the largest volume segment. The shift toward pre-filled syringes from traditional vials reflects a push for improved safety, dosing accuracy, and ease of administration.
Market access hinges on compliance with stringent manufacturing and quality standards set by regulators like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These bodies enforce current Good Manufacturing Practices (cGMP) for aseptic processing, which dictates facility design, operational protocols, and validation requirements. Future competitive advantage will depend on securing resilient supply chains for active pharmaceutical ingredients and investing in advanced aseptic filling technologies.
Market Dynamics
The increasing molecular complexity of biologic drugs, particularly monoclonal antibodies and cell therapies, is the central force shaping the sterile injectable market. This shift dictates more stringent aseptic manufacturing requirements, drives investment in lyophilization capacity, and necessitates the development of advanced drug delivery systems.
Growth Catalysts
- Biologic Pipeline Expansion:The robust pipeline of biologic drugs for oncology and autoimmune diseases creates sustained demand for parenteral administration, as these large molecules cannot be delivered orally.
- Regulatory Harmonization:Efforts by bodies like the International Council for Harmonisation (ICH) to align technical requirements, alongside reforms by China's NMPA, streamline global drug development and market entry.
- Shift to Home-Based Care:The development of user-friendly delivery devices, such as autoinjectors and pre-filled syringes, facilitates the transition of chronic disease management from hospitals to home settings, expanding the patient base.
Market Restraints
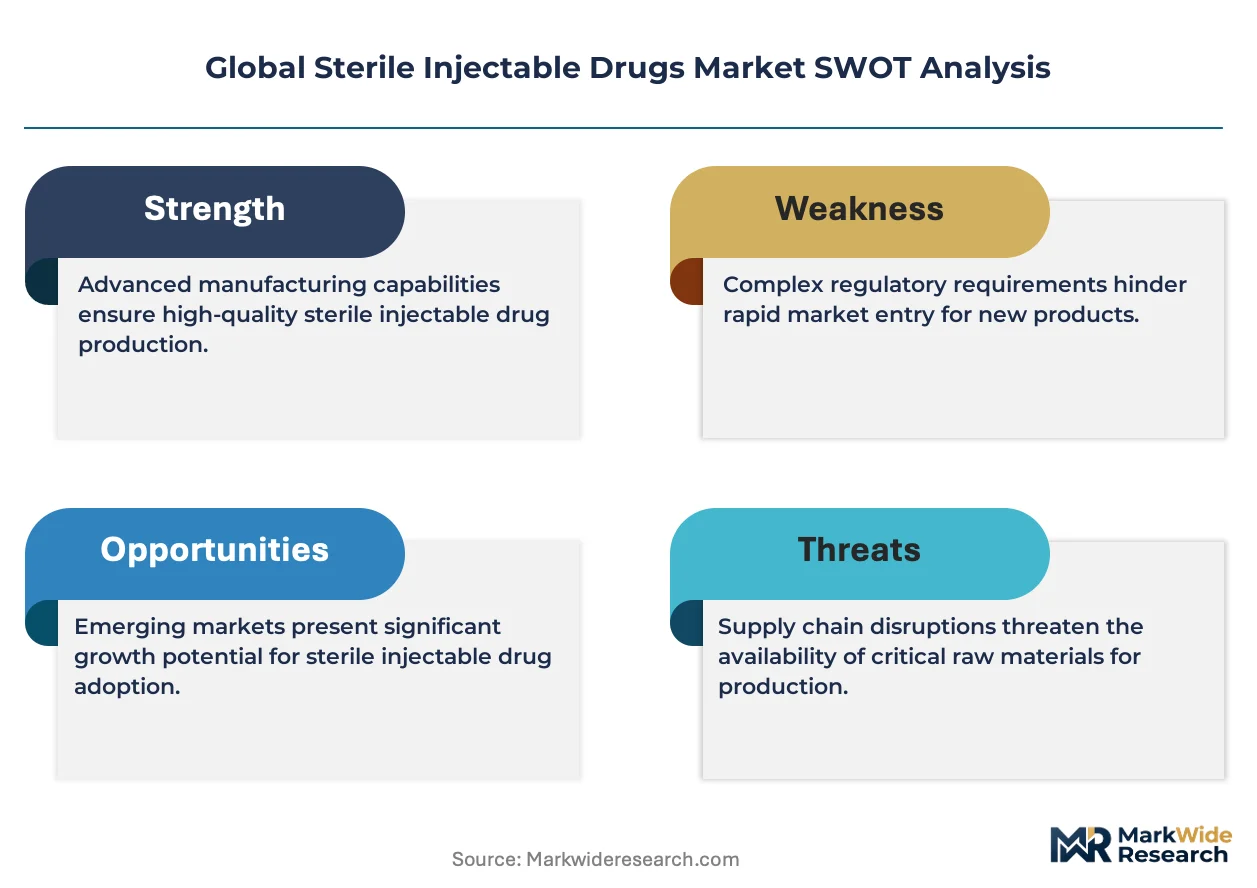
- High Capital Investment:Establishing and maintaining aseptic manufacturing facilities that comply with cGMP standards set by the FDA and EMA requires substantial, long-term capital investment in specialized equipment and cleanrooms.
- Raw Material Bottlenecks:Supply chain vulnerability for critical components, including high-quality glass for vials and syringes and specialized polymers for stoppers, can lead to production delays and shortages.
- Complex Regulatory Hurdles:Navigating the stringent and often lengthy approval pathways for new sterile products and manufacturing line modifications presents a significant barrier to entry and slows time-to-market.
Strategic Opportunities
- Advanced Aseptic Technologies:Investing in isolator and robotic systems for aseptic filling minimizes human intervention, reducing contamination risk and improving sterility assurance levels, creating a competitive advantage.
- Emerging Market Expansion:Building manufacturing and distribution capabilities in underpenetrated markets, such as Brazil and India, addresses growing local demand for essential medicines and vaccines.
- Ready-to-Use Formulations:Developing ready-to-use or ready-to-administer injectable products reduces the need for hospital pharmacy reconstitution, minimizing medication errors and improving workflow efficiency.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of technicians, microbiologists, and quality assurance professionals with expertise in aseptic processing and sterile manufacturing constrains capacity expansion across the industry.
- Cold Chain Integrity:Ensuring the integrity of the cold chain for temperature-sensitive biologics and vaccines from the manufacturing plant to the point of administration poses significant logistical and cost challenges.
- Regulatory Compliance Burden:The continuous evolution of global cGMP standards, such as the EU's revised Annex 1, requires ongoing investment in process validation, environmental monitoring, and quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sterile Injectable Drugs Market |
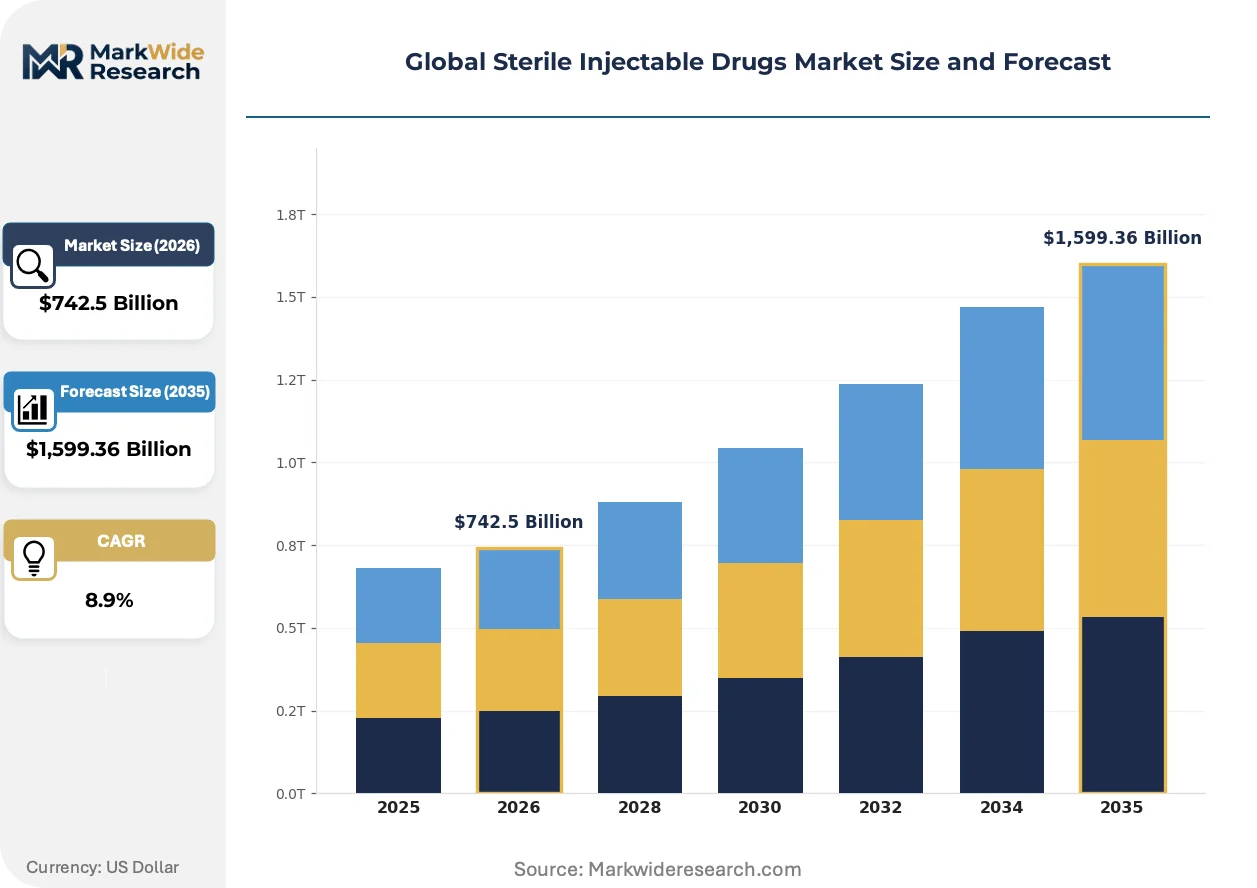
| Market Size in 2026 | $742.5 Billion |
| Market Size in 2035 | $1,599.36 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lyophilized Powder, Liquid Injection, Suspensions, Emulsions, Implants Therapy Area: Oncology, Vaccinology, Cardiovascular Disorders, Neurology, Anti-infectives End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Delivery Mode: Pre-filled Syringes, Vials, Ampoules, Cartridges, Pen Injectors |
| Companies Covered | Sanofi, Fresenius Kabi, Pfizer Inc., Viatris, Sandoz, Johnson & Johnson, AstraZeneca, Teva, Novartis Pharmaceuticals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sterile Injectable Drugs Market Strategic Shifts & Innovations
The industrialization of sterile drug production is accelerating to manage the growing volume and complexity of biologics. This involves a fundamental shift toward automated, closed-process manufacturing and integrated digital quality oversight to ensure sterility and compliance at scale.
Wearable patch pump systems are a key product evolution. These devices adhere to the skin to provide continuous, subcutaneous drug delivery for chronic conditions. Specialty clinics and home healthcare providers are driving adoption for managing diseases like diabetes, which is miniaturizing the entire administration process from a clinical procedure to a patient-managed activity.
The EU's revised GMP Annex 1 regulation is a significant policy shift impacting sterile manufacturing globally. It mandates a holistic and documented Contamination Control Strategy (CCS) that covers all aspects of facility design, personnel training, and production processes. Contract manufacturers are most affected, as they must upgrade systems and provide extensive validation data to serve clients marketing products in Europe.
A clear behavioral shift is occurring in how injectable drugs are sourced by healthcare providers. The traditional model of large, centralized hospital pharmacies placing bulk vial orders is being supplemented by direct purchasing from specialty clinics and ambulatory surgical centers. This change favors suppliers who can manage smaller, more frequent shipments of pre-filled syringes, particularly visible in the fragmented US healthcare system.
Global Sterile Injectable Drugs Market Segmentation
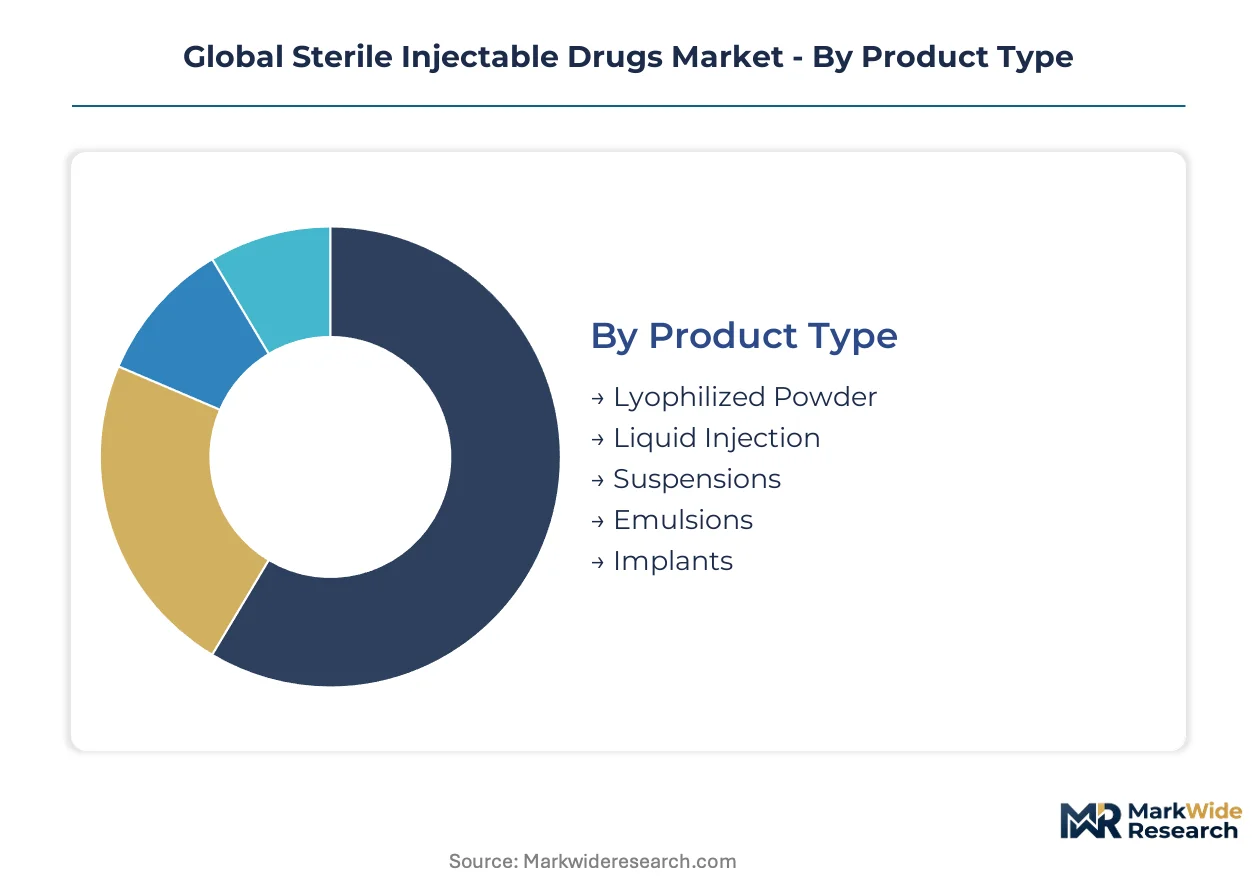
The segmentation of the global sterile injectable drugs market highlights distinct product forms, therapeutic applications, and administration methods. Understanding these categories reveals critical shifts in manufacturing complexity, patient care settings, and regulatory compliance. Each segment reflects unique demand patterns and technological requirements across the pharmaceutical landscape.
Product Type:
Substitution pressure affects product type choices, as healthcare providers balance cost, convenience, and efficacy for parenteral medications.
- Lyophilized Powder:These formulations are freeze-dried drug products requiring reconstitution before administration, preserving stability for sensitive biologics and small molecules. Complex manufacturing processes often lead to higher margins, with demand concentrating in specialized oncology treatments.
- Liquid Injection:These ready-to-administer solutions represent the largest volume segment, offering immediate use and reducing preparation errors in hospital and clinic settings. Their widespread adoption is driven by convenience and established manufacturing scalability for essential medicines.
- Suspensions:Heterogeneous mixtures of solid particles in a liquid, suspensions are used for sustained drug release, particularly for intramuscular or subcutaneous routes.
- Emulsions:Comprising immiscible liquid phases, emulsions deliver poorly soluble drugs and are critical for intravenous nutrition and certain anesthetic agents.
- Implants:Solid or semi-solid sterile drug delivery devices provide long-term, controlled release of therapeutic agents, often for hormonal or contraceptive applications.
Liquid Injection anchors the volume base while Lyophilized Powder gains share at the steepest rate.
Therapy Area:
The market's therapy area segmentation reflects the specific disease states addressed by sterile injectable drugs, influencing development priorities and regulatory pathways.
- Oncology:This segment covers treatments for various cancers, primarily utilizing biologics like monoclonal antibodies and cell therapies, which require precise parenteral administration. Demand is concentrated in advanced markets like the US and Europe due to robust R&D pipelines and patient access.
- Vaccinology:Vaccines protect against infectious diseases, delivered parenterally to elicit immune responses, often requiring strict cold chain management. Global health organizations and national immunization programs drive significant volume, particularly in emerging economies.
- Cardiovascular Disorders:Injectable therapies manage acute cardiac events, hypertension, and thrombosis, often administered in emergency settings or for chronic management.
- Neurology:This segment includes treatments for neurological conditions such as multiple sclerosis and Parkinson's disease, frequently involving specialized biologics.
- Anti-infectives:Sterile injectables provide potent antibiotics, antivirals, and antifungals for severe infections, especially in hospital-acquired cases.
Oncology applications dominate high-value biologics, while Vaccinology maintains a consistent, high-volume demand across global health initiatives.
End User:
Customer type dictates procurement patterns, with a notable shift from traditional large-scale purchasers to specialized care providers.
- Hospitals:These institutions serve as major consumers of sterile injectables for acute care, surgical procedures, and inpatient treatment across a broad range of therapeutic areas. Bulk purchasing of vials historically defined this channel, but procurement is evolving.
- Ambulatory Surgical Centers:These outpatient facilities administer injectables for same-day surgical procedures, prioritizing ready-to-use formulations for efficiency and safety.
- Specialty Clinics:These clinics focus on specific disease states like oncology or rheumatology, driving demand for high-value biologics, often delivered in pre-filled syringes. Procurement patterns here favor smaller, more frequent shipments.
- Research Laboratories:Academic and pharmaceutical research facilities utilize sterile injectables for preclinical and clinical studies, demanding high purity and specific formulations.
Hospitals remain the primary point of administration, but Specialty Clinics are rapidly expanding their share of injectable drug utilization.
Delivery Mode:
Technology adoption within delivery modes emphasizes user safety, dosing accuracy, and workflow efficiency across diverse care settings.
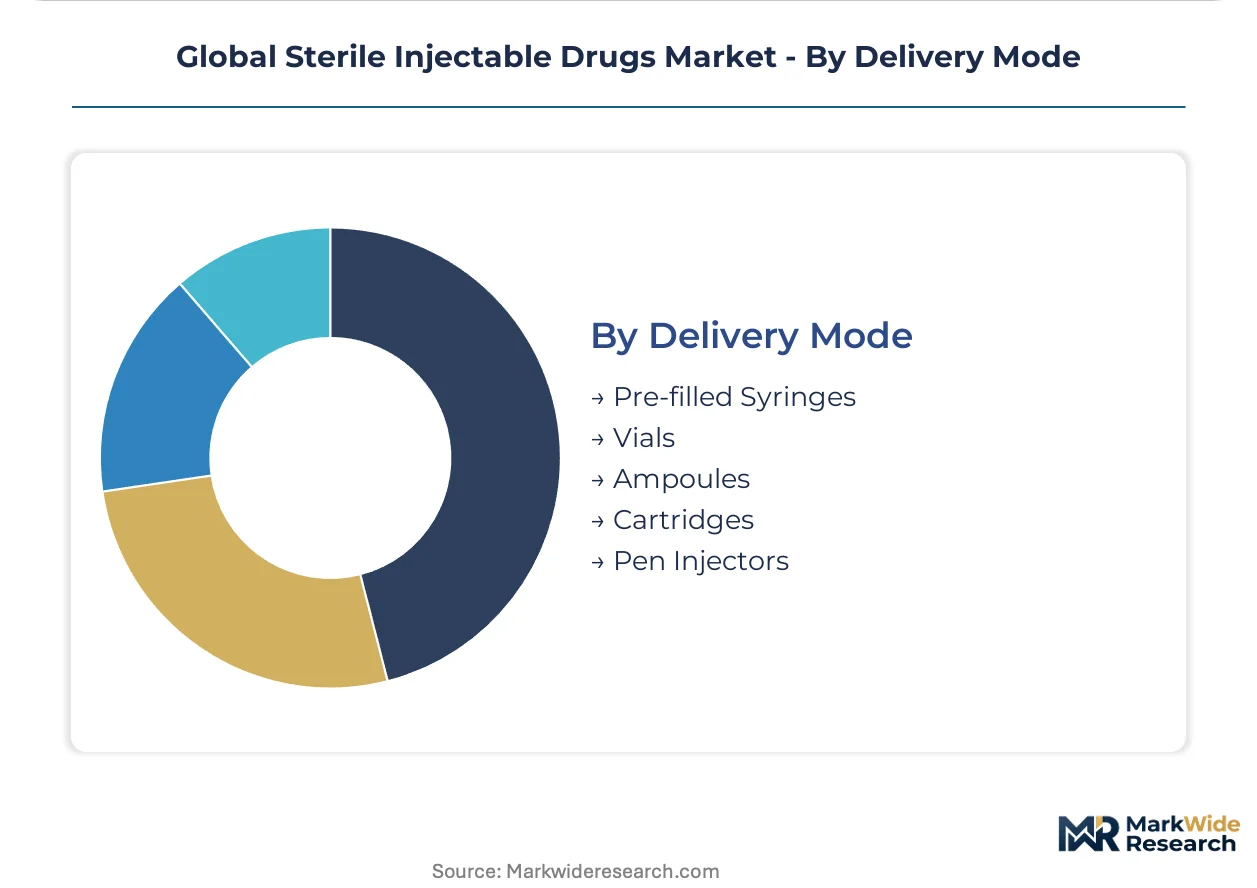
- Pre-filled Syringes:These ready-to-use devices enhance patient safety and dosing accuracy by eliminating preparation steps, particularly for complex biologics and home-based care. Demand is accelerating in chronic disease management and self-administration.
- Vials:Traditional glass containers hold multi-dose or single-dose injectable medications, requiring drawing and preparation before administration. They remain a cost-effective solution for high-volume generic drugs and hospital-based compounding.
- Ampoules:Single-use glass containers for liquid injectables, ampoules ensure sterility but require breaking the glass, introducing a potential for sharps injury.
- Cartridges:These contain multiple doses for use with pen injectors, offering convenience and precise dosing for conditions like diabetes or growth hormone deficiency.
- Pen Injectors:User-friendly devices designed for self-administration, pen injectors facilitate accurate and convenient delivery of pre-filled cartridges, improving patient adherence.
Pre-filled Syringes command a growing share due to user-friendliness, while Vials continue to serve as a foundational, cost-effective delivery mechanism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's pharmaceutical exports to global markets drive significant sterile injectable drug availability, particularly for essential medicines. This trade dynamic underscores the interdependent nature of the supply chain, balancing innovation in advanced economies with manufacturing scale in emerging regions. Regulatory frameworks across key geographies shape market access.
United States
Biologic pipeline expansion for oncology and autoimmune diseases creates sustained demand for parenteral administration. The US FDA's stringent cGMP standards ensure product quality and safety across the industry. The Boston-Cambridge biotech cluster focuses on advanced cell and gene therapies requiring sterile injectables.
Germany
High-value biologics and vaccine production drives demand for advanced aseptic filling technologies. The European Medicines Agency (EMA) enforces strict manufacturing guidelines for market approval. The Frankfurt Rhine-Main region hosts numerous pharmaceutical manufacturers investing in sterile injectable capacity.
Japan
An aging population and advanced healthcare infrastructure sustain demand for specialized injectable therapies. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product approvals and manufacturing compliance. The Kansai region, including Osaka, features strong research and development activities for novel injectable drug development.
China
Domestic pharmaceutical manufacturing capabilities are expanding, increasing local sterile injectable production. China's NMPA reforms streamline drug development and market entry for new products. The Yangtze River Delta region is a major hub for pharmaceutical production, including advanced aseptic facilities.
India
Growing healthcare access and a large generic drug manufacturing base fuel demand for essential sterile injectables. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical quality and safety. Hyderabad's Genome Valley concentrates pharmaceutical and biotech companies developing injectable formulations.
Global Sterile Injectable Drugs Market Key Industry Players
Listed leaders compete with private specialists across manufacturing scale and therapeutic focus, creating a dynamic market environment. The market exhibits a tiered structure, with large pharmaceutical companies dominating high-value biologics and global distribution channels. Several strategic archetypes emerge, including integrated pharmaceutical giants and specialized contract development and manufacturing organizations that provide critical support. Companies frequently engage in capacity expansion and strategic partnerships to secure resilient supply chains and accelerate product development.
Specialists in high-value biologics and essential medicines include companies like Pfizer Inc., which leverages an extensive manufacturing network to supply a broad portfolio. Sanofi represents a strong focus on advanced biologics and vaccines, often distributed in specialized care settings requiring specific administration protocols. Novartis Pharmaceuticals Corporation, through its Sandoz division, exemplifies a strategy centered on biosimilars and generic injectable pipelines, addressing broad market needs with cost-effective solutions. These entities anchor distinct segments within the sterile injectable drugs market, reflecting diverse approaches to product development and distribution.
| Leading Market Players |
|---|
| Sanofi |
| Fresenius Kabi |
| Pfizer Inc. |
| Viatris |
| Sandoz |
| Johnson & Johnson |
| AstraZeneca |
| Teva |
| Novartis Pharmaceuticals Corporation |
| Others |
Cost & Logistics Intelligence
The shift from traditional vials to pre-filled syringes reshapes sterile injectable supply geography by decentralizing demand and simultaneously elevates pricing economics through added user convenience and safety. This product evolution influences distribution networks and cost structures across the value chain.
Pricing Analysis
The technology-generation pricing gap between complex lyophilized biologics and high-volume liquid injectables defines market value. The dominant pricing structure combines per-unit transactional models for generics with value-based pricing for high-value biologics. Price differentiation stems from manufacturing complexity, stringent regulatory compliance like US FDA cGMP adherence, and the formulation's ready-to-use nature. Pricing softness reflects increased competition in generic liquid injectables. Hospitals are highly price-sensitive for high-volume essential medicines, while specialty clinics prioritize therapeutic value for high-cost biologics.
Supply Chain Analysis
The limited global supply of high-purity glass for pharmaceutical packaging presents a critical chokepoint for sterile injectable manufacturing. Geographic supply concentrates in China and India for active pharmaceutical ingredients and generic production, while Germany and the US lead advanced biologic manufacturing. Raw material dependencies include high-quality glass for vials and syringes, specialized polymers for stoppers, and active pharmaceutical ingredients. Single-source vulnerability for specialized components, particularly for new biologic delivery systems, represents a structural risk. Distribution runs through a hybrid model with centralized warehousing for hospitals and direct-to-clinic or home delivery for specialty products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global sterile injectable drugs market represents a platform-economics inflection. The integration of user-friendly delivery devices with chronic disease management creates a connected patient care ecosystem, transforming drug administration.
For Market Incumbents: Shield core market share by investing in advanced aseptic manufacturing technologies. Acquire specialized contract development and manufacturing organizations with lyophilization expertise to counter emerging biologics manufacturers. Deepen vertical integration into critical component manufacturing, such as specialized glass, to mitigate supply chain risks. Capacity additions in advanced aseptic filling facilities, particularly in Germany, reinforce market leadership.
For New Entrants and Emerging Players: Differentiate on user-friendly delivery systems for home-based care. Target niche oncology biologics requiring advanced pre-filled syringes and specialized vaccines for underpenetrated markets as white-space opportunities. Home-based chronic disease management, particularly for conditions amenable to autoinjectors, represents the most penetrable segment. Partner with specialty clinics and home healthcare providers for direct patient access as a key go-to-market angle.
For Investors and Strategic Acquirers: The EU's revised GMP Annex 1 reshapes the acquisition landscape by demanding enhanced compliance infrastructure. The market offers sustained long-term viability driven by biologic pipeline expansion and chronic disease prevalence over the next 5-10 years. Target specialized contract development and manufacturing organizations with expertise in advanced aseptic filling and lyophilization for acquisition. Increased M&A activity among smaller technology providers specializing in isolator and robotic filling systems is a specific signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Investing in advanced aseptic facilities in China enhances global manufacturing scale for essential medicines. |
| Product Development | Developing ready-to-use pre-filled syringes improves patient safety and convenience for home administration. |
| Strategic Partnerships | Collaborating with biologics developers for co-development accelerates market entry for novel injectable therapies. |
| Regulatory Compliance | Investing in EU GMP Annex 1 upgrades ensures market access and maintains product quality standards for European distribution. |
| Talent Acquisition | Recruiting specialized microbiologists and QA professionals addresses critical skill gaps in aseptic manufacturing operations. |
Research Approach
The analysis maps sterile injectable product types, therapeutic areas, and end-user segments, each validated through primary interviews with industry stakeholders. This approach combined insights from drug development executives, regulatory affairs leads, hospital procurement managers, and specialty clinic directors. Secondary data sources included US FDA filings, European Medicines Agency (EMA) submissions, China NMPA reports, and various industry association publications. Bottom-up data aggregation from company disclosures and top-down market sizing provided comprehensive triangulation.
Forecast outputs were validated for consistency against historical market trends and external economic indicators over the projection horizon. The analytical framework modeled segmentation dimensions such as product type, therapy area, end-user, delivery mode, and regional regulatory frameworks. Compound Annual Growth Rates were derived from a multi-variable regression model incorporating demand drivers and market restraints. Biologic drug pipeline expansion rates and regulatory approval timelines for novel injectables served as key industry-specific forecast inputs.
Material uncertainties — including unforeseen supply chain disruptions or major policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding technological adoption and global healthcare spending. Geopolitical instability affecting raw material supply and evolving regulatory landscapes could revise these forecasts. Practitioners should keep alternative scenarios live as global health priorities and manufacturing capabilities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
Mexico Diabetes Drugs Market