
 Peptide Therapeutics Market | 2026-2036
Peptide Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide Therapeutics Market Intelligence
Oncology is recalibrating demand profiles across the peptide therapeutics landscape as immuno-oncology protocols expand peptide-based targeting mechanisms. Novo Nordisk anchors its position through deep R&D intensity in metabolic peptide engineering, while Eli Lilly and Company leverages manufacturing scale to supply hospital and specialty clinic networks. Pfizer competes through geographic dominance in North American and European distribution channels.
Peptide therapeutics are short chains of amino acids, typically comprising 2–50 residues, synthesized through solid-phase peptide synthesis or recombinant DNA expression systems, designed to modulate cellular signaling pathways with high target specificity and reduced off-target toxicity. Their primary purpose centers on treating chronic metabolic, oncologic, and cardiovascular conditions where small-molecule drugs lack sufficient selectivity. Hormonally active peptides occupy the largest revenue pool given established insulin and GLP-1 analog franchises, while antimicrobial peptides represent the fastest-growing category amid rising hospital-acquired infection rates and multidrug-resistant pathogen prevalence. Injectable delivery dominates current volumes, though oral formulations are gaining structural attention as permeation enhancers and cyclization techniques improve bioavailability profiles.
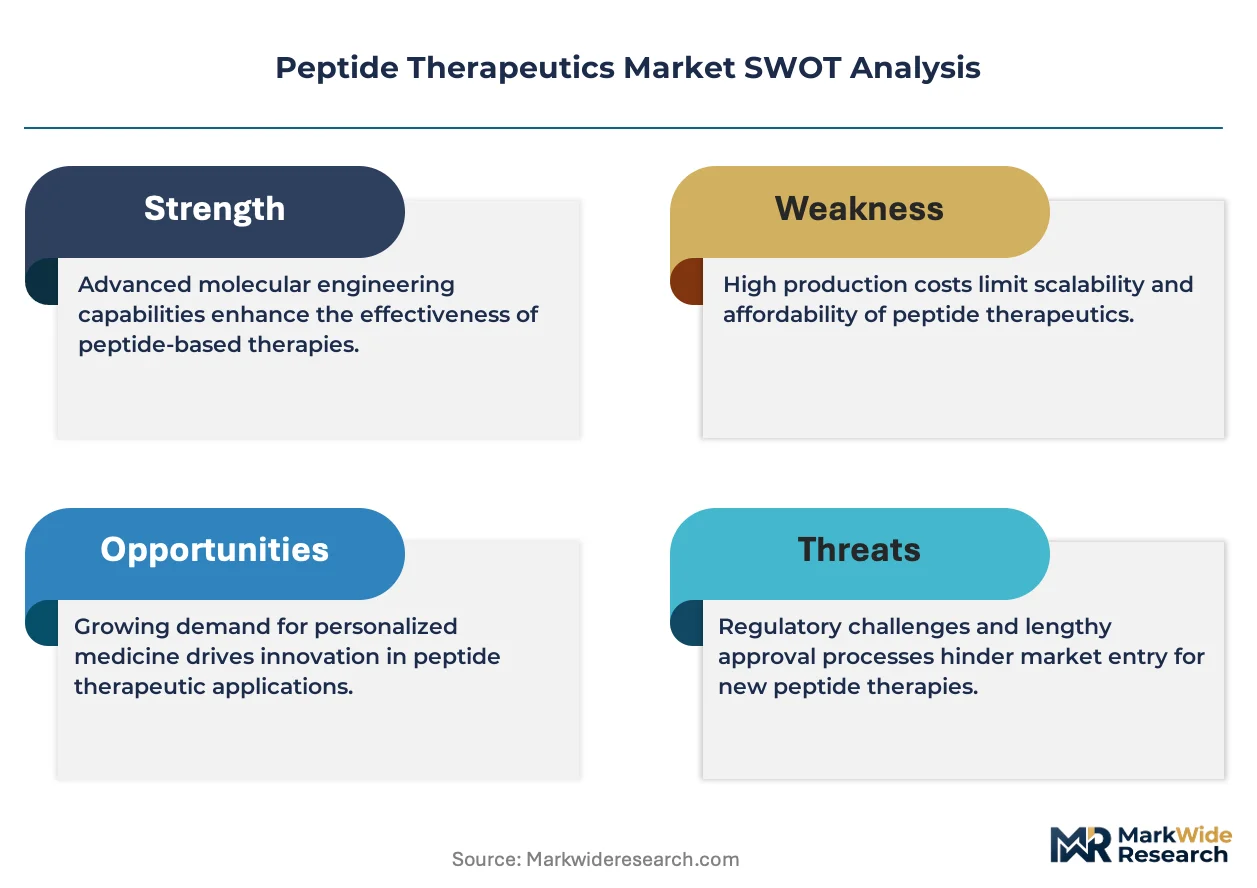
The FDA enforces Current Good Manufacturing Practice standards for peptide purity and endotoxin limits, while the EMA's MDR framework imposes additional clinical evidence requirements for novel therapeutic peptides seeking European market access. These dual regulatory architectures shape development timelines, manufacturing investment decisions, and regional launch sequencing for developers. Stakeholders must monitor evolving immunogenicity assessment protocols and biosimilar pathway clarifications as peptide portfolios mature and competitive entry intensifies.
Market Dynamics
The FDA's tightened purity and endotoxin standards are compressing development timelines while forcing developers toward recombinant manufacturing platforms, creating a bifurcation between capital-intensive players and legacy solid-phase synthesis operators.
Growth Catalysts
- GLP-1 analog expansion:Metabolic peptide engineering is pulling hospital networks into specialty clinic partnerships for chronic disease management protocols.
- MDR clinical evidence pathways:The EMA's framework is accelerating European market access for recombinant peptides with superior immunogenicity profiles.
- Hospital-acquired infection protocols:Antimicrobial peptide demand is concentrating in United States academic medical centers facing multidrug-resistant pathogen prevalence.
Market Restraints
- Recombinant platform capex intensity:Cell culture and fermentation infrastructure requires capital deployment that excludes mid-scale developers.
- Supply concentration in contract manufacturers:United States and European CDMOs control capacity for GMP-grade peptide production.
- Oral bioavailability ceiling:Permeation enhancers face structural limits against gastrointestinal degradation for peptides exceeding 30 residues.
Strategic Opportunities
- Japan's PMDA accelerated review:The regenerative medicine and cell therapy framework creates fast-track pathways for novel peptide modalities.
- Cardiovascular peptide underpenetration:Natriuretic peptide analogs for heart failure remain undeveloped relative to metabolic and oncology applications.
- Continuous manufacturing convergence:Flow chemistry integration with solid-phase synthesis is enabling real-time quality control and batch size flexibility.
Industry Challenges
- Peptide chemist scarcity:Solid-phase synthesis expertise concentrates in legacy pharmaceutical hubs, constraining workforce expansion for new entrants.
- Immunogenicity assay standardization:Preclinical T-cell epitope prediction lacks harmonized FDA-EMA guidance, extending IND preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide Therapeutics Market |
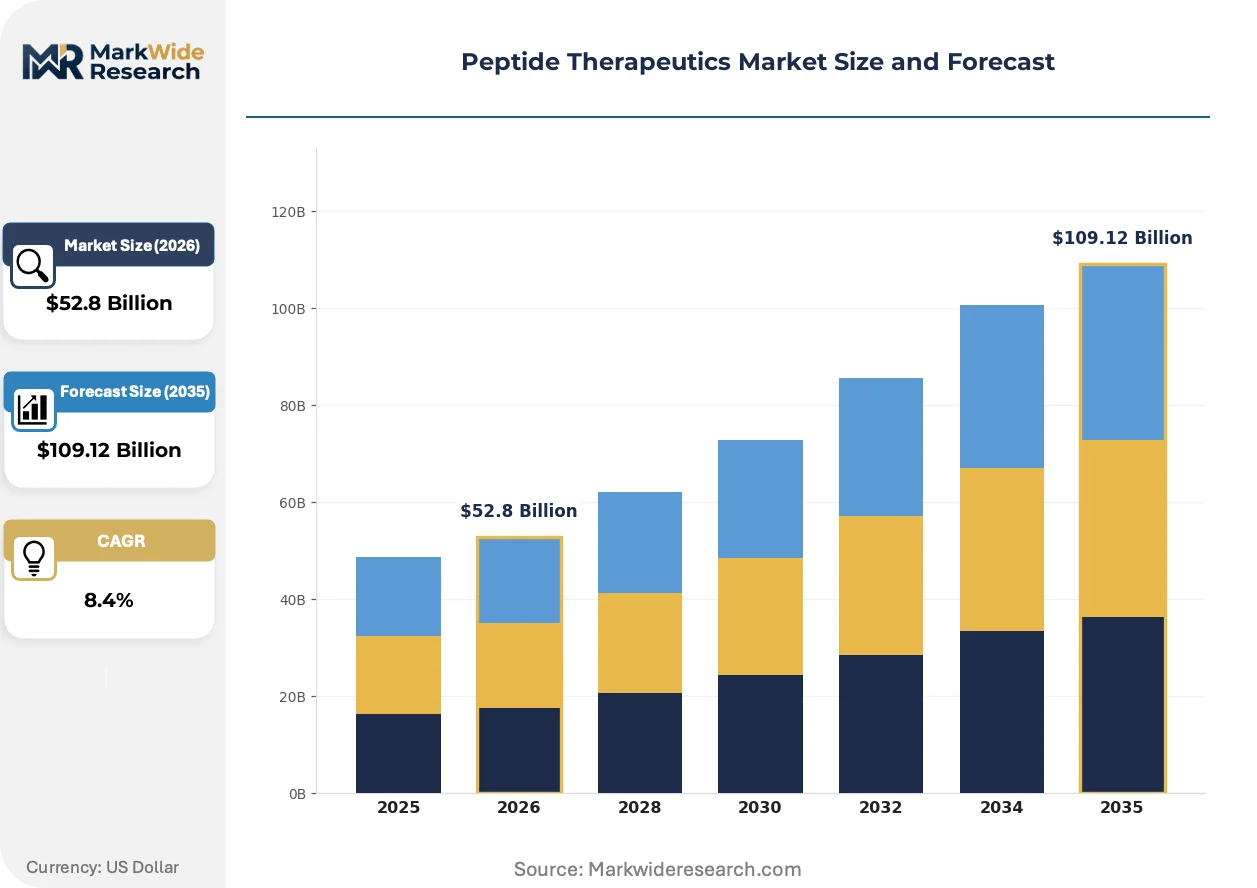
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonally Active Peptides, Antimicrobial Peptides, Signal Peptides, Cytokines Therapy Area: Oncology, Diabetes, Cardiovascular Disorders, Neurological Disorders Delivery Mode: Injectable, Oral, Transdermal, Intranasal End User: Hospitals, Specialty Clinics, Research Laboratories, Pharmaceutical Companies |
| Companies Covered | AstraZeneca, Novo Nordisk, Eli Lilly and Company, Pfizer, Novartis, Amgen, GlaxoSmithKline, Takeda Pharmaceuticals, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide Therapeutics Market Strategic Shifts & Innovations
Peptide therapeutics are undergoing structural transformation through manufacturing technology migration, regulatory pathway evolution, and delivery mechanism innovation that collectively reshape competitive positioning across metabolic and oncology applications.
Cyclization techniques and non-natural amino acid incorporation are converging with permeation enhancer chemistry to expand oral peptide viability beyond historical bioavailability constraints. Specialty clinics in the United States are piloting these formulations for GLP-1 analogs. This convergence is compressing the injectable-or-nothing paradigm that has dominated peptide delivery for three decades.
REACH chemical registration requirements are extending to peptide intermediates and synthetic reagents, forcing European manufacturers to requalify supply chains for novel building blocks. The industrial consequence is accelerated backward integration into captive amino acid production. Small-scale developers without in-house synthesis capabilities face exclusion from European commercialization pathways.
Hospital procurement committees are consolidating peptide therapeutic purchasing under centralized pharmacy and therapeutics protocols, displacing individual physician-driven prescribing for high-cost metabolic analogs. United States health systems are negotiating outcome-based contracts with manufacturers for GLP-1 and insulin franchises. This behavioral shift is visible most acutely in integrated delivery networks across the Midwest and Southeast regions.
Peptide Therapeutics Market Segmentation
Peptide therapeutic developers configure product portfolios across four structural dimensions that determine manufacturing investment, regulatory pathway selection, and commercial access strategy. Each segmentation axis carries distinct margin profiles and competitive intensity.
Product Type:
Hormonally active peptides function as standalone therapeutic modalities, while antimicrobial and signal peptides embed into broader treatment protocols requiring combination therapy infrastructure.
- Hormonally Active Peptides:Engineered analogs of insulin, GLP-1, and growth hormone dominate prescription volumes through established receptor-mediated metabolic regulation. United States specialty clinics and hospital networks concentrate procurement for diabetes and obesity management, with Novo Nordisk and Eli Lilly controlling manufacturing scale.
- Antimicrobial Peptides:Cationic amphipathic sequences disrupt bacterial membranes through non-receptor mechanisms, offering activity against multidrug-resistant pathogens. United States academic medical centers facing hospital-acquired infection protocols drive demand concentration, though recombinant production costs constrain formulary adoption.
- Signal Peptides:Short targeting sequences direct protein localization within cellular machinery.
- Cytokines:Immunomodulatory peptides regulate inflammatory and immune responses.
Hormonally active peptides lead volumes today; antimicrobial peptides are gaining share fastest.
Therapy Area:
Cost tier stratification separates chronic disease management from acute intervention, with diabetes and cardiovascular applications commanding premium pricing through long-term administration protocols.
- Diabetes:GLP-1 receptor agonists and insulin analogs constitute the largest revenue pool, with United States integrated delivery networks negotiating outcome-based contracts for metabolic peptide franchises. Injectable delivery dominates, though oral formulations are penetrating specialty clinic pilot programs.
- Oncology:Peptide-drug conjugates and tumor-targeting sequences integrate into immuno-oncology protocols at major cancer centers. The FDA's tightened immunogenicity standards are compressing IND timelines for novel modalities.
- Cardiovascular Disorders:Natriuretic peptide analogs for heart failure remain underdeveloped relative to metabolic applications.
- Neurological Disorders:Blood-brain barrier penetration limits peptide viability for CNS indications.
Diabetes anchors revenue today; oncology is climbing the fastest.
Delivery Mode:
Application context determines route selection, with hospital-based acute care favoring injectable precision while outpatient chronic management creates pressure for oral alternatives.
- Injectable:Subcutaneous and intravenous administration delivers bioactive peptides with complete systemic availability. United States hospital pharmacies and specialty clinics standardize procurement around pre-filled pen devices and infusion protocols for GLP-1 and insulin analogs.
- Oral:Cyclization techniques and permeation enhancers are compressing bioavailability gaps for peptides under 30 residues. Japanese PMDA accelerated review pathways are attracting developers testing novel gastrointestinal protection chemistries.
- Transdermal:Microneedle arrays and iontophoresis enable non-invasive delivery for selected sequences.
- Intranasal:Olfactory epithelium absorption offers rapid onset for emergency applications.
Injectable delivery dominates volume today; oral formulations are expanding most quickly.
End User:
Customer type segmentation reflects procurement authority concentration, with centralized hospital pharmacy committees displacing individual physician prescribing for high-cost metabolic peptides.
- Hospitals:Integrated delivery networks across the United States Midwest and Southeast regions consolidate peptide therapeutic purchasing under pharmacy and therapeutics committees. Outcome-based contracting with manufacturers is standard for GLP-1 and insulin franchises.
- Specialty Clinics:Endocrinology and obesity medicine practices pilot novel oral formulations and combination therapies. These sites function as early adoption channels for next-generation peptide modalities before hospital formulary expansion.
- Research Laboratories:Academic and contract research organizations supply preclinical and clinical trial materials.
- Pharmaceutical Companies:In-house manufacturing and external CDMO partnerships supply commercial and development-stage inventories.
Hospitals lead procurement volume today; specialty clinics are gaining influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston biopharmaceutical corridor anchors peptide therapeutic innovation through dense concentrations of contract research organizations and academic medical centers. United States integrated delivery networks negotiate outcome-based contracts for metabolic peptide franchises, while European manufacturers face REACH chemical registration extensions on synthetic reagents. Japanese regulators have opened accelerated review pathways for novel modalities.
United States
Specialty clinics in the Midwest and Southeast pilot oral GLP-1 formulations ahead of hospital formulary expansion. The FDA enforces tightened Current Good Manufacturing Practice standards for peptide purity and endotoxin limits. Massachusetts and North Carolina manufacturing clusters concentrate recombinant platform investment from established metabolic peptide developers.
Germany
Hospital procurement committees consolidate purchasing under centralized pharmacy and therapeutics protocols for high-cost insulin analogs. The EMA's Medical Device Regulation framework imposes additional clinical evidence requirements for novel therapeutic peptides. Baden-Württemberg and Bavaria host fermentation infrastructure serving European CDMO demand.
Japan
Academic medical centers in Tokyo and Osaka drive early adoption of peptide-drug conjugates for oncology applications. The PMDA's regenerative medicine and cell therapy framework creates fast-track pathways for novel peptide modalities. The Kanto region concentrates permeation enhancer chemistry development for oral bioavailability improvement.
Switzerland
Swissmedic maintains stringent immunogenicity assessment protocols that extend IND preparation timelines for synthetic peptides. Basel and Zurich clusters specialize in solid-phase synthesis expertise for legacy pharmaceutical hubs. The country's central bank supports biopharmaceutical R&D through favorable capital allocation frameworks.
India
Contract manufacturers in Maharashtra and Gujarat expand GMP-grade peptide production capacity for export markets. The CDSCO harmonizes with FDA purity standards while maintaining cost advantages in fermentation infrastructure. Hyderabad and Bangalore clusters develop biosimilar pathways for mature peptide franchises.
Peptide Therapeutics Market Key Industry Players
Capacity expansion dominates the current landscape as developers race to secure recombinant manufacturing infrastructure before regulatory deadlines compress. The vendor base organizes around three tiers: multinational pharmaceutical conglomerates with captive fermentation facilities, mid-scale specialists leveraging contract manufacturing partnerships, and emerging biotechnology firms pursuing platform licensing arrangements. Strategic archetypes separate metabolic peptide incumbents defending GLP-1 and insulin franchises from oncology-focused entrants commercializing peptide-drug conjugates. Portfolio diversification and geographic expansion constitute the dominant competitive moves, with players extending manufacturing footprints across United States, European, and Asian regulatory jurisdictions.
Within the multinational tier, Novo Nordisk and Eli Lilly and Company exemplify divergent approaches to manufacturing scale deployment. Novo Nordisk anchors metabolic peptide engineering through deep R&D intensity in hormone analog development. Eli Lilly and Company occupies a position emphasizing supply chain breadth for hospital and specialty clinic network penetration. Pfizer represents the geographic dominance archetype, leveraging North American and European distribution channel control to maintain commercial presence across multiple therapeutic categories.
| Leading Market Players |
|---|
| AstraZeneca |
| Novo Nordisk |
| Eli Lilly and Company |
| Pfizer |
| Novartis |
| Amgen |
| GlaxoSmithKline |
| Takeda Pharmaceuticals |
| Bristol-Myers Squibb |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up contract manufacturers now control United States and European GMP-grade peptide capacity, tightening pricing discipline through consolidated purchasing power over amino acid feedstocks and fermentation infrastructure. This ownership pattern concentrates supply-side leverage while forcing downstream developers into long-term offtake commitments that embed cost escalation clauses tied to FDA purity standard compliance.
Pricing Analysis
Distributor margins for GLP-1 and insulin analogs compress as United States integrated delivery networks negotiate direct manufacturer contracts, bypassing wholesale layers entirely. Three-tier pricing structure across premium recombinant, standard solid-phase, and economy biosimilar levels differentiates on immunogenicity certification and endotoxin grade. Pricing pressure stems from hospital pharmacy and therapeutics committees demanding outcome-based rebates for metabolic peptide franchises. Academic medical centers exhibit highest price sensitivity due to constrained formulary budgets, while specialty clinics absorb premium pricing for novel oral formulations.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital procurement committees mandate qualified backup suppliers for all GMP-grade peptide APIs, extending qualification timelines and locking capacity years ahead of commercial launch. Manufacturing concentrates in United States, Germany, and India, with Baden-Württemberg fermentation clusters and Maharashtra contract manufacturers anchoring regional supply. Raw material dependencies center on protected amino acid derivatives, recombinant expression vectors, and chromatography resins. Single-source vulnerability persists in synthetic reagent supply following REACH registration extensions. Distribution runs through captive logistics networks serving hospital pharmacies and specialty clinic chains directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peptide therapeutics market reads as a late-cycle quality story, with hospital procurement committees filtering purchasing toward GMP-certified recombinant platforms and away from legacy solid-phase synthesis. Demand is shifting toward premium specifications as FDA immunogenicity standards tighten and EMA clinical evidence requirements harden.
For Market Incumbents: Lock in recombinant manufacturing capacity through backward integration into captive fermentation infrastructure before CDMO availability tightens further. Secure multi-year amino acid supply agreements with Indian and German producers to insulate against REACH-driven reagent cost escalation. Defend GLP-1 and insulin franchise positioning by accelerating oral formulation pilots through United States specialty clinic networks, preempting biosimilar entry at hospital formularies. For New Entrants and Emerging Players: The price-point gap between premium recombinant peptides and economy solid-phase alternatives creates entry space for mid-scale developers with hybrid manufacturing platforms. Target antimicrobial peptide supply to United States academic medical centers facing multidrug-resistant pathogen protocols, where reimbursement pathways are clarifying faster than metabolic categories. Penetrate through CDMO partnerships that offer qualified GMP capacity without capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among solid-phase synthesis specialists with established regulatory dossiers but limited recombinant migration capability. Long-term viability favors platforms with demonstrated oral bioavailability improvement through cyclization or permeation enhancer chemistry. Watch for inflection in Japanese PMDA accelerated review approvals for novel peptide modalities, signaling regulatory pathway maturation that would compress development risk premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Manufacturing Scale-Up | Captive fermentation infrastructure insulates against CDMO concentration and FDA purity deadline compression. |
| Oral Formulation Development | Cyclization and permeation enhancer chemistry unlocks specialty clinic adoption ahead of hospital formulary expansion. |
| Regulatory Approval Pathway | PMDA accelerated review access reduces time-to-revenue for novel peptide-drug conjugates in oncology. |
| Backward Integration | In-house amino acid production circumvents REACH reagent registration constraints on European commercialization. |
| Hospital System Partnership | Outcome-based contracting with United States integrated delivery networks secures metabolic peptide volume commitments. |
Research Approach
Coverage spans United States, Germany, Japan, Switzerland, and India, with primary inputs from each market's regulatory and manufacturing clusters. The analysis combines primary interviews with peptide development executives, regulatory affairs leads, hospital procurement managers, and CDMO operations directors with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up prescription volume modeling and top-down revenue triangulation anchor market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from price evolution across therapy area, delivery mode, and manufacturing platform segments. The analytical framework models diabetes, oncology, cardiovascular, and neurological applications alongside injectable, oral, transdermal, and intranasal routes. CAGRs derive from patient population expansion, treatment penetration assumptions, and pricing trajectory synthesis. Forecast inputs incorporate regulatory timeline probability, manufacturing capacity buildout schedules, and hospital procurement behavioral shifts.
The model assumes a particular technology adoption path; alternative pathways for oral bioavailability enhancement would alter the outlook if permeation enhancer chemistry advances faster than cyclization techniques. Forecasts reflect assumptions around FDA-EMA regulatory harmonization, recombinant platform cost curves, and hospital formulary consolidation velocity. Deviation in immunogenicity assay standardization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Japan Pharmaceutical 3PL Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Retinal Drugs Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Targeted Therapeutics Market