
 Vessel Energy Storage Systems Market | 2026-2036
Vessel Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Vessel Energy Storage Systems Market Intelligence
Direct sales channels from specialist integrators to shipyards is tilting towards partnerships with major marine equipment suppliers. This shift broadens market access for battery manufacturers. Corvus Energy leverages its extensive track record and focus on maritime-certified lithium-ion systems. Wärtsilä competes by bundling energy storage into its complete hybrid propulsion and power management packages. Siemens Energy specializes in large-scale system integration for complex vessels like cruise ships and ferries.
Vessel energy storage systems are integrated solutions combining high-density battery modules with sophisticated battery management and thermal management systems. These systems are engineered to withstand harsh marine conditions, featuring robust enclosures and advanced fire suppression. Their primary purpose is to enable hybrid-electric propulsion, optimize engine loads for fuel efficiency, and provide silent, zero-emission power in ports. Lithium-ion batteries dominate the system type segment due to their energy density, while offshore support vessels represent a leading application category for early adoption.
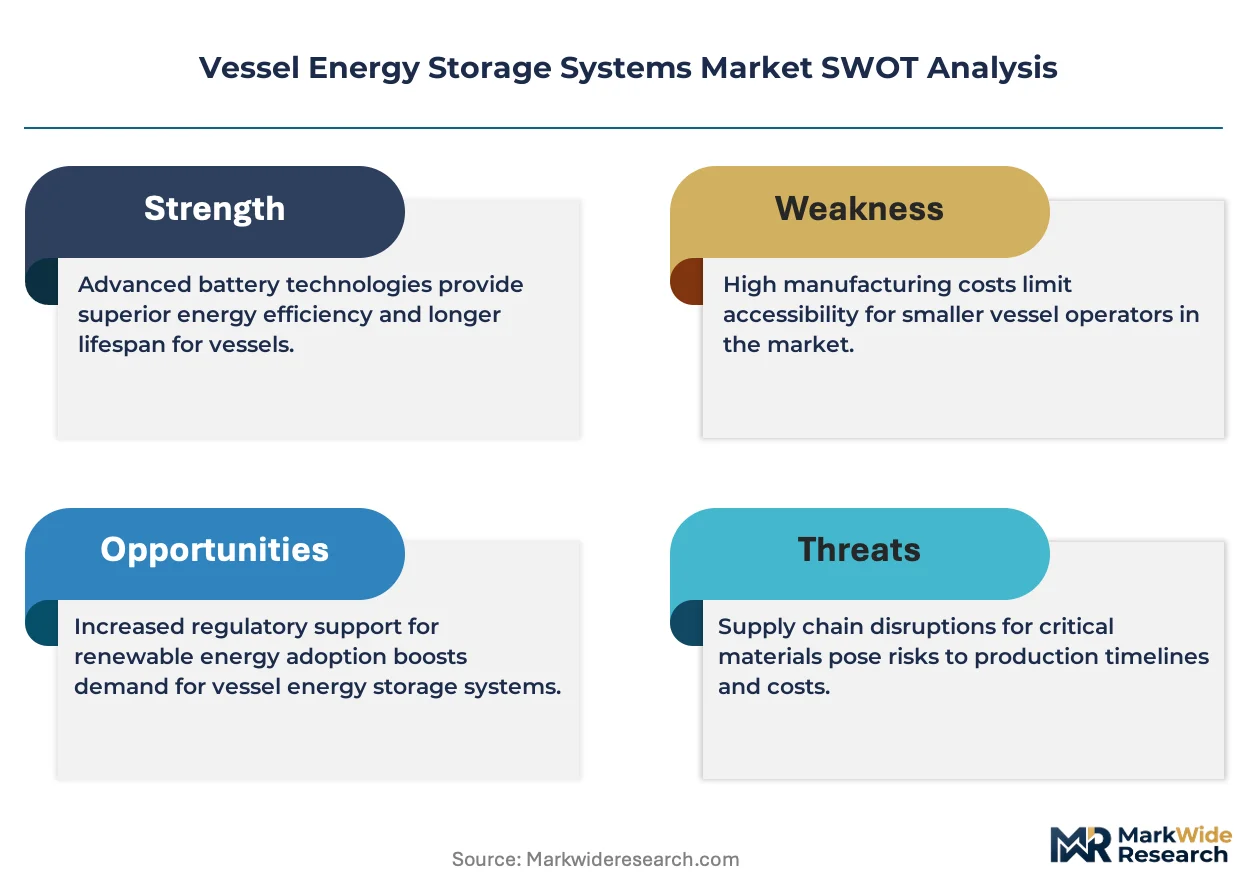
Regulatory frameworks from the International Maritime Organization (IMO), including the Energy Efficiency Existing Ship Index (EEXI), are compelling owners to invest in efficiency technologies. In parallel, European Union directives under the Green Deal create specific targets for reducing maritime emissions. Classification societies like DNV and the American Bureau of Shipping (ABS) enforce stringent safety and installation standards, shaping product design. Vessel operators must now weigh the capital expenditure of battery installation against the operational savings and compliance benefits.
Market Dynamics
The push for maritime decarbonization, driven by stringent International Maritime Organization (IMO) regulations on carbon intensity, is the central force compelling vessel owners to integrate energy storage systems for efficiency and compliance.
Growth Catalysts
- Regulatory Mandates:The IMO's Energy Efficiency Existing Ship Index (EEXI) and Carbon Intensity Indicator (CII) frameworks compel fleet-wide upgrades, making battery systems a key technology for achieving compliance and avoiding operational penalties.
- Fuel Cost Volatility:Persistent fluctuations in marine fuel prices incentivize the adoption of hybrid systems, where batteries enable engine load optimization and peak shaving, directly reducing fuel consumption and operational expenditures for vessel operators.
- Application-Specific Demand:Offshore support vessels (OSVs) require battery systems for efficient dynamic positioning operations, while ferries benefit from zero-emission port stays, creating strong, distinct demand segments that validate the technology's business case.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for marine-grade battery systems, including installation and integration, remains a primary barrier for many shipowners, especially for older vessels with shorter remaining service lives.
- Infrastructure Gaps:A lack of standardized, high-capacity shore-side charging infrastructure in many ports globally limits the potential for fully electric operations and constrains the operational profile of battery-dependent hybrid vessels.
- Supply Chain Concentration:The supply of high-density, maritime-certified lithium-ion battery cells is concentrated among a few key manufacturers, creating potential bottlenecks and price sensitivity linked to raw material costs like lithium and cobalt.
Strategic Opportunities
- Vessel Retrofitting:The vast global fleet of existing vessels presents a substantial opportunity for retrofitting energy storage systems to meet new environmental regulations, extending asset life and improving operational competitiveness without requiring newbuilds.
- Alternative Chemistries:Research and development into alternative battery chemistries, such as sodium-ion or solid-state batteries, offers a path to reduce reliance on critical minerals and potentially enhance safety and cost-effectiveness for marine applications.
- Newbuild Integration in Asia:Integrating advanced energy storage systems at the design stage in newbuilds from major shipbuilding nations like South Korea and China provides an opportunity to optimize vessel architecture for hybrid-electric propulsion.
Industry Challenges
- System Integration Complexity:Integrating battery systems with a vessel's existing power management, propulsion, and automation systems is technically complex, requiring specialized engineering expertise to ensure seamless and safe operation across different vessel types.
- Specialized Workforce Scarcity:The maritime industry faces a shortage of crew and engineers trained to operate and maintain high-voltage DC electrical systems and manage the specific safety protocols associated with large-scale battery installations.
- Evolving Safety Standards:Adhering to the rigorous and continuously updated safety standards for fire detection and suppression from classification societies like DNV and ABS requires ongoing product development and complex validation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vessel Energy Storage Systems Market |
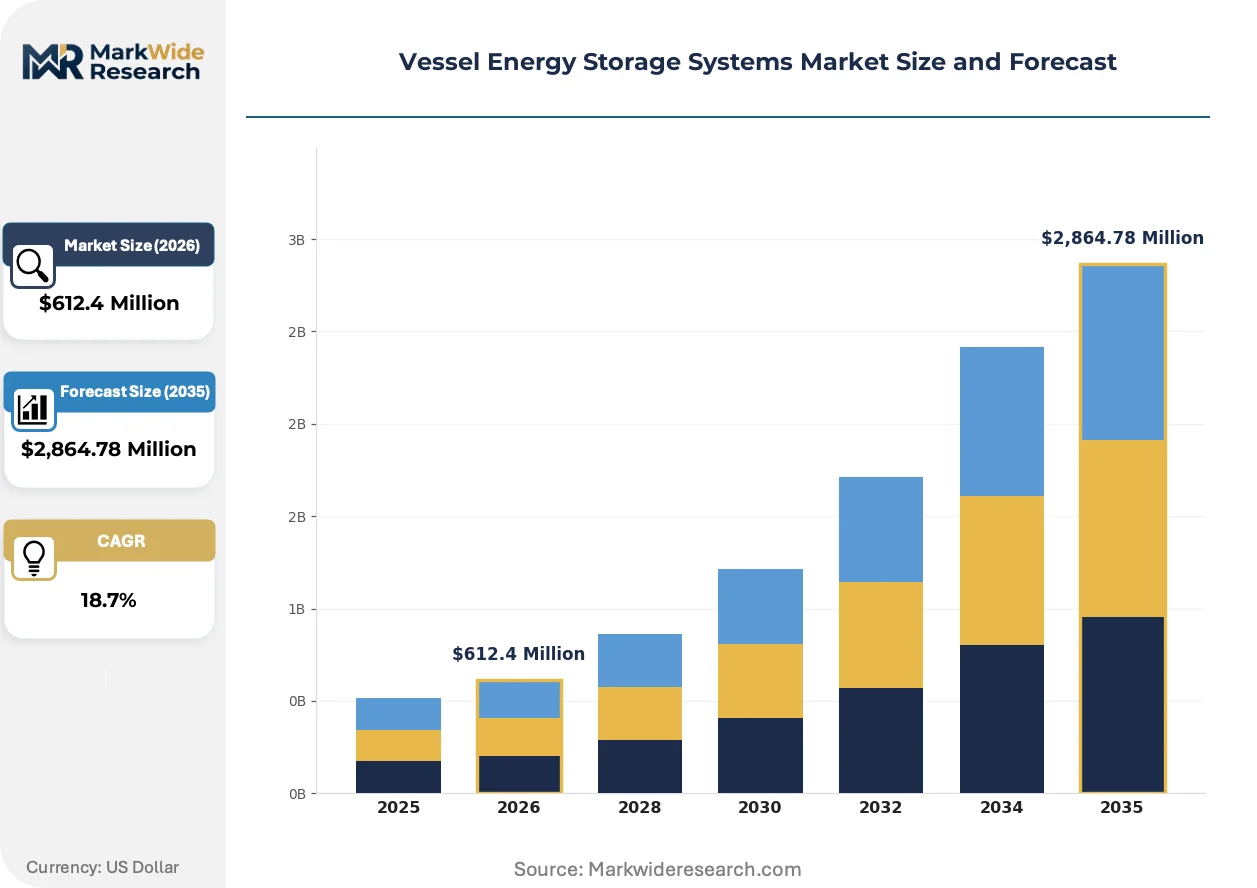
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Lithium-Ion Battery, Flow Battery, Supercapacitor, Sodium-Sulfur Battery Technology: Battery Management System, Thermal Management, Power Conversion System, Energy Recovery System Application: Passenger Vessels, Cargo Carriers, Offshore Support, Research Ships End User: Shipyards, Retrofitters, Shipping Operators, Marine Energy Providers |
| Companies Covered | Corvus Energy, Wärtsilä, ABB, Siemens Energy, Leclanché, EST-Floattech, Plan B Energy Storage, General Electric, PATHION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vessel Energy Storage Systems Market Strategic Shifts & Innovations
A fundamental shift is underway from deploying batteries as auxiliary power sources to designing them as core components of integrated vessel energy architectures. This evolution prioritizes system-level performance, fuel efficiency, and regulatory compliance over standalone component sales.
Advanced Battery Management Systems (BMS) are crucial for monitoring cell health, managing thermal loads, and optimizing charge-discharge cycles. Adoption is accelerating in complex vessels like passenger ferries and cruise ships where safety and reliability are paramount. This intelligent oversight is hybridizing the entire vessel power grid, enabling dynamic energy flow between generators, batteries, and propulsion loads.
The European Union’s 'Fit for 55' package introduces specific mandates, including the FuelEU Maritime initiative, to reduce the greenhouse gas intensity of energy used on board ships. This directly pressures operators to adopt low-carbon technologies like battery systems to avoid financial penalties. The regulation most affects vessels on frequent, short-sea routes within Europe, such as Ro-Ro and container feeder ships.
Vessel owners increasingly evaluate energy storage investments based on a total cost of ownership (TCO) framework, factoring in fuel savings, reduced maintenance, and potential carbon tax avoidance. This model favors suppliers offering turnkey hybrid systems over individual component sellers. The shift is most pronounced in regions with high operational costs and stringent environmental rules, such as Scandinavia.
Vessel Energy Storage Systems Market Segmentation
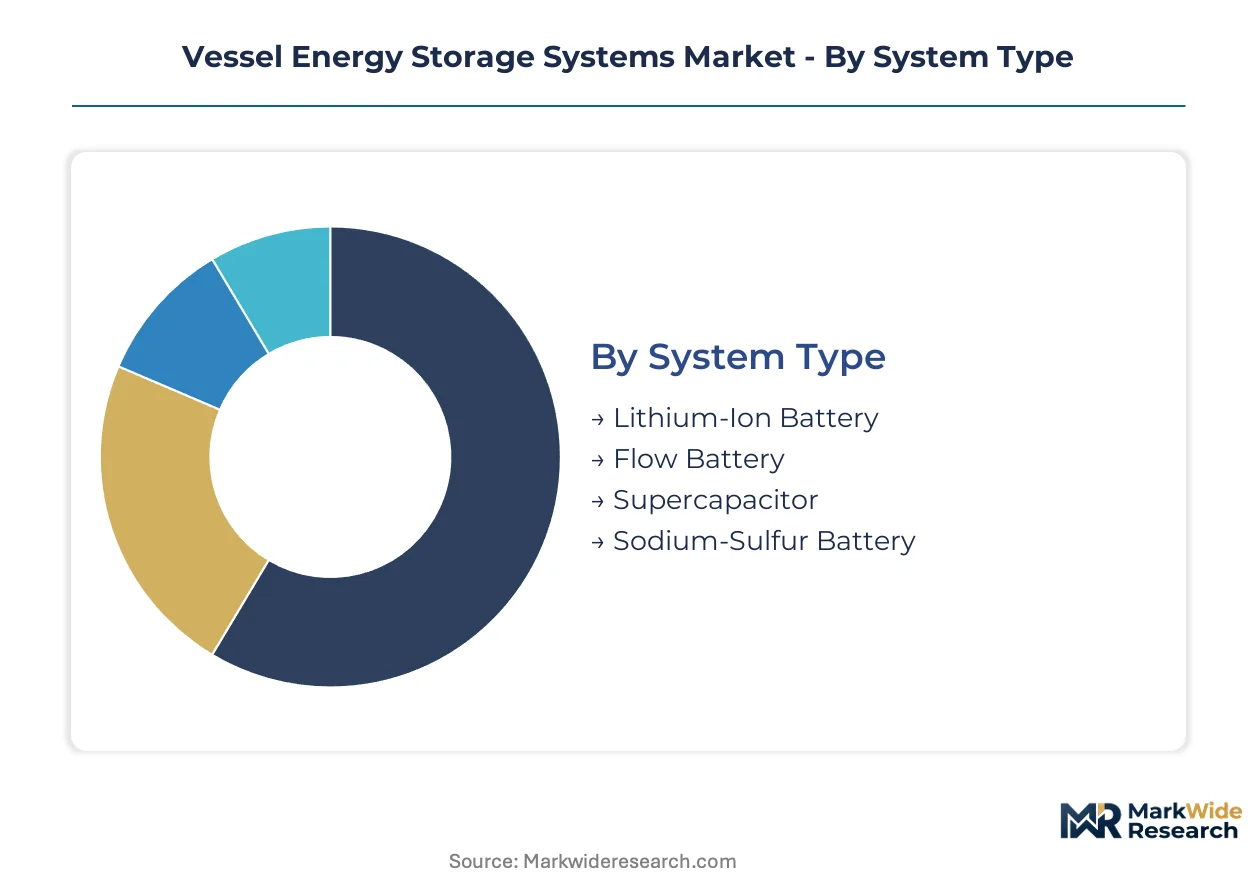
The Vessel Energy Storage Systems Market segments across various dimensions, revealing how specific technologies, applications, and end-users drive adoption. Understanding these segments helps identify key areas of investment and operational focus for decarbonization efforts. This detailed breakdown illuminates the specific needs and integration challenges within the maritime industry.
System Type:
The after-sales-service intensity for different vessel energy storage system types significantly influences their total cost of ownership and operational viability. Maintenance requirements, specialized repair protocols, and spare parts availability vary considerably across these battery chemistries.
- Lithium-Ion Battery:These systems utilize highly energy-dense lithium-ion cells, commonly NMC or LFP chemistries, integrated with advanced battery management and thermal control. Demand concentrates in offshore support vessels and ferries due to their high power requirements for dynamic positioning and zero-emission port operations.
- Flow Battery:Flow batteries separate energy storage from power delivery, using liquid electrolytes stored in external tanks, offering long cycle life and scalability. Their demand is emerging for larger vessels requiring extended discharge durations, particularly for grid-scale energy support in port or long-haul auxiliary power.
- Supercapacitor:Supercapacitors provide rapid charge and discharge capabilities with high power density, primarily for short bursts of power and regenerative braking.
- Sodium-Sulfur Battery:These high-temperature batteries offer long duration energy storage, suitable for applications needing stable, continuous power over extended periods.
Lithium-Ion Battery holds the largest share; momentum sits with Flow Battery due to its potential for enhanced safety and modularity.
Technology:
The cost tier of these integrated technologies often dictates the overall system expenditure and the complexity of installation within a vessel’s existing infrastructure. Each component plays a vital role in ensuring the safety, efficiency, and longevity of the energy storage solution.
- Battery Management System:This electronic system monitors and controls individual battery cells, ensuring optimal performance, preventing overcharge/discharge, and balancing cell voltage. Its demand is universal across all battery installations, critical for safety compliance and extending battery lifespan in demanding marine environments.
- Thermal Management:Thermal management systems regulate battery temperature through cooling or heating, preventing thermal runaway and maximizing operational efficiency. Demand is particularly high for high-power lithium-ion systems on passenger vessels and cruise ships where safety is paramount.
- Power Conversion System:These systems convert stored DC battery power to AC for vessel loads or vice versa, integrating batteries with the main power grid.
- Energy Recovery System:Energy recovery systems capture and reuse waste energy, such as heat from exhaust or braking, to improve overall vessel efficiency.
Integration complexity varies significantly across these technology components, necessitating specialized engineering expertise for seamless vessel operation.
Application:
The operational application of vessel energy storage systems directly impacts the required power density, energy capacity, and duty cycle of the battery solution. Different vessel types demand tailored approaches to maximize fuel savings and regulatory compliance.
- Passenger Vessels:This segment includes ferries, cruise ships, and passenger-only vessels, prioritizing silent operation in port, reduced emissions, and enhanced redundancy for safety. European Union directives like FuelEU Maritime compel these vessels to adopt battery systems for short-sea routes and port calls.
- Offshore Support:Offshore support vessels (OSVs) utilize battery systems for dynamic positioning, peak shaving, and spinning reserve, significantly reducing fuel consumption and engine wear. Norwegian maritime clusters are at the forefront of battery integration for these specialized vessels.
- Cargo Carriers:Cargo carriers, including container ships and bulk carriers, increasingly adopt battery systems for auxiliary power, cold ironing, and optimizing engine loads on long voyages.
- Research Ships:Research vessels leverage batteries for silent operation during sensitive acoustic surveys and to provide stable power for scientific equipment.
Efficiency gains are most pronounced in applications requiring frequent power cycling and precise load management, such as dynamic positioning.
End User:
The diverse customer types in the vessel energy storage market each possess unique procurement processes, technical requirements, and financial considerations. Understanding these distinctions is vital for suppliers to tailor product offerings and service models effectively.
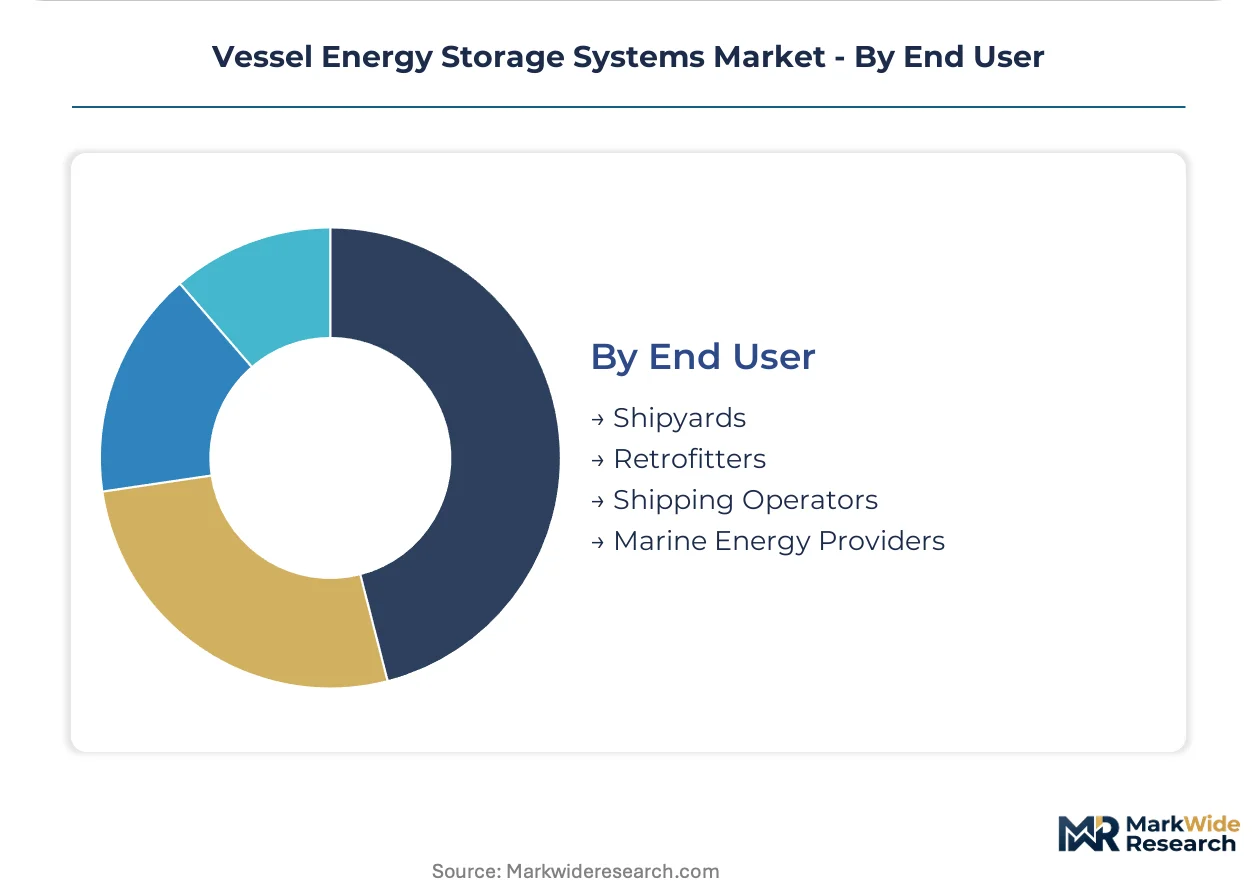
- Shipyards:Shipyards integrate energy storage systems into newbuild vessels, often collaborating with battery manufacturers during the design phase to optimize vessel architecture. South Korea's major shipyards are key demand centers for these integrated solutions.
- Shipping Operators:Shipping operators, encompassing fleet owners and managers, invest in energy storage for existing vessels (retrofits) and newbuilds to achieve fuel savings and comply with IMO carbon intensity regulations. They prioritize operational reliability and return on investment.
- Retrofitters:Retrofitters specialize in upgrading existing vessels with energy storage systems, extending asset life and enhancing environmental performance for older fleets.
- Marine Energy Providers:These providers focus on developing and supplying integrated energy solutions, including shore power and charging infrastructure, to support hybrid and electric vessels.
Each end user segment evaluates energy storage solutions based on distinct operational and financial metrics, influencing purchasing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Maritime Organization (IMO) carbon intensity regulations compel owners globally to adopt vessel energy storage systems. These mandates drive investment in efficiency technologies across diverse maritime nations. Market growth is concentrated in key shipbuilding and maritime technology hubs.
South Korea
South Korean shipyards drive demand for integrated energy storage systems in newbuild vessels, particularly for cargo and passenger ships. The country's strong shipbuilding industry aligns with IMO regulations, compelling enhanced vessel efficiency. Major shipyards in Ulsan and Geoje actively integrate these advanced solutions into their designs.
Norway
Norwegian maritime operators prioritize battery systems for offshore support vessels, enhancing dynamic positioning capabilities and fuel efficiency. DNV classification society standards ensure rigorous safety and operational compliance for these installations. Maritime technology clusters around Bergen and Ålesund lead innovation in hybrid vessel design.
Germany
German passenger vessel operators seek energy storage for silent port operations and reduced emissions on short-sea routes. European Union directives, including FuelEU Maritime, incentivize investment in low-carbon technologies. Northern German shipyards in Rostock and Papenburg specialize in integrating these systems into ferries and cruise ships.
China
China's vast shipbuilding capacity fuels demand for energy storage in cargo carriers and newbuild projects. The nation's dual carbon goals and IMO regulations drive the adoption of more efficient propulsion systems. Major shipbuilding centers in the Yangtze River Delta focus on integrating hybrid-electric solutions.
Denmark
Danish shipping companies implement battery solutions for ferries and short-sea routes to meet strict environmental targets. The FuelEU Maritime initiative directly pressures operators to reduce greenhouse gas intensity. Maritime technology firms in Copenhagen and Esbjerg develop advanced energy management systems.
Vessel Energy Storage Systems Market Key Industry Players
Specialist integrators and major marine equipment suppliers split the vessel energy storage market, creating a dynamic competitive landscape. This market structure reflects a push for integrated system solutions alongside component sales, broadening market access for battery manufacturers. Strategic archetypes include dedicated battery system providers focused on maritime certification and diversified industrial conglomerates offering complete hybrid packages. Companies pursue strategic partnerships, portfolio diversification, and advanced system integration capabilities to broaden market access and meet evolving regulatory demands.
Specialists in integrated energy solutions, such as Corvus Energy, exemplify the focus on maritime-certified lithium-ion systems, leveraging extensive track record in the sector. Wärtsilä, a Finnish technology group, occupies a position offering complete hybrid propulsion and power management packages, bundling its energy storage offerings. Siemens Energy, a German industrial powerhouse, anchors the large-scale system integration segment for complex vessels like cruise ships and ferries, emphasizing bespoke engineering. These players navigate a market where technical expertise and adherence to stringent marine safety standards are paramount.
| Leading Market Players |
|---|
| Corvus Energy |
| Wärtsilä |
| ABB |
| Siemens Energy |
| Leclanché |
| EST-Floattech |
| Plan B Energy Storage |
| General Electric |
| PATHION |
| Others |
Cost & Logistics Intelligence
South Korean shipyard undercapacity in specialized vessel segments drives integrators' pricing posture, influencing both component procurement and system integration costs. This utilization dynamic directly impacts supplier negotiations and overall system affordability for vessel owners.
Pricing Analysis
Geographic price spreads for vessel energy storage systems vary significantly due to regional regulatory mandates and labor costs. The dominant pricing model remains project-based, reflecting the bespoke nature of marine installations and integration complexity. Price differentiation stems from the specific certification level required by classification societies like DNV and ABS, alongside the degree of system customization for vessel types. Pricing pressure intensifies from shipowners evaluating total cost of ownership against high upfront capital expenditure. Shipping operators, focused on long-term operational savings, exhibit moderate price sensitivity, while retrofitters often seek more cost-effective solutions for older vessels.
Supply Chain Analysis
Upstream feedstock for high-density lithium-ion cells, primarily lithium and cobalt, originates predominantly from Australia, Chile, and the Democratic Republic of Congo, with processing capacity concentrated in China. The supply chain for vessel energy storage systems depends heavily on these critical raw materials and their subsequent manufacturing into battery cells in South Korea and China. Commodity price volatility for key materials represents a significant supply chain risk, impacting cell manufacturers' costs. Distribution runs through specialist integrators directly to shipyards for newbuilds and through partnerships with major marine equipment suppliers for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a platform-economics inflection, driven by the interoperability demands between energy storage, propulsion, and power management systems within a vessel's integrated architecture.
For Market Incumbents: Insulate core market share by deepening strategic partnerships with major shipyards and marine equipment suppliers. Invest in advanced thermal management and fire suppression R&D to address evolving safety standards and mitigate risks from alternative chemistries. Expand global service networks to support the growing fleet of hybrid vessels, countering emerging entrants focused on regional niches. The threat of high capital expenditure for shipowners necessitates comprehensive financing solutions.
For New Entrants and Emerging Players: Establish a beachhead in the vessel retrofitting segment, leveraging modular battery solutions and specialized integration expertise. The market for smaller ferries and regional cargo carriers presents a penetrable segment due to less complex integration requirements. A specific go-to-market angle should emphasize total cost of ownership benefits, highlighting fuel savings and regulatory compliance for existing fleets rather than solely upfront system cost.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialist integrators offering comprehensive after-sales service and long-term maintenance contracts. Long-term viability hinges on the accelerating pace of maritime decarbonization and the increasing stringency of IMO regulations. Acquisition targets should include companies with strong intellectual property in battery management systems or established certification pathways with DNV and ABS. Standardized shore-side charging infrastructure development across major ports is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Global Service Network | Incumbents like Wärtsilä reinforce customer loyalty and support complex hybrid systems across diverse geographies. |
| Invest in Alternative Battery Chemistries | Corvus Energy diversifies its product portfolio, reducing reliance on critical minerals and enhancing safety profiles. |
| Develop Modular Retrofit Solutions | New entrants target the vast existing vessel fleet, lowering entry barriers for shipowners seeking compliance. |
| Secure Long-term Raw Material Contracts | Battery manufacturers mitigate commodity price volatility, ensuring stable production costs for marine-grade cells. |
| Form Strategic Partnerships with Shipyards | Siemens Energy ensures early integration of large-scale systems into newbuild designs, optimizing vessel architecture. |
Research Approach
Initial hypotheses were tested against primary input from shipyard engineers, vessel operators, classification society experts, and battery manufacturers, then refined. This involved combining insights from targeted interviews with secondary validation from sources such as IMO regulations, EU Green Deal directives, DNV and ABS standards, and leading company reports. The approach ensured comprehensive bottom-up and top-down triangulation of market dynamics.
The analytical framework balanced demand-side drivers with supply-side capabilities across the analysis window. Segmentation dimensions modeled included system type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market drivers, integrating industry-specific inputs like newbuild vessel orders and marine fuel price forecasts throughout the forecast period.
Macroeconomic conditions sit as an overlay; deviation in global trade volumes or marine fuel prices would shift the trajectory of vessel energy storage system adoption. Forecasts reflect assumptions documented through extensive research and validation. Cross-checking against external maritime industry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Ultracapacitors Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Water Electrolysis Machine Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Power Bank Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
South America Energy Storage Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Energy Storage Battery for Microgrid Market