
 Hydrogen Liquefaction System Market | 2026-2036
Hydrogen Liquefaction System Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Liquefaction System Market Insights
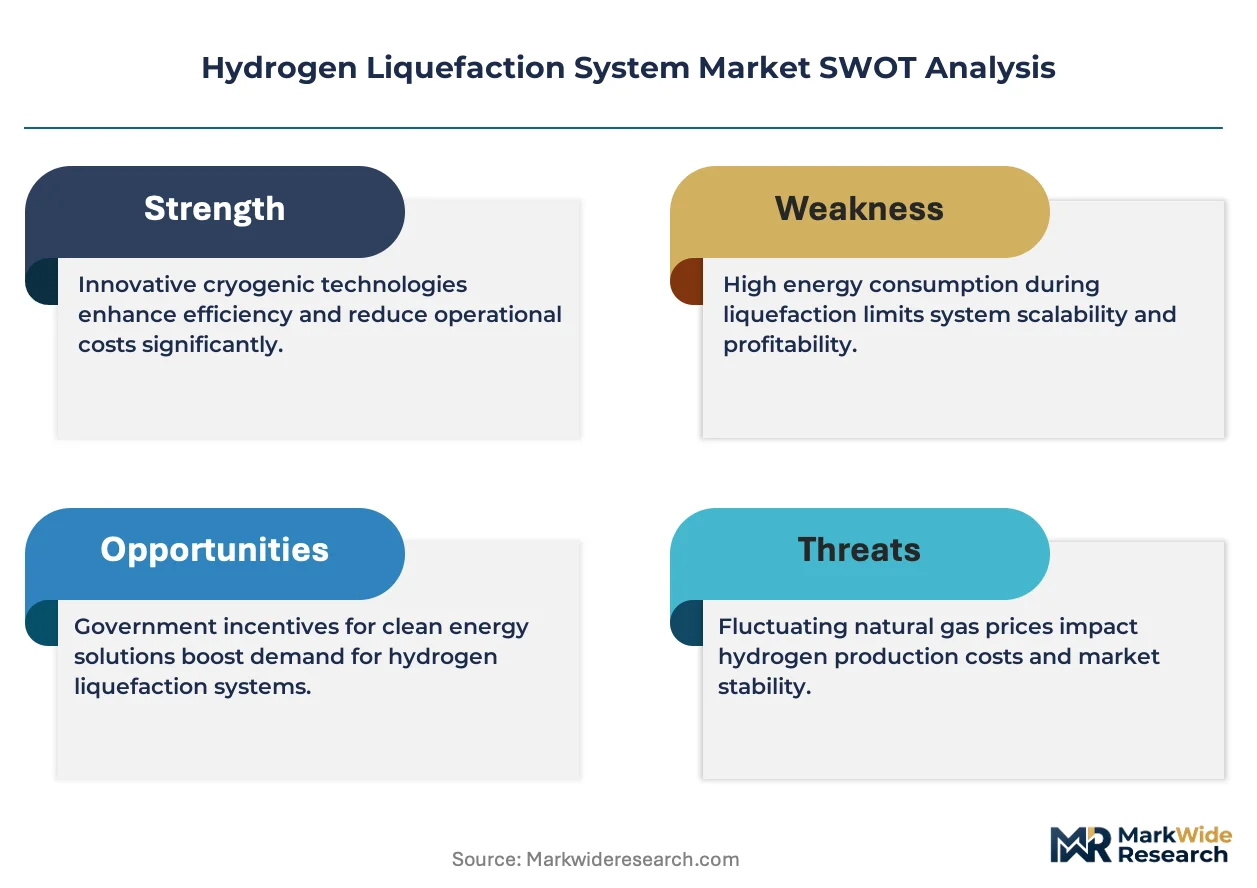
Capital-intensity divergence between cryogenic equipment specialists and diversified industrial gas conglomerates is rotating competitive dynamics across the hydrogen liquefaction system value chain. Linde leverages its integrated hydrogen production and liquefaction footprint to anchor large-scale project economics in Europe and the Gulf Coast. Air Products and Chemicals, Inc. sustains technology leadership through proprietary reverse-Brayton cycle architectures deployed at export-scale facilities. GenH2 specializes in modular, containerized liquefaction units that occupy the distributed hydrogen infrastructure niche below 10 tonnes per day.
Hydrogen liquefaction systems cool gaseous hydrogen below its critical temperature of 33.2 Kelvin and compress it to 1.3 bar for density-efficient storage and transport, primarily serving fuel cell mobility, industrial ammonia synthesis, and emerging aviation propulsion applications. Cryogenic technology dominates installed base capacity due to proven ortho-para hydrogen conversion efficiency, though hybrid systems integrating Joule-Thomson pre-cooling with reverse-Brayton expansion are gaining traction where energy recovery and turndown flexibility command premium positioning. Component-level margin pools concentrate in heat exchanger and compressor assemblies where proprietary alloys and seal technologies create supplier stickiness.
The EU Green Deal and delegated acts on renewable fuels of non-biological origin, alongside the EPA's evolving hydrogen production tax credit guidance under the IRA, are reshaping equipment certification requirements and project financeability across jurisdictions. Japan's METI hydrogen supply chain targets and South Korea's MFDS pressure equipment codes further fragment compliance burdens for system integrators serving multiple export markets. Stakeholders must monitor how regulatory convergence or divergence on carbon intensity thresholds affects equipment specification standardization and aftermarket service attach rates.
Market Dynamics
Energy recovery architectures and modular system footprints are fragmenting the historical dominance of centralized mega-liquefaction facilities, redistributing capital deployment toward distributed hydrogen hubs serving regional fuel cell ecosystems.
Growth Catalysts
- EU Green Deal delegated acts:Binding carbon intensity thresholds for renewable fuels of non-biological origin are mandating equipment upgrades across European hydrogen import terminals, accelerating replacement cycles for legacy liquefaction assets.
- Aviation propulsion:Turbofan manufacturers and airframe integrators are qualifying liquid hydrogen storage systems for narrow-body aircraft prototypes, creating new demand for aviation-grade liquefaction purity specifications.
- Hamburg-Ruhr corridor:Industrial cluster aggregation around German hydrogen import terminals and ammonia synthesis facilities is concentrating offtake agreements for large-scale liquefaction capacity.
Market Restraints
- Helium supply concentration:Cryogenic cooling circuits depend on helium as a process fluid, with extraction concentrated in Qatar and the United States, exposing liquefaction project timelines to geopolitical supply disruptions.
- Ortho-para conversion efficiency ceiling:Proven catalyst technologies face thermodynamic limits that constrain unit energy consumption reductions, compressing margin improvement potential for equipment operators.
- IRA hydrogen production tax credit uncertainty:Evolving EPA guidance on carbon intensity accounting methods is freezing final investment decisions for Gulf Coast export projects awaiting certification clarity.
Strategic Opportunities
- Containerized modular units:Sub-10 tonne per day liquefaction systems can penetrate distributed hydrogen infrastructure gaps at ports and industrial parks where pipeline hydrogen remains unavailable.
- South Korea MFDS alignment:Pressure equipment code harmonization with European standards is opening certification pathways for European system integrators to supply Korean hydrogen refueling networks.
- Joule-Thomson pre-cooling convergence:Hybrid architectures combining Brayton expansion with Joule-Thomson stages enable energy recovery and turndown flexibility for variable renewable hydrogen feedstocks.
Industry Challenges
- Cryogenic welding certification:Qualified technicians for 304L and 316L stainless steel fabrication at sub-40 Kelvin operating conditions remain scarce, extending project commissioning timelines.
- Legacy ammonia plant integration:Brownfield hydrogen liquefaction retrofits must interface with existing synthesis gas handling infrastructure, complicating process safety reviews and mechanical integrity assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Liquefaction System Market |
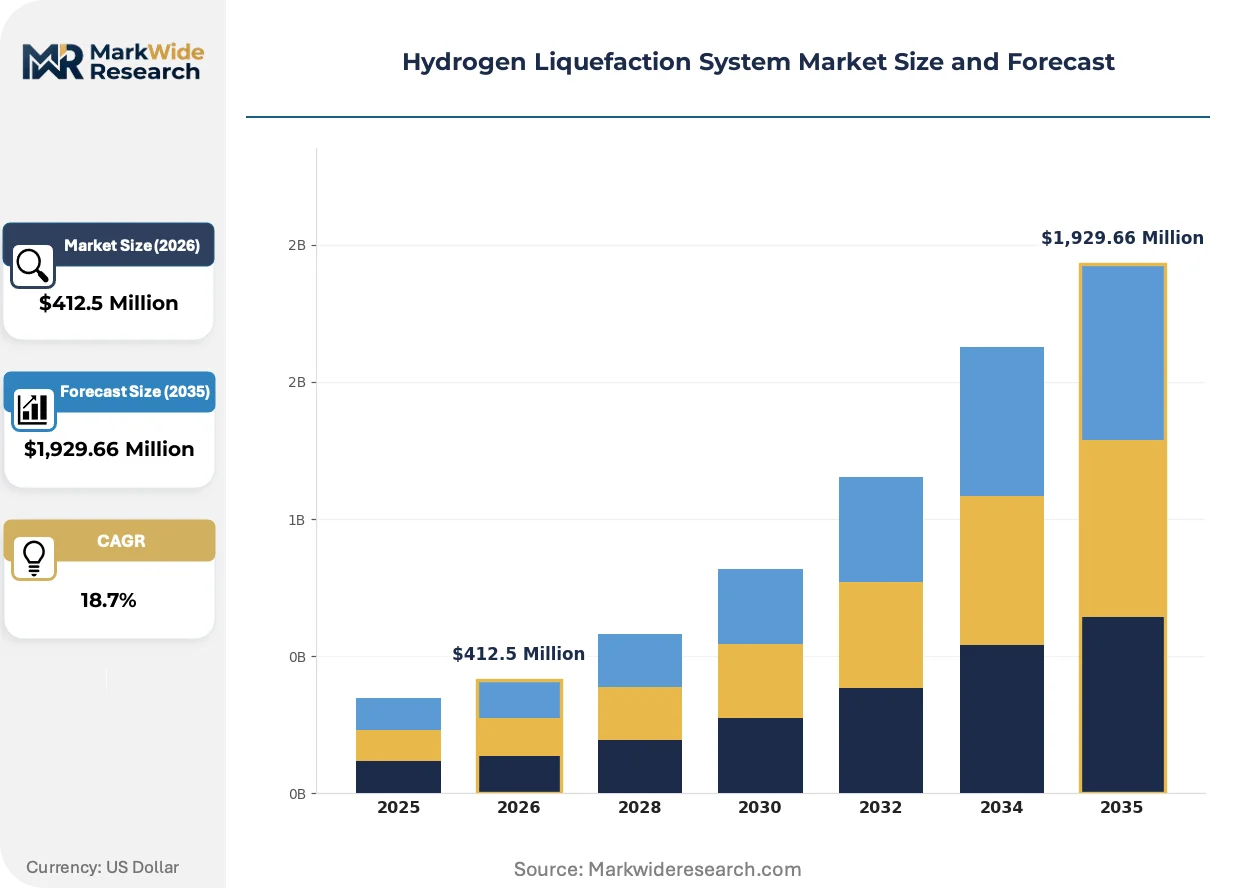
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cryogenic, Reverse-Brayton, Joule-Thomson, Hybrid Systems Component: Heat Exchanger, Compressor, Storage Tank, Control System Application: Fuel Cell, Industrial Uses, Transportation, Power Generation End User: Energy Sector, Automotive, Aerospace, Research Institutions |
| Companies Covered | Linde, Air Liquide, Air Products and Chemicals, Inc., Chart Industries, Kawasaki Heavy Industries, Iwatani Corporation, Honeywell UOP, MAN Energy Solutions, GenH2, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Liquefaction System Market Trends and Innovations
Reverse-Brayton cycle optimization and ortho-para conversion catalyst advancement are redefining efficiency benchmarks, while regulatory carbon accounting is hardening equipment specification requirements across export markets.
Magnetic bearing turboexpanders are fragmenting the compressor landscape in hydrogen liquefaction trains. These oil-free rotating assemblies eliminate contamination risks in cryogenic process streams. Fuel cell vehicle fleet operators in Germany and Japan are specifying magnetic bearing systems for refueling station liquefiers. The technology is fragmenting supplier ecosystems by displacing conventional lubricated centrifugal compressors in applications below 30 tonnes per day.
REACH and F-Gas Regulation amendments are tightening refrigerant containment standards for hydrogen pre-cooling circuits. Equipment manufacturers must now certify leak-tightness across extended temperature cycling protocols. Heat exchanger fabricators serving European projects are responding by adopting vacuum-brazed aluminum core designs with improved fatigue resistance for pressure-boundary joints.
Service contract unbundling is separating aftermarket maintenance from original equipment procurement in buyer decision frameworks. Industrial gas offtakers in the Netherlands and Belgium are negotiating standalone technical service agreements with third-party cryogenic specialists. This pattern is most visible in port hydrogen hub developments where project finance structures favor operational expenditure transparency over bundled capital-plus-service packages.
Hydrogen Liquefaction System Market Segmentation
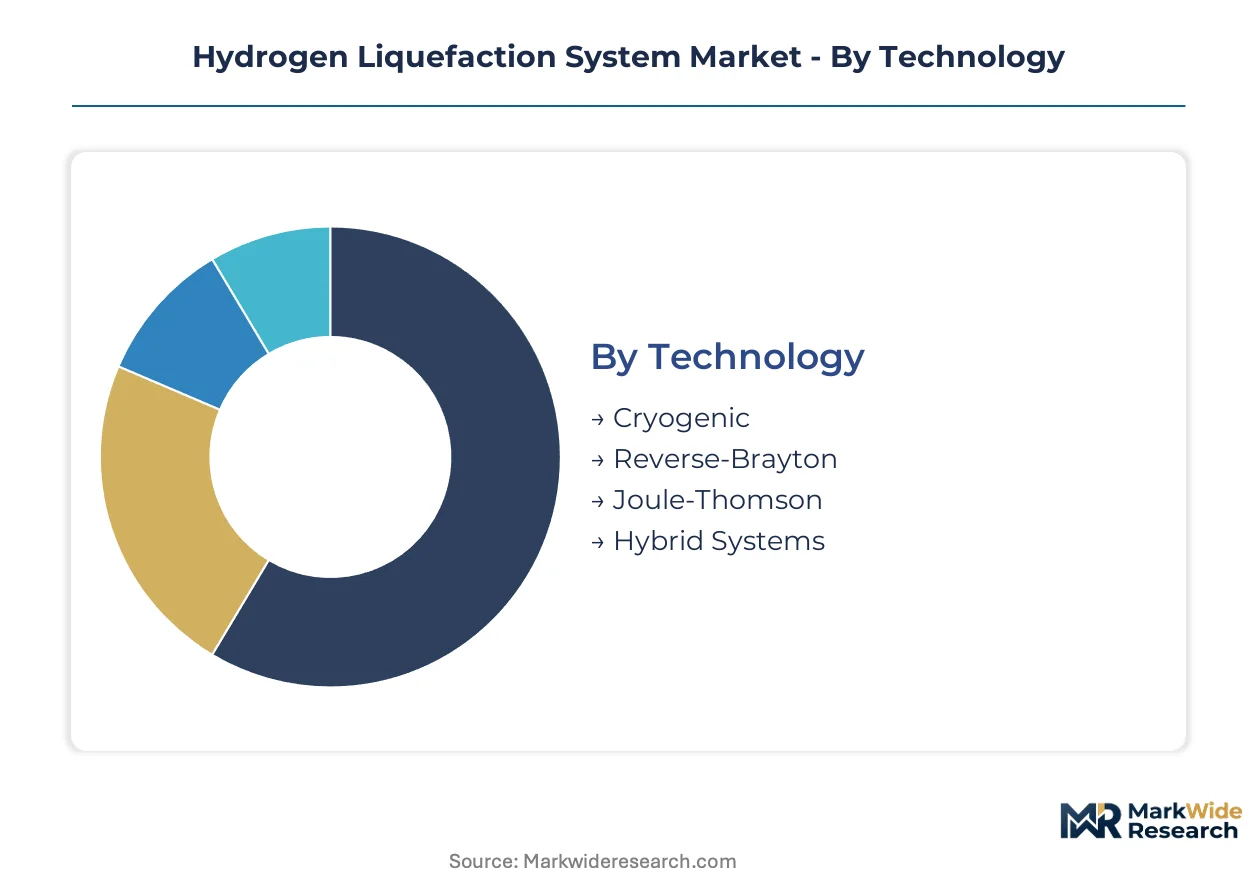
Hydrogen liquefaction system segmentation reveals how technology choices, component specifications, and application requirements fragment capital deployment and margin capture across the value chain. Equipment buyers prioritize different performance attributes depending on whether they serve export terminals, fuel cell fleets, or industrial ammonia synthesis.
Technology:
Margin pools concentrate in proprietary cycle architectures where energy recovery and turndown flexibility command premium positioning over commodity cryogenic units.
- Cryogenic:Proven ortho-para hydrogen conversion efficiency anchors installed base capacity. Demand clusters around German hydrogen import terminals where legacy asset replacement cycles accelerate under EU Green Deal carbon intensity mandates.
- Reverse-Brayton:Proprietary expansion turbine designs enable superior energy recovery at export-scale facilities. Air Products deploys this architecture at Gulf Coast liquefaction trains where IRA hydrogen production tax credit eligibility hinges on carbon accounting certification clarity.
- Joule-Thomson:Pre-cooling stages suit distributed hydrogen hubs with variable renewable feedstocks.
- Hybrid Systems:Brayton expansion integrated with Joule-Thomson stages balances efficiency and operational flexibility for mid-scale deployments.
The dominant share belongs to Cryogenic, while Hybrid Systems are closing the gap fastest.
Component:
Supplier stickiness varies sharply across the bill of materials, with proprietary alloys and seal technologies creating defensible positions in high-pressure boundary assemblies.
- Heat Exchanger:Vacuum-brazed aluminum core designs with fatigue-resistant pressure-boundary joints respond to REACH and F-Gas Regulation leak-tightness protocols. European fabricators capture premium pricing at Hamburg-Ruhr corridor hydrogen hubs.
- Compressor:Magnetic bearing turboexpanders displace lubricated centrifugal units below 30 tonnes per day. German and Japanese fuel cell fleet operators specify oil-free rotating assemblies to eliminate cryogenic contamination risks.
- Storage Tank:Double-walled vacuum insulation systems face qualified welder scarcity for 304L and 316L stainless fabrication at sub-40 Kelvin conditions.
- Control System:Process automation packages integrate ortho-para conversion monitoring with predictive maintenance algorithms.
Heat Exchanger assemblies command the deepest margin pools, though Compressor technology is climbing the fastest as magnetic bearing adoption accelerates.
Application:
End-use specifications diverge on purity benchmarks, with aviation propulsion and fuel cell mobility imposing stricter liquefaction standards than industrial ammonia synthesis.
- Fuel Cell:Refueling station liquefiers demand contamination-free compression for proton exchange membrane durability. Japanese METI hydrogen supply chain targets and South Korean MFDS pressure equipment codes fragment certification requirements for system integrators.
- Industrial Uses:Ammonia synthesis facilities retrofit brownfield hydrogen liquefaction into existing synthesis gas handling infrastructure, complicating process safety reviews.
- Transportation:Heavy freight operators scale liquid hydrogen offtake for fuel cell truck fleets across German industrial clusters.
- Power Generation:Grid-scale hydrogen storage applications remain nascent, awaiting turbine combustion technology maturation.
Fuel Cell applications anchor current procurement volume, while Transportation is expanding most quickly as fleet electrification timelines compress.
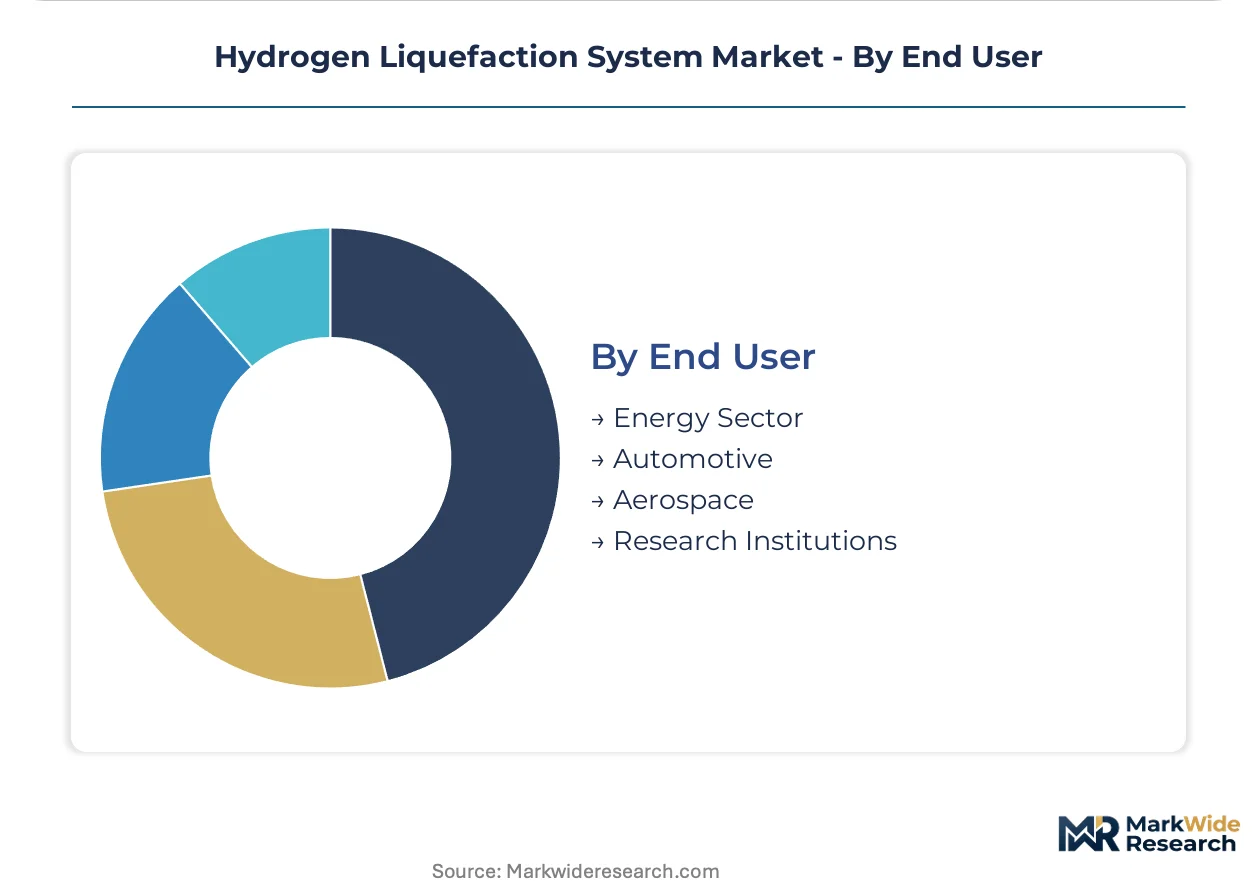
End User:
Customer procurement sophistication ranges from integrated industrial gas conglomerates negotiating unbundled service contracts to research institutions requiring bespoke pilot-scale configurations.
- Energy Sector:Hydrogen import terminal operators in the Netherlands and Belgium negotiate standalone technical service agreements with third-party cryogenic specialists, favoring operational expenditure transparency over bundled capital-plus-service packages.
- Automotive:Fuel cell vehicle manufacturers specify magnetic bearing systems for refueling infrastructure, fragmenting supplier ecosystems away from conventional lubricated compressors.
- Aerospace:Turbofan manufacturers qualify liquid hydrogen storage systems for narrow-body aircraft prototypes, creating new demand for aviation-grade purity specifications.
- Research Institutions:National laboratories and university consortia drive sub-10 tonne per day modular liquefier demand for materials science and propulsion research.
Energy Sector offtakers dominate capital deployment, though Aerospace is gaining share fastest as aviation decarbonization roadmaps harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and South Korea exhibit the lowest price elasticity, absorbing premium equipment costs under strict regulatory mandates, while Gulf Coast project developers in the United States freeze procurement pending IRA certification clarity, displaying acute sensitivity to policy uncertainty.
Germany
Heavy freight operators scaling liquid hydrogen offtake for fuel cell truck fleets drive equipment procurement volumes. The EU Green Deal delegated acts on renewable fuels of non-biological origin mandate carbon intensity thresholds that accelerate replacement cycles for legacy liquefaction assets. The Hamburg-Ruhr corridor concentrates hydrogen import terminals and ammonia synthesis facilities where offtake agreements aggregate for large-scale capacity.
United States
Gulf Coast export projects await final investment decisions as developers seek clarity on EPA hydrogen production tax credit eligibility under evolving IRA guidance. The EPA's carbon intensity accounting methods remain unresolved, freezing procurement timelines for mega-liquefaction trains. Texas and Louisiana industrial clusters host the bulk of planned capacity, though financing structures favor operational expenditure transparency over bundled capital-plus-service packages.
Japan
METI hydrogen supply chain targets fragment compliance burdens for system integrators serving export markets with divergent certification requirements. The national hydrogen roadmap concentrates demand around fuel cell mobility and emerging aviation propulsion applications. Tokyo and Osaka metropolitan areas anchor refueling infrastructure deployment where contamination-free compression specifications command premium positioning.
South Korea
MFDS pressure equipment codes create certification pathways for European system integrators supplying domestic hydrogen refueling networks. The national hydrogen economy roadmap drives procurement of magnetic bearing turboexpanders for oil-free rotating assemblies. Busan-Ulsan industrial clusters concentrate demand from fuel cell vehicle fleet operators specifying aviation-grade purity benchmarks.
Netherlands
Port hydrogen hub developments in Rotterdam and Amsterdam redistribute capital deployment toward distributed infrastructure serving regional fuel cell ecosystems. Service contract unbundling separates aftermarket maintenance from original equipment procurement in buyer decision frameworks. REACH and F-Gas Regulation amendments tighten refrigerant containment standards, vacuum-brazed aluminum heat exchanger designs capture premium pricing.
Hydrogen Liquefaction System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence rotating competitive dynamics across the value chain. The upper tier commands project economics through captive hydrogen production and liquefaction footprints, while mid-scale specialists penetrate distributed infrastructure gaps below ten tonnes per day. Three archetypes define positioning: integrated industrial gas conglomerates, cryogenic equipment specialists, and modular containerized unit fabricators. Capacity expansion and technology licensing represent the dominant competitive moves, with players securing ortho-para conversion catalyst supply chains and magnetic bearing turboexpander manufacturing partnerships.
Within the integrated conglomerate tier, Linde and Air Products and Chemicals, Inc. exemplify scale-driven positioning through proprietary cycle architectures and export-scale facility deployment. GenH2 occupies the modular specialist archetype, representing containerized liquefaction approaches for sub-ten tonne per day distributed hydrogen infrastructure where pipeline supply remains unavailable. Air Liquide anchors European market presence through cryogenic technology leadership and hydrogen import terminal project participation.
| Leading Market Players |
|---|
| Linde |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Chart Industries |
| Kawasaki Heavy Industries |
| Iwatani Corporation |
| Honeywell UOP |
| MAN Energy Solutions |
| GenH2 |
| Others |
Pricing and Supply Chain Analysis
Magnetic bearing turboexpanders displacing conventional lubricated compressors below 30 tonnes per day simultaneously concentrate procurement leverage among German and Japanese fuel cell fleet operators while compressing margin pools for legacy compressor fabricators unable to certify oil-free rotating assemblies.
Pricing Analysis
Aftermarket technical service agreements now drive lifetime value capture as Dutch and Belgian hydrogen import terminal operators unbundle maintenance from capital procurement. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and magnetic bearing specification, with aviation-grade purity benchmarks commanding substantial premia. Cost compression in standard-tier cryogenic units is intensifying because qualified welders for 304L and 316L stainless fabrication at sub-40 Kelvin conditions remain scarce. Research institutions and pilot-scale operators exhibit highest price sensitivity, while German heavy freight operators absorbing EU Green Deal mandates display lowest elasticity.
Supply Chain Analysis
Qatar and the United States anchor helium extraction for cryogenic cooling circuits, with Germany and Japan fabricating magnetic bearing turboexpanders and vacuum-brazed aluminum heat exchanger cores. The supply chain draws from proprietary ortho-para conversion catalysts, rare-earth magnetic materials, and fatigue-resistant brazing alloys. Single-source vulnerability concentrates in helium process fluid supply, exposing liquefaction project timelines to geopolitical disruption. Distribution runs through EPC contractors integrating liquefaction trains at hydrogen import terminals and regional fuel cell hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen liquefaction system markets constitute a defensive-moat opportunity anchored in regulatory entrenchment, where EU Green Deal delegated acts and MFDS pressure equipment codes create certification barriers that incumbent cryogenic specialists exploit against unqualified entrants.
For Market Incumbents: Secure captive supply chains for ortho-para conversion catalysts and magnetic bearing turboexpander manufacturing partnerships before emerging modular specialists achieve scale. Capacity addition in the Hamburg-Ruhr corridor defends positioning against Air Products' Gulf Coast export-scale deployments. Certification investment in REACH and F-Gas Regulation leak-tightness protocols maintains European pricing power. For New Entrants and Emerging Players: Anchor in containerized sub-10 tonne per day distributed hydrogen infrastructure gaps at ports and industrial parks where pipeline supply remains unavailable. South Korean MFDS alignment opens the most penetrable geography for European system integrators seeking certification pathway arbitrage. Technology licensing from established cryogenic equipment specialists accelerates time-to-revenue versus organic R&D. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular liquefaction specialists possessing containerized unit portfolios but lacking integrated hydrogen production footprints. Long-term viability hinges on regulatory convergence toward aviation-grade purity specifications and carbon intensity accounting standardization. Monitor EPA hydrogen production tax credit guidance resolution as inflection indicator for Gulf Coast mega-project financing viability.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Turboexpander Manufacturing Partnership | Eliminates oil contamination risks for German fuel cell fleet operators specifying contamination-free compression. |
| Orth-para Conversion Catalyst Supply Chain Security | Captures margin pools in heat exchanger assemblies where thermodynamic efficiency limits constrain competitor entry. |
| MFDS Pressure Equipment Code Harmonization | Opens certification pathways for European system integrators supplying Busan-Ulsan hydrogen refueling networks. |
| Containerized Modular Unit Portfolio Expansion | Penetrates distributed infrastructure gaps below 10 tonnes per day where GenH2 currently occupies niche positioning. |
| Aviation-Grade Liquefaction Purity Certification | Qualifies liquid hydrogen storage systems for turbofan manufacturers prototyping narrow-body aircraft propulsion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA hydrogen infrastructure databases, IEA technology roadmaps, SEC 10-K filings from industrial gas conglomerates, and EU delegated act regulatory texts. Interviews with cryogenic equipment procurement managers at hydrogen import terminals, EPC contractors integrating liquefaction trains, aftermarket service directors at industrial gas operators, and ortho-para conversion catalyst suppliers combined with customs trade data and FERC project filings. Bottom-up bill-of-materials costing and top-down capacity aggregation triangulate market sizing across the analysis window.
Segmentation dimensions modeled span liquefaction technology architecture, component category, application purity specification, and end-user procurement sophistication. CAGRs derive from installed base replacement cycle analysis, carbon intensity mandate compliance timelines, and fleet electrification trajectory assumptions. Forecast inputs incorporate IRA hydrogen production tax credit eligibility probability weighting and aviation propulsion qualification schedule uncertainty.
Material uncertainties — EPA carbon intensity accounting method revisions, helium supply disruption events, and ortho-para conversion catalyst technology breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions documented in regulatory scenario weighting and project finance structure prevalence. Recalibration cycles align with material shifts in delegated act implementation timelines and aviation-grade certification standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Energy Storage Software Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Supercapacitor Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Long-Duration Energy Storage Market