
 Flywheel Energy Storage (FES) Systems Market | 2026-2036
Flywheel Energy Storage (FES) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Flywheel Energy Storage (FES) Systems Market Insights
Market Context
The performance gap between premium magnetic-bearing systems and commodity steel flywheel units is expanding as end users sort into uptime-critical and cost-sensitive camps. Beacon Power, LLC dominates grid-frequency regulation installations across North America. Calnetix Technologies leverages advanced magnetic bearing expertise to sustain premium positioning in aerospace and medical backup segments. Stornetic GmbH competes on modular containerized architectures for industrial microgrids.
Technical Definition and Segments
Flywheel energy storage systems are electromechanical devices that store kinetic energy in a rotating mass, typically achieving 85-90% round-trip efficiency at spin rates exceeding 10,000 RPM, and discharge within seconds to minutes for grid stabilization or uninterruptible power. Carbon fiber flywheels command the highest specific energy density and attract aerospace and premium utility applications, while steel flywheels occupy cost-driven backup power roles in commercial buildings. Magnetic bearing technology leads R&D investment flows due to friction elimination and maintenance reduction, whereas containerized installation formats are capturing share in remote renewable integration projects where rapid deployment outweighs permanent infrastructure economics.
Regulatory Outlook
The US Federal Energy Regulatory Commission shapes market access through Order 841 mandates for energy storage participation in wholesale markets, while the EPA enforces emissions thresholds that indirectly favor zero-emission flywheel systems over fossil peaker plants. Germany's KBA and grid regulator Bundesnetzagentur impose rotational inertia requirements that preserve mechanical storage relevance amid inverter-dominated renewable expansion. Stakeholders must track evolving frequency-response compensation mechanisms and carbon border adjustments that could re-tier flywheel competitiveness against chemical battery alternatives.
Market Dynamics
The divergence between uptime-critical data center operators and cost-conscious industrial buyers is bifurcating flywheel procurement patterns, with magnetic-bearing systems commanding premium positioning against commodity steel alternatives.
Growth Catalysts
- US Inflation Reduction Act storage incentives:Federal tax credits for clean energy storage deployments accelerate utility-scale flywheel procurement for grid stabilization services.
- Carbon fiber rotor advancement:Higher specific energy density in aerospace-grade composite flywheels enables longer discharge durations for mission-critical backup applications.
- German rotational inertia mandates:Bundesnetzagentur requirements preserve mechanical storage relevance as inverter-based renewables displace synchronous generation.
Market Restraints
- Rare-earth magnet supply concentration:Dependence on processed neodymium from limited refining jurisdictions creates input cost volatility for magnetic-bearing manufacturers.
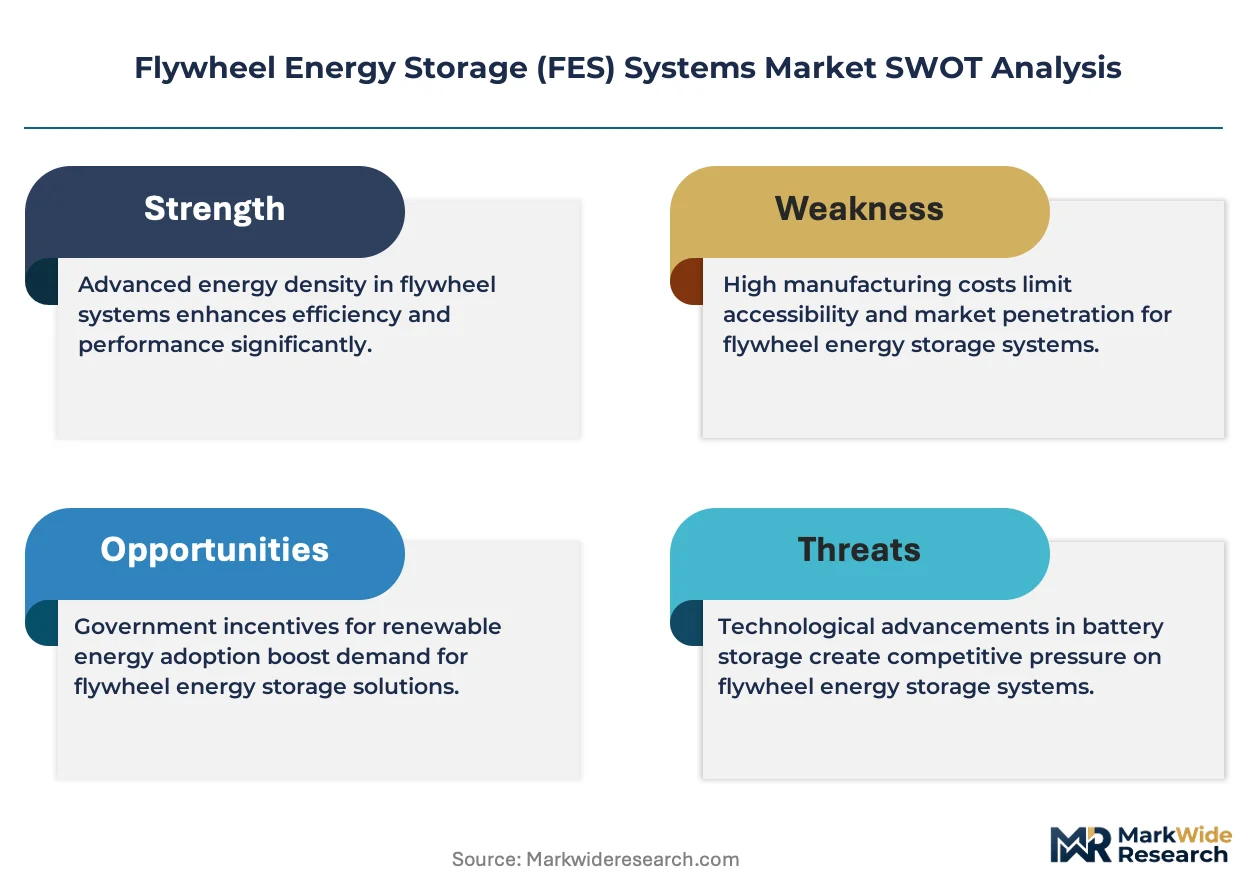
- Lithium-ion cost compression:Chemical battery price declines threaten flywheel competitiveness in sub-15-minute discharge duration segments.
- High-precision machining bottleneck:Limited supplier base for vacuum-sealed carbon fiber rotor fabrication constrains premium system output.
Strategic Opportunities
- India industrial microgrid expansion:CEA-mandated renewable integration targets create openings for containerized flywheel systems in captive power applications.
- Maritime vessel electrification:Harbor craft and short-sea shipping battery-buffer applications represent untapped kinetic storage demand.
- ISO 50001 energy management convergence:Certification-driven power quality investments channel capital toward flywheel-based uninterruptible power architectures.
Industry Challenges
- Magnetic bearing calibration expertise scarcity:Specialized field service technician shortages extend commissioning timelines for high-RPM installations.
- Multi-physics simulation complexity:Integrated thermal-structural-electromagnetic modeling requirements strain in-house engineering capacity at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flywheel Energy Storage (FES) Systems Market |
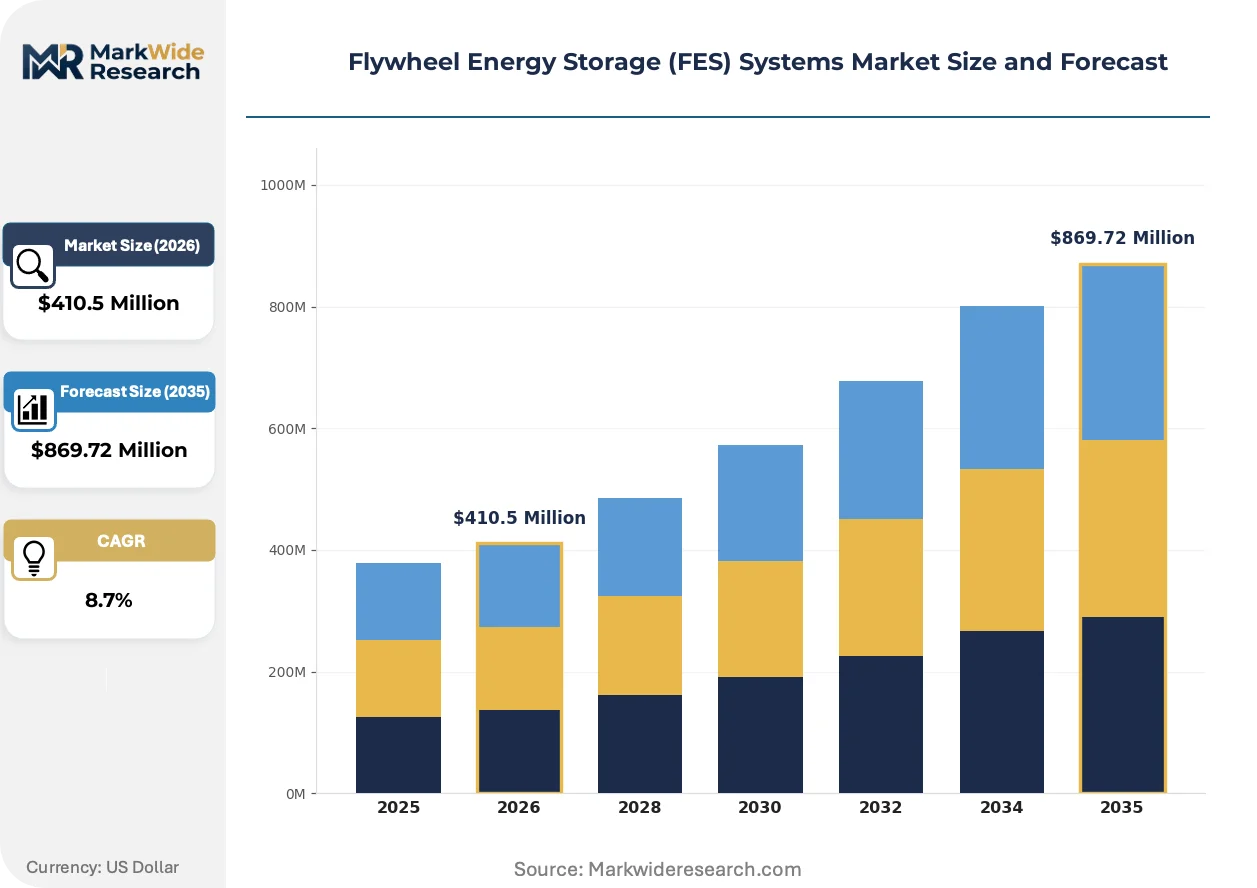
| Market Size in 2026 | $410.5 Million |
| Market Size in 2035 | $869.72 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Bearings, Carbon Fiber, Steel Flywheels, Composite Materials Application: Grid Energy Storage, Uninterruptible Power Supply, Transportation, Renewable Integration End User: Utilities, Industrial Manufacturers, Commercial Buildings, Transportation Sector Installation: Onshore, Offshore, Containerized, Stationary |
| Companies Covered | Amber Kinetics, Inc., Beacon Power, LLC, Stornetic GmbH, Calnetix Technologies, POWERTHRU, Langley Holdings plc, Energiestro, Kinetic Traction Systems, Inc., Piller Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flywheel Energy Storage (FES) Systems Market Trends and Innovations
Flywheel system architectures are fragmenting into purpose-built configurations as end-use requirements diverge across grid services, industrial backup, and aerospace applications. Technical evolution now prioritizes deployment velocity and operational flexibility over incremental efficiency gains.
Containerized flywheel arrays are modularizing for rapid renewable integration at remote mining sites and islanded microgrids. Mining operators in Western Australia and Chilean lithium provinces adopt skid-mounted configurations that compress installation from months to weeks. This shift is modularizing supplier business models toward equipment-leasing and performance-contracting structures.
EPA emissions enforcement under the Clean Air Act accelerates flywheel displacement of diesel peaker plants in urban airsheds. Fossil-fired frequency regulation capacity faces retirement pressure across California and Texas interconnection zones. Grid operators respond with hybrid storage procurements pairing flywheel fast response with chemical battery duration.
Power purchase agreement structures now unbundle spinning reserve services from energy arbitrage in utility procurement. Data center operators in Northern Virginia and Frankfurt prioritize guaranteed frequency response over capital ownership. This behavioral pivot favors third-party flywheel fleet operators with wholesale market participation capabilities.
Flywheel Energy Storage (FES) Systems Market Segmentation
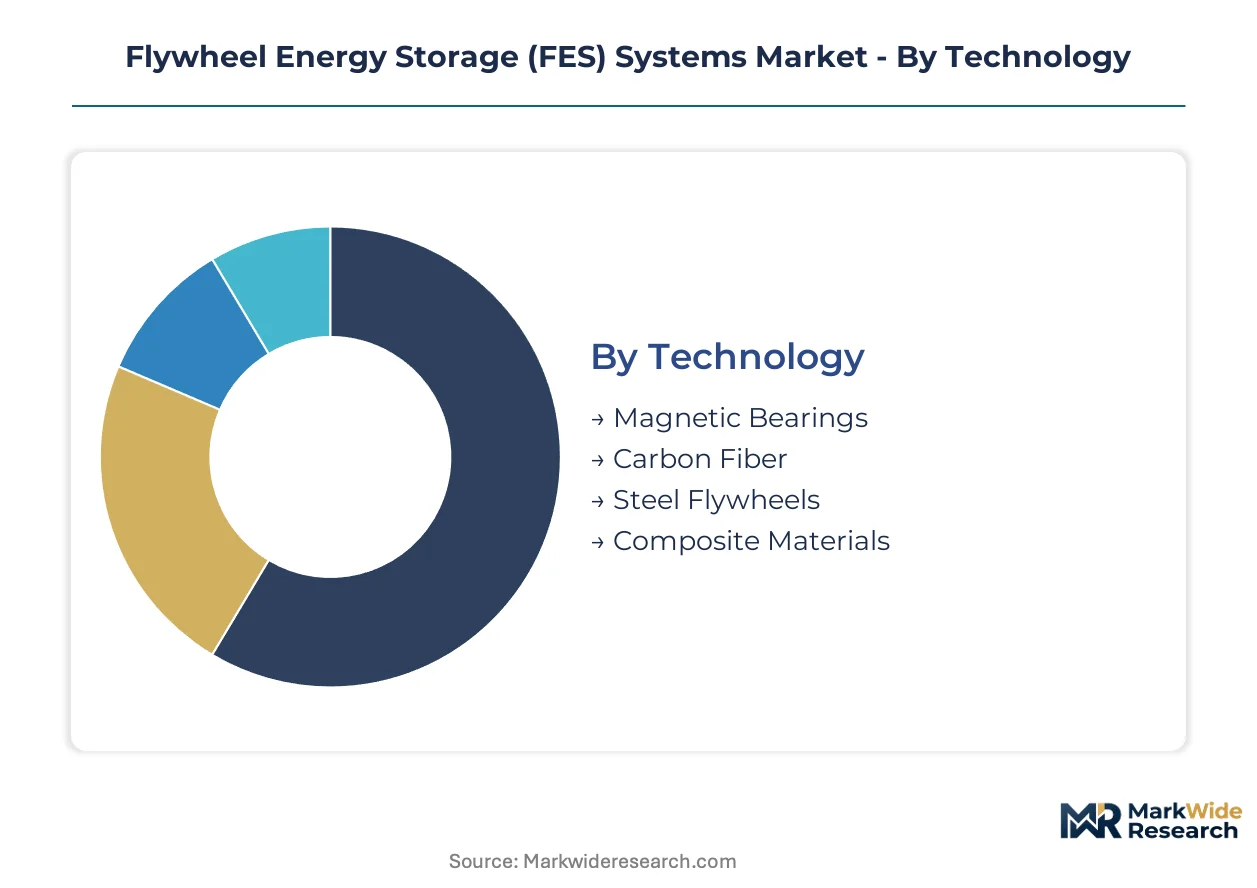
Flywheel procurement patterns diverge sharply across technology tiers and deployment contexts, with magnetic-bearing systems commanding premium positioning while steel alternatives serve cost-sensitive backup roles. End-user requirements for discharge duration, cycling frequency, and footprint constraints reshape competitive boundaries between carbon fiber and composite architectures.
Technology:
Upgrade cycles differentiate magnetic-bearing installations from steel flywheel replacements, with aerospace-grade carbon fiber systems extending operational lifespans beyond conventional mechanical bearing units.
- Magnetic Bearings:Electromagnetic levitation eliminates mechanical friction, enabling spin rates above 50,000 RPM with minimal maintenance intervals. Demand concentrates in Northern Virginia data centers where 99.999% uptime requirements justify premium capital outlays against lithium-ion hybrid configurations.
- Carbon Fiber:Aerospace-grade composite rotors achieve the highest specific energy density among commercial flywheel technologies, supporting 15-30 minute discharge durations. German industrial microgrid operators under Bundesnetzagentur rotational inertia mandates prioritize these systems for grid stabilization services.
- Steel Flywheels:Conventional forged steel rotors dominate commercial building UPS installations where 30-second to 5-minute ride-through requirements limit premium technology justification.
- Composite Materials:Hybrid glass-carbon fiber laminates offer intermediate cost-performance positioning for renewable integration projects in Western Australian mining corridors.
Steel flywheels sit at the top of the volume ranking, with magnetic bearings climbing the fastest as data center operators consolidate procurement around frictionless architectures.
Application:
Application selection tracks discharge duration requirements against capital intensity trade-offs, with grid services favoring rapid-cycling designs and transportation applications demanding compact form factors.
- Grid Energy Storage:Frequency regulation and spinning reserve services exploit flywheel sub-second response capabilities. Texas and California grid operators under FERC Order 841 procurement frameworks favor hybrid storage pairings with chemical batteries.
- Uninterruptible Power Supply:Mission-critical facility protection drives demand for vacuum-sealed rotor systems with 20-year operational lifespans. Frankfurt financial data centers specify magnetic-bearing configurations for harmonic isolation.
- Transportation:Kinetic energy recovery systems for rail and heavy-duty vehicle applications utilize compact composite rotors with high power density.
- Renewable Integration:Containerized flywheel arrays buffer solar and wind intermittency at remote Chilean lithium extraction sites where diesel displacement economics prove favorable.
Grid energy storage commands the largest installed base, with renewable integration expanding most quickly as mining operators electrify captive power systems.
End User:
End-user procurement sophistication varies across utility-scale frequency regulation and commercial building backup applications, with divergent technical specifications and lifecycle cost models.
- Utilities:Wholesale market participation requires fast-response assets capable of 100,000+ annual cycles. PJM Interconnection procurement standards favor flywheel systems for regulation signal tracking accuracy.
- Industrial Manufacturers:Semiconductor fabrication and pharmaceutical production facilities specify power quality systems isolating sensitive processes from voltage sags.
- Commercial Buildings:Cost-driven UPS procurement favors steel flywheel alternatives to chemical batteries where discharge duration requirements remain minimal.
- Transportation Sector:Harbor craft electrification programs in California ports under EPA Clean Air Act enforcement create kinetic buffer demand for shore power integration.
Utilities represent the dominant revenue concentration, with transportation sector deployment gaining share fastest as maritime decarbonization accelerates.
Installation:
Installation format selection balances deployment velocity against permanent infrastructure economics, with modular configurations capturing remote and temporary power applications.
- Onshore:Fixed foundation installations at utility substations and industrial campuses dominate established markets with predictable long-term load profiles.
- Offshore:Platform-mounted systems for North Sea wind farms address synthetic inertia requirements as synchronous generation retires.
- Containerized:Skid-mounted modular arrays compress commissioning timelines from months to weeks at Western Australian iron ore operations. This format is climbing the fastest as remote renewable integration demands surge.
- Stationary:Permanent building-integrated systems serve urban data centers where space constraints and seismic requirements dictate custom engineering.
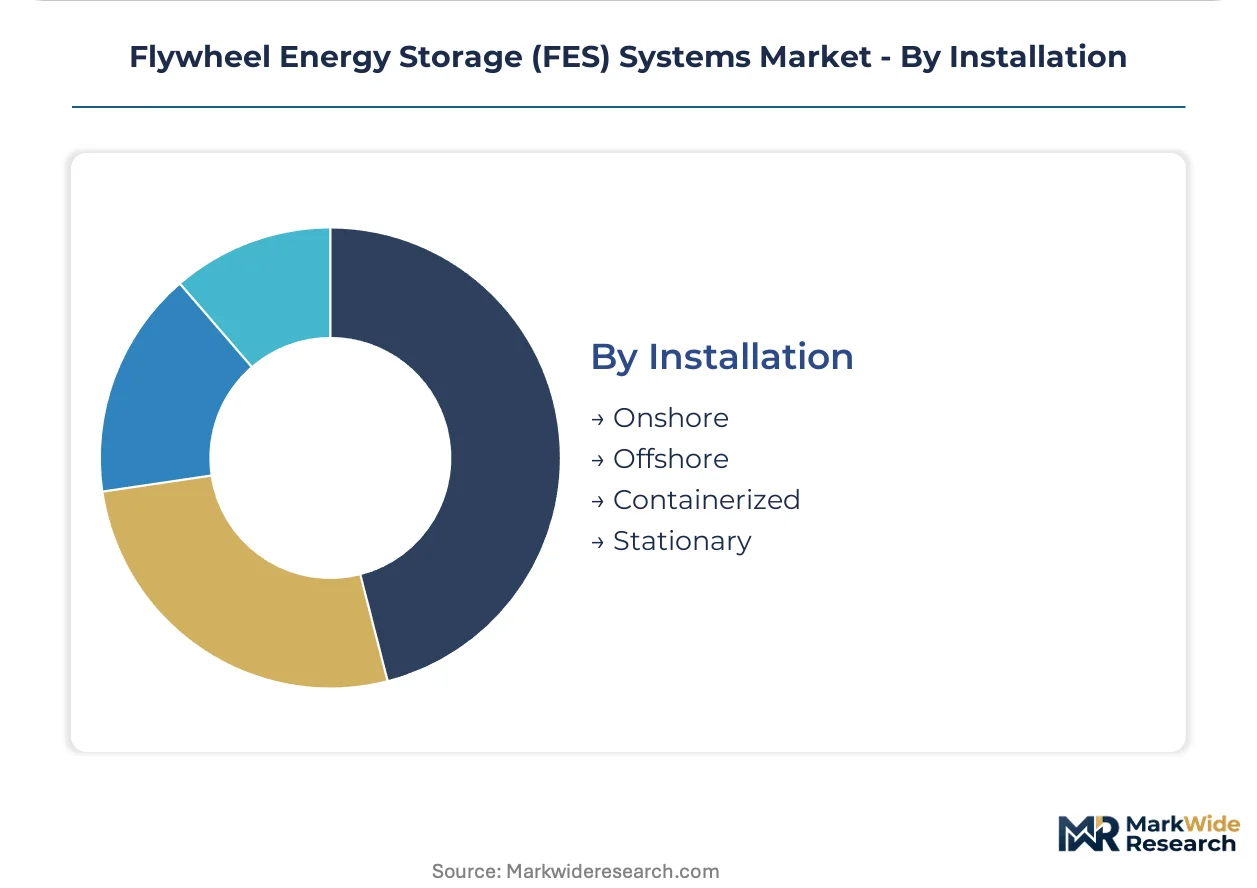
Onshore installations hold the volume leadership position, with containerized formats expanding most rapidly across mining and islanded microgrid deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized magnetic bearing engineers and high-precision machining talent cluster in Germany and the United States, anchoring flywheel R&D concentration while Chinese manufacturing scale builds composite rotor fabrication capacity.
United States
FERC Order 841 mandates energy storage participation in wholesale markets, accelerating utility-scale flywheel procurement for frequency regulation services. The Inflation Reduction Act extends tax credits to clean storage deployments, benefiting grid stabilization projects. Northern Virginia data center operators specify magnetic-bearing systems for 99.999% uptime requirements.
Germany
Bundesnetzagentur rotational inertia requirements preserve mechanical storage relevance as inverter-based renewables displace synchronous generation. The KBA enforces grid code compliance that favors fast-response kinetic systems. Industrial microgrid operators in North Rhine-Westphalia deploy carbon fiber flywheels for voltage stabilization.
China
Dual carbon goals under MIIT direction accelerate renewable integration investments, creating demand for containerized flywheel buffers. GB standards for grid-connected storage specify response time thresholds favoring electromechanical systems. Western mining corridors in Xinjiang and Inner Mongolia electrify captive power with skid-mounted kinetic arrays.
India
CEA-mandated renewable integration targets for industrial microgrids open procurement channels for containerized systems. PLI scheme incentives for advanced chemistry cell manufacturing indirectly pressure flywheel cost competitiveness. Gujarat and Maharashtra pharmaceutical clusters specify power quality systems isolating sensitive processes from grid disturbances.
Australia
Remote mining electrification programs in Western Australia drive containerized flywheel adoption for diesel displacement at iron ore operations. The national renewable energy target underpins hybrid storage procurements pairing kinetic fast response with chemical battery duration. Queensland and New South Wales grid operators pilot synthetic inertia services from platform-mounted systems.
Flywheel Energy Storage (FES) Systems Market Competitive Landscape
Top-tier vendors anchor premium magnetic-bearing and carbon fiber architectures, while mid-tier specialists compete on modular containerized formats and steel flywheel cost positioning. The vendor base stratifies across three functional tiers: aerospace-grade precision manufacturers, grid-scale frequency regulation operators, and industrial backup power fabricators. Competitive moves concentrate on strategic partnerships for rare-earth magnet supply security and geographic expansion into Indian and Australian mining corridors.
Within the grid-scale frequency regulation tier, Beacon Power, LLC and Stornetic GmbH exemplify divergent strategic positioning—Beacon Power represents North American utility market penetration while Stornetic occupies European modular architecture specialization. Calnetix Technologies anchors the premium magnetic-bearing segment, exemplifying aerospace and medical backup power concentration. These three entities collectively represent the technology-to-application mapping visible across procurement patterns: frequency regulation, containerized industrial microgrids, and mission-critical uptime assurance.
| Leading Market Players |
|---|
| Amber Kinetics, Inc. |
| Beacon Power, LLC |
| Stornetic GmbH |
| Calnetix Technologies |
| POWERTHRU |
| Langley Holdings plc |
| Energiestro |
| Kinetic Traction Systems, Inc. |
| Piller Power Systems |
| Others |
Pricing and Supply Chain Analysis
Captive production of rare-earth magnet assemblies in China and Japan anchors both supply security and premium pricing power for magnetic-bearing manufacturers serving Northern Virginia data centers and German industrial microgrids. This upstream integration choice insulates tier-one vendors from neodymium price volatility while enabling sustained margin capture against steel flywheel commodity competitors.
Pricing Analysis
Bundled spinning-reserve service contracts now dominate utility procurement, unbundling frequency response from energy arbitrage and shifting buyer economics toward operational expenditure models. Three-tier pricing structure across premium magnetic-bearing, standard composite, and economy steel configurations tracks certification grade and cycling durability. Cost compression in lithium-ion hybrid pairings is intensifying price competition for sub-15-minute discharge applications. Commercial building operators exhibit highest price sensitivity, while data center uptime requirements sustain premium magnetic-bearing positioning.
Supply Chain Analysis
Reverse-logistics flows for carbon fiber rotor refurbishment concentrate in Germany and the United States, extending asset lifecycles and creating secondary supply channels for aerospace-grade systems. Raw material dependencies center on Chinese-processed neodymium, Japanese high-tensile steel, and German precision-machined vacuum housings. Single-source vulnerability in rare-earth refining capacity threatens input cost stability. Distribution runs through EPC contractors for utility-scale deployments and direct OEM channels for data center UPS integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in flywheel energy storage hinges on carbon fiber cost-down curves and the ongoing shift from capital sale to performance-contracting revenue models. Magnetic-bearing premiumization and containerized format standardization together compress unit economics while extending addressable market reach.
For Market Incumbents: Deploy field service network density as the primary defensive lever against lithium-ion substitution in frequency regulation markets. Beacon Power and Calnetix Technologies should deepen captive magnet supply agreements with Japanese refiners to offset Chinese export restriction risks. Capacity addition in Western Australian mining corridors captures containerized demand growth before modular specialists establish beachheads. For New Entrants and Emerging Players: Composite rotor manufacturing automation represents the most penetrable technology-first wedge for challenging established precision machining specialists. Target India's CEA-mandated industrial microgrid segment through performance-contracting structures that bypass upfront capital barriers. Harbor craft electrification in California ports offers a white-space application with limited incumbent presence. For Investors and Strategic Acquirers: Roll-up economics work for regional field service and commissioning specialists because magnetic bearing calibration expertise scarcity fragments the aftermarket across disconnected local providers. Long-term viability favors platform consolidation plays spanning five-to-ten year holding periods. Acquisition target archetypes include containerized system integrators with Australian mining relationships. Watch FERC Order 841 compensation rule revisions as the signal for frequency regulation revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Supply Agreement | Secures neodymium processing capacity against Chinese export volatility for magnetic-bearing production. |
| Containerized Format Standardization | Compresses Western Australian iron ore site commissioning from months to weeks. |
| Performance Contracting Transition | Shifts revenue from capital equipment to spinning-reserve service fees under FERC Order 841 frameworks. |
| Carbon Fiber Rotor Refurbishment Network | Extends aerospace-grade system lifecycles and creates recurring aftermarket revenue streams. |
| German KBA Certification Investment | Unlocks Bundesnetzagentur-mandated rotational inertia procurement channels for grid stabilization. |
Research Methodology
Bottom-up data center and utility procurement modeling reconciled against top-down carbon fiber and steel flywheel production tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and magnetic bearing field service technicians combined with secondary validation from FERC filings, EIA grid interconnection data, IEA energy storage reports, and Bundesnetzagentur regulatory notices. Triangulation across these sources ensures segment-level accuracy without reliance on single-source disclosures.
Input-output matrices map rotor material throughput to installed capacity across magnetic-bearing, carbon fiber, steel, and composite technology tiers. Segmentation dimensions span discharge duration requirements, cycling frequency specifications, and regional regulatory frameworks including FERC Order 841 and German rotational inertia mandates. CAGRs derive from regression against historical deployment velocities and policy incentive trajectories. Forecast inputs incorporate lithium-ion cost curve projections and rare-earth magnet price elasticity assumptions.
The model holds under sustained US Inflation Reduction Act credit availability and stable Chinese rare-earth export policy; deviation in either trigger would shift utility procurement timing and magnetic-bearing cost structures. Forecasts reflect documented assumptions regarding technology cost convergence and regulatory compensation mechanisms. Practitioners should monitor FERC frequency-response pricing rulemakings and Bundesnetzagentur inertia requirement enforcement for early signals of revenue model disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Solar Energy Storage Market
Energy Storage
South America Energy Storage Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Natural Gas Storage Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
Solar Storage System Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Energy Storage Sodium Ion Battery Market