
 Solar Energy Storage Market | 2026-2036
Solar Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Energy Storage Market Intelligence
Modular battery rack configurations bundled with inverter hardware is repositioning procurement decisions for commercial and utility buyers. Tesla Inc. leverages vertical integration across cell production and software-controlled dispatch to sustain cost advantages in large-scale deployments. LG Energy Solution anchors its position through manufacturing scale across multiple geographies, while Fluence competes on grid-forming inverters and energy management platforms for utility-scale operators.
Solar energy storage encompasses electrochemical systems that capture photovoltaic output for time-shifted dispatch, typically operating at 85-95% round-trip efficiency with lithium-ion cells dominating current installations. The primary commercial purpose is to firm intermittent solar generation and provide frequency regulation services to grid operators. Lithium-ion technology occupies the dominant share due to declining cell costs and established supply chains, while flow batteries attract interest for multi-hour duration applications above four hours. Solid-state chemistries represent the fastest-growing development track as manufacturers target higher energy density and reduced thermal runaway risk.
The US Inflation Reduction Act production credits, EU Green Deal domestic content requirements, and China's MIIT battery recycling mandates collectively reshape where cells are manufactured and how systems qualify for subsidies. The US EPA and FERC coordinate on interconnection standards that determine market access timelines for co-located solar-plus-storage projects. Stakeholders must monitor evolving domestic content thresholds across jurisdictions to assess supply chain qualification risks and manufacturing location decisions.
Market Dynamics
Co-located solar-plus-storage procurement is compressing interconnection timelines and forcing developers to pre-integrate battery hardware with photovoltaic inverters before grid application. This structural shift favors vertically integrated suppliers capable of certifying bundled systems under evolving utility standards.
Growth Catalysts
- US Inflation Reduction Act production credits:Domestic cell manufacturing mandates accelerate factory construction across the American Southeast and Southwest. Battery packagers co-locate with solar assembly plants to qualify for full credit stacks.
- Frequency regulation services:Grid operators in Germany and Australia procure fast-response battery capacity to stabilize renewable intermittency. Utility-scale operators capture recurring revenue streams beyond energy arbitrage.
- Lithium-ion cost curves:Cathode chemistry improvements and scale manufacturing in China compress system-level pricing. Residential installers pass savings to homeowners through lease structures.
Market Restraints
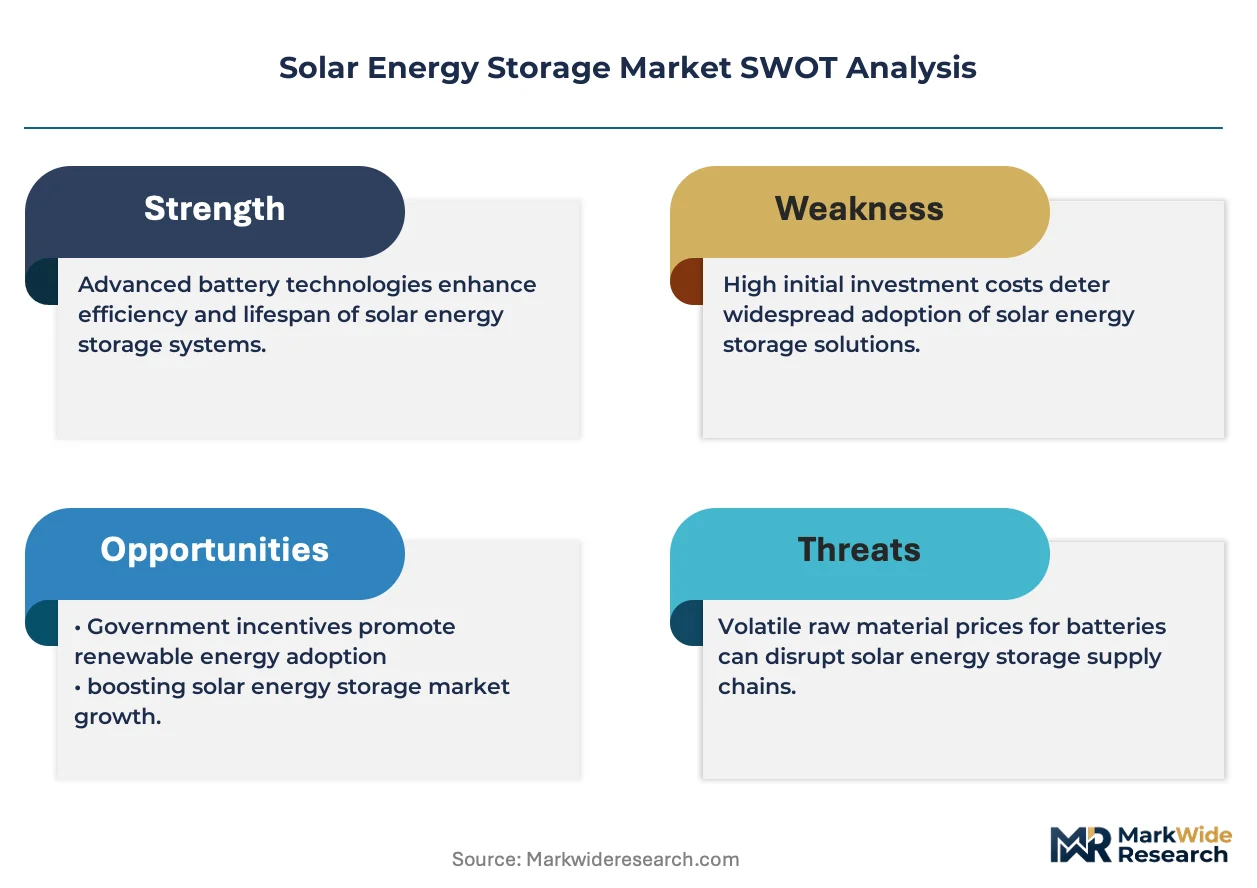
- Lithium carbonate volatility:Raw material spot markets in South America and Australia transmit price shocks to cell producers. Long-term offtake contracts fail to insulate integrated manufacturers.
- Transformer and power electronics concentration:Semiconductor fabrication for grid-forming inverters clusters in East Asian foundries. Western project developers face 18-24 month lead times for critical components.
- Flow battery duration economics:Vanadium redox systems above four hours struggle against lithium-ion learning curves despite superior cycle life. Utility procurement committees default to familiar chemistry.
Strategic Opportunities
- India CEA storage mandates:Renewable purchase obligations now require solar developers to bundle discharge capacity. State-level tenders open for multi-gigawatt hour installations.
- Behind-the-meter commercial aggregation:Virtual power plant software stacks monetize distributed battery fleets for wholesale market participation. C&I facility managers capture new revenue without operational burden.
- Solid-state chemistry convergence:Sulfide electrolyte research bridges automotive and stationary applications. Joint development agreements between cell startups and solar integrators accelerate pilot deployments.
Industry Challenges
- Grid interconnection queue management:Co-located projects face compounded study timelines as FERC and regional transmission organizations reconcile solar and storage impact assessments. Developers burn carrying costs during procedural delays.
- Thermal runaway mitigation engineering:Battery rack designers must certify cascade prevention systems under evolving UL and IEC test protocols. Fire suppression integration adds non-recurring engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Energy Storage Market |
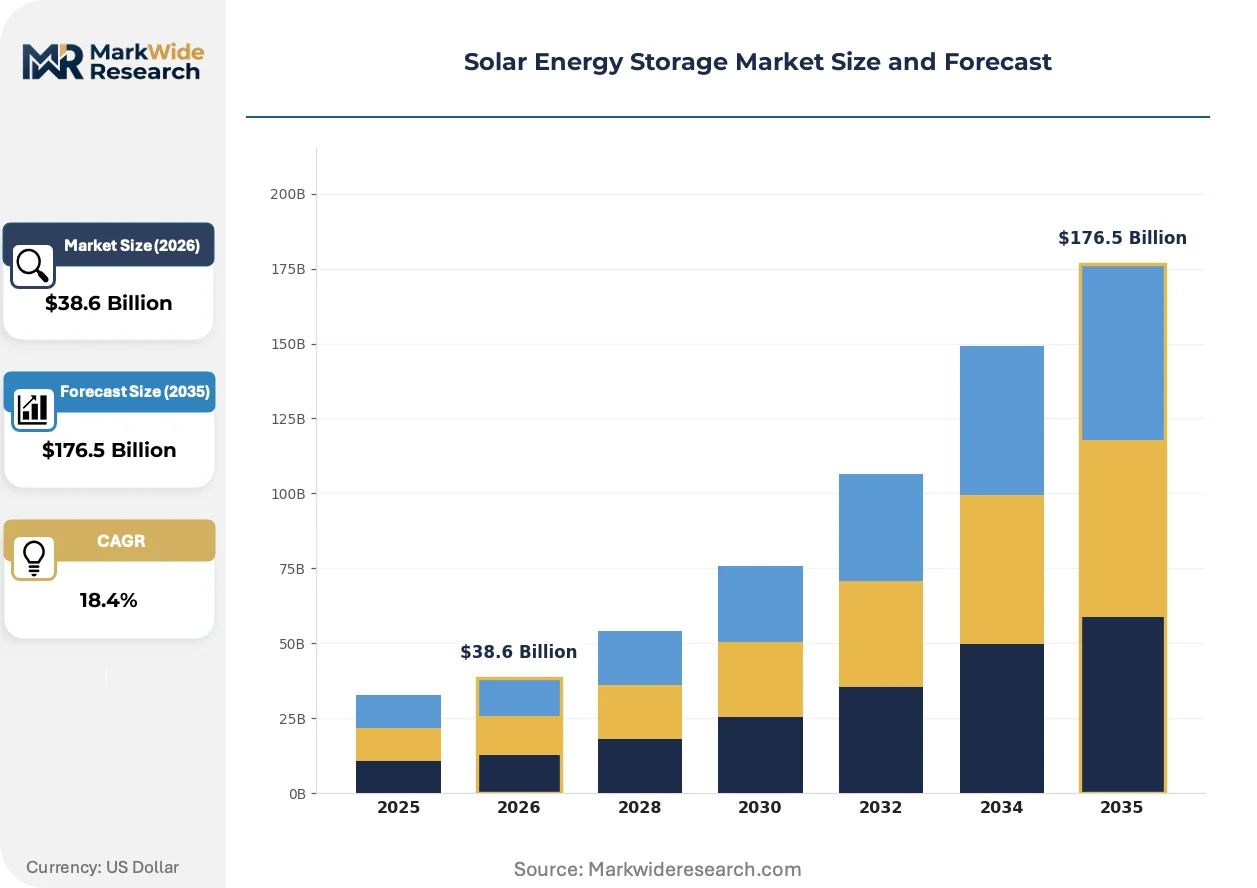
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $176.5 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-Ion, Flow Batteries, Lead-Acid, Sodium-Nickel Chloride, Solid-State Application: Residential Systems, Commercial Facilities, Microgrids, Remote Power Supply, Telecom Towers Storage Capacity: Below 10 kWh, 10-50 kWh, 50-200 kWh, Above 200 kWh End User: Utility-Scale Operators, Solar EPC Contractors, Energy Traders, Off-Grid Consumers |
| Companies Covered | Tesla Inc., LG Energy Solution, Samsung SDI, BYD Co. Ltd., General Electric, ABB Ltd., SolarEdge Technologies Inc., Panasonic Holdings Corporation, Fluence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Energy Storage Market Strategic Shifts & Innovations
Solid-state electrolyte research and containerized system architectures are compressing development cycles for next-generation storage. Manufacturers race to qualify higher-density configurations before subsidy windows contract.
Lithium iron phosphate cell chemistry is modularizing into standardized rack formats compatible with multiple inverter protocols. Utility EPC contractors specify these configurations to reduce commissioning time and spare parts complexity. The technology is modularizing procurement decisions around interoperability rather than single-vendor lock-in.
EU Green Deal domestic content thresholds are forcing supply chain reconfiguration across cell and module production. Manufacturers relocate finishing capacity to European economic zones to qualify for auction premiums. Battery system integrators with existing EU manufacturing footprints capture preferential offtake from German and Spanish solar developers.
Commercial buyers are consolidating procurement through energy-as-a-service platforms that bundle hardware, software, and maintenance into single contracts. Traditional equipment distributors lose volume to vertically integrated providers offering guaranteed performance outcomes. This pattern concentrates in California and Texas where C&I electricity rates create arbitrage value.
Solar Energy Storage Market Segmentation
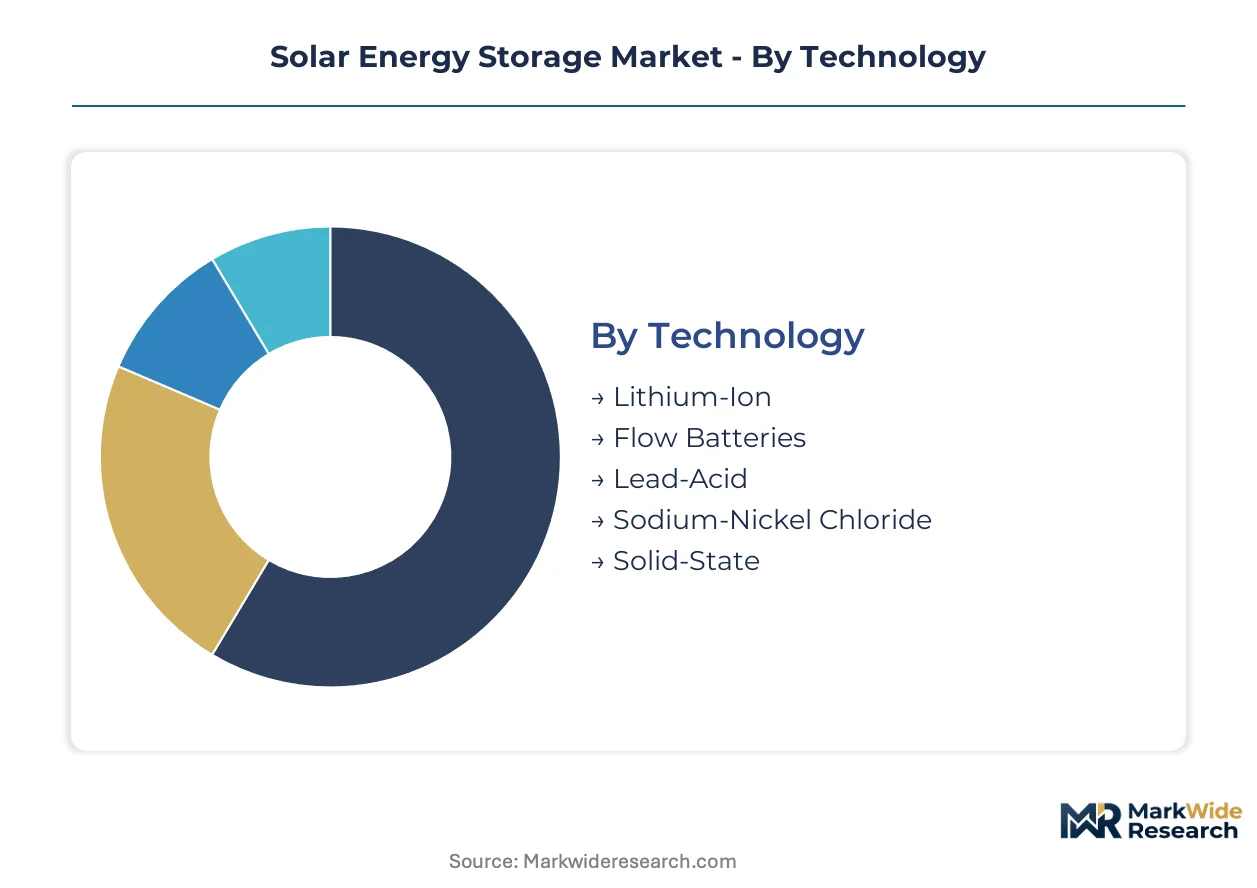
Solar energy storage procurement splits across integration depth, from behind-the-meter residential units to front-of-meter utility installations. Technology chemistry and capacity sizing determine interconnection protocols, subsidy eligibility, and operational revenue streams for each segment.
Technology:
Integration depth varies sharply: lithium-ion dominates co-located solar-plus-storage where DC-coupled architectures merge photovoltaic output with battery racks, while flow batteries and solid-state chemistries occupy standalone or specialized embedded applications.
- Lithium-Ion:Lithium iron phosphate and nickel-manganese-cobalt cells deliver 85-95% round-trip efficiency in modular rack formats. Utility-scale operators across the United States and Germany specify these systems for frequency regulation services, though lithium carbonate volatility from South American and Australian spot markets transmits cost shocks to integrators.
- Flow Batteries:Vanadium redox systems separate energy and power scaling through liquid electrolyte tanks, enabling duration configurations above four hours. Multi-hour discharge economics struggle against lithium-ion learning curves despite superior cycle life, limiting procurement to niche utility committees seeking chemistry diversification.
- Lead-Acid:Mature flooded and valve-regulated designs serve remote telecom towers and off-grid installations where capital constraints override energy density requirements.
- Sodium-Nickel Chloride:High-temperature molten salt chemistry operates without thermal runaway risk, attracting safety-critical applications in extreme climates.
- Solid-State:Sulfide and oxide electrolyte architectures replace flammable liquid separators, targeting higher energy density for space-constrained commercial rooftops and residential installations.
Volume placements concentrate in lithium-ion; the faster expansion belongs to solid-state.
Application:
Cost tier stratification separates premium utility-scale installations from economy-grade remote power systems, with commercial and residential segments occupying mid-tier pricing bands based on soft costs and permitting complexity.
- Residential Systems:Behind-the-meter battery units paired with rooftop solar capture net metering credits and backup power value. California and Texas installers dominate lease origination, passing lithium-ion cost savings to homeowners through third-party ownership structures.
- Commercial Facilities:C&I load managers deploy 100-500 kWh systems for demand charge reduction and virtual power plant aggregation. Energy-as-a-service platforms bundle hardware, software, and maintenance into single contracts, displacing traditional equipment distributors.
- Microgrids:Island-capable architectures integrate solar, storage, and backup generation for campuses, military installations, and island utilities seeking resilience against grid outages.
- Remote Power Supply:Off-grid mining operations and rural electrification projects in India and Australia specify containerized solar-plus-storage to displace diesel generation.
- Telecom Towers:Lead-acid and lithium-ion hybrid configurations ensure 99.99% uptime for mobile network infrastructure across emerging markets with unreliable grid access.
Revenue concentration sits with commercial facilities; microgrids are climbing the fastest as resilience premiums expand.
Storage Capacity:
Customer type mapping reveals divergent procurement patterns: homeowners cluster below 50 kWh, C&I buyers span 50-200 kWh, and utility-scale operators specify above 200 kWh for wholesale market participation.
- Below 10 kWh:Compact wall-mounted units serve residential backup and self-consumption optimization. German and Australian households lead procurement under feed-in tariff evolution and high retail electricity rates.
- 10-50 kWh:Small commercial shops and large residential estates balance peak shaving with export limitation compliance. India's CEA storage mandates are opening state-level tenders in this range for agricultural solar pumps.
- 50-200 kWh:Industrial facilities and community solar gardens arbitrage time-of-use rates while providing grid services. Transformer lead times of 18-24 months from East Asian foundries constrain deployment velocity for this segment.
- Above 200 kWh:Containerized megawatt-hour systems co-locate with utility-scale solar for energy arbitrage and ancillary service revenue. FERC interconnection queues compound study timelines as regional transmission organizations reconcile solar and storage impact assessments.
Deployment scale favors above 200 kWh; the steepest expansion trajectory runs through 50-200 kWh as C&I aggregation platforms mature.
End User:
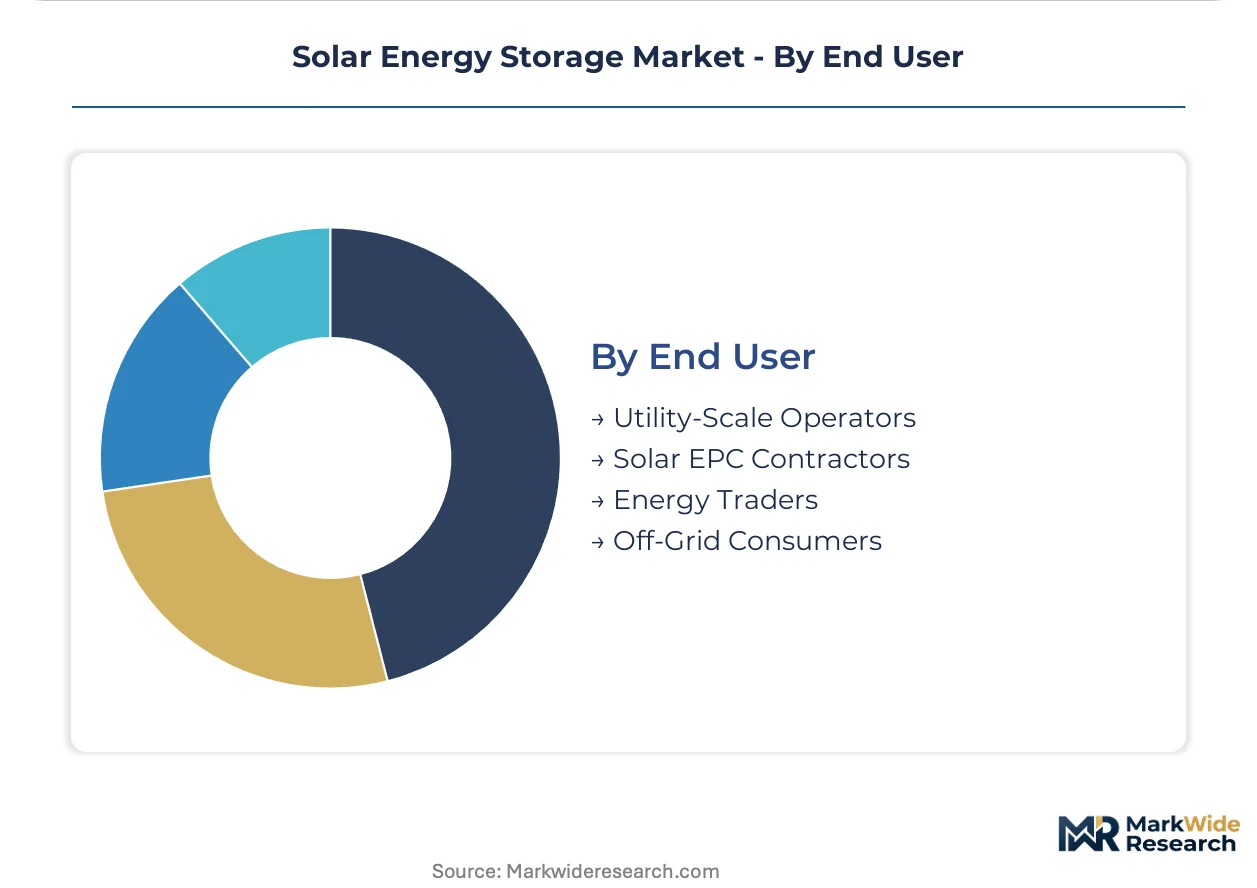
Margin structure varies by buyer sophistication: energy traders demand algorithmic dispatch optimization, while off-grid consumers prioritize capital efficiency over performance guarantees.
- Utility-Scale Operators:Independent power producers and regulated utilities procure multi-hundred-megawatt-hour installations under long-term offtake agreements. The US Inflation Reduction Act production credits accelerate factory construction across the American Southeast, with battery packagers co-locating with solar assembly plants to qualify for full credit stacks.
- Solar EPC Contractors:Engineering-procurement-construction firms specify standardized rack formats to reduce commissioning time and spare parts complexity across project portfolios.
- Energy Traders:Merchant battery owners exploit wholesale price volatility through automated bidding algorithms, capturing spreads between day-ahead and real-time markets.
- Off-Grid Consumers:Rural households and remote industrial sites prioritize lowest lifecycle cost over technical performance, accepting lead-acid degradation curves in exchange for upfront affordability.
Contract flow concentrates with utility-scale operators; energy traders are gaining share fastest as market liberalization expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's production tax credits have transformed the American Southeast into a magnet for battery packagers seeking full credit stacks alongside solar assembly plants.
United States
Utility-scale operators in Texas and California are procuring co-located battery systems at record pace. FERC coordinates with regional transmission organizations on interconnection standards that determine market access timelines. Arizona and Nevada host manufacturing clusters where battery packagers co-locate with photovoltaic assembly to capture IRA incentives.
Germany
Grid operators procure fast-response battery capacity to stabilize renewable intermittency across the national network. EU Green Deal domestic content requirements force supply chain reconfiguration for auction qualification. Bavaria and North Rhine-Westphalia concentrate manufacturing footprints serving Spanish and German solar developers.
China
Dual carbon goals accelerate domestic manufacturing mandates for electrochemical storage systems. MIIT battery recycling mandates reshape qualification protocols for subsidy access. The Yangtze River Delta and Pearl River Delta host cathode chemistry improvements that compress system-level pricing globally.
Australia
State-level tenders open for multi-gigawatt hour installations under renewable purchase obligations. Frequency regulation services create recurring revenue streams beyond energy arbitrage for utility-scale operators. South Australia and Queensland lead deployment of containerized solar-plus-storage for remote mining operations.
India
CEA storage mandates now require solar developers to bundle discharge capacity in state-level tenders. Agricultural solar pumps drive procurement in the 10-50 kWh range across Maharashtra and Gujarat. Karnataka and Tamil Nadu host engineering-procurement-construction firms specifying standardized rack formats.
Solar Energy Storage Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the solar energy storage value chain. The vendor base organizes around three strategic archetypes: vertically integrated cell producers, grid-forming inverter specialists, and energy management platform providers. Dominant competitive moves include manufacturing co-location for subsidy qualification and strategic partnerships for software-controlled dispatch capabilities.
Within the vertically integrated tier, Tesla Inc. and LG Energy Solution exemplify contrasting geographic strategies. Tesla anchors its position through captive cell production and software-controlled dispatch systems. LG Energy Solution occupies a multinational manufacturing position across multiple economic zones. Fluence represents the platform-specialist archetype, sitting within grid-forming inverters and energy management systems for utility-scale procurement committees.
| Leading Market Players |
|---|
| Tesla Inc. |
| LG Energy Solution |
| Samsung SDI |
| BYD Co. Ltd. |
| General Electric |
| ABB Ltd. |
| SolarEdge Technologies Inc. |
| Panasonic Holdings Corporation |
| Fluence |
| Others |
Cost & Logistics Intelligence
Solid-state electrolyte manufacturing transitions from laboratory batch processing toward pilot-scale continuous production lines, compressing unit economics while concentrating cathode precursor supply within the Yangtze River Delta and South Korean industrial corridors. This simultaneous cost and geographic concentration reshapes how integrators negotiate long-term offtake terms against spot market volatility.
Pricing Analysis
Premium pricing attaches to battery systems delivering under 12-week lead times as transformer and power electronics shortages stretch standard procurement cycles to 18-24 months. Project-based contract structures dominate utility-scale procurement, with price differentiation driven by UL 9540A thermal runaway certification tier and domestic content compliance under the US Inflation Reduction Act. Cost compression in lithium iron phosphate rack systems is intensifying because Chinese cathode manufacturers are expanding finishing capacity, though margins are tightening for European assemblers lacking qualified cell supply. Off-grid consumers in emerging markets exhibit highest price sensitivity, accepting lead-acid degradation curves for upfront affordability.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions and Panama Canal constraints adds 8-15% landed cost variance for containerized battery systems moving from East Asian assembly hubs. Manufacturing gravity centers on China, South Korea, and Japan for lithium-ion cell production, with cathode active materials drawing from Indonesian nickel processing and Chilean lithium carbonate conversion. Supply chain risk rests on single-source vulnerability for semiconductor fabrication of grid-forming inverters clustering in Taiwan and South Korea. Distribution runs through engineering-procurement-construction contractors specifying standardized rack formats, with direct OEM relationships gaining share in utility-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell manufacturing capacity constraints in qualified supply geographies prop pricing power for producers meeting domestic content thresholds, creating a supply-constrained market structure through the projection horizon.
For Market Incumbents: Anchor market position through captive cathode precursor supply and backward integration into lithium carbonate conversion. Defensive moves require securing FERC interconnection pre-certification for co-located solar-plus-storage bundles and expanding manufacturing footprints to Arizona or Nevada to capture full IRA credit stacks. Threats from solid-state chemistry startups and European domestic content mandates demand certification investment in UL 9540A cascade prevention systems. For New Entrants and Emerging Players: Solid-state electrolyte pilot production creates entry leverage into space-constrained commercial rooftop segments where lithium-ion fire suppression costs erode project economics. White-space targets include 10-50 kWh agricultural solar pump installations under India's CEA storage mandates and behind-the-meter C&I aggregation platforms in Texas and California. Go-to-market positioning through energy-as-a-service platforms bundles hardware, software, and performance guarantees to displace traditional equipment distributors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified industrial conglomerates seeking grid-forming inverter capabilities and energy management software stacks. Long-term viability favors cell producers with qualified supply under EU Green Deal domestic content thresholds and US IRA manufacturing credits. Acquisition target archetypes include mid-scale battery packagers with existing EU manufacturing footprints and virtual power plant software providers with live dispatch contracts. Signal to watch: FERC Order 2023 interconnection reform implementation timelines as inflection indicator for project development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Co-location for IRA Qualification | Battery packagers co-locating with solar assembly in Arizona capture full production credit stacks under US Treasury guidance. |
| Grid-Forming Inverter Certification | FERC-compliant grid-forming capabilities unlock frequency regulation revenue streams for utility-scale operators in Texas and Germany. |
| Virtual Power Plant Platform Integration | Software stacks aggregating distributed C&I batteries monetize wholesale market participation without facility manager operational burden. |
| Solid-State Chemistry Pilot Deployment | Sulfide electrolyte systems targeting commercial rooftops reduce fire suppression engineering overhead versus lithium-ion alternatives. |
| EU Domestic Content Supply Chain Reconfiguration | Finishing capacity relocation to Bavaria qualifies battery systems for German and Spanish auction premiums under Green Deal thresholds. |
Research Approach
Trade association filings, customs shipment records, and interconnection queue databases formed the secondary backbone for supply chain mapping and capacity tracking. Primary interviews with utility planning officers, independent power producer development leads, EPC procurement directors, and grid operator interconnection specialists validated demand assumptions and pricing trajectories. Bottom-up project development pipelines were triangulated against top-down regulatory mandate analysis across the analysis window.
Bottom-up modeling of individual project announcements and interconnection filings was cross-referenced against top-down policy target aggregation. Segmentation dimensions included technology chemistry, application tier, storage capacity band, and end-user sophistication. CAGRs were derived from fitted growth curves anchored to disclosed manufacturing capacity expansions and subsidy program budget allocations. Forecast inputs incorporated lithium carbonate spot price volatility bands and transformer lead time assumptions from East Asian foundry disclosures.
Several conditions sit outside the modeled scope, including unannounced solid-state chemistry breakthroughs, abrupt FERC interconnection rule revisions, and geopolitical disruptions to South American lithium supply. Forecasts reflect assumptions about subsidy program continuity and qualified manufacturing capacity ramp rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
ASEAN Energy Storage Devices Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Solar Storage System Market