
 Gravity Energy Storage Market | 2026-2036
Gravity Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Gravity Energy Storage Market Insights
Project finance tied to power purchase agreements is narrowing the competitive field for gravity energy storage developers. Energy Vault leverages its crane-based modular architecture to attract utility-scale contracts across multiple continents. Gravitricity anchors its position through shaft-based systems repurposing abandoned mine infrastructure. ARES North America competes on rail-based designs optimized for flat terrain where vertical options prove impractical.
Gravity energy storage harnesses gravitational potential energy by lifting massive masses during low-demand periods and releasing them to generate electricity when grid stress peaks, with round-trip efficiencies typically ranging from 80% to 90% depending on mechanical design. Falling weight systems currently dominate commercial deployments due to their modularity and lower civil engineering requirements. Rail-based configurations represent the fastest-growing technology segment as they bypass geological constraints that limit vertical shaft alternatives. Energy arbitrage applications command the strongest margin pools among end-use cases, reflecting merchant power traders' willingness to pay premium rates for dispatchable long-duration capacity.
The Federal Energy Regulatory Commission in the United States, the EU Green Deal framework, and Australia's Clean Energy Regulator collectively shape market access through interconnection standards, carbon accounting rules, and storage procurement mandates. Germany's Federal Network Agency and state-level mining regulators additionally influence project economics through shaft repurposing permits and grid connection cost allocations. Stakeholders must monitor evolving capacity market designs and duration requirements that determine which mechanical storage technologies qualify for revenue streams.
Market Dynamics
Project finance structures tied to long-duration storage procurement mandates are compressing development timelines and favoring technologies with proven grid interconnection pathways over experimental alternatives.
Growth Catalysts
- EU Green Deal storage procurement frameworks:Germany, Spain, and Poland have embedded gravity storage eligibility into renewable auction designs, creating guaranteed offtake channels for developers with operational track records.
- Decommissioned mine shaft inventory:Australia, South Africa, and the United Kingdom possess thousands of abandoned vertical shafts with existing grid infrastructure, eliminating civil engineering costs that burden greenfield pumped hydro.
- Merchant power trader demand for 8+ hour duration:Energy arbitrage desks in Texas, California, and the United Kingdom pay substantial premiums for dispatchable capacity that outlasts lithium-ion degradation curves.
Market Restraints
- Steel and concrete input cost volatility:Mass-based systems require thousands of tons of engineered materials per megawatt, exposing project economics to commodity swings that battery manufacturers avoid through chemistry hedging.
- Geological constraint concentration:Vertical shaft designs depend on specific hard-rock formations found in limited geographies, forcing rail-based alternatives in flat terrain markets with higher land acquisition costs.
- FERC interconnection queue friction:United States projects face standardized study timelines designed for conventional generation, delaying gravity storage with unique power electronics and protection requirements.
Strategic Opportunities
- India's pumped hydro moratorium zones:Seismic and ecological restrictions in the Himalayan foothills create white space for modular gravity systems that bypass reservoir requirements.
- Hybrid solar-gravity configurations:Co-located photovoltaic arrays can direct surplus generation to lifting operations without transmission losses, opening desert and semi-arid markets previously uneconomical for standalone storage.
- Duration-based capacity market redesign:United Kingdom and Italy are piloting procurement mechanisms that explicitly weight storage duration, tilting auction scoring toward mechanical alternatives over four-hour batteries.
Industry Challenges
- Mechatronics engineering talent scarcity:Gravity systems require rare combinations of civil, mechanical, and power electronics expertise, with only a handful of universities offering relevant cross-disciplinary programs.
- Grid code certification timelines:Each interconnected market requires utility-specific protection studies and dynamic model validation, stretching commissioning schedules by 12-18 months beyond construction completion.
- Legacy SCADA integration complexity:Utility control rooms demand seamless communication with existing energy management systems, forcing costly custom protocol development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gravity Energy Storage Market |
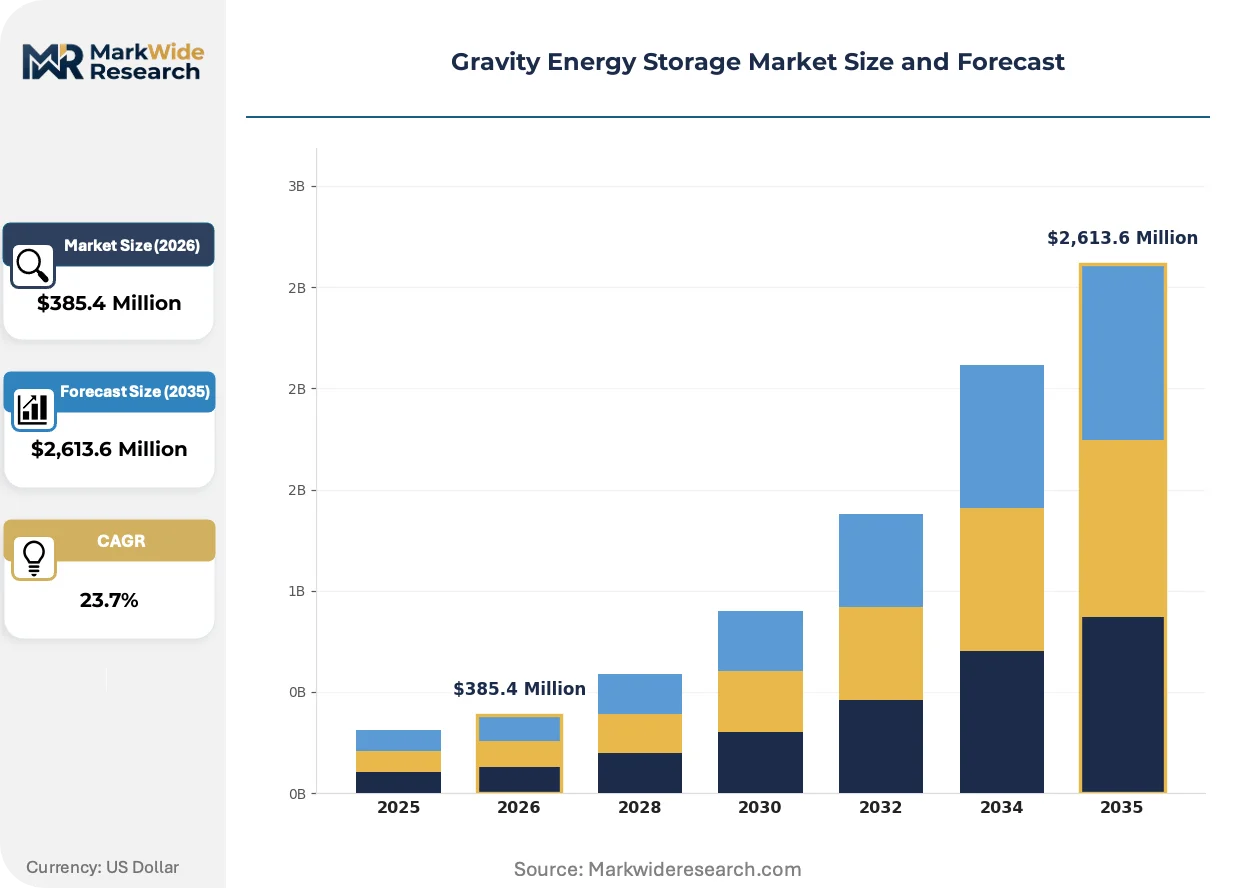
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,613.6 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Falling Weight, Pneumatic, Vertical Shaft, Rail-Based End User: Utilities, Industrial Facilities, Commercial Buildings, Residential Areas Deployment: Onshore, Offshore, Remote, Urban Application: Load Shifting, Renewable Integration, Peak Shaving, Energy Arbitrage |
| Companies Covered | Energy Vault, Gravitricity, ARES North America, Gravity Power, Green Gravity Energy Pty, GRAVIENT, Gravity Storage, Renewell Energy, RheEnergise Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gravity Energy Storage Market Trends and Innovations
Mechanical storage architectures are fragmenting into specialized designs optimized for specific terrain constraints, with modularity and rapid deployment displacing the scale-at-all-costs logic that dominated early pilot projects.
Composite block lifting systems are migrating from fixed crane configurations to autonomous vehicle-based architectures that enable distributed mass storage across larger footprints. Utility-scale developers in flat terrain markets are adopting these designs to bypass shaft availability constraints. The technology is migrating from demonstration phases to commercial procurement, compressing the competitive window for first-mover advantages in rail-based alternatives.
The EU Green Deal's delegated acts on carbon border adjustments are forcing storage developers to document embodied emissions in steel and concrete components. Projects with verifiable low-carbon material sourcing now qualify for preferential auction scoring in German and French renewable tenders. This regulatory pressure is concentrating engineering resources on lightweight composite masses and recycled aggregate formulations.
Merchant offtake contracts are displacing traditional utility ownership models as the dominant procurement pathway for gravity storage. Independent power producers in Texas and the United Kingdom are signing direct agreements with data center operators and industrial load facilities, bypassing regulated utility intermediaries. This channel shift is most visible in markets with nodal pricing and transparent wholesale market access.
Gravity Energy Storage Market Segmentation
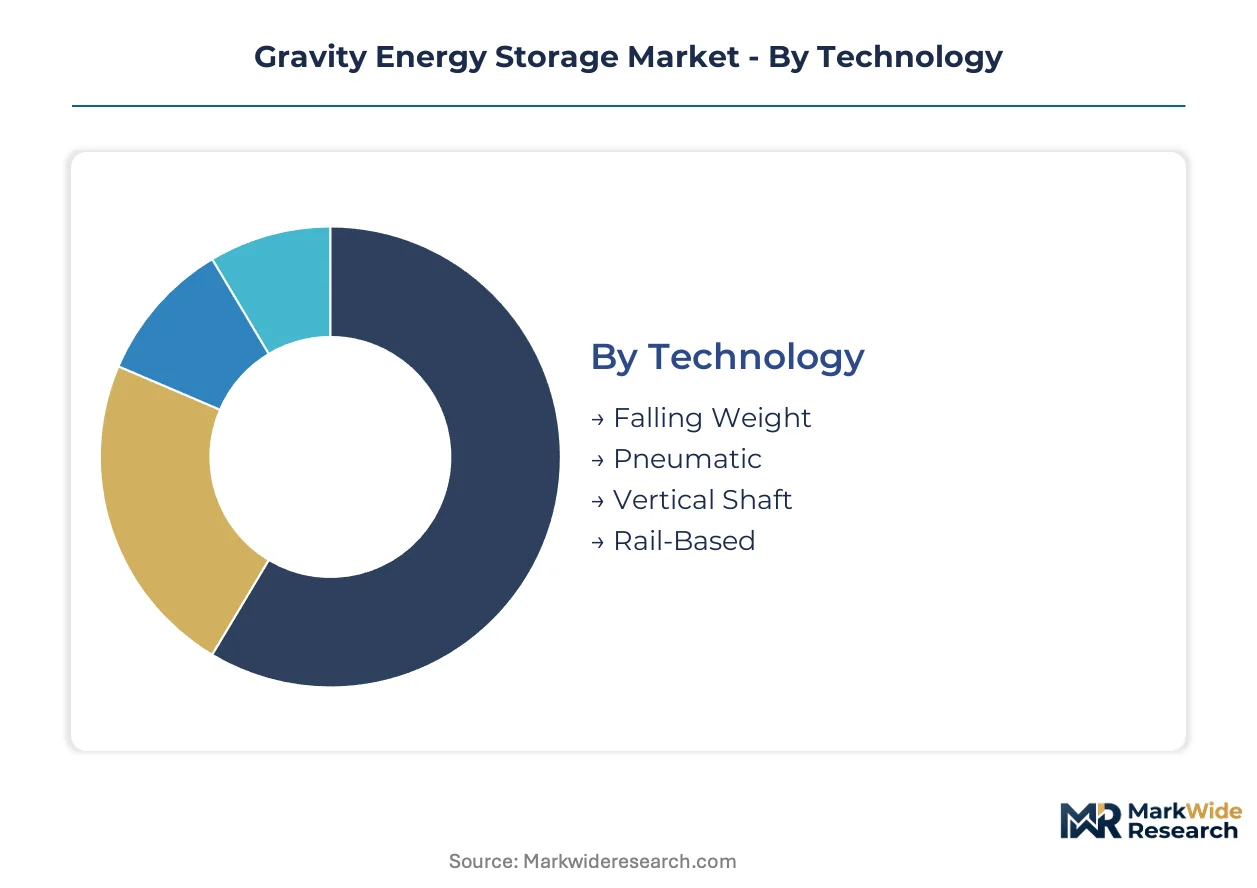
Gravity energy storage technologies diverge sharply by mechanical architecture and deployment context, with each configuration commanding distinct project economics and regulatory pathways. Understanding these segment boundaries clarifies why certain designs dominate specific geographies while others remain niche.
Technology:
Use-case spectrum spans decommissioned infrastructure repurposing through entirely novel mechanical systems.
- Falling Weight:Crane-suspended composite blocks descend to drive motor-generators, achieving 80-90% round-trip efficiency with minimal civil works. Utility-scale procurements in Texas and California concentrate here due to flat-terrain compatibility and rapid deployment timelines.
- Rail-Based:Automated vehicles transport masses up graded tracks, bypassing vertical shaft geology constraints entirely. Australia and South Africa's mining corridors drive adoption where abandoned shafts prove unsuitable or distant from transmission infrastructure.
- Vertical Shaft:Mine shaft repurposing with winch-based mass lifting leverages existing grid connections in Germany and Poland. EU Green Deal eligibility for circular economy materials sourcing strengthens project finance access.
- Pneumatic:Compressed air combined with gravitational potential in sealed shafts offers higher energy density but requires precision engineering. Niche deployments concentrate in Switzerland and Austria's alpine tunnel networks.
Established volume favors falling weight systems; emerging adoption favors rail-based configurations.
End User:
Customer archetypes range from regulated monopolies with mandated storage procurement to merchant operators seeking arbitrage margins.
- Utilities:Grid-scale deployments under renewable portfolio standards in Germany, Spain, and Australia anchor commercial pipelines. Long-duration requirements in capacity market redesigns tilt procurement toward 8+ hour mechanical storage over lithium-ion.
- Industrial Facilities:Cement, steel, and data center operators pursue behind-the-meter installations for demand charge management and carbon reporting. United Kingdom and Netherlands industrial clusters lead procurement through corporate power purchase agreements.
- Commercial Buildings:Mixed-use developments in urban constraint zones adopt modular crane systems for resilience and ESG compliance. Singapore and Dubai building codes increasingly embed storage requirements for large floorplates.
- Residential Areas:Micro-gravity prototypes for off-grid housing remain experimental, with pilot programs in rural India and sub-Saharan Africa testing village-scale deployments.
Regulated procurement concentrates in utility channels; merchant flexibility drives industrial adoption.
Deployment:
Site conditions dictate civil engineering intensity and interconnection cost structures across terrain types.
- Onshore:Greenfield installations on flat or gently sloped terrain accommodate rail-based and surface crane systems. United States Great Plains and Australian interior dominate project pipelines.
- Remote:Island grids and mining camps require self-contained storage without transmission dependency. Pacific island nations and Canadian Arctic communities evaluate gravity alternatives to diesel displacement.
- Urban:Space-constrained environments favor vertical shaft retrofits or compact crane architectures. London, Berlin, and Melbourne assess decommissioned industrial sites for distributed storage.
- Offshore:Floating gravity platforms remain conceptual, with North Sea oil platform repurposing studies ongoing in Norway and United Kingdom waters.
Onshore economics favor scale; remote deployments command premium pricing for reliability.
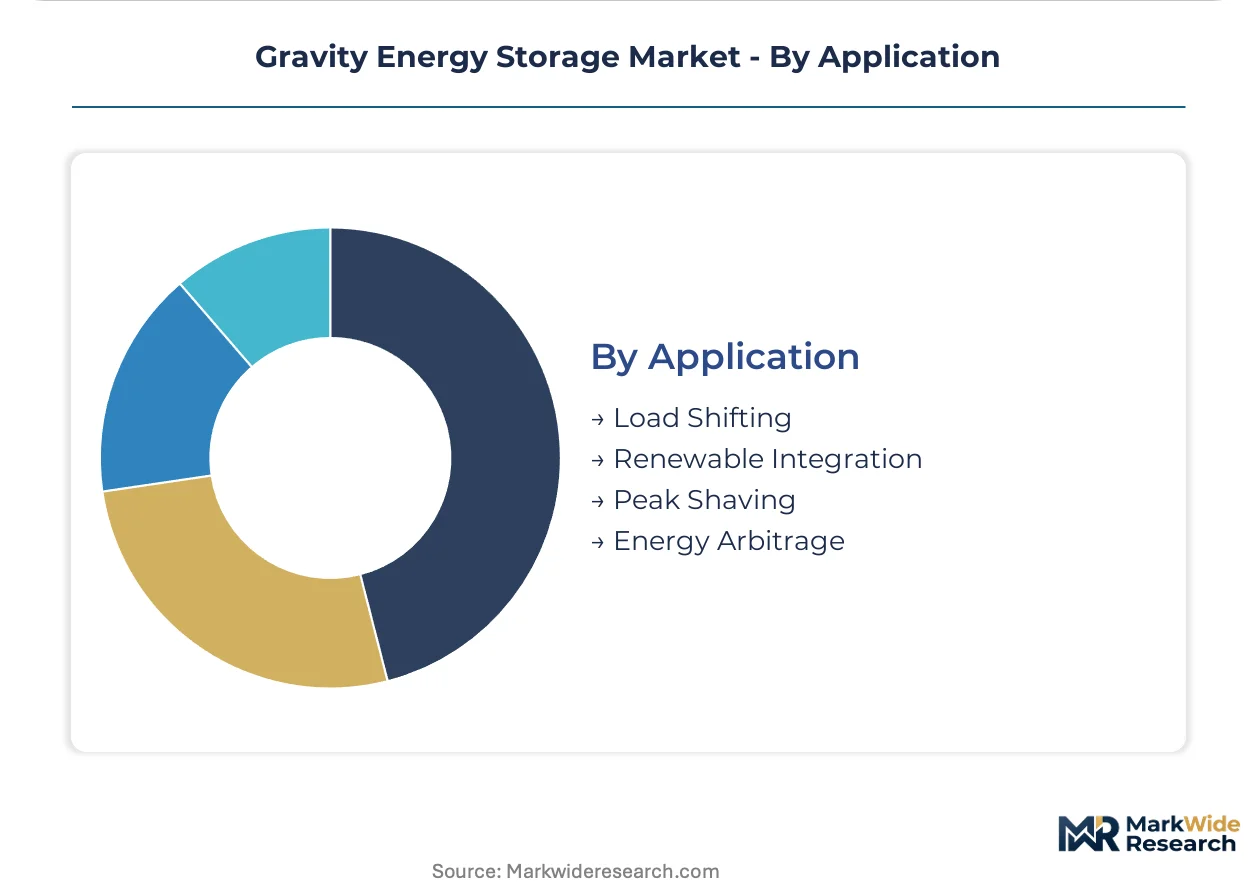
Application:
Revenue model differentiation separates regulated capacity payments from volatile merchant arbitrage.
- Energy Arbitrage:Buying low and selling high across diurnal price spreads rewards 8+ hour duration. Texas ERCOT and United Kingdom wholesale markets attract merchant developers with transparent nodal pricing.
- Renewable Integration:Curtailment reduction and firming services for solar and wind farms secure offtake in Spain, Australia, and California. Co-located configurations eliminate transmission losses.
- Load Shifting:Time-of-use rate optimization for industrial and commercial consumers drives behind-the-meter installations. Germany and Italy's evolving tariff structures expand addressable market.
- Peak Shaving:Demand charge reduction for large electricity consumers offers predictable returns. United States commercial and industrial rate structures particularly reward this application.
Merchant arbitrage captures margin expansion; renewable integration secures volume commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gravity energy storage project pipelines concentrate in markets with decommissioned mine infrastructure and favorable permitting regimes. Germany, the United States, Australia, South Africa, and the United Kingdom each present distinct deployment pathways shaped by legacy industrial assets and regulatory frameworks.
Germany
Abandoned hard-coal shafts in the Ruhr and Lusatia regions offer ready-made vertical infrastructure for winch-based systems. The Federal Network Agency's capacity market redesigns explicitly weight storage duration, tilting procurement toward 8+ hour mechanical alternatives. Project clusters in North Rhine-Westphalia leverage existing grid connections from shuttered mining operations.
United States
ERCOT's nodal pricing and California's renewable portfolio standards create merchant arbitrage opportunities for crane-based deployments. FERC interconnection standards, designed for conventional generation, delay gravity projects with unique power electronics requirements. Texas and California utility-scale procurements concentrate in flat-terrain markets where rail-based and surface crane systems bypass geological constraints.
Australia
Thousands of abandoned vertical shafts across Queensland and Western Australia eliminate civil engineering costs that burden greenfield alternatives. The Clean Energy Regulator's storage procurement mandates accelerate permitting timelines for projects with proven grid interconnection pathways. Mining corridor infrastructure supports both shaft-based retrofits and rail-based configurations where vertical geology proves unsuitable.
South Africa
Decommissioned gold and platinum shafts in the Witwatersrand and Bushveld complexes provide deep vertical infrastructure with existing hoisting equipment. The country's integrated resource plan embeds long-duration storage eligibility into renewable auction designs. Project development concentrates around Johannesburg and Rustenburg where transmission infrastructure from mining operations remains intact.
United Kingdom
Abandoned coal and tin shafts in Scotland, Wales, and northern England attract Gravitricity's shaft-based systems with circular economy material sourcing advantages. The UK's pilot duration-based capacity market mechanisms explicitly weight storage duration beyond four-hour lithium-ion limits. Edinburgh and Glasgow assess distributed urban deployments on decommissioned industrial sites.
Gravity Energy Storage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying engineered masses, winch assemblies, and power conversion equipment. The vendor base concentrates around three to five integrated developers with operational track records, while dozens of component fabricators compete on material specifications and manufacturing scale. Two strategic archetypes dominate: shaft-repurposing specialists leveraging legacy mining infrastructure, and modular crane architects optimizing for rapid deployment across flat terrain. Competitive moves center on project finance partnerships with utility offtakers and geographic expansion through joint ventures with local construction firms.
Within the integrated platform tier, Energy Vault, Gravitricity, and ARES North America exemplify contrasting mechanical philosophies. Energy Vault occupies a position representing crane-based modularity optimized for greenfield deployment without geological constraints. Gravitricity anchors the shaft-repurposing archetype, converting abandoned vertical infrastructure into storage assets. ARES North America sits within the rail-based segment, addressing markets where vertical shaft geology proves unavailable. Each represents a distinct pathway to grid-scale commercialization.
| Leading Market Players |
|---|
| Energy Vault |
| Gravitricity |
| ARES North America |
| Gravity Power |
| Green Gravity Energy Pty |
| GRAVIENT |
| Gravity Storage |
| Renewell Energy |
| RheEnergise Limited |
| Others |
Pricing and Supply Chain Analysis
The Ruhr industrial cluster anchors engineered mass fabrication capacity, with German steel and composite suppliers commanding premium positioning against Chinese commodity alternatives. This geographic concentration grants incumbent fabricators pricing power over utility-scale developers seeking low-carbon material certification for EU auction eligibility.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing with long-term offtake structures spanning construction through operation. Price differentiation hinges on embodied carbon documentation and ISO 14001 environmental certification tiers. Cost compression in standard-grade steel masses is intensifying because Chinese mills are flooding European spot markets. Merchant IPPs exhibit acute price sensitivity, while regulated utilities absorbing capacity mandates show greater tolerance for certified premium tiers.
Supply Chain Analysis
Extended payment terms from 90 to 180 days have become standard for crane assembly and winch system procurement, with supply-chain finance facilities now embedded in major EPC contracts. Manufacturing concentrates in Germany, China, and South Korea for precision mechanical components. Raw material dependencies span high-grade structural steel, carbon-fiber reinforced composites, and rare-earth permanent magnets for motor-generators. Single-source vulnerability in Chinese magnet processing creates exposure to export licensing disruptions. Distribution runs through utility procurement departments and independent power producer development teams rather than traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gravity energy storage represents a defensive-moat market where regulatory entrenchment creates durable competitive positioning. FERC interconnection standards and EU Green Deal eligibility criteria embed switching costs that protect first-movers with operational track records.
For Market Incumbents: Build regulatory entrenchment moats through accelerated grid code certification in multiple jurisdictions. Deepen backward integration into composite mass manufacturing to offset steel price volatility threatening project margins. Capacity additions in Poland and Texas address emerging procurement pipelines while lithium-ion substitution risk intensifies in four-hour duration segments.
For New Entrants and Emerging Players: Establish a beachhead in India's pumped hydro moratorium zones where seismic restrictions eliminate conventional competition. Target hybrid solar-gravity configurations in Australian mining corridors, co-locating with existing transmission infrastructure. A go-to-market angle emphasizing rapid deployment timelines without geological surveys differentiates against shaft-repurposing incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform developers with operational track records over component specialists. Long-term viability rests on duration-based capacity market redesigns spreading beyond UK and Italian pilots. Acquisition targets with certified EU projects and FERC interconnection approvals signal inflection readiness. The signal to monitor is merchant offtake contract volume in Texas ERCOT nodal pricing zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Execution | Secures revenue visibility for utility-scale deployments under Germany's Federal Network Agency mandates. |
| Technology Licensing to Regional EPCs | Accelerates geographic expansion into South African mining corridors without direct capital deployment. |
| Vertical Integration into Composite Manufacturing | Captures margin pool from carbon-fiber block production while satisfying EU Green Deal embodied emissions requirements. |
| Grid Code Certification Investment | Reduces FERC interconnection queue friction that currently delays gravity projects by standardized study timelines. |
| Green Certification Program | Qualifies projects for preferential auction scoring in German and French renewable tenders under delegated acts. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation across EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity buildout modeling triangulated against top-down renewable integration demand forecasts.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with segmentation modeled by mechanical architecture, end-user archetype, deployment terrain, and application revenue model. CAGRs derived from project pipeline velocity and procurement mandate implementation schedules. Forecast inputs incorporated steel and concrete commodity price trajectories alongside interconnection queue clearance rates.
Stress conditions across raw material cost bands, permitting timeline extensions, and merchant price spread compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and technology performance validation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
ASEAN Energy Storage Devices Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Residential Solar Energy Storage Market