
 North America Battery Energy Storage System Market | 2026-2036
North America Battery Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Battery Energy Storage System Market Intelligence
The customer base for utility-scale projects in North America is consolidating around a core group of large independent power producers and regulated utilities. Fluence Energy Inc leverages its Siemens and AES parentage to secure large-scale deployment contracts. Tesla Inc leads the residential and commercial segments with its vertically integrated hardware and software ecosystem. AES Corporation operates as both a major project developer and an owner-operator, influencing procurement standards across its US and Latin American portfolio.
A battery energy storage system (BESS) is an electrochemical device that captures energy from the grid or a power plant to discharge it at a later time. These systems integrate battery cells, a battery management system (BMS), and a power conversion system (PCS) to manage precise charge and discharge cycles. Lithium-ion batteries command the market due to their high energy density, modularity, and declining cost curves. Grid stabilization and renewable integration applications represent the largest segments, driven by grid modernization efforts across the United States and Canada.
In the United States, Federal Energy Regulatory Commission (FERC) orders like 841 and 2222 facilitate BESS participation in wholesale electricity markets. The Investment Tax Credits within the US Inflation Reduction Act directly subsidize project costs, while Canadian provincial clean energy mandates create parallel demand. Navigating complex grid interconnection queues and securing stable lithium-ion battery supply chains remain the critical challenges for project developers.
Market Dynamics
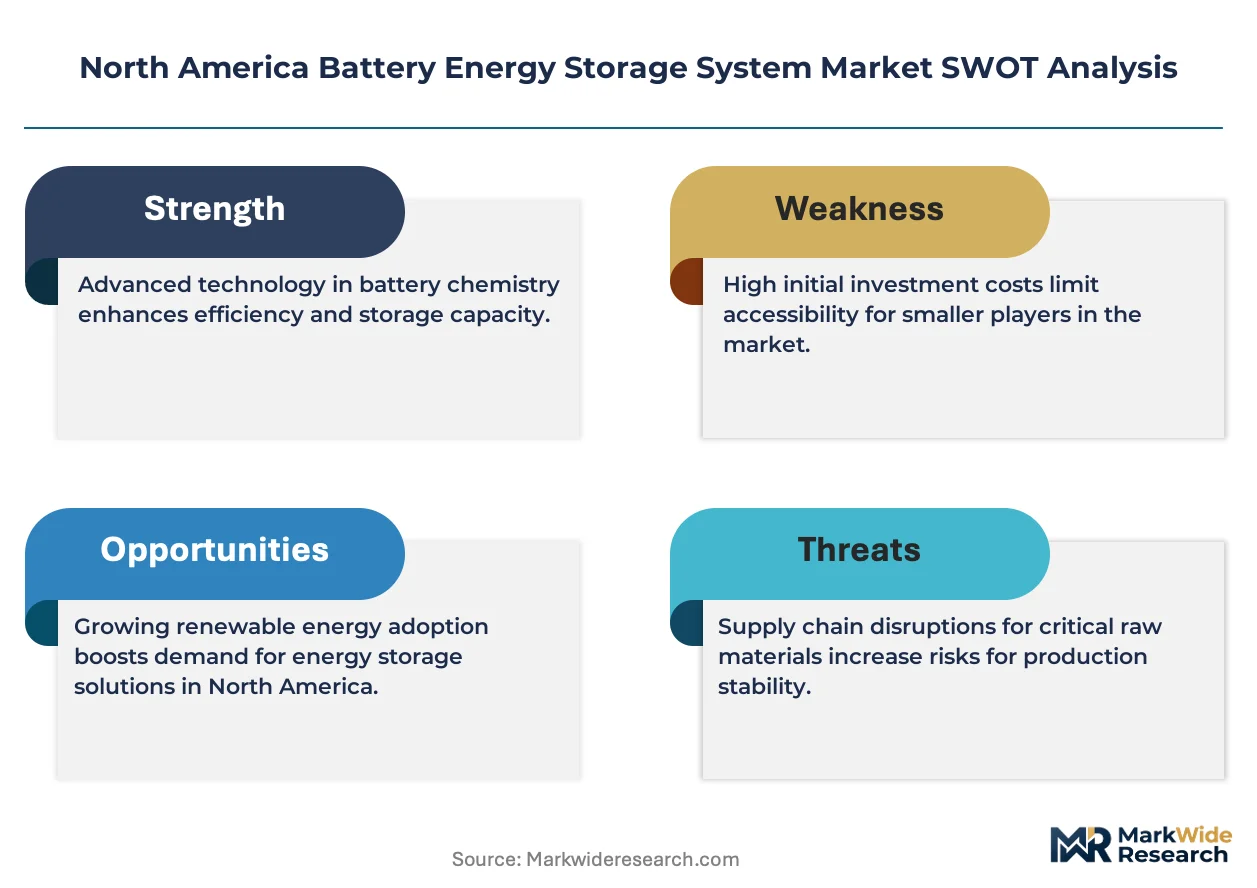
The central tension shaping the North America battery storage market is the collision between urgent grid modernization requirements and the structural constraints of the lithium-ion battery supply chain, which remains concentrated outside the continent, creating procurement bottlenecks.
Growth Catalysts
- Federal Incentives:The US Inflation Reduction Act provides long-term Investment Tax Credits for standalone storage projects, directly improving project economics and accelerating final investment decisions for developers.
- Renewable Integration Mandates:State-level targets for renewable energy penetration, particularly in California and Texas, necessitate large-scale energy storage to manage the intermittency of wind and solar generation.
- Technology Maturation:Continuous cost reductions and performance improvements in lithium-ion battery technology, specifically regarding energy density and modular design, make BESS a more competitive solution for grid services.
Market Restraints
- Supply Chain Concentration:Heavy reliance on raw materials like lithium and cobalt, and cell manufacturing capacity located primarily in Asia, exposes North American developers to price volatility and geopolitical risks.
- Grid Interconnection Delays:Project developers face significant backlogs and long wait times in grid interconnection queues across the United States, delaying project commissioning and revenue generation.
- High Capital Costs:Despite falling battery prices, the total installed cost for utility-scale BESS projects remains substantial, creating a high barrier to entry for smaller developers without access to significant capital.
Strategic Opportunities
- Long-Duration Storage Technologies:There is a significant opportunity for alternative, non-lithium-ion technologies like flow batteries or compressed air energy storage to meet emerging demand for long-duration (8+ hours) applications.
- Canadian Provincial Markets:Provinces like Ontario and Alberta are expanding their clean energy programs, creating new geographic markets for BESS deployment to support grid reliability and decarbonization goals.
- Software and Optimization Services:A growing market exists for advanced software platforms that use machine learning to optimize BESS dispatch for participation in multiple electricity markets, maximizing asset revenue.
Industry Challenges
- Skilled Labor Shortages:A scarcity of trained engineers and technicians for the design, construction, and operation of complex BESS projects creates execution risks and can lead to project delays.
- Component Sourcing Volatility:Securing a consistent supply of critical components beyond battery cells, such as power conversion systems (PCS) and transformers, remains a persistent operational challenge for EPC contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Battery Energy Storage System Market |
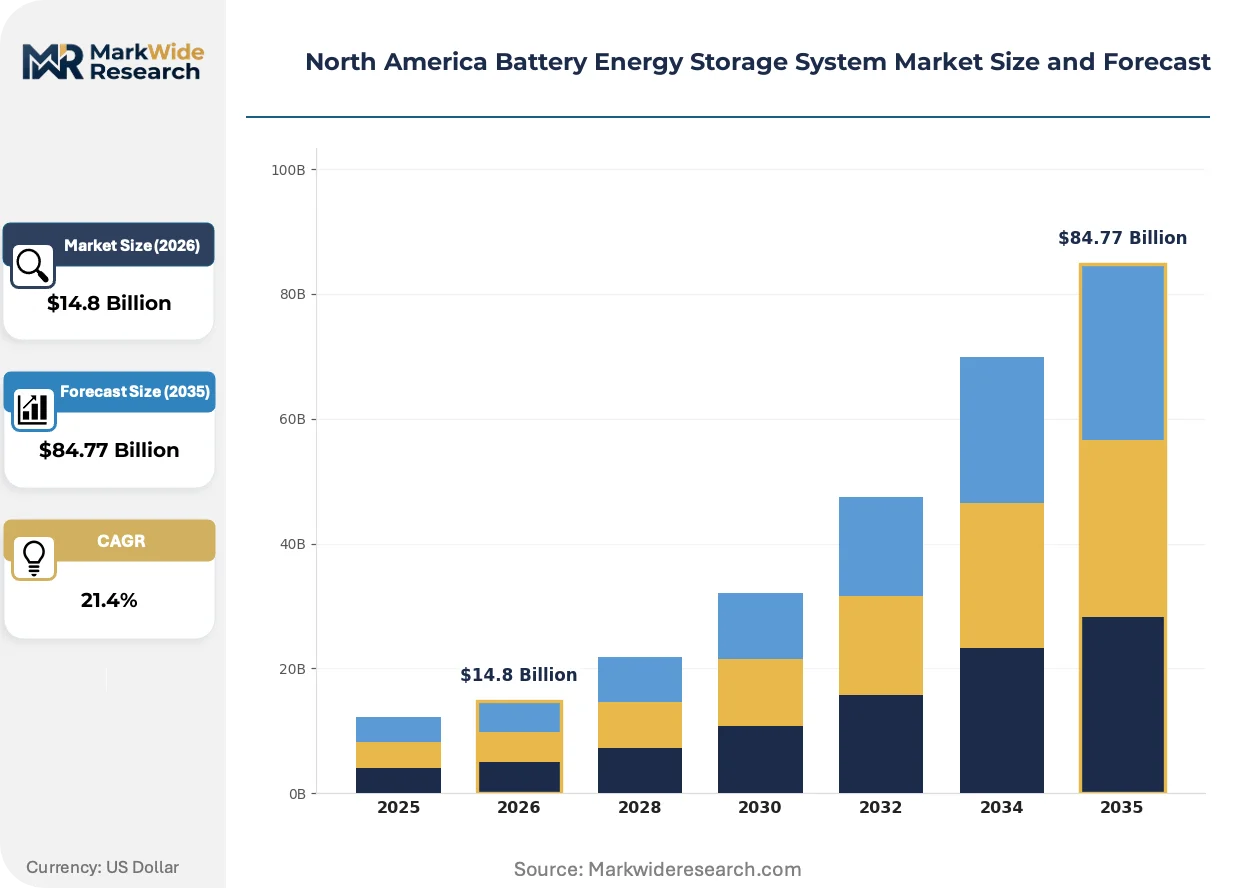
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $84.77 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lead Acid, Flow, Sodium Sulfur, Nickel Cadmium, Zinc Air Application: Grid Stabilization, Renewable Integration, Peak Shaving, Backup Power, Microgrid Support, Frequency Regulation End User: Utility Companies, Commercial Enterprises, Residential Buildings, Data Centers, Telecom Operators, Defense Facilities Deployment Type: Utility-Scale, Commercial-Scale, Residential-Scale, Islanded, Networked, Hybrid Systems |
| Companies Covered | Samsung SDI Co Ltd, AES Corporation, Tesla Inc, Saft America Inc, GE Vernova, LG Energy Solution Ltd, Fluence Energy Inc, Sunverge Energy LLC, BYD Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Battery Energy Storage System Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from deploying BESS for basic energy arbitrage to using sophisticated software and controls for providing complex, high-value grid services. This transition is unlocking new revenue streams and changing asset management strategies.
Battery energy management software provides the critical real-time monitoring, state-of-charge control, and thermal management for BESS assets. Utility operators and independent power producers are rapidly adopting these platforms to ensure asset safety and optimize operational performance. This advanced control functionality is converging with AI-powered energy trading software, enabling automated bidding and dispatch into complex wholesale electricity markets.
In the United States, Federal Energy Regulatory Commission (FERC) Order 2222 directly facilitates market expansion by allowing aggregations of distributed energy resources (DERs) to compete in wholesale energy markets. This policy change creates a viable business case for smaller, behind-the-meter battery systems. The commercial and industrial segment is responding by partnering with DER aggregators to form virtual power plants (VPPs), especially in markets like the PJM Interconnection and CAISO.
A notable shift in asset ownership models is occurring as utilities move from direct procurement to utilizing Energy Storage-as-a-Service (ESaaS) agreements. This model transfers the upfront capital investment and operational risk to a third-party developer, which receives payments based on the storage system's availability and performance. The trend is most visible in the US utility-scale segment, where regulated entities can secure grid services without impacting their balance sheets.
North America Battery Energy Storage System Market Segmentation
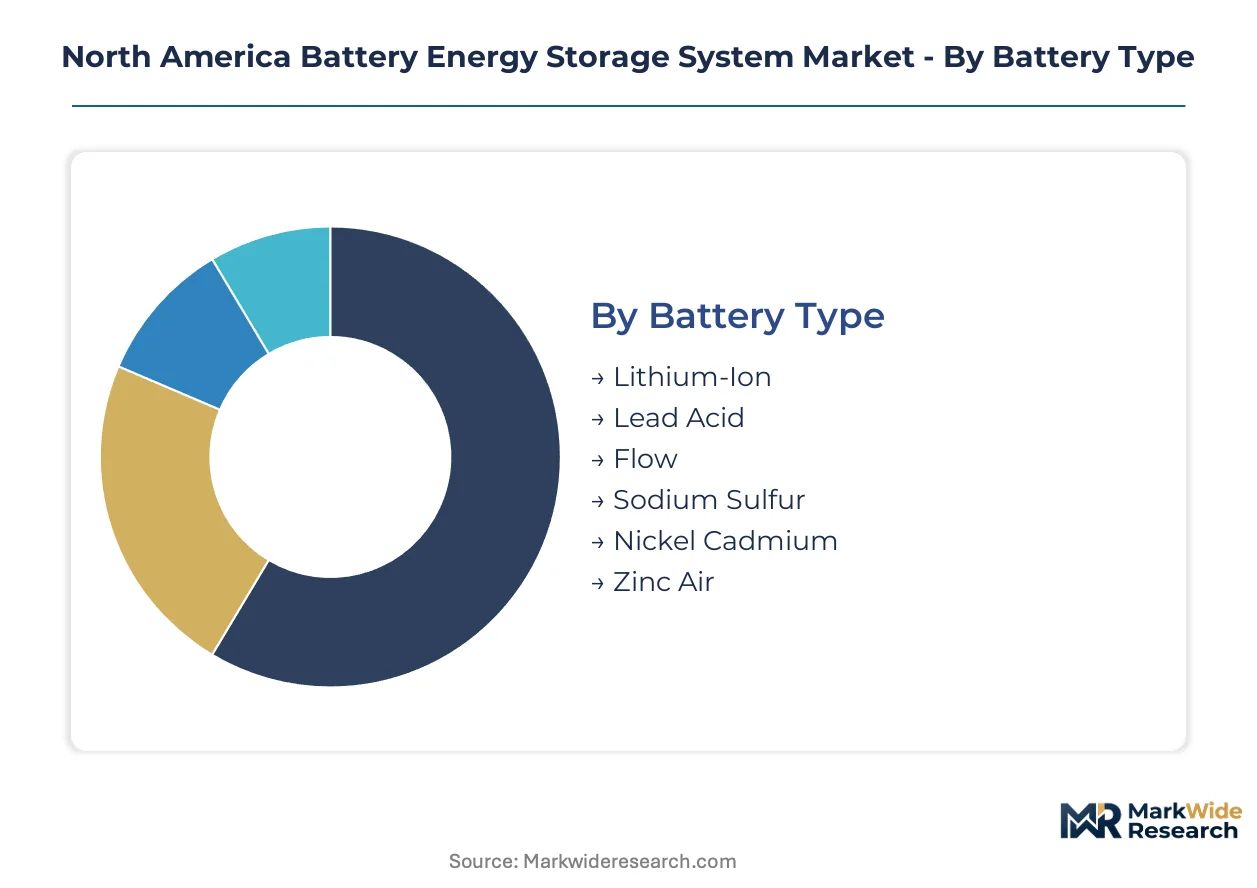
The North America battery energy storage system market is highly segmented, reflecting the diverse technological options, application requirements, and end-user demands across the region. Understanding these distinct segments provides clarity on where investment capital flows and where regulatory frameworks exert the most influence on project development.
Battery Type:
The North American battery energy storage market categorizes battery types by their specific safety and performance certifications required for grid integration across US states and Canadian provinces.
- Lithium-Ion:These batteries utilize lithium ions as the primary charge carriers, offering high energy density and long cycle life for various applications. Demand concentrates in utility-scale projects and electric vehicle integration, driven by continuous cost reductions and performance improvements.
- Flow:Flow batteries store energy in external electrolyte tanks, allowing for independent scaling of power and energy capacity, making them suitable for long-duration applications. Demand is emerging for these systems in grid-scale deployments in Texas and California, where extended discharge times are increasingly valuable.
- Lead Acid:These are mature, cost-effective battery technologies often used for backup power and smaller, off-grid systems in remote Canadian communities.
- Sodium Sulfur:High-temperature batteries offering long discharge durations, primarily deployed in large-scale utility applications for grid stability in states like New York.
- Nickel Cadmium:Robust and reliable batteries suitable for harsh environments and critical backup power in industrial facilities across the US.
- Zinc Air:These batteries use zinc and oxygen, offering high theoretical energy density for potential long-duration storage, with pilot projects appearing in remote Alaskan communities.
Lithium-Ion sits at the top of the volume ranking, with Flow batteries climbing the fastest.
Application:
The application segmentation reflects the diverse operational needs addressed by battery energy storage systems across the North American power grid.
- Grid Stabilization:These applications involve maintaining grid frequency and voltage within acceptable limits, preventing blackouts and ensuring reliable power delivery. Demand is strong across the PJM Interconnection and ERCOT markets, driven by Federal Energy Regulatory Commission (FERC) orders facilitating market participation.
- Renewable Integration:BESS manages the intermittency of solar and wind generation, storing surplus energy and discharging it when needed to smooth power output. This application sees significant demand in California and Texas, supported by state-level renewable energy mandates.
- Peak Shaving:Energy storage systems discharge during periods of high electricity demand, reducing reliance on expensive peaker plants and lowering utility bills for commercial users in Ontario.
- Backup Power:Provides emergency power during grid outages, ensuring continuous operation for critical facilities like hospitals and data centers across the United States.
- Microgrid Support:BESS enables microgrids to operate independently from the main grid, enhancing resilience for military bases and remote communities in Canada.
- Frequency Regulation:Rapidly injects or absorbs power to maintain grid frequency, a critical ancillary service for grid operators in areas like New England.
Grid Stabilization applications currently dominate, while Microgrid Support is expanding most quickly.
End User:
End-user categories delineate the primary beneficiaries and operators of battery energy storage systems, each with distinct procurement patterns and operational requirements.
- Utility Companies:These entities deploy large-scale BESS for grid-level services, including transmission and distribution deferral, and wholesale market participation. Regulated utilities in states like California and New York are primary drivers, often utilizing Energy Storage-as-a-Service models.
- Commercial Enterprises:Businesses use BESS to reduce demand charges, participate in demand response programs, and ensure power reliability for their operations. Industrial facilities in the US Midwest and Canadian manufacturing sectors are key adopters, seeking operational cost savings.
- Residential Buildings:Homeowners integrate battery storage with rooftop solar to maximize self-consumption and provide backup power, particularly in regions with high electricity rates or frequent outages like California.
- Data Centers:These facilities require uninterrupted power supply for critical operations, making BESS an essential component for enhancing reliability and reducing reliance on traditional diesel generators in Virginia and Texas.
- Telecom Operators:BESS provides reliable backup power for cell towers and network infrastructure, ensuring continuous communication services, especially in remote or storm-prone areas across North America.
- Defense Facilities:Military bases and government installations deploy BESS for energy resilience, microgrid support, and critical infrastructure protection, often under specific federal procurement standards in the United States.
Utility Companies represent the largest end-user segment, with Data Centers gaining share fastest due to reliability demands.
Deployment Type:
Deployment types vary significantly in their scale and architectural complexity, influencing project size and required regulatory compliance across North America.
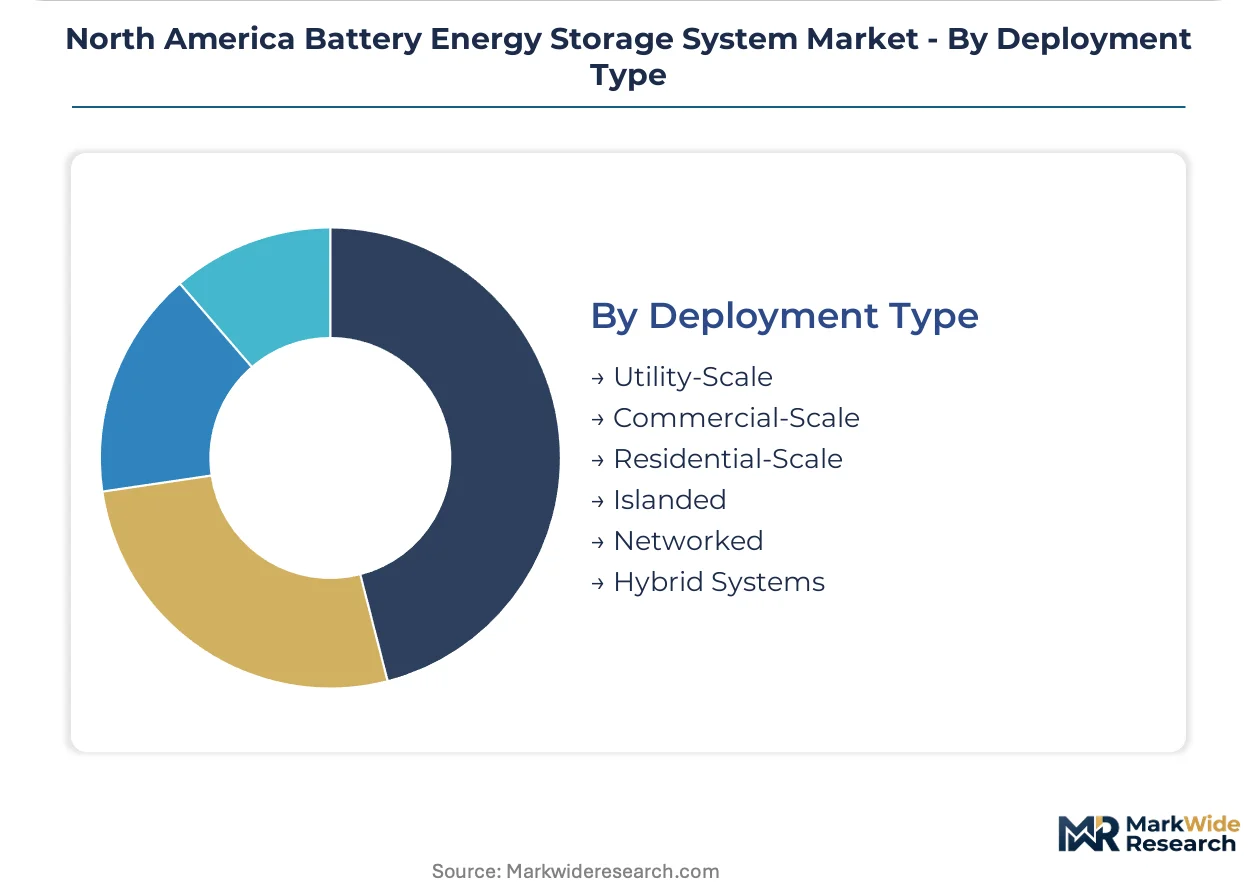
- Utility-Scale:These are large, centralized battery systems connected directly to the transmission or distribution grid, typically exceeding 10 MW in capacity. Projects in California and Texas dominate this segment, driven by renewable integration and grid modernization goals.
- Commercial-Scale:BESS deployed at commercial and industrial sites, usually ranging from 100 kW to several megawatts, primarily for demand charge management and backup power. Businesses in urban centers like Toronto and Chicago are key implementers.
- Residential-Scale:Smaller systems, typically under 50 kW, installed at individual homes, often paired with rooftop solar for energy independence and resilience in regions like Arizona.
- Islanded:Systems designed to operate independently from the main grid, providing power to remote communities, industrial sites, or military bases in northern Canada.
- Networked:Multiple distributed energy resources, including BESS, aggregated and managed as a single entity to provide grid services, common in virtual power plant initiatives in the PJM territory.
- Hybrid Systems:Combinations of BESS with other generation sources, such as solar-plus-storage or gas turbine-plus-storage, optimizing energy delivery and grid stability in markets like Alberta.
Utility-Scale projects account for the largest installed capacity, while Hybrid Systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives significant battery energy storage system deployment through federal tax credits, Canada's market expansion is propelled by provincial clean energy mandates. Both nations prioritize grid modernization and renewable energy integration, albeit with distinct regulatory frameworks. This regional dynamic shapes investment patterns and technology adoption across North America.
United States
The United States market experiences robust demand for grid stabilization and renewable integration applications. The Inflation Reduction Act's Investment Tax Credits directly subsidize project costs, accelerating deployment. Key utility-scale projects concentrate in states like California and Texas, supporting large-scale wind and solar integration.
Canada
Canadian provinces like Ontario and Alberta are expanding their clean energy programs, creating new geographic markets for BESS. Provincial clean energy mandates drive significant BESS deployment to support grid reliability and decarbonization goals. Remote communities in northern Canada increasingly utilize microgrid support for energy independence.
Mexico
Mexico's energy storage market is emerging, primarily driven by industrial demand for backup power and grid stability. The country's energy sector reforms aim to integrate more renewable sources, necessitating storage solutions. Industrial zones near Monterrey and Mexico City are exploring BESS for demand charge management and operational resilience.
California
California leads the US in renewable energy integration, creating substantial demand for large-scale battery storage to manage intermittency. The state's ambitious clean energy mandates and utility procurement targets heavily influence BESS project development. The CAISO market actively facilitates BESS participation, optimizing grid services and energy arbitrage.
Texas
Texas experiences strong BESS demand driven by its rapidly expanding wind and solar generation capacity. The ERCOT market design encourages merchant energy storage projects, enhancing grid reliability. Large-scale utility projects near Houston and Dallas are critical for managing peak loads and preventing grid congestion.
North America Battery Energy Storage System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists to capture market share in North America's battery energy storage system sector. The market structure features both large industrial players offering integrated solutions and agile technology firms concentrating on specific BESS components or software. Strategic archetypes include vertically integrated developers, technology providers, and project owner-operators. Competitive moves often involve strategic partnerships to bridge technology gaps and significant capacity expansion to meet escalating demand.
Technology providers like Tesla Inc. occupy a significant position in the residential and commercial segments, leveraging their integrated hardware and software ecosystems for energy management. Fluence Energy Inc., a joint venture, represents a key player in utility-scale deployment, consistently anchoring large-scale project contracts across the region. Furthermore, AES Corporation exemplifies the owner-operator archetype, influencing procurement standards and project development across its extensive portfolio in the United States and Latin America.
| Leading Market Players |
|---|
| Samsung SDI Co Ltd |
| AES Corporation |
| Tesla Inc |
| Saft America Inc |
| GE Vernova |
| LG Energy Solution Ltd |
| Fluence Energy Inc |
| Sunverge Energy LLC |
| BYD Company Limited |
Cost & Logistics Intelligence
Lithium carbonate spot prices directly influence battery cell manufacturing costs, which then cascade through the BESS supply chain into project-level pricing tiers. This commodity volatility creates a challenging environment for long-term contract pricing.
Pricing Analysis
Capacity additions in Asian manufacturing hubs are reshaping price floors for lithium-ion battery cells. The dominant pricing model for utility-scale BESS projects is contract-based long-term offtake, often hybrid with performance-based incentives. Price differentiation stems from energy density, cycle life, and bundled software optimization services. Pricing softness reflects continuous technology maturation and increased manufacturing scale, creating higher price sensitivity among commercial enterprises compared to utility companies prioritizing reliability.
Supply Chain Analysis
Workforce availability in key battery manufacturing geographies like China, South Korea, and Japan underpins the global supply chain. The BESS industry sources critical inputs such as lithium, cobalt, and power conversion systems from a concentrated base. Geopolitical risks and raw material price volatility represent significant structural risks for developers. Distribution runs through direct sales channels for utility-scale projects and through specialized integrators for commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America battery energy storage system market is evolving into a late-cycle quality story, driven by a demand-shift toward premium specifications for complex grid services. Asset owners increasingly seek integrated software for optimized dispatch and revenue maximization.
For Market Incumbents: Deepen vertical integration into power conversion system manufacturing to mitigate component sourcing volatility. Secure long-term raw material contracts for lithium and cobalt, reducing exposure to commodity price risks. This strategy counters the threat of supply chain concentration and grid interconnection delays. Invest in R&D for alternative, non-lithium-ion chemistries and advanced software platforms. For New Entrants and Emerging Players: Advanced software and optimization services present a technology-first wedge into the market, particularly for maximizing asset revenue. Target the commercial and industrial segment for peak shaving and demand response programs, where underpenetration remains significant. Develop specialized solutions for microgrid support in remote Canadian communities. Offer Energy Storage-as-a-Service (ESaaS) models to reduce upfront capital costs for customers. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized software capabilities and long-duration storage technologies offer strategic advantages. The market presents a compelling long-term viability story over the next 5-10 years, given its critical infrastructure role. Target acquisition archetypes include specialized software firms and developers of alternative battery chemistries. The signal to watch is the rate of grid interconnection queue clearances across the United States.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for PCS Manufacturing | This move mitigates component sourcing risks and enhances supply chain resilience for developers. |
| Investment in Long-Duration Storage R&D | This initiative unlocks new revenue streams for applications requiring 8+ hours of discharge. |
| AI-Powered Energy Trading Software Development | This improves dispatch optimization, maximizing asset revenue in complex wholesale markets. |
| Strategic Partnerships for Grid Interconnection | This accelerates project commissioning by navigating complex regulatory and technical hurdles. |
| Energy Storage-as-a-Service (ESaaS) Model Adoption | This lowers upfront capital barriers for commercial and industrial customers, expanding market access. |
Research Approach
Coverage spans North America, including the United States, Canada, and Mexico, with primary inputs from each key market. The analysis incorporates insights from utility planning officers, EPC contractors, battery manufacturers, and energy software developers. Secondary validation draws from EIA data, FERC filings, IEA reports, and provincial energy mandates. This approach enables robust bottom-up and top-down triangulation of market data.
Rate-of-change decomposition underpins the quantitative forecast, modeling market shifts across the analysis window. Segmentation dimensions include battery type, application, end-user, deployment type, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) derive from historical trends and projected market drivers. Key forecast inputs include US Inflation Reduction Act deployment rates and grid interconnection queue processing times.
The model holds under current regulatory environments and stable raw material supply conditions; deviation in geopolitical stability or US Inflation Reduction Act policy would shift projections. Forecasts reflect documented assumptions regarding technology maturation and market adoption, though supply chain disruptions or unforeseen economic downturns represent specific risk factors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Smart Battery Maintainer Market
Battery Management System
Battery Management System (BMS) Market
Battery Management System
Energy Storage Market
Battery Management System
North America Battery Management System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
North America Energy Storage Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
Distributed Energy Storage System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market