
 Marine Energy Storage System Market | 2026-2036
Marine Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Energy Storage System Market Insights
Modular battery-pack configurations is expanding buyer choice in the marine energy storage sector, allowing shipyards to scale capacity without redesigning hull architecture. Corvus Energy leverages its vertical integration into cell manufacturing to sustain cost advantages in large ferry deployments. Wärtsilä anchors its position through system-level integration expertise that spans power electronics and vessel automation. ABB competes on channel control, securing fleet-wide service contracts that lock in recurring revenue across installed bases.
A marine energy storage system comprises electrochemical cells, thermal management hardware, and power conversion electronics engineered for salt-air corrosion resistance, vibration tolerance, and IEC 62619 safety compliance, serving to store and dispatch electrical power aboard vessels and offshore structures. Electrochemical storage dominates current installations due to lithium-ion energy density advantages, while mechanical storage retains niche relevance in vessels requiring extreme cycle durability for dynamic positioning. Shipping applications lead volume demand, though renewable energy systems tied to offshore wind represent the fastest-growing end-user category as hybrid service vessels proliferate.
The International Maritime Organization's carbon intensity regulations and the EU MRV monitoring framework are tightening operational efficiency standards, forcing fleet operators to document emissions reductions that battery-hybrid configurations directly address. The US Coast Guard and classification societies including DNV are evolving type-approval protocols for battery spaces aboard passenger vessels, extending certification timelines but raising barriers against unproven suppliers. Stakeholders must monitor how port infrastructure electrification timelines synchronize with vessel retrofit cycles to avoid stranded asset risk in hybrid fleets.
Market Dynamics
Vessel electrification mandates are compressing retrofit timelines across commercial fleets, forcing shipyards to integrate battery systems during standard dry-dock cycles rather than waiting for end-of-life replacements.
Growth Catalysts
- IMO Carbon Intensity Indicators:The International Maritime Organization's mandatory efficiency ratings are compelling container lines to install hybrid configurations to avoid commercial penalties in key trade lanes.
- Fjord transit restrictions:Norway's zero-emission requirements for ferry routes through UNESCO-protected waterways are generating concentrated vessel replacement demand.
- Offshore wind service vessels:Turbine maintenance fleets require dynamic positioning endurance that battery-hybrid systems deliver more efficiently than conventional diesel-electric arrangements.
Market Restraints
- Lithium supply concentration:Cathode material processing capacity clusters in China, exposing European and North American system integrators to input cost volatility and geopolitical supply risk.
- DNV battery space certification:The classification society's evolving fire-safety protocols for passenger vessels extend type-approval timelines by 8-14 months, freezing procurement decisions.
- Mechanical storage persistence:Flywheel systems retain niche relevance in offshore drilling units requiring extreme cycle durability, limiting electrochemical capture in this sub-segment.
Strategic Opportunities
- EU Green Deal maritime funding:The European Commission's dedicated vessel decarbonization facility offers concessional financing for battery-hybrid retrofits in Mediterranean short-sea shipping.
- Port electrification synchronization:Shore power infrastructure rollouts in Rotterdam and Hamburg create fleet-wide upgrade opportunities when paired with onboard storage for peak shaving.
- Autonomous vessel integration:Unmanned surface vehicle developers require compact, fault-tolerant energy architectures that favor solid-state battery chemistries over conventional lithium-ion.
Industry Challenges
- Marine electrical engineering talent scarcity:Shipyards lack sufficient technicians certified for high-voltage DC system installation, constraining fleet-wide deployment velocity.
- IEC 62619 testing backlog:Safety validation queues at accredited laboratories are stretching product qualification timelines, delaying revenue recognition for system suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Energy Storage System Market |
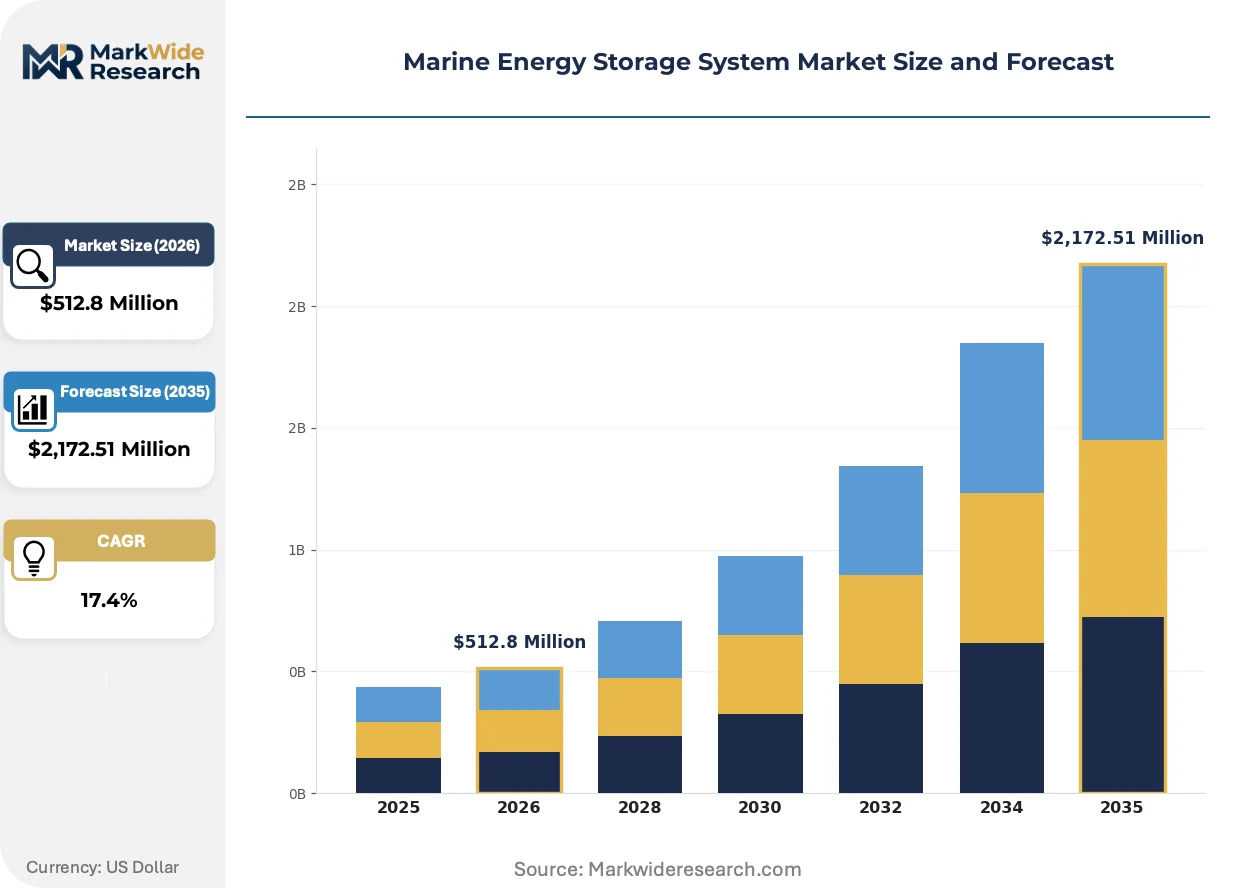
| Market Size in 2026 | $512.8 Million |
| Market Size in 2035 | $2,172.51 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batteries, Flywheels, Supercapacitors, Compressed Air End User: Shipping, Offshore Platforms, Renewable Energy Systems, Aquaculture Application: Energy Management, Backup Power, Load Shifting, Frequency Regulation Technology: Mechanical Storage, Electrochemical Storage, Thermal Storage, Chemical Storage |
| Companies Covered | Corvus Energy, Wärtsilä, ABB, Siemens Energy, Leclanché, Samsung SDI, Rolls-Royce, PATHION Inc., EST-Floattech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Energy Storage System Market Trends and Innovations
Battery system architectures are converging around modular platforms that decouple cell chemistry from pack geometry, enabling faster adaptation to evolving safety standards and vessel-specific spatial constraints.
Lithium iron phosphate chemistry is consolidating its position in passenger ferry applications where thermal stability outweighs energy density requirements. Scandinavian operators are specifying these configurations for routes with frequent high-power charging cycles. The technology is consolidating supplier margins by reducing thermal management system complexity and warranty reserve requirements.
The EU MRV monitoring framework now mandates verified emissions reporting for vessels above 5,000 gross tonnage calling at European ports. Fleet operators must install continuous monitoring equipment that battery-hybrid systems can interface with directly. Container lines serving Asia-Europe trades are responding by accelerating retrofit schedules to avoid commercial disadvantage in charter markets.
Service contract unbundling is fragmenting traditional supplier relationships in the offshore support vessel segment. Charterers are separating energy system maintenance from propulsion service agreements, creating openings for specialized battery service providers. This pattern is most visible in the North Sea, where platform supply vessel operators seek operational flexibility through multi-vendor arrangements.
Marine Energy Storage System Market Segmentation
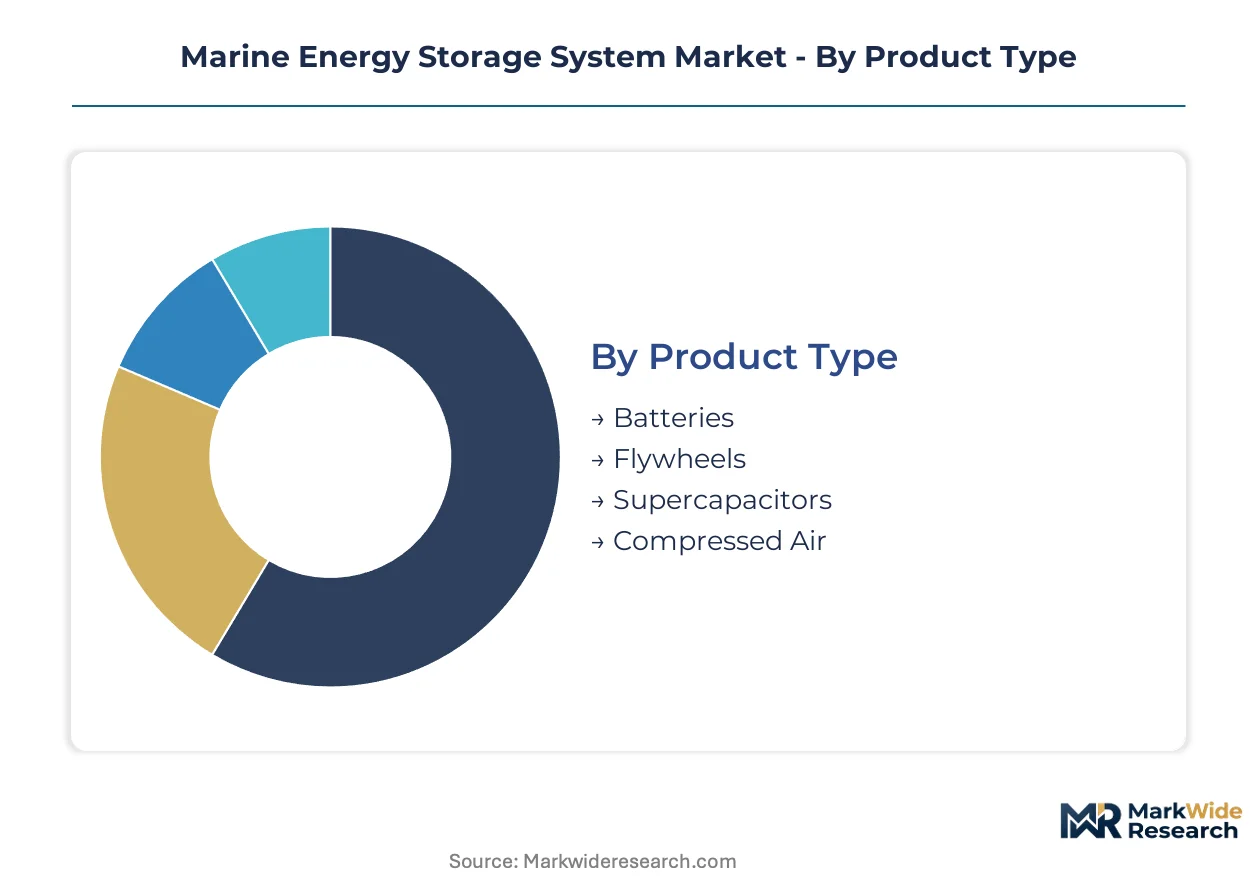
Segmentation in marine energy storage reveals where capital deployment concentrates and which configurations match vessel-specific operational profiles. Each dimension—product chemistry, end-use environment, functional application, and underlying technology—carries distinct certification burdens and integration complexity that shape procurement decisions.
Product Type:
Batteries command the steepest upfront capital outlays due to cell manufacturing scale, thermal management infrastructure, and IEC 62619 compliance testing.
- Batteries:Lithium-ion configurations dominate installed base with lithium iron phosphate chemistry consolidating in passenger ferry applications where thermal stability outweighs energy density requirements. Norwegian fjord transit restrictions and ferry fleet renewal programs are generating concentrated procurement for these systems.
- Flywheels:Kinetic energy storage systems deliver extreme cycle durability for dynamic positioning operations in offshore drilling units. Mechanical storage retains niche relevance where rapid charge-discharge cycles exceed electrochemical tolerance, limiting battery capture in this sub-segment.
- Supercapacitors:Ultracapacitor modules provide burst power for winch operations and crane loads on platform supply vessels.
- Compressed Air:CAES systems remain experimental in marine contexts with limited commercial deployments to date.
Batteries absorb the bulk of installed capacity; supercapacitors are expanding most quickly in hybrid peak-shaving configurations.
End User:
Offshore platforms require the most complex integration engineering due to salt-air corrosion resistance specifications and hazardous area classifications.
- Shipping:Container lines and short-sea operators face compressed retrofit timelines as IMO Carbon Intensity Indicators threaten commercial penalties in key trade lanes. The EU MRV monitoring framework mandates verified emissions reporting that battery-hybrid configurations directly address.
- Offshore Platforms:Drilling units and production facilities deploy storage for load leveling and emergency backup. DNV battery space certification protocols extend type-approval timelines by 8-14 months, freezing procurement decisions for this capital-intensive segment.
- Renewable Energy Systems:Offshore wind service vessels represent the fastest-growing end-user category as turbine maintenance fleets require dynamic positioning endurance.
- Aquaculture:Fish farm operations in Norway and Scotland adopt battery-hybrid workboats to meet local emissions restrictions.
Shipping retains the largest installed base; renewable energy systems tied to offshore wind development are gaining share fastest.
Application:
Frequency regulation applications demand the most sophisticated power electronics due to real-time grid synchronization requirements.
- Energy Management:Integrated vessel power systems optimize generator loading and fuel consumption across operational profiles. Scandinavian operators specify these configurations for routes with frequent high-power charging cycles.
- Backup Power:Redundant storage arrays ensure propulsion and hotel load continuity during primary power failures. Classification societies including DNV are evolving type-approval protocols for battery spaces aboard passenger vessels serving this critical function.
- Load Shifting:Storage arbitrage between low-demand charging and peak operational discharge.
- Frequency Regulation:Grid-forming inverters maintain voltage stability in islanded microgrids.
Energy management captures dominant deployment volume; frequency regulation shows the steepest expansion trajectory as shore power integration advances.
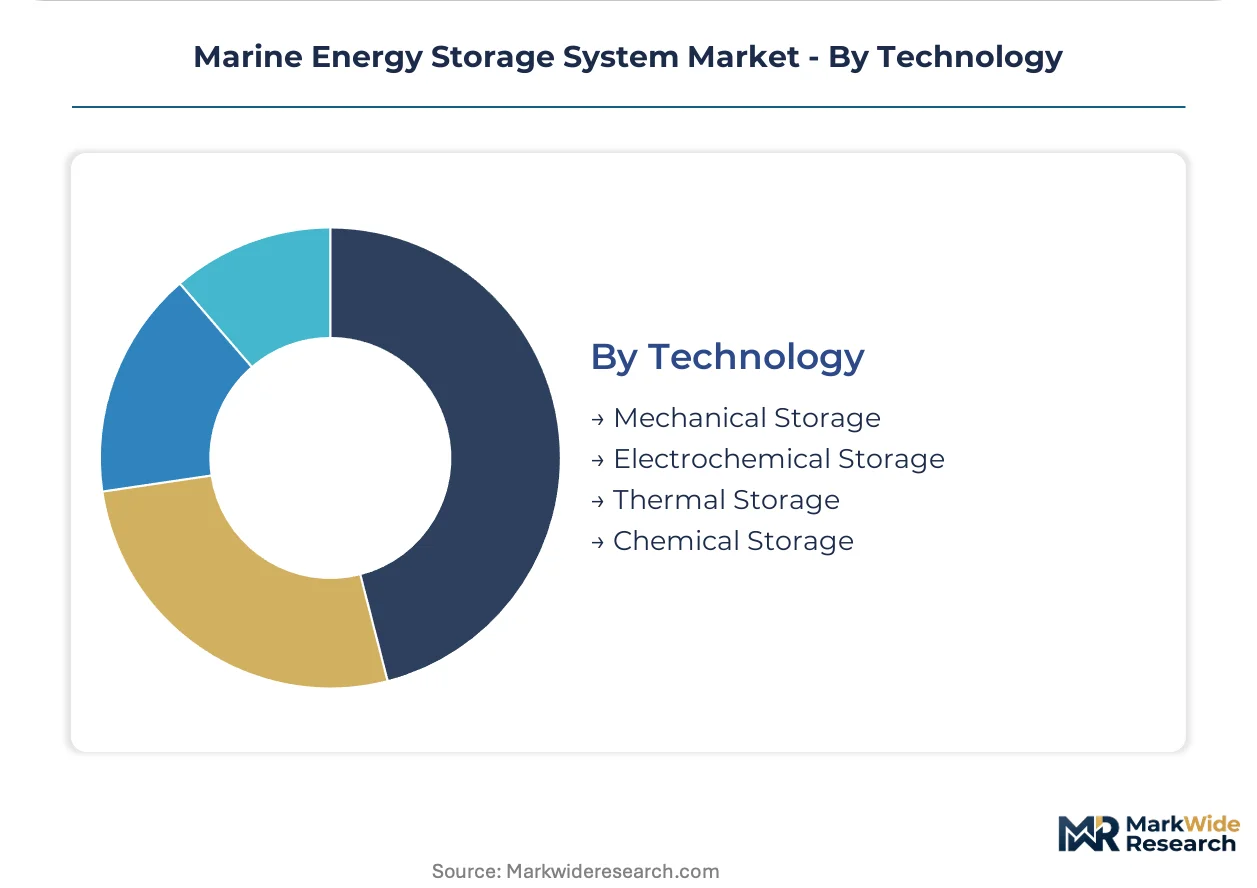
Technology:
Electrochemical storage requires the most extensive safety engineering due to thermal runaway risks in confined marine spaces.
- Electrochemical Storage:Lithium-ion systems leverage energy density advantages for volume-constrained vessel installations. Lithium supply concentration in China exposes European and North American integrators to input cost volatility and geopolitical supply risk.
- Mechanical Storage:Flywheel and compressed air systems eliminate chemical hazard concerns. These configurations retain relevance in offshore drilling units where cycle durability requirements exceed electrochemical capabilities.
- Thermal Storage:Phase-change materials capture waste heat for auxiliary power generation.
- Chemical Storage:Hydrogen and synthetic fuel carriers remain pre-commercial for marine propulsion.
Electrochemical storage dominates current installations; thermal storage is climbing the fastest in waste heat recovery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China and South Korea while deployment concentrates in European waters. Norway's fjord transit restrictions and Germany's port electrification programs are pulling systems toward North Sea installations faster than Asian yards can expand cell output.
Norway
Ferry fleet renewal programs and UNESCO-protected waterway restrictions are generating concentrated procurement for lithium iron phosphate systems. The Norwegian Maritime Authority enforces zero-emission mandates on specific routes. Bergen and Stavanger anchor the Nordic installation cluster where hybrid vessel retrofits dominate shipyard order books.
Germany
Port electrification timelines in Hamburg and Bremerhaven are synchronizing with container line retrofit cycles. The EU Green Deal maritime funding facility channels concessional financing through KfW development bank. The Elbe River corridor hosts the densest concentration of shore power integration projects pairing onboard storage with quayside infrastructure.
China
Cathode material processing capacity and cell manufacturing scale position domestic yards as cost leaders for export markets. MIIT dual carbon goals and GB standards for marine electrical safety shape product certification requirements. The Yangtze River Delta shipbuilding cluster dominates battery system assembly for international ferry operators.
United States
Offshore wind lease auctions in the Atlantic are spawning demand for hybrid service vessels requiring dynamic positioning endurance. The US Coast Guard evolves type-approval protocols for battery spaces aboard passenger vessels. The Port of Long Beach and Los Angeles corridor represents the most advanced shore power deployment where peak-shaving storage commands premium pricing.
South Korea
Battery cell manufacturing scale and shipyard integration capabilities support container line hybrid retrofits serving Asia-Europe trades. METI-aligned efficiency standards and KSA maritime safety protocols govern product qualification. The Ulsan-Busan industrial corridor concentrates both cell output and vessel construction where system-level integration expertise commands margin premiums.
Marine Energy Storage System Market Competitive Landscape
The competitive structure tilts toward system integrators with captive cell supply or classification society relationships. Consolidation around three to five full-stack providers has compressed the viable vendor base for large ferry and offshore platform deployments. Two archetypes dominate: vertically integrated battery specialists and diversified marine propulsion conglomerates. Capacity expansion and strategic partnerships with shipyards constitute the primary competitive vectors.
Among Nordic system integrators, Corvus Energy and Wärtsilä occupy positions defined by cell manufacturing control and power electronics expertise respectively. ABB anchors the Swiss-German tier through channel relationships securing fleet-wide service contracts. These three exemplify how competitive positioning in marine energy storage now depends on upstream supply security and downstream service lock-in rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Corvus Energy |
| Wärtsilä |
| ABB |
| Siemens Energy |
| Leclanché |
| Samsung SDI |
| Rolls-Royce |
| PATHION Inc. |
| EST-Floattech |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between IEC 62619-compliant systems and non-marine-rated battery packs manifests in pricing spreads exceeding thirty percent and supply chain segregation between DNV-validated integrators and industrial battery assemblers lacking maritime type-approval. This divergence concentrates procurement authority with classification society-certified vendors while channeling volume buyers toward captive cell arrangements that compress landed costs.
Pricing Analysis
Margin tightening in standard-tier ferry retrofits reflects lithium iron phosphate cell commoditization and Chinese cathode material oversupply. Project-based contract pricing dominates large vessel deployments, with price differentiation anchored in DNV certification status and thermal management system complexity. Cost-down pressure accelerates as Norwegian operators consolidate fleet procurement through framework agreements. Charter-sensitive container lines exhibit highest price sensitivity; offshore drilling contractors prioritize cycle durability over unit economics.
Supply Chain Analysis
DNV type-approval queues stretching eight to fourteen months gate supplier market access and concentrate order books with pre-qualified integrators. Cathode material processing clusters in China, cell manufacturing scales in South Korea, and system integration concentrates in Norway and Germany. Raw material dependencies span lithium carbonate, nickel sulfate, and copper foil for busbar assemblies. Single-source vulnerability in Chinese lithium hydroxide refining exposes European assemblers to geopolitical supply disruption. Distribution runs through shipyard-direct contracts and fleet operator framework agreements, bypassing traditional marine equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
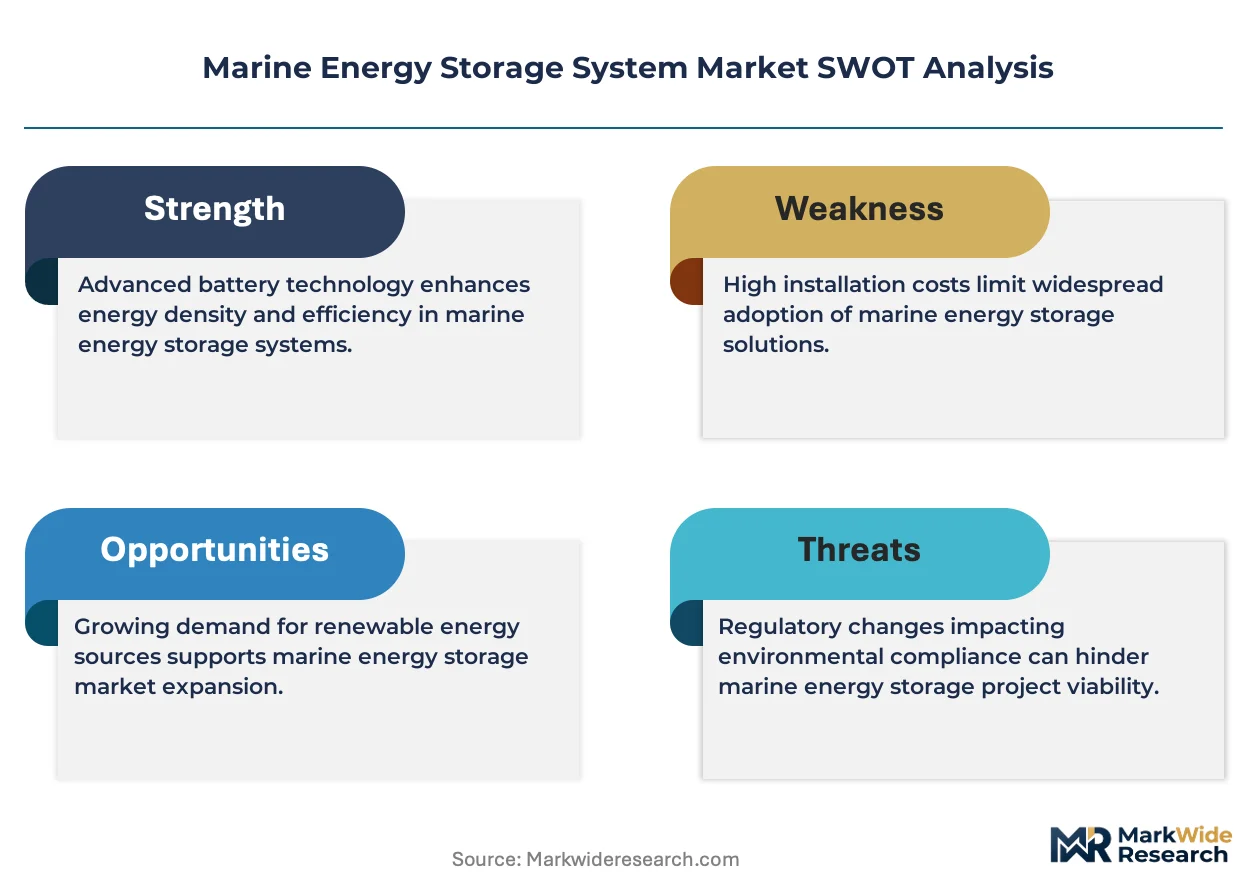
Vertical integration into cell manufacturing and captive service network deployment constitute the primary levers shaping competitive survival in marine energy storage, with upstream control over lithium iron phosphate supply separating margin-sustainable integrators from assembly-dependent competitors.
For Market Incumbents: Hedge against solid-state battery disruption by securing pilot installation partnerships with autonomous vessel developers and pre-qualifying next-generation chemistries through DNV accelerated approval tracks. Deepen backward integration into thermal management hardware to defend system-level margins against modular pack competitors. Lock in ten-year service contracts with Scandinavian ferry operators before charterers unbundle maintenance agreements. For New Entrants and Emerging Players: The premium-to-economy pricing gap in offshore platform backup power systems creates entry space for flywheel-battery hybrid configurations targeting cycle durability requirements. Concentrate development resources on aquaculture workboat electrification in Scotland and Chile, where emissions restrictions outpace incumbent service coverage. Pursue channel partnerships with regional shipyards lacking in-house electrical engineering capability rather than competing for direct fleet operator procurement. For Investors and Strategic Acquirers: Re-rating potential sits with system integrators possessing captive cell supply and DNV pre-approval status given accelerating IMO regulatory enforcement. Long-term viability favors full-stack providers over pack assemblers across the five-to-ten-year technology transition window. Target acquisition profiles emphasize thermal management engineering teams and classification society relationships over pure manufacturing scale. The signal to watch is IEC 62619 testing laboratory capacity expansion announcements as a lead indicator of qualification bottleneck easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Captive lithium iron phosphate supply insulates Corvus Energy and Wärtsilä from cathode material volatility. |
| DNV Accelerated Type-Approval Pathway | Pre-qualified battery space designs compress procurement decision timelines for Norwegian ferry operators. |
| Shore Power Infrastructure Partnership | Rotterdam and Hamburg port electrification synchronizes with onboard storage deployment for peak shaving. |
| Autonomous Vessel System Integration | Solid-state battery architectures address fault-tolerance requirements for unmanned surface vehicle developers. |
| Fleet-Wide Service Contract Unbundling | Specialized battery maintenance providers capture margin from traditional propulsion service agreements in the North Sea. |
Research Methodology
Independent corroboration across vessel operator interviews, shipyard procurement directors, and classification society engineering heads underwrites the qualitative findings in this study. Primary fieldwork engaged marine electrical system integrators, ferry fleet managers, offshore platform power engineers, and port authority infrastructure planners across Norway, Germany, and China. Secondary validation drew from DNV type-approval registries, IEC 62619 testing laboratory disclosures, EU MRV emissions monitoring databases, and IMO regulatory amendment tracking. Bottom-up installation data triangulated against top-down market sizing from cathode material trade flows and shipyard order book analysis.
Rate-of-change decomposition across the projection horizon separates volume growth from value expansion through chemistry-mix shifts and system integration complexity premiums. Segmentation modeling spans product type, end-user environment, functional application, and underlying storage technology, with additional disaggregation by vessel class and regulatory compliance tier. CAGRs derive from fitted growth curves against historical installation trajectories and policy-mandated fleet renewal schedules. Key forecast inputs include fjord transit restriction enforcement timelines and offshore wind lease auction pacing.
Inputs from DNV certification queues and shipyard capacity utilization data were available through the study window; gaps in proprietary cell manufacturing cost structures introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding IMO Carbon Intensity Indicator enforcement stringency and lithium supply chain geographic diversification. A model refresh is warranted upon material change in EU Green Deal maritime funding allocation or solid-state battery commercialization timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Solar Storage System Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Power Bank Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Water Electrolysis Machine Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
South America Energy Storage Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market