
 United Kingdom Energy Storage Systems Market | 2026-2036
United Kingdom Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Energy Storage Systems Market Analytics
Market Context with Strategic Players
Aftermarket service revenue for grid-connected battery assets is rewriting how vendors capture lifetime value from hardware deployments. Tesla leverages its vertically integrated energy software stack to sustain recurring revenue streams across utility-scale installations. ABB competes through its power electronics specialization and grid integration expertise in frequency regulation contracts. LG Chem anchors its position via advanced lithium-ion cell chemistry leadership and manufacturing scale for European utility buyers.
Technical Definition and Structural Segments
Energy storage systems encompass electrochemical, mechanical, and thermal technologies designed to capture electrical energy for deferred discharge, with lithium-ion battery systems typically operating at 85-95% round-trip efficiency and 10-20 year operational lifespans depending on cycling intensity. Their primary commercial purpose centers on temporal arbitrage, grid stability services, and renewable generation firming for power system operators. Battery Energy Storage dominates current deployment volumes across utility and commercial segments, while Redox Flow technology occupies emerging niches in long-duration applications where daily cycling exceeds four hours. Residential end-user adoption remains structurally constrained by retrofit costs and distributed network access rules, though commercial peak shaving applications are expanding fastest among C&I buyers seeking demand charge reduction.
Regulatory Framework and Forward Outlook
Ofgem, the national energy regulator, shapes market access through its network charging reform consultations and capacity market rulebook amendments that directly determine storage asset revenue stacking potential. BEIS and the Climate Change Committee establish decarbonization pathways that mandate storage deployment levels compatible with net-zero electricity system targets. Stakeholders must monitor how forthcoming grid connection queue reforms and distributed generation interconnection standards alter project economics for co-located versus standalone storage configurations.
Market Dynamics
Offshore wind integration mandates are forcing grid operators across England and Scotland to procure multi-hour battery capacity at unprecedented scale, compressing project development timelines and reshaping interconnection queue priorities for storage developers.
Growth Catalysts
- Capacity Market reforms:BEIS rulebook amendments now permit storage assets to stack revenues from frequency response, capacity payments, and wholesale arbitrage simultaneously.
- Transmission constraint pricing:National Grid's zonal pricing signals in southern England concentrate merchant storage investment where congestion costs peak.
- Redox flow maturation:Vanadium-based systems achieve 20,000+ cycle lifespans, enabling daily 8-hour discharge economics for wind farm co-location.
Market Restraints
- Lithium carbonate volatility:Raw material input costs for NMC and LFP chemistries swing 40-60% annually, eroding fixed-price EPC contract margins.
- Grid connection queues:Ofgem's first-come-first-served interconnection regime traps 20+ GW of storage projects in procedural limbo.
- Gas peaker competition:Existing CCGT fleets in East Anglia and Yorkshire undercut battery LCOS through sunk capital recovery.
Strategic Opportunities
- Wales and Northern Ireland penetration:These sub-regions hold 15% of UK renewable generation but under 5% of operational storage capacity.
- Behind-the-meter C&I aggregation:Virtual power plant platforms can pool commercial peak-shaving assets into grid-scale flexibility services.
- Contracts for Difference expansion:BEIS consultation on extending CfD eligibility to standalone storage would de-risk merchant revenue exposure.
Industry Challenges
- Power electronics engineering scarcity:Grid-forming inverter specialists command 35% salary premiums over conventional solar EPC talent.
- DC-coupling retrofit complexity:Legacy solar farms require complete inverter replacement to accept battery augmentation, doubling integration capex.
- Battery safety certification timelines:UN 38.3 and IEC 62619 testing protocols add 6-9 months to project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Energy Storage Systems Market |
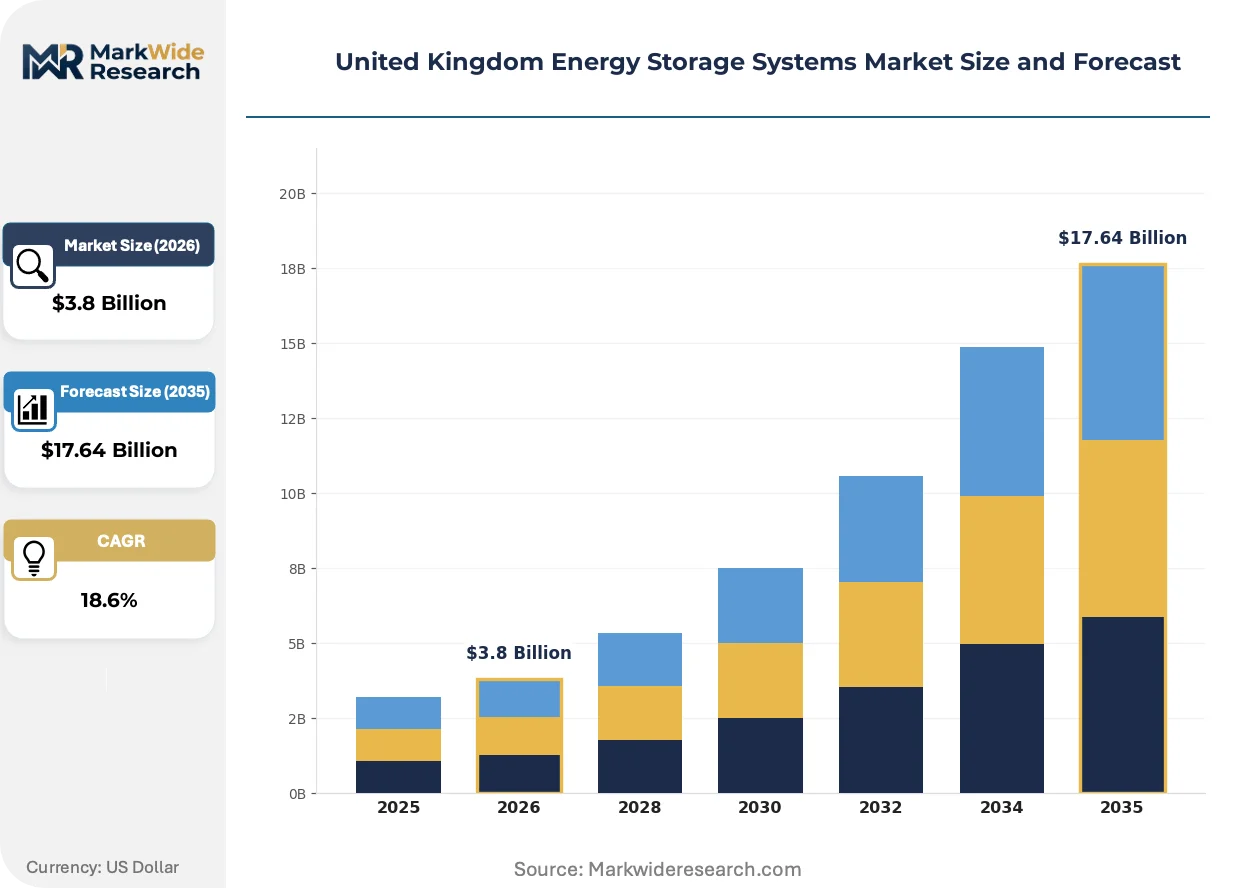
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Energy Storage, Flywheel Energy Storage, Pumped Hydro Storage, Thermal Energy Storage Technology: Lithium-ion, Sodium-sulfur, Compressed Air, Redox Flow Application: Grid Stabilization, Renewable Integration, Peak Shaving, Frequency Regulation End User: Utilities, Commercial, Industrial, Residential |
| Companies Covered | Samsung Electronics Co Ltd, AES Energy Storage, Tesla Inc, General Electric, ABB Ltd, Contemporary Amperex Technology, BYD Co Ltd ADR, HOPPECKE Batteries, LG Chem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Energy Storage Systems Market Evolving Landscape
Software-defined asset management is displacing hardware-centric procurement as the primary value lever for UK storage investors, with virtual power plant platforms and predictive analytics reshaping how battery fleets monetize grid services.
Grid-forming inverter technology is virtualizing the traditional synchronous condenser market by enabling battery systems to provide synthetic inertia, fault current, and voltage regulation without rotating machinery. Scottish Power and SSE are deploying these inverters across their Highland wind-storage hybrids. This virtualization collapses the cost premium for grid stability services, forcing conventional equipment suppliers to reposition around software integration.
Ofgem's Targeted Charging Review is eliminating residual network charges for storage assets that do not import during peak periods, redirecting investment toward co-located configurations that minimize grid import dependency. The reform takes effect across distribution network operator territories in phases. Standalone storage developers in constrained zones face stranded asset risk unless they reconfigure for solar or wind pairing.
Aggregators like Limejump and Flexitricity are unbundling after-sales service from hardware ownership, offering battery owners guaranteed revenue floors through algorithmic trading while retaining optimization IP. C&I buyers in London and Birmingham increasingly prefer this opex-light structure over direct asset ownership. The model concentrates technical risk with platforms that can arbitrage across multiple revenue streams simultaneously.
United Kingdom Energy Storage Systems Market Segmentation
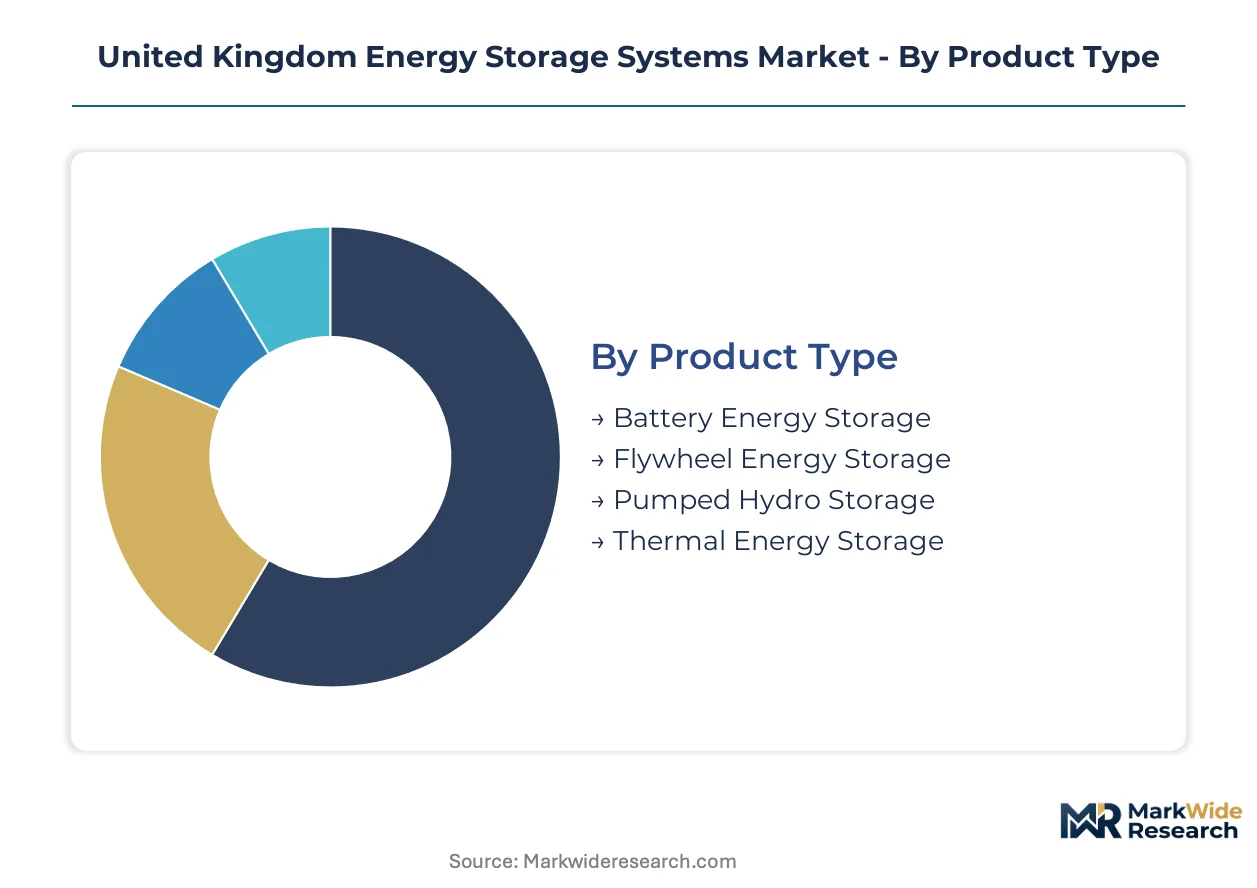
Segmentation reveals how revenue capture mechanics differ across hardware configurations and operational use cases in the UK storage market. Aftermarket service intensity varies dramatically by product maturity and cycling regime, reshaping vendor profitability profiles.
Product Type:
After-sales service intensity peaks with electrochemical systems requiring active thermal management and cell replacement scheduling.
- Battery Energy Storage:Lithium-ion and flow battery configurations dominate utility-scale deployments across England and Scotland. Southern load centers and offshore wind co-location projects in the North Sea corridor concentrate procurement volumes. Grid operators prioritize 2-4 hour duration assets for frequency response and wholesale arbitrage stacking.
- Flywheel Energy Storage:Kinetic energy systems deliver sub-second response times for grid stabilization services. National Grid's Enhanced Frequency Response tenders in southern England anchor demand, though limited energy density constrains deployment scale outside transmission-critical nodes.
- Pumped Hydro Storage:Scotland's Highland terrain hosts the majority of UK capacity, with Dinorwig and Cruachan providing bulk storage for renewable generation firming.
- Thermal Energy Storage:Molten salt and phase-change materials serve district heating networks and industrial process heat applications in northern England.
Battery Energy Storage holds the largest share; momentum sits with Flywheel Energy Storage in ultra-fast grid services.
Technology:
Cost tier stratification separates premium chemistries from standardized commodity cells in procurement contracts.
- Lithium-ion:NMC and LFP variants capture utility and C&I segments through declining manufacturing scale economies. Manufacturing concentration in Asian supply chains exposes UK developers to shipping cost volatility and tariff exposure.
- Sodium-sulfur:High-temperature ceramic electrolyte systems operate at 300°C, suiting long-duration daily cycling in wind farm co-location. Limited UK deployment history constrains EPC contractor familiarity and insurance underwriting appetite.
- Compressed Air:Subterranean salt cavern storage in Cheshire and Yorkshire provides multi-day discharge capability for seasonal arbitrage.
- Redox Flow:Vanadium-based systems achieve 20,000+ cycle lifespans, enabling 8-hour discharge economics that lithium-ion cannot match. Welsh and Scottish developers are piloting flow-wind hybrids for capacity market qualification.
Lithium-ion dominates installed capacity; Redox Flow is expanding most quickly in long-duration tenders.
Application:
Application focus determines which revenue streams assets can stack under Ofgem and BEIS rulebook frameworks.
- Grid Stabilization:Synthetic inertia and fault current services from grid-forming inverters displace synchronous condensers. Scottish Power's Highland deployments demonstrate commercial viability without rotating machinery.
- Renewable Integration:Co-located storage smooths offshore wind output volatility for CfD-compliant generation profiles. Transmission-connected projects in East Anglia and the Humber cluster lead deployment.
- Peak Shaving:C&I buyers in London and Birmingham reduce demand charges through behind-the-meter discharge during triad periods.
- Frequency Regulation:Dynamic containment and firm frequency response contracts provide baseload revenue for assets with sub-second response capability.
Grid Stabilization commands premium pricing; Peak Shaving is gaining share fastest among C&I aggregators.
End User:
Customer type dictates procurement sophistication and contract structure preferences across the value chain.
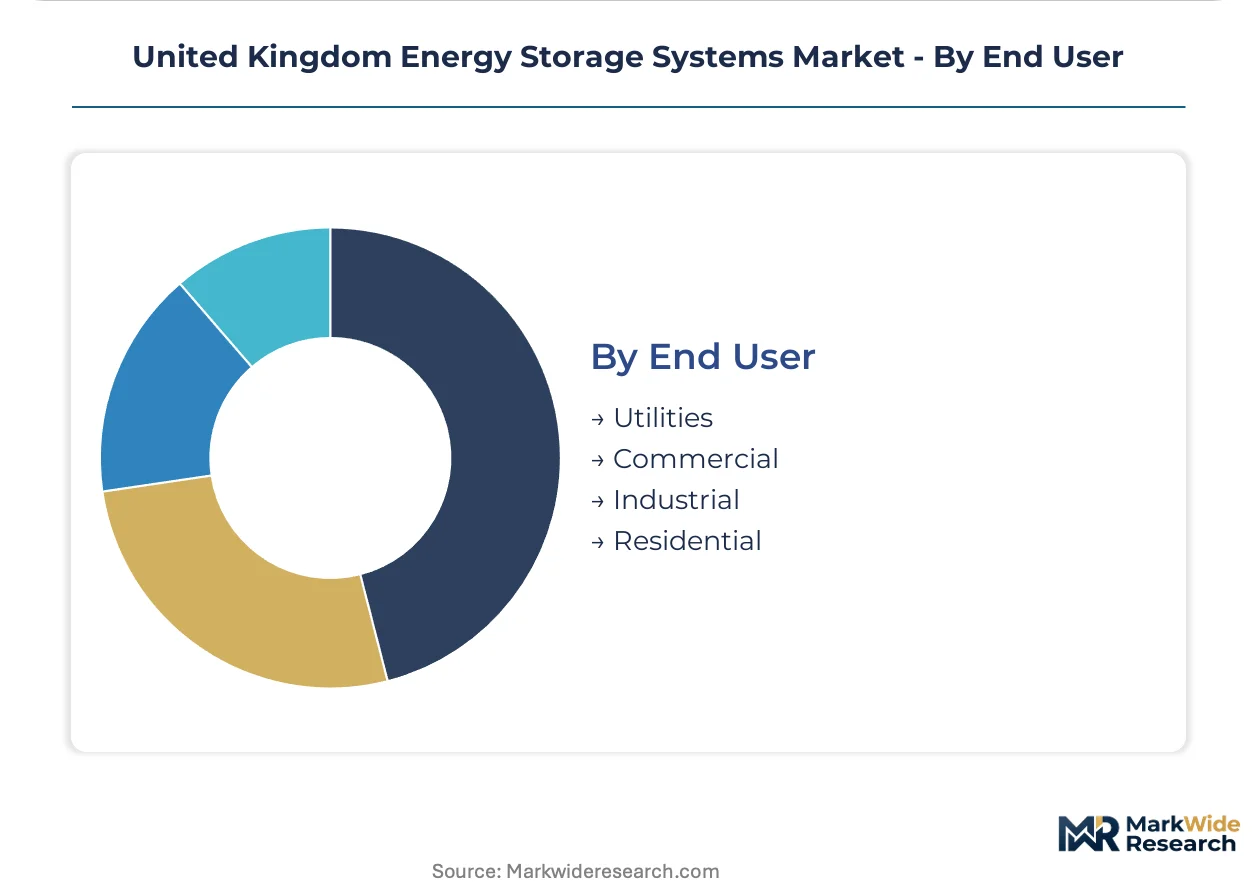
- Utilities:Transmission and distribution operators procure multi-hundred megawatt assets through competitive tenders. National Grid ESO's stability pathfinder contracts reshape technical specifications toward grid-forming capability.
- Commercial:Retail chains and data center operators favor opex-light aggregation models over direct ownership. Limejump and Flexitricity platforms pool distributed assets into grid-scale flexibility services.
- Industrial:Manufacturing facilities with high power demand volatility deploy storage for power quality and resilience. Peak charge avoidance drives payback calculations in energy-intensive sectors.
- Residential:Retrofit costs and distribution network access rules constrain deployment despite solar PV co-location potential. Smart export guarantee tariffs provide insufficient revenue support for standalone economics.
Utilities anchor procurement volumes; Commercial segment shows steepest expansion trajectory through aggregation platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developer attention clusters where transmission constraints and renewable generation coincide, with project pipelines concentrating in zones where grid operators face the steepest balancing challenges.
London and Southeast England
Merchant storage investors target this zone for its triad-period congestion pricing and proximity to urban load centers. National Grid's zonal transmission charges create arbitrage opportunities for assets co-located with existing solar farms. The Thames corridor hosts multiple gigawatt-scale battery projects awaiting Ofgem connection approvals.
East Anglia
Offshore wind clusters in the North Sea drive demand for multi-hour storage to firm generation output for CfD compliance. The Bacton gas terminal area and Great Yarmouth port infrastructure support heavy component logistics. Developers here navigate competing interconnection queue priorities with wind farm offtake agreements.
Scotland
Highland pumped hydro facilities at Dinorwig and Cruachan anchor bulk storage, while new battery deployments target grid stability services for wind-rich northern zones. Scottish Power's grid-forming inverter pilots demonstrate synthetic inertia provision without rotating machinery. The region holds surplus renewable generation seeking southbound transmission capacity.
Wales
This sub-region holds substantial onshore wind capacity but underdeveloped storage infrastructure relative to its generation profile. Vanadium redox flow pilots target long-duration tenders where daily cycling exceeds lithium-ion economics. Grid connection queue reform discussions particularly affect Welsh projects given their distance from major demand centers.
Northern England
Industrial load centers in Yorkshire and the Humber cluster drive peak-shaving demand from energy-intensive manufacturing. Salt cavern geology in Cheshire supports compressed air energy storage exploration for seasonal arbitrage. The region's CCGT fleet creates merchant pricing competition for battery developers seeking capacity market revenues.
United Kingdom Energy Storage Systems Market Competitive Landscape
Vertically integrated conglomerates and specialized power electronics firms split the market along capability lines, with hardware manufacturing scale separating tier-one deployers from regional integrators. The vendor map shows moderate concentration at the utility-scale EPC level and fragmentation among behind-the-meter service providers. Three archetypes dominate: Asian cell manufacturers with captive module assembly, European power engineering houses with grid integration expertise, and software-centric aggregators unbundling optimization from asset ownership. Competitive moves center on co-location partnership structures and algorithmic trading platform licensing.
Within the conglomerate tier, Samsung Electronics Co Ltd and LG Chem exemplify integrated manufacturing scale, while Tesla Inc anchors the software-defined archetype with vertically controlled energy management systems. ABB Ltd occupies the power engineering specialist position through grid-forming inverter and frequency regulation contracting expertise.
| Leading Market Players |
|---|
| Samsung Electronics Co Ltd |
| AES Energy Storage |
| Tesla Inc |
| General Electric |
| ABB Ltd |
| Contemporary Amperex Technology |
| BYD Co Ltd ADR |
| HOPPECKE Batteries |
| LG Chem |
| Others |
Value Network & Pricing Analysis
Overcapacity in South Korean lithium-ion cell manufacturing is compressing supplier margins and forcing tier-one producers to absorb shipping volatility rather than pass through costs to UK EPC contractors. This utilization dynamic shifts bargaining power toward developers who can secure fixed-price module contracts while suppliers compete for offtake commitments.
Pricing Analysis
Ofgem's Targeted Charging Review dictates the pricing tier structure for storage assets by eliminating residual network charges for systems that minimize grid imports. Three-tier pricing structure across premium, standard, and economy levels separates grid-forming inverter packages from conventional frequency response assets and commodity peak-shaving units. Cost compression in standard-tier lithium-ion systems is intensifying because Chinese manufacturers are dumping excess NMC and LFP capacity into European markets. Commercial aggregators exhibit the highest price sensitivity due to thin merchant revenue margins, while utility-scale developers prioritize technical specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from UK project developers are forcing Asian cell manufacturers to rely on supply-chain finance facilities backed by Korean and Japanese trade credit agencies. Manufacturing concentration in China, South Korea, and Japan draws from cobalt hydroxide, lithium carbonate, and electrolyte salt inputs. Single-source vulnerability in refined lithium chemical processing creates exposure to export licensing disruptions. Distribution runs through Rotterdam port logistics and UK-based EPC integrators who manage installation and commissioning risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among utility-scale developers who can commit multi-hundred megawatt pipelines, fragmenting the vendor landscape into price-takers and technology differentiators.
For Market Incumbents: Pre-empt margin erosion in lithium-ion hardware by securing captive cathode material supply through offtake agreements with Korean refiners. Grid-forming inverter capability represents the priority defensive investment as National Grid ESO's stability pathfinder contracts disqualify conventional frequency response assets. Co-location partnership structures with Scottish and Welsh wind developers lock in pipeline visibility before CfD rulebook amendments take effect. For New Entrants and Emerging Players: Mid-market commercial buildings in Birmingham and Manchester represent the most penetrable entry point for behind-the-meter aggregation platforms that bypass utility-scale interconnection queues. Vanadium redox flow technology in Welsh long-duration tenders offers technology differentiation where lithium-ion economics fail. Virtual power plant software licensing to existing C&I asset owners provides capital-light market access without hardware manufacturing exposure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-centric aggregators who retain optimization IP while outsourcing hardware ownership. Long-term viability over a multi-year horizon rests on platforms that can arbitrage across frequency response, capacity market, and wholesale revenue streams simultaneously. Grid connection queue reform implementation serves as the critical inflection signal for reallocating capital between standalone and co-located storage configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Deployment | Scottish Power's Highland pilots demonstrate synthetic inertia provision displacing synchronous condenser contracts. |
| Vanadium Redox Flow Piloting | Welsh developers target 8-hour discharge economics for capacity market qualification beyond lithium-ion limits. |
| Virtual Power Plant Platform Licensing | Limejump and Flexitricity unbundle optimization IP from hardware ownership to capture C&I aggregation fees. |
| Co-Location Partnership Structuring | East Anglia offshore wind clusters drive CfD-compliant storage procurement for generation firming requirements. |
| Supply-Chain Finance Facility Expansion | Korean trade credit agencies back extended payment terms demanded by UK project developers. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary fieldwork with battery system integrators and power electronics specialists combined with secondary validation from Ofgem consultation documents, BEIS policy papers, National Grid ESO tender databases, and IEA energy storage deployment trackers. Bottom-up project pipeline aggregation and top-down regulatory scenario modeling provided cross-referenced triangulation.
Scenario-bracketing around Ofgem network charging reform implementation and CfD eligibility expansion framed the analytical approach across the projection horizon. Segmentation dimensions modeled include technology chemistry, application use case, project scale tier, and regional grid constraint profile. CAGRs were derived from capacity deployment trajectories and revenue stacking potential under evolving market rulebooks. Forecast inputs incorporated interconnection queue clearance rates and raw material contract pricing volatility.
Practitioners should monitor lithium carbonate contract pricing and grid connection queue reform implementation for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Power Bank Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Solar Storage System Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
Super Capacitor Energy Storage System Market