
 Behind-The-Meter Stationary Battery Storage Market | 2026-2036
Behind-The-Meter Stationary Battery Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Behind-The-Meter Stationary Battery Storage Market Insights
The US Inflation Reduction Act is shifting the cost-of-entry calculus for behind-the-meter storage developers by extending investment tax credits to standalone battery systems without solar pairing. Tesla leverages its integrated hardware-software stack to dominate residential and commercial deployments across multiple continents. LG Energy Solution anchors its position through captive cell production and scale advantages in lithium-ion pack assembly. BYD competes aggressively on cost structure through in-house production of lithium iron phosphate cells.
Behind-the-meter stationary battery storage denotes electrochemical energy systems installed on the customer side of the utility meter, typically employing lithium-ion cells with 5-20 year cycle life ratings, designed to store grid or on-site renewable electricity for later dispatch. These systems serve commercial and industrial facilities seeking to reduce demand charges, participate in grid services, or ensure power continuity during outages. Lithium-ion chemistry commands the dominant share of new capacity additions due to falling cell costs and proven performance at commercial scale. Peak shaving applications attract the deepest customer penetration because the payback arithmetic is simplest for facility managers tracking demand charges. Residential rooftop installations represent the fastest-growing installation category as homeowners pair batteries with solar and time-of-use rate structures spread.
The US Federal Energy Regulatory Commission shapes market access through Order 2222 aggregation rules, while state-level public utility commissions in California and New York mandate storage targets that pull demand forward. The EU Battery Regulation imposes carbon footprint disclosure and recycled content thresholds that will filter supply chain participants by compliance capability. Stakeholders must monitor how interconnection queue reforms and evolving capacity market rules determine which projects clear final investment decisions.
Market Dynamics
The US Inflation Reduction Act's standalone storage ITC is compressing payback periods and pulling project economics into positive territory for commercial building owners who previously deferred battery investments. This policy recalibration is accelerating deployment velocity across grid-constrained urban corridors.
Growth Catalysts
- Standalone Storage ITC:The US IRA extends investment tax credits to battery systems without solar pairing, rewriting project returns for C&I facility managers in California and Texas.
- Time-of-Use Arbitrage:California's investor-owned utilities deploy steep TOU rate differentials that create predictable revenue streams for 4-hour lithium-ion systems.
- Demand Charge Management:Commercial building operators in New York and Massachusetts deploy peak shaving to neutralize 30-70% of utility demand charges.
Market Restraints
- Lithium Carbonate Volatility:Cell input costs swing with Chinese lithium refining capacity and South American brine extraction disruptions.
- Interconnection Queues:US regional transmission organizations and independent system operators impose 18-36 month queue delays that freeze project cash flows.
- Fire Safety Codes:NFPA 855 and local amendments mandate thermal runaway detection and explosion control systems that add 8-15% to installed costs.
Strategic Opportunities
- Virtual Power Plant Aggregation:FERC Order 2222 enables residential battery fleets to stack grid services revenue atop retail arbitrage in PJM and CAISO territories.
- Lithium Iron Phosphate Chemistry:LFP cells displace NMC in commercial deployments due to superior cycle life and thermal stability profiles.
- India C&I Microgrids:State electricity boards in Maharashtra and Gujarat tolerate open access rules that permit behind-the-meter storage for textile and pharmaceutical clusters.
Industry Challenges
- Commissioning Complexity:Utility interconnection engineers and fire marshals impose non-standardized testing protocols that stretch commercial project timelines.
- Recycling Infrastructure Gaps:Spent lithium-ion packs accumulate in California and Nevada warehouses due to absent EPA-certified hydrometallurgical processing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behind-The-Meter Stationary Battery Storage Market |
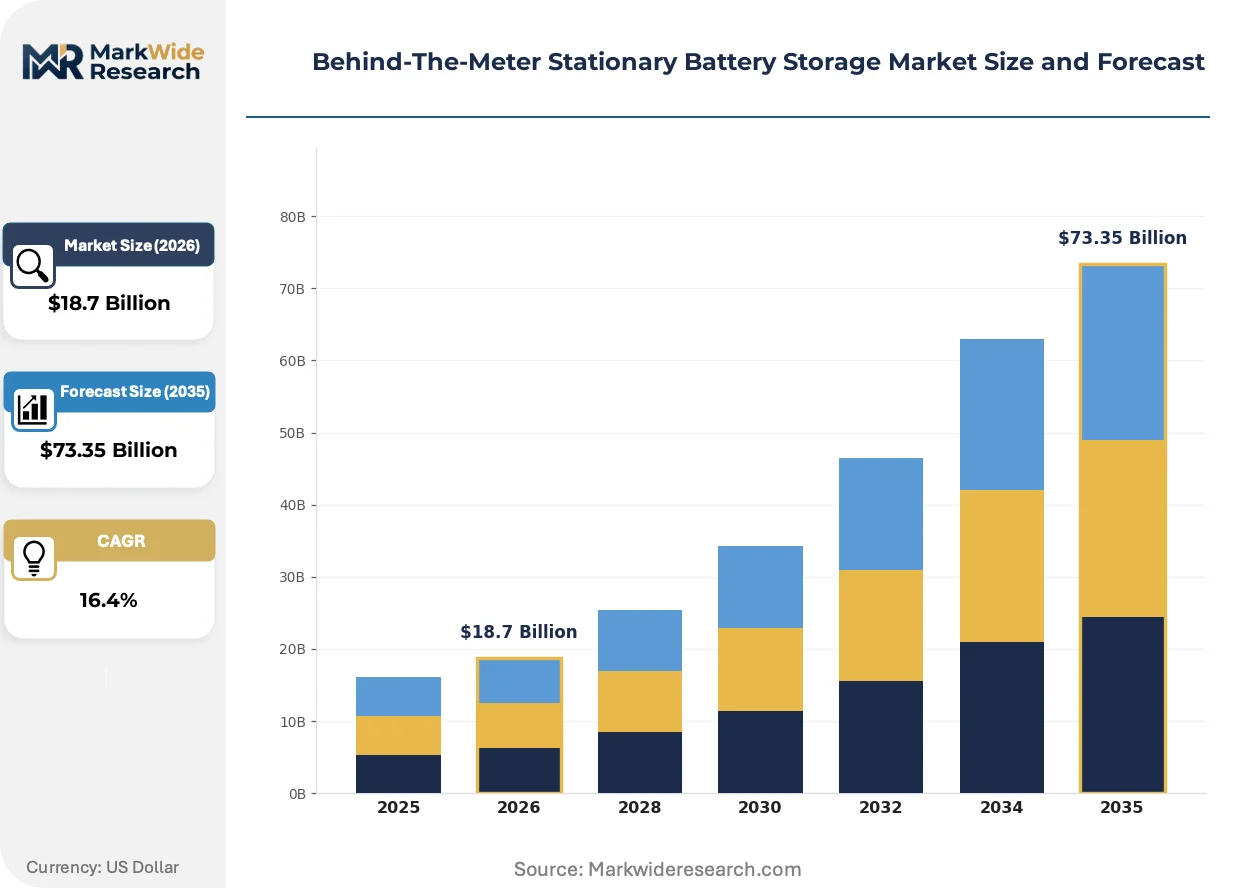
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead Acid, Flow, Nickel Cadmium, Sodium Sulfur Application: Peak Shaving, Demand Response, Backup Power, Load Balancing, Energy Arbitrage Installation Type: Residential Rooftop, Commercial Building, Industrial Facility, Microgrid, Campus End User: Data Centers, Telecommunications, Manufacturing Plants, Educational Institutions, Hospitality |
| Companies Covered | Tesla, BYD, LG Energy Solution, Panasonic Holdings, Siemens, Samsung SDI, Schneider Electric, ABB, Sonnen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behind-The-Meter Stationary Battery Storage Market Trends and Innovations
Software-defined control architectures are displacing hardware-centric battery management systems. This shift enables dynamic dispatch optimization and multi-revenue stream stacking that hardware-only vendors cannot replicate.
Lithium iron phosphate chemistry is decentralizing commercial and industrial storage procurement away from nickel manganese cobalt systems. Facility managers in Arizona and Colorado specify LFP for 6,000+ cycle life ratings that compress levelized cost of storage calculations. The technology is decentralizing supplier power from Korean cell makers toward Chinese LFP specialists with captive iron phosphate supply.
The EU Battery Regulation imposes carbon footprint disclosure thresholds and recycled content mandates that filter supply chain participants by compliance capability. Battery passport requirements force cell manufacturers to document upstream mining emissions and material provenance. European C&I buyers now screen vendors for CE marking alignment and due diligence compliance before tendering.
Energy-as-a-service contracting is displacing direct equipment purchases among risk-averse commercial building owners. Third-party financiers in Texas and Florida assume performance risk and capture arbitrage upside through 10-15 year offtake agreements. This model concentrates fastest in hospitality and retail verticals where capex budgets face competing priorities.
Behind-The-Meter Stationary Battery Storage Market Segmentation
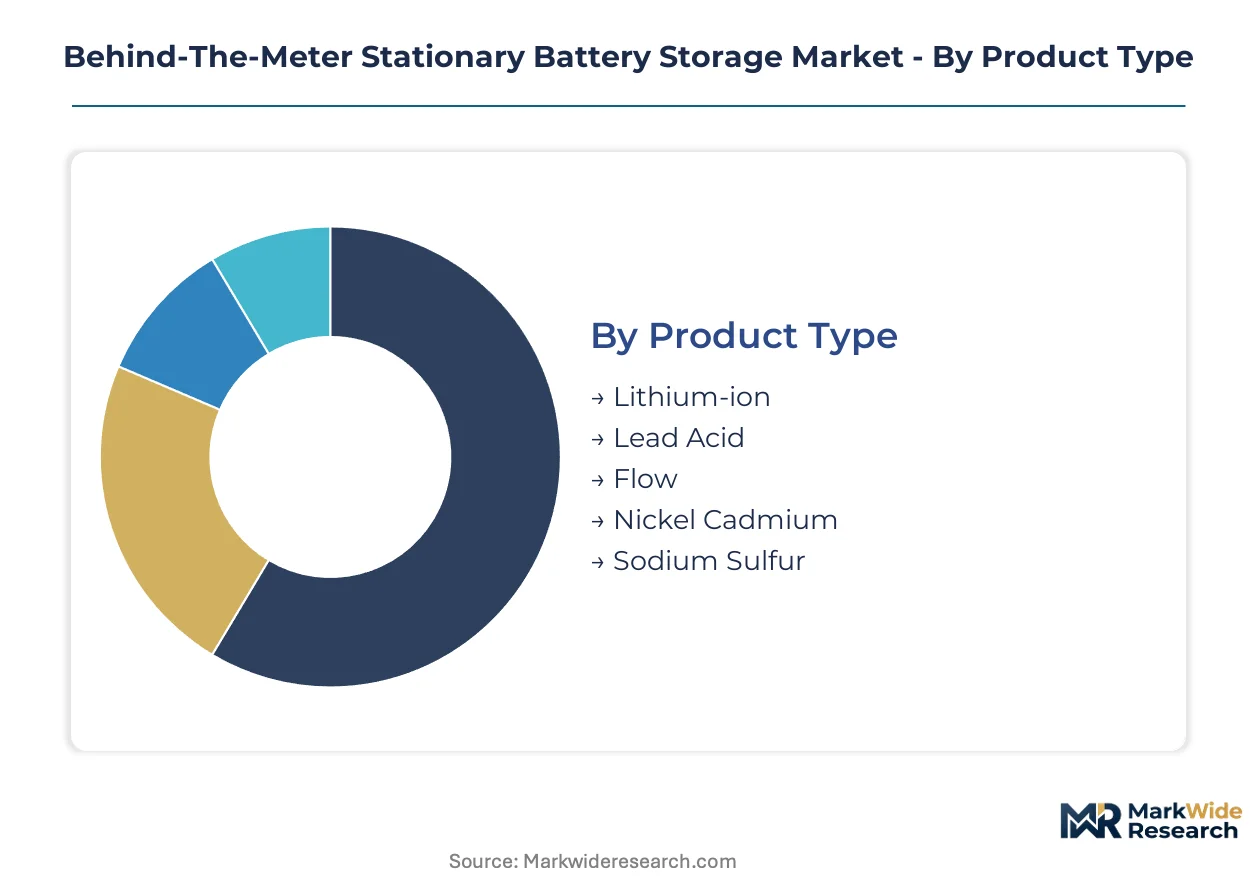
Segmentation in behind-the-meter storage reveals how technology choices, use-case economics, and facility characteristics determine procurement patterns. Each dimension carries distinct margin profiles and vendor specialization requirements that shape competitive strategy.
Product Type:
Standardization dominates at the cell chemistry level, while system-level customization varies by thermal management and enclosure specifications.
- Lithium-ion:NMC and LFP variants constitute the installed base for commercial and residential applications. Demand clusters in California's grid-constrained corridors where FERC Order 2222 aggregation rules enable stacked revenue streams.
- Flow:Vanadium redox systems deliver 20-year cycle life for industrial microgrids requiring daily deep discharge. Installations concentrate in Massachusetts and New York where state storage mandates and long-duration incentives align with capital-intensive project structures.
- Lead Acid:Mature technology serving backup power niches in telecommunications shelters with limited cycling requirements.
- Nickel Cadmium:Specialized deployments in extreme temperature environments where electrolyte resilience outweighs cost premiums.
- Sodium Sulfur:High-temperature chemistry deployed in large-scale campus microgrids with predictable load profiles and dedicated maintenance capabilities.
Leading the category by volume: Lithium-ion. Growing fastest: Flow.
Application:
Revenue model clarity separates mature applications from emerging use cases still seeking tariff alignment.
- Peak Shaving:Commercial facility managers deploy 2-4 hour lithium-ion systems to neutralize demand charges during 15-minute utility metering intervals. This application attracts the deepest penetration in Texas and California where tariff structures expose full demand charge exposure.
- Energy Arbitrage:Automated dispatch software charges batteries during off-peak TOU periods and discharges during peak rate windows. California's investor-owned utilities provide the steepest rate differentials, creating predictable returns for systems with 85%+ round-trip efficiency.
- Demand Response:Aggregated fleets participate in wholesale capacity markets through utility-controlled dispatch programs.
- Backup Power:Critical facility operators prioritize seamless transfer switches over cycling economics.
- Load Balancing:Manufacturing sites with intermittent process loads smooth power quality without full islanding capability.
Peak shaving commands current deployment share. Energy arbitrage shows steepest expansion trajectory as TOU rate structures proliferate.
Installation Type:
Project scale and interconnection complexity create distinct vendor ecosystems across installation categories.
- Commercial Building:Behind-the-meter systems ranging from 100kWh to 2MWh serve office and retail properties seeking demand charge reduction. Procurement concentrates among building owners in New York and Massachusetts where utility incentives and fire safety codes have standardized around NFPA 855 compliance frameworks.
- Residential Rooftop:Homeowners pair 10-20kWh battery packs with solar installations to maximize self-consumption and hedge against outage risk. This segment climbs fastest in California, Texas, and Florida where net metering revisions and hurricane-driven resilience concerns drive adoption.
- Industrial Facility:Heavy manufacturing sites require megawatt-scale systems with specialized power conditioning.
- Microgrid:Campus and community systems integrate multiple generation sources with islanding controls.
- Campus:University and medical center deployments prioritize resilience over arbitrage returns.
Commercial building leads by installed capacity. Residential rooftop gains share fastest as solar-plus-storage economics improve.
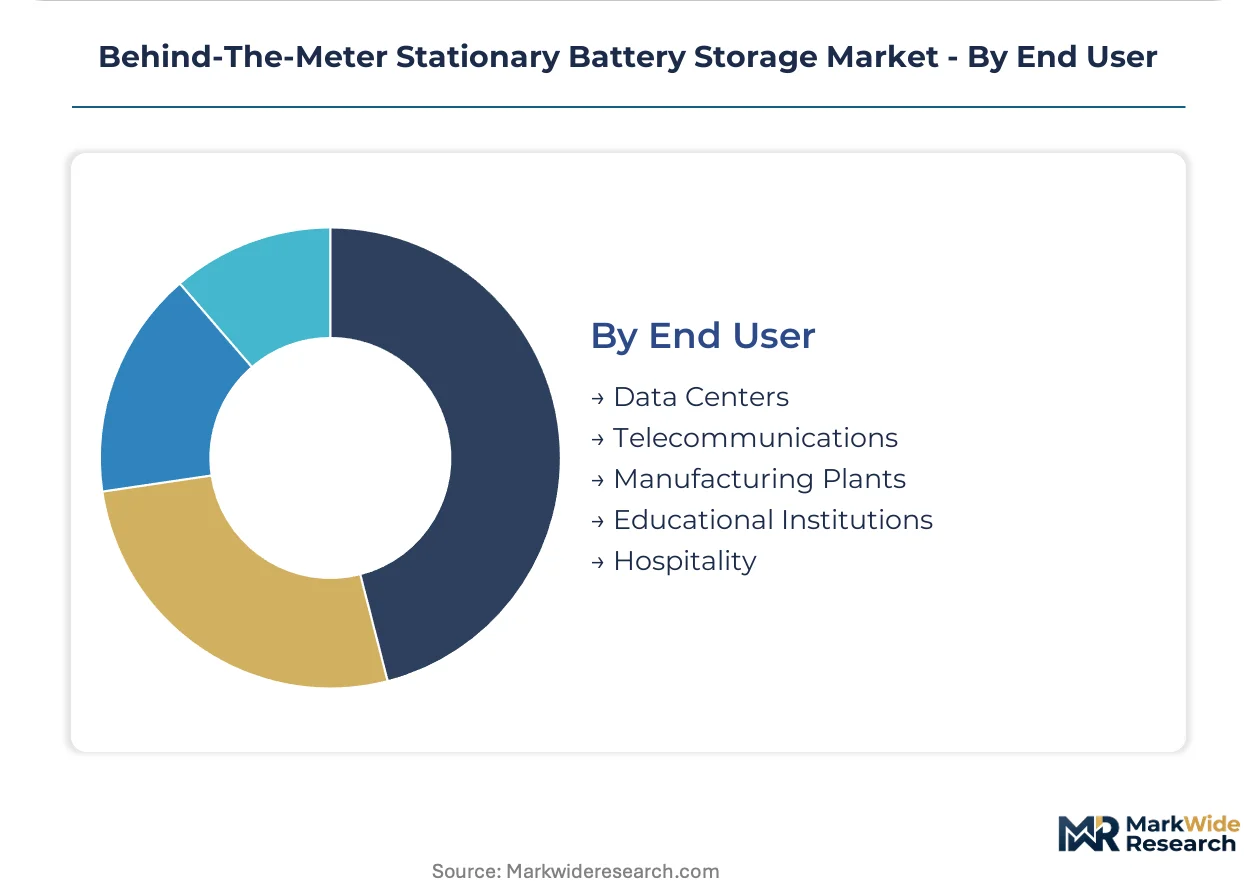
End User:
Uptime requirements and procurement sophistication vary sharply across verticals, filtering vendor access.
- Data Centers:Hyperscale and colocation operators deploy lithium-ion systems for seamless UPS integration and peak shaving alongside diesel backup. Demand concentrates in Northern Virginia and Dallas-Fort Worth where grid instability and massive load growth strain utility infrastructure.
- Telecommunications:Tower operators and central offices require 4-8 hour backup autonomy for network continuity. This vertical standardizes on lead-acid and lithium-ion configurations with remote monitoring capabilities across FCC-regulated infrastructure.
- Manufacturing Plants:Process industries prioritize power quality and ride-through capability over energy arbitrage.
- Educational Institutions:University procurement favors visible sustainability credentials and curriculum integration opportunities.
- Hospitality:Hotels and resorts emphasize guest experience protection during outages.
Data centers anchor category volume. Telecommunications expands most quickly with 5G infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's standalone storage ITC has established North American tax-incentive zones as the primary concentration zone for behind-the-meter deployment velocity, with California's grid-constrained urban corridors absorbing disproportionate capacity additions.
United States
Commercial building owners in California and Texas are expanding installations to neutralize demand charges and capture time-of-use arbitrage. The Federal Energy Regulatory Commission's Order 2222 aggregation rules enable residential battery fleets to stack grid services revenue. Demand concentrates in California's urban corridors where investor-owned utilities deploy steep rate differentials.
Germany
Industrial facility managers deploy lithium-ion systems for peak shaving under the country's evolving capacity market frameworks. The EU Battery Regulation imposes carbon footprint disclosure thresholds that filter vendor selection by compliance capability. Procurement clusters in Bavaria and North Rhine-Westphalia where manufacturing microgrids seek power quality assurance.
China
State electricity boards in manufacturing-heavy provinces tolerate open access rules that permit behind-the-meter storage for textile and pharmaceutical clusters. The Ministry of Industry and Information Technology shapes domestic deployment through GB standards and dual carbon goals enforcement. Installations concentrate in the Yangtze River Delta where grid constraints intersect with export-oriented industrial load.
India
Maharashtra and Gujarat textile clusters adopt lithium iron phosphate systems under state-level open access regulations that permit behind-the-meter configurations. The Central Electricity Authority and state electricity boards administer evolving storage mandates and interconnection protocols. Procurement accelerates in Ahmedabad and Surat industrial corridors where power quality interruptions disrupt continuous process manufacturing.
Australia
Residential rooftop solar-plus-storage adoption climbs in New South Wales and Victoria as net metering revisions and outage resilience concerns drive homeowner investment. The national regulator and state-level energy market authorities shape grid services participation rules for aggregated battery fleets. Deployment concentrates in Sydney and Melbourne metropolitan zones where time-of-use rate structures create arbitrage economics.
Behind-The-Meter Stationary Battery Storage Market Competitive Landscape
US and Chinese producers anchor one tier; Korean specialists hold established positions in cell chemistry supply. The vendor base stratifies across integrated hardware-software stacks, captive cell producers, and system integrators with project development capabilities. Three archetypes dominate: vertically integrated technology platforms, scale-driven lithium-ion pack assemblers, and energy-as-a-service financiers assuming performance risk. Competitive moves concentrate on software-defined control architectures and multi-revenue stream stacking capabilities.
Within the integrated technology platform tier, Tesla and BYD exemplify divergent geographic anchoring and chemistry strategies. LG Energy Solution occupies a position among Korean cell producers with captive manufacturing scale. These three names represent how competitive positioning splits across Silicon Valley software-hardware integration, Chinese cost-structured LFP specialization, and Korean NMC scale advantages. Each archetype captures distinct margin pools: Tesla captures software and services upside, BYD compresses hardware costs through in-house cell production, and LG Energy Solution leverages proven supply relationships with global automotive and stationary storage offtakers.
| Leading Market Players |
|---|
| Tesla |
| BYD |
| LG Energy Solution |
| Panasonic Holdings |
| Siemens |
| Samsung SDI |
| Schneider Electric |
| ABB |
| Sonnen |
| Others |
Pricing and Supply Chain Analysis
Energy-as-a-service financiers rolled up by private equity sponsors now anchor procurement discipline across the US and Australian markets, compressing hardware margins while extending performance-risk contracts that reshape supplier pricing power and inventory positioning.
Pricing Analysis
Premium pricing for sub-90-day lead-time lithium-ion pack deliveries commands 12-18% spreads over standard 180-day contract slots, while spot inventory from Chinese LFP specialists trades at deeper discounts during quarterly production ramps. Three-tier pricing structure across premium certified-UL, standard CE-marked, and economy non-certified tiers separates procurement channels. Cost compression in economy-tier residential systems is intensifying because BYD and CATL captive cell output floods spot markets. Data center operators show lowest price sensitivity due to uptime guarantees, while hospitality verticals negotiate hardest on capex.
Supply Chain Analysis
Skilled battery pack assembly technician shortages in China's Fujian and Jiangsu provinces constrain quarterly output expansion despite automated cell production scale. Manufacturing concentrates in China, South Korea, and Japan for cell fabrication, with US and German facilities handling final system integration and fire-safety testing. Raw material flows draw from Chilean lithium brine, Indonesian nickel laterite, and Australian spodumene concentrate. Single-source vulnerability in Chinese graphite anode processing creates tariff-exposure risk. Distribution runs through EPC contractors and direct OEM relationships for commercial projects, with residential sales flowing via solar installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream cell production control to capture margin pools that system integrators currently surrender to Korean and Chinese suppliers.
For Market Incumbents: Anchor software-defined control architectures as the primary defensive moat against hardware-commoditization pressure from Chinese LFP specialists. Invest in captive lithium iron phosphate cell capacity in US or European jurisdictions to mitigate IRA domestic content requirements and shipping cost volatility. Certification investment in UL 9540A fire-safety testing protocols preserves access to California and New York building codes that filter out uncertified competitors. For New Entrants and Emerging Players: Launch via energy-as-a-service financing partnerships that assume performance risk and capture arbitrage upside without requiring balance-sheet hardware purchases. Target India's Maharashtra and Gujarat textile clusters where state open-access rules permit behind-the-meter configurations with minimal utility interconnection friction. White-space concentration exists in 4-8 hour vanadium flow systems for Massachusetts and New York industrial microgrids seeking 20-year cycle life. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale system integrators with FERC Order 2222 aggregation software and established utility interconnection track records in PJM and CAISO territories. Long-term viability over the next decade hinges on lithium carbonate price normalization and recycling infrastructure maturation. Watch California's net metering revision trajectory as the signal for residential rooftop demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | Captures margin pools surrendered to Korean suppliers and satisfies IRA domestic content thresholds. |
| FERC Order 2222 Aggregation Platform Launch | Enables residential fleets to stack grid services revenue atop retail arbitrage in restructured markets. |
| Lithium Iron Phosphate Chemistry Transition | Displaces NMC in commercial deployments due to superior cycle life and thermal stability profiles. |
| Energy-as-a-Service Contracting Expansion | Shifts capex risk to third-party financiers and accelerates adoption among hospitality verticals. |
| EU Battery Regulation Compliance Investment | Preserves European market access through carbon footprint disclosure and recycled content certification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. EIA capacity databases, IEA technology roadmaps, FERC interconnection queue filings, and state public utility commission dockets provided quantitative foundations. Bottom-up project-level aggregation and top-down market sizing triangulated volume estimates.
Segmentation modeling operated at chemistry-variant, application-use-case, installation-scale, and end-user-vertical granularity across the projection horizon. CAGRs derived from fitted growth curves against policy-triggered demand pull and technology cost reduction trajectories. Forecast inputs incorporated lithium carbonate price scenarios, interconnection queue clearance rates, and state storage mandate trajectories.
IRA incentive duration uncertainty, lithium supply disruption events, and interconnection reform delays are the dominant revision risks to installed capacity projections. Forecasts reflect documented assumptions on policy continuity and commodity price normalization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Battery Energy Storage Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
South America Energy Storage Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Australia Energy Storage Systems (ESS) Market