
 Subsea Well Access and BOP System Market | 2026-2036
Subsea Well Access and BOP System Market Size, Share, and Industry Trends Forecast 2026-2036
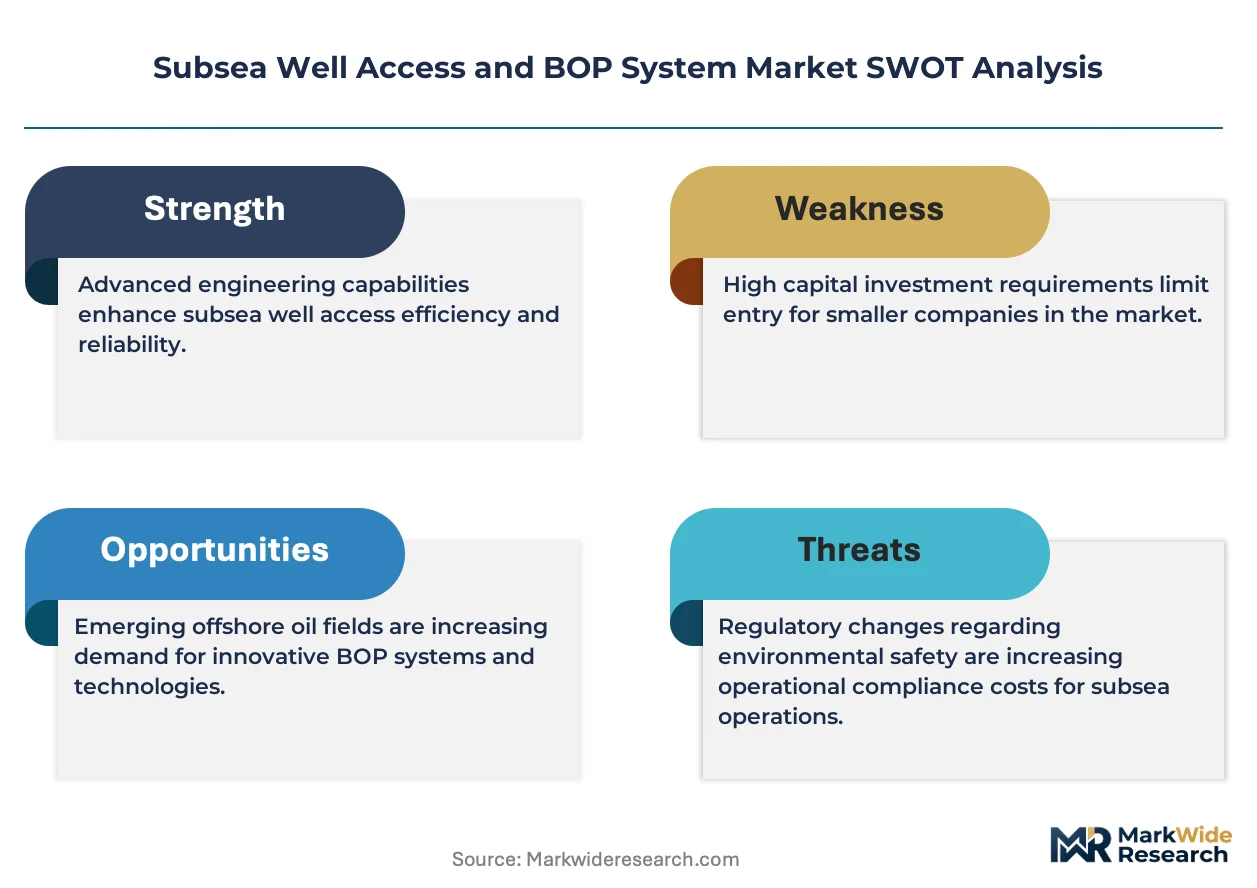
Subsea Well Access and BOP System Market Outlook
Subsea equipment lifecycle management is hardening into a discrete revenue layer as operators extend field life in mature basins. TechnipFMC leverages integrated service contracts to capture recurring revenue from installed BOP fleets. Baker Hughes Company anchors its position through proprietary wellhead connector technologies that reduce intervention downtime. Schlumberger Limited competes by bundling digital monitoring with physical intervention hardware across deepwater accounts.
Subsea Well Access and BOP Systems comprise pressure-containing assemblies—ram and annular BOPs rated to 20,000 psi working pressure, subsea trees with vertical or horizontal configurations, and multiplex electro-hydraulic control pods—that enable safe drilling, completion, and intervention of subsea wells. Riser Systems and BOPs command the largest capital allocation due to safety-critical redundancy requirements and regulatory stack mandates. Ultra-deepwater deployment is expanding fastest as pre-salt and Lower Tertiary plays push operational boundaries beyond 3,000 meters water depth, though margin pools concentrate in Integrated Systems that combine hydraulic, mechanical, and electrical control architectures.
API standards, Norway's Petroleum Safety Authority framework, and Brazil's ANP well control regulations collectively mandate dual BOP redundancy and real-time monitoring capability for deepwater permits. These requirements force capital rotation toward certified suppliers and exclude uncertified equipment from active drilling programs. Stakeholders must track regulatory divergence between North Sea and Gulf of Mexico prescriptive standards as electrification of BOP control systems introduces new certification pathways.
Market Dynamics
API 16D certification mandates and electrification of BOP control architectures are forcing capital rotation toward certified suppliers while compressing margins for legacy hydraulic system providers.
Growth Catalysts
- Pre-salt exploration:Brazil's ANP regulatory framework for well control is accelerating deployment of 20,000 psi-rated BOP stacks in ultra-deepwater concessions.
- Electro-hydraulic multiplex controls:Real-time monitoring capabilities mandated by Norway's Petroleum Safety Authority are driving replacement cycles across North Sea installed bases.
- Lower Tertiary plays:Gulf of Mexico drilling programs above 3,000 meters water depth are expanding demand for integrated riser-BOP systems with redundant shear ram configurations.
Market Restraints
- High-grade alloy supply concentration:Forged components for 20,000 psi pressure housings depend on a limited supplier base concentrated in Western Europe and Japan.
- Protracted certification timelines:API 16D witness testing and DNV-ST-E273 qualification protocols extend lead times for new BOP control system entrants by 18-24 months.
- Capital intensity of dual redundancy:Regulatory mandates for two complete BOP stacks per drilling unit double capital requirements compared to surface wellhead equivalents.
Strategic Opportunities
- Field life extension services:Mature basins in the UK North Sea and Gulf of Mexico are creating recurring revenue pools through BOP recertification and component refurbishment programs.
- All-electric actuation convergence:Integration of permanent magnet motors with subsea power distribution architectures eliminates hydraulic fluid columns and reduces maintenance intervals.
- Digital twin deployment:Physics-based modeling of BOP fatigue life is enabling condition-based maintenance contracts that displace calendar-based service schedules.
Industry Challenges
- Subsea systems engineering talent scarcity:Deepwater BOP design and commissioning requires specialized expertise in high-pressure sealing and well control dynamics that outpaces training pipeline output.
- Legacy stack integration complexity:Retrofitting electro-hydraulic control pods onto existing ram BOP configurations demands custom interface engineering that fragments supplier margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Well Access and BOP System Market |
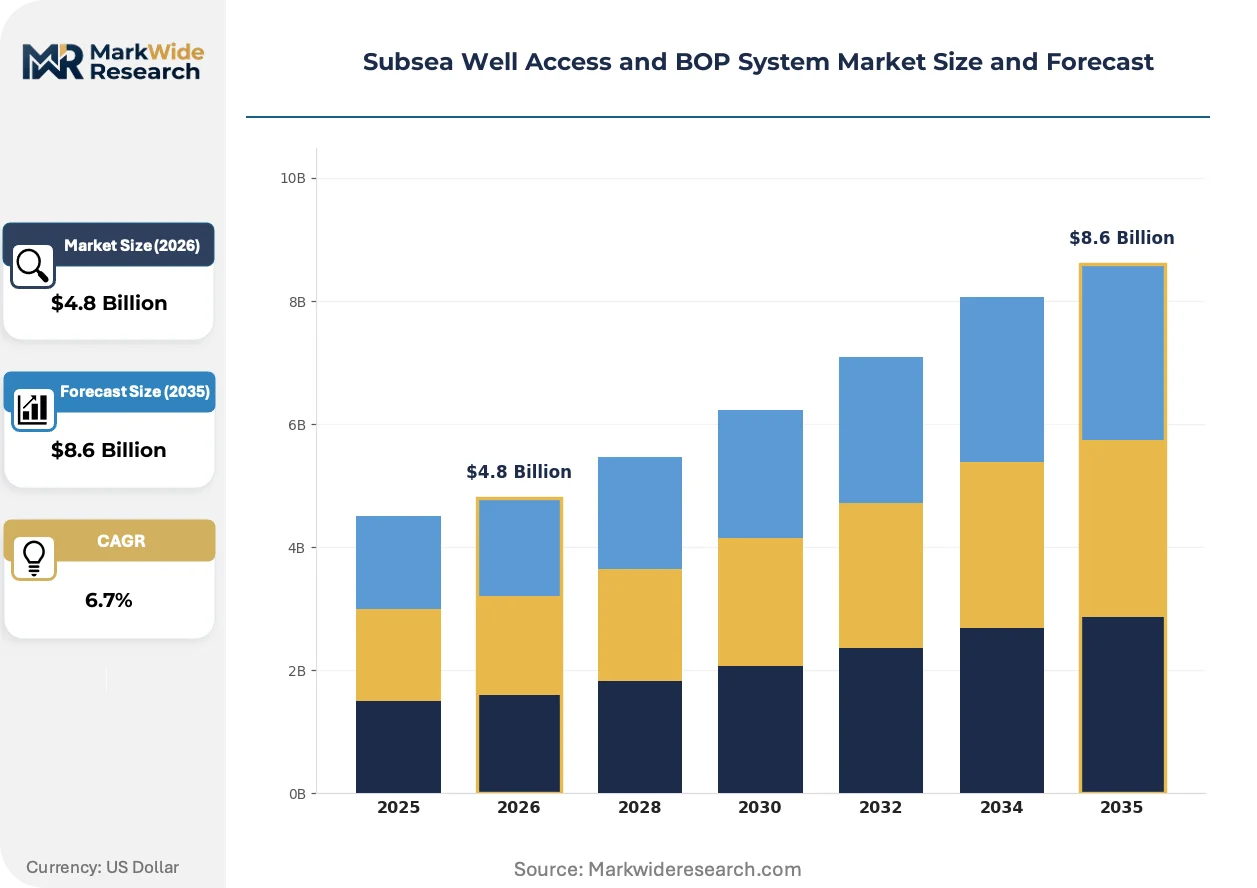
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Riser Systems, Subsea Trees, BOPs, Control Systems Deployment Type: Deepwater, Ultra-deepwater, Shallow Water, Hybrid Systems Technology: Hydraulic, Mechanical, Electrical, Integrated Systems End User: Oil & Gas Companies, Service Providers, Contractors, Manufacturers |
| Companies Covered | Aker Solutions, TechnipFMC, Baker Hughes Company, Dril-Quip, Oceaneering International, Schlumberger Limited, Weatherford International, Subsea 7, National Oilwell Varco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Well Access and BOP System Market Strategic Shifts
Subsea intervention hardware is absorbing digital monitoring layers and all-electric actuation, compressing the traditional separation between mechanical safety systems and software-defined control architectures.
All-electric BOP actuation is absorbing hydraulic functions previously performed by multiplex electro-hydraulic pods. Operators in Norway's Johan Sverdrup field and Brazil's pre-salt cluster are piloting permanent magnet motor configurations that eliminate high-pressure fluid columns. This convergence is absorbing maintenance budgets previously allocated to hydraulic power unit refurbishment and subsea accumulator bank replacement.
Norway's Petroleum Safety Authority framework now mandates real-time BOP status transmission to onshore operation centers. This requirement is compressing the acceptable response window for well control events from hours to minutes. Deepwater drilling contractors are absorbing capital costs for fiber-optic telemetry upgrades to maintain permit eligibility in Norwegian waters.
Integrated service contracts are displacing equipment-only procurement in major deepwater accounts. Operators now bundle BOP stack provision with ongoing certification management and spare parts logistics under multi-year agreements. This shift is most visible among international oil companies operating in Brazil and the US Gulf Coast, where drilling efficiency metrics now dominate supplier selection criteria over upfront capital cost.
Subsea Well Access and BOP System Market Segmentation
Subsea Well Access and BOP System procurement decisions hinge on water depth, pressure rating, and regulatory certification tier. Operators allocate capital across product categories based on field maturity and intervention frequency rather than upfront equipment cost alone.
Product Type:
Capital allocation follows safety-critical redundancy mandates and intervention access requirements rather than unit economics.
- Riser Systems:Tensioned marine drilling risers and production risers rated to 20,000 psi form the structural conduit between surface vessels and subsea wellheads. Demand concentrates in Brazil's pre-salt cluster and US Gulf of Mexico Lower Tertiary plays where dynamic positioning requirements drive specification intensity. Dual-barrier metallurgy and fatigue-resistant weld designs dominate contractor qualification criteria.
- BOPs:Ram and annular blowout preventer stacks with redundant shear capabilities represent the largest single capital line item per drilling unit. Norway's Petroleum Safety Authority mandates real-time monitoring integration, accelerating replacement cycles across North Sea installed bases. API 16D certification gates market access for new suppliers.
- Subsea Trees:Vertical and horizontal wellhead assemblies enable production and intervention access at seabed level.
- Control Systems:Multiplex electro-hydraulic pods and all-electric actuation architectures manage BOP function sequencing.
Riser Systems lead on scale; BOPs lead on momentum.
Deployment Type:
Water depth thresholds determine pressure rating requirements, metallurgy specifications, and regulatory oversight intensity.
- Ultra-deepwater:Operations beyond 3,000 meters water depth in Brazil's pre-salt formations and Gulf of Mexico Lower Tertiary plays demand 20,000 psi-rated BOP stacks with titanium alloy pressure housings. ANP and BSEE permitting frameworks mandate dual redundancy configurations that double capital intensity versus shallower equivalents.
- Deepwater:Fields between 1,000 and 3,000 meters water depth across Angola, Nigeria, and Norway's mature basins drive the installed base volume. Electrification retrofits and recertification programs are absorbing maintenance budgets previously allocated to hydraulic system refurbishment.
- Shallow Water:Shelf developments in the Gulf of Mexico and Southeast Asia utilize simplified wellhead configurations with reduced intervention complexity.
- Hybrid Systems:Configurable architectures adapt to variable water depth profiles within single field developments.
Deepwater leads on scale; Ultra-deepwater leads on momentum.
Technology:
Control architecture selection determines maintenance intervals, certification pathways, and supplier qualification status.
- Integrated Systems:Combined hydraulic, mechanical, and electrical control architectures consolidate BOP function management under unified telemetry protocols. Norway's Johan Sverdrup field and Brazil's Buzios complex are absorbing integrated system deployments to satisfy real-time monitoring mandates. Margin pools concentrate here due to engineering complexity barriers.
- Electrical:All-electric actuation using permanent magnet motors eliminates hydraulic fluid columns and reduces subsea accumulator bank requirements. Pilot programs in the North Sea are climbing the fastest as operators target maintenance cost reduction.
- Hydraulic:Conventional multiplex electro-hydraulic pods dominate legacy installed bases requiring recertification.
- Mechanical:Direct hydraulic actuation persists in shallow water applications with limited intervention frequency.
Hydraulic leads on scale; Integrated Systems lead on momentum.
End User:
Procurement authority and risk allocation determine contract structure and supplier relationship intensity.
- Oil & Gas Companies:International oil companies operating in Brazil, Norway, and the US Gulf Coast bundle BOP provision with multi-year integrated service contracts. Operators now weight drilling efficiency metrics over upfront capital cost in supplier selection, displacing equipment-only procurement models.
- Service Providers:Specialist intervention contractors in the UK North Sea and Gulf of Mexico absorb capital costs for BOP stack provision under rental or performance-based arrangements. Recertification and refurbishment revenue pools are expanding as field life extension programs accelerate.
- Contractors:Deepwater drilling contractors maintain owned BOP fleets for permit eligibility in regulated jurisdictions.
- Manufacturers:Component suppliers and forging houses serve certified system integrators under captive supply arrangements.
Oil & Gas Companies lead on scale; Service Providers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates ultra-deepwater demand for 20,000 psi-rated BOP stacks, while Norway drives electrification retrofits across mature North Sea basins. The United States anchors Gulf of Mexico Lower Tertiary activity. Regulatory divergence between these jurisdictions shapes supplier qualification pathways and capital allocation priorities.
United States
Gulf of Mexico drilling above 3,000 meters water depth expands demand for integrated riser-BOP systems with redundant shear ram configurations. The Bureau of Safety and Environmental Enforcement mandates dual BOP redundancy and real-time monitoring capability for deepwater permits. Houston clusters concentrate engineering services for Lower Tertiary field development programs.
Brazil
Pre-salt exploration in ultra-deepwater concessions accelerates deployment of 20,000 psi-rated BOP stacks with titanium alloy pressure housings. The National Petroleum Agency regulatory framework for well control tightens certification requirements for active drilling programs. The Santos Basin pre-salt cluster absorbs integrated system deployments to satisfy ANP permitting standards.
Norway
Electrification retrofits across North Sea installed bases drive replacement cycles for legacy hydraulic control systems. The Petroleum Safety Authority mandates real-time BOP status transmission to onshore operation centers, compressing response windows for well control events. The Johan Sverdrup field pilots permanent magnet motor configurations that eliminate high-pressure fluid columns.
United Kingdom
Field life extension programs in mature UK North Sea basins create recurring revenue pools through BOP recertification and component refurbishment. The Health and Safety Executive offshore safety framework governs well control equipment integrity management. Aberdeen clusters concentrate specialist intervention contractors absorbing capital costs under rental arrangements.
Angola
Deepwater fields between 1,000 and 3,000 meters water depth drive installed base volume for conventional multiplex electro-hydraulic systems. The national petroleum regulator enforces well control standards aligned with North Sea practice. Block developments offshore Cabinda absorb maintenance budgets for hydraulic system refurbishment and recertification cycles.
Subsea Well Access and BOP System Market Competitive Environment
Top-tier vendors anchor integrated system provision, while mid-tier specialists occupy retrofit and refurbishment niches. The supplier base concentrates around certified system integrators with API 16D qualification and DNV-ST-E273 protocol compliance. Strategic archetypes include full-service integrated contractors, component-focused forging houses, and digital-enabled service bundlers. Competitive moves center on multi-year integrated service contracts and all-electric actuation technology licensing.
Among the named players, Aker Solutions and TechnipFMC occupy positions within the integrated systems tier, exemplifying the engineering complexity barriers that concentrate margin pools. Baker Hughes Company anchors a position through proprietary technology representation. Schlumberger Limited sits within the digital-enabled service archetype, bundling monitoring capabilities with physical hardware across deepwater accounts.
| Leading Market Players |
|---|
| Aker Solutions |
| TechnipFMC |
| Baker Hughes Company |
| Dril-Quip |
| Oceaneering International |
| Schlumberger Limited |
| Weatherford International |
| Subsea 7 |
| National Oilwell Varco |
| Others |
Value Chain & Pricing Dynamics
API 16D certification mandates gate qualified supply and premium-tier pricing access for 20,000 psi-rated BOP stacks, compressing margins for uncertified hydraulic system providers while elevating certified integrated system premiums.
Pricing Analysis
Capacity additions in Southeast Asian forging facilities are reshaping price floors for high-grade alloy pressure housings. Three-tier pricing structure across API-certified premium, transitional standard, and uncertified economy levels segments buyer archetypes. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in economy-tier hydraulic controls is intensifying because legacy installed base refurbishment demand is fragmenting procurement volumes. National oil companies in Brazil and Norway exhibit lowest price sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Titanium alloy forgings for 20,000 psi pressure housings rest on specialty metallurgy producers concentrated in Japan, Germany, and Austria. Subsea accumulator banks and multiplex electro-hydraulic control pods draw from precision machining clusters in the United States and Norway. Single-source vulnerability persists for forged billet supply qualified to DNV-ST-E273 protocols. Distribution runs through certified system integrators with API 16D witness testing capabilities, excluding uncertified component suppliers from active drilling programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in subsea well access equipment is accelerating through electrification retrofits that displace hydraulic maintenance budgets toward premium-tier integrated service contracts.
For Market Incumbents: Deploy all-electric actuation technology licensing to capture replacement cycles across North Sea installed bases. Anchor defensive positioning through captive supply arrangements for high-grade alloy forgings. API 16D certification investment gates market access against emerging hydraulic system providers. For New Entrants and Emerging Players: Capture BOP recertification and component refurbishment revenue pools in mature UK North Sea and Gulf of Mexico basins. Field life extension services represent the most penetrable white-space segment. Pursue performance-based rental arrangements with specialist intervention contractors to bypass capital-intensive stack ownership barriers. For Investors and Strategic Acquirers: Roll-up economics work for digital-enabled service bundlers because real-time monitoring mandates are compressing acceptable response windows and elevating software-defined control architectures. Five-to-ten year viability favors suppliers with integrated hydraulic-mechanical-electrical capabilities. Watch API 16D certification timeline compression as the inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| All-Electric Actuation Deployment | Norway's Johan Sverdrup field pilots eliminate hydraulic fluid columns and reduce maintenance intervals. |
| API 16D Certification Investment | Witness testing protocols extend lead times and concentrate margin pools among qualified suppliers. |
| Integrated Service Contract Expansion | Brazil's ANP framework drives multi-year agreements bundling BOP provision with certification management. |
| Digital Twin Development | Physics-based BOP fatigue modeling enables condition-based maintenance contracts displacing calendar schedules. |
| Backward Integration into Forging | Titanium alloy pressure housing supply concentration in Western Europe and Japan creates captive supply incentives. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged drilling contractors, subsea equipment procurement leads at international oil companies, BOP system engineering directors, and aftermarket service heads. Secondary validation drew from API certification registries, ANP drilling permit disclosures, Norway Petroleum Safety Authority audit reports, and Bureau of Safety and Environmental Enforcement incident data. Bottom-up equipment shipment tracking and top-down operator capital expenditure analysis were triangulated against segment-level revenue estimates.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions included water depth tier, pressure rating, control architecture type, and regional regulatory framework cluster. CAGRs were derived from fitted growth curves calibrated to disclosed contract awards and installed base replacement cycles. Forecast inputs incorporated electrification retrofit adoption rates and pre-salt exploration permit issuance velocity.
Regulatory divergence between North Sea and Gulf of Mexico standards, titanium alloy supply disruption, and all-electric actuation pilot failure are the dominant revision risks. Forecasts reflect documented assumptions about certification timeline stability and operator maintenance budget allocation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market