
 Residential Energy Storage System Market | 2026-2036
Residential Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Energy Storage System Market Analysis
Chinese cell manufacturing is decoupling from pack assembly in North America and Europe as trade barriers harden. Tesla leverages its Nevada gigafactory to sustain vertically integrated battery pack production for residential deployments. LG Energy Solution anchors South Korean supply through its Michigan assembly operations, while Enphase Energy competes via modular microinverter-battery architecture that reduces installer dependency.
A residential energy storage system is an electrochemical or mechanical device rated typically between 5 kWh and 20 kWh usable capacity, designed to store electricity from on-site generation or the grid for later dispatch to household loads. The primary purpose is to reduce electricity costs through time-of-use arbitrage, provide backup power during outages, and enable participation in grid services. Lithium-ion chemistry dominates installed base due to energy density and cycle life advantages, though sodium-ion variants are gaining traction for cost-sensitive segments. Solar Integration technology leads new installations as module-level power electronics converge with battery management, while Virtual Power Plant aggregation creates recurring revenue streams for homeowners and margin expansion for platform operators.
FERC Order 2222 enables distributed energy resource participation in wholesale markets, reshaping how residential storage qualifies for capacity payments. California's SGIP incentive structure and CPUC rate reforms mandate storage pairing for solar export compensation, directly conditioning demand. EPA clean energy tax credits under the IRA reduce capital barriers for homeowners. Stakeholders must monitor interconnection queue reforms and utility rate case outcomes to anticipate where storage economics shift next.
Market Dynamics
Net metering reforms across US states are accelerating solar-storage pairing mandates, transforming standalone solar economics and forcing behind-the-meter storage adoption as a prerequisite for export compensation.
Growth Catalysts
- California's NEM 3.0 framework:The state's revised net metering rules slash export credits for solar-only systems, compelling homeowners to add storage to preserve project returns.
- Grid instability events:Extreme weather-induced outages in Texas and Florida drive backup power demand among residential buyers seeking energy independence.
- FERC Order 2222 implementation:Wholesale market participation rules for distributed resources unlock capacity revenue streams for aggregated residential battery fleets.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress pack assembler margins and delay project payback calculations for price-sensitive buyers.
- Chinese cell supply concentration:Geopolitical trade barriers disrupt cell-to-pack logistics, forcing North American assemblers to qualify alternative cell sources.
- Interconnection queue delays:Utility backlogs for distributed resource approval extend project timelines and erode installer economics.
Strategic Opportunities
- Virtual Power Plant aggregation platforms:Software-enabled grid services create recurring revenue models beyond hardware sales for platform operators.
- Sodium-ion chemistry commercialization:Emerging cell technology addresses cost-sensitive segments with reduced lithium dependency and improved thermal stability.
- Texas retail electricity market restructuring:Real-time pricing volatility creates arbitrage value for storage-equipped households.
Industry Challenges
- Certified installer scarcity:NEC 2020 rapid shutdown requirements and battery-specific electrical codes constrain qualified labor supply.
- Permitting standardization gaps:Jurisdictional variation in fire safety and installation codes forces product redesigns and compliance fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Energy Storage System Market |
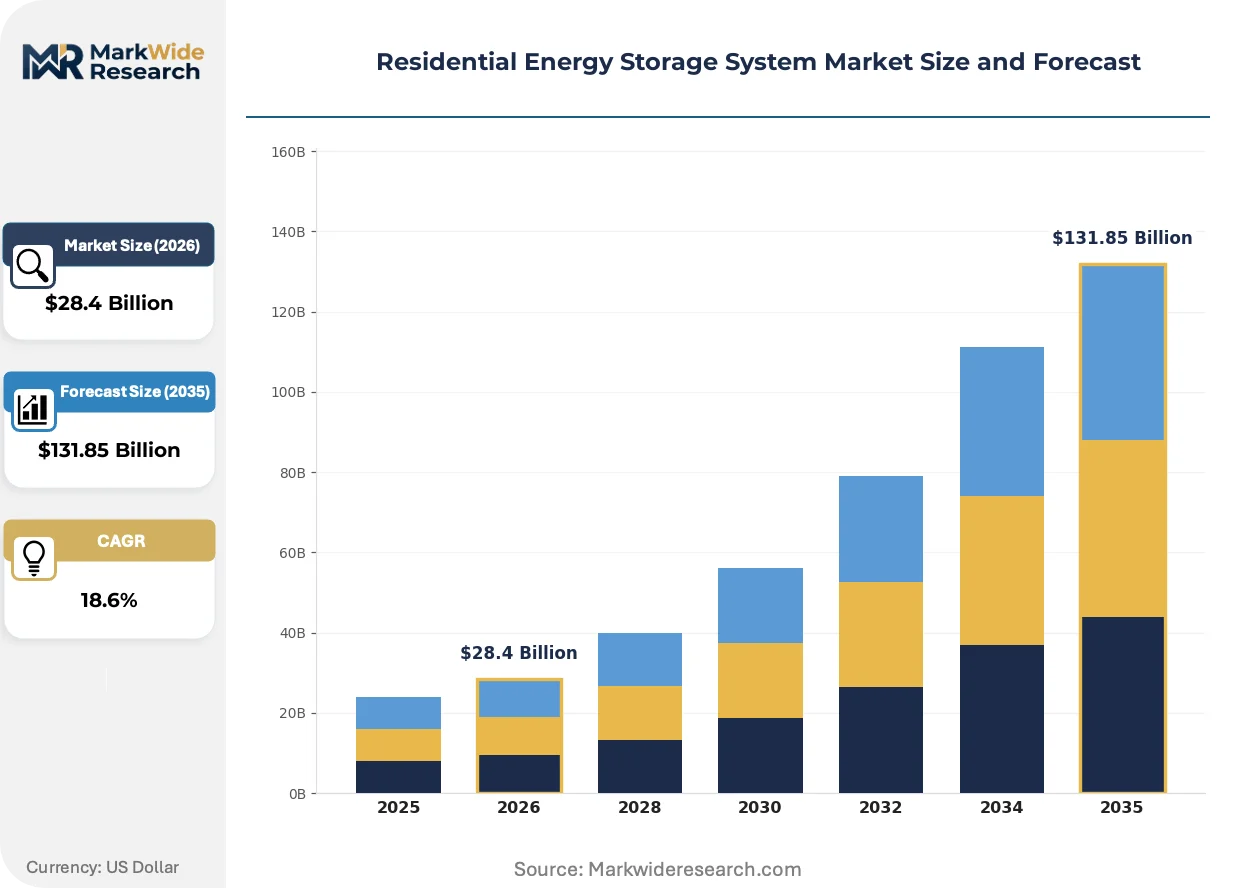
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $131.85 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Flow Batteries, Sodium-ion Technology: Solar Integration, Grid Support, Off-grid Solutions, Virtual Power Plant End User: Homeowners, Property Developers, Utility Companies, Energy Cooperatives Installation: On-grid Systems, Off-grid Systems, Hybrid Systems, Community Storage |
| Companies Covered | Tesla, LG Energy Solution, Panasonic Corporation, Samsung SDI, Sonnen GmbH, Enphase Energy, BYD, Huawei Technologies, SolarEdge Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Energy Storage System Market Emerging Trajectories
Module-level power electronics convergence with battery management systems is collapsing installation complexity and reshaping competitive advantage toward software-integrated hardware platforms.
AI-driven energy management software is automating dispatch decisions across time-of-use arbitrage, solar self-consumption optimization, and grid services participation. Homeowners with paired solar-storage systems adopt these platforms fastest where retail rate structures penalize unoptimized exports. The technology is compressing installer dependency by reducing commissioning time and ongoing system tuning requirements.
California's SGIP incentive restructuring now mandates storage pairing for extended solar export compensation, directly conditioning deployment economics. The policy compresses payback periods for hybrid systems while disqualifying standalone solar from full value stacking. Residential buyers in high-fire-threat districts respond fastest due to additional resiliency incentives.
Direct-to-consumer sales channels are displacing traditional installer-led procurement for modular, plug-compatible battery systems. Online configurators and remote permitting tools reduce customer acquisition costs for manufacturers while shifting technical support burdens. This pattern concentrates in states with standardized interconnection rules and virtual inspection approvals.
Residential Energy Storage System Market Segmentation
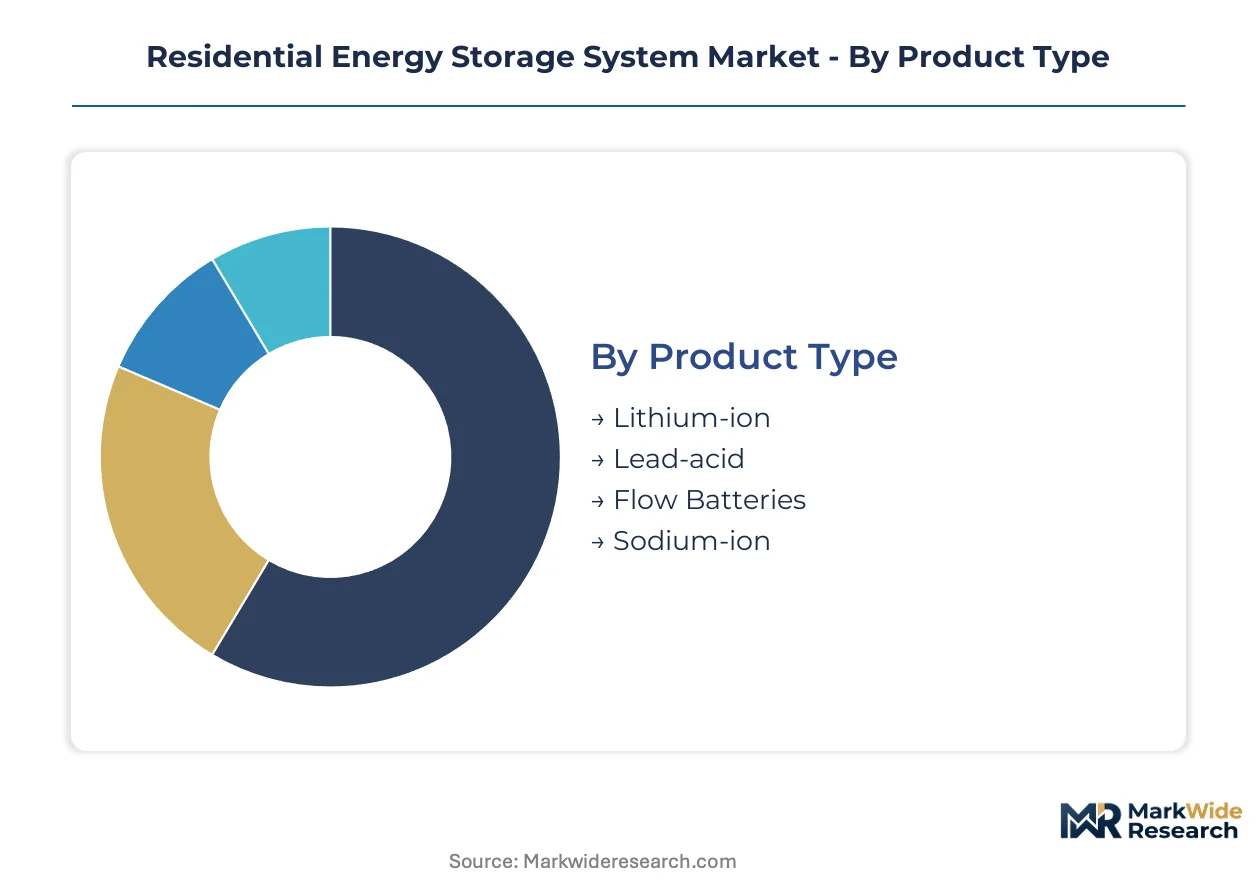
Segmentation in residential energy storage reveals how chemistry choices, software architectures, and ownership models reshape procurement economics. Each dimension carries distinct certification burdens and margin profiles that condition vendor strategy.
Product Type:
UL 1973 and IEC 62619 certifications dominate lithium-ion validation, while sodium-ion variants navigate emerging UN 38.3 transport protocols and nascent safety standards.
- Lithium-ion:NMC and LFP chemistries deliver 5-20 kWh usable capacity with 6,000-10,000 cycle life. Demand concentrates in California and Texas where NEM 3.0 export rules and storm-induced outages reward high energy density. FERC Order 2222 eligibility requires IEEE 1547.1 grid-interconnection compliance.
- Sodium-ion:Prussian white cathode systems eliminate cobalt and nickel dependencies, targeting cost-sensitive homeowners in Arizona and Nevada. Thermal runaway thresholds exceed lithium variants, though energy density penalties limit deployment to garage-sited installations with relaxed space constraints.
- Lead-acid:Flooded and AGM variants serve off-grid cabins and rural properties where capital constraints outweigh cycle life concerns.
- Flow Batteries:Vanadium redox systems scale to 20+ kWh for multi-day backup, finding niche adoption in fire-threat districts where lithium restrictions apply.
Lithium-ion sits at the top of the volume ranking, with sodium-ion climbing the fastest as cell qualification accelerates.
Technology:
Software integration depth separates margin tiers, with VPP platforms commanding recurring revenue premiums over hardware-only deployments.
- Solar Integration:DC-coupled architectures with module-level power electronics reduce conversion losses and enable rapid shutdown NEC 2020 compliance. California SGIP incentives mandate this pairing for extended export compensation, driving deployment in high-fire-threat districts.
- Virtual Power Plant:Aggregated dispatch software enrolls residential batteries in wholesale capacity markets under FERC Order 2222 rules. Texas ERCOT nodal pricing and California CAISO resource adequacy programs create revenue stacking opportunities for enrolled households.
- Grid Support:Frequency response and voltage regulation services require utility-controlled inverters with sub-second telemetry.
- Off-grid Solutions:Standalone inverters with generator integration serve rural properties beyond distribution infrastructure.
Solar Integration leads installed capacity, while Virtual Power Plant expands most quickly as retail electricity markets restructure.
End User:
Procurement authority and financing access fragment customer economics across single-family owners and institutional portfolio managers.
- Homeowners:Individual purchasers drive behind-the-meter growth through solar-plus-storage loans and lease structures. California, Texas, and Florida account for concentrated demand as net metering reforms and hurricane exposure reshape payback calculations.
- Property Developers:Master-planned communities in Arizona and Nevada pre-install battery systems to meet Title 24 building code mandates and attract premium buyers.
- Utility Companies:Investor-owned utilities deploy aggregated residential fleets as non-wires alternatives to distribution upgrades.
- Energy Cooperatives:Rural electric cooperatives in Colorado and Minnesota pilot community-owned storage for demand charge management.
Homeowners dominate transaction volume, with Property Developers gaining share fastest as building codes mandate storage readiness.
Installation:
Interconnection complexity and permitting pathways diverge sharply across grid-tied and island-capable configurations.
- Hybrid Systems:Grid-tied inverters with seamless islanding capability command premium pricing for backup power assurance. Florida building codes mandate this architecture for new construction in flood zones, while Texas retail market volatility rewards arbitrage-optimized dispatch.
- On-grid Systems:Simple battery-inverter pairs without islanding functionality serve time-of-use arbitrage in markets with stable grid infrastructure.
- Off-grid Systems:Generator-integrated installations serve properties beyond distribution network reach.
- Community Storage:Shared battery assets split ownership among multiple households, requiring complex metering and dispatch allocation frameworks.
Hybrid Systems anchor deployment value, with Community Storage showing steepest expansion trajectory as shared ownership models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting battery pack assembly toward jurisdictions with favorable trade rules and domestic content incentives. Manufacturers now site final assembly in markets where tariff exposure on Chinese cells can be minimized through regional qualification.
United States
NEM 3.0 export credit reductions and SGIP incentive restructuring compel storage pairing for solar projects. FERC Order 2222 enables wholesale market participation for aggregated residential fleets. Pack assembly concentrates in Nevada and Michigan where gigafactory-scale operations serve Western and Midwestern demand clusters.
Germany
High retail electricity tariffs and feed-in tariff phase-outs accelerate behind-the-meter storage economics. EU Green Deal domestic content requirements and ECHA battery passport regulations condition supply chain localization. Industrial activity clusters in Bavaria and Baden-Württemberg where automotive supplier networks pivot toward residential energy systems.
China
Dual carbon goals and provincial renewable integration mandates expand residential storage pilot programs. MIIT battery industry standards and GB certification protocols govern cell-to-pack export qualification. Manufacturing gravity centers on Guangdong and Jiangsu provinces where cell production scales feed global pack assembly demand.
Australia
High solar penetration rates and volatile wholesale pricing create arbitrage value for storage-equipped households. CER small-scale technology certificates and state-level battery rebate programs reduce capital barriers. Deployment concentrates in South Australia and Queensland where grid instability events and retail market restructuring reshape purchase decisions.
Japan
Post-Fukushima resilience mandates and METI storage subsidy programs sustain premium-tier demand. JIS safety standards and stringent fire codes favor established domestic suppliers. Installation activity clusters in Tokyo Metro and Kansai regions where density constraints and earthquake preparedness drive compact system preferences.
Residential Energy Storage System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sodium-ion commercialization and VPP software specialization. The vendor base stratifies across three tiers: integrated automotive suppliers with cell manufacturing depth, solar inverter specialists with module-level electronics convergence, and pure-play storage providers with software-centric business models. Dominant competitive moves include backward integration into cell supply and strategic partnerships with utility aggregators for grid services enrollment.
Among vertically integrated North American producers, Tesla anchors the premium tier through captive cell supply from its Nevada operations. LG Energy Solution represents the Korean conglomerate archetype with Michigan-based assembly serving domestic content requirements. Enphase Energy exemplifies the solar-native entrant competing via modular architecture that reduces installer dependency and accelerates commissioning timelines.
| Leading Market Players |
|---|
| Tesla |
| LG Energy Solution |
| Panasonic Corporation |
| Samsung SDI |
| Sonnen GmbH |
| Enphase Energy |
| BYD |
| Huawei Technologies |
| SolarEdge Technologies |
| Others |
Supply Flow & Price Mechanics
Sodium-ion cell commercialization is collapsing lithium dependency premiums while redrawing cathode material sourcing maps around salt-flat deposits rather than hard-rock mining concessions. This chemistry transition compresses pack-level costs for garage-sited installations and weakens incumbent pricing power tied to nickel-cobalt supply chains.
Pricing Analysis
Installer markup layers dominate residential battery economics, with certified electrical contractors capturing margin between factory gate and homeowner invoice. Three-tier pricing structure across premium, standard, and economy levels separates UL 9540A-certified systems with 10-year warranties from garage-sited sodium-ion alternatives with relaxed thermal specifications. Cost compression in the standard tier is intensifying because Chinese cell qualification is accelerating for North American pack assemblers. Price-sensitive buyers cluster in Arizona and Nevada where solar self-consumption economics alone justify deployment, while least-sensitive purchasers occupy California fire-threat districts where SGIP resiliency incentives mask capital outlay.
Supply Chain Analysis
IRA domestic content bonuses and EU Green Deal battery passport rules are forcing cell-to-pack traceability investments that favor regional assembly over pure import models. Supply concentrates in China for cathode active material, South Korea for separator films, and Japan for electrolyte formulations. Raw material dependencies rest on lithium carbonate from Chilean brine operations, nickel laterite from Indonesian smelters, and refined copper from Zambian-DRC cross-border logistics. Single-source vulnerability runs through Chinese graphite anode production where export licensing creates chokepoint exposure. Distribution runs through utility-approved installer networks in regulated states and direct-to-consumer channels where virtual inspection protocols exist.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in residential storage hinges on software-enabled recurring revenue displacing hardware-only transaction economics as VPP enrollment scales. Sodium-ion qualification timelines and FERC Order 2222 implementation velocity represent the twin levers compressing payback periods and premium-tier pricing power.
For Market Incumbents: To counter modular microinverter-battery architectures that reduce installer dependency, Tesla and LG Energy Solution must deepen captive cell supply control through Nevada and Michigan capacity additions. NEC 2020 rapid shutdown compliance investments and SGIP incentive capture software represent defensive certification moats against solar-native entrants.
For New Entrants and Emerging Players: FERC Order 2222 in Texas opens a window for wholesale market aggregation software specialists to capture capacity revenue streams without manufacturing hardware. Arizona and Nevada garage-sited sodium-ion deployments offer the most penetrable white-space, with direct-to-consumer online configurators as the viable go-to-market path around installer scarcity constraints.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play VPP software providers lacking hardware manufacturing depth but holding utility aggregation contracts. Long-term viability across the analysis window favors platform operators with enrolled battery fleets exceeding threshold scale for CAISO or ERCOT resource adequacy participation. The inflection signal to watch is interconnection queue reform passage in key states, which would unlock installer capacity and accelerate deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Supply | Nevada and Michigan gigafactory investments satisfy IRA domestic content requirements for tax credit eligibility. |
| VPP Platform Development | Aggregation software unlocks FERC Order 2222 wholesale market revenue streams beyond hardware margins. |
| Sodium-Ion Chemistry Qualification | Prussian white cathode systems address cost-sensitive segments with reduced lithium price exposure. |
| Direct-to-Consumer Channel Buildout | Online configurators and remote permitting bypass installer scarcity in standardized interconnection states. |
| Utility Aggregation Partnership | CAISO and ERCOT enrollment contracts create recurring revenue visibility for platform operators. |
Methodological Framework
Coverage spans the United States, Germany, China, Australia, and Japan, with primary inputs from each market's regulatory and deployment clusters. The approach combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators alongside secondary validation through EIA data, IEA reports, FERC filings, and project development databases. Bottom-up installation forecasts triangulate against top-down incentive budget allocations and interconnection queue tracking.
Granularity-level modeling distinguishes lithium-ion from sodium-ion chemistry tiers, solar-integrated from standalone battery architectures, and homeowner from property developer procurement channels across the projection horizon. CAGRs derive from segment-specific adoption curves conditioned on net metering reform implementation timelines and SGIP incentive exhaustion trajectories. Wholesale market participation assumptions feed from ERCOT nodal pricing volatility patterns and CAISO resource adequacy credit clearing prices.
Revisions become necessary when lithium carbonate price volatility exceeds modeled bands, when interconnection queue reforms stall in key states, or when FERC Order 2222 implementation timelines slip. Forecasts reflect documented assumptions regarding incentive continuity, installer labor supply elasticity, and cell import tariff trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Supercapacitor Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Ultracapacitors Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
South America Energy Storage Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
ASEAN Energy Storage Devices Market