
 South America Energy Storage Market | 2026-2036
South America Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
South America Energy Storage Market Analytics
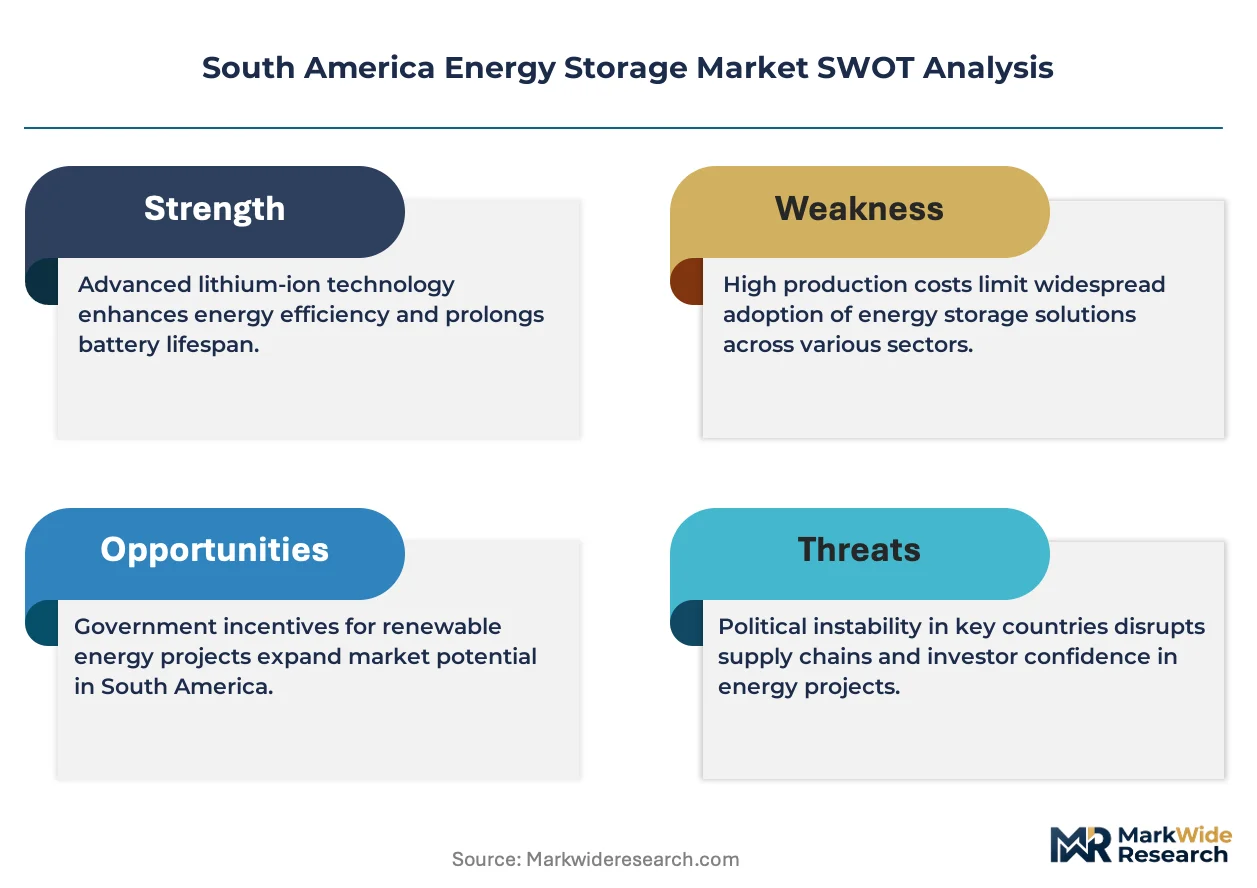
Lithium iron phosphate is rebalancing cost structures across utility-scale projects as developers prioritize cycle stability over energy density. Enel S.p.A. leverages its integrated generation portfolio to anchor large-scale hybrid solar-storage deployments in Chile and Brazil. Engie SA sustains competitive positioning through dedicated green hydrogen and storage divisions serving Colombian and Peruvian grids. Sungrow competes aggressively on power conversion and battery management system integration, capturing share in distributed commercial installations.
South America energy storage encompasses electrochemical and mechanical systems designed to capture electrical energy for timed discharge, with lithium-ion configurations typically operating at 85-95% round-trip efficiency and 4,000-8,000 cycle lifespans depending on chemistry and thermal management architecture. The primary commercial purpose centers on arbitrage, frequency regulation, and renewable firming for grids with rising variable generation penetration. Lithium-ion products dominate installed capacity given manufacturing scale and declining cell costs, while flow batteries occupy emerging niches in long-duration applications requiring 8-12 hour discharge profiles. Grid Storage and Renewable Integration applications command the largest addressable pools, though Backup Power segments in industrial corridors show faster margin expansion due to reliability premiums.
Brazil's ANEEL mandates grid stability investments from renewable generators, Chile's Ministry of Energy enforces storage co-location requirements for new solar concessions, and Colombia's UPME integrates battery targets into national reliability planning. These frameworks directly shape procurement timelines, technical specifications for frequency response, and market access for non-domestic equipment suppliers. Stakeholders must monitor evolving local content rules and auction designs that increasingly penalize standalone renewable bids lacking firming capacity.
Market Dynamics
The lithium iron phosphate chemistry transition is compressing unit economics for utility-scale developers while Chile's Ministry of Energy co-location mandates and Brazil's ANEEL grid stability requirements accelerate procurement timelines for battery systems paired with solar and wind assets.
Growth Catalysts
- Chile's Solar Co-location Mandates:The Ministry of Energy requires battery storage for new Atacama Desert solar concessions, forcing developers to procure lithium-ion systems alongside photovoltaic installations.
- Frequency Response Arbitrage:Grid operators in Colombia and Peru now compensate battery assets for fast-frequency regulation services, creating revenue streams beyond energy shifting.
- LFP Chemistry Scale:Manufacturing scale for lithium iron phosphate cells is lowering delivered costs per megawatt-hour and extending cycle life expectations for utility buyers.
Market Restraints
- Lithium Carbonate Volatility:Battery-grade lithium carbonate price swings from Chilean and Argentine brine operations create input cost uncertainty for cell packagers.
- Asian Cell Concentration:Over 80 percent of lithium-ion cell production concentrates in Chinese and South Korean manufacturing bases, exposing South American project developers to supply chain disruption risk.
- Flow Battery Competition:Vanadium redox flow systems are capturing long-duration storage tenders requiring 8-12 hour discharge profiles, limiting lithium-ion addressable market in grid-scale applications.
Strategic Opportunities
- Colombian Industrial Backup:Manufacturing corridors around Bogotá and Medellín show underpenetrated demand for commercial-scale battery systems serving reliability-sensitive pharmaceutical and food processing facilities.
- Green Hydrogen Convergence:Electrolyzer-battery hybrid configurations are emerging as a co-optimization play for Chilean and Brazilian developers seeking to firm renewable output while producing hydrogen for export.
- ANEEL Auction Design Evolution:Brazil's regulator is revising renewable auction rules to penalize standalone wind and solar bids, creating procurement pull-through for storage-equipped projects.
Industry Challenges
- Thermal Management Engineering Gap:Local EPC contractors lack experience sizing HVAC and fire suppression systems for megawatt-scale lithium-ion installations in high-altitude Andean and tropical coastal environments.
- Interconnection Queue Backlogs:Grid connection studies for storage-plus-renewable projects face 18-24 month delays at transmission operators in Brazil and Chile, compressing project IRRs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Energy Storage Market |
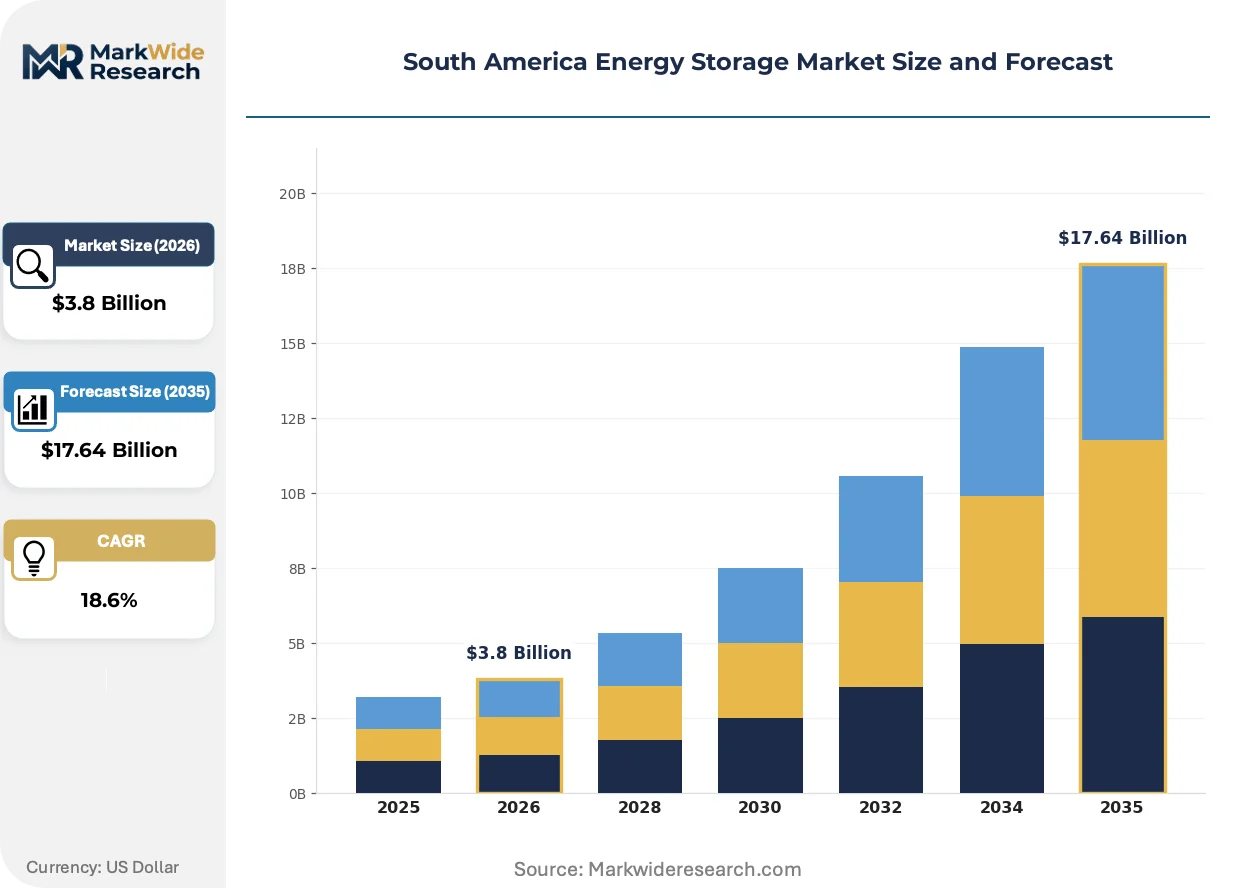
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Flow Batteries, Flywheel Energy Storage Application: Grid Storage, Renewable Integration, Backup Power, Electric Vehicles Installation Type: On-Site, Off-Site, Centralized, Distributed End User: Utilities, Commercial, Residential, Industrial |
| Companies Covered | Enel S.p.A., Engie SA, Sungrow, Grenergy, LG Energy Solution, Fluence Energy, BYD Co Ltd, Copenhagen Infrastructure Partners, AES Andes, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Energy Storage Market Evolving Landscape
Technology convergence and procurement model evolution are redefining competitive advantage in South American energy storage. Developers now prioritize integrated hardware-software platforms and service-based revenue structures over pure equipment sales.
Lithium iron phosphate is absorbing market share from nickel manganese cobalt configurations across utility-scale deployments. Brazilian and Chilean project developers are specifying LFP for new solar-storage hybrids given superior thermal stability and 6,000-plus cycle life ratings. This chemistry shift is compressing pricing for NMC suppliers and forcing cell manufacturers to reconfigure regional supply commitments.
Brazil's ANEEL has mandated grid stability investments from renewable generators through revised auction participation rules. Developers must now demonstrate frequency response capability or partner with storage providers to qualify for capacity payments. This regulatory pressure is accelerating procurement of battery management systems with sub-second response times in the northeastern wind corridor.
Power purchase agreement structures are evolving from equipment-centric to availability-guarantee contracts. Industrial offtakers in Colombian manufacturing zones now procure storage-as-a-service rather than owning battery assets, shifting balance sheet risk to specialized operators. This model is concentrating in pharmaceutical and data center verticals where uptime penalties exceed energy arbitrage value.
South America Energy Storage Market Segmentation
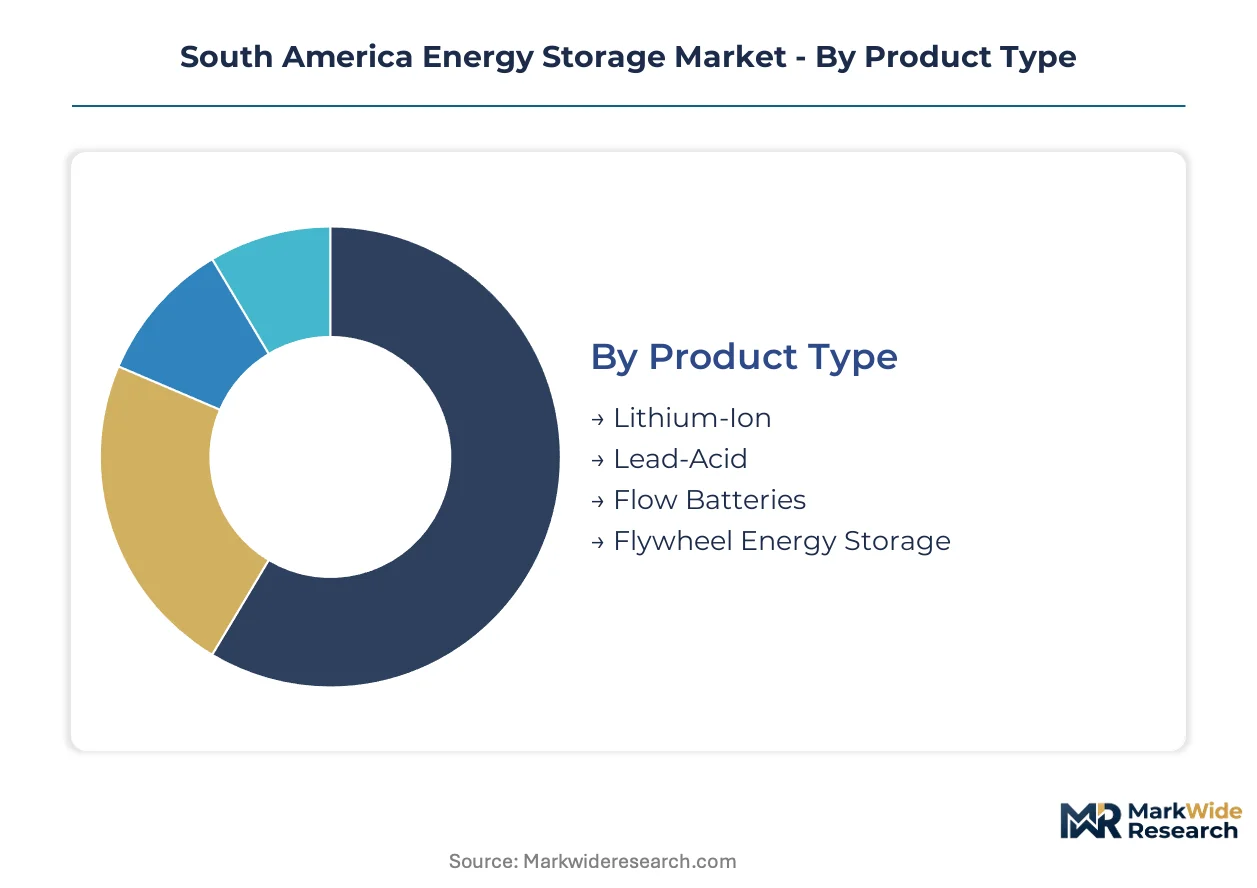
Technology differentiation and deployment architecture determine procurement economics across South American energy storage. Developers select chemistries and installation modes based on grid service requirements, thermal constraints, and regulatory co-location mandates.
Product Type:
Lithium iron phosphate chemistry is rebalancing procurement specifications as developers prioritize cycle stability over energy density in utility-scale tenders.
- Lithium-Ion:Lithium iron phosphate configurations dominate new procurement given 6,000-plus cycle ratings and superior thermal stability for Atacama Desert and northeastern Brazil deployments. Grid operators in Chile and Colombia now specify LFP for frequency response assets.
- Lead-Acid:Mature technology occupies commercial backup segments where capital constraints outweigh cycle life requirements. Colombian industrial corridors specify lead-acid for short-duration reliability applications.
- Flow Batteries:Vanadium redox systems capture long-duration tenders requiring 8-12 hour discharge profiles. Chilean solar developers evaluate flow batteries for overnight firming.
- Flywheel Energy Storage:Kinetic storage serves frequency regulation niches demanding sub-second response. Brazilian grid operators deploy flywheels for inertia services in wind corridors.
Lithium-Ion leads on scale; Flow Batteries leads on momentum.
Application:
Revenue model evolution is fragmenting the addressable market across energy arbitrage, capacity services, and behind-the-meter reliability.
- Grid Storage:Frequency regulation and peak shaving services command the largest installed base. ANEEL auction redesigns in Brazil now mandate storage-equipped bids for grid stability payments.
- Renewable Integration:Solar-plus-storage and wind-plus-storage hybrids concentrate near-term procurement. Chile's Ministry of Energy enforces battery co-location for new Atacama concessions.
- Backup Power:Pharmaceutical and data center verticals in Bogotá and Medellín drive fastest margin expansion. Uptime penalties exceed energy arbitrage value for Colombian industrial offtakers.
- Electric Vehicles:Second-life battery repurposing creates emerging supply for stationary applications. Brazilian charging infrastructure operators evaluate retired EV packs for grid services.
Grid Storage leads on scale; Backup Power leads on momentum.
Installation Type:
Project finance structures and interconnection access determine siting decisions across centralized utility assets and distributed commercial systems.
- On-Site:Co-located assets at generation facilities reduce transmission losses and land permitting complexity. Chilean solar developers favor on-site batteries to meet co-location mandates.
- Off-Site:Standalone storage farms aggregate capacity for wholesale market participation. Brazilian developers pursue off-site configurations where grid congestion limits generator interconnection.
- Centralized:Utility-owned assets at substations provide system-wide reliability services. Colombia's UPME targets centralized installations for national reliability planning.
- Distributed:Commercial and industrial behind-the-meter systems avoid demand charges and backup premiums. Sungrow captures share in distributed segments through integrated power conversion platforms.
Centralized leads on scale; Distributed leads on momentum.
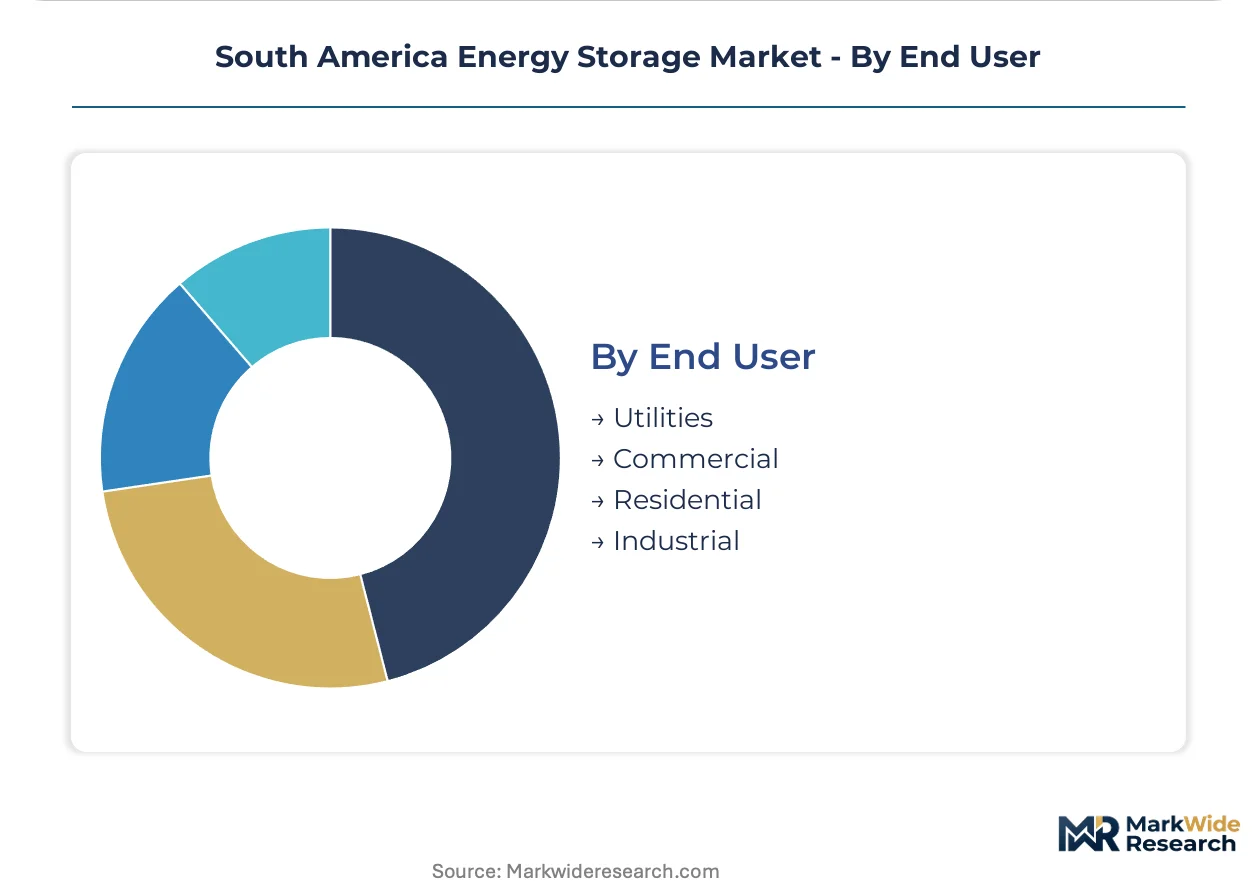
End User:
Procurement sophistication and balance sheet capacity segment demand across regulated utilities, commercial offtakers, and industrial facilities.
- Utilities:State-owned and private grid operators anchor utility-scale procurement through auction mechanisms. Enel and Engie leverage integrated generation portfolios to anchor hybrid deployments.
- Commercial:Retail and office building operators evaluate storage-as-a-service models to avoid capital expenditure. Colombian pharmaceutical facilities contract specialized operators for uptime guarantees.
- Residential:Solar-plus-storage adoption remains nascent outside premium segments. Net metering policy uncertainty constrains household investment in Brazil and Chile.
- Industrial:Manufacturing corridors prioritize reliability over energy arbitrage. Food processing and data center verticals in Peru and Colombia drive premium pricing for guaranteed availability.
Utilities leads on scale; Industrial leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Atacama Desert solar corridor anchors near-term procurement activity as Chilean developers accelerate battery co-location investments to meet concession requirements. Brazil's northeastern wind belt and Colombia's Andean manufacturing corridors concentrate complementary demand for grid stability assets. Regulatory mandates across these three markets are reshaping deployment timelines and technical specifications for electrochemical storage systems.
Brazil
Northeastern wind farms in Rio Grande do Norte and Ceará drive procurement of frequency-responsive battery systems. ANEEL's revised auction rules now penalize standalone renewable bids lacking firming capacity, forcing developers to partner with storage providers. São Paulo-based industrial clusters evaluate behind-the-meter lithium-ion configurations to manage demand charges and backup premiums.
Chile
Atacama Desert solar installations concentrate the continent's most aggressive storage procurement as developers comply with Ministry of Energy co-location mandates. Antofagasta and Calama substations host utility-scale lithium iron phosphate assets serving mining load centers. The northern transmission network's congestion forces developers to specify batteries with sub-second frequency response capabilities.
Colombia
Andean wind corridors in La Guajira and manufacturing zones around Bogotá anchor divergent demand profiles for grid and industrial applications. UPME's national reliability planning integrates battery targets into capacity expansion roadmaps. Medellín's pharmaceutical and data center verticals contract specialized operators for storage-as-a-service uptime guarantees.
Peru
Lima's coastal industrial corridor and southern mining districts drive procurement of hybrid renewable-storage configurations. The Ministry of Energy and Mines evaluates storage co-location requirements for new solar concessions in Arequipa and Moquegua. Grid operators compensate battery assets for fast-frequency regulation services, creating revenue streams beyond energy arbitrage.
South America Energy Storage Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek integrated hardware-software platforms and specialized operators pursue availability-guarantee contracts. The vendor base organizes around three tiers: integrated European utilities with captive generation portfolios, Asian cell and power electronics manufacturers, and specialized independent power producers. Archetypes include hybrid project developers anchoring utility-scale deployments, power conversion specialists capturing distributed commercial share, and dedicated storage operators managing storage-as-a-service contracts. Geographic expansion and technology licensing represent the dominant competitive moves as players seek positioning across multiple national regulatory frameworks.
Within the integrated utility tier, Enel S.p.A. and Engie SA exemplify archetypes leveraging captive generation portfolios to anchor hybrid solar-storage deployments across Chile and Brazil. Sungrow occupies a position among power conversion specialists competing aggressively on battery management system integration for distributed installations. These three entities represent contrasting strategic postures: European utilities with project development depth, and Asian equipment providers with manufacturing scale advantages in cell and inverter supply.
| Leading Market Players |
|---|
| Enel S.p.A. |
| Engie SA |
| Sungrow |
| Grenergy |
| LG Energy Solution |
| Fluence Energy |
| BYD Co Ltd |
| Copenhagen Infrastructure Partners |
| AES Andes |
| Others |
Value Network & Pricing Analysis
Battery system integration engineers in Shenzhen and Seoul concentrate technical expertise that compresses labor-cost spreads between premium and standard-tier lithium-ion installations across South American utility tenders.
Pricing Analysis
Input-cost pass-through from lithium carbonate volatility in Chilean and Argentine brine operations compresses margins for cell packagers serving Brazilian and Colombian developers. Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation driven by certification tier (UL 9540A fire safety validation) and geographic delivery cost to remote Atacama or northeastern Brazil sites. Pricing pressure stems from LFP chemistry scale lowering delivered costs per megawatt-hour. Industrial offtakers in Colombian manufacturing corridors show highest price sensitivity, while mining load centers in Chilean northern grids accept reliability premiums.
Supply Chain Analysis
Lithium iron phosphate cell supply rests on Chinese and South Korean manufacturing bases, with cathode active material production concentrated in Fujian and Hunan provinces. Raw material dependencies include battery-grade lithium carbonate from Chilean and Argentine salares, copper foil from Chinese smelters, and electrolyte salts from Japanese specialty chemical producers. Single-source vulnerability from Asian cell concentration exposes South American project developers to logistics chokepoint risk at Pacific port terminals. Distribution runs through EPC contractors with regional project development capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America energy storage market functions as a stable compounder anchored by regulatory mandates that enforce storage co-location across renewable concessions in Chile, Brazil, and Colombia.
For Market Incumbents: Lock in procurement relationships with Chilean and Brazilian grid operators ahead of ANEEL auction redesigns that penalize standalone renewable bids. Secure captive lithium carbonate offtake from Atacama brine producers to defend against input cost volatility. Deepen backward integration into power conversion hardware to protect margin position from Sungrow's aggressive distributed commercial pricing.
For New Entrants and Emerging Players: Launch via storage-as-a-service contracts targeting Colombian pharmaceutical and data center verticals in Bogotá and Medellín where uptime penalties exceed energy arbitrage value. Prioritize industrial backup segments over saturated utility-scale tenders. Establish partnerships with local EPC contractors lacking thermal management engineering experience for megawatt-scale lithium-ion installations.
For Investors and Strategic Acquirers: European integrated utilities with captive generation portfolios are the most active acquirer in this space, seeking project development pipelines across multiple national regulatory frameworks. Acquisition targets include specialized storage operators managing availability-guarantee contracts and power conversion specialists with battery management system integration capabilities. Watch for electrolyzer-battery hybrid configuration announcements as inflection indicators for green hydrogen convergence plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Restructuring | Availability-guarantee contracts shift balance sheet risk to specialized operators serving Colombian pharmaceutical facilities. |
| LFP Chemistry Manufacturing Scale-Up | Chinese cell producers extend cycle life ratings to capture Chilean Ministry of Energy co-location mandates. |
| Backward Integration into Lithium Supply | Developers secure captive carbonate offtake from Atacama brine operations to stabilize input cost exposure. |
| Green Hydrogen Convergence Partnerships | Electrolyzer-battery hybrid configurations firm renewable output for Brazilian export-oriented hydrogen production. |
| Regional EPC Capability Acquisition | Storage operators acquire local contractors to close thermal management engineering gaps in Andean deployments. |
Research Methodology
Coverage spans Brazil, Chile, Colombia, and Peru, with primary inputs from each market combining structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators alongside secondary validation from ANEEL regulatory filings, Chilean Ministry of Energy concession databases, and UPME national reliability planning documents. Bottom-up project pipeline tracking triangulates against top-down market sizing from customs import records and equipment supplier shipment disclosures.
Granularity-level modeling disaggregates volume and value outputs across chemistry configuration, application type, installation architecture, and end-user procurement sophistication throughout the forecast period. CAGRs derive from regression analysis against renewable penetration trajectories and regulatory mandate implementation schedules. Industry-specific forecast inputs include interconnection queue backlogs at Brazilian and Chilean transmission operators and evolving local content requirements for non-domestic equipment suppliers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium carbonate price spike scenarios or Pacific supply chain disruption events. Forecasts reflect documented assumptions regarding ANEEL auction rule evolution and Chilean co-location mandate enforcement timelines. Lithium brine production expansion, Asian cell manufacturing capacity additions, and green hydrogen subsidy program announcements constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Power Bank Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Water Electrolysis Machine Market