
 Natural Gas Storage Market | 2026-2036
Natural Gas Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Gas Storage Market Intelligence
China's rapid expansion of domestic storage capacity is narrowing the supply-demand gap for seasonal price arbitrage opportunities. Major operators like Enbridge Inc. leverage extensive North American pipeline networks to optimize storage asset utilization. Gazprom PJSC sustains its strategic influence through its control over vast depleted reservoir storage sites in Eastern Europe. Separately, Kinder Morgan Inc. specializes in high-deliverability salt cavern facilities along the US Gulf Coast.
Natural gas storage involves injecting surplus gas into large-volume containment facilities, such as depleted reservoirs or salt caverns, for later withdrawal. These systems maintain specific pressures and gas quality to ensure grid stability and manage peak energy loads. Underground storage, particularly in depleted reservoirs, constitutes the largest volume segment due to its scale and cost-effectiveness. Among applications, peak shaving and seasonal storage remain the core revenue drivers for utility companies and power producers.
Regulatory frameworks from bodies like the US Federal Energy Regulatory Commission (FERC) and directives under the EU Green Deal govern facility permitting, safety, and market access. In parallel, China's National Development and Reform Commission sets mandatory storage capacity targets for gas suppliers, directly shaping investment decisions. Stakeholder success will depend on correctly anticipating the pace of hydrogen blending mandates and their impact on existing asset compatibility and valuation.
Market Dynamics
The central dynamic is the dual pressure from decarbonization mandates and the concurrent need for grid stability. Intermittent renewable energy sources require reliable backup, positioning natural gas storage as a critical buffer asset in the energy transition.
Growth Catalysts
- Transitional Fuel Policies:The EU Green Deal positions natural gas as a bridge fuel, stimulating investment in storage infrastructure to ensure supply security.
- Renewable Grid Balancing:Power producers expand gas storage to provide backup capacity for intermittent wind and solar generation, ensuring grid stability.
- LNG Export Growth:The build-out of liquefied natural gas export terminals, particularly on the US Gulf Coast, creates concentrated demand for storage to manage feedstock supply.
Market Restraints
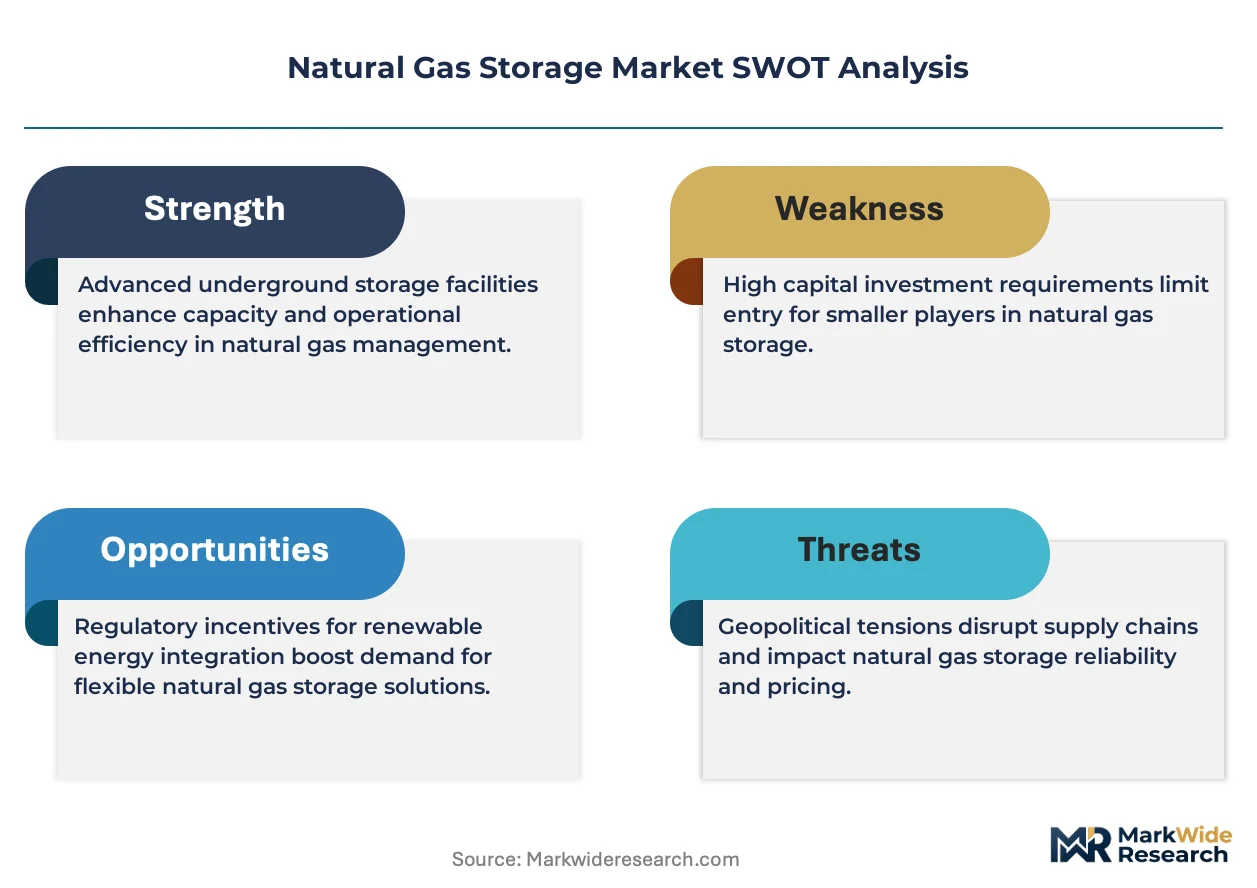
- High Capital Intensity:The substantial upfront investment for new underground storage, particularly salt caverns, limits market entry for smaller operators.
- Lengthy Permitting Processes:Complex regulatory approvals from bodies like the US Federal Energy Regulatory Commission (FERC) create significant project delays and investment uncertainty.
- Long-Term Substitution Threat:The falling costs of utility-scale battery storage and the development of green hydrogen pose a structural threat to gas for peak shaving applications.
Strategic Opportunities
- Hydrogen Storage Conversion:Repurposing existing gas infrastructure like salt caverns for storing hydrogen blends or pure hydrogen offers a significant long-term growth pathway for asset owners.
- Asian Market Development:Building storage capacity in emerging Asian economies that are expanding their gas infrastructure provides a key geographic growth opportunity.
- Decentralized Storage Services:Developing high-deliverability storage for industrial clusters creates a new service model beyond traditional utility-scale contracts.
Industry Challenges
- Aging Asset Integrity:Operators face rising costs to maintain the integrity of older storage assets, like depleted reservoirs, to meet stricter safety and environmental rules.
- Specialized Talent Shortages:A scarcity of geoscientists and reservoir engineers with expertise in subsurface storage management hinders project development and safe operational oversight.
- Operational Technology Security:Protecting critical control systems for gas injection and withdrawal from sophisticated cyber threats is a constant operational challenge for facility owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Gas Storage Market |
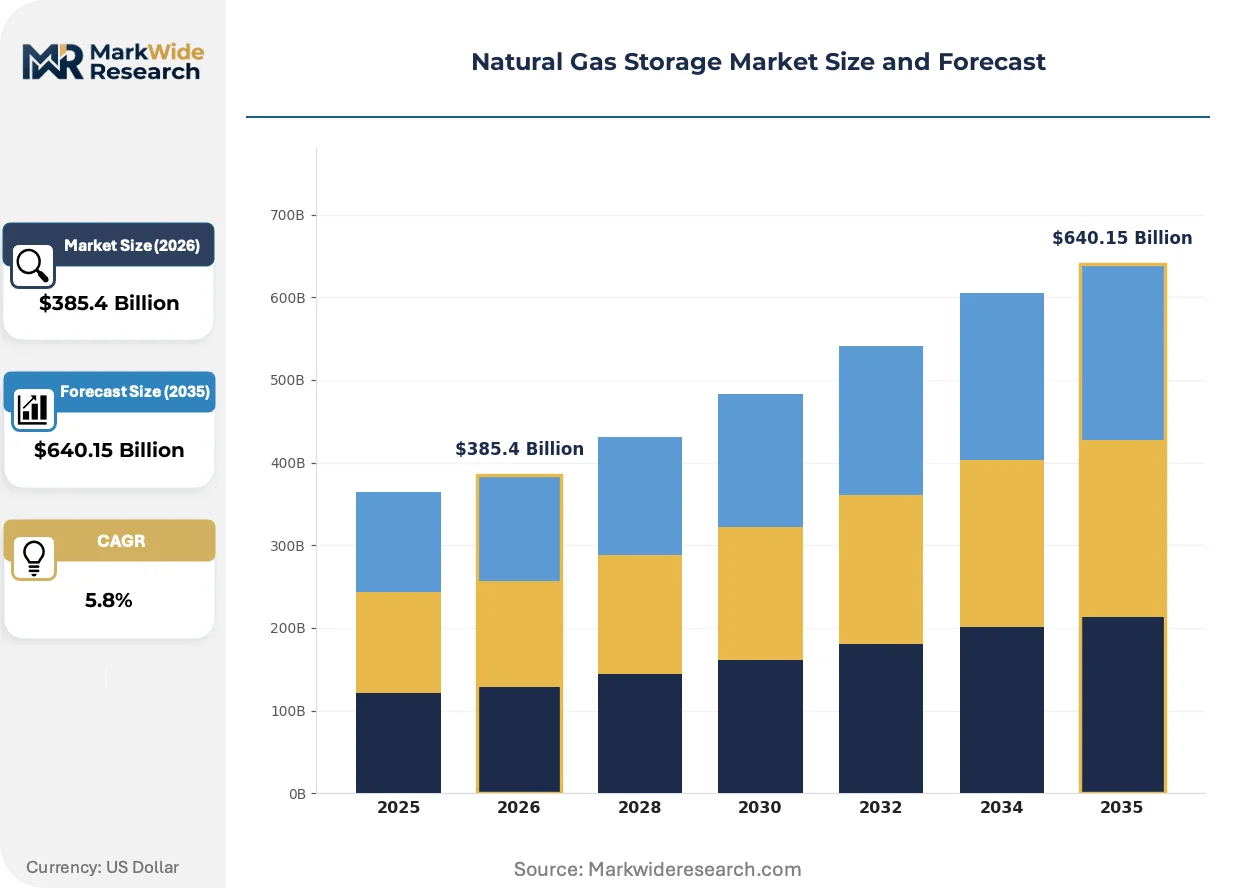
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $640.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Underground Storage, Aboveground Storage, Liquefied Natural Gas, Depleted Reservoirs, Salt Caverns Application: Peak Shaving, Seasonal Storage, Emergency Reserves, Balancing Supply & Demand, Load Management End User: Utility Companies, Renewable Energy Firms, Industrial Manufacturers, Gas Distributors, Power Producers Technology: Compressed Gas Storage, Cryogenic Technology, Adsorbed Natural Gas, Pipeline Storage, Pressure Vessels |
| Companies Covered | Kinder Morgan Inc., Sempra Infrastructure, Gazprom PJSC, Royal Vopak N.V., National Grid plc, China National Petroleum Corporation, Enbridge Inc., NAFTA a.s., TC Energy Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Gas Storage Market Strategic Shifts & Innovations
Digitalization is enhancing the precision of storage management, from reservoir modeling to withdrawal scheduling. Concurrently, technological innovation is focused on adapting existing infrastructure for future energy systems, including compatibility with low-carbon gases.
Advanced sensor networks combined with AI-powered analytics provide real-time monitoring of subsurface conditions in storage reservoirs. Major operators are rapidly deploying these systems to improve operational safety and efficiency. This integration is hybridizing the physical gas storage asset with a dynamic digital twin, enabling predictive maintenance and optimizing withdrawal strategies for seasonal arbitrage.
Mandatory storage capacity targets set by China's National Development and Reform Commission (NDRC) are a powerful market driver. These regulations compel gas suppliers to build or contract for storage capacity equivalent to a set percentage of their annual sales. This policy directly impacts all gas distributors in China, forcing rapid investment in new underground facilities and LNG tank expansions to meet compliance.
A shift towards more flexible, short-term contracting models is altering how storage capacity is sold. The traditional model of long-term, fixed-volume contracts is being supplemented by dynamic, unbundled service offerings. This trend is most visible in liberalized European energy markets, where traders and industrial consumers procure capacity and services to manage price volatility and supply risk more actively.
Natural Gas Storage Market Segmentation
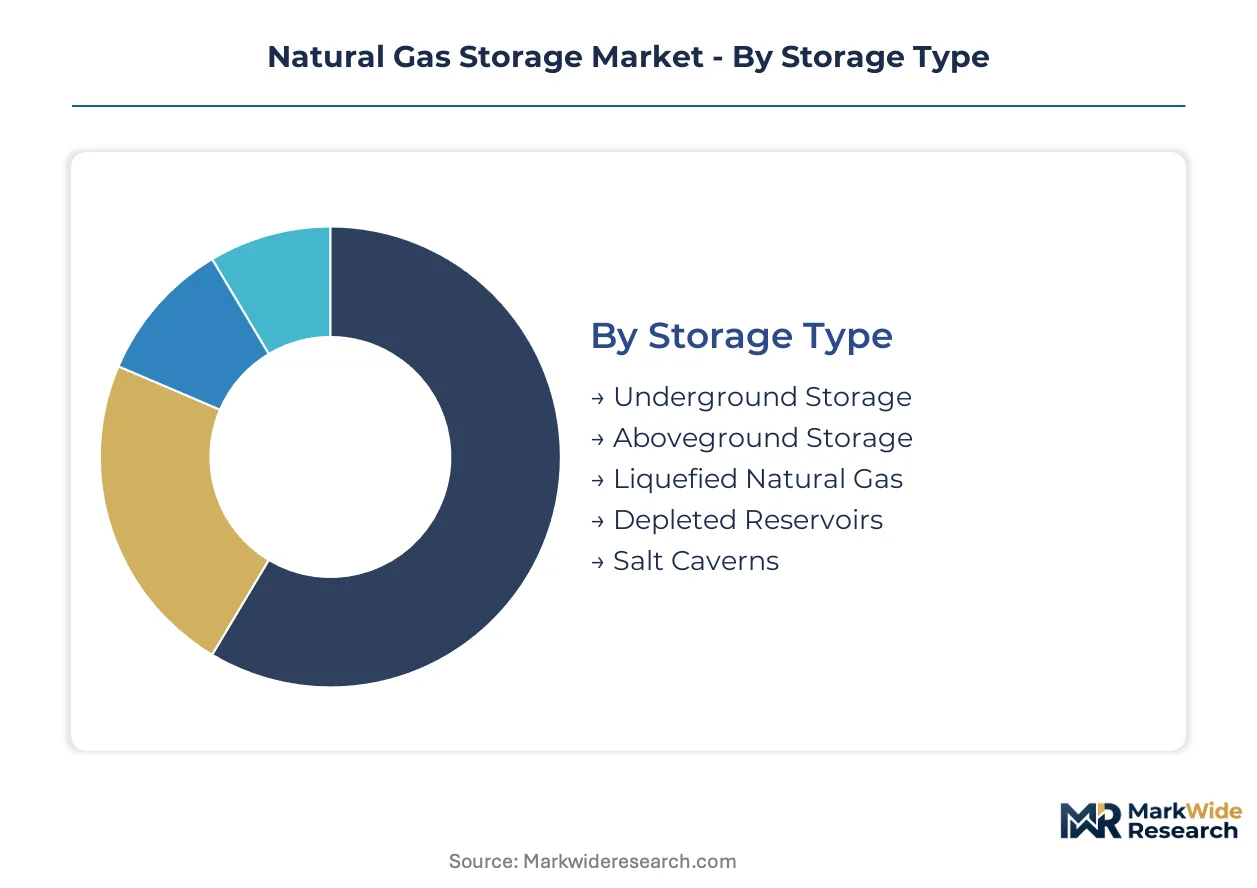
Understanding the Natural Gas Storage Market segmentation provides clarity on operational priorities and investment allocation. Distinct storage types cater to varying demand profiles, while diverse end-users drive specific application requirements. Technology advancements further refine efficiency and safety across the market infrastructure.
Storage Type:
The operational cycle time for natural gas storage varies significantly across different facility types, from rapid withdrawal capabilities to long-duration seasonal buffering.
- Depleted Reservoirs:These facilities utilize exhausted oil or gas fields, offering large storage volumes and cost-effective solutions for seasonal balancing. Demand concentrates in regions like Eastern Europe and the US Gulf Coast, where extensive hydrocarbon production history provides suitable geological formations.
- Salt Caverns:Formed by dissolving salt deposits, these facilities provide high deliverability rates and rapid cycling capabilities, ideal for peak shaving and daily load balancing. The US Gulf Coast sees concentrated demand for salt caverns due to LNG export facilities requiring flexible feedstock supply.
- Underground Storage:This broad category encompasses depleted reservoirs, salt caverns, and aquifers, serving as the primary method for large-scale, long-term natural gas containment.
- Liquefied Natural Gas:Stored in cryogenic tanks at extremely low temperatures, LNG facilities enable high-density storage and global transport, crucial for import/export terminals and strategic reserves.
- Aboveground Storage:Primarily used for smaller volumes and shorter durations, these facilities often serve industrial consumers or act as buffer storage at processing plants.
Depleted Reservoirs anchors the volume base while Salt Caverns gains share at the steepest rate for high-deliverability applications.
Application:
Service duration and response speed define the primary applications for natural gas storage, ranging from instantaneous grid support to multi-month energy security.
- Peak Shaving:This application involves withdrawing gas during periods of highest demand, often daily or weekly, to meet sudden load spikes and stabilize prices. Utility companies in North America and Europe rely heavily on peak shaving for grid reliability.
- Seasonal Storage:Facilities store gas during low-demand periods (e.g., summer) for withdrawal during high-demand seasons (e.g., winter), ensuring supply security and price arbitrage. European gas distributors prioritize seasonal storage to manage winter heating demand.
- Emergency Reserves:Strategic stockpiles maintained for national energy security or to mitigate supply disruptions from unforeseen events, such as pipeline outages or geopolitical incidents.
- Balancing Supply & Demand:Storage facilities absorb excess gas during oversupply and release it during undersupply, maintaining pipeline pressure and market equilibrium.
- Load Management:Optimizing gas flow to match varying consumption patterns of industrial users or power plants, ensuring a consistent and efficient energy supply.
The demand for Peak Shaving is driven by short-term grid volatility, whereas Seasonal Storage addresses long-term supply security requirements.
End User:
The regulatory and operational requirements of each end-user segment dictate their specific natural gas storage needs and contracting models.
- Utility Companies:These entities manage gas distribution networks, utilizing storage to balance daily and seasonal demand fluctuations for residential and commercial customers. Regulatory mandates from bodies like the US Federal Energy Regulatory Commission (FERC) influence their storage investments.
- Power Producers:Gas-fired power plants use storage to ensure a reliable fuel supply, particularly as backup for intermittent renewable energy sources like wind and solar. European power producers are expanding storage capacity to support grid stability under the EU Green Deal.
- Gas Distributors:Companies responsible for transporting and delivering natural gas to end consumers, relying on storage for operational flexibility and supply assurance.
- Industrial Manufacturers:Energy-intensive industries, such as chemicals or fertilizers, use storage to manage their feedstock supply, hedge against price volatility, and ensure continuous operations.
- Renewable Energy Firms:While not direct gas consumers, these firms indirectly drive gas storage demand by requiring flexible gas-fired generation as a grid balancing partner.
Utility Companies represent the largest contracting base, with Power Producers rapidly increasing their storage procurement for grid stabilization.
Technology:
The technological sophistication of natural gas storage solutions reflects advancements in containment, monitoring, and energy density for various operational demands.
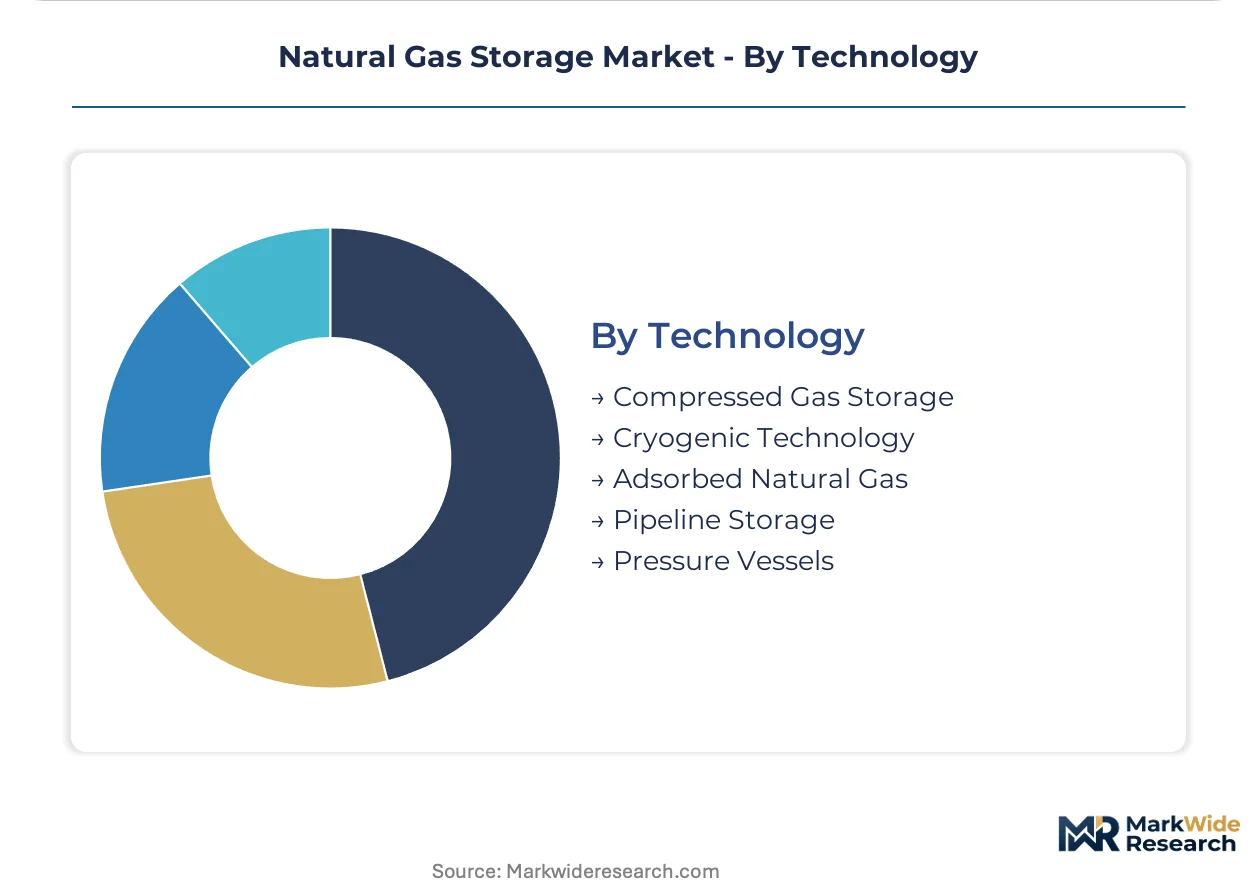
- Compressed Gas Storage:This method stores natural gas at high pressure in underground formations or aboveground vessels, offering a mature and widely deployed storage solution. Demand is consistent across established gas infrastructure networks in North America.
- Cryogenic Technology:Involves cooling natural gas to -162°C (-260°F) to liquefy it, enabling high-density storage in specialized tanks for efficient transportation and large-scale reserves. Asia-Pacific countries like China are expanding LNG import terminals, driving demand for this technology.
- Pipeline Storage:Utilizing the existing pipeline network's line pack capacity to temporarily store gas by increasing pressure, offering short-term operational flexibility.
- Adsorbed Natural Gas:Stores natural gas at lower pressures by adsorbing it onto porous materials, a developing technology with potential for smaller-scale, distributed storage applications.
- Pressure Vessels:Aboveground steel tanks designed to hold compressed natural gas, typically for industrial on-site storage or smaller distribution hubs.
Compressed Gas Storage remains the most prevalent technology, while Cryogenic Technology continues to expand its footprint in international trade and strategic reserves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Federal Energy Regulatory Commission (FERC) anchors the dominant geography for natural gas storage, influencing investment and operational standards across North America. Regional dynamics reflect diverse energy policies and infrastructure needs, from robust export capabilities to seasonal demand balancing. Each major market adapts storage strategies to its unique geological and regulatory landscape.
United States
Demand for natural gas storage in the United States is driven by the build-out of liquefied natural gas (LNG) export facilities and the need for renewable grid balancing. The US Federal Energy Regulatory Commission (FERC) governs facility permitting and market access. The US Gulf Coast sees concentrated demand for high-deliverability salt cavern facilities supporting export terminals.
China
China's rapid expansion of domestic storage capacity supports its narrowing supply-demand gap for seasonal price arbitrage opportunities. The National Development and Reform Commission (NDRC) sets mandatory storage capacity targets for gas suppliers. Major industrial zones in coastal regions are driving significant investment in new underground facilities and LNG tank expansions.
Germany
Germany prioritizes seasonal storage to manage winter heating demand and ensure supply security for its industrial base. The EU Green Deal positions natural gas as a transitional fuel, stimulating infrastructure investment. Industrial regions like North Rhine-Westphalia rely on extensive storage networks for consistent energy supply and grid stability.
Canada
Canada leverages its extensive pipeline networks to optimize storage asset utilization, supporting both domestic consumption and cross-border trade. Natural Resources Canada oversees the development and regulation of energy infrastructure projects. Western Canada plays a key role in connecting abundant natural gas production to major demand centers and export hubs.
Australia
Australia's natural gas storage market expands with growing LNG export capabilities and increasing domestic industrial consumption. The Australian Energy Market Operator (AEMO) ensures gas supply reliability and market stability. Queensland and Western Australia are key regions developing storage infrastructure to support export terminals and resource sector operations.
Natural Gas Storage Market Key Industry Players
Capability concentration sits with one tier of specialized high-deliverability operators; scale advantage sits with another tier of integrated energy majors. The market structure features a mix of large, diversified energy companies and specialized storage providers. Dominant competitive moves include strategic partnerships to optimize asset utilization and significant capital investments in new capacity.
Specialists in high-deliverability storage, Kinder Morgan Inc. exemplifies the focus on flexible, rapid-response facilities, particularly along the US Gulf Coast. Gazprom PJSC, a Russian public joint-stock company, represents the strategic influence of state-backed entities controlling vast depleted reservoir storage sites in Eastern Europe. Enbridge Inc., a Canadian corporation, anchors the extensive North American pipeline networks that integrate storage assets for optimized system-wide efficiency.
| Leading Market Players |
|---|
| Kinder Morgan Inc. |
| Sempra Infrastructure |
| Gazprom PJSC |
| Royal Vopak N.V. |
| National Grid plc |
| China National Petroleum Corporation |
| Enbridge Inc. |
| NAFTA a.s. |
| TC Energy Corp. |
| Others |
Cost & Logistics Intelligence
The US Gulf Coast's concentrated salt cavern capacity directly influences regional natural gas storage pricing power. This build-out for LNG exports shapes contract terms for industrial users.
Pricing Analysis
Regional price spreads for natural gas storage are most pronounced between the US Gulf Coast and inland markets. The dominant pricing structure involves contract-based long-term offtake agreements for base capacity, supplemented by short-term transactional services. Price differentiation stems from deliverability rates and location proximity to major pipeline interconnects. Pricing softness reflects oversupply in some regional markets, particularly where new LNG export capacity has yet to fully ramp up. Industrial manufacturers exhibit the highest price sensitivity, while utility companies prioritize reliability over marginal cost savings.
Supply Chain Analysis
Extended payment terms are common for storage infrastructure projects, often facilitated by supply-chain finance arrangements with major energy companies. Geographic supply concentration for natural gas storage is notable in the United States, Eastern Europe, and China, reflecting historical production and consumption patterns. The sector primarily relies on specialized geological surveys and high-grade steel for pipeline and well construction. A structural risk involves lengthy permitting processes, which create investment uncertainty and project delays. Distribution runs through integrated pipeline networks, connecting storage facilities to utility companies and power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural gas storage market is experiencing a shift in buyer power, driven by the consolidation of utility companies and power producers seeking integrated energy solutions. This dynamic influences long-term contract negotiations and service offerings.
For Market Incumbents: Insulate core assets from long-term substitution threats posed by utility-scale battery storage through strategic hydrogen storage conversion projects. Invest in advanced sensor networks and AI-powered analytics to optimize existing asset utilization and predictive maintenance. Deepen vertical integration into renewable energy projects, offering bundled storage and balancing services to power producers. This approach mitigates operational technology security risks and enhances overall grid reliability.
For New Entrants and Emerging Players: High-deliverability storage services for industrial clusters represent a penetrable entry point beyond traditional utility contracts. Focus on developing specialized salt cavern facilities along the US Gulf Coast, capitalizing on LNG export growth. Offer flexible, short-term contracting models tailored to manage price volatility for industrial manufacturers. A key go-to-market angle involves providing bespoke solutions for specific industrial processes requiring consistent, on-demand gas supply.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure play because natural gas remains a transitional fuel for grid stability and renewable energy backup. Target mid-cap specialists with expertise in high-deliverability salt cavern operations or those possessing strategic depleted reservoir sites. These firms offer established regulatory compliance and asset integrity management. The signal to watch is the pace of hydrogen blending mandates, which will impact existing asset compatibility and valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Storage Conversion | Repurposing salt caverns for hydrogen blends extends asset lifespan and supports decarbonization goals for power producers. |
| Digital Twin Implementation | AI-powered analytics and real-time monitoring enhance operational safety and optimize withdrawal strategies for utility companies. |
| Capacity Buildout in Asia | Expanding storage infrastructure in China addresses mandatory capacity targets and supports LNG import growth for gas distributors. |
| Long-Term Offtake Agreements | Securing stable revenue streams from power producers mitigates market volatility and ensures financial predictability for asset owners. |
| Cybersecurity Enhancement | Protecting critical control systems from sophisticated threats maintains grid stability and ensures operational integrity for facility owners. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. Engagement included utility planning officers, reservoir engineers, LNG terminal operators, and regulatory affairs specialists. Secondary validation drew from FERC filings, EIA data, IEA reports, and China's NDRC policy documents. This approach employed both bottom-up market sizing and top-down validation to ensure data accuracy.
The analytical framework calibrated market projections using a robust multi-variate regression model across the analysis window. Segmentation dimensions modeled included storage type, application, end-user, technology, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected investment cycles. Key forecast inputs included planned LNG export capacity additions and renewable energy integration targets.
Macroeconomic conditions sit as an overlay; deviation in global energy demand or geopolitical stability would shift the trajectory. Forecasts reflect assumptions regarding regulatory support for transitional fuels and the pace of renewable energy deployment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
ASEAN Energy Storage Devices Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Global Data Center Energy Storage Market