
 Water Electrolysis Machine Market | 2026-2036
Water Electrolysis Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Water Electrolysis Machine Market Analysis
Long-term service contracts and performance-based maintenance agreements are recalibrating how electrolyzer OEMs capture lifetime value from each installation. Nel ASA leverages its integrated hydrogen fueling and electrolyzer service platform to extend customer retention across project phases. Siemens Energy anchors large-scale alkaline and PEM deployments through captive engineering services tied to utility-scale hydrogen hubs.
Water electrolysis machines electrochemically split purified water into hydrogen and oxygen gases using direct current, with modern alkaline systems operating at 60-80 degrees Celsius and 1-30 bar pressure to serve industrial hydrogen supply chains. Proton Exchange Membrane technology leads in rapid-response grid balancing applications where intermittent renewable power demands fast ramp rates. Alkaline Electrolysis dominates manufacturing scale and unit economics for baseload chemical production, while Solid Oxide systems occupy emerging high-temperature integration opportunities with industrial heat recovery.
The EU Green Deal and delegated acts under the Renewable Energy Directive shape product certification requirements for green hydrogen output across European installations. Germany's KBA and federal hydrogen strategy coordinate infrastructure standards with electrolyzer performance benchmarks. China's MIIT and GB standards govern domestic manufacturing scale-up and export qualification protocols. Stakeholders must monitor how regulatory definitions of renewable hydrogen content determine machine eligibility for production subsidies and offtake guarantees.
Market Dynamics
The shift from pilot-scale electrolyzer deployments to gigawatt manufacturing commitments is compressing equipment lead times and forcing OEMs to restructure supply chains around rare earth catalyst sourcing and high-purity membrane fabrication.
Growth Catalysts
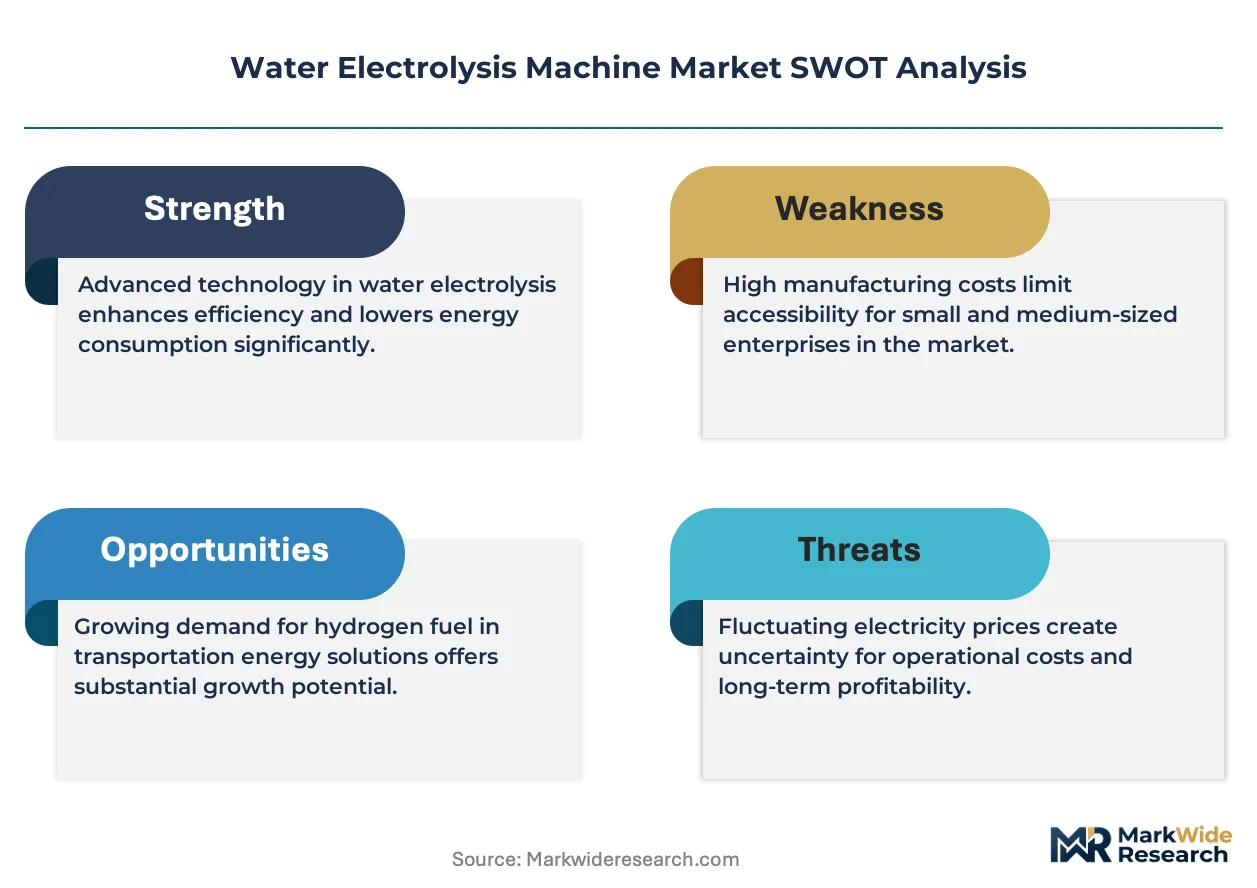
- EU Green Deal delegated acts:The Renewable Energy Directive's certification criteria for renewable hydrogen production create guaranteed offtake pathways for electrolyzer installations meeting carbon intensity thresholds.
- Steelmaking decarbonization:Direct reduced iron facilities in Germany, Sweden, and China are contracting for dedicated green hydrogen supply, anchoring baseload demand for megawatt-scale alkaline systems.
- Proton Exchange Membrane maturation:Improved catalyst loading densities and thinner membrane architectures are extending stack lifetimes beyond 60,000 hours in grid-balancing service.
Market Restraints
- Platinum-group metal dependency:PEM stack manufacturing concentrates catalyst supply from South African and Russian mining operations, exposing cost volatility to geopolitical disruption.
- Grid interconnection queues:Utility-scale electrolyzer projects in Germany and the United States face 24-36 month transmission access delays that stall project financing.
- Alkaline system footprint constraints:Large-format alkaline electrolyzers require substantial floor space and cooling infrastructure that limits retrofit deployment in dense industrial zones.
Strategic Opportunities
- Australia hydrogen export hubs:The country's National Hydrogen Strategy and Pilbara-Kimberley renewable corridors position electrolyzer OEMs for 10+ GW of export-oriented manufacturing capacity.
- Solid Oxide Electrolysis Cell integration:High-temperature co-electrolysis with industrial waste heat from cement and glass manufacturing opens efficiency gains above 85 percent LHV.
- Japan's METI hydrogen roadmap:Import terminal infrastructure and ammonia cracking investments create demand for electrolyzers configured to synthetic fuel production rather than pure hydrogen output.
Industry Challenges
- Electrolyzer stack engineering talent scarcity:Specialized expertise in electrochemical cell design, thin-film coating, and high-pressure sealing remains concentrated among a handful of research institutions and incumbent suppliers.
- Green hydrogen certification fragmentation:Divergent national standards for renewable electricity sourcing and carbon accounting across Germany's KBA, Japan's METI, and China's MIIT complicate cross-border project development.
- Legacy ammonia plant retrofit complexity:Brownfield integration of electrolyzers into Haber-Bosch facilities requires extensive reconfiguration of compression, storage, and process control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Electrolysis Machine Market |
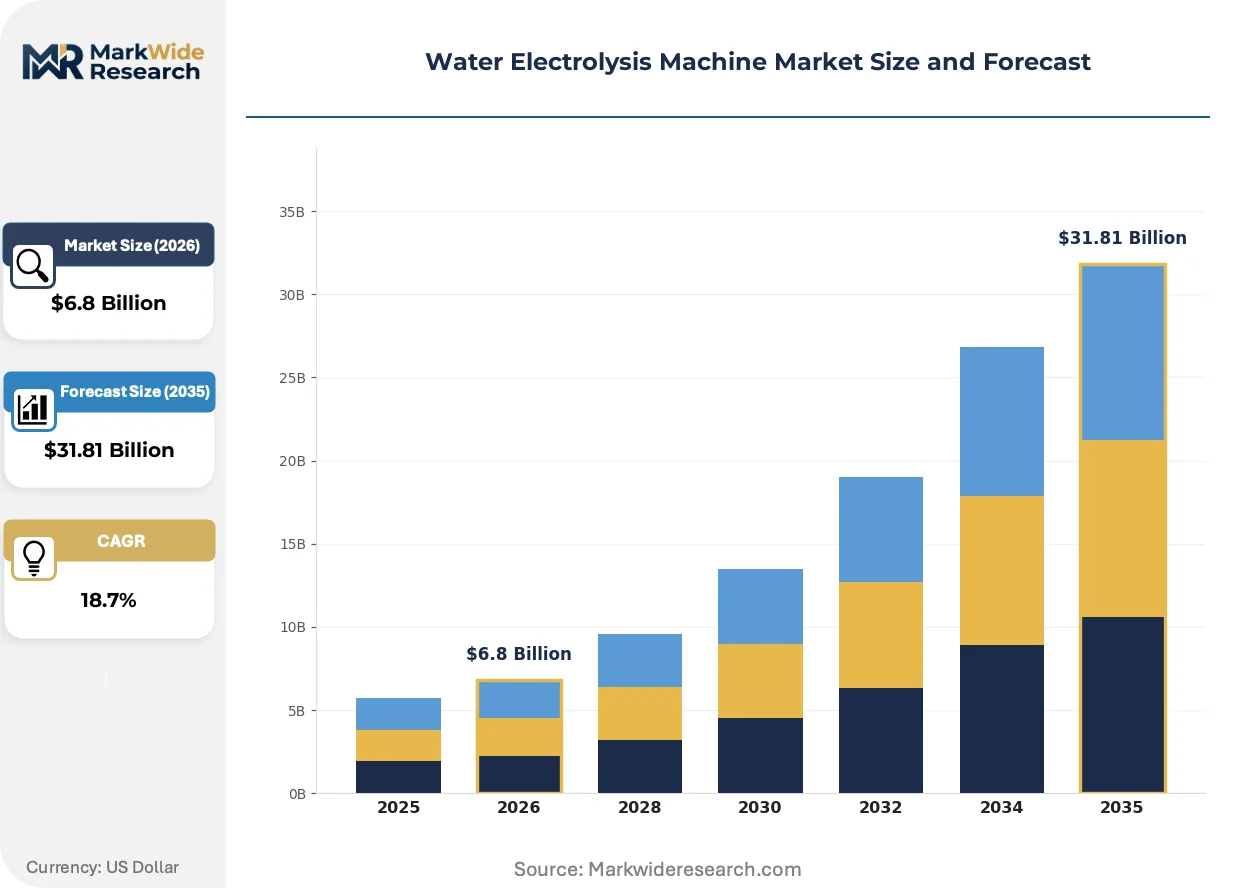
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.81 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Alkaline Electrolysis, Proton Exchange Membrane, Solid Oxide, Anion Exchange Membrane End User: Industrial Manufacturing, Renewable Energy, Chemical Production, Research Institutions Application: Hydrogen Production, Oxygen Generation, Fuel Cell Systems, Water Treatment Capacity: Small Scale, Medium Scale, Large Scale, Custom Solutions |
| Companies Covered | Nel ASA, Cummins Inc., Siemens Energy AG, ITM Power Plc, thyssenkrupp nucera, Asahi Kasei Corporation, Air Products and Chemicals, Inc., Plug Power Inc., Hitachi Zosen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Electrolysis Machine Market Emerging Trajectories
Electrolyzer system architectures are converging with power electronics and digital controls, blurring traditional boundaries between equipment supply and energy management services.
Pressurized alkaline electrolysis is overtaking atmospheric designs in utility-scale deployments. The technology operates at 30 bar delivery pressure, eliminating downstream compression stages. European hydrogen valley developers favor these systems for direct pipeline injection. The structural compression in balance-of-plant costs is accelerating project returns.
China's MIIT GB standards for electrolyzer efficiency and safety are tightening domestic certification requirements. Manufacturers must now demonstrate 72-hour continuous operation at rated load before qualifying for state-backed project procurement. Export-oriented suppliers are dual-certifying to European CE and Chinese GB protocols to preserve market access.
Long-term hydrogen purchase agreements are displacing equipment-only transactions. Industrial offtakers in chemicals and refining now contract for delivered molecules rather than buying electrolyzers outright. Germany's chemical corridor and the US Gulf Coast hydrogen hub are pioneering this model. The shift transfers operational risk to OEMs while locking in decade-long revenue streams.
Water Electrolysis Machine Market Segmentation
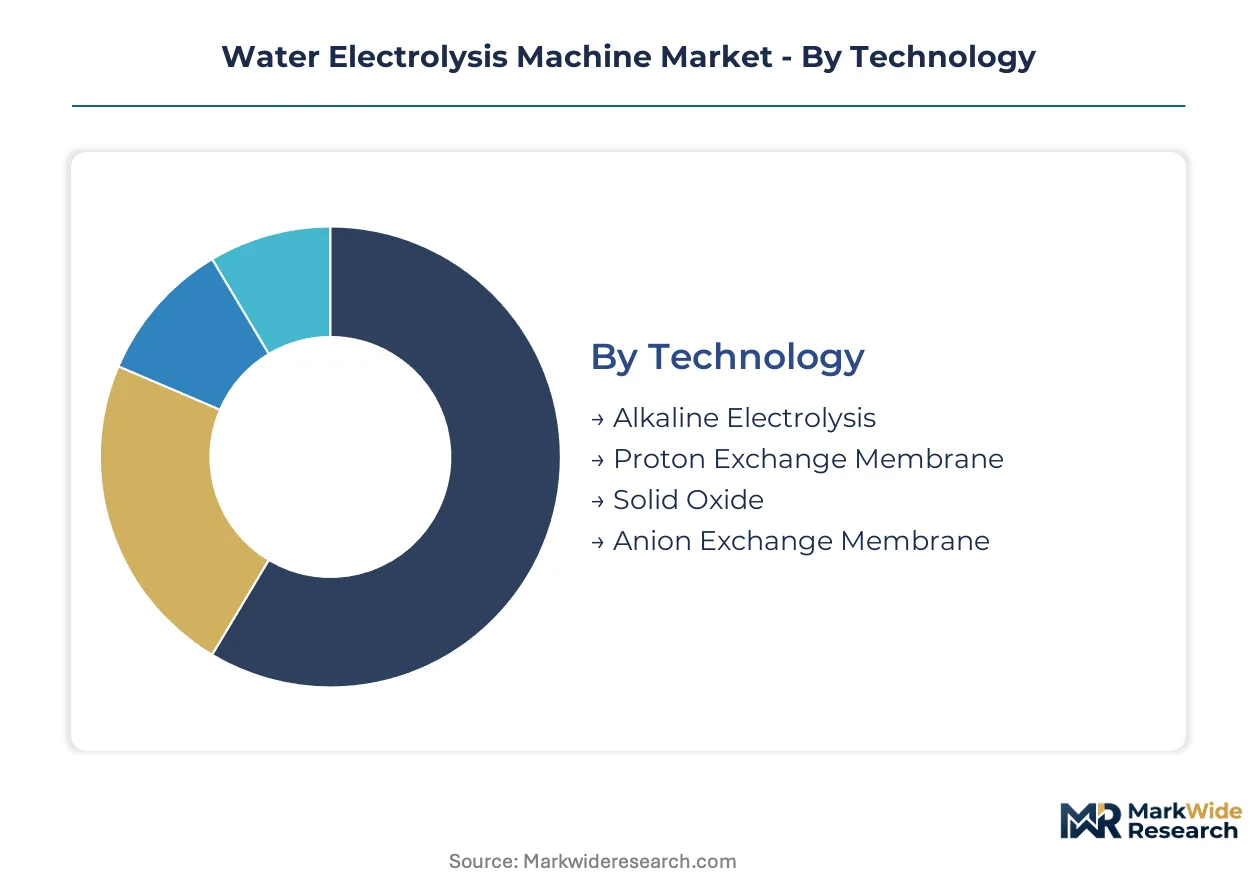
Water electrolysis machine segmentation reveals how technology maturity, end-use requirements, and deployment scale determine equipment specifications and procurement patterns. Buyers select systems based on integration depth with existing industrial infrastructure and hydrogen purity demands.
Technology:
Integration depth varies sharply: alkaline and PEM systems dominate standalone installations, while solid oxide and anion exchange technologies embed into high-temperature industrial processes.
- Alkaline Electrolysis:Uses aqueous potassium hydroxide electrolyte in bipolar or monopolar cell configurations, achieving 60-80% system efficiency at atmospheric or pressurized operation. Germany's hydrogen valleys and China's industrial clusters anchor demand for megawatt-scale alkaline systems serving steelmaking and ammonia production feedstock requirements.
- Proton Exchange Membrane:Employs solid polymer electrolyte membranes with platinum-group catalysts, enabling rapid load-following from 5-150% of rated capacity within seconds. Grid-balancing applications in California and Texas favor PEM stacks for coupling with intermittent wind and solar generation, though catalyst supply concentration from South African mining operations constrains deployment scale.
- Solid Oxide:Operates at 700-900°C with ceramic electrolytes, achieving the highest electrical efficiency when integrated with industrial waste heat sources.
- Anion Exchange Membrane:Combines alkaline chemistry with solid-state architecture, eliminating liquid electrolyte handling while reducing precious metal loading.
Alkaline Electrolysis leads volumes today; Anion Exchange Membrane is gaining share fastest.
End User:
Cost tier stratification separates capital-intensive industrial buyers from research-oriented purchasers with lower volume thresholds and higher specification flexibility.
- Industrial Manufacturing:Steelmakers, refineries, and glass producers deploy multi-megawatt systems for process heat decarbonization and feedstock substitution. Sweden's HYBRIT initiative and Germany's Salzgitter steelworks exemplify dedicated green hydrogen supply contracting at scale.
- Renewable Energy:Wind and solar developers integrate electrolyzers for power-to-gas storage and grid stabilization services. Australia's Pilbara-Kimberley renewable corridors position this segment for export-oriented hydrogen production.
- Chemical Production:Ammonia and methanol producers retrofit Haber-Bosch synthesis loops with electrolytic hydrogen to displace steam methane reforming.
- Research Institutions:Universities and national laboratories operate sub-megawatt systems for catalyst development and system optimization studies.
Industrial Manufacturing commands the largest equipment budgets; Renewable Energy is expanding most quickly.
Application:
Application focus determines purity specifications, pressure requirements, and downstream processing integration.
- Hydrogen Production:Generates high-purity hydrogen for industrial feedstock, fuel cell vehicles, and synthetic fuel synthesis. Germany's chemical corridor and the US Gulf Coast hydrogen hub prioritize this application for delivered-molecule contracting.
- Oxygen Generation:Produces medical-grade or industrial oxygen as co-product, with particular relevance for wastewater treatment and steelmaking oxyfuel combustion.
- Fuel Cell Systems:Supplies on-site hydrogen generation for stationary power and mobility refueling infrastructure.
- Water Treatment:Leverages electrolytic processes for disinfection and contaminant oxidation in municipal and industrial water systems.
Hydrogen Production dominates absolute deployment; Fuel Cell Systems shows the steepest expansion trajectory.
Capacity:
Volume tiering reflects project finance structures and equipment standardization tradeoffs.
- Small Scale:Systems below 1 MW serve distributed refueling stations, remote power applications, and pilot demonstrations. Japan's METI hydrogen roadmap supports this tier through import terminal and ammonia cracking infrastructure development.
- Medium Scale:1-10 MW installations bridge pilot and commercial phases, often deployed in industrial parks with shared hydrogen distribution.
- Large Scale:Exceeds 10 MW single-train capacity, with European hydrogen valley developers favoring pressurized alkaline designs for direct pipeline injection.
- Custom Solutions:Engineered for specific pressure, purity, or integration requirements outside standard product ranges.
Large Scale captures the dominant share of capital deployment; Medium Scale is climbing the fastest as projects transition from demonstration to commercial operation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hydrogen valleys command larger electrolyzer commitments than Australia's export corridors, though both nations pursue gigawatt-scale manufacturing. China compresses equipment costs through domestic supply chain consolidation. Japan prioritizes ammonia cracking integration over direct hydrogen distribution.
Germany
Steelmaking decarbonization at Salzgitter and direct reduced iron facilities in the Ruhr region anchor baseload demand for megawatt-scale alkaline systems. The KBA coordinates infrastructure standards with federal hydrogen strategy benchmarks. Hydrogen valleys in North Rhine-Westphalia and Lower Saxony pressurize electrolyzer designs for direct pipeline injection.
China
Industrial clusters in the Yangtze River Delta and Shandong Peninsula scale alkaline electrolyzer manufacturing for ammonia and methanol feedstock substitution. MIIT GB standards mandate 72-hour continuous operation certification for state-backed procurement eligibility. Export-oriented suppliers dual-certify to European CE and domestic GB protocols.
United States
The Gulf Coast hydrogen hub and California grid-balancing deployments drive divergent technology preferences across regions. FERC interconnection queues impose 24-36 month transmission access delays that stall utility-scale project financing. Texas wind-solar corridors favor rapid-response PEM stacks for intermittent renewable coupling.
Australia
The Pilbara-Kimberley renewable corridors and National Hydrogen Strategy position the country for 10+ GW of export-oriented manufacturing capacity. TGA-equivalent safety frameworks govern equipment certification for offshore shipment. Queensland and Western Australia host electrolyzer deployments configured for ammonia synthesis rather than pure hydrogen export.
Japan
METI's hydrogen roadmap prioritizes import terminal infrastructure and ammonia cracking investments over domestic electrolyzer manufacturing. Kansai and Kyushu industrial zones contract for synthetic fuel production systems rather than pure hydrogen output. JIS standards integration with maritime shipping protocols shapes equipment specifications.
Water Electrolysis Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated engineering-service platforms capturing extended revenue streams. The vendor base concentrates among electrochemical system architects, industrial conglomerates with captive hydrogen divisions, and power equipment OEMs diversifying into electrolyzer stacks. Three archetypes dominate: Norwegian-originated hydrogen fueling integrators, German-Swiss industrial engineering houses, and Japanese chemical-industrial conglomerates. Competitive positioning hardens through long-term service contract capture and performance-based maintenance agreements.
Within the integrated service tier, Nel ASA exemplifies platform-based customer retention across project phases. Siemens Energy anchors large-scale deployments through captive engineering services tied to utility-scale hydrogen hubs. thyssenkrupp nucera occupies a position linking steelmaking heritage with electrolyzer manufacturing scale.
| Leading Market Players |
|---|
| Nel ASA |
| Cummins Inc. |
| Siemens Energy AG |
| ITM Power Plc |
| thyssenkrupp nucera |
| Asahi Kasei Corporation |
| Air Products and Chemicals, Inc. |
| Plug Power Inc. |
| Hitachi Zosen Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and Germany anchor supply concentration while enforcing disciplined pricing through state-backed procurement protocols and long-term offtake guarantees. This ownership pattern compresses margin volatility for alkaline systems while amplifying cost pressure on PEM manufacturers dependent on South African platinum-group metal supply.
Pricing Analysis
Capacity additions in China are reshaping price floors for alkaline electrolyzer systems as domestic manufacturers achieve scale economies through MIIT GB-certified production lines. Contract-based long-term offtake agreements dominate procurement, with price differentiation driven by certification tier (CE versus GB standards) and after-sales service bundling. Cost compression in mid-scale systems is intensifying because European hydrogen valley developers consolidate purchasing through framework agreements. Industrial manufacturing buyers exhibit highest price sensitivity due to feedstock cost exposure, while research institutions accept premium pricing for customization flexibility.
Supply Chain Analysis
Freight costs for membrane stacks and catalyst materials constitute a rising share of landed equipment costs as European and Australian developers source from Chinese and German manufacturing hubs. Supply concentrates in China for alkaline cell manufacturing, Germany for precision engineering components, and South Africa for platinum-group catalysts. The chain draws from rare earth mining operations, high-purity polymer membrane fabrication, and specialized coating equipment. Single-source vulnerability in catalyst supply exposes PEM manufacturers to geopolitical disruption. Distribution runs through EPC contractors and hydrogen project developers rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water electrolysis machine market functions as a stable compounder anchored by irreversible industrial decarbonization mandates across steelmaking and chemical production sectors.
For Market Incumbents: Anchor market position through backward integration into membrane manufacturing and captive catalyst recycling capabilities. Defend against emerging Chinese alkaline specialists by securing exclusive service contracts with Germany's hydrogen valley developers. Prioritize CE-GB dual certification investment to preserve cross-border procurement eligibility. For New Entrants and Emerging Players: Capture white-space opportunity in anion exchange membrane technology where precious metal loading requirements remain unresolved. Australia's Pilbara-Kimberley export corridors offer the most penetrable geography given 10+ GW development commitments and limited incumbent service presence. Pursue synthetic ammonia production integration as the go-to-market angle rather than pure hydrogen output. For Investors and Strategic Acquirers: Valuations sit cheapest among alkaline-focused contract manufacturers with state-backed order pipelines but limited aftermarket service penetration. Five-to-ten year viability hinges on successful transition from equipment sales to delivered-molecule contracting. Monitor FERC and German KBA grid interconnection queue clearance rates as the critical inflection signal for utility-scale project finance viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive supply of proton exchange membranes insulates PEM stack producers from polymer supply volatility. |
| Dual Certification to CE and GB Standards | Dual qualification preserves procurement eligibility across European hydrogen valleys and Chinese industrial clusters. |
| Long-term Hydrogen Purchase Agreements | Delivered-molecule contracting transfers operational risk to OEMs while securing decade-long revenue streams. |
| Solid Oxide Electrolysis Cell Development | High-temperature integration with cement and glass waste heat unlocks efficiency gains above 85 percent LHV. |
| Grid Balancing Service Partnerships | Texas and California ISO coupling agreements position PEM stacks for rapid-response renewable integration revenue. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrolyzer OEM engineering directors, hydrogen project developers at European hydrogen valleys, utility procurement officers, and EPC contractor technical leads with secondary validation from MIIT GB standard filings, EU Green Deal delegated act documentation, FERC interconnection queue databases, and IEA hydrogen project tracking. Bottom-up electrolyzer deployment tallies triangulated against top-down hydrogen demand forecasts from steelmaking and ammonia production capacity announcements.
Segment-weighting across the projection horizon applied technology-type, end-user industry, and capacity-tier dimensions to distribute growth assumptions. CAGRs derived from installed base expansion trajectories, equipment cost learning curves, and policy-driven demand mandates. Forecast inputs incorporated electrolyzer stack lifetime degradation curves and renewable electricity availability constraints specific to hydrogen valley site selection.
Underlying measurement precision varies by segment; large-scale alkaline deployments carry tighter precision than emerging solid oxide installations due to disclosed procurement contract values. Forecasts reflect assumptions about grid interconnection clearance timelines and renewable hydrogen certification standard convergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Ultracapacitors Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Natural Gas Storage Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Long-Duration Energy Storage Market