
 Electric Vehicle Charging Station Market | 2026-2036
Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Station Market Analysis
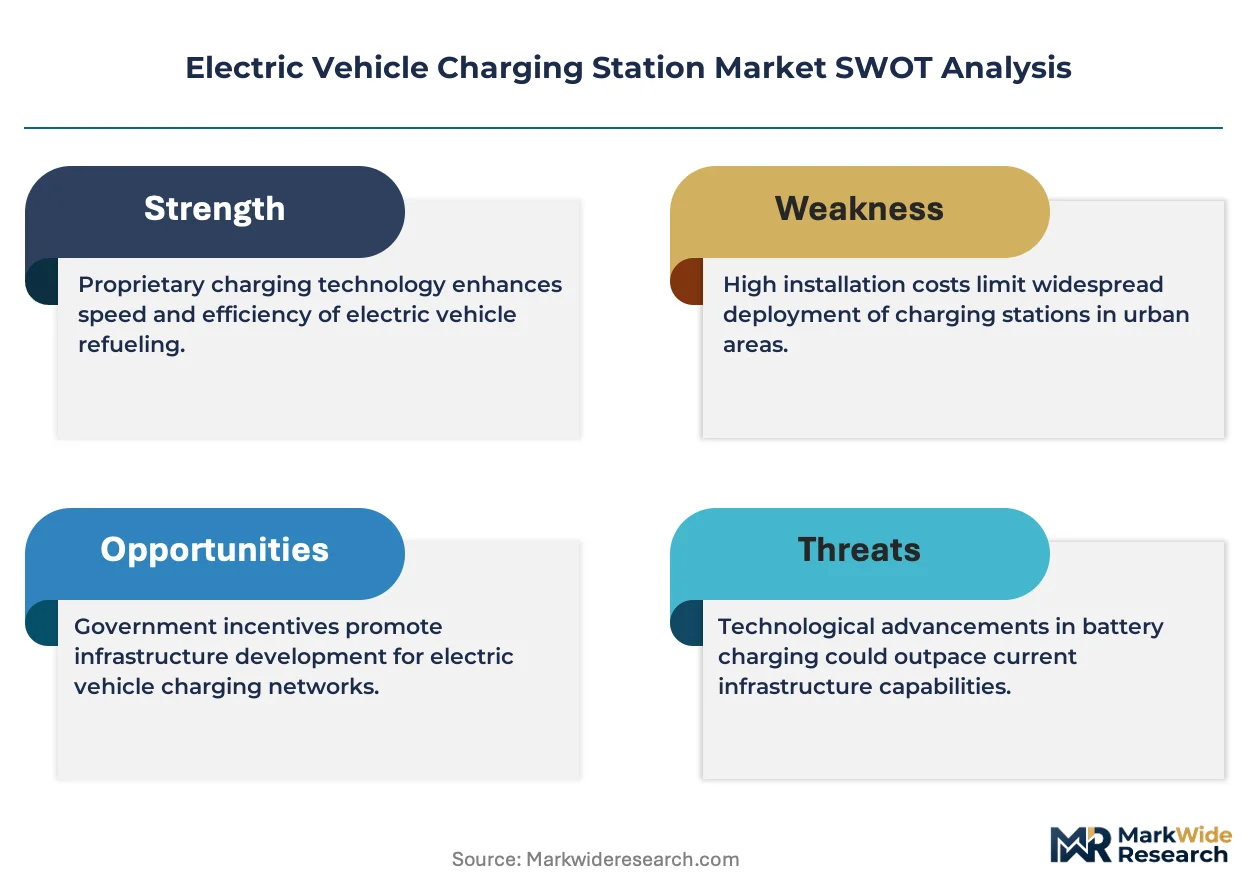
The US Inflation Reduction Act is realigning the cost-of-entry calculus for charging infrastructure developers by extending investment tax credits that directly reduce capital deployment thresholds. Tesla leverages its supercharger network density to sustain proprietary connector dominance across highway corridors. ABB anchors European grid integration through high-power charging systems engineered for fleet depots. Shell competes via forecourt conversions that repurpose existing retail fuel locations into dual-use energy stations.
An electric vehicle charging station is an electromechanical system that converts grid alternating current into direct current at outputs ranging from 3.7 kW to 350 kW, depending on charger classification, to replenish battery electric vehicle storage. Its primary commercial purpose centers on enabling vehicle uptime for passenger transportation, logistics fleets, and shared mobility services through predictable energy replenishment cycles. DC Fast Chargers command the steepest capital intensity but capture premium utilization rates along interstate corridors and commercial hubs where dwell-time minimization drives site selection. Smart Charging technology is gaining structural traction as grid operators impose demand-response requirements that reward load-balancing algorithms. Residential installations remain volume-heavy but carry thinner hardware margins compared to networked commercial deployments.
The US Department of Transportation coordinates with the Federal Energy Regulatory Commission to standardize interstate charging accessibility under the National Electric Vehicle Infrastructure formula program. The European Union's Alternative Fuels Infrastructure Regulation mandates minimum coverage density along trans-European transport corridors, compelling member states to accelerate permitting timelines. China's Ministry of Industry and Information Technology enforces GB/T connector standards that shape equipment certification requirements for domestic manufacturers. Stakeholders must monitor how evolving interoperability mandates between CCS, NACS, and GB/T protocols reshape equipment procurement strategies and stranded asset risk across multi-standard markets.
Market Dynamics
Interoperability mandates between CCS, NACS, and GB/T connector protocols are forcing hardware manufacturers into multi-standard engineering cycles that compress product refresh timelines and elevate certification costs.
Growth Catalysts
- IRA Tax Credit Expansion:The US Inflation Reduction Act extends investment tax credits that directly reduce capital deployment thresholds for charging infrastructure developers, accelerating site buildout across interstate corridors.
- Fleet Depot Electrification:Logistics operators in North America are scaling centralized charging hubs to electrify medium-duty and heavy-duty vehicle segments, creating concentrated demand for high-power charging systems.
- GB/T Standard Enforcement:China's Ministry of Industry and Information Technology enforces domestic connector certification requirements that shape equipment procurement strategies for manufacturers serving the coastal manufacturing corridor.
Market Restraints
- Copper and Silicon Carbide Volatility:Power electronics input costs fluctuate with commodity markets, squeezing hardware margins for DC fast charger producers.
- Grid Interconnection Queues:Utility approval timelines for high-capacity connections extend project completion schedules, particularly in jurisdictions with aging distribution infrastructure.
- Residential Load Limitations:Single-phase residential electrical panels constrain Level 2 installation feasibility in older housing stock, capping addressable market penetration.
Strategic Opportunities
- AFIR Corridor Mandates:The European Union's Alternative Fuels Infrastructure Regulation compels member states to accelerate permitting timelines for trans-European transport corridor coverage.
- Smart Charging Convergence:Vehicle-to-grid integration and load-balancing algorithms are converging to create revenue streams from demand-response participation.
- Forecourt Asset Repositioning:Existing retail fuel locations offer prime real estate for dual-use energy stations with established traffic patterns and zoning clearances.
Industry Challenges
- Power Electronics Talent Scarcity:Specialized engineering capacity for high-frequency converter design remains concentrated among a limited pool of experienced practitioners.
- Multi-Standard Certification Burden:Simultaneous UL, CE, and GB/T testing protocols extend product validation cycles and strain quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Station Market |
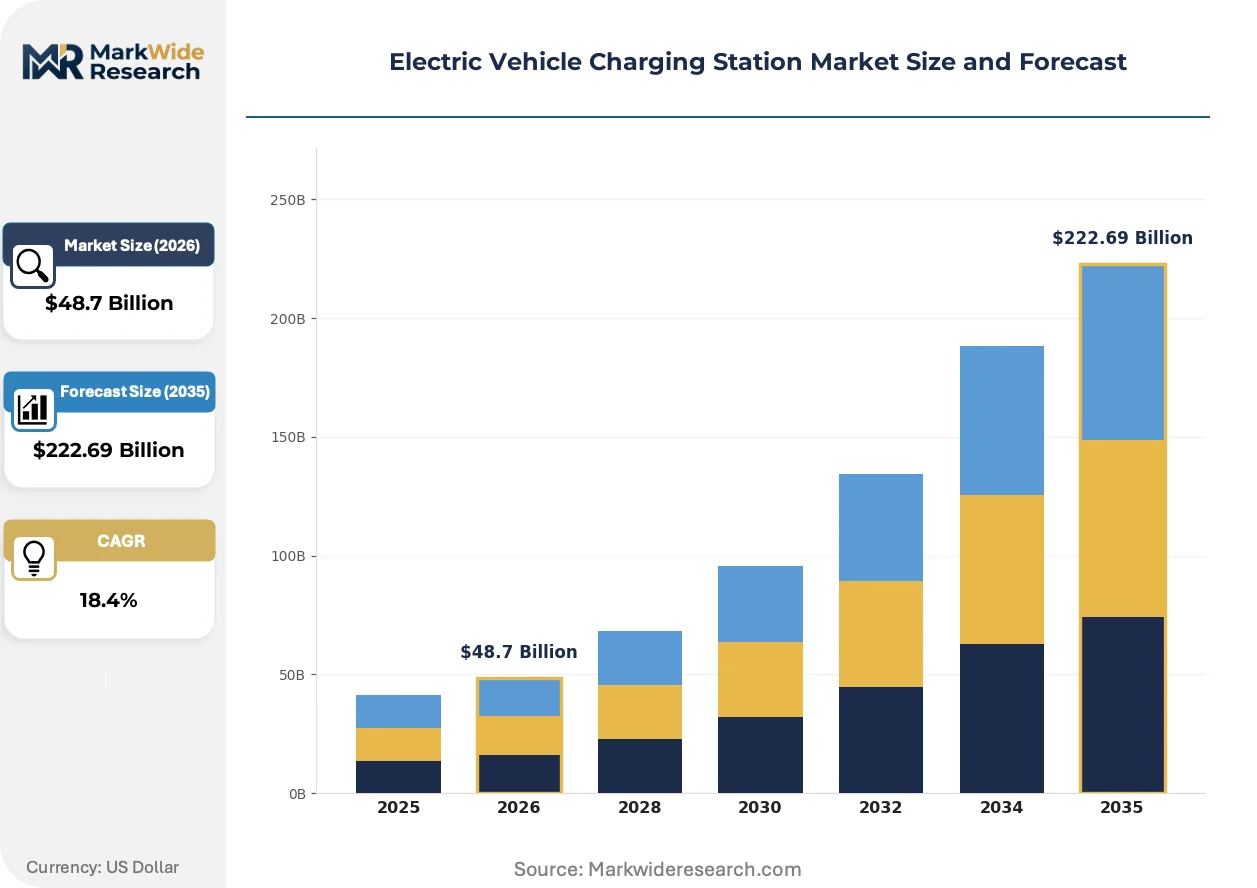
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Chargers, Level 1 Chargers, Level 2 Chargers, DC Fast Chargers Installation Type: On-Street, Off-Street, Residential, Commercial End User: Fleet Operators, Municipalities, Individual Consumers, Businesses Technology: Wireless Charging, Plug-In Charging, Smart Charging, Vehicle-to-Grid |
| Companies Covered | ChargePoint, Tesla, ABB, EVBox, Shell, BYD, BP, TotalEnergies, TGOOD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Station Market Emerging Trajectories
Hardware-software convergence is redefining competitive differentiation in charging infrastructure, with intelligence layers now determining utilization rates and grid integration value.
Bi-directional charging technology is integrating vehicle battery storage into grid stabilization services. Fleet operators with predictable dwell schedules are piloting vehicle-to-grid participation in frequency regulation markets. This capability is integrating stationary energy assets into utility resource planning, compressing the boundary between transportation and power sector infrastructure.
The EU Green Deal's transport decarbonization targets are tightening emission performance standards for commercial vehicle segments. Member states must deploy alternative fuel infrastructure to avoid penalty mechanisms under the Climate Action Regulation. Heavy-duty fleet operators in Germany and the Netherlands are responding by pre-ordering megawatt-class charging systems ahead of regulatory deadlines.
Charging network access is consolidating through roaming platform subscriptions that displace direct membership models. Fleet managers and ride-hail operators now procure interoperable access across multiple networks through single billing relationships. This aggregation is most visible in California and Germany, where high station density enables platform economics that individual network operators cannot match.
Electric Vehicle Charging Station Market Segmentation
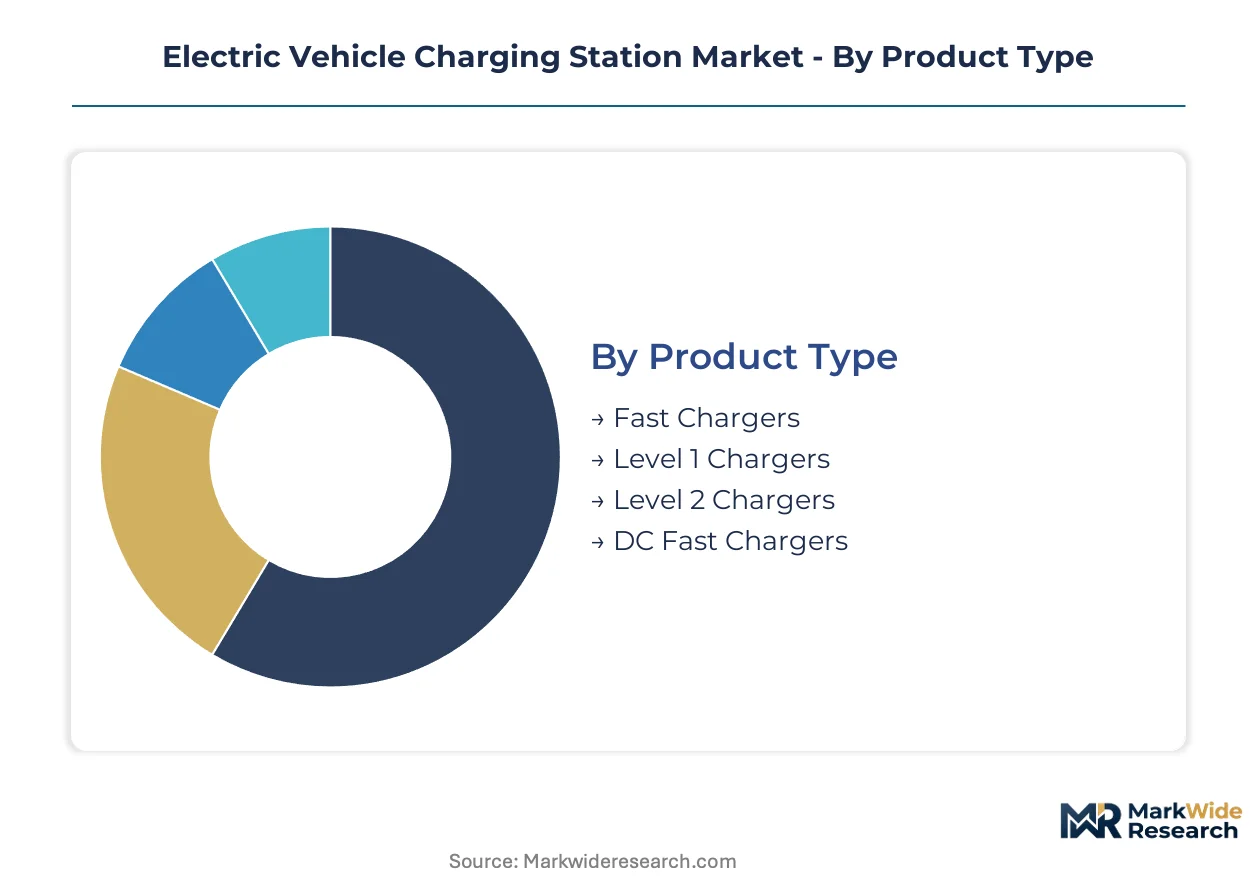
Segmentation in the Electric Vehicle Charging Station Market reveals how capital allocation, site constraints, and user behavior fragment procurement patterns. Equipment specifications diverge sharply between highway corridor deployments and residential garage installations, while power electronics sophistication separates premium from commodity tiers.
Product Type:
Power output and charging speed separate buyers into distinct capital expenditure tiers, with dwell-time tolerance determining hardware selection.
- DC Fast Chargers:These systems deliver 50 kW to 350 kW through direct current conversion, bypassing onboard vehicle inverters. Highway corridor operators in Germany and California concentrate procurement here, driven by interstate commerce mandates under the EU AFIR and US NEVI programs.
- Level 2 Chargers:Operating at 240V alternating current with outputs of 3.3 kW to 19.2 kW, these units dominate workplace and multi-unit dwelling installations. Fleet depot operators across North America standardize on this tier for overnight medium-duty vehicle replenishment, balancing equipment cost against 4-8 hour dwell cycles.
- Fast Chargers:A mid-tier classification spanning 20 kW to 50 kW outputs, serving commercial hubs with moderate dwell-time constraints.
- Level 1 Chargers:Standard 120V residential outlets delivering under 2.4 kW, constrained to emergency and low-mileage use cases.
Level 2 chargers lead volumes today; DC Fast Chargers are gaining share fastest.
Installation Type:
Site control and grid access permissions create divergent deployment economics across public right-of-way versus private property.
- Commercial:Retail parking structures, workplace campuses, and logistics facilities host these installations. Property owners in China's coastal manufacturing corridors leverage state-backed grid upgrades to accelerate deployment, capturing fleet operator demand concentrated around Shenzhen and Shanghai industrial zones.
- Residential:Single-family and multi-unit dwelling installations depend on panel capacity and utility rate structures. Older housing stock across the US Northeast constrains addressable penetration where 100-amp service limits Level 2 feasibility without costly electrical upgrades.
- Off-Street:Dedicated parking facilities including garages and surface lots with controlled access.
- On-Street:Curb-side deployments requiring municipal permits and utility coordination for public right-of-way trenching.
Commercial installations concentrate revenue value; residential units expand unit volumes most rapidly.
End User:
Predictability of utilization and aggregation scale differentiate procurement sophistication across customer types.
- Fleet Operators:Centralized logistics, delivery, and ride-hail fleets with scheduled dwell windows and route predictability. These buyers in the Netherlands and California pre-order megawatt-class charging systems ahead of EU Green Deal and California Air Resources Board deadlines.
- Businesses:Corporate campuses, retail chains, and hospitality properties installing destination charging. Employee and customer retention objectives drive site selection, with parking duration shaping power level selection.
- Individual Consumers:Homeowners and renters purchasing through utility rebate programs or aftermarket retailers.
- Municipalities:City and regional governments deploying public infrastructure under federal formula funding requirements.
Fleet operators anchor high-utilization revenue; businesses are expanding installation commitments most aggressively.
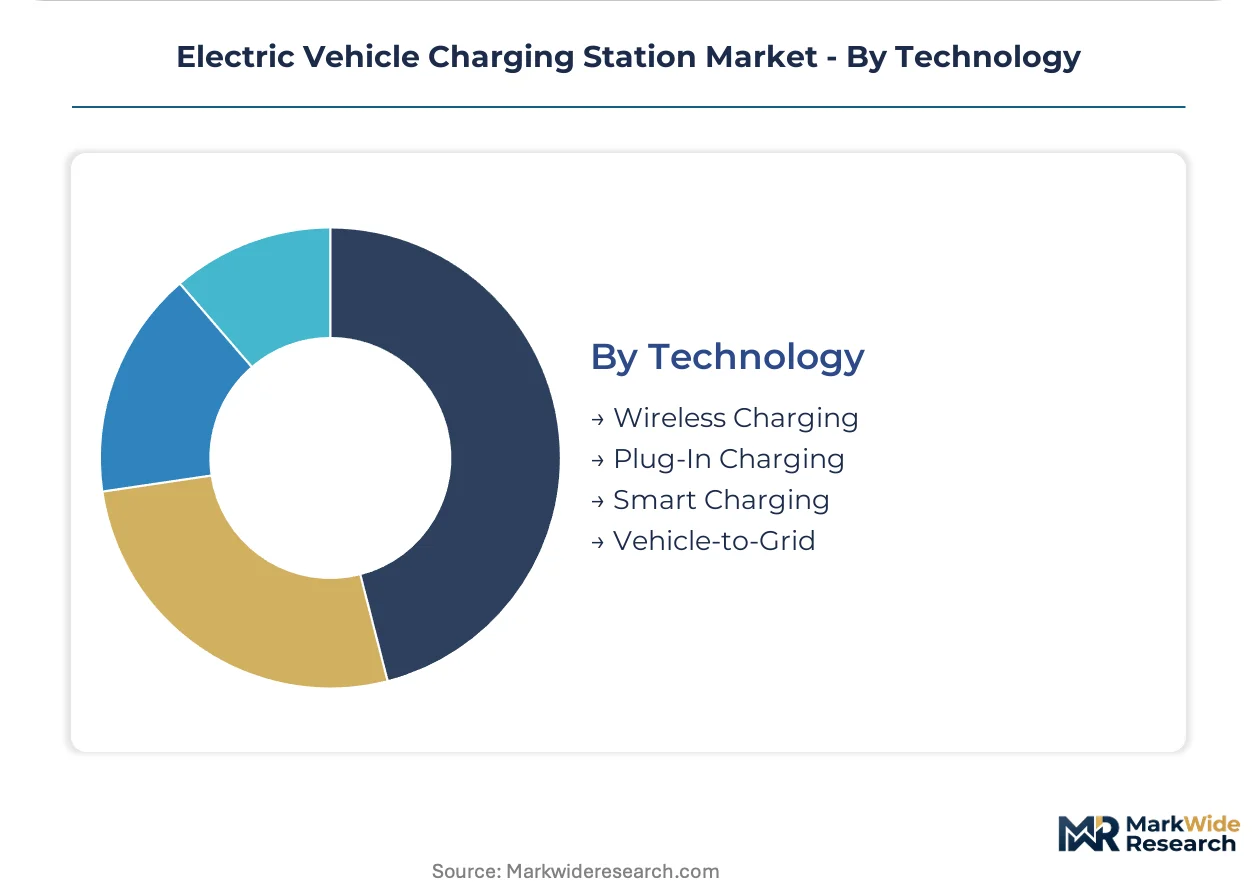
Technology:
Intelligence integration and grid interactivity now separate commodity hardware from premium-positioned systems.
- Smart Charging:Load-balancing algorithms and demand-response capabilities enable revenue participation in utility ancillary services. Grid operators in Germany and California impose requirements that reward these systems with interconnection priority and rate schedule access.
- Vehicle-to-Grid:Bi-directional power flow integrates vehicle batteries into frequency regulation and peak shaving services. Pilot programs with predictable-dwell fleets in the Netherlands demonstrate revenue stacking that improves total cost of ownership calculations.
- Plug-In Charging:Conventional conductive connection via CCS, NACS, or GB/T connectors.
- Wireless Charging:Inductive power transfer eliminating physical connectors, currently constrained by efficiency losses and equipment cost premiums.
Plug-in charging dominates installed base; Smart Charging is climbing the fastest as regulatory mandates spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized power electronics engineers cluster in Germany's industrial belt, California's Silicon Valley corridor, and China's Pearl River Delta manufacturing zones, anchoring regional deployment capacity for high-frequency converter design and grid integration systems.
United States
Fleet depot electrification and highway corridor mandates under NEVI are accelerating capital deployment across interstate networks. The Federal Energy Regulatory Commission coordinates with the Department of Transportation to standardize interconnection protocols and streamline utility approval timelines. California's Central Valley logistics hubs and Texas triangle freight corridors concentrate megawatt-class charging pre-orders from heavy-duty operators.
Germany
Heavy-duty fleet operators are pre-ordering high-power systems ahead of EU Green Deal commercial vehicle deadlines. The Alternative Fuels Infrastructure Regulation compels accelerated permitting for trans-European transport corridor coverage. Industrial zones in North Rhine-Westphalia and Bavaria host concentrated manufacturing of grid-integrated charging systems for depot applications.
China
State-backed grid upgrades in coastal manufacturing corridors are compressing deployment timelines for fleet operators. The Ministry of Industry and Information Technology enforces GB/T connector certification requirements that shape domestic equipment procurement. Shenzhen and Shanghai industrial zones anchor the highest density of charging infrastructure manufacturing and deployment.
Netherlands
Predictable-dwell fleet operators are piloting vehicle-to-grid participation in frequency regulation markets. National implementation of EU AFIR mandates is accelerating corridor coverage along the Rotterdam-Antwerp logistics axis. The Randstad metropolitan cluster concentrates smart charging algorithm development and grid integration testing facilities.
United Kingdom
Workplace and multi-unit dwelling installations are expanding through utility rebate programs and corporate sustainability commitments. The national regulator coordinates grid capacity assessments for high-power commercial connections. London's orbital logistics corridors and Midlands manufacturing zones are prioritizing depot electrification for medium-duty commercial fleets.
Electric Vehicle Charging Station Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented tiering that reflects capital intensity differences between residential and commercial deployment. Market structure concentrates around three archetypes: integrated energy majors repurposing forecourt assets, automotive-origin network operators leveraging vehicle ecosystem control, and independent hardware specialists engineering grid-integration systems. Dominant competitive moves include strategic partnerships for roaming platform consolidation and backward integration into power electronics manufacturing to secure silicon carbide supply.
Within the automotive-integrated tier, Tesla occupies a position exemplifying proprietary connector strategy and highway corridor density. Among diversified energy majors, Shell and BP represent archetypes of forecourt asset repositioning toward dual-use energy stations. On the independent hardware vector, ABB and ChargePoint anchor distinct approaches to grid integration engineering and networked software platforms.
| Leading Market Players |
|---|
| ChargePoint |
| Tesla |
| ABB |
| EVBox |
| Shell |
| BYD |
| BP |
| TotalEnergies |
| TGOOD |
| Others |
Supply Flow & Price Mechanics
Fleet operators consolidating depot electrification programs across Germany and California command pricing leverage through volume procurement contracts that compress hardware margins for DC fast charger manufacturers. This buyer concentration feeds a hybrid pricing model blending capital equipment sales with recurring software subscriptions for network management services.
Pricing Analysis
Bundled hardware-software service packages separate from unbundled equipment-only transactions across procurement tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation between UL-listed highway corridor systems and unlisted residential units. Cost compression in residential Level 2 hardware is intensifying because Chinese manufacturers are scaling GB/T-certified production for domestic export. Fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations, while individual consumers purchasing through utility rebate programs drive hardest bargain hunting.
Supply Chain Analysis
Single-source vulnerability sits with silicon carbide substrate suppliers concentrated in Japan and Germany for high-frequency power electronics. Power module assembly draws from China, South Korea, and Mexico for cost-optimized tiers while premium grid-integration systems source from Germany and the United States. Tariff exposure on Chinese-manufactured power electronics components threatens margin stability for North American hardware producers. Distribution runs through direct OEM relationships for fleet depot projects and electrical distributor networks for residential and small commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as fleet operators pre-order megawatt-class charging systems ahead of EU Green Deal commercial vehicle deadlines, shifting procurement specifications toward grid-integrated smart charging tiers.
For Market Incumbents: Hedge stranded asset exposure across CCS-NACS-GB/T protocol fragmentation by engineering modular power electronics platforms that accommodate connector swaps without full system replacement. Prioritize backward integration into silicon carbide supply to secure power semiconductor allocation against emerging entrant competition for limited wafer capacity. For New Entrants and Emerging Players: Multi-unit dwelling property managers in the US Northeast represent an underserved buyer archetype constrained by aging electrical infrastructure and limited panel capacity. Target this segment with load-management software overlays that enable Level 2 deployment without costly service upgrades, using utility rebate program partnerships as the primary go-to-market channel. For Investors and Strategic Acquirers: Integrated energy majors repurposing forecourt assets are the most active acquirer in this space, seeking charging network operators to anchor dual-use station economics. Long-term viability favors targets with established roaming platform integrations and software-defined load management capabilities. Watch NEVI program disbursement velocity as the signal to monitor for inflection in US highway corridor deployment cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive silicon carbide supply secures margin protection against commodity volatility. |
| Roaming Platform Consolidation | ChargePoint and EVBox aggregation enables fleet operator single-billing relationships. |
| Forecourt Asset Repositioning | Shell and BP conversion programs leverage existing retail fuel zoning and traffic patterns. |
| Vehicle-to-Grid Certification Investment | ABB and Tesla bi-directional systems qualify for FERC frequency regulation revenue streams. |
| Multi-Standard Hardware Engineering | Modular connector platforms reduce stranded asset risk across CCS-NACS-GB/T markets. |
Methodological Framework
Multiple input streams — primary interviews with fleet operations directors and utility interconnection planners, secondary validation through FERC filings and NEVI program disbursement records, and customs data on power electronics imports — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included charging network deployment executives, electrical contractor procurement leads, and state transportation department formula program administrators. Secondary sources encompassed EPA emissions compliance databases, EIA electricity demand projections, and SEC filings from diversified energy majors.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning charger power tier, installation site control type, end-user procurement sophistication, and regional regulatory framework cluster. CAGRs were derived from installed base growth trajectories and utilization rate assumptions calibrated against fleet electrification commitment announcements. Forecast inputs incorporated grid interconnection queue timelines, copper and silicon carbide price indices, and evolving interoperability mandate compliance deadlines.
Underlying measurement precision varies by segment; fleet operator depot installations carry tighter precision than dispersed residential deployments due to centralized procurement visibility. Forecasts reflect assumptions about IRA tax credit continuity, EU AFIR enforcement rigor, and GB/T standard revision timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market