
 Ultracapacitors Market | 2026-2036
Ultracapacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Ultracapacitors Market Outlook
The gap between lithium-ion energy density and ultracapacitor power delivery is narrowing as electrode material science advances. Skeleton Technologies leverages proprietary curved graphene formulations to sustain cycle-life advantages in heavy-duty transport. Panasonic Corporation anchors consumer electronics supply chains with compact cylindrical ultracapacitor designs. LS Mtron Co., Ltd. dominates Korean grid-stabilization deployments through high-voltage module integration.
Ultracapacitors store energy via electrostatic charge separation at electrode-electrolyte interfaces, achieving power densities exceeding batteries by orders of magnitude while operating across temperature ranges from minus forty to plus sixty-five degrees Celsius. Their primary commercial purpose is to deliver burst power, absorb regenerative energy, and bridge power gaps in systems requiring rapid charge-discharge cycling. Double-layer capacitors command the installed base due to mature manufacturing economics, while hybrid capacitors capture expanding share in electric vehicle kinetic-energy recovery where asymmetric voltage profiles match duty-cycle demands. Aerospace end-user applications remain niche but carry premium pricing for radiation-hardened and weight-optimized configurations.
The EU Green Deal and F-Gas Regulation constrain fluorinated electrolyte chemistries, redirecting formulation investment toward acetonitrile and ionic liquid alternatives. EPA tailpipe standards and NHTSA fuel-economy mandates in the United States compel automotive OEMs to integrate ultracapacitor-assisted start-stop and regenerative systems. China's MIIT dual carbon goals and GB standards for new energy vehicles establish domestic procurement quotas that shape supplier qualification requirements. Stakeholders must monitor evolving electrolyte toxicity classifications and solid-state electrode pilot lines to anticipate which technology trajectory captures the next generation of grid and mobility contracts.
Market Dynamics
The convergence of electrode material breakthroughs with automotive electrification mandates is restructuring procurement patterns across heavy transport and grid storage verticals. Skeleton Technologies' curved graphene formulations and LS Mtron's high-voltage module architectures exemplify how proprietary material science is capturing differentiated contract positions.
Growth Catalysts
- EU F-Gas Regulation:Fluorinated electrolyte restrictions under the EU Green Deal are redirecting R&D investment toward acetonitrile and ionic liquid formulations, accelerating domestic European supply chain development.
- China MIIT dual carbon goals:Domestic procurement quotas for new energy vehicles establish supplier qualification requirements that concentrate volume around qualified local producers.
- Regenerative braking integration:Electric bus and rail transit manufacturers specify ultracapacitor modules for kinetic energy recovery, creating sustained demand pull from heavy-duty transport OEMs.
Market Restraints
- Acetonitrile supply concentration:Electrolyte precursor availability clusters with Chinese petrochemical producers, exposing formulation costs to feedstock volatility and trade policy friction.
- Lithium-ion cost compression:Battery pack economics continue improving through scale and chemistry optimization, constraining ultracapacitor penetration in cost-sensitive consumer applications.
- REACH compliance burden:European chemical registration requirements extend development timelines for novel electrolyte formulations, delaying market entry for innovative suppliers.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Production-linked incentives for energy storage manufacturing create localized assembly opportunities for module integrators serving South Asian grid stabilization projects.
- Aerospace radiation-hardened configurations:Satellite and defense applications command premium pricing for weight-optimized ultracapacitor systems with extended temperature tolerances.
- Solid-state electrode pilot scale-up:Dry electrode coating processes eliminate solvent handling costs and enable thicker active material layers, potentially disrupting incumbent manufacturing economics.
Industry Challenges
- Electrochemist talent scarcity:Specialized expertise in interfacial charge storage mechanisms and ionic liquid characterization remains concentrated within national laboratory and select university research groups.
- Module-level certification timelines:UL and IEC safety testing protocols for high-voltage ultracapacitor banks extend qualification cycles, compressing window for design win capture in automotive programs.
- Legacy battery system integration:Hybrid energy architectures require sophisticated power electronics and control firmware, elevating system engineering complexity beyond component substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultracapacitors Market |
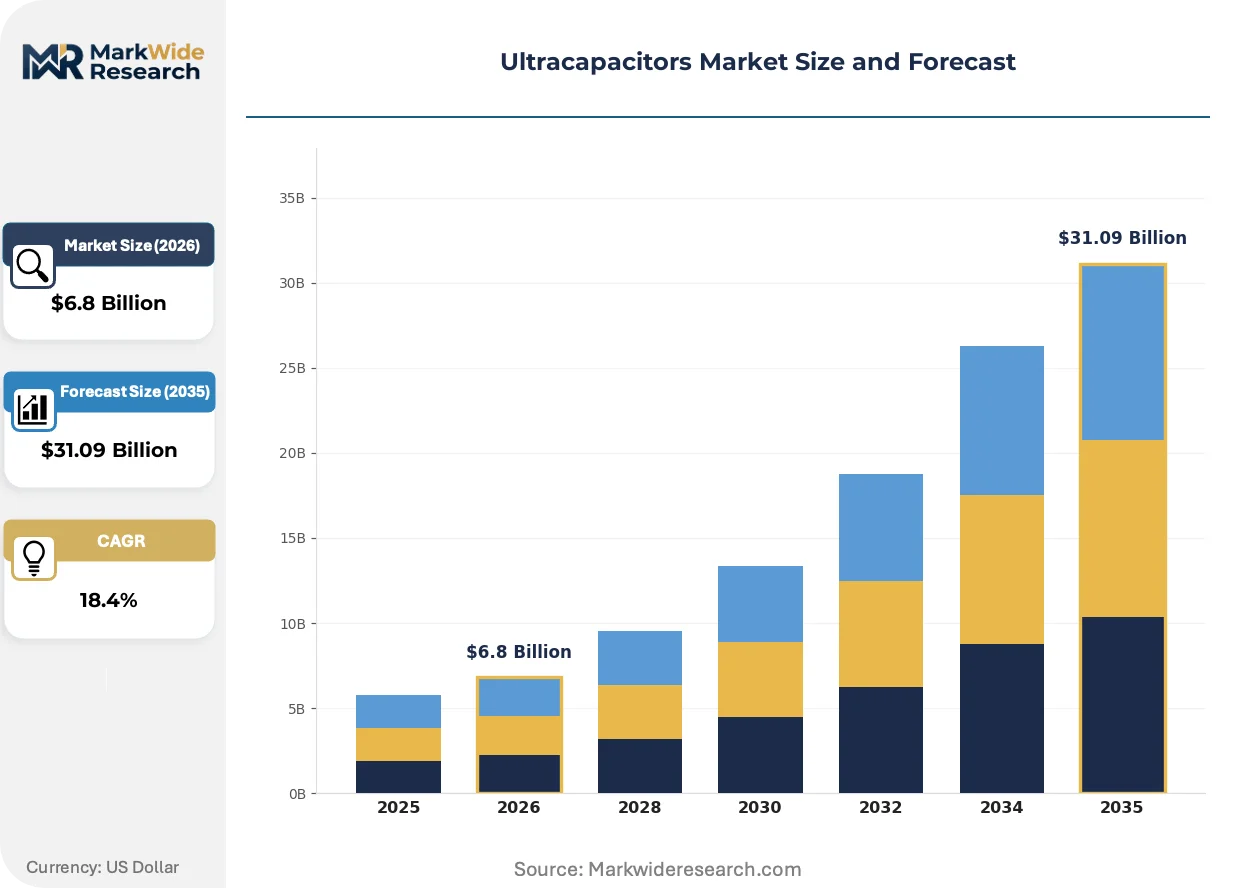
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
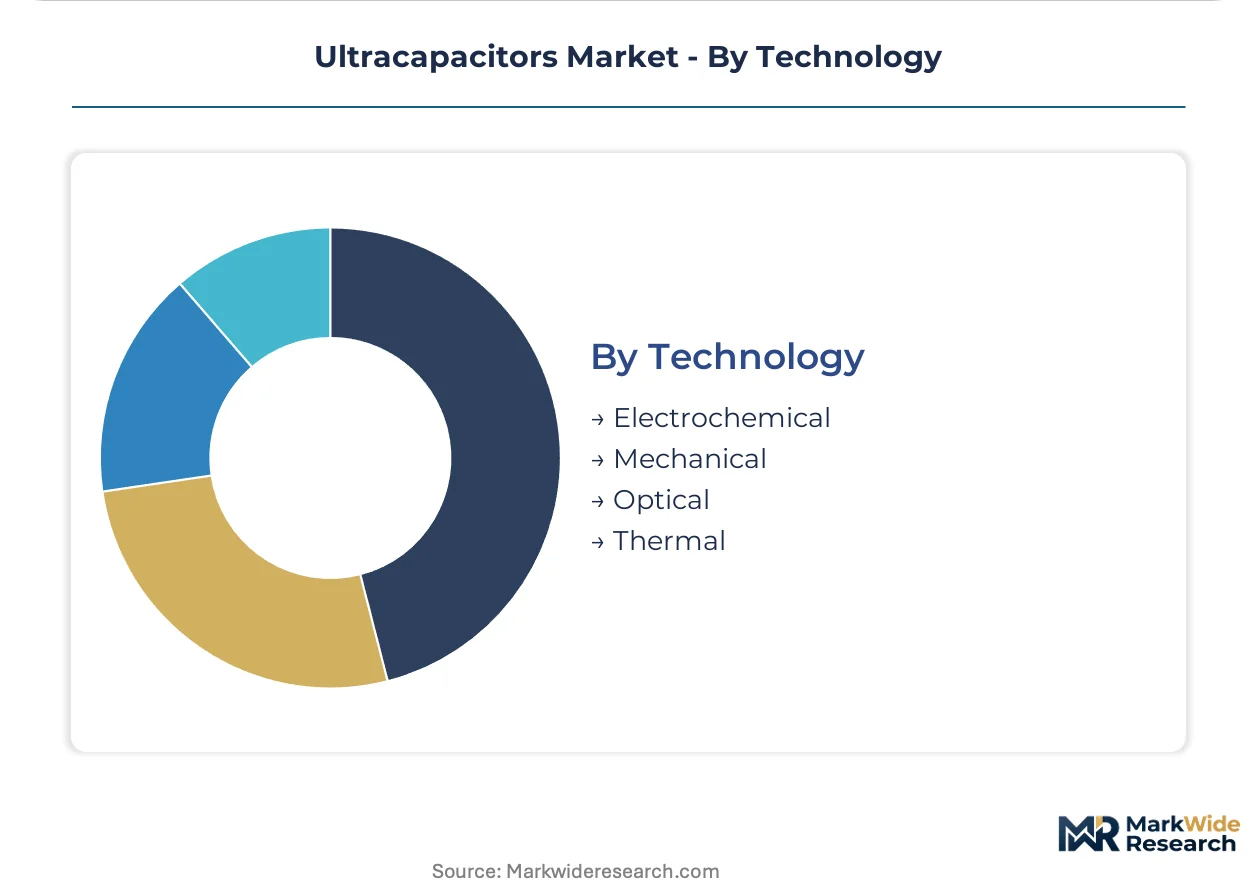
| Segmentation | Product Type: Double-Layer Capacitors, Pseudocapacitors, Hybrid Capacitors, Asymmetric Capacitors Application: Energy Storage Systems, Power Backup Systems, Electric Vehicles, Consumer Electronics End User: Automotive Industry, Renewable Energy, Electronics, Aerospace Technology: Electrochemical, Mechanical, Optical, Thermal |
| Companies Covered | Panasonic Corporation, Skeleton Technologies, Nippon Chemi-Con Corporation, Eaton Corporation, LS Mtron Co., Ltd., KEMET Corporation, Maxwell Technologies, NEC Corporation, KYOCERA AVX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultracapacitors Market Strategic Shifts
Material science advances in carbon nanostructure engineering and electrolyte ionic conductivity are compressing the historical performance gap between power-dense and energy-dense storage technologies. These developments are reshaping competitive positioning across electric mobility and stationary power applications.
Hybrid asymmetric capacitor architectures are collapsing the distinction between double-layer capacitors and battery electrodes by combining Faradaic and non-Faradaic charge storage mechanisms. Automotive tier-one suppliers are qualifying these systems for 48V mild-hybrid platforms where voltage profile flexibility matches irregular duty cycles. The resulting module designs are compressing bill-of-materials costs while extending cycle life beyond pure electrochemical alternatives.
EPA tailpipe standards and NHTSA fuel-economy mandates are compelling Detroit Three OEMs to integrate ultracapacitor-assisted start-stop systems across light-truck and SUV nameplates. The regulatory pressure is accelerating supplier diversification away from single-source battery dependencies. Powertrain engineering teams are responding with dual-source architectures that segment burst power and sustained energy functions across complementary storage technologies.
Chinese electric bus fleet operators are consolidating procurement through state-owned transit authorities, concentrating volume with domestic module integrators qualified under GB standards. This buyer concentration is displacing distributed purchasing through municipal tender processes. The procurement pattern is most visible in Shenzhen and Beijing, where centralized fleet electrification timelines compress supplier selection windows and elevate performance guarantee requirements.
Ultracapacitors Market Segmentation
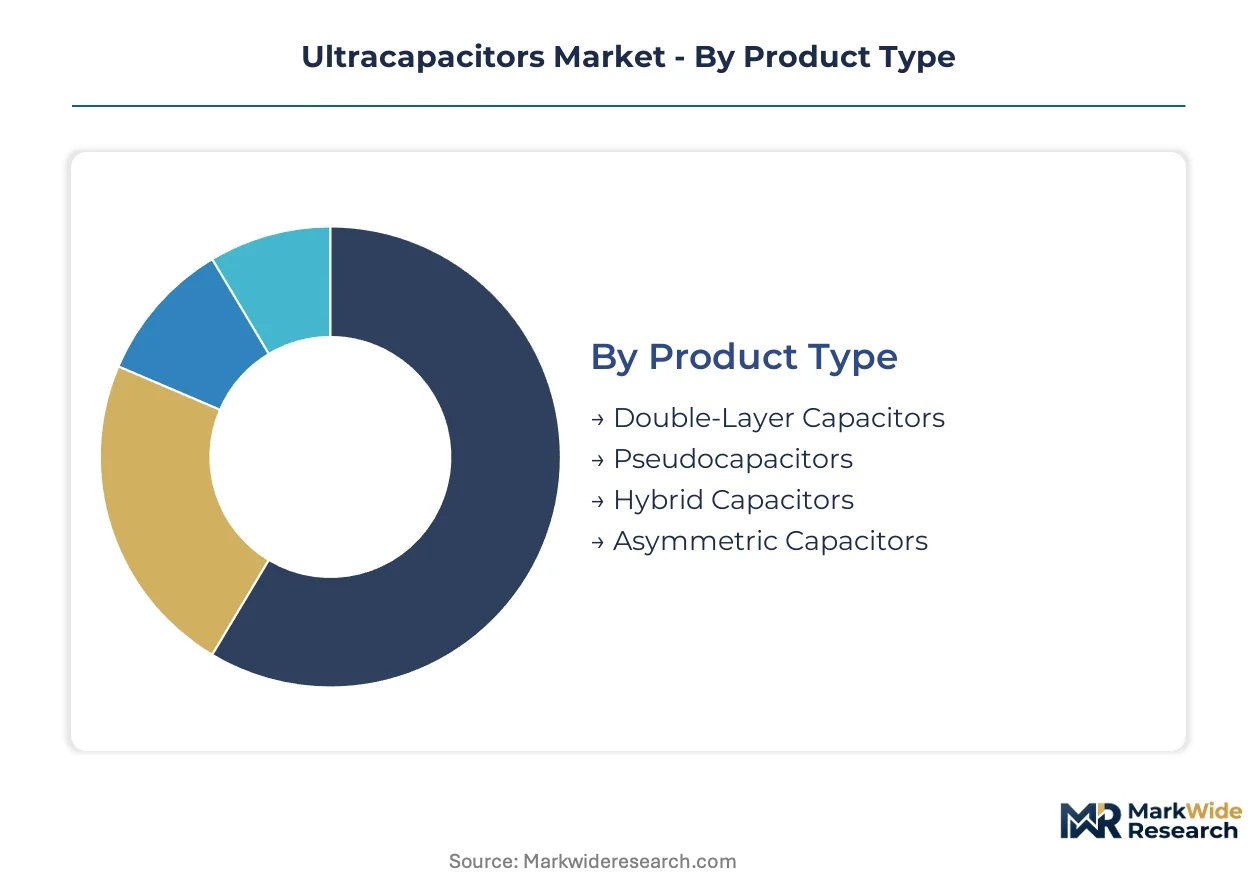
Ultracapacitor procurement cycles vary dramatically by segment—automotive qualification timelines stretch across years while consumer electronics refresh quarterly. Understanding these velocity differentials shapes inventory strategy and R&D prioritization for suppliers competing across divergent end-use requirements.
Product Type:
Cycle times compress from mature double-layer architectures to emerging hybrid formats, with manufacturing scale and electrode complexity driving procurement velocity divergence.
- Double-Layer Capacitors:Electrostatic charge storage at activated carbon-electrolyte interfaces delivers the lowest cost-per-farad in high-volume production. Chinese electric bus operators in Shenzhen and Beijing specify these modules for regenerative braking systems under GB standards, though acetonitrile electrolyte supply concentration with domestic petrochemical producers exposes pricing to feedstock volatility.
- Hybrid Capacitors:Asymmetric electrode pairings combine Faradaic and non-Faradaic mechanisms to bridge power-energy performance gaps. Automotive tier-one suppliers are qualifying these systems for 48V mild-hybrid platforms where voltage profile flexibility matches irregular duty cycles, with expansion concentrating in European OEM programs driven by EU Green Deal emissions mandates.
- Pseudocapacitors:Transition metal oxide electrodes enable higher energy density through surface redox reactions, finding niche deployment in Korean grid-stabilization projects where LS Mtron dominates high-voltage module integration.
- Asymmetric Capacitors:Dissimilar electrode materials optimize cost-performance tradeoffs for specific voltage windows, with Japanese manufacturers advancing pilot lines under METI-funded research programs.
Double-layer capacitors dominate installed base. Hybrid capacitors are where expansion concentrates.
Application:
Cost tiers stratify sharply—electric vehicle modules command premium pricing against commoditized consumer electronics cells, with volume scale inversely correlating with margin capture.
- Electric Vehicles:Heavy-duty transport applications require module-level thermal management and vibration hardening for kinetic energy recovery systems. Procurement concentrates with Chinese state-owned transit authorities consolidating fleet electrification timelines in Beijing and Shenzhen, compressing supplier selection windows while elevating performance guarantee requirements under MIIT dual carbon goals.
- Energy Storage Systems:Grid-scale deployments prioritize cycle life and round-trip efficiency over energy density. Korean utility operators specify LS Mtron high-voltage architectures for frequency regulation services, with India's PLI scheme for advanced chemistry cells now creating localized assembly opportunities for South Asian stabilization projects.
- Power Backup Systems:Industrial uninterruptible power supply integration emphasizes rapid response and wide temperature tolerance, with German manufacturing clusters driving demand for REACH-compliant acetonitrile formulations.
- Consumer Electronics:Compact cylindrical designs from Panasonic anchor smartphone and wearable supply chains, though lithium-ion cost compression constrains ultracapacitor penetration in price-sensitive segments.
Electric vehicle applications capture premium pricing. Consumer electronics delivers volume scale.
End User:
Customer sophistication and technical specification intensity vary across sectors, with aerospace demanding radiation-hardened configurations while automotive prioritizes cost-engineered modularity.
- Automotive Industry:EPA tailpipe standards and NHTSA fuel-economy mandates compel Detroit Three OEMs to integrate ultracapacitor-assisted start-stop systems across light-truck and SUV nameplates. The regulatory pressure accelerates supplier diversification away from single-source battery dependencies.
- Renewable Energy:Wind turbine pitch control and solar smoothing applications require extended temperature operation from minus forty to plus sixty-five degrees Celsius, with European offshore wind clusters specifying Skeleton Technologies curved graphene formulations for salt-corrosion resistance.
- Electronics:Burst power delivery for camera flashes and wireless transmission modules leverages ultracapacitor power density advantages, with Japanese consumer electronics manufacturers qualifying compact form factors under JIS standards.
- Aerospace:Satellite and defense applications command premium pricing for weight-optimized systems with radiation-hardened packaging, though volumes remain constrained by qualification timelines and mission-specific customization requirements.
Automotive end-use generates procurement volume. Aerospace commands margin premiums.
Technology:
Supply concentration clusters with electrochemical expertise, while alternative mechanisms remain laboratory-scale with unproven manufacturing economics.
- Electrochemical:Ionic liquid and acetonitrile electrolyte formulations store charge through interfacial separation and surface reactions, with EU F-Gas Regulation redirecting investment away from fluorinated chemistries toward domestic European supply chain development.
- Mechanical:Flywheel and compressed gas alternatives achieve comparable power density for specific duty cycles but lack the form factor flexibility driving ultracapacitor adoption in mobility applications.
- Optical:Photonic energy storage mechanisms remain experimental, with no commercial deployments qualifying for automotive or grid-scale procurement frameworks.
- Thermal:Phase-change and thermochemical approaches compete for stationary applications where weight and volume constraints relax, though electrochemical cost trajectories limit addressable market expansion.
Electrochemical technology anchors commercial deployment. Alternative mechanisms occupy research-stage positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese ultracapacitor module exports supply European electric bus operators and Korean grid stabilization projects, establishing a dominant east-west trade corridor that shapes regional procurement patterns and supplier qualification requirements.
China
Domestic electric bus and rail transit manufacturers consume significant ultracapacitor volume through state-owned transit authorities in Shenzhen and Beijing. MIIT dual carbon goals establish GB standards compliance as a mandatory supplier qualification threshold. Centralized fleet electrification timelines compress procurement windows while elevating performance guarantee requirements for module integrators.
Germany
Automotive OEMs integrate ultracapacitor-assisted start-stop systems across light-truck platforms to meet EU Green Deal emissions targets. REACH compliance requirements extend development timelines for novel electrolyte formulations. Industrial clusters in Baden-Württemberg drive demand for acetonitrile-based formulations as fluorinated alternatives face F-Gas Regulation constraints.
United States
Detroit Three automakers specify dual-source energy architectures separating burst power and sustained energy functions. EPA tailpipe standards and NHTSA fuel-economy mandates compel ultracapacitor integration across SUV nameplates. Grid stabilization deployments concentrate in Texas and California where frequency regulation services prioritize cycle life metrics.
South Korea
Utility operators specify high-voltage module architectures for grid frequency regulation services. Domestic module integrators leverage advanced electrode material science to capture differentiated contract positions. Busan-Ulsan industrial corridors anchor manufacturing scale for regional export markets.
India
Production-linked incentives for advanced chemistry cell manufacturing create localized assembly opportunities for module integrators. State-owned power utilities in Maharashtra and Gujarat pilot grid stabilization projects requiring extended temperature operation. Central government procurement frameworks concentrate volume around qualified domestic suppliers.
Ultracapacitors Market Competitive Environment
Channel-controlling players compete with product-specialist players across differentiated procurement tiers. Market structure exhibits moderate concentration with scale-driven manufacturers holding automotive qualification advantages while regional specialists capture grid and industrial segments. Strategic archetypes include graphene electrode innovators, high-voltage module integrators, and cylindrical cell volume producers. Competitive moves center on backward integration into electrode material supply and geographic expansion through joint venture manufacturing.
Among European electrode material specialists, Skeleton Technologies exemplifies curved graphene formulation capabilities. LS Mtron Co., Ltd. and Panasonic Corporation occupy distinct positioning tiers—Korean high-voltage module integration against Japanese cylindrical cell consumer electronics supply chains. These three anchors represent the primary competitive vectors shaping procurement qualification frameworks and technology licensing patterns across automotive and stationary power applications.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Skeleton Technologies |
| Nippon Chemi-Con Corporation |
| Eaton Corporation |
| LS Mtron Co., Ltd. |
| KEMET Corporation |
| Maxwell Technologies |
| NEC Corporation |
| KYOCERA AVX Corporation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor carries electrode material shipments where freight cost volatility feeds directly into module pricing tiers, compressing margins for European integrators while Chinese manufacturers absorb logistics swings through state-backed financing facilities.
Pricing Analysis
Double-layer capacitor pricing sits at commodity parity against declining lithium-ion pack costs, while hybrid capacitor premiums widen as automotive qualification timelines stretch. Three-tier pricing structure across premium, standard, and economy levels separates radiation-hardened aerospace configurations from industrial backup systems and consumer electronics cells. Pricing pressure stems from acetonitrile feedstock volatility concentrated with Chinese petrochemical producers. Consumer electronics buyers exhibit highest price sensitivity, while grid operators prioritize cycle-life guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from Chinese state-owned transit authorities anchor supplier-financing structures that cascade through electrode precursor procurement. Manufacturing gravity centers on China, South Korea, and Germany, with activated carbon processing drawing from coconut shell suppliers in Southeast Asia and synthetic graphite producers in Japan. Single-source vulnerability concentrates in acetonitrile electrolyte feedstock. Distribution runs through Tier 1 automotive module integrators and state utility procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including predictive maintenance contracts and performance guarantee insurance layers are expanding faster than hardware shipments, creating recurring-revenue multiples that justify upfront module cost compression.
For Market Incumbents: Build certification moats around UL and IEC high-voltage bank testing protocols to extend automotive qualification timelines beyond entrant reach. Backward integration into curved graphene electrode production secures material cost advantages against emerging Korean competitors. Capacity addition in India captures PLI scheme benefits before localized qualification requirements harden.
For New Entrants and Emerging Players: Build out solid-state electrode pilot production to bypass incumbent solvent-handling cost structures. India's grid stabilization projects present the most penetrable geography given nascent domestic supplier qualification. Target state-owned power utilities in Maharashtra and Gujarat through joint venture structures with established module integrators.
For Investors and Strategic Acquirers: Korean high-voltage module specialists with established LS Mtron-tier utility relationships represent the priority acquisition archetype. Long-term viability hinges on electrochemical expertise concentration within national laboratory networks rather than manufacturing scale alone. Watch solid-state electrode pilot scale-up announcements as inflection indicators for next-generation cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Materials | Captive graphene supply insulates Skeleton Technologies from acetonitrile volatility. |
| High-Voltage Module Certification Investment | UL testing protocols compress design win windows for automotive tier-one suppliers. |
| Joint Venture Manufacturing in India | PLI scheme localization requirements concentrate volume around qualified domestic assemblers. |
| Solid-State Electrode Pilot Scale-Up | Dry coating processes eliminate solvent handling costs for next-generation manufacturing. |
| Performance Guarantee Insurance Products | Service-attach revenue layers extend customer lifetime value beyond hardware margins. |
Study Parameters
Cross-validation between primary interviews with ultracapacitor procurement managers at Chinese state-owned transit authorities and secondary validation through MIIT production filings anchors the qualitative findings. Stakeholder roles engaged include OEM platform engineers at Detroit Three automakers, utility planning officers at Korean frequency regulation operators, electrode R&D directors at national laboratories, and Tier 1 supplier procurement leads. Secondary sources encompass customs trade data for activated carbon and graphene imports, EPA tailpipe standard compliance filings, SEC 10-K disclosures from component suppliers, and GB standards documentation from SAMR. Bottom-up module shipment tallies triangulate against top-down energy storage investment flows.
Calibration against historical CAGRs from double-layer and hybrid capacitor shipment trajectories shapes the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, application vertical, end-user sophistication tier, and regional regulatory cluster. CAGRs derive from slope analysis of technology adoption curves and input cost trajectories. Forecast inputs incorporate electrode material science advancement timelines and automotive electrification mandate compliance schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by solid-state electrode specialists or state-backed Chinese producers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Solar Storage System Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
South America Energy Storage Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Residential Energy Storage System Market