
 Battery Cell Dry Room Dehumidification Systems Market | 2026-2036
Battery Cell Dry Room Dehumidification Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Cell Dry Room Dehumidification Systems Market Insights
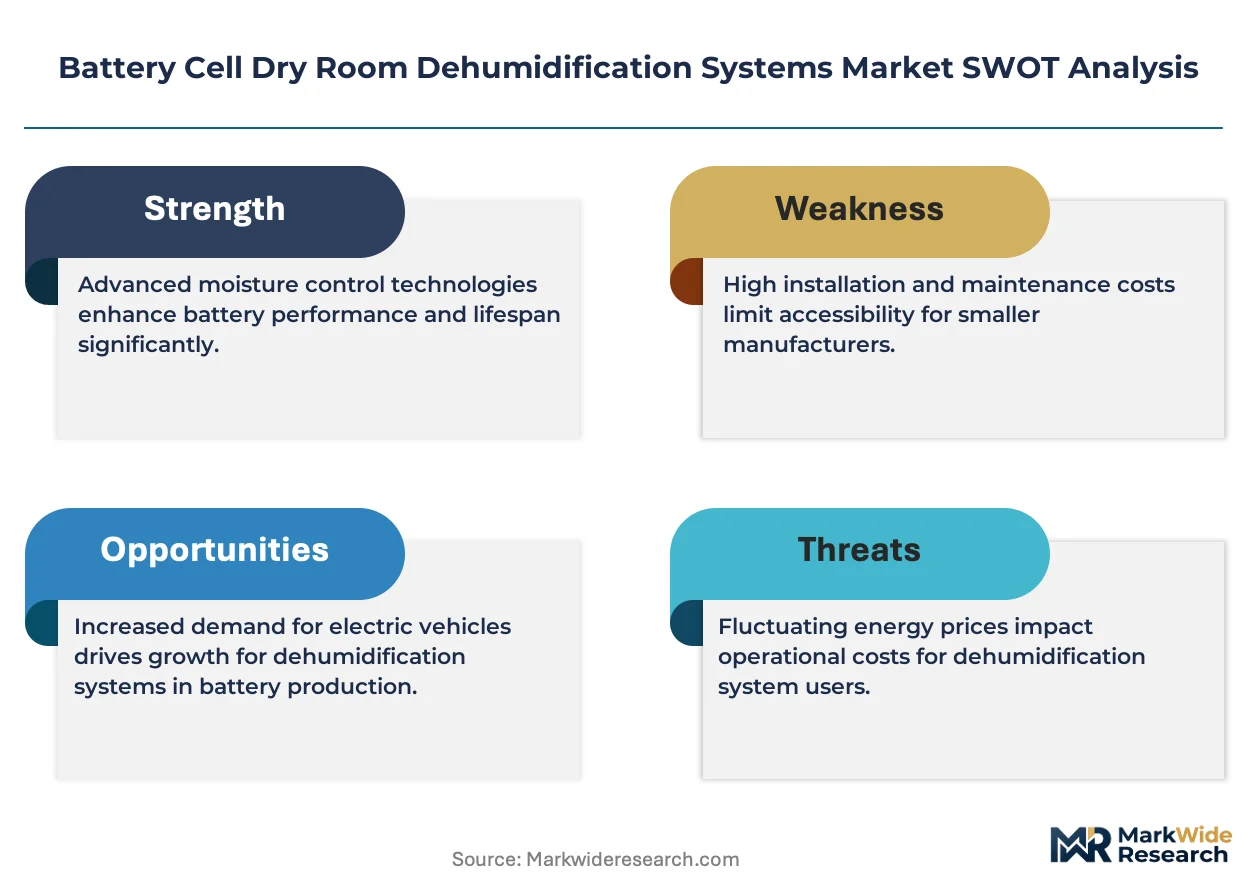
Project finance for large-scale battery gigafactories is narrowing the competitive field for dehumidification system suppliers. Munters leverages its desiccant wheel technology leadership to sustain long-term service contracts with cell producers. Bry-Air anchors its position through backward integration into silica gel rotor manufacturing, controlling critical component supply.
Battery cell dry room dehumidification systems maintain ultra-low dew points, typically below minus 40 degrees Celsius, to prevent moisture contamination during electrode coating and electrolyte filling operations. Desiccant wheel configurations dominate installations above 10,000 cubic meters per hour due to their superior moisture removal capacity at extreme low humidity levels. Membrane dehumidifiers represent the fastest-growing system type as solid-state battery prototyping demands even drier process environments. Application demand concentrates heavily in battery manufacturing, where humidity control directly impacts cell cycle life and safety performance.
China's MEE enforces GB standards on industrial energy consumption that push manufacturers toward hybrid dehumidification systems combining thermal wheels with heat pump recovery. The EU F-Gas Regulation and REACH framework restrict refrigerant chemistries used in conventional cooling-based dehumidifiers, redirecting R&D investment toward alternative drying media. Stakeholders must evaluate whether their technology portfolios can adapt to refrigerant phase-down schedules without sacrificing the minus 60 degree Celsius dew points that next-generation solid-state formats require.
Market Dynamics
The transition from liquid-electrolyte to solid-state battery formats is forcing dry room specifications toward minus 60 degrees Celsius dew points, compressing equipment refresh cycles and concentrating procurement among suppliers capable of extreme humidity engineering.
Growth Catalysts
- China's dual carbon goals:The MEE enforces GB standards that mandate heat recovery in industrial dehumidification, accelerating hybrid system adoption across Jiangsu and Fujian battery clusters.
- Solid-state battery prototyping:Next-generation cell formats require process environments below minus 50 degrees Celsius dew point, pulling membrane dehumidifier demand from pilot lines into volume production.
- CATL and BYD capacity expansion:Gigafactory buildouts in Ningde and Shenzhen are locking in decade-long service contracts for desiccant wheel maintenance and rotor replacement.
Market Restraints
- Silica gel rotor supply concentration:Three Asian manufacturers control over 80 percent of high-performance desiccant media, exposing buyers to input cost volatility and 14-week lead times.
- EU F-Gas Regulation phase-down:The refrigerant chemistry restrictions compress R&D timelines for cooling-based dehumidifiers that cannot achieve ultra-low dew points with alternative working fluids.
- Membrane material technical ceiling:Current polymeric membranes degrade above 80 degrees Celsius, limiting their deployment in electrode drying zones where thermal loads exceed material tolerance.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:The 18,100 crore rupee production-linked incentive is attracting first-mover dry room suppliers to Gujarat and Tamil Nadu greenfield sites.
- AI-driven predictive maintenance:Machine learning algorithms analyzing rotor saturation patterns and airflow differential pressure are enabling outcome-based service contracts that unbundle hardware from uptime guarantees.
- North American IRA clean energy manufacturing credits:The 30 percent investment tax credit for battery production equipment is redirecting European and Asian dehumidification vendors toward Kentucky and Nevada gigafactory projects.
Industry Challenges
- Commissioning engineer scarcity:The specialized skill set combining psychrometrics, cleanroom protocols, and battery process safety commands 40 percent salary premiums, constraining deployment velocity for multi-line facilities.
- ISO 14644-1 cleanroom certification timelines:Third-party validation of particulate and humidity performance adds 8-12 weeks to project schedules, compressing equipment installation windows before production ramp deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Cell Dry Room Dehumidification Systems Market |
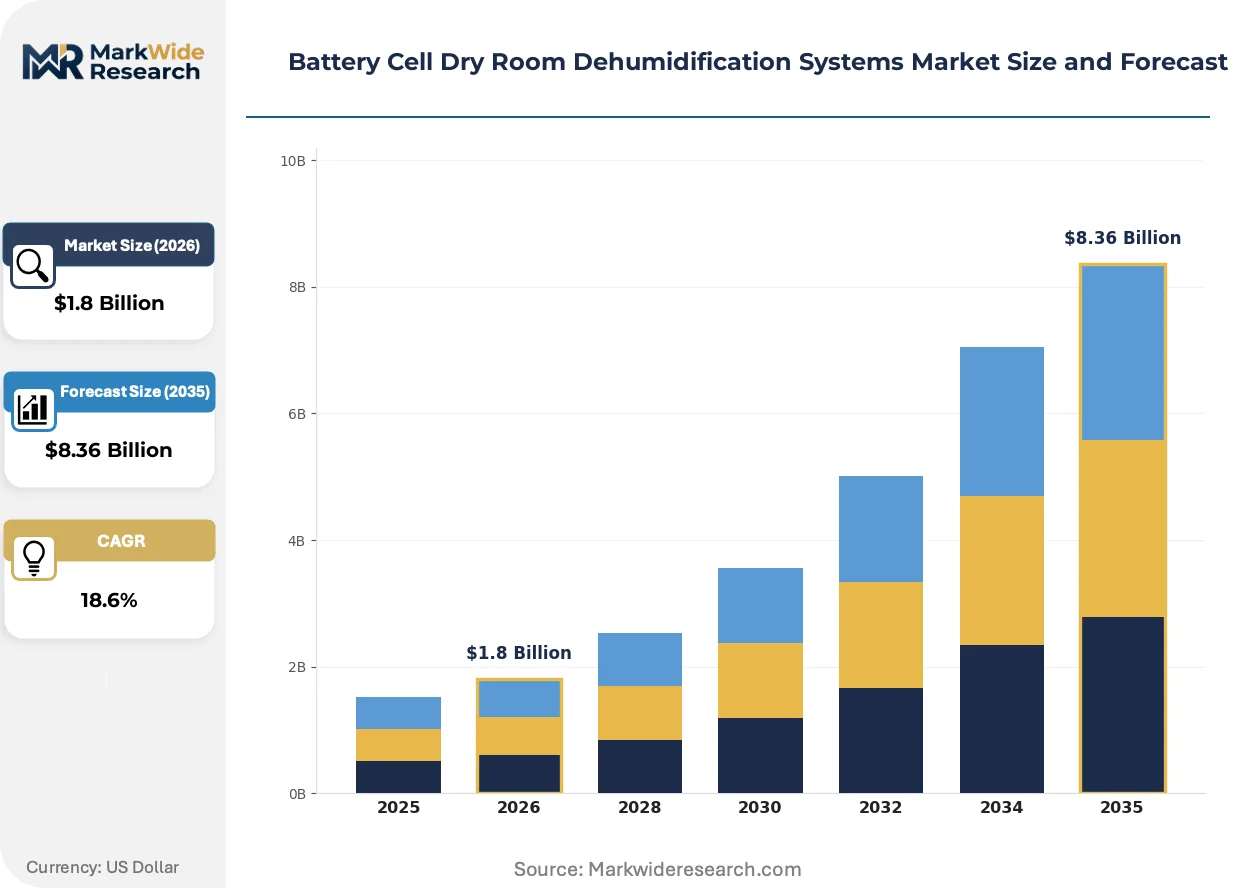
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Refrigerant-Based, Desiccant Wheel, Membrane Dehumidifiers, Hybrid Systems Application: Battery Manufacturing, Semiconductor Fabrication, Pharmaceutical Production, Composite Material Processing End User: Electronics Manufacturers, Chemical Processors, OEMs, Research Laboratories Control Technology: Humidity Sensors, PLC Systems, Remote Monitoring, Programmable Timers, Manual Controls |
| Companies Covered | Munters, Bry-Air, Seibu Giken DST, Cotes, Weiss Technik, Condair, Dürr, Trotec, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Cell Dry Room Dehumidification Systems Market Trends and Innovations
Digital twin technology is compressing commissioning timelines for complex dehumidification arrays while regulatory pressure on refrigerant chemistries accelerates alternative drying media R&D. These forces are reshaping how suppliers defend long-term service relationships.
Desiccant wheel systems equipped with IoT-enabled humidity sensors and edge computing nodes are digitizing maintenance workflows across CATL and LG Energy Solution facilities. Real-time rotor saturation monitoring enables predictive replacement scheduling that cuts unplanned downtime by half. The data infrastructure is digitizing supplier-customer relationships from transactional equipment sales toward continuous performance contracts.
The EU F-Gas Regulation mandates an 80 percent reduction in hydrofluorocarbon consumption by 2030, eliminating conventional cooling-based dehumidifiers from most new battery facility specifications. Equipment manufacturers are redirecting engineering resources toward solid desiccant and membrane alternatives that bypass refrigerant chemistry entirely. German and Hungarian battery plants are piloting hybrid thermal wheel-heat pump configurations that recover 70 percent of process energy while meeting the phase-down timeline.
Cell producers are consolidating procurement authority from individual plant engineers to corporate technical standards teams, centralizing vendor qualification and compressing the approved supplier list. This concentration shifts negotiation leverage toward buyers with multi-gigafactory footprints. The pattern is most visible in South Korea, where Samsung SDI and SK On have standardized on two desiccant wheel suppliers across their domestic and European production networks.
Battery Cell Dry Room Dehumidification Systems Market Segmentation
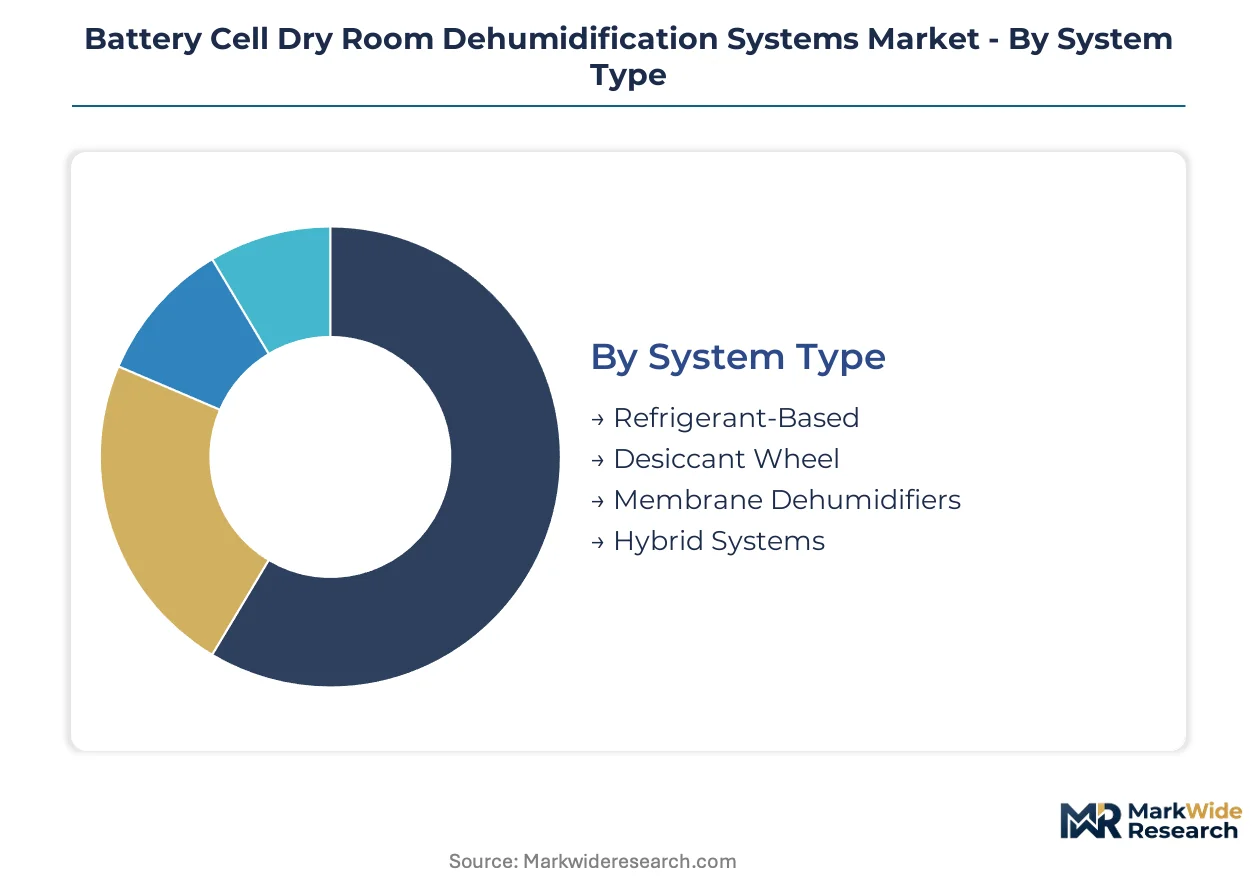
Dry room dehumidification procurement cycles vary dramatically by system complexity and end-use criticality. Equipment refresh timelines stretch from 5-year membrane replacements to 15-year desiccant wheel overhauls, reshaping supplier revenue models across the value chain.
System Type:
Refrigerant-based systems turn over slowest due to capital intensity, while membrane units refresh fastest as solid-state prototyping accelerates pilot-line upgrades.
- Desiccant Wheel:Silica gel or molecular sieve rotors rotate through process and regeneration air streams, achieving dew points below minus 40 degrees Celsius. Jiangsu province's lithium-ion battery cluster near CATL and BYD supply bases concentrates demand as gigafactory buildouts lock in decade-long service contracts.
- Hybrid Systems:Thermal wheel-heat pump configurations recover 70 percent of process energy while meeting EU F-Gas phase-down timelines. German and Hungarian battery plants are piloting these units as MEE GB standards and EU regulations tighten simultaneously.
- Membrane Dehumidifiers:Solid-state battery prototyping below minus 50 degrees Celsius dew point pulls demand from pilot lines into volume production.
- Refrigerant-Based:Conventional cooling dehumidifiers face elimination from new battery specifications under EU F-Gas Regulation mandates.
Desiccant wheel systems anchor the volume base while membrane dehumidifiers gain share at the steepest rate.
Application:
Cost tier separation is pronounced: battery manufacturing commands premium pricing for extreme humidity control, while composite processing tolerates wider dew point bands at lower equipment spend.
- Battery Manufacturing:Electrode coating and electrolyte filling operations require minus 40 to minus 60 degrees Celsius dew points to prevent moisture contamination that degrades cell cycle life. China's dual carbon goals and NMPA efficiency mandates are tightening specifications across Ningde and Shenzhen gigafactories.
- Semiconductor Fabrication:Cleanroom protocols demand continuous humidity control during photolithography and wafer processing steps. SK On and Samsung SDI procurement teams are standardizing vendor lists across domestic and European production networks.
- Pharmaceutical Production:Tablet coating and powder handling operations require moderate dehumidification without extreme low-humidity engineering.
- Composite Material Processing:Carbon fiber layup and resin curing applications tolerate higher dew points, reducing equipment complexity and maintenance frequency.
Battery manufacturing commands the highest equipment investment per square meter while semiconductor fabrication maintains the most stringent vendor qualification protocols.
End User:
Customer type determines contract structure: OEMs negotiate enterprise frameworks, while research laboratories purchase through capital expenditure cycles with minimal service attachments.
- Electronics Manufacturers:Cell producers and semiconductor fabs operate continuous processes where unplanned downtime costs exceed equipment capital expense. AI-driven predictive maintenance analyzing rotor saturation patterns is enabling outcome-based service contracts that unbundle hardware from uptime guarantees.
- Chemical Processors:Specialty chemical and active pharmaceutical ingredient facilities require humidity control for powder handling and reaction stability.
- OEMs:Battery pack integrators and equipment manufacturers specify dry rooms for incoming cell quality assurance and module assembly.
- Research Laboratories:Solid-state battery prototyping facilities purchase membrane units for experimental process environments with limited production scale.
Electronics manufacturers generate the recurring service revenue base while research laboratories drive pilot-line technology transitions.
Control Technology:
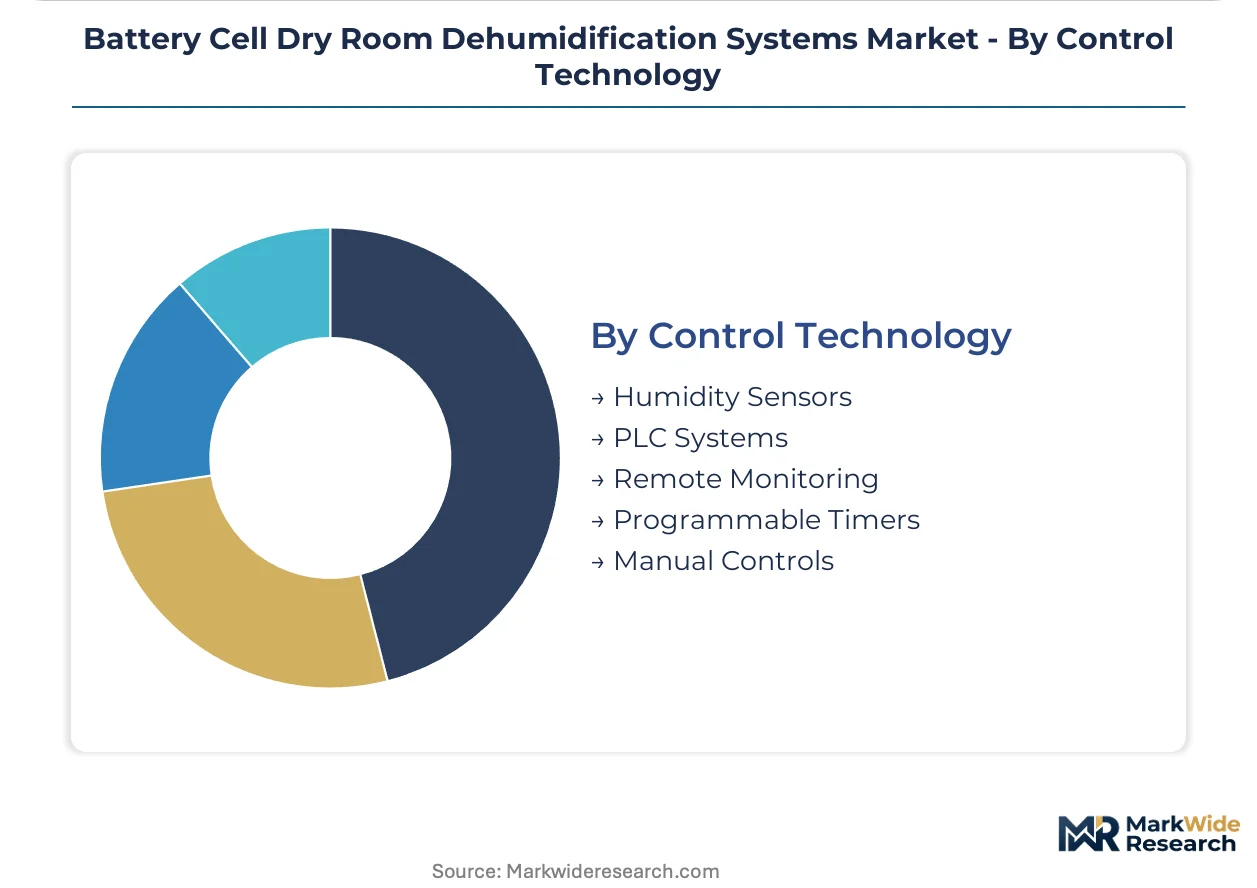
Technology maturity separates legacy installations from greenfield specifications: PLC systems and remote monitoring dominate new construction, while manual controls persist in retrofit budgets.
- Remote Monitoring:IoT-enabled humidity sensors and edge computing nodes digitize maintenance workflows across CATL and LG Energy Solution facilities. Real-time rotor saturation monitoring enables predictive replacement scheduling that cuts unplanned downtime by half.
- PLC Systems:Programmable logic controllers integrate dehumidification arrays with facility management systems for automated setpoint adjustment and alarm management.
- Humidity Sensors:Capacitive and chilled-mirror sensing elements provide feedback signals for control loop optimization.
- Programmable Timers:Basic scheduling functions manage regeneration cycles without continuous process feedback.
- Manual Controls:Operator-adjustable setpoints and regeneration timing persist in legacy installations with limited automation infrastructure.
Remote monitoring platforms are displacing manual controls fastest in battery manufacturing greenfield projects, while programmable timers retain share in cost-constrained retrofit environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Jiangsu province's battery cluster exceeds that of German industrial zones by a substantial margin, reflecting concentrated demand density and tighter regulatory windows. Equipment suppliers command longer contract terms and higher service attach rates in Chinese manufacturing corridors than in European markets where regulatory fragmentation disperses procurement authority.
China
CATL and BYD are expanding dry room capacity across Ningde and Shenzhen to meet aggressive cell production targets. The MEE enforces GB standards mandating heat recovery in industrial dehumidification, pushing manufacturers toward hybrid thermal wheel-heat pump configurations. Jiangsu province's lithium-ion battery cluster concentrates demand as gigafactory buildouts lock in decade-long service contracts for rotor replacement and maintenance.
Germany
SK On and Samsung SDI procurement teams have standardized vendor lists across domestic and European production networks. The EU F-Gas Regulation mandates an 80 percent reduction in hydrofluorocarbon consumption by 2030, eliminating conventional cooling-based dehumidifiers from new specifications. Hungarian and German battery plants are piloting hybrid configurations that recover 70 percent of process energy while meeting phase-down timelines.
United States
The IRA clean energy manufacturing credit redirects European and Asian dehumidification vendors toward Kentucky and Nevada gigafactory projects. Kentucky and Nevada gigafactory developments are accelerating procurement cycles for ultra-low dew point equipment. The 30 percent investment tax credit for battery production equipment is reshaping supplier geographic priorities.
India
The PLI scheme for advanced chemistry cells is attracting first-mover dry room suppliers to Gujarat and Tamil Nadu greenfield sites. The 18,100 crore rupee production-linked incentive creates immediate demand for humidity control infrastructure. Gujarat and Tamil Nadu greenfield developments are establishing new procurement patterns for membrane and desiccant wheel systems.
South Korea
Samsung SDI and SK On have consolidated procurement authority to corporate technical standards teams, compressing approved supplier lists. The MFDS and national industrial regulators enforce cleanroom protocols that align with semiconductor fabrication standards. Seoul Capital Area and Busan-Ulsan industrial corridors concentrate battery and electronics manufacturing demand.
Battery Cell Dry Room Dehumidification Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling critical desiccant media and rotor manufacturing. The market structure concentrates around desiccant wheel technology leaders and membrane system innovators, with procurement authority shifting toward buyers with multi-gigafactory footprints. Three archetypes dominate: full-system integrators with service contract depth, component manufacturers with captive rotor supply, and membrane technology specialists addressing solid-state prototyping demand. Competitive moves center on backward integration into silica gel manufacturing and predictive maintenance platform development.
Within the full-system integrator tier, Munters and Bry-Air exemplify contrasting strategic positions. Munters represents the service-contract depth archetype, leveraging long-term maintenance relationships with cell producers. Bry-Air occupies the upstream control position through in-house production of silica gel rotors. Seibu Giken DST anchors the precision-engineering segment for extreme low-humidity applications. These three entities collectively illustrate how technology leadership, component supply security, and service infrastructure define competitive differentiation in procurement cycles extending 10-15 years.
| Leading Market Players |
|---|
| Munters |
| Bry-Air |
| Seibu Giken DST |
| Cotes |
| Weiss Technik |
| Condair |
| Dürr |
| Trotec |
| Parker Hannifin |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in high-performance silica gel rotor manufacturing across East Asian production hubs is compressing supplier margins while amplifying pricing leverage for desiccant media specialists. The 14-week lead times documented across Jiangsu and Fujian battery corridors force buyers into long-term offtake commitments that lock in service-anchored pricing structures.
Pricing Analysis
Configured-to-order pricing for minus 60 degrees Celsius dew point systems commands substantial premiums over standard minus 40 degrees Celsius configurations. Project-based contracting dominates, with price differentiation resting on certification grade and customization level. Cost compression in standard desiccant wheel tiers is intensifying because membrane alternatives are capturing pilot-line volume. Research laboratories exhibit highest price sensitivity due to capital expenditure cycles, while electronics manufacturers with multi-gigafactory footprints negotiate enterprise frameworks with embedded service guarantees.
Supply Chain Analysis
Silica gel feedstock production concentrates in China, Japan, and South Korea, with molecular sieve media sourcing tethered to petrochemical catalyst supply chains. High-performance desiccant rotors, aluminum honeycomb substrates, and precision drive motors constitute critical input dependencies. Single-source vulnerability in specialty zeolite manufacturing exposes buyers to input cost volatility. Distribution runs through direct OEM relationships for large-scale installations, with aftermarket rotor replacement flowing through authorized service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating among buyers with multi-gigafactory footprints, fragmenting the supplier base into service-contract specialists and component manufacturers. Samsung SDI and SK On's vendor list compression across domestic and European networks exemplifies this shift.
For Market Incumbents: Pre-empt membrane technology displacement by embedding predictive maintenance platforms into existing desiccant wheel installations. Secure captive supply of high-performance silica gel media through backward integration into rotor manufacturing. The EU F-Gas Regulation phase-down threatens cooling-based system incumbents unable to pivot toward solid desiccant alternatives.
For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cells offers the most penetrable geographic entry point, with Gujarat and Tamil Nadu greenfield sites lacking established service infrastructure. Target membrane dehumidifier supply for solid-state battery prototyping facilities as a beachhead application. A technical partnership with commissioning engineering specialists accelerates credibility in psychrometrics-intensive installations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid thermal wheel-heat pump configurations as MEE GB standards and EU regulations tighten simultaneously. Acquisition targets should display in-house rotor manufacturing capability or AI-driven predictive maintenance platforms. Watch for silica gel supply contract renegotiation cycles as inflection indicators of supplier pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Gel Manufacturing | Captive rotor supply secures margin control against 14-week lead time volatility in Jiangsu corridors. |
| AI-Driven Predictive Maintenance Platform Deployment | Outcome-based service contracts at CATL and LG Energy Solution facilities unbundle hardware from uptime guarantees. |
| Hybrid Thermal Wheel-Heat Pump Configuration Launch | Seventy percent energy recovery meets MEE GB standards and EU F-Gas phase-down timelines simultaneously. |
| Membrane Dehumidifier Scale-Up for Solid-State Prototyping | Minus 50 degrees Celsius dew point capability captures pilot-line demand transitioning to volume production. |
| Geographic Expansion to India PLI Scheme Sites | Gujarat and Tamil Nadu greenfield developments establish first-mover positioning in 18,100 crore rupee incentive corridor. |
Research Methodology
A standing panel of dry room commissioning engineers, battery plant facility managers, OEM procurement directors, and aftermarket service heads provided ongoing calibration across primary interview cycles. Secondary validation drew from customs trade data, MEE GB standard filings, EU F-Gas Regulation implementation notices, and SEC equipment supplier disclosures. Bottom-up project pipeline analysis triangulated against top-down capacity buildout announcements across Ningde, Shenzhen, Kentucky, and Nevada gigafactory developments.
Scenario-bracketing framed demand trajectories across conservative, baseline, and accelerated solid-state battery adoption pathways. System type, application criticality, control technology tier, and regional regulatory cluster segmentation dimensions anchored the analytical framework. CAGRs derived from equipment refresh cycle analysis and production capacity expansion schedules, with membrane technology substitution rates and hybrid system adoption curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed equipment consortia would shift outcomes substantially. Cross-checking against announced gigafactory construction timelines and MEE enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Power Bank Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Energy Storage Software Market