
 Power Bank Market | 2026-2036
Power Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Power Bank Market Analysis
The gap between high-volume OEM manufacturing and premium brand R&D spending is collapsing as lithium-polymer cell costs equalize. Anker Innovations leverages its direct-to-consumer channel control to sustain margin density in North American and European markets. Xiaomi Corporation anchors volume leadership through backward integration into battery pack assembly, while Samsung Electronics differentiates via proprietary fast-charge protocol ecosystems.
A power bank is a portable electrochemical energy storage device, typically employing lithium-ion or lithium-polymer cells with capacities ranging from 1000mAh to 20000mAh, designed to recharge consumer electronics via USB-C, Lightning, or wireless induction interfaces. Portable units dominate unit economics due to commodity cell sourcing and minimal enclosure complexity, while solar-integrated variants occupy a premium niche constrained by conversion efficiency limits and weather dependency. The 10000mAh capacity tier captures the largest addressable base, balancing weight constraints against smartphone triple-cycle charging demands.
FCC Part 15 emissions compliance and UN 38.3 lithium battery transport certification shape cross-border shipment eligibility for US-bound inventory, while India's BIS compulsory registration scheme blocks uncertified imports at customs. China's GB 31241 cell safety standard and the EU's REACH substance restrictions add layered compliance costs that favor vertically integrated manufacturers with in-house testing laboratories. Stakeholders must monitor emerging solid-state cell prototypes and regional right-to-repair mandates that could redefine serviceable design requirements and aftermarket channel structures.
Market Dynamics
Lithium-polymer cell cost equalization is collapsing the historical margin buffer between OEM manufacturers and premium brand R&D operations, forcing simultaneous volume and innovation investments across all tiers.
Growth Catalysts
- Smartphone-dependent mobile workforces:Logistics corridors across Asia-Pacific are absorbing high-capacity units for field operations requiring triple-cycle charging reliability.
- India's BIS certification mandate:Compulsory registration scheme at customs is filtering uncertified imports and elevating compliant domestic assembly capacity.
- GB 31241 cell safety standard:China's unified lithium battery transport protocol is harmonizing cross-border shipment eligibility and reducing testing redundancy for export-oriented manufacturers.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress margin predictability for cell pack assemblers lacking long-term offtake contracts.
- Solar conversion efficiency ceiling:Photovoltaic-integrated variants face 15-22% panel efficiency limits that constrain practical charging yields in overcast conditions.
- UN 38.3 transport certification backlog:Testing laboratory capacity constraints in major export hubs delay shipment clearances during seasonal demand spikes.
Strategic Opportunities
- Tier-2 Indian city penetration:Digital payment infrastructure expansion is creating first-time power bank demand among merchant populations previously reliant on shared charging.
- EU right-to-repair mandates:Emerging serviceable design requirements favor modular architectures that enable aftermarket battery replacement and extend product lifecycles.
- Wireless induction convergence:Qi2 magnetic alignment standard integration with USB-C Power Delivery is enabling dual-mode charging ecosystems that command premium positioning.
Industry Challenges
- Solid-state cell integration complexity:Prototype solid-electrolyte designs require retooling of existing pack assembly lines and thermal management systems.
- FCC Part 15 emissions retesting:Design modifications trigger recertification timelines that delay North American market entry by 8-14 weeks.
- REACH substance restriction compliance:EU chemical registry updates demand continuous supply chain auditing for restricted flame retardants and plasticizers in enclosure materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Bank Market |
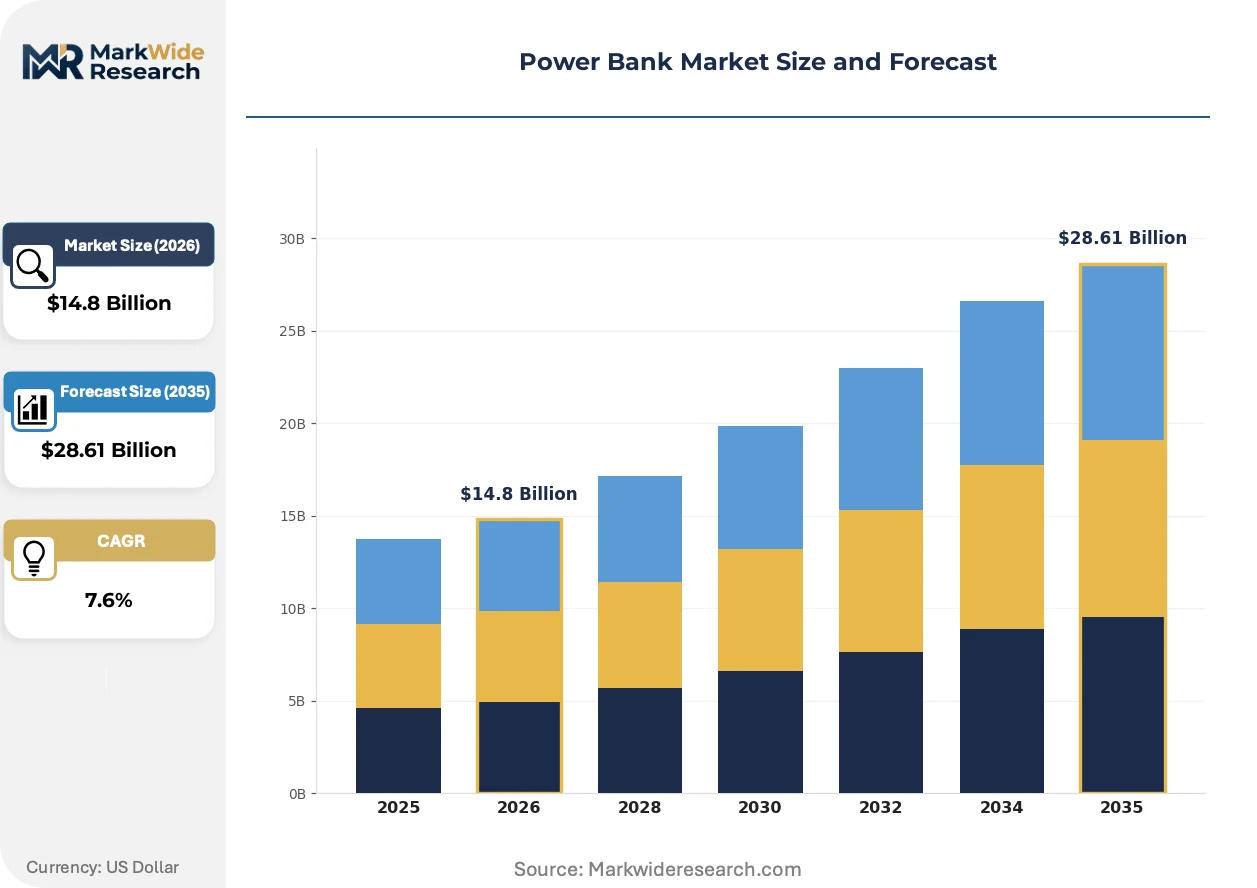
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Solar, AC, Multi-port Technology: Li-ion, Li-polymer, NiMH, Refurbished Capacity: 1000mAh, 5000mAh, 10000mAh, 20000mAh End User: Consumers, Corporate, Retailers, OEMs |
| Companies Covered | Anker Innovations, Xiaomi Corporation, Samsung Electronics, Huawei Technologies, RAVPower, AUKEY, Sony Corporation, Lenovo Group, Ambrane India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Bank Market Emerging Trajectories
Gallium nitride power electronics and solid-state cell prototyping are compressing form factors while regulatory pressure on transport safety and substance disclosure is elevating compliance engineering to a core competency.
Gallium nitride semiconductors in DC-DC conversion circuits are miniaturizing thermal management requirements and enabling 65W+ output from palm-sized enclosures. Mobile professionals and content creators are adopting these units for laptop-tablet-phone simultaneous charging. The technology is miniaturizing the traditional tradeoff between capacity density and port versatility, collapsing the premium tier's physical differentiation advantage.
REACH substance restrictions under ECHA oversight are mandating supply chain disclosure for flame retardants and plasticizers in polymer enclosures. Manufacturers with captive testing laboratories are absorbing compliance costs more efficiently than outsourced certification-dependent competitors. EU-bound inventory faces the most stringent documentation requirements, pushing some suppliers toward simplified material specifications that sacrifice color range for regulatory certainty.
Direct-to-consumer channel control is displacing traditional electronics retail distribution for brand-conscious buyers. Anker Innovations and comparable operators are capturing margin previously allocated to distributor markups through owned storefronts and algorithmic advertising. North American and European urban markets exhibit the highest concentration of this behavioral shift, where same-day delivery expectations override tactile pre-purchase evaluation.
Power Bank Market Segmentation
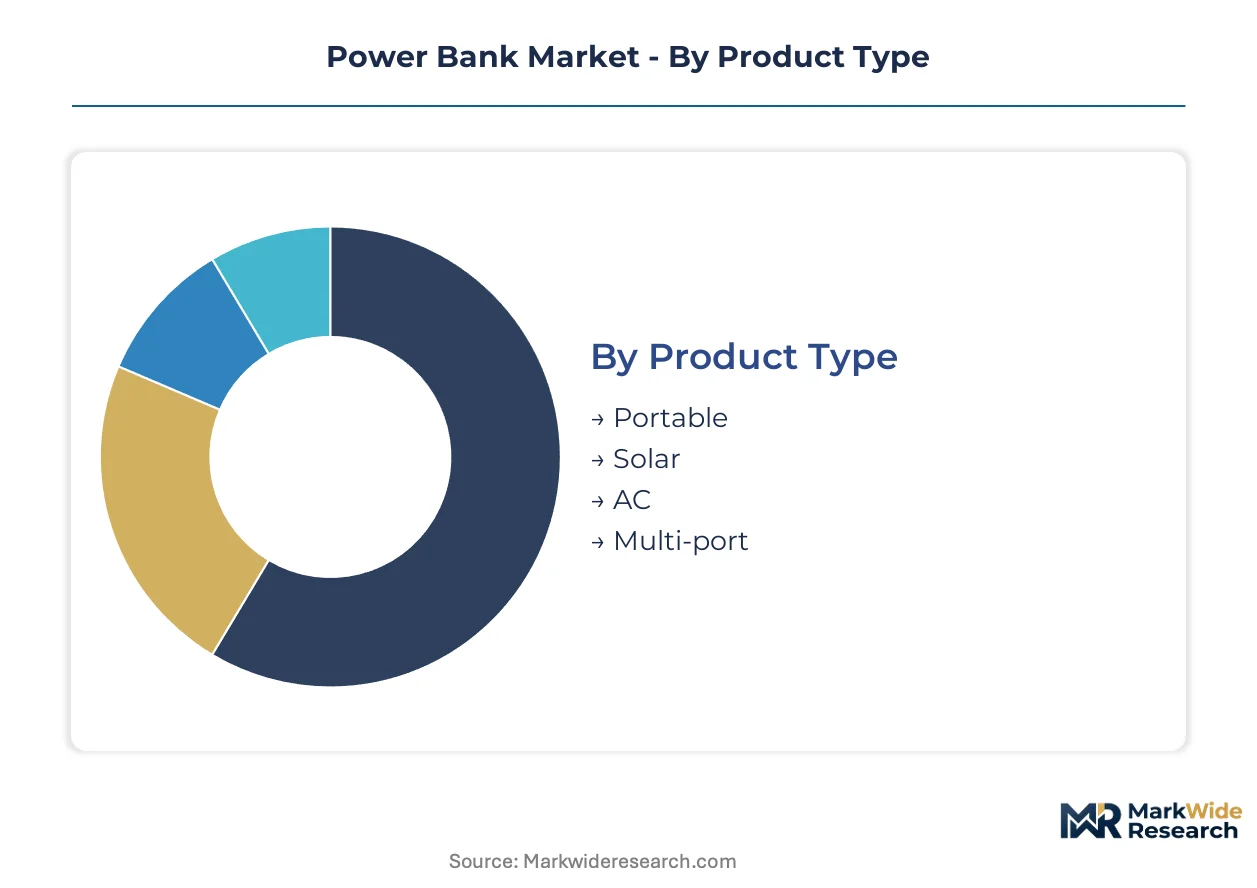
Segmentation in the power bank market reveals how substitution pressures from device-native battery improvements and alternative charging infrastructure reshape demand across product tiers. Understanding these fault lines exposes where margin compression concentrates and which segments retain pricing power.
Product Type:
Portable units face the most acute substitution threat from embedded smartphone battery capacity gains, while solar and AC variants compete against fixed infrastructure expansion.
- Portable:These compact electrochemical storage units, typically housing 10000mAh to 20000mAh lithium-ion or lithium-polymer cells, dominate unit economics through commodity cell sourcing and minimal enclosure complexity. Demand concentrates among smartphone-dependent mobile workforces across Asia-Pacific logistics corridors, where triple-cycle charging reliability outweighs embedded battery improvements.
- Solar:Photovoltaic-integrated designs incorporate monocrystalline or polycrystalline panels with 15-22% conversion efficiency, creating premium positioning constrained by weather dependency and slow charging yields. Adoption clusters among outdoor recreation enthusiasts and remote field operations in regions with unreliable grid access.
- AC:Units with integrated AC inverters enable laptop and small appliance charging through standard wall outlets, serving mobile professionals requiring workstation-equivalent power in transit.
- Multi-port:Configurations with four or more simultaneous output channels address device ecosystem charging needs for content creators and digital nomads managing multiple electronics.
Portable anchors the volume base while multi-port gains share at the steepest rate.
Technology:
Cost tier differentiation separates premium cell chemistries from legacy alternatives facing obsolescence pressure.
- Li-ion:Cylindrical 18650 and 21700 format cells deliver established energy density at the lowest per-watt-hour cost, anchoring mass-market assembly. Procurement concentrates in China's Jiangsu and Guangdong manufacturing clusters where GB 31241 certification compliance is mandatory for domestic sale and export eligibility.
- Li-polymer:Pouch cell architectures enable thinner form factors and custom shapes, commanding premium positioning in direct-to-consumer channels where industrial design differentiation justifies higher price points.
- NiMH:Nickel-metal hydride chemistry persists in price-sensitive emerging market segments where safety perceptions outweigh energy density disadvantages.
- Refurbished:Second-life cells recovered from electric vehicle battery packs enter the power bank supply chain through specialized recyclers, creating economy-tier positioning with shorter cycle life guarantees.
Li-ion captures the highest shipment volumes while Li-polymer commands the strongest margin expansion.
Capacity:
Application-driven sizing creates distinct use-case boundaries that resist direct substitution between tiers.
- 1000mAh:Ultra-compact emergency reserves fit keychain or card-wallet form factors, serving occasional top-up scenarios where device abandonment risk exceeds capacity needs.
- 5000mAh:Single-cycle smartphone charging capability targets daily commuters with predictable access to overnight charging infrastructure.
- 10000mAh:The dominant capacity tier balances weight constraints against smartphone triple-cycle charging demands, capturing the largest addressable base among general consumers and field service personnel.
- 20000mAh:High-density packs enable laptop charging and multi-device simultaneous output, expanding most quickly among mobile professionals and content creators requiring workstation-equivalent autonomy.
10000mAh retains the volume leadership position while 20000mAh climbs the fastest toward share gains.
End User:
Customer type determines channel structure and margin capture potential more than any technical specification.
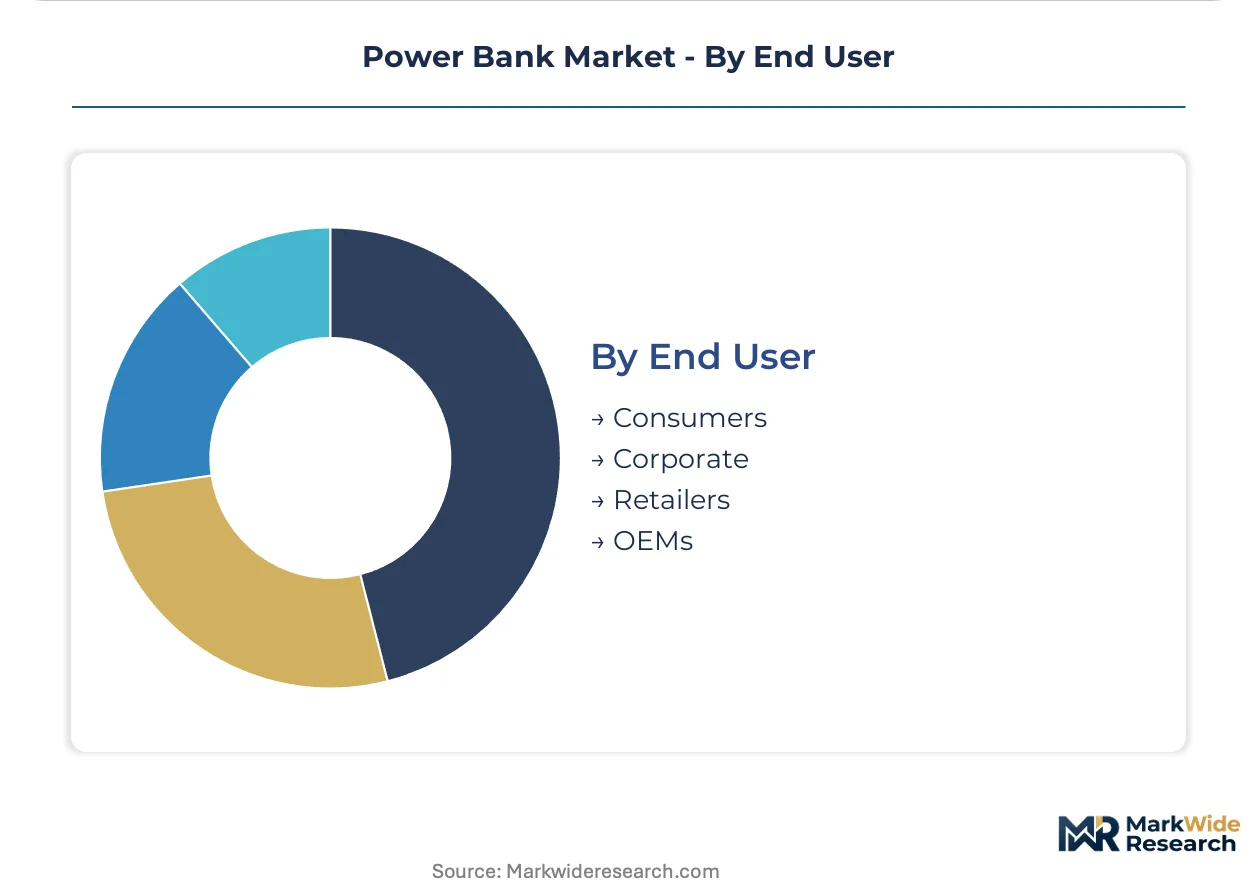
- Consumers:Individual purchasers through direct-to-consumer platforms and electronics retail drive the highest absolute volume, with purchasing decisions dominated by brand recognition and port configuration rather than cell chemistry transparency.
- Corporate:Enterprise procurement for field workforce deployment emphasizes UN 38.3 transport certification and multi-year cycle life guarantees over aesthetic considerations.
- Retailers:Private-label buyers and electronics chains source white-label units for brand extension, with India's BIS compulsory registration scheme filtering supplier eligibility since customs enforcement tightened.
- OEMs:Device manufacturers bundle power banks with smartphone or laptop sales, requiring proprietary fast-charge protocol compatibility and co-branded industrial design.
Consumer channels anchor volume throughput while corporate procurement exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers exhibit the sharpest price elasticity in mass-market tiers, while German and Japanese purchasers absorb premium positioning for certified transport-grade units. Chinese procurement concentrates on domestic GB-certified supply chains, insulating local assemblers from import substitution pressure.
China
Logistics corridors across the Yangtze River Delta absorb high-capacity units for smartphone-dependent delivery fleets requiring triple-cycle charging reliability. MIIT enforces GB 31241 cell safety standards that harmonize cross-border shipment eligibility for export-oriented manufacturers. Shenzhen and Dongguan manufacturing clusters dominate lithium-polymer cell sourcing and battery pack assembly operations.
India
Tier-2 cities generate first-time demand among merchant populations as digital payment penetration deepens beyond metro boundaries. BIS compulsory registration schemes at customs filter uncertified imports and elevate compliant domestic assembly capacity. Noida and Gurugram electronics corridors concentrate contract manufacturing operations serving both local consumption and re-export markets.
Germany
Mobile professionals and content creators adopt gallium nitride-enabled units for laptop-tablet-phone simultaneous charging in transit. ECHA REACH substance restrictions mandate supply chain disclosure for flame retardants in polymer enclosures. Bavaria's industrial design studios shape premium product aesthetics for EU-wide distribution.
United States
Direct-to-consumer channel control displaces traditional electronics retail for brand-conscious urban buyers seeking same-day delivery. FCC Part 15 emissions compliance shapes cross-border shipment eligibility for inventory bound through West Coast ports. California's consumer electronics retail density sustains showroom-based tactile evaluation for premium-tier positioning.
Japan
Corporate procurement for field workforce deployment emphasizes UN 38.3 transport certification and multi-year cycle life guarantees over aesthetic considerations. METI safety standards govern lithium battery transport protocols for domestic distribution. Tokyo-Osaka logistics corridors concentrate enterprise channel distribution for ruggedized high-reliability units.
Power Bank Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium positioning depends on protocol ecosystem control rather than manufacturing scale alone. The vendor base spans vertically integrated cell producers, direct-to-consumer brand operators, and electronics conglomerates with captive accessory channels. Three archetypes dominate: direct-to-consumer specialists with algorithmic advertising mastery, conglomerates leveraging device ecosystem lock-in, and contract manufacturers with BIS/FCC certification infrastructure. Competitive moves concentrate on backward integration into battery pack assembly and direct-to-consumer channel capture.
Within the direct-to-consumer specialist tier, Anker Innovations and AUKEY exemplify algorithmic advertising-driven margin capture through owned storefronts. Xiaomi Corporation anchors the conglomerate archetype with backward integration advantages in cell procurement. Samsung Electronics occupies the ecosystem-lock-in position through proprietary fast-charge protocol compatibility. These three patterns illustrate how certification infrastructure, advertising efficiency, and device integration create distinct competitive moats rather than converging on a single optimal structure.
| Leading Market Players |
|---|
| Anker Innovations |
| Xiaomi Corporation |
| Samsung Electronics |
| Huawei Technologies |
| RAVPower |
| AUKEY |
| Sony Corporation |
| Lenovo Group |
| Ambrane India |
| Others |
Supply Flow & Price Mechanics
Commodity lithium-polymer cell sourcing at 10000mAh scale economies compresses price floors for mass-market assemblers while elevating margin capture for GB 31241-certified operators with captive testing infrastructure. This concentration dynamic rewards Shenzhen and Dongguan manufacturing clusters with procurement leverage over tier-2 Indian and Southeast Asian contract competitors.
Pricing Analysis
After-sales battery replacement services and extended warranty contracts now drive lifetime value more than initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates gallium nitride-enabled multi-port units from legacy single-output designs. Cost compression in the 10000mAh tier intensifies because lithium carbonate volatility squeezes pack assemblers lacking long-term offtake agreements. Corporate procurement teams exhibit the lowest price sensitivity due to UN 38.3 certification requirements, while India's tier-2 merchant buyers absorb the sharpest elasticity.
Supply Chain Analysis
Inventory cycles extending through peak demand seasons strain testing laboratory capacity for UN 38.3 and FCC Part 15 certifications. Cell production concentrates in China, South Korea, and Japan, with Jiangsu and Guangdong provinces anchoring lithium-polymer pouch manufacturing. The supply chain draws from cobalt, lithium carbonate, and copper foil inputs. Single-source vulnerability around gallium nitride semiconductor foundries threatens DC-DC converter availability. Distribution runs through direct-to-consumer storefronts and electronics retail chains, with algorithmic advertising displacing traditional channel markups in North American and European urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power bank hardware margins are flattening toward commoditization, yet certified refurbishment programs and BIS compliance consulting services expand faster than device sales. This service-attach dynamic rewards operators who capture recurring revenue through battery lifecycle management and regulatory navigation.
For Market Incumbents: Fortify position by deepening backward integration into GB 31241-certified cell testing laboratories and securing direct-to-consumer channel control against algorithmic advertising cost inflation. Defend against gallium nitride miniaturization threats by accelerating proprietary fast-charge protocol ecosystem lock-in. Prioritize captive supply of lithium-polymer cells to isolate margin from raw material volatility.
For New Entrants and Emerging Players: Enterprise-grade UN 38.3 certification consulting represents an under-served service layer where incumbents under-invest. Target India's tier-2 city merchant populations through BIS-compliant domestic assembly partnerships and digital payment-integrated point-of-sale financing. Pursue white-label corporate procurement channels with multi-year cycle life guarantees rather than competing on consumer brand recognition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors direct-to-consumer specialists with algorithmic advertising mastery and captive certification infrastructure over pure manufacturing scale plays. Long-term viability across the projection horizon hinges on solid-state cell integration readiness and right-to-repair modular design capabilities. Acquisition targets should demonstrate in-house GB 31241 and UN 38.3 testing capacity. The signal to watch is BIS customs enforcement intensity filtering import eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Testing | Captive GB 31241 and UN 38.3 laboratories compress certification timelines and protect margins from outsourced testing bottlenecks. |
| Direct-to-Consumer Channel Expansion | Owned storefronts and algorithmic advertising displace distributor markups in North American and European urban markets. |
| Gallium Nitride Power Electronics Adoption | 65W+ palm-sized enclosures enable laptop-tablet-phone simultaneous charging for mobile professional segments. |
| Qi2 Magnetic Alignment Integration | Dual-mode wireless and USB-C Power Delivery ecosystems command premium positioning through protocol ecosystem lock-in. |
| Modular Serviceable Design Architecture | EU right-to-repair mandates favor battery replacement programs that extend product lifecycles and capture aftermarket revenue. |
Methodological Framework
A standing panel of battery pack assembly engineers, BIS certification consultants, electronics retail category buyers, and logistics fleet procurement managers provided ongoing calibration against shifting regulatory enforcement patterns. This primary fieldwork combined with secondary validation from MIIT GB standard filings, Indian customs BIS registration databases, UN 38.3 testing laboratory capacity reports, and FCC Part 15 equipment authorization records. Bottom-up shipment data from manufacturing clusters triangulated against top-down consumer spending estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs through the projection horizon. The analytical framework modeled capacity tier, cell chemistry, port configuration, end-user archetype, and regional regulatory cluster segmentation dimensions. CAGRs derived from fitted growth curves applied to base-year shipment values, with inputs including lithium carbonate price indices, smartphone battery capacity improvement rates, and digital payment penetration trajectories in Indian tier-2 cities.
Underlying assumptions cover stable GB 31241 and UN 38.3 enforcement intensity, with deviation risk concentrated in lithium carbonate supply disruptions and solid-state cell commercialization timelines. Forecasts reflect these conditions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Residential Energy Storage System Market
Energy Storage
Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
Supercapacitor Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Solar Storage System Market