
 ASEAN Energy Storage Market | 2026-2036
ASEAN Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Energy Storage Market Outlook
Utility procurement is bifurcating the ASEAN energy storage landscape away from captive industrial installations. BYD Co Ltd leverages its integrated cell-to-system manufacturing to dominate containerized utility tenders in Thailand and Vietnam. GS Yuasa Corporation anchors the region's lead-acid replacement cycle through its established automotive battery distribution networks across Indonesia and Malaysia.
Energy storage encompasses electrochemical and electrostatic systems designed to capture electrical energy for deferred discharge, with lithium-ion cells achieving round-trip efficiencies above 90% at scale. These systems buffer intermittency from solar and wind assets while providing frequency stabilization to national grids. Lithium-ion technology leads installed capacity across ASEAN due to declining cell costs and proven cycle life in tropical climates. Flow batteries occupy a specialized niche in long-duration utility contracts where daily cycling exceeds eight hours. Containerized installations are expanding fastest, driven by standardized shipping formats that slash deployment timelines for islanded grids in the Philippines and Indonesia.
Thailand's Department of Alternative Energy Development and Efficiency mandates energy storage co-location for new solar farms above 10 MW, while Indonesia's MEMR regulations require frequency regulation services from grid-scale battery assets. Vietnam's MOIT circulars on direct power purchase agreements enable private offtakers to contract storage-backed renewable supply without state utility intermediation. Stakeholders must weigh technology lock-in risks against the flexibility premium of modular containerized systems as procurement standards crystallize across divergent national frameworks.
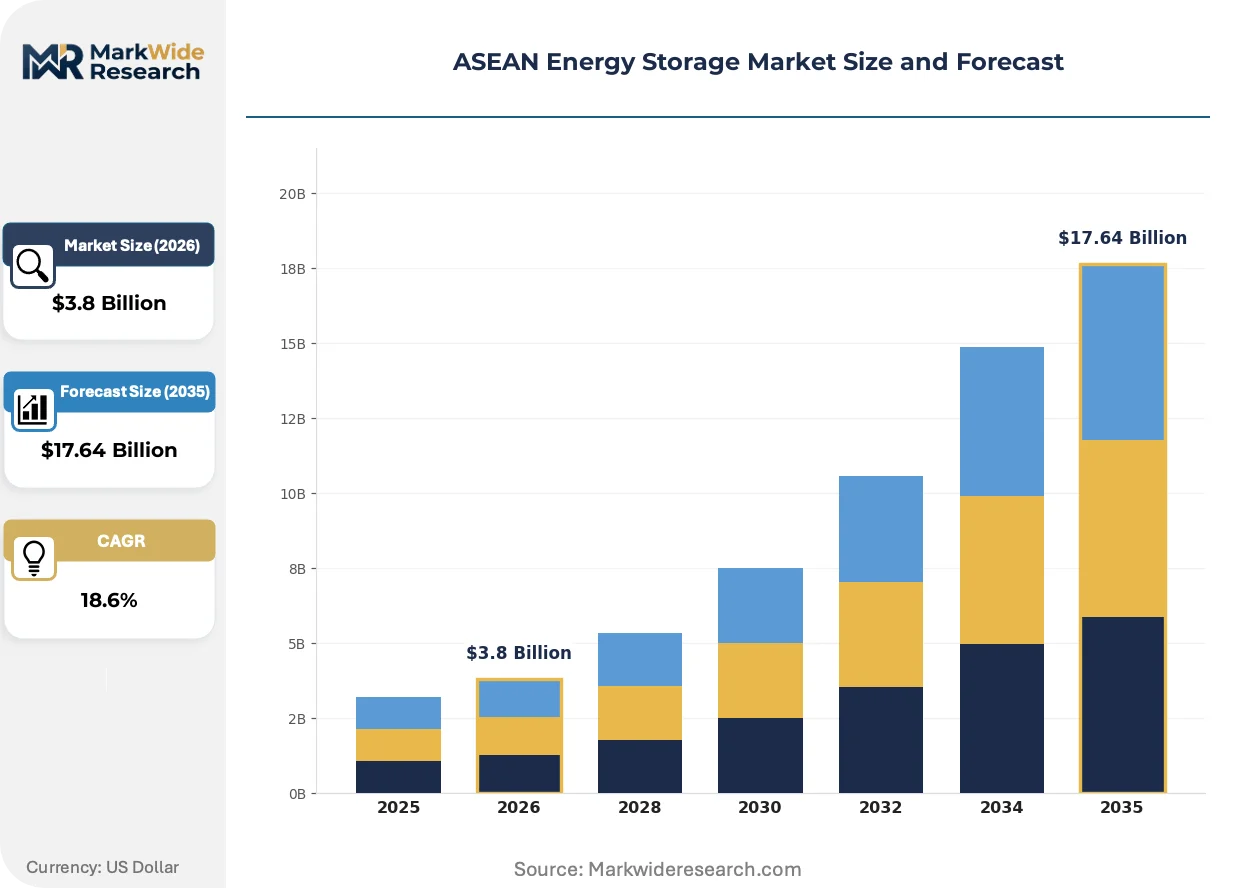
Market Dynamics
Utility-scale procurement is displacing industrial self-consumption as the dominant buyer archetype across Southeast Asia, fundamentally restructuring deployment patterns and vendor selection criteria in the ASEAN energy storage landscape.
Growth Catalysts
- Thailand's DEDE co-location mandate:The Department of Alternative Energy Development and Efficiency requires energy storage paired with new solar farms above 10 MW, forcing developers toward standardized containerized solutions.
- Vietnam's direct power purchase agreements:MOIT circulars enable private offtakers to contract storage-backed renewable supply without state utility intermediation, unlocking commercial and industrial demand.
- Indonesia's frequency regulation requirements:MEMR regulations mandate grid-scale battery assets provide ancillary services, creating guaranteed revenue streams for utility tenders.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress project margins and delay financial close on merchant storage developments.
- Cell supply concentration:Manufacturing capacity clusters in Northeast Asia, exposing ASEAN developers to shipping bottlenecks and currency mismatch risks.
- Tropical degradation rates:High humidity and temperature cycling accelerate electrolyte decomposition, shortening warranted cycle life versus temperate benchmarks.
Strategic Opportunities
- Philippines islanded grids:Archipelago geography and diesel dependence create premium pricing for solar-plus-storage microgrids in Visayas and Mindanao.
- Flow battery long-duration contracts:Daily cycling exceeding eight hours in Indonesian utility tenders favors vanadium redox systems over lithium-ion economics.
- Malaysia's net energy metering expansion:Revised NEM regulations allow commercial consumers to export surplus solar generation, stimulating behind-the-meter storage attachment.
Industry Challenges
- Grid code harmonization delays:Divergent interconnection standards across Thailand, Vietnam, and Indonesia force manufacturers to maintain multiple firmware variants.
- Project finance liquidity gaps:Limited local currency lending and absence of long-dated power purchase agreements constrain non-recourse debt availability.
- Thermal runaway containment certification:Evolving fire safety protocols require expensive third-party testing, extending equipment qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Energy Storage Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Lead-acid, Flow Batteries, Supercapacitors End User: Renewable Energy, Utilities, Industrial, Residential Installation Type: On-grid, Off-grid, Hybrid, Containerized Application: Peak Shaving, Load Shifting, Backup Power, Frequency Regulation |
| Companies Covered | BYD Co Ltd, GS Yuasa Corporation, NGK Insulators Ltd, Samsung SDI, LG Chem Ltd, Contemporary Amperex Technology Co Ltd (CATL), SEC Battery Company, Tesla, Wartsila Oyj Abp, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Energy Storage Market Strategic Shifts
Technology trajectories and procurement models are converging to reshape competitive positioning in ASEAN energy storage, with standardization pressures and regulatory fragmentation creating divergent pathways for market participants.
Solid-state battery research is bifurcating the technology roadmap for tropical climate applications. Automotive-derived cell formats dominate current deployments, but next-generation sulfide electrolyte designs promise enhanced thermal stability for containerized utility installations. Thai and Vietnamese developers are piloting hybrid procurement strategies that split awards between proven lithium-ion and emerging solid-state suppliers.
Indonesia's MEMR regulations on frequency regulation services are compressing commissioning timelines for grid-connected assets. The mandate requires sub-second response capabilities, forcing inverter manufacturers to pre-certify equipment with national grid operators. Battery integrators in Java-Bali now face parallel approval tracks with PLN and independent power producers.
Power purchase agreement structures are fragmenting buyer risk profiles across the region. Merchant exposure is replacing take-or-pay contracts in Vietnam's competitive selection rounds, while Thailand maintains utility-backed offtake for Eastern Economic Corridor developments. Indonesian independent power producers are experimenting with tolling arrangements that separate battery ownership from energy trading rights.
ASEAN Energy Storage Market Segmentation
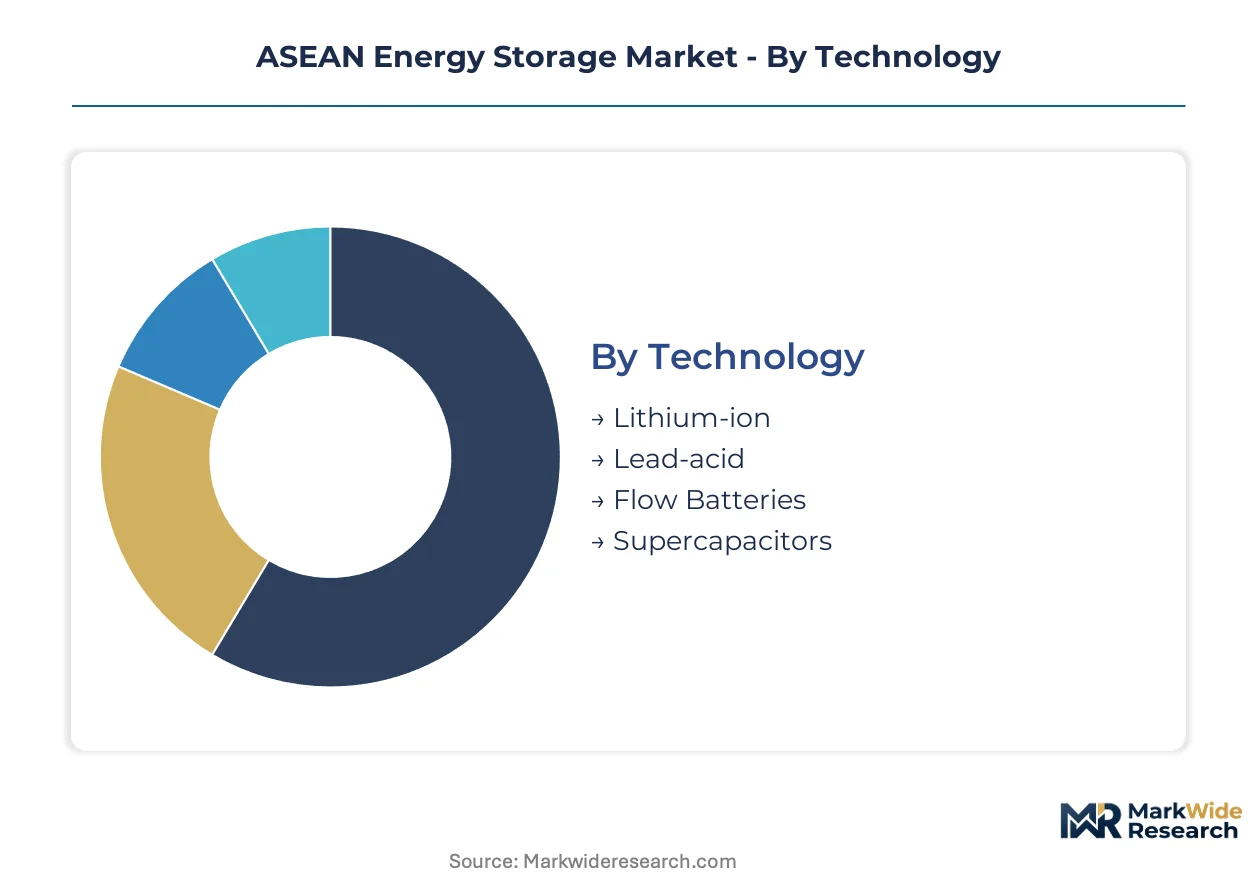
Technology choices in ASEAN energy storage lock in decades of operational economics, while installation type and application segmentation determine which vendors capture procurement mandates from Thailand's DEDE to Indonesia's MEMR.
Technology:
Margin pools concentrate in lithium-ion system integration and long-duration flow battery engineering, where tropical climate adaptation commands pricing premiums.
- Lithium-ion:Nickel-manganese-cobalt and lithium iron phosphate chemistries dominate containerized utility tenders across Thailand and Vietnam. Round-trip efficiencies above 90% and declining cell costs anchor procurement decisions for solar-plus-storage clusters in the Eastern Economic Corridor.
- Lead-acid:Flooded and valve-regulated designs persist in automotive replacement cycles and rural microgrids across Indonesia and Malaysia. Established distribution networks and lower capital outlays sustain demand where cycle depth requirements remain shallow.
- Flow Batteries:Vanadium redox systems capture Indonesian utility tenders requiring daily cycling beyond eight hours.
- Supercapacitors:Electrostatic double-layer capacitors serve frequency regulation applications demanding sub-second response in Java-Bali grid infrastructure.
The dominant share belongs to lithium-ion, while flow batteries are closing the gap fastest on long-duration contracts.
End User:
Customer archetypes split between regulated utility procurement with guaranteed revenue streams and merchant industrial offtakers bearing price exposure.
- Utilities:State-owned power corporations in Thailand, Vietnam, and Indonesia drive grid-scale battery procurement through co-location mandates and ancillary service requirements. PLN, EGAT, and EVN tender standardized containerized assets with frequency regulation obligations.
- Renewable Energy:Solar and wind developers attach storage to meet DEDE co-location rules and MOIT direct power purchase agreement frameworks. Private offtakers in Vietnam contract storage-backed supply without state utility intermediation.
- Industrial:Manufacturing zones in Thailand's Eastern Economic Corridor deploy captive systems for peak demand management.
- Residential:Net energy metering expansions in Malaysia stimulate behind-the-meter attachment for surplus solar export.
Utility procurement commands the largest project pipelines, though renewable energy developers are expanding fastest under Vietnam's competitive selection rounds.
Installation Type:
Deployment format selection trades standardization benefits against site-specific customization needs across archipelago and mainland geographies.
- Containerized:Standardized 20-foot and 40-foot shipping formats slash deployment timelines for islanded grids in the Philippines and Indonesia. Factory-integrated battery management systems and thermal management reduce field commissioning risks in humid tropical conditions.
- On-grid:Grid-connected assets in Thailand and Vietnam provide frequency stabilization and renewable integration services under utility offtake structures.
- Off-grid:Diesel displacement drives solar-plus-storage microgrids across Visayas and Mindanao.
- Hybrid:Combined grid-tied and islanding capabilities serve industrial estates requiring uninterrupted power quality.
Containerized formats hold the dominant procurement share, while hybrid installations are climbing the fastest as resilience requirements harden.
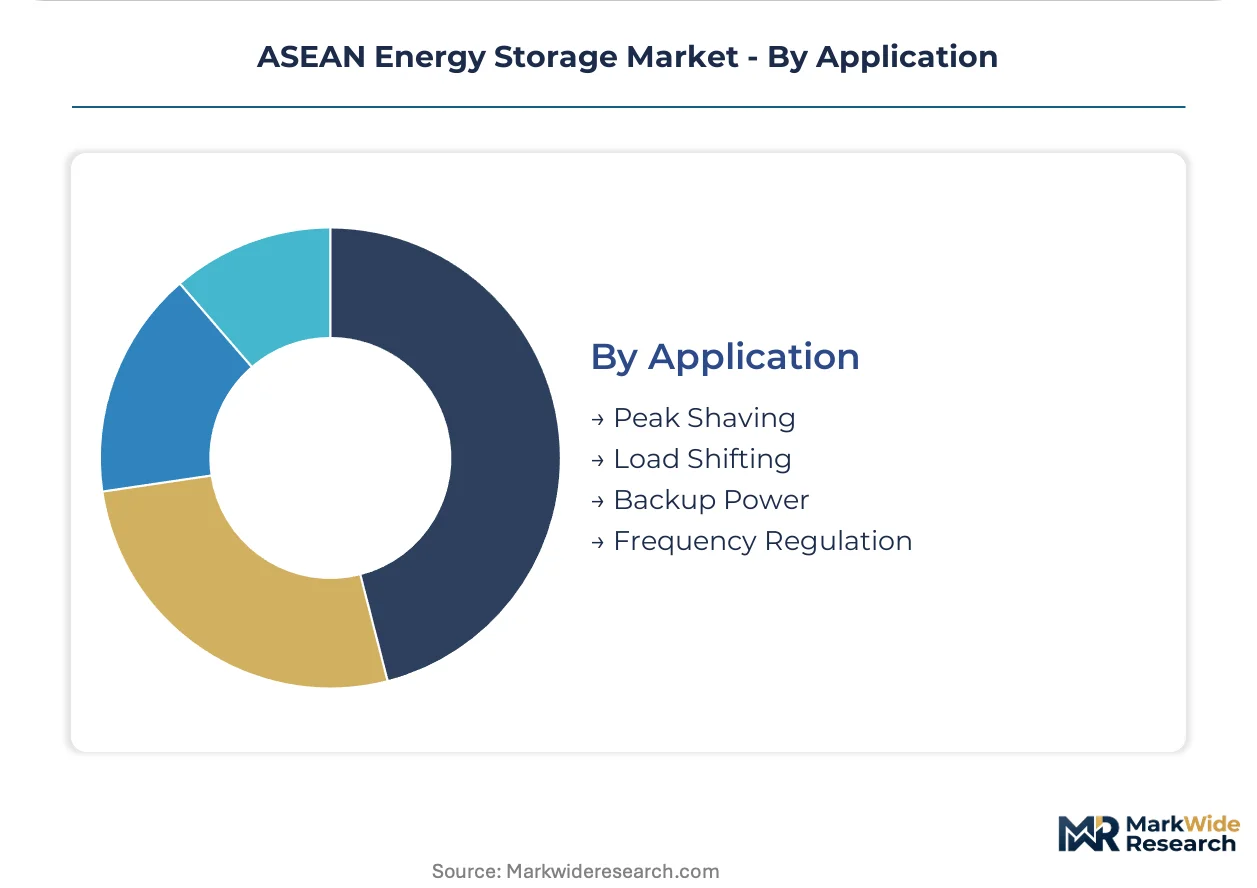
Application:
Revenue stack composition varies by application, with frequency regulation offering contracted returns and peak shaving exposing operators to merchant price volatility.
- Frequency Regulation:Sub-second response capabilities satisfy Indonesia's MEMR mandates and create guaranteed revenue streams for grid-scale assets. Pre-certified inverter equipment with PLN approval tracks separates qualified integrators from commodity suppliers.
- Peak Shaving:Demand charge reduction drives industrial adoption in Thailand's manufacturing corridors where electricity tariffs stratify by time-of-use. Merchant exposure replaces take-or-pay structures in Vietnam's evolving procurement landscape.
- Load Shifting:Arbitrage between low-cost solar generation and evening peak pricing supports utility-scale economics.
- Backup Power:Uninterruptible supply requirements anchor residential and commercial installations where grid reliability fluctuates.
Frequency regulation captures the dominant revenue share, while peak shaving is gaining traction fastest under commercial and industrial procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
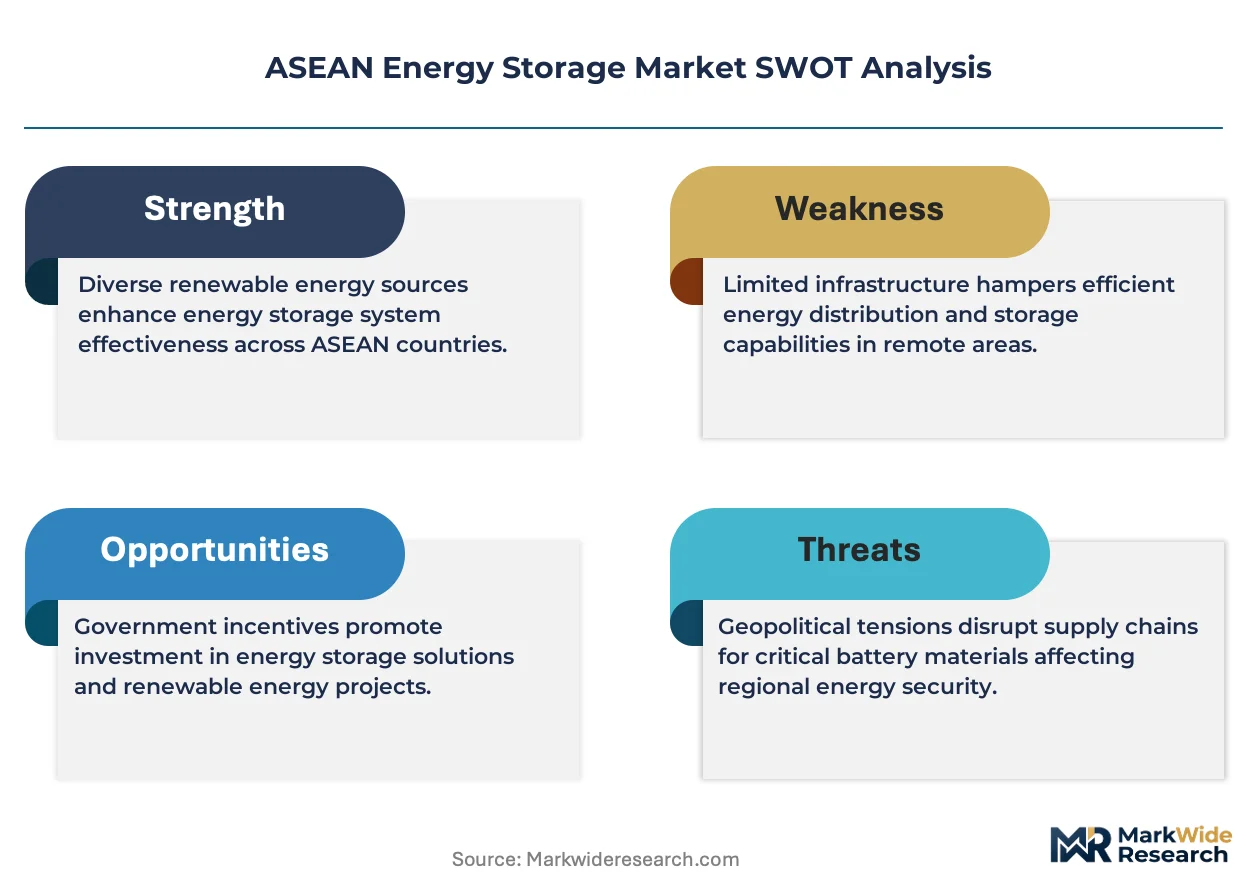
Cell manufacturing capacity clusters in Northeast Asia, exposing ASEAN developers to shipping bottlenecks and currency mismatch risks while procurement standards crystallize across divergent national frameworks.
Thailand
Solar-plus-storage clusters concentrate in the Eastern Economic Corridor where manufacturing zones drive peak demand management. The Department of Alternative Energy Development and Efficiency mandates energy storage co-location for new solar farms above 10 MW. Rayong and Chonburi provinces host standardized containerized deployments serving automotive and electronics factories.
Vietnam
Direct power purchase agreements unlock commercial and industrial demand without state utility intermediation. The Ministry of Industry and Trade circulars enable private offtakers to contract storage-backed renewable supply. Northern industrial provinces including Bac Ninh and Hai Phong anchor grid-connected battery procurement for export manufacturing.
Indonesia
Frequency regulation services create guaranteed revenue streams for utility tenders across the Java-Bali grid. The Ministry of Energy and Mineral Resources regulations mandate sub-second response capabilities from grid-scale assets. Jakarta and Surabaya metropolitan areas concentrate pre-certified inverter equipment approvals with PLN.
Philippines
Archipelago geography and diesel dependence generate premium pricing for solar-plus-storage microgrids. Islanded grids in Visayas and Mindanao deploy standardized shipping formats that slash deployment timelines. Cebu and Davao serve as logistics hubs for containerized installations reaching remote island provinces.
Singapore
Grid stability requirements and land scarcity drive demand for high-efficiency electrochemical systems. The Energy Market Authority frameworks support ancillary service participation from distributed storage assets. Jurong Island industrial complexes pilot hybrid installations combining grid-tied and islanding capabilities for uninterrupted power quality.
ASEAN Energy Storage Market Competitive Environment
Concentration sits with integrated cell-to-system manufacturers and established industrial battery suppliers. The vendor base spans three tiers: vertically integrated Chinese producers commanding utility tenders, Japanese conglomerates leveraging automotive distribution networks, and European power engineering specialists capturing long-duration contracts. Strategic moves center on backward integration into raw material refining and captive supply of battery management system firmware.
Within the integrated manufacturing tier, BYD Co Ltd and Contemporary Amperex Technology Co Ltd exemplify cell-to-system production scale. GS Yuasa Corporation anchors the lead-acid replacement cycle through automotive battery distribution networks across Indonesia and Malaysia. Samsung SDI occupies a position bridging consumer electronics cell supply with emerging grid-scale system integration.
| Leading Market Players |
|---|
| BYD Co Ltd |
| GS Yuasa Corporation |
| NGK Insulators Ltd |
| Samsung SDI |
| LG Chem Ltd |
| Contemporary Amperex Technology Co Ltd (CATL) |
| SEC Battery Company |
| Tesla |
| Wartsila Oyj Abp |
| Others |
Value Chain & Pricing Dynamics
Indonesia's MEMR frequency regulation certification gates both equipment qualification and price differentiation simultaneously, forcing inverter manufacturers to pre-certify with PLN before tender participation while creating tiered supplier pools based on response capability premiums.
Pricing Analysis
Thailand's DEDE co-location mandate dictates the pricing tier structure for containerized utility systems. Premium-mid-economy pricing differentiation separates PLN-pre-certified integrators from commodity suppliers, with frequency regulation capability commanding margin premiums. Cost compression in standard lithium-ion tiers is intensifying because cell supply concentrates in Northeast Asia. Industrial offtakers in Vietnam's manufacturing zones show highest price sensitivity, while Indonesian utility tenders exhibit lowest sensitivity due to guaranteed ancillary service revenues.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for ASEAN battery manufacturing. Cell production clusters in China, South Korea, and Japan, drawing from lithium carbonate feedstock anchored in Australia and Chile. Single-source vulnerability concentrates in cathode precursor refining. Distribution runs through Bangkok, Jakarta, and Ho Chi Minh City logistics hubs serving containerized project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN energy storage is approaching a platform-economics inflection where battery management system interoperability will determine which vendors capture multi-country procurement frameworks.
For Market Incumbents: Fortify firmware certification pipelines with PLN, EGAT, and EVN to defend against emerging Chinese integrators. Backward integration into battery management system software reduces exposure to grid code harmonization delays. Captive thermal testing facilities in Bangkok and Jakarta compress equipment qualification timelines.
For New Entrants and Emerging Players: Anchor in Philippine islanded grids where diesel displacement premiums support higher project margins. Visayas and Mindanao microgrids represent the most penetrable geography. Partner with Cebu and Davao logistics operators for containerized deployment speed.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across flow battery engineering as vanadium redox systems scale for Indonesian long-duration tenders. Target acquisition archetype: system integrators with pre-certified PLN approval tracks and established EPC relationships. Watch for lithium carbonate price stabilization as inflection indicator for merchant storage project finance liquidity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | BYD and CATL's captive production insulates against raw material volatility in Thai utility tenders. |
| Pre-Certification with National Grid Operators | PLN approval tracks separate qualified Indonesian integrators from commodity inverter suppliers. |
| Containerized System Standardization | Factory-integrated thermal management slashes field commissioning risks in Philippine humidity. |
| Flow Battery Long-Duration Positioning | Vanadium redox systems capture Indonesian utility contracts exceeding eight-hour daily cycling. |
| Direct Power Purchase Agreement Structuring | Vietnam's MOIT circulars enable private offtakers to bypass EVN intermediation. |
Study Parameters
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary interviews with secondary validation from IEA reports, FERC-equivalent ASEAN regulatory filings, project development databases, and customs trade records. Bottom-up project pipelines and top-down regulatory mandate trajectories were triangulated for consistency.
External benchmark checks against IEA and EIA-equivalent regional data validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology chemistry, installation format, application type, end-user archetype, and national regulatory framework. CAGRs were derived from installed capacity buildout curves and system cost decline trajectories, incorporating tropical degradation rate assumptions and currency mismatch risk premiums specific to ASEAN procurement.
Material uncertainties — lithium carbonate price volatility, grid code harmonization delays, and thermal runaway certification evolution — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as national renewable energy targets and frequency regulation mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Gravity Energy Storage Market
Energy Storage
Water Electrolysis Machine Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Ultracapacitors Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Power Bank Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Hybrid Solar Wind Energy Storage Market