
 Vehicle Subscription Market | 2026-2036
Vehicle Subscription Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Subscription Market Intelligence
Connected vehicle platforms and embedded telematics is rewriting how automotive OEMs deliver subscription services, shifting from static lease contracts to dynamic, usage-based mobility products. Sixt leverages its European fleet network and digital infrastructure to sustain multi-country subscription operations. FINN anchors its growth model on fully digital onboarding and all-inclusive monthly pricing for individual consumers. Carvolution differentiates through Swiss-market specialization with flexible vehicle-swapping capabilities.
A vehicle subscription is a flexible mobility contract granting consumers temporary access to automobiles through recurring fees that typically bundle insurance, maintenance, and roadside assistance into a single payment, with contract durations ranging from one month to several years and termination options far shorter than traditional leases. The primary commercial purpose is to convert vehicle ownership from a capital-intensive asset purchase into an operating expense with predictable cash flows and minimal residual risk. Monthly subscription plans lead the service type category by revenue contribution due to their alignment with consumer cash-flow preferences and lower psychological commitment barriers. Electric vehicles within the vehicle type segment represent the fastest-growing pool as OEMs use subscription channels to accelerate EV trial and adoption without purchase risk.
The EU Green Deal and national zero-emission vehicle mandates across member states are reshaping fleet composition rules for subscription providers, while the F-Gas Regulation pressures refrigerant choices in climate-controlled vehicle interiors. The US EPA tailpipe standards and state-level ZEV programs in California and New York create divergent compliance obligations for multi-state operators. Stakeholders must monitor how fragmented regulatory timelines for ICE phase-outs alter residual value assumptions and vehicle procurement strategies across operating territories.
Market Dynamics
Connected vehicle platforms and embedded telematics are collapsing the traditional separation between vehicle access and mobility services, enabling real-time usage-based pricing and dynamic fleet reallocation that static lease contracts cannot match.
Growth Catalysts
- EU Green Deal mandates:National zero-emission vehicle requirements across member states are compelling subscription providers to electrify fleets faster than retail purchase channels, creating pull-through for EV-first business models.
- Telematics integration:Embedded connectivity hardware now supports automated mileage tracking, predictive maintenance scheduling, and remote vehicle health monitoring that reduces operational overhead for multi-asset operators.
- Germany:Mature digital infrastructure and established fleet management ecosystems concentrate demand for flexible vehicle access models among corporate mobility managers seeking to convert fixed asset costs to variable operating expenses.
Market Restraints
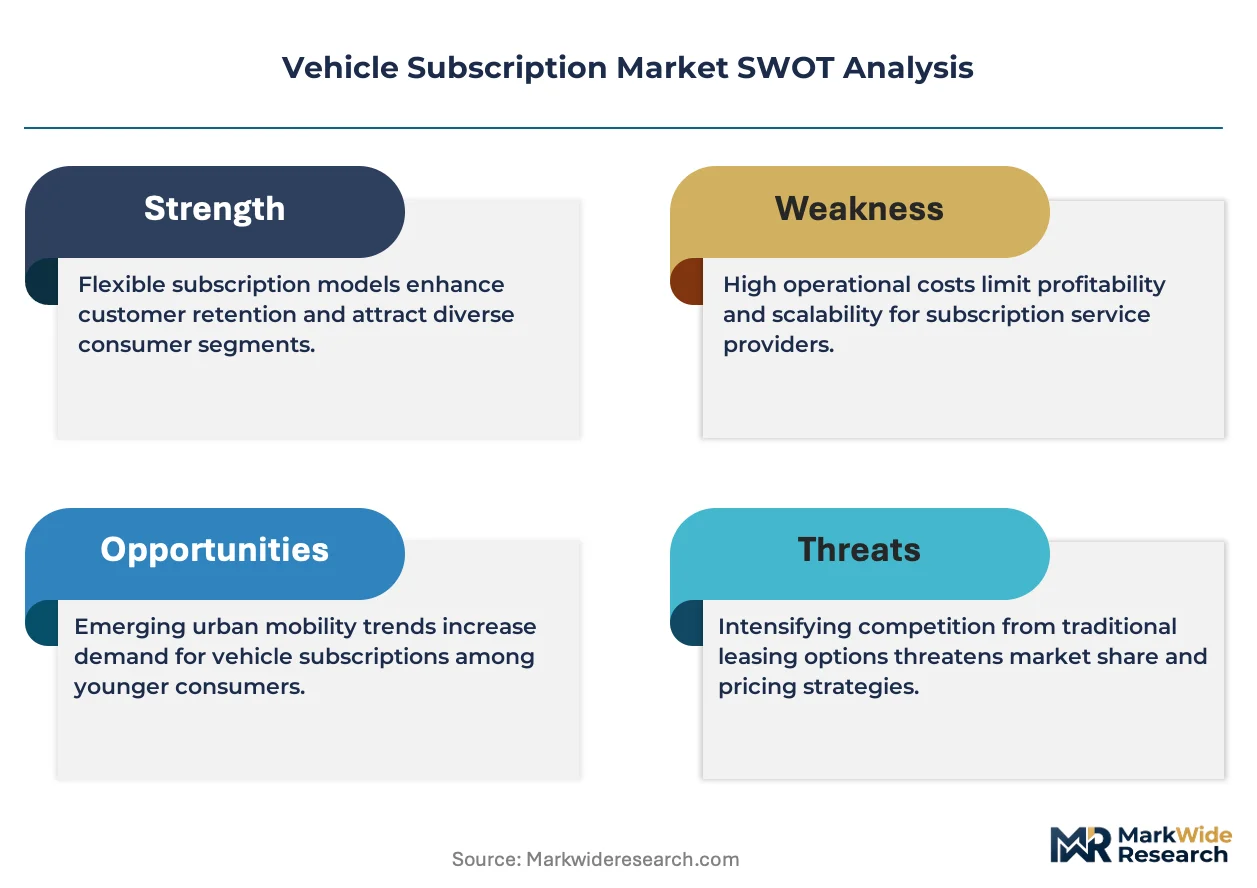
- Residual value volatility:Accelerated ICE phase-out timelines under EU F-Gas Regulation and national bans compress depreciation schedules for internal combustion assets, forcing providers to absorb faster write-downs.
- Insurance cost concentration:All-inclusive pricing models expose operators to aggregate liability risk that concentrates in high-claim geographies, squeezing margins when actuarial assumptions misprice driver behavior.
- Vehicle procurement bottlenecks:OEM allocation priorities favor retail and traditional fleet buyers over emerging subscription channels, constraining supply availability during model-year transitions.
Strategic Opportunities
- India:Underpenetrated flexible mobility markets present first-mover advantages for digital-native platforms that can navigate BIS certification requirements and localize payment infrastructure.
- Usage-based insurance convergence:Real-time driving data streams enable dynamic risk pricing that aligns subscriber premiums with actual behavior, unlocking margin expansion beyond fixed-rate bundled offerings.
- California ZEV program:State-level clean vehicle incentives and HOV lane access privileges for electric subscriptions create differentiated value propositions against conventional ownership in the largest US state market.
Industry Challenges
- Telematics engineering talent scarcity:Shortages of embedded systems developers and data pipeline architects constrain platform scalability for operators racing to deploy connected fleet management capabilities.
- Multi-jurisdiction compliance complexity:Fragmented insurance licensing requirements across US states and divergent data privacy obligations under GDPR versus state-level frameworks multiply legal overhead.
- Legacy dealer network integration:Established franchise agreements and territorial exclusivity clauses complicate vehicle sourcing and service handoff coordination for subscription providers seeking maintenance partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Subscription Market |
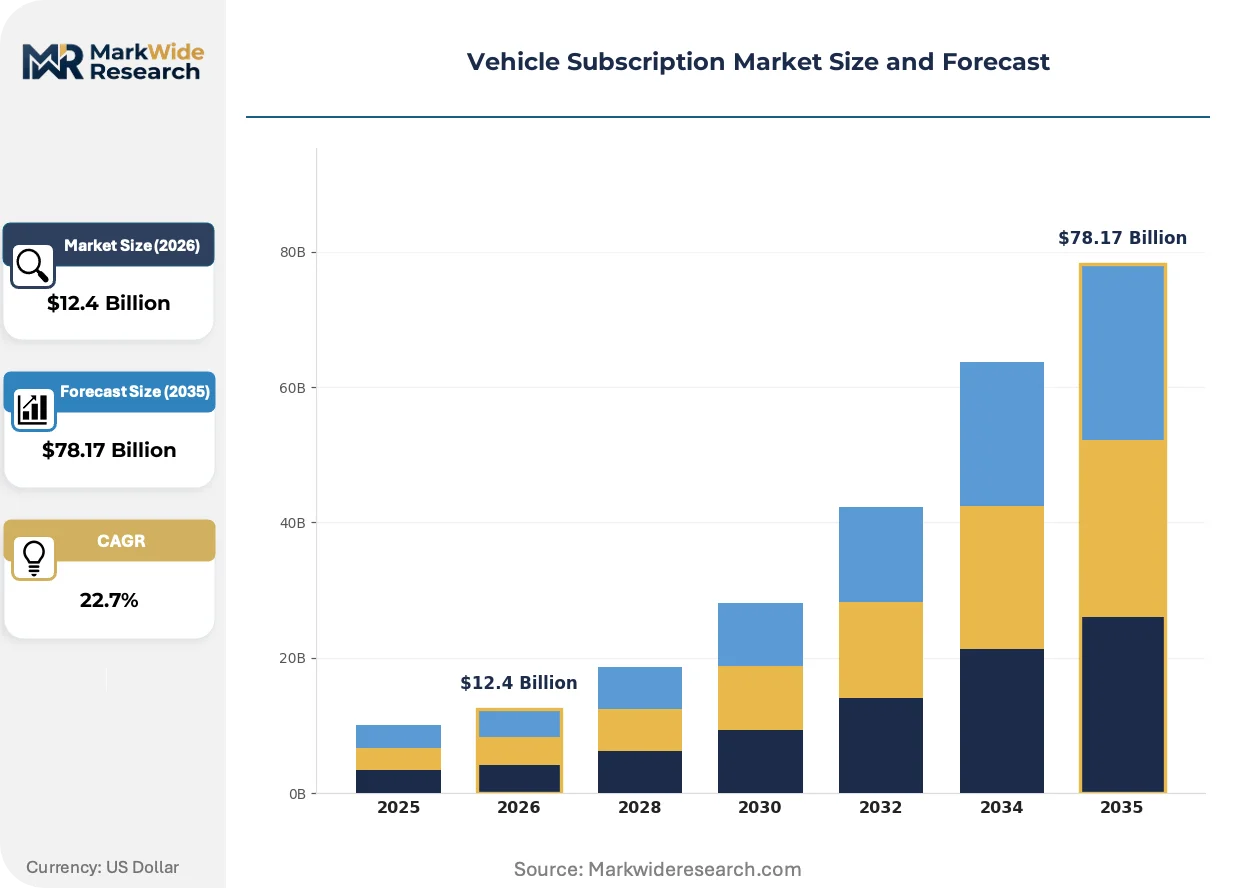
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $78.17 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Monthly Subscription, Daily Rentals, Long-Term Leases, On-Demand Services Customer Type: Individual Consumers, Corporate Clients, Fleet Management, Car Dealerships Vehicle Type: Luxury Cars, SUVs, Electric Vehicles, Sedans Access Method: Mobile Apps, Online Platforms, Dealer Showrooms, Subscription Websites |
| Companies Covered | Sixt, Carvolution, FINN, Mercedes-Benz Mobility, Volkswagen AG, Care by Volvo, BMW Subscription Service, Hertz, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Subscription Market Strategic Shifts & Innovations
Digital-native mobility platforms are dismantling the traditional vehicle distribution stack, compressing customer acquisition cycles and collapsing the information asymmetries that once protected incumbent lease channels.
Embedded telematics hardware is collapsing the distinction between vehicle access and mobility-as-a-service, transforming automobiles into software-defined assets. Fleet operators are deploying these systems at scale to enable real-time utilization tracking and automated rebalancing. This infrastructure compression eliminates the manual inspection and paper-based contracting that previously gated subscription onboarding speed.
EPA tailpipe standards and California Air Resources Board ZEV mandates are forcing accelerated electrification commitments from multi-state operators. The regulatory pressure compresses ICE fleet turnover timelines and elevates compliance costs for providers with geographic exposure to divergent state programs. Electric vehicle subscriptions in New York and Massachusetts markets are responding by front-loading clean vehicle incentives into simplified monthly pricing.
Corporate procurement departments are consolidating mobility spend under single-vendor subscription contracts that displace fragmented lease and reimbursement programs. Human resources and fleet managers in technology and professional services verticals are driving this consolidation, prioritizing consolidated reporting and predictable budgeting over asset ownership. This demand compression is most visible in Germany and the United States, where enterprise mobility budgets exceed individual consumer subscription volumes.
Vehicle Subscription Market Segmentation
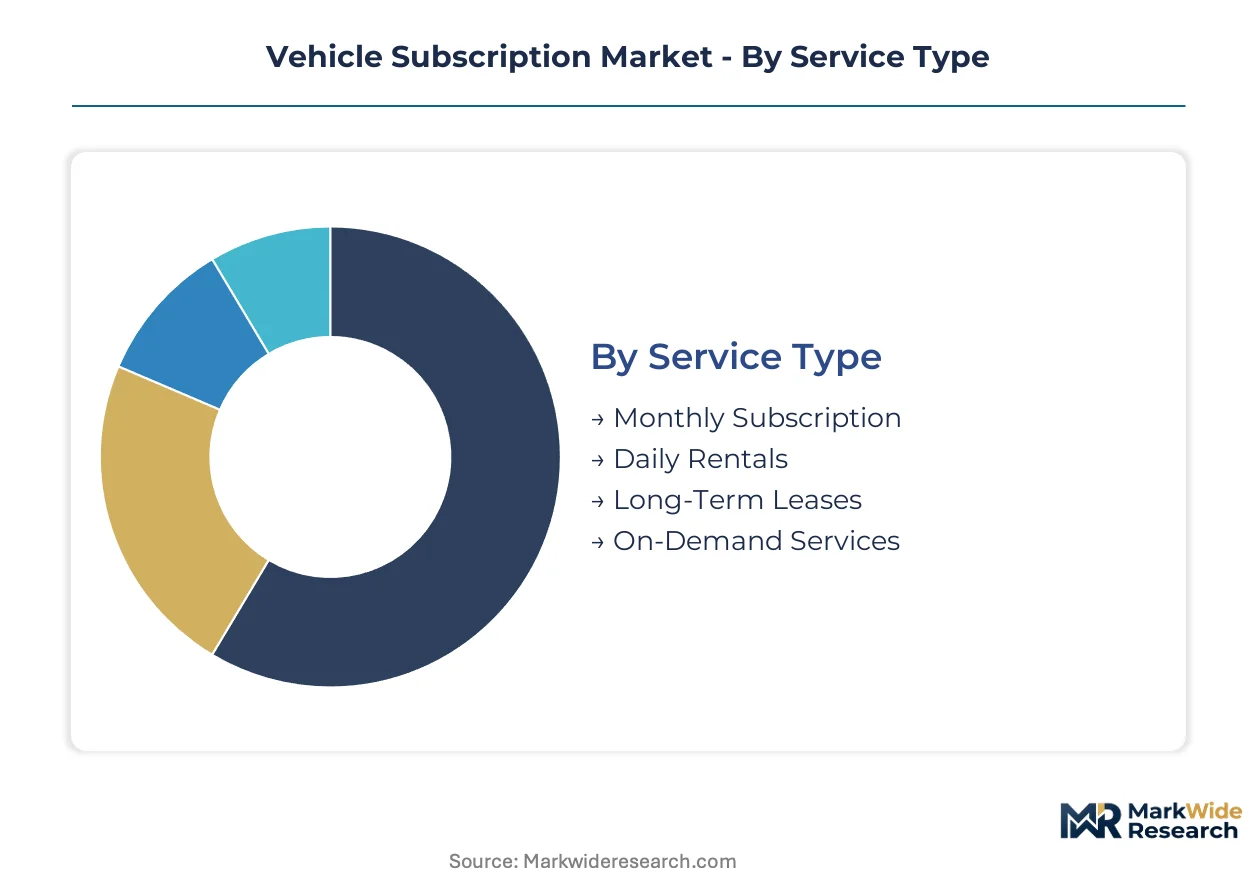
Vehicle subscription segmentation reveals how service architecture, customer economics, and vehicle technology intersect to determine profitability. Each dimension carries distinct operational requirements and capital intensity profiles that shape provider strategy.
Service Type:
Use cases span from daily mobility emergencies to multi-year corporate fleet commitments, with contract duration and bundling depth determining margin structure.
- Monthly Subscription:Recurring payment models consolidate insurance, maintenance, and roadside assistance into single invoices. Corporate mobility managers in Germany favor these structures for converting fixed asset costs to predictable operating expenses with quarterly termination flexibility.
- Daily Rentals:Short-term access periods measured in hours or days serve intermittent mobility needs without residual obligations. Urban consumers in high-density US metropolitan areas leverage these for weekend trips and business travel where parking ownership is impractical.
- Long-Term Leases:Extended commitments spanning 12-36 months with embedded maintenance schedules appeal to risk-averse subscribers seeking price stability. Fleet operators use these to lock in vehicle supply during OEM allocation crunches.
- On-Demand Services:Triggered access activated through digital platforms for immediate vehicle deployment. These models concentrate in Swiss and Dutch markets where dense charging infrastructure supports electric fleet utilization.
Established volume favors monthly subscriptions; emerging adoption favors on-demand services.
Customer Type:
Revenue concentration shifts toward institutional buyers as procurement departments consolidate fragmented mobility spend.
- Corporate Clients:Enterprise procurement teams negotiate master service agreements covering employee mobility across multiple jurisdictions. Technology and professional services verticals in the United States drive this consolidation, prioritizing consolidated reporting over asset ownership.
- Fleet Management:Third-party operators managing vehicle pools for logistics, delivery, and service fleets convert capital-intensive ownership to operating leases. EU Green Deal mandates accelerate their electrification timelines faster than retail channels.
- Individual Consumers:Digital-native subscribers seeking flexibility without credit-intensive purchase commitments. Young professionals in Chinese tier-one cities represent concentrated demand for EV-first trial subscriptions.
- Car Dealerships:Franchise networks deploying subscription inventory to maintain customer relationships between purchase cycles and absorb excess stock during model transitions.
Procurement consolidation elevates corporate clients; digital onboarding efficiency elevates individual consumers.
Vehicle Type:
Powertrain technology and cabin configuration determine depreciation curves and residual value risk exposure.
- Electric Vehicles:Battery-electric platforms with zero tailpipe emissions carry accelerated depreciation schedules under EU ICE phase-out timelines. California ZEV program incentives and HOV lane access privileges create differentiated value propositions against conventional ownership.
- SUVs:Higher-margin body styles with elevated seating positions and cargo capacity command premium positioning. Family-oriented subscribers in suburban US markets prioritize these for safety perception and versatility.
- Luxury Cars:Premium marques with advanced driver assistance and cabin technology attract status-conscious subscribers. Swiss and German markets show concentrated demand for flexible access to aspirational brands without long-term capital commitment.
- Sedans:Traditional three-box configurations with balanced weight distribution and established service networks. Fleet operators favor these for predictable total cost of ownership in high-mileage applications.
Margin concentration favors SUVs; technology transition favors electric vehicles.
Access Method:
Channel economics determine customer acquisition costs and onboarding velocity.
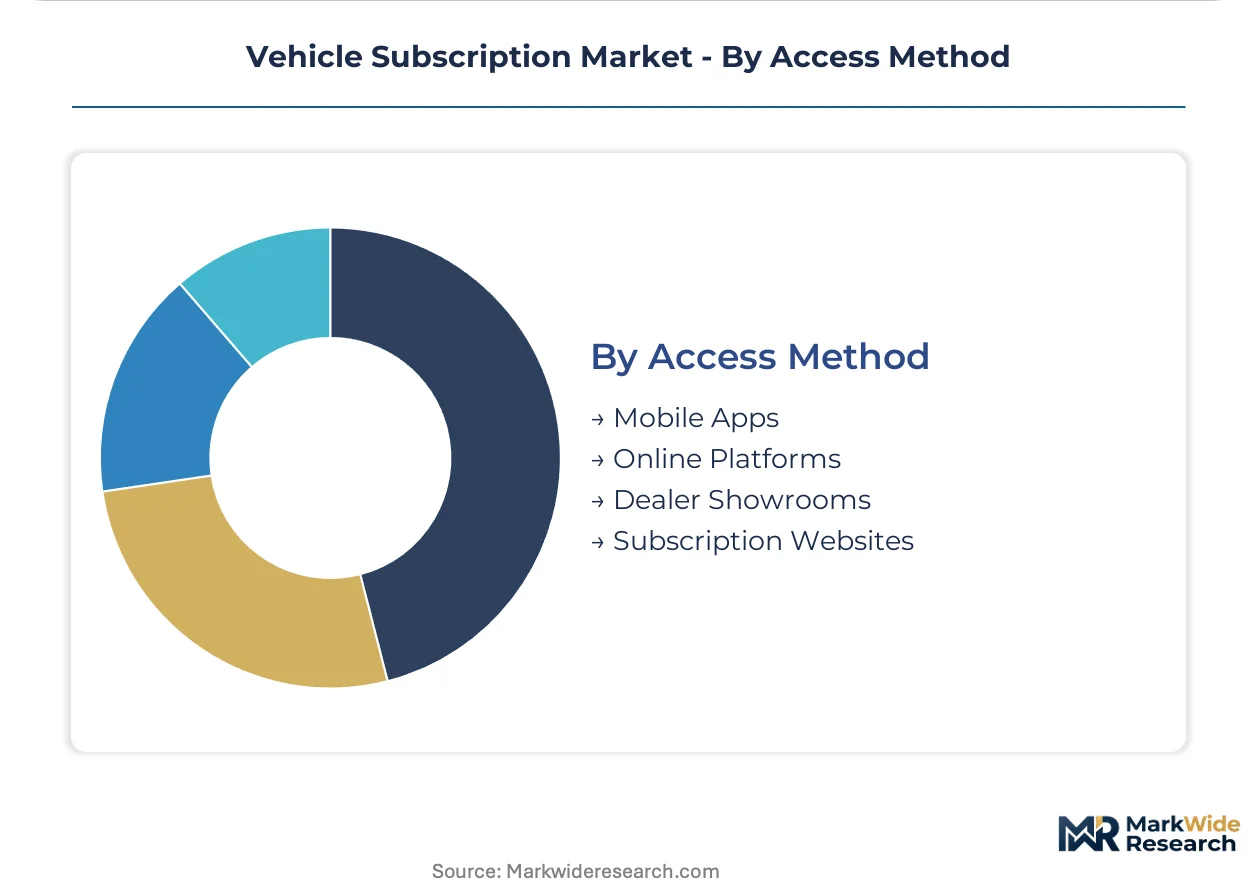
- Mobile Apps:Native smartphone applications with embedded telematics integration enable real-time vehicle status, remote unlock, and mileage tracking. FINN and similar digital-native platforms anchor growth on frictionless app-based onboarding.
- Online Platforms:Browser-based subscription marketplaces aggregating multiple provider inventories for price-transparent comparison. These channels concentrate subscriber acquisition in markets with mature digital payment infrastructure.
- Dealer Showrooms:Physical retail environments where franchise staff demonstrate subscription alternatives to traditional purchase or lease. Legacy network integration faces territorial exclusivity complications.
- Subscription Websites:Dedicated web portals operated by OEM captive finance arms or independent providers for direct consumer enrollment. Sixt leverages these for multi-country subscription operations.
Scalability favors mobile apps; trust establishment favors dealer showrooms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators export subscription management expertise to corporate buyers across the Netherlands and Switzerland, establishing a westward trade corridor in flexible mobility services.
United States
Corporate procurement teams in technology and professional services verticals consolidate fragmented mobility spend under single-vendor contracts. California Air Resources Board ZEV mandates and EPA tailpipe standards force accelerated electrification commitments from multi-state operators. The San Francisco Bay Area and Los Angeles metropolitan clusters concentrate demand for EV-first subscription offerings with HOV lane access privileges.
Germany
Mature digital infrastructure and established fleet management ecosystems drive corporate adoption of monthly subscription models with quarterly termination flexibility. EU Green Deal mandates and national zero-emission vehicle requirements compel providers to electrify fleets faster than retail purchase channels. Berlin and Munich anchor multi-country subscription operations through dense charging infrastructure and centralized fleet rebalancing capabilities.
China
Young professionals in tier-one cities generate concentrated demand for EV-first trial subscriptions without purchase risk. MIIT new energy vehicle mandates and dual carbon goals accelerate battery-electric platform deployment through subscription channels. Shanghai and Shenzhen metropolitan areas lead vehicle-swapping capabilities and embedded telematics integration for real-time fleet utilization tracking.
Switzerland
Status-conscious subscribers in Zurich and Geneva seek flexible access to aspirational luxury brands without long-term capital commitment. F-Gas Regulation pressures refrigerant choices in climate-controlled vehicle interiors while supporting ICE phase-out timelines. The Swiss market specializes in flexible vehicle-swapping capabilities and dense charging infrastructure supporting electric fleet utilization.
India
Underpenetrated flexible mobility markets present first-mover advantages for digital-native platforms navigating localized payment infrastructure. BIS certification requirements and central bank digital payment frameworks shape platform entry strategies. Mumbai and Bangalore metropolitan clusters concentrate early adoption among technology sector employees seeking asset-light mobility solutions.
Vehicle Subscription Market Key Industry Players
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single operator holds dominant share. Fleet-based incumbents leverage existing vehicle pools and maintenance networks while digital-native entrants compress customer acquisition cycles through app-first onboarding. Three archetypes define competitive positioning: fleet-heavy established lessors, OEM captive finance arms, and pure-play digital platforms. Strategic moves center on telematics platform development and geographic expansion through regulatory arbitrage.
Within the fleet-heavy tier, Sixt anchors multi-country subscription operations through European network density. FINN exemplifies the digital-native archetype with fully digital onboarding capabilities. Carvolution occupies a specialized position representing Swiss-market-focused operators with vehicle-swapping differentiation.
| Leading Market Players |
|---|
| Sixt |
| Carvolution |
| FINN |
| Mercedes-Benz Mobility |
| Volkswagen AG |
| Care by Volvo |
| BMW Subscription Service |
| Hertz |
| Hyundai Motor Company |
| Others |
Cost & Logistics Intelligence
Residual value volatility under EU F-Gas Regulation and national ICE phase-out timelines compresses depreciation schedules and forces providers to absorb faster write-downs, widening pricing spreads between electric and combustion fleets while reshaping procurement toward shorter asset-holding periods.
Pricing Analysis
The technology-generation pricing gap between battery-electric platforms, plug-in hybrids, and internal combustion engines determines tier spreads across subscription offerings. Three-tier pricing structure across premium, standard, and economy levels aligns with vehicle age, powertrain certification, and bundled service depth. Price differentiation stems from embedded telematics capability and geographic delivery cost to subscriber locations. Cost compression in combustion fleets is intensifying because accelerated depreciation under EU Green Deal mandates erodes residual assumptions faster than actuarial models project. Fleet management operators show least price sensitivity due to consolidated procurement scale, while individual consumers in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from OEM captive finance arms and supply-chain finance facilities anchor working capital structures for multi-asset operators. Vehicle sourcing concentrates in Germany, China, and the United States where OEM allocation priorities favor retail and traditional fleet buyers. Battery cell supply, semiconductor content, and climate-control refrigerants constitute critical input dependencies. Single-source vulnerability in telematics hardware constrains platform scalability for operators racing to deploy connected fleet capabilities. Distribution runs through digital-native platforms with embedded app onboarding, though legacy dealer networks retain service handoff functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineering and data pipeline architecture expertise sits in acute shortage, constraining platform scalability for operators racing to deploy connected fleet management capabilities.
For Market Incumbents: Build telematics platform moats through proprietary data infrastructure that automates mileage tracking and predictive maintenance scheduling. Deepen backward integration into embedded connectivity hardware to reduce dependency on scarce engineering talent pools. Expand capacity addition in Germany and Switzerland where mature digital infrastructure supports multi-country subscription operations. Invest in GDPR-compliant data architecture to preempt multi-jurisdiction compliance complexity. For New Entrants and Emerging Players: Mid-market corporate mobility managers in India and Southeast Asia represent the most penetrable entry point where flexible mobility markets remain underpenetrated and BIS certification requirements create barriers for less prepared competitors. Digital-native platforms with localized payment infrastructure can capture first-mover advantages before incumbent fleet operators establish presence. Prioritize app-first onboarding with embedded telematics integration to compress customer acquisition cycles against legacy channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platforms with captive vehicle supply and proprietary telematics infrastructure. Long-term viability over the coming decade hinges on electrification execution speed and regulatory arbitrage capabilities across fragmented ICE phase-out timelines. Acquisition target archetype: digital-native platforms with proven multi-jurisdiction compliance frameworks and scalable embedded connectivity deployments. Watch OEM allocation priority shifts toward subscription channels as the inflection indicator for channel power redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Development | Embedded connectivity hardware transforms vehicles into software-defined assets with real-time utilization tracking. |
| Battery Supply Agreement | Long-term cell procurement contracts secure EV fleet expansion under EU Green Deal electrification mandates. |
| Geographic Manufacturing Footprint | Multi-country operations in Germany and Switzerland leverage dense charging infrastructure for fleet rebalancing. |
| Software-Defined Vehicle Investment | Over-the-air capability enables dynamic pricing and remote vehicle health monitoring for margin expansion. |
| Charging Infrastructure Partnership | Strategic alliances with network operators reduce subscriber friction and support electric subscription adoption. |
Research Approach
Desk research of regulatory filings, vehicle production databases, and fleet operator financial disclosures preceded structured interviews with subscription platform executives, automotive OEM captive finance leads, corporate mobility managers, and telematics systems engineers. Primary fieldwork captured operational metrics on fleet utilization, subscriber acquisition costs, and residual value realization. Secondary validation drew from EU Green Deal implementation documents, EPA tailpipe standard rulemakings, and MIIT new energy vehicle policy frameworks. Bottom-up subscriber volume estimates triangulated against top-down market sizing from automotive registration data.
Assumptions held fixed include EU member state ICE phase-out timelines, EPA tailpipe standard stringency, and MIIT dual carbon goal enforcement. Variables tested across the analysis window encompassed EV adoption acceleration rates, telematics platform deployment speeds, and insurance cost inflation in high-claim geographies. Segmentation dimensions modeled span service type, customer archetype, vehicle powertrain, and access channel. CAGRs derived from logistic diffusion curves fitted to historical subscription penetration patterns, with fleet operator expansion rates and consumer preference shifts as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, energy price volatility, or semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Automotive Retail Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Parking Services Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Airbag Repair Service Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Europe Car Wash Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Car Washing Service Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Singapore Car Rental Market