
 Parking Services Market | 2026-2036
Parking Services Market Size, Share, and Industry Trends Forecast 2026-2036
Parking Services Market Analytics
Modular service bundling is broadening buyer choice across the parking services landscape. SP Plus Corporation leverages its national facility management footprint to anchor multi-service contracts with property owners. LAZ Parking competes through specialized event and airport operations that dominate high-throughput venues. ParkMobile LLC differentiates via mobile payment integration that controls digital transaction flows across fragmented municipal networks.
Parking services encompass the organized provision of vehicle storage space, access control, revenue collection, and traffic flow management within structured or surface facilities, typically incorporating automated gate systems, payment kiosks, and real-time occupancy monitoring to maximize space utilization and minimize curb congestion. The primary commercial purpose centers on monetizing land assets while reducing urban circulation delays and emissions from idling search traffic. Valet parking and garage parking operations sustain the deepest margin pools due to premium pricing structures and operational density in central business districts. Mobile payment solutions and parking management software represent the fastest-expanding technology segments as municipalities mandate cashless transactions and demand real-time data interoperability.
The Federal Highway Administration and municipal transportation authorities shape demand through curb management ordinances and accessibility compliance standards that dictate space allocation and technology requirements. EPA emissions guidelines and local air quality regulations accelerate adoption of sensor-driven guidance systems that reduce vehicle circling. Stakeholders must monitor evolving municipal data-sharing mandates and interoperability standards that will determine which technology platforms achieve scalable deployment.
Market Dynamics
Sensor-based parking guidance systems are compressing dwell times and forcing facility operators to restructure revenue models around dynamic pricing algorithms rather than fixed hourly rates.
Growth Catalysts
- EPA emissions guidelines:Local air quality mandates in California, Texas, and New York accelerate deployment of vehicle detection sensors that curb idling search traffic. Municipal procurement now prioritizes vendors with real-time data interoperability.
- E-commerce logistics hubs:Last-mile delivery consolidation in urban commercial districts generates demand for dedicated loading zones managed through automated reservation platforms. Facility operators capture premium rates from logistics tenants.
- 5G-enabled edge computing:Low-latency occupancy processing allows dynamic pricing adjustments at 15-minute intervals. Garage operators in Chicago, London, and Singapore deploy these systems to maximize yield during event surges.
Market Restraints
- Sensor hardware concentration:Lidar and ultrasonic component supply chains cluster in Shenzhen and Seoul, exposing operators to 12-16 week lead times during semiconductor allocation cycles.
- ADA compliance retrofit costs:The Department of Justice's 2024 accessibility enforcement wave forces legacy facilities to reconfigure space layouts, absorbing 8-14% of annual facility revenue in structural modifications.
- Shared mobility substitution:Microtransit and bike-share networks in Copenhagen, Amsterdam, and Vancouver reduce vehicle ownership rates among urban professionals aged 25-40.
Strategic Opportunities
- India's smart city mission:Municipal corporations in Bangalore, Hyderabad, and Pune issue tenders for integrated parking management under the Ministry of Housing and Urban Affairs' 100 Smart Cities program.
- Curbside delivery digitization:Commercial loading zone reservation APIs integrate with logistics fleet management systems. Operators in Frankfurt, Milan, and Barcelona monetize time-blocked access for freight carriers.
- EV charging infrastructure bundling:The EU Green Deal's Alternative Fuels Infrastructure Regulation mandates charging point density targets. Parking facilities combine storage monetization with energy retail margins.
Industry Challenges
- Interoperability talent scarcity:Facility operators struggle to recruit software engineers capable of integrating legacy PARCS hardware with cloud-native payment platforms and municipal open-data APIs.
- Dynamic pricing algorithm liability:Litigation risk emerges when surge pricing during medical emergencies or severe weather events triggers consumer protection complaints and regulatory scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parking Services Market |
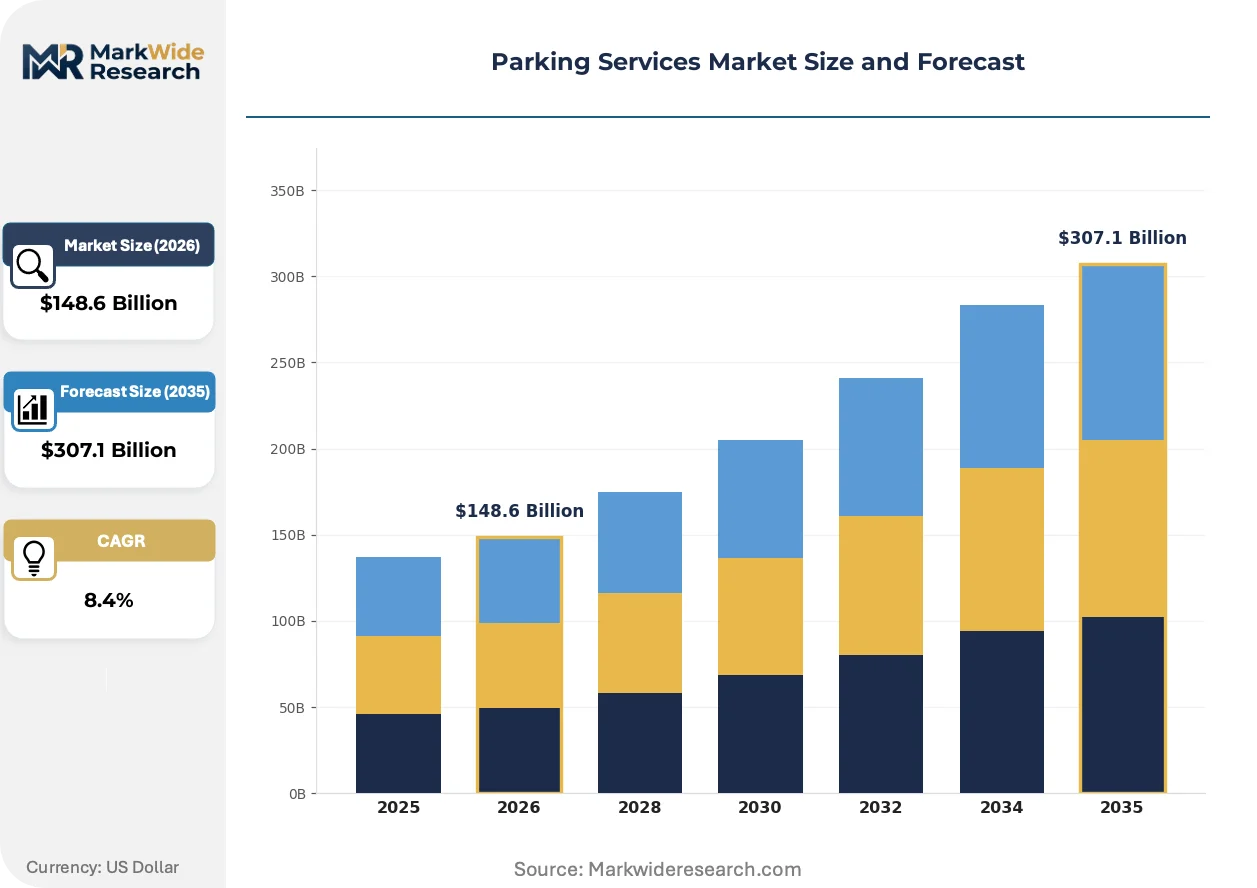
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $307.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Valet Parking, Self-Parking, Garage Parking, On-Street Parking End User: Commercial Spaces, Government Facilities, Residential Areas, Event Venues Technology: Mobile Payment Solutions, License Plate Recognition, Parking Management Software, IoT Sensors Payment Model: Hourly Rates, Subscription Plans, Flat Fees, Dynamic Pricing |
| Companies Covered | LAZ Parking, SP Plus Corporation, ABM Industries, Propark Mobility, ParkMobile LLC, SpotHero Inc, Passport Labs Inc, FlashParking Inc, Impark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parking Services Market Evolving Landscape
Computer vision and edge AI are compressing the gap between vehicle detection and payment authorization, eliminating friction points that previously required human attendant intervention.
Camera-based occupancy detection with embedded machine learning inference is electrifying how garage operators manage space allocation. Large commercial property owners in Manhattan, Dubai, and Sydney deploy these systems to eliminate loop detector maintenance and enable license plate recognition for frictionless entry. The technology compresses payment processing from 45 seconds to sub-3-second automated billing, collapsing the cost structure of attended facilities.
The EU AI Act's risk classification framework imposes documentation and human oversight requirements on automated decision systems used for pricing and access control. Parking operators deploying dynamic rate algorithms in France, Germany, and the Netherlands must maintain audit trails and appeal mechanisms. Mid-sized municipal contractors without compliance infrastructure face procurement exclusion from public facility contracts.
Fleet managers at logistics and ride-hailing companies now mandate API-first parking procurement that unbundles space reservation from payment settlement. Corporate buyers in São Paulo, Mexico City, and Jakarta negotiate enterprise contracts with guaranteed availability blocks rather than spot-market transactions. This procurement compression squeezes independent garage operators lacking real-time inventory connectivity.
Parking Services Market Segmentation
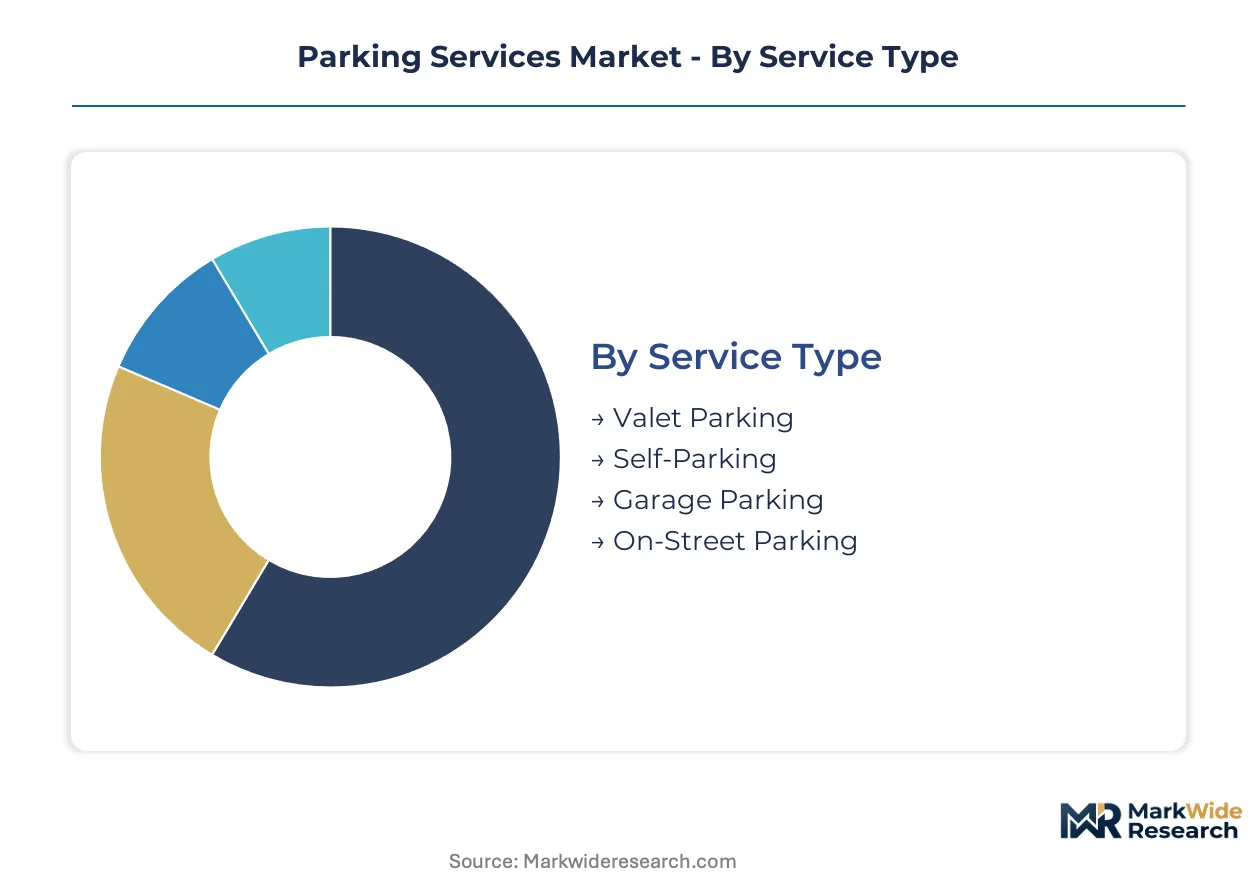
Parking services fragment across operational models, user contexts, and technology stacks that determine capital intensity and margin structure. Each segmentation axis reveals distinct competitive dynamics and vendor specialization patterns.
Service Type:
Supply concentration clusters around high-touch versus automated operational models, with labor intensity and real estate positioning driving vendor selection.
- Valet Parking:Labor-intensive service requiring trained attendants for vehicle retrieval and staging. Demand concentrates in Manhattan, Dubai, and Beverly Hills luxury hospitality and premium retail where land scarcity justifies premium pricing and throughput optimization.
- Garage Parking:Structured multi-level facilities with automated gate systems and vertical space utilization. Underground and podium garages in Chicago, London, and Singapore command the deepest margins through density and dynamic yield management during event surges.
- Self-Parking:Unattended surface lots and ramp structures with minimal staffing. Airport satellite lots and suburban retail clusters deploy this model to minimize overhead.
- On-Street Parking:Curb space managed through metered zones and residential permit systems. Municipal contracts in Barcelona, Milan, and Amsterdam favor vendors with integrated enforcement and payment platform capabilities.
Garage Parking absorbs the bulk of installed capacity; Valet Parking is expanding most quickly in premium urban districts.
End User:
Application context determines contract duration, pricing flexibility, and technology integration requirements across buyer categories.
- Commercial Spaces:Mixed-use developments, office towers, and retail centers requiring 24/7 operational continuity. Class A properties in Boston, Sydney, and Toronto mandate real-time occupancy dashboards and tenant experience apps as procurement prerequisites.
- Event Venues:Stadiums, arenas, and convention centers with extreme demand volatility. Surge pricing algorithms and pre-paid reservation platforms dominate RFP requirements for NFL, NBA, and Premier League facilities.
- Government Facilities:Municipal garages, courthouse parking, and administrative buildings with accessibility compliance mandates. ADA retrofit obligations and prevailing wage requirements constrain vendor margins.
- Residential Areas:Condo podiums, apartment complexes, and HOA-managed communities. Subscription-based monthly parking and visitor management systems drive technology adoption in high-density multifamily developments.
Commercial Spaces generate the highest contract values; Event Venues show the steepest expansion trajectory as post-pandemic attendance rebounds.
Technology:
Margin distribution favors software and data layers over hardware components, with interoperability emerging as the primary procurement filter.
- Parking Management Software:Cloud-native platforms integrating access control, revenue reconciliation, and business intelligence. Enterprise buyers in São Paulo, Mexico City, and Jakarta require API-first architectures that unbundle reservation from payment settlement.
- Mobile Payment Solutions:Smartphone-based transaction processing with digital wallet integration. Municipal mandates for cashless operations in California, Texas, and New York accelerate vendor consolidation around platforms with municipal interoperability certification.
- License Plate Recognition:Camera-based vehicle identification for frictionless entry and enforcement. Edge AI deployment in Manhattan, Dubai, and Sydney compresses payment processing from 45 seconds to sub-3-second automated billing.
- IoT Sensors:Ultrasonic, magnetic, and lidar-based occupancy detection for guidance systems. Supply chain concentration in Shenzhen and Seoul exposes operators to 12-16 week lead times during semiconductor allocation cycles.
Parking Management Software captures the dominant share of technology spending; Mobile Payment Solutions are climbing the fastest as municipalities mandate cashless infrastructure.
Payment Model:
Customer type and usage predictability determine pricing structure selection, with subscription models gaining traction among fleet and corporate buyers.
- Dynamic Pricing:Algorithmic rate adjustment based on real-time demand, event schedules, and weather conditions. Chicago, London, and Singapore garage operators deploy 15-minute interval pricing to maximize yield during surge periods.
- Subscription Plans:Monthly or annual fixed-rate access for commuters and residents. Corporate fleet managers in Frankfurt, Milan, and Barcelona negotiate enterprise contracts with guaranteed availability blocks.
- Hourly Rates:Time-based charging with minimum thresholds and daily maximums. Transient parkers in airport and hospital contexts retain price sensitivity to rate transparency.
- Flat Fees:Single-price event parking and early-bird specials. Stadium and arena operators use this model to accelerate ingress and reduce payment friction.
Hourly Rates still dominate transaction volume; Subscription Plans are gaining share fastest among urban professionals aged 25-40.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility operators in the United States consume the majority of sensor hardware and software platforms, while component manufacturing concentrates in East Asian electronics clusters. Demand fragmentation across municipal procurement systems creates regional specialization in compliance and integration capabilities.
United States
EPA emissions guidelines in California, Texas, and New York accelerate deployment of vehicle detection sensors that curb idling search traffic. The Federal Highway Administration shapes demand through curb management ordinances that dictate space allocation requirements. Chicago garage operators deploy 5G-enabled edge computing for 15-minute interval dynamic pricing during event surges.
Germany
The EU Green Deal's Alternative Fuels Infrastructure Regulation mandates EV charging point density targets in parking facilities. The EU AI Act imposes documentation requirements on automated pricing systems used for access control. Frankfurt operators monetize curbside delivery digitization through time-blocked reservation APIs for logistics fleets.
China
Municipal smart city initiatives in Shenzhen and Shanghai drive sensor-based guidance system procurement for congestion reduction. MIIT standards govern IoT device interoperability in connected parking infrastructure. Electronics manufacturing clusters in Shenzhen and Seoul supply lidar and ultrasonic components with 12-16 week lead times.
India
The Ministry of Housing and Urban Affairs' 100 Smart Cities program generates tenders for integrated parking management in Bangalore, Hyderabad, and Pune. BIS certification requirements shape technology vendor selection for municipal contracts. Rapid urbanization in these metros concentrates demand for automated revenue collection and real-time occupancy monitoring.
United Kingdom
Local air quality mandates accelerate adoption of sensor-driven guidance systems that reduce vehicle circling in London and Manchester. The Department for Transport's accessibility standards enforce ADA-equivalent compliance retrofit obligations. Enterprise fleet managers in London negotiate API-first procurement contracts with guaranteed availability blocks.
Parking Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across operational and technology segments. The market structure shows moderate consolidation around national facility management networks and municipal payment platforms. Three archetypes dominate: multi-service facility operators, mobile payment integrators, and sensor-software technology vendors. Competitive moves center on municipal contract consolidation and API-first platform partnerships that unbundle reservation from settlement.
Within the diversified facility management tier, SP Plus Corporation and ABM Industries occupy positions anchored by national real estate footprints. LAZ Parking exemplifies the specialized venue operator archetype through its concentration in high-throughput locations. ParkMobile LLC represents the mobile payment integration vector that controls digital transaction flows across fragmented municipal networks.
| Leading Market Players |
|---|
| LAZ Parking |
| SP Plus Corporation |
| ABM Industries |
| Propark Mobility |
| ParkMobile LLC |
| SpotHero Inc |
| Passport Labs Inc |
| FlashParking Inc |
| Impark |
| Others |
Value Network & Pricing Analysis
EPA emissions guidelines in California and New York gate qualified supply for sensor-based guidance systems while simultaneously anchoring premium-tier pricing access for vendors with certified interoperability. Municipal procurement mandates for real-time data sharing create a bifurcated market where certified platforms command sustained rate premiums over uncertified competitors.
Pricing Analysis
Margin tightening in automated facility tiers reflects semiconductor allocation volatility and extended hardware lead times from East Asian manufacturing clusters. Pricing stratifies across premium certified, standard compliant, and economy legacy tiers, with differentiation driven by municipal interoperability certification and edge-AI processing capability. Cost-down pressure on self-parking surface lots accelerates because logistics fleet buyers consolidate procurement around API-first platforms with guaranteed availability blocks. Commercial property managers in Class A developments show lowest price sensitivity due to tenant experience mandates, while airport satellite operators remain most sensitive to rate transparency.
Supply Chain Analysis
Engineering talent scarcity in Shenzhen and Seoul constrains lidar and ultrasonic sensor module production capacity for parking guidance systems. Component manufacturing draws from China, South Korea, and Taiwan, with raw material dependencies spanning semiconductor-grade silicon, rare earth magnets, and precision optical glass. Single-source vulnerability concentrates in edge-AI chip fabrication, where foundry allocation cycles create procurement bottlenecks. Distribution runs through municipal contractor networks and national facility management integrators who bundle hardware with long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as interoperability mandates and compliance retrofit costs force undercapitalized municipal contractors toward exit. Procurement compression around API-first platforms accelerates this structural thinning.
For Market Incumbents: Anticipate sensor hardware commoditization by deepening software layer control through parking management platform acquisitions. Municipal data-sharing mandates threaten operators lacking cloud-native architecture; vertical integration into edge-AI development secures pricing power during semiconductor allocation cycles. Defensive consolidation of regional facility networks in Chicago, London, and Singapore preserves yield management advantages during event surge periods. For New Entrants and Emerging Players: Capture white-space in India's smart city mission tenders where BIS certification requirements have slowed established vendor penetration. Bangalore, Hyderabad, and Pune municipal corporations seek integrated parking management under Ministry of Housing and Urban Affairs programs with limited incumbent lock-in. Fleet-facing reservation APIs for logistics hubs in Frankfurt, Milan, and Barcelona offer the most penetrable entry vector through unbundled procurement models. For Investors and Strategic Acquirers: EU AI Act enforcement waves in France, Germany, and Netherlands are the leading indicator that compliance infrastructure scarcity will determine scalable platform viability. Mid-sized municipal contractors lacking audit trail capabilities face procurement exclusion, creating distressed acquisition targets with embedded customer relationships. The signal to watch is Department of Justice accessibility enforcement settlement frequency, which accelerates retrofit cost burdens and forced divestitures.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Unbundles reservation from payment settlement for fleet procurement consolidation in São Paulo and Jakarta. |
| Edge-AI Sensor Deployment | Compresses payment processing latency for Manhattan and Dubai garage operators eliminating attendant costs. |
| Municipal Contract Consolidation | Captures smart city infrastructure mandates across California, Texas, and New York regulatory clusters. |
| EV Charging Infrastructure Bundling | Combines parking monetization with energy retail margins under EU Green Deal density targets. |
| Curbside Delivery Digitization | Monetizes time-blocked loading zone access through logistics fleet management system integration. |
Research Methodology
Multi-period observation of municipal procurement patterns, sensor hardware deployment cycles, and dynamic pricing algorithm adoption anchored the trend analysis, supplemented by interviews with facility operations directors, municipal transportation authority procurement leads, parking management software engineers, and commercial property asset managers. Secondary validation drew from Federal Highway Administration curb management ordinances, EPA emissions guideline enforcement records, EU AI Act regulatory filings, and smart city tender databases from India's Ministry of Housing and Urban Affairs. Bottom-up facility operator revenue modeling triangulated against top-down market sizing across service type, end user, and technology segmentation dimensions.
Segment-weighting approaches distributed value projections across valet parking, garage parking, self-parking, and on-street operational models, with additional weighting for commercial spaces, event venues, government facilities, and residential area end-user contexts. CAGRs were derived through driver elasticity modeling against EPA regulatory enforcement intensity, 5G infrastructure deployment timelines, and e-commerce logistics hub formation patterns across the analysis window. Parking management software and mobile payment solution technology segments received distinct growth coefficients reflecting municipal cashless transaction mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor allocation cycle duration, ADA compliance enforcement wave intensity, and shared mobility substitution rates among urban professionals. Forecasts reflect documented assumptions regarding municipal procurement standardization timelines and interoperability certification adoption curves. A small set of triggers warrants ongoing watch: EU AI Act audit requirement implementation, India's BIS certification pathway clarity, and logistics fleet API procurement consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Register Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Global Car Wash Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Automatic Tire Changer Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Europe Car Wash Market
Automotive Services
GCC Car Wash Market
Automotive Services
North America Car Wash Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Motorsports Market