
 Unmanned Marine Vehicles Market | 2026-2036
Unmanned Marine Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Marine Vehicles Market Intelligence
Autonomous navigation stacks is rewriting how unmanned marine vehicles execute missions without human-in-the-loop intervention. Kongsberg Gruppen leverages decades of sonar integration to dominate subsea mapping contracts. BAE Systems anchors its position through classified defense programs in the UK and Australia. Teledyne Technologies Incorporated sustains competitive pressure via its sensor-agnostic platform architecture.
Unmanned marine vehicles are self-propelled craft operating on or below the water surface, typically measuring 1-15 meters in length and rated for depths from 10 to 6,000 meters depending on pressure hull construction, designed for survey, inspection, or intervention tasks without onboard human operators. Autonomous underwater vehicles now lead procurement volumes in offshore energy inspection, while surface vehicles capture expanding share in persistent maritime domain awareness missions. Propulsion technologies represent the fastest-evolving segment, with hydrogen fuel cells and buoyancy-driven gliders displacing conventional battery-electric architectures in endurance-critical applications.
The US Navy's Unmanned Maritime Autonomy Architecture and the UK's Maritime Autonomy Framework both mandate interoperable command protocols, compressing development timelines for vendors seeking multi-national certification. ISO 13628-8 subsea production system standards and NATO STANAG 4817 unmanned underwater vehicle interoperability guidelines further constrain product design while opening access to pooled procurement budgets. Stakeholders must monitor how emerging seabed mining regulations and exclusive economic zone enforcement protocols reshape mission requirements before committing to next-generation platform investments.
Market Dynamics
Propulsion architecture decisions now dominate platform economics as hydrogen fuel cells and buoyancy-driven gliders compress mission costs for endurance-critical applications, forcing legacy battery-electric designs into shorter-range niches.
Growth Catalysts
- NATO STANAG 4817 interoperability mandate:Standardized command protocols unlock pooled procurement budgets across member navies, accelerating multi-national certification timelines for compliant vendors.
- Seabed mining regulatory frameworks:Emerging exclusive economic zone enforcement protocols in the Pacific and Atlantic create sustained demand for autonomous survey and intervention platforms.
- Lithium-sulfur energy density advances:Next-generation battery chemistry extends submerged mission duration beyond 90 days for deep-water inspection tasks.
Market Restraints
- Pressure hull raw material concentration:Titanium alloy supply chains cluster around Russian and Chinese smelters, exposing Western manufacturers to export control volatility.
- Autonomous navigation liability frameworks:Absence of unified maritime insurance standards for unmanned collisions creates coverage gaps that delay commercial adoption.
- Acoustic sensor substitution risk:Satellite-based synthetic aperture radar increasingly captures surface vessel tracking data at lower unit costs than sonar-equipped USVs.
Strategic Opportunities
- UK Maritime Autonomy Framework compliance services:Vendors certifying to UK-specific command protocols gain preferential access to Royal Navy and Australian Defence Force programs.
- Offshore wind farm inspection automation:Unmanned surface vehicles with integrated blade-crawler payloads address turbine maintenance gaps in the North Sea and Baltic markets.
- Cross-domain sensor fusion:Convergence of synthetic aperture sonar with machine-vision systems enables real-time seabed classification without surface relay.
Industry Challenges
- Maritime autonomy software certification:ISO 13628-8 subsea production system standards lack specific algorithm-validation protocols, forcing vendors into bilateral negotiations with each end-user.
- Underwater communications engineering scarcity:Acoustic modem and optical tether specialists command premium compensation that strains mid-tier platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Marine Vehicles Market |
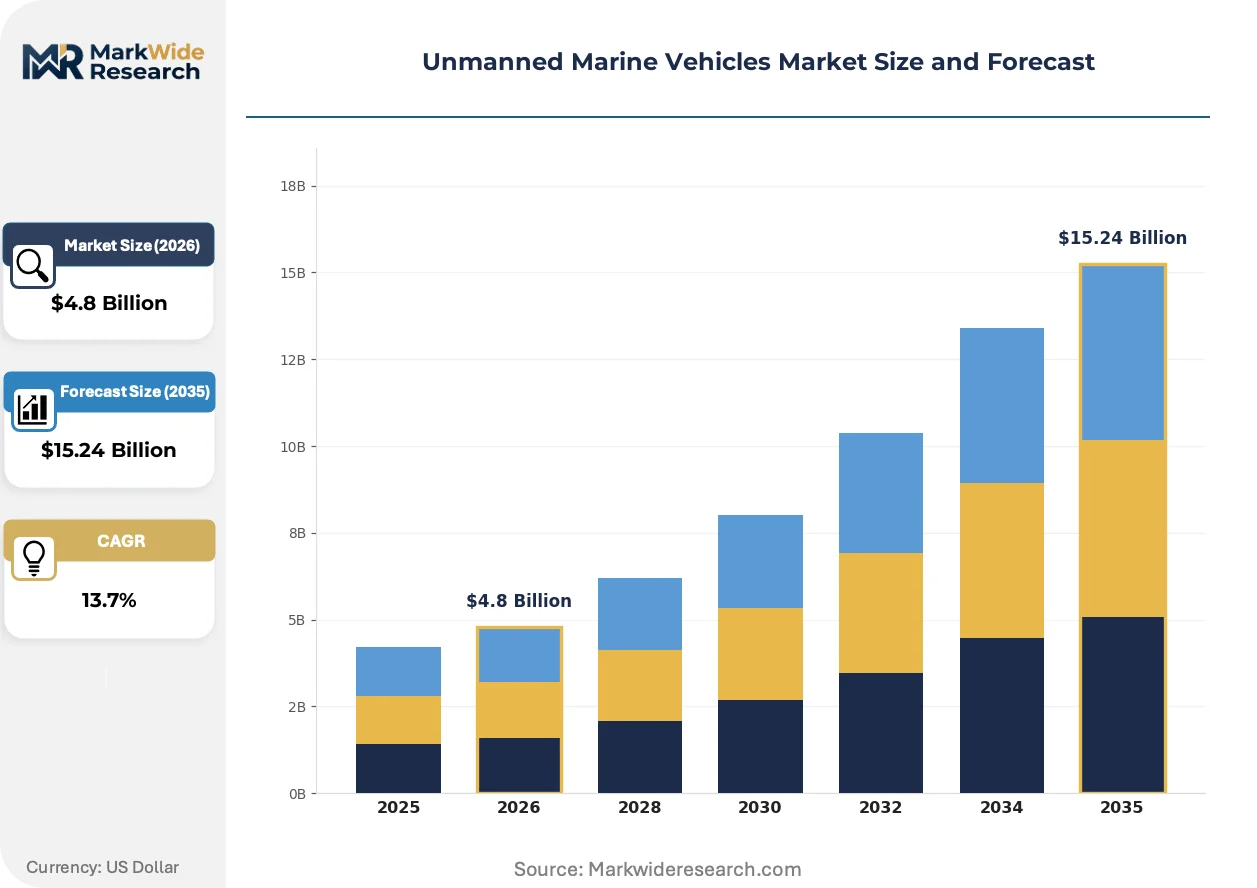
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Autonomous Underwater Vehicles, Surface Vehicles, Remotely Operated Vehicles, Hybrid Vehicles Application: Military, Commercial, Environmental Monitoring, Research Technology: Navigation Systems, Communication Systems, Propulsion Technologies, Sensors End User: Government Agencies, Research Institutions, Oil & Gas Companies, Fisheries |
| Companies Covered | L3Harris Technologies, Inc., Kongsberg Gruppen, BAE Systems, Teledyne Technologies Incorporated, Lockheed Martin Corporation, The Boeing Company, Thales Group, Saab AB, General Dynamics Mission Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Marine Vehicles Market Strategic Shifts & Innovations
Autonomous marine platforms are bifurcating into two evolutionary tracks: ultra-endurance systems sacrificing speed for persistence, and high-mobility architectures optimized for rapid task-switching in contested environments.
Hydrogen fuel cell propulsion is migrating from experimental demonstrators to operational deployments in the offshore energy sector. Major inspection contractors in the North Sea now specify fuel-cell endurance above 30 days for pipeline survey contracts. This technology is compressing the total cost of ownership for long-duration missions while relegating conventional lithium-ion systems to harbor-security and rapid-response roles.
The EU AI Act's risk-classification framework for autonomous decision systems is forcing marine autonomy vendors to document algorithmic transparency in navigation stacks. Industrial consequence includes mandatory human-in-the-loop provisions for vessels operating in commercial shipping lanes. Surface vehicle segments serving port security and coastal patrol are most affected, with several consortia now pooling resources for shared conformity assessment procedures.
Asset-light service contracting is displacing capital-heavy platform ownership among offshore energy operators. Inspection-as-a-service providers now retain fleet ownership and charge per-kilometer surveyed, transferring obsolescence risk from oil majors to specialized unmanned vehicle operators. This restructuring is most visible in the US Gulf of Mexico and Norwegian continental shelf, where integrated energy firms have shed in-house subsea robotics capabilities.
Unmanned Marine Vehicles Market Segmentation
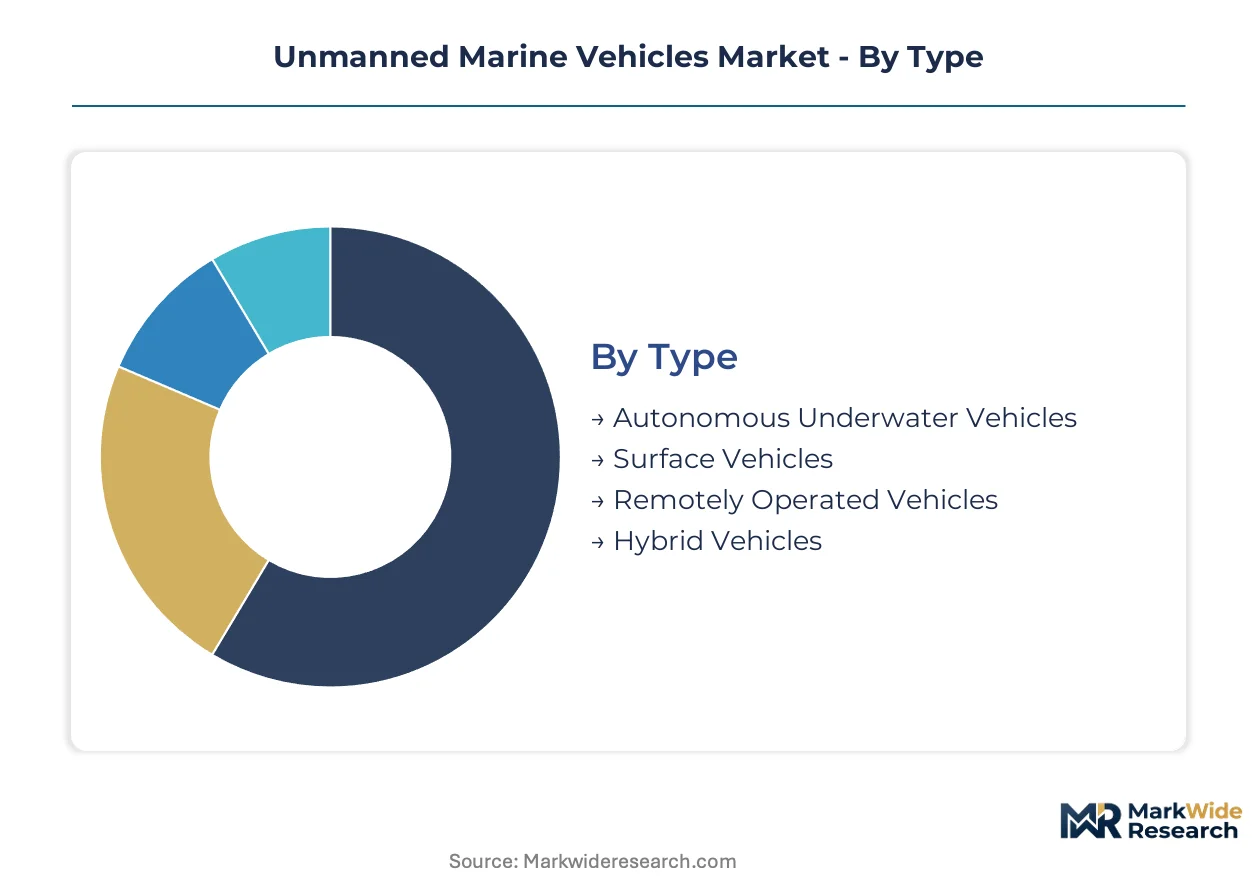
Segmentation in unmanned marine vehicles reveals how mission profiles dictate platform specifications. Procurement patterns diverge sharply between defense programs requiring hardened autonomy stacks and commercial operators prioritizing sensor payload flexibility.
Type:
After-sales intensity varies dramatically across vehicle architectures, with submersible platforms demanding specialized pressure-hull recertification and surface craft requiring more routine hull maintenance.
- Autonomous Underwater Vehicles:Self-propelled submersibles rated for depths from 200 to 6,000 meters depending on pressure vessel construction. Demand concentrates in offshore energy corridors around Norway and the US Gulf of Mexico, driven by pipeline inspection mandates that require extended submerged endurance beyond 30 days.
- Surface Vehicles:Wave- or motor-propelled craft operating at the air-sea interface with persistent solar or diesel-electric power. US Navy Maritime Autonomy Architecture procurement in Virginia and California anchors volume, with coastal domain awareness missions consuming multi-unit deployments for harbor security.
- Remotely Operated Vehicles:Tethered platforms dependent on surface vessel support for power and command links.
- Hybrid Vehicles:Architectures switching between autonomous and tethered modes for mission flexibility.
By volume, Surface Vehicles lead. By growth pace, Autonomous Underwater Vehicles is climbing the fastest.
Application:
Cost tier separation distinguishes defense-grade systems with hardened encryption from commercial platforms competing on survey economics.
- Military:Classified programs requiring STANAG 4817 interoperability and hardened acoustic signatures. NATO pooled procurement budgets accelerate multi-national certification timelines for compliant vendors supplying mine countermeasures and intelligence-gathering missions.
- Commercial:Offshore energy inspection and aquaculture monitoring where per-kilometer pricing dominates procurement decisions. Norwegian and UK North Sea operators now favor inspection-as-a-service contracting over capital ownership.
- Environmental Monitoring:Long-duration oceanographic data collection for climate research networks.
- Research:Academic and institutional deployments with customized sensor payloads.
By volume, Commercial leads. By growth pace, Military is expanding most quickly.
Technology:
Supply concentration in acoustic modem engineering creates bottlenecks for Communication Systems while Navigation Systems commoditize faster.
- Navigation Systems:Inertial measurement units fused with Doppler velocity logs and acoustic positioning. EU AI Act risk-classification mandates now require algorithmic transparency documentation for autonomous decision stacks operating in commercial shipping lanes.
- Propulsion Technologies:Hydrogen fuel cells and buoyancy-driven gliders displacing lithium-ion architectures in endurance-critical deployments. North Sea inspection contractors now specify fuel-cell endurance above 30 days for pipeline survey contracts.
- Communication Systems:Acoustic modems, optical tethers, and satellite links for command-and-control.
- Sensors:Synthetic aperture sonar, multibeam echosounders, and machine-vision systems for seabed classification.
By volume, Sensors leads. By growth pace, Propulsion Technologies shows the steepest expansion trajectory.
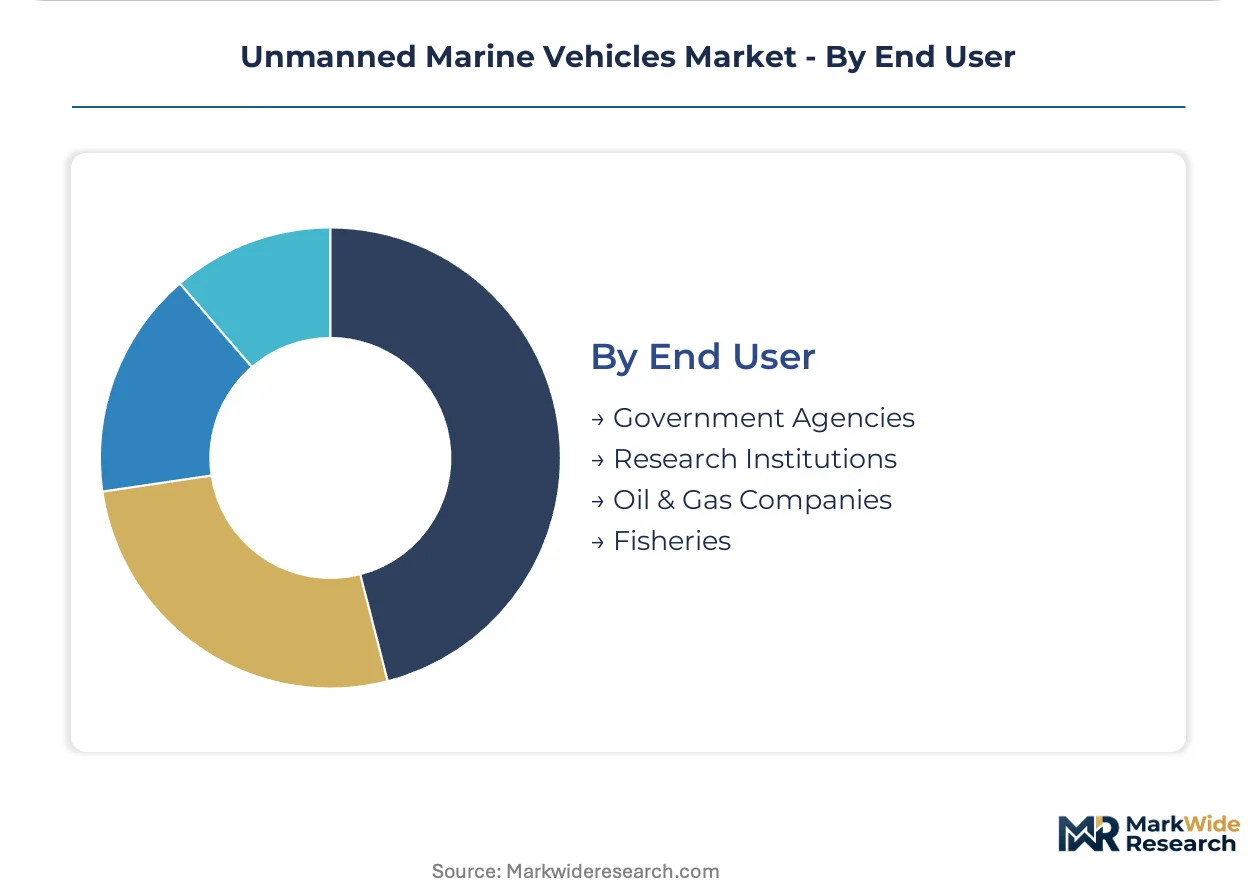
End User:
Customer type determines procurement rhythm, with Government Agencies running multi-year programs and Oil & Gas Companies shifting toward operational expenditure models.
- Government Agencies:Naval and maritime enforcement programs with classified requirements and interoperability mandates. UK Maritime Autonomy Framework compliance unlocks preferential access to Royal Navy and Australian Defence Force procurement channels.
- Oil & Gas Companies:Integrated energy firms shedding in-house subsea robotics capabilities in favor of asset-light service contracting. US Gulf of Mexico and Norwegian continental shelf operators now charge inspection tasks per-kilometer surveyed.
- Research Institutions:Academic and government laboratories with customized payload requirements.
- Fisheries:Aquaculture and wild-stock monitoring applications with cost-constrained platform specifications.
By volume, Government Agencies leads. By growth pace, Oil & Gas Companies is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian subsea equipment flows into UK North Sea energy corridors, while US defense contractors supply NATO Pacific fleets through technology licensing arrangements.
United States
Virginia and California defense technology corridors anchor naval procurement for autonomous underwater systems. The US Navy's Unmanned Maritime Autonomy Architecture mandates interoperable command protocols that compress vendor certification timelines. Kongsberg Gruppen maintains sonar integration facilities near Washington DC to service classified mine countermeasures programs.
Norway
Offshore energy inspection mandates drive sustained demand for autonomous underwater vehicles rated beyond 6,000 meters depth. The country's petroleum regulator enforces pipeline survey requirements that specify 30-day submerged endurance minimums. Stavanger and Bergen host concentrated clusters of inspection-as-a-service providers charging per-kilometer surveyed.
United Kingdom
Royal Navy and Australian Defence Force procurement channels favor vendors certifying to UK Maritime Autonomy Framework protocols. The framework mandates algorithmic transparency documentation for autonomous decision stacks. Plymouth and Portsmouth submarine bases coordinate joint development programs with BAE Systems for mine-hunting architectures.
Germany
Industrial autonomy engineering concentrates in northern shipbuilding regions supplying Baltic and North Sea patrol requirements. The country's federal maritime authority participates in NATO STANAG 4817 standardization working groups. Kiel and Hamburg harbor districts test hydrogen fuel cell propulsion for persistent maritime domain awareness missions.
Australia
Indo-Pacific submarine detection priorities accelerate sovereign unmanned underwater vehicle manufacturing partnerships. The Defence Department's investment mandate requires domestic content thresholds for autonomous maritime platforms. Perth and Adelaide defense corridors integrate US and UK technology transfers into localized production.
Unmanned Marine Vehicles Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent certification pathways. Defense procurement concentrates around vendors with NATO interoperability credentials, while commercial energy operators prioritize per-kilometer survey economics over platform ownership. Three archetypes dominate: integrated defense conglomerates with classified program access, sensor-agnostic platform architects, and inspection-service operators retaining fleet ownership. Competitive moves center on strategic partnerships for multi-national certification and geographic expansion into Pacific seabed mining corridors.
Among US-based defense conglomerates, L3Harris Technologies, Inc. and Lockheed Martin Corporation exemplify the classified-program archetype with established Navy supply relationships. Kongsberg Gruppen represents the European specialist tier leveraging decades of sonar integration heritage. Teledyne Technologies Incorporated occupies a position bridging defense and commercial demand through sensor-agnostic platform architectures that accommodate diverse payload configurations.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Kongsberg Gruppen |
| BAE Systems |
| Teledyne Technologies Incorporated |
| Lockheed Martin Corporation |
| The Boeing Company |
| Thales Group |
| Saab AB |
| General Dynamics Mission Systems Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese lithium-sulfur cell production is compressing battery pack pricing for AUV endurance extensions, forcing Western platform integrators to choose between cost arbitrage and supply security in procurement postures.
Pricing Analysis
Current-generation hydrogen fuel cell systems command substantial premiums against prior-generation lithium-ion architectures, while next-generation solid-state battery prototypes remain pre-commercial. Three-tier pricing structure across NATO-certified defense-grade, commercial inspection-grade, and research-grade platforms separates procurement channels. Price differentiation hinges on STANAG 4817 interoperability certification and pressure-hull depth rating. Cost compression in commercial surface vehicle segments is intensifying because inspection-as-a-service operators are consolidating fleet purchasing power. Oil and gas companies exhibit highest price sensitivity due to operational expenditure conversion, while naval programs demonstrate lowest sensitivity given classified mission requirements.
Supply Chain Analysis
Upstream titanium alloy feedstock draws from Russian and Chinese smelter concentration, with Japanese and US secondary processing adding value. Raw material dependencies span high-grade titanium, lithium-sulfur cathode materials, and acoustic modem ceramic substrates. Single-source vulnerability in Russian titanium sponge exposes Western pressure-hull fabricators to export control disruption. Distribution runs through defense prime contractors for naval programs and inspection-service operators for commercial energy contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among inspection-as-a-service operators consolidating multi-year offshore energy contracts, fragmenting platform OEM pricing leverage across the commercial segment.
For Market Incumbents: Pre-empt hydrogen fuel cell commoditization by locking exclusive supply agreements with emerging solid-state battery developers before next-generation chemistry reaches scale. Anchor defensive positioning through backward integration into titanium alloy recycling to offset Russian feedstock exposure. Certification investment in UK Maritime Autonomy Framework compliance unlocks Royal Navy and Australian Defence Force procurement preference against NATO rivals. For New Entrants and Emerging Players: Establish a beachhead in Pacific seabed mining survey services before regulatory frameworks mature and incumbent operators deploy dedicated fleets. The most penetrable segment is environmental monitoring glider services for academic oceanographic networks, where price competition remains fragmented and technical specifications tolerate lower depth ratings. A direct go-to-market angle through per-kilometer contracting models mimics successful inspection-as-a-service structures without capital-intensive fleet ownership. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among inspection-as-a-service operators retaining fleet ownership and charging subscription-style per-kilometer fees. Long-term viability over the projection horizon favors platform-agnostic sensor integrators over hardware-specialist OEMs vulnerable to propulsion technology obsolescence. The acquisition target archetype is mid-tier autonomy software vendors with UK Maritime Autonomy Framework certification and existing Royal Navy relationships. Watch for lithium-sulfur battery cost-parity signals with conventional lithium-ion as the inflection indicator for AUV fleet refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| UK Maritime Autonomy Framework Certification | Unlocks preferential Royal Navy and Australian Defence Force procurement channels against non-compliant rivals. |
| Hydrogen Fuel Cell Supply Agreement | Secures 30-day endurance specifications for North Sea pipeline inspection contracts ahead of competitor deployment. |
| Inspection-as-a-Service Platform Launch | Transfers obsolescence risk from oil majors to operators while capturing recurring per-kilometer revenue streams. |
| Acoustic Modem Engineering Acquisition | Addresses supply bottleneck in underwater communications where specialist talent commands premium compensation. |
| Pacific Seabed Mining Survey Partnership | Positions for emerging exclusive economic zone enforcement demand before regulatory frameworks solidify. |
Research Approach
Initial hypotheses were tested against primary input from naval program managers, offshore energy inspection directors, autonomy software engineers, and acoustic systems procurement leads, then refined through secondary validation against NATO STANAG documentation, national maritime authority procurement databases, SEC filings from defense conglomerates, and offshore energy regulatory survey mandates. Bottom-up platform deployment counts were triangulated against top-down addressable market sizing across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation modeled across vehicle type, application, propulsion technology, and end-user procurement rhythm. CAGRs were derived from deployment trajectory analysis and replacement cycle timing. Industry-specific forecast inputs included NATO pooled procurement budget allocations and offshore wind farm installation pipelines in the North Sea and Baltic markets.
Stress conditions across titanium alloy export restriction severity, lithium-sulfur cell cost reduction velocity, and seabed mining regulatory timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against national defense budget authorization documents and offshore energy operator capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
GCC ROV Market
Marine
Marine Turbocharger Market
Marine
Marine Navigation System Market
Marine
Marine Electronics Market
Marine
Global Discount-Marine Trenchers Market
Marine
Marine Chronometers Market
Marine
Marine Auxiliary Engine Market
Marine
Electric Outboard Engines Market
Marine
North Sea Offshore Support Vessels Market
Marine
Marine VFD Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
India Boat Davits Market
Marine
Hydrofoil Market
Marine
Boat Trolling Motor Market
Marine
Europe ROV Market
Marine
Passenger Vessel Propeller Market