
 Brushless Car Wash Machine Market | 2026-2036
Brushless Car Wash Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Brushless Car Wash Machine Market Outlook
Skilled technician availability for PLC programming and high-pressure pump maintenance is reorganizing how regional distributors allocate service resources across North America. WashTec AG leverages its German engineering base to sustain premium positioning in conveyorized tunnel systems. Coleman Hanna Carwash Systems anchors its competitiveness through vertically integrated manufacturing of stainless-steel arch assemblies in the United States. Sonny's Enterprises, LLC dominates the replacement parts aftermarket through proprietary channel control over its DuraShine component catalog.
A brushless car wash machine employs high-pressure water jets, chemical foam applicators, and air-dry systems to clean vehicle exteriors without physical contact brushes, typically operating at pressures between 1,200 and 2,500 PSI with programmable oscillating nozzles. These systems serve commercial fleet operators, retail tunnel locations, and residential property managers seeking scratch-free finish preservation and reduced water consumption per wash cycle. Conveyorized installations generate the deepest margin pools due to throughput volume and recurring chemical supply contracts, while in-bay automatic units lead unit shipments across urban sites with space constraints. Smart control technology represents the fastest-expanding segment as operators integrate IoT-enabled chemical monitoring and predictive maintenance alerts to minimize downtime.
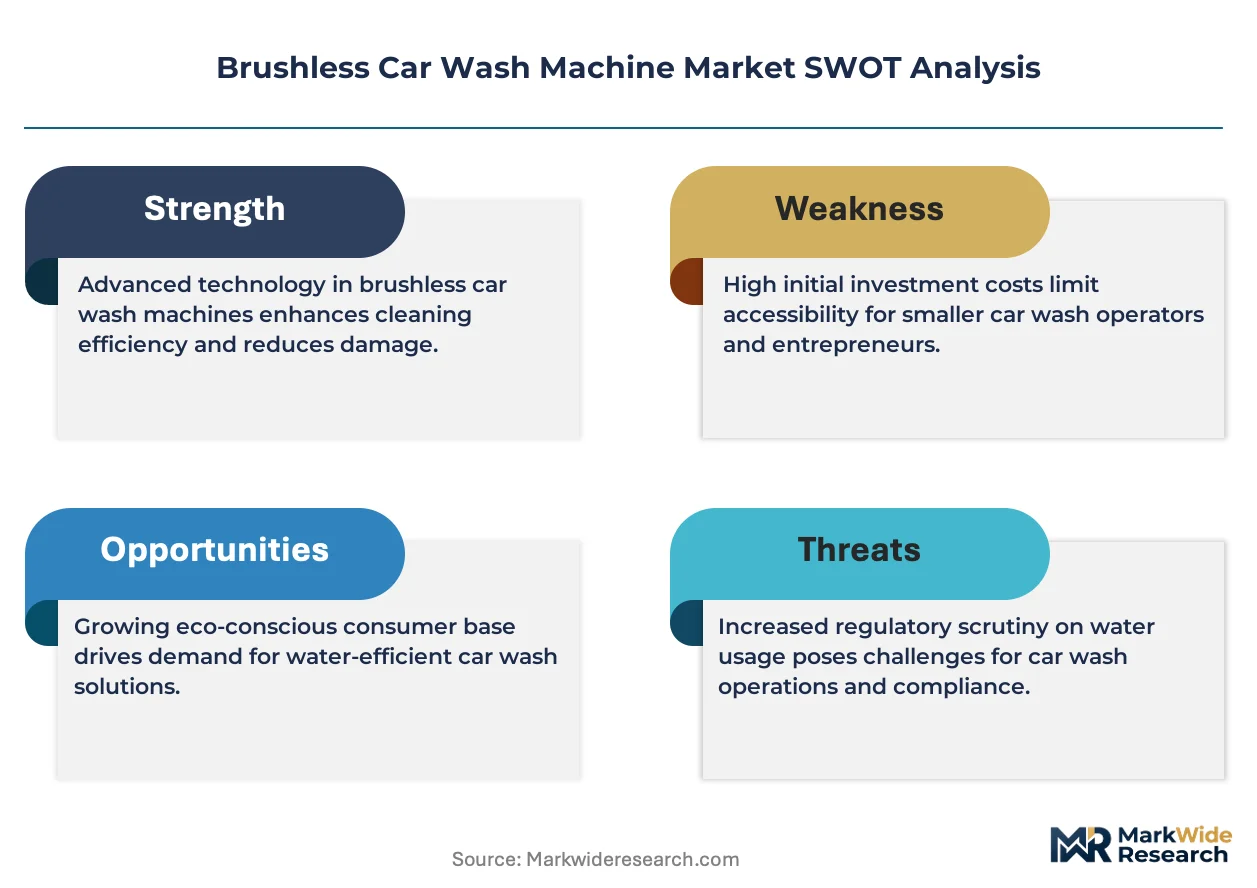
EPA effluent guidelines and OSHA worker safety standards govern chemical handling protocols and wastewater discharge limits for commercial wash operations in the United States, while ISO 14001 certification increasingly filters procurement eligibility for municipal fleet contracts. State-level water boards in California, Arizona, and Texas impose supplemental reclaim-ratio requirements that directly shape equipment specification sheets and system pricing. Stakeholders must monitor evolving regional water scarcity designations and corresponding rebate program qualification criteria to align capital deployment with subsidy-accessible upgrade cycles.
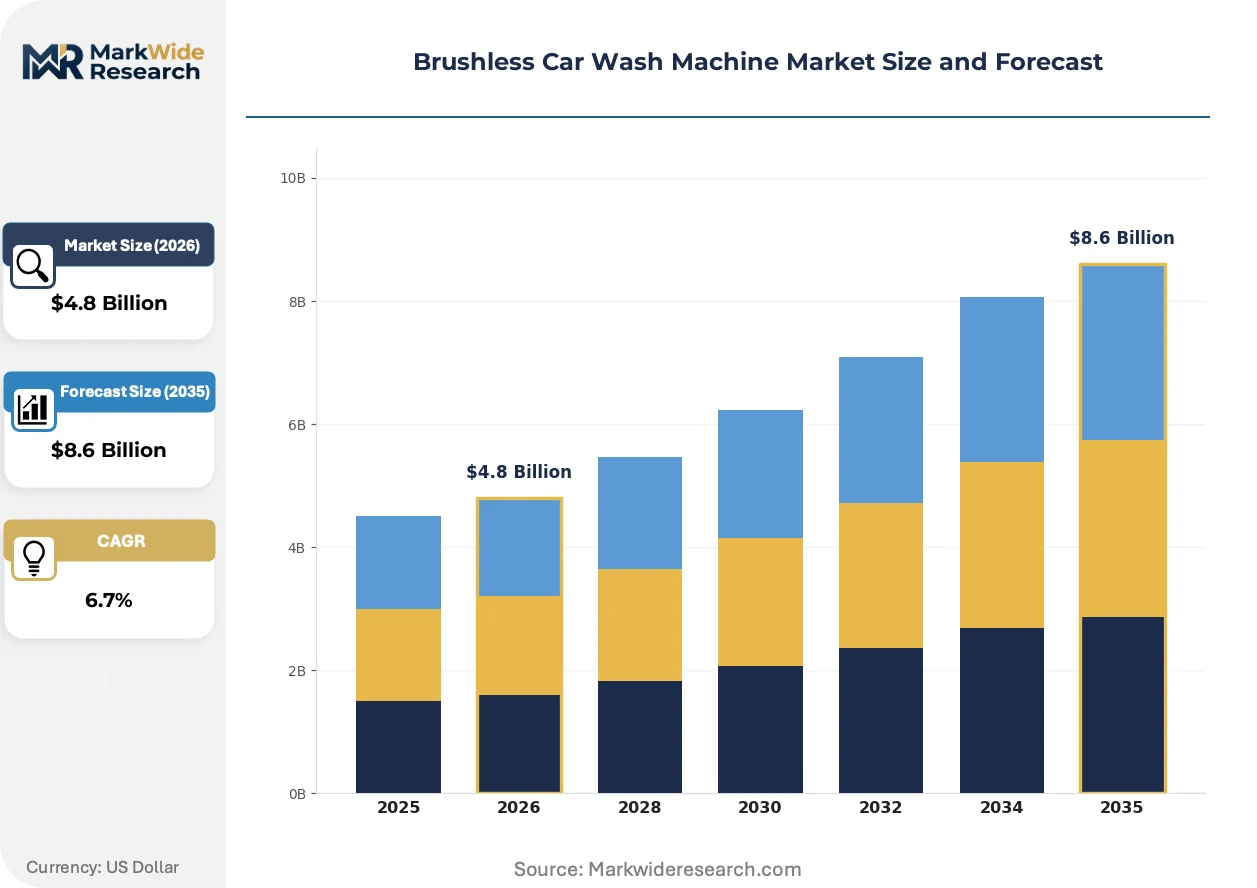
Market Dynamics
Water reclamation mandates from the EPA and state-level environmental agencies in the United States are compelling equipment upgrades toward closed-loop systems, while fleet operators expand automated wash bay installations to reduce labor dependency and vehicle turnaround times.
Growth Catalysts
- EPA effluent guidelines:The agency's wastewater discharge limits for commercial wash operations are accelerating equipment replacement cycles toward closed-loop reclaim systems in the United States.
- Fleet service automation:Commercial fleet operators are expanding automated wash bay installations to compress vehicle turnaround times and reduce labor dependency in high-density logistics corridors.
- Smart control technology:IoT-enabled chemical monitoring and predictive maintenance alerts are minimizing downtime and attracting upgrade investment from tunnel operators.
Market Restraints
- Skilled technician scarcity:Regional distributors face constrained availability of PLC programmers and high-pressure pump maintenance specialists across North America.
- Stainless steel input volatility:Arch assembly fabrication depends on stainless steel pricing, exposing vertically integrated manufacturers to commodity swings.
- Water board reclaim-ratio mandates:California, Arizona, and Texas impose supplemental requirements that inflate system specification costs and extend sales cycles.
Strategic Opportunities
- American Southwest drought response:Persistent water scarcity in California, Arizona, and Nevada is creating concentrated procurement of low-water brushless configurations.
- Municipal fleet ISO 14001 procurement:Certification eligibility filters are opening specification access for reclaim-system suppliers bidding on government contracts.
- Residential property manager segment:Scratch-free finish preservation requirements are penetrating multi-unit housing complexes and commercial parking structures.
Industry Challenges
- PLC programming talent gap:Regional distributors must reorganize service resource allocation due to scarcity of technicians capable of oscillating nozzle calibration and control system troubleshooting.
- Integration complexity with legacy wash infrastructure:Retrofit installations face mechanical incompatibility with existing conveyor foundations and chemical delivery architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brushless Car Wash Machine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Bay Automatic, Conveyorized, Self-Service, Mobile Technology: High-Pressure Water, Foam Wash, Eco-Friendly, Smart Control End User: Commercial, Residential, Fleet Services, Detail Shops Distribution Channel: Direct Sales, Online Retail, Distributors, Franchise |
| Companies Covered | Sonny's Enterprises, LLC, Coleman Hanna Carwash Systems, WashTec AG, Belanger, Inc., MacNeil Wash Systems, Ryko Solutions, Inc., Istobal S.A., Motor City Wash Works, PDQ Manufacturing, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brushless Car Wash Machine Market Strategic Shifts
Programmable oscillating nozzle arrays and IoT-enabled chemical monitoring are actively reshaping equipment specifications, while regulatory pressure on water consumption accelerates reclaim technology adoption across commercial installations.
High-pressure water jet systems operating between 1,200 and 2,500 PSI with programmable oscillating nozzles are displacing legacy brush-based tunnel configurations. Fleet operators and retail tunnel locations are adopting these systems at accelerated pace to eliminate paint damage liability. This displacement is compressing the installed base of contact-wash equipment and elevating chemical applicator and air-dry subsystem specifications.
EPA effluent guidelines and OSHA worker safety standards are tightening chemical handling protocols and wastewater discharge limits for commercial wash operations in the United States. These rules are forcing capital allocation toward closed-loop reclaim systems and automated chemical dosing. Conveyorized installations in drought-designated counties face the most acute compliance pressure and are responding with accelerated rebate-program qualification efforts.
Outcome-based service contracts bundling chemical supply, predictive maintenance, and uptime guarantees are displacing traditional equipment-only procurement in the fleet operator segment. Tunnel operators with high throughput volumes are adopting these bundled arrangements to transfer performance risk to OEM service organizations. This shift is most visible in Texas and California logistics corridors where vehicle turnaround economics dominate capital planning.
Brushless Car Wash Machine Market Segmentation
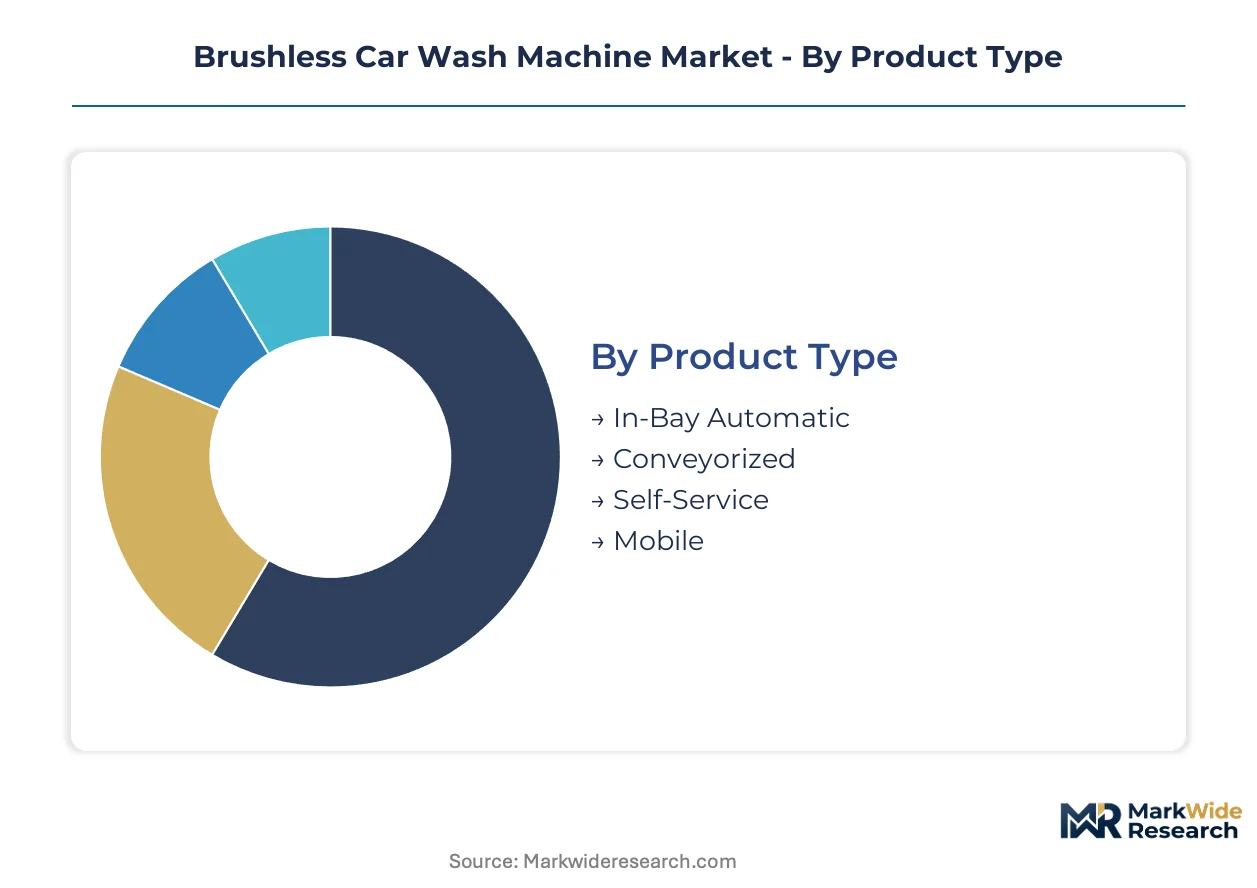
Equipment specification varies sharply across installation environments and operator scale. Procurement patterns in the brushless car wash machine market split between high-volume fleet infrastructure and constrained urban footprints, with technology selection directly tied to water reclamation mandates and labor reduction targets.
Product Type:
Domestic manufacturing concentrates on conveyorized and in-bay systems for the American Southwest drought corridor, while export demand pulls mobile and self-service configurations toward emerging fleet markets in Mexico and Central America.
- Conveyorized:High-throughput tunnel configurations process vehicles on continuous chains with integrated reclaim systems and chemical dosing arches. Fleet operators in Texas and California logistics corridors specify these for sub-five-minute turnaround economics under EPA effluent pressure.
- In-Bay Automatic:Single-vehicle units with programmable oscillating nozzles occupy compact footprints in urban retail locations and multi-unit housing complexes. Space-constrained sites in Phoenix, Las Vegas, and Los Angeles favor these for permit flexibility and lower capital deployment.
- Self-Service:Coin-operated wand stations with customer-controlled high-pressure guns serve price-sensitive rural markets and small-town operators.
- Mobile:Trailer-mounted or truck-integrated units serve on-site fleet washing and event-based detailing contractors.
Conveyorized installations command the established base. The steepest expansion runs through in-bay automatic configurations.
Technology:
Cost tiering separates premium smart control systems from baseline high-pressure configurations, with mid-tier foam wash and eco-friendly variants capturing municipal fleet contracts sensitive to ISO 14001 certification eligibility.
- Smart Control:IoT-enabled platforms with predictive maintenance alerts, remote chemical monitoring, and PLC-driven nozzle calibration minimize downtime for tunnel operators. Fleet services in drought-designated counties adopt these to secure water board rebate program qualification.
- High-Pressure Water:Baseline systems operating between 1,200 and 2,500 PSI with fixed or oscillating jet arrays dominate replacement cycles for legacy brush-based equipment. Independent operators in secondary markets specify these for scratch-free liability reduction without connectivity premiums.
- Foam Wash:Chemical pre-soak applicators with controlled dwell times enhance soil suspension before high-pressure rinse cycles.
- Eco-Friendly:Biodegradable surfactant compatibility and reduced water volume per cycle serve California and Arizona regulatory environments.
High-pressure water systems anchor current installed capacity. Smart control platforms are climbing the fastest as outcome-based service contracts displace equipment-only procurement.
End User:
Application intensity varies by vehicle throughput and finish preservation requirements, with fleet services and commercial operators driving specification toward reclaim integration while residential and detail shop segments prioritize space efficiency and cosmetic outcomes.
- Fleet Services:Commercial logistics operators, rental car companies, and municipal vehicle pools demand automated wash bays with closed-loop water systems and compressed turnaround protocols. EPA effluent guidelines and OSHA chemical handling standards govern these installations most stringently.
- Commercial:Retail tunnel locations and convenience store operators balance throughput volume against real estate constraints and local water board reclaim-ratio mandates.
- Residential:Property managers of multi-unit housing complexes and commercial parking structures specify compact in-bay units for tenant amenity value and scratch-free finish preservation.
- Detail Shops:High-end automotive service providers combine brushless exterior systems with interior detailing bays for comprehensive vehicle reconditioning.
Fleet services command the established base. The steepest expansion runs through residential property manager procurement.
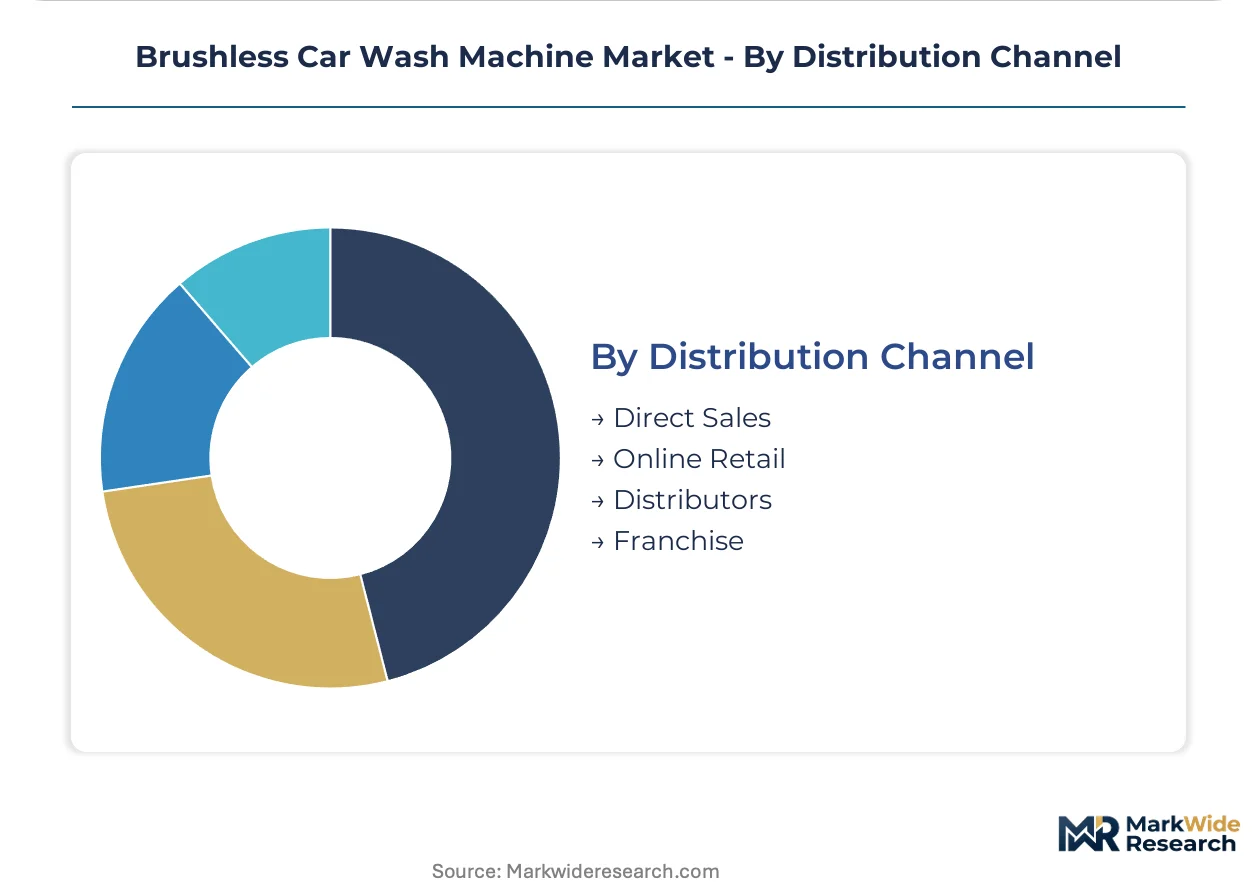
Distribution Channel:
Customer type and order scale dictate channel selection, with direct sales capturing large fleet deployments while distributors and franchise networks serve fragmented independent operators and regional chains.
- Direct Sales:OEM field organizations handle specification, installation, and service bundling for conveyorized tunnel projects and multi-site fleet rollouts. These relationships transfer performance risk through outcome-based contracts with uptime guarantees.
- Distributors:Regional networks with PLC programming and high-pressure pump maintenance capabilities provide geographic coverage for in-bay automatic and self-service installations across dispersed markets.
- Online Retail:E-commerce platforms serve mobile unit purchasers and replacement component buyers with standardized configurations.
- Franchise:Branded wash chain networks specify equipment through centralized procurement with exclusive chemical supply arrangements.
Direct sales command the established base. The steepest expansion runs through distributor networks as skilled technician scarcity forces service resource reorganization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brushless car wash deployment patterns diverge sharply by water stress and fleet density. Arid jurisdictions prioritize closed-loop reclaim systems, while logistics corridors emphasize throughput velocity over water conservation.
United States
Fleet operators in Texas and California logistics corridors drive conveyorized tunnel procurement for sub-five-minute turnaround economics. EPA effluent guidelines and OSHA chemical handling standards govern commercial wash operations most stringently. The American Southwest drought corridor concentrates low-water brushless configuration demand across Phoenix, Las Vegas, and Los Angeles metro areas.
Germany
Engineering-intensive tunnel systems serve premium retail locations and commercial fleet depots across the industrial belt. REACH chemical regulations and CE marking requirements shape equipment specification sheets for cross-border export. WashTec AG anchors conveyorized system production from its Baden-Württemberg engineering base.
China
Domestic manufacturing scales high-pressure pump assemblies and PLC control modules for price-sensitive regional markets. GB standards and MIIT industrial policy guide smart control technology integration in commercial installations. Yangtze River Delta manufacturing clusters supply oscillating nozzle arrays to Southeast Asian export markets.
Japan
Compact in-bay automatic units penetrate urban retail sites with severe space constraints in Tokyo and Osaka metro areas. METI energy efficiency guidelines and JIS standards filter municipal fleet procurement eligibility. Kanto region distributors reorganize service resources around PLC programming technician scarcity.
Canada
Cold-climate adaptations in water reclamation systems address freeze-risk in Alberta and Prairie Provinces fleet operations. Health Canada and PMRA chemical registration requirements govern surfactant formulations for commercial wash discharge. Ontario distributors serve cross-border fleet customers with EPA-aligned equipment specifications.
Brushless Car Wash Machine Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in brushless car wash equipment supply. Conveyorized tunnel manufacturers with captive stainless-steel fabrication capabilities occupy the premium pricing band, while regional distributors with service networks capture fragmented in-bay automatic demand. Two strategic archetypes dominate: vertically integrated arch assembly fabricators and aftermarket parts specialists with proprietary component catalogs. Competitive moves concentrate on geographic service network expansion and smart control technology licensing arrangements.
Among North American fabricators, Coleman Hanna Carwash Systems and Sonny's Enterprises, LLC occupy distinct positioning archetypes. Coleman Hanna exemplifies vertically integrated manufacturing through its stainless-steel arch assembly production in the United States. Sonny's Enterprises anchors the replacement parts aftermarket through proprietary channel control. WashTec AG represents the German engineering-intensive tier sustaining premium positioning in conveyorized tunnel systems for export markets.
| Leading Market Players |
|---|
| Sonny's Enterprises, LLC |
| Coleman Hanna Carwash Systems |
| WashTec AG |
| Belanger, Inc. |
| MacNeil Wash Systems |
| Ryko Solutions, Inc. |
| Istobal S.A. |
| Motor City Wash Works |
| PDQ Manufacturing, Inc. |
| Others |
Value Chain & Pricing Dynamics
Outcome-based service contracts bundling chemical supply with uptime guarantees lock in supply access and price visibility for fleet operators across Texas and California logistics corridors. These multi-year arrangements transfer performance risk to OEM service organizations while insulating buyers from stainless steel commodity swings in arch assembly fabrication.
Pricing Analysis
Long-term offtake contracts dominate conveyorized tunnel procurement, with price differentiation resting on smart control tier certification and reclaim-system integration depth. Premium-mid-economy pricing stratification separates IoT-enabled predictive maintenance platforms from baseline high-pressure configurations. Cost compression in standard-tier equipment is intensifying due to stainless steel input volatility. Fleet services exhibit lowest price sensitivity given throughput economics, while independent rural operators in self-service segments face acute margin pressure.
Supply Chain Analysis
Inventory lead times for PLC control modules and oscillating nozzle arrays have extended as regional distributors reorganize service resources around technician scarcity. Manufacturing concentrates in Germany for premium tunnel engineering, the United States for stainless steel arch fabrication, and China for high-pressure pump assemblies. Raw material dependencies span 316-grade stainless steel, specialized ceramic nozzle inserts, and industrial surfactant formulations. Single-source vulnerability concentrates in German-engineered conveyor chain systems. Distribution runs through direct sales for fleet rollouts and regional distributor networks for fragmented urban sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring chemical supply contracts and predictive maintenance subscriptions expand faster than hardware unit shipments. The shift toward outcome-based procurement transfers performance risk upstream and deepens OEM-customer stickiness.
For Market Incumbents: Shield installed base relationships by embedding IoT-enabled chemical monitoring before smart control platforms commoditize. Deepen backward integration into stainless steel arch fabrication to offset commodity volatility eroding standard-tier margins. Prioritize certification investment for ISO 14001 eligibility in municipal fleet procurement.
For New Entrants and Emerging Players: Differentiate on rapid-deployment in-bay automatic configurations for residential property managers in Phoenix, Las Vegas, and Los Angeles metro areas. Target the residential segment where scratch-free finish requirements penetrate multi-unit housing complexes with minimal incumbent presence. Pursue distributor partnership routes rather than direct sales to leverage existing PLC programming capabilities.
For Investors and Strategic Acquirers: Regional distributor networks with captive service technician pools represent the most defensible acquisition archetype as skilled labor scarcity intensifies. Long-term viability hinges on exposure to recurring revenue streams rather than equipment-only transaction models. Monitor water board reclaim-ratio mandate expansion as the inflection signal for closed-loop system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Control Technology Licensing | IoT-enabled predictive maintenance platforms minimize downtime for tunnel operators under EPA effluent pressure. |
| Backward Integration into Stainless Steel Fabrication | Captive arch assembly production insulates margin from commodity volatility in North American manufacturing. |
| Outcome-Based Service Contract Expansion | Bundled chemical supply and uptime guarantees transfer performance risk from fleet operators to OEMs. |
| ISO 14001 Certification Investment | Environmental management certification opens municipal fleet procurement eligibility in drought-designated jurisdictions. |
| Regional Service Network Densification | PLC programming and pump maintenance capabilities address technician scarcity constraining distributor coverage. |
Study Parameters
Desk research of trade association technical specifications, EPA effluent guideline filings, and state water board regulatory databases preceded structured interviews with fleet operations managers, regional equipment distributors, PLC programming technicians, and municipal procurement officers. Secondary validation drew from customs records, stainless steel commodity pricing indices, and equipment manufacturer technical documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Variance decomposition across product type, technology tier, end-user application intensity, and geographic water stress designation shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory compliance cycle timing. Forecast inputs incorporated drought designation frequency updates and rebate program qualification criteria evolution.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement of effluent guidelines or abrupt shifts in stainless steel tariff structures would require recalibration. Forecasts reflect documented assumptions regarding fleet automation adoption curves and water reclamation technology cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Car Wash Franchise Market
Automotive Services
North America Car Wash Market
Automotive Services
Automotive Subscription Services Market
Automotive Services
Mobility Scooters Market
Automotive Services
Motorsports Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Automotive Register Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Car Washing Service Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Car Vending Machine Market
Automotive Services
Garage and Service Station Service Market