
 Automotive Activated Carbon Canister Market | 2026-2036
Automotive Activated Carbon Canister Market Size, Share, and Industry Trends Forecast 2026-2036
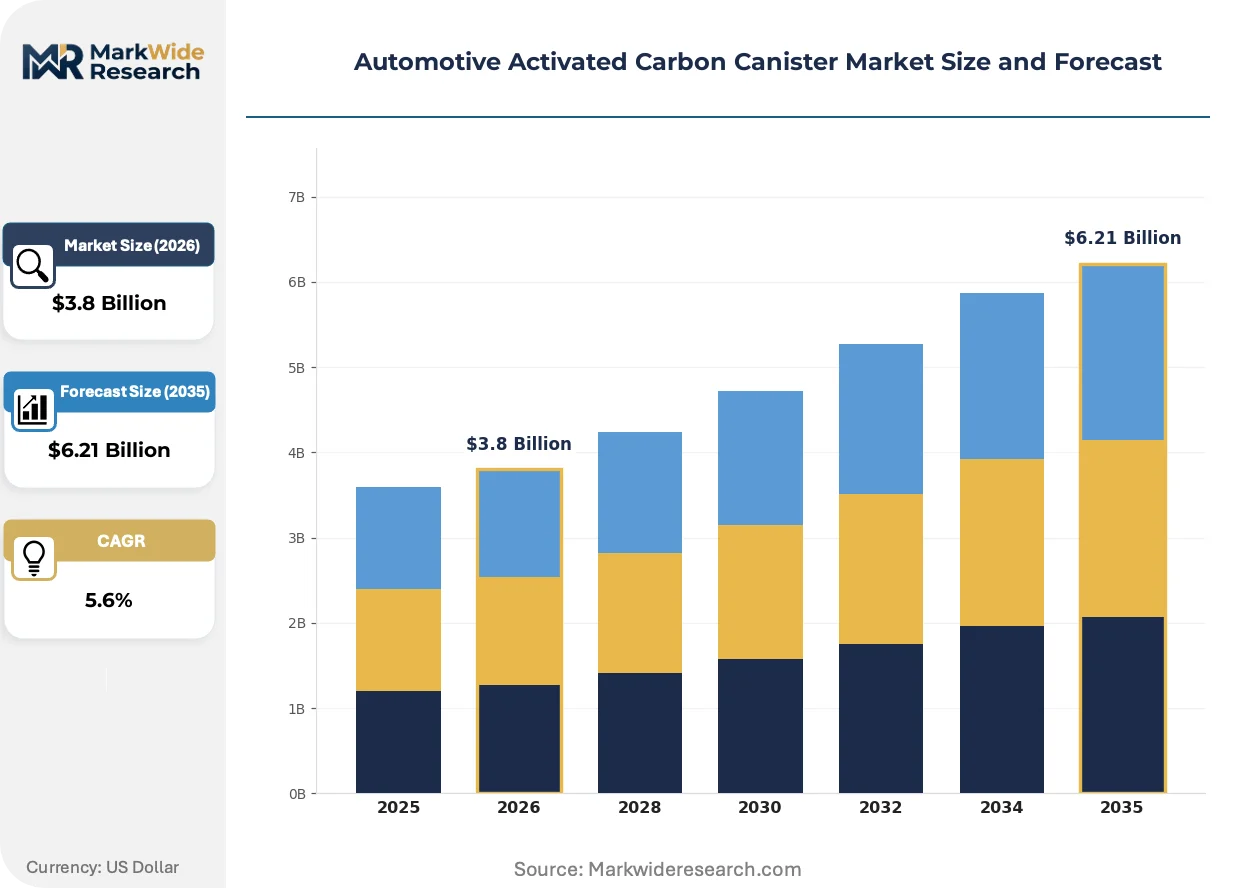
Automotive Activated Carbon Canister Market Outlook
Buyer concentration among vehicle manufacturers is rebalancing as Asian automakers diversify supplier portfolios beyond incumbent European and Japanese vendors. Robert Bosch GmbH leverages its integrated powertrain division to bundle canister modules with fuel injection systems for European OEMs. MANN+HUMMEL anchors its position through filtration-centric R&D pipelines that extend into vapor-phase hydrocarbon capture. Denso competes primarily on manufacturing scale across its Southeast Asian plant network, supplying Toyota and Honda assembly lines with standardized canister architectures.
An automotive activated carbon canister is a sealed vessel containing granular or pelletized activated carbon media designed to adsorb fuel vapors from a vehicle's evaporative emission control system, typically operating with breakthrough capacities measured in grams of butane per liter of carbon. The device prevents hydrocarbon release to atmosphere during diurnal temperature cycling and refueling events, serving as a mandatory component in gasoline-powered vehicles subject to evaporative emission regulations. OEM canisters dominate value capture due to design-in complexity and validation requirements, while aftermarket canisters face margin compression from commoditized plastic-housing replacements. Integrated systems combining canisters with pressure sensors and purge valves represent the fastest-expanding product configuration, as vehicle manufacturers consolidate underhood packaging.
The US EPA enforces evaporative emission test procedures under 40 CFR Part 86 that mandate canister efficiency across diurnal, hot soak, and running loss cycles, directly determining carbon bed sizing and purge strategy calibration. The European Union's Euro 6d regulation through ECHA-aligned material compliance and the California Air Resources Board's LEV III program collectively tighten hydrocarbon permeation limits, forcing reformulation of canister housing polymers and seal materials. Stakeholders must monitor pending EPA rulemakings on supplemental federal test procedures and emerging Chinese GB 18352.6 standards, as divergence in test protocols threatens to fragment platform engineering and carbon media specifications across regulatory jurisdictions.
Market Dynamics
Stringent evaporative emission regulations across multiple jurisdictions are forcing a fundamental redesign of canister architectures, with carbon loading densities and purge calibration complexity now determining competitive positioning in fuel system supply chains.
Growth Catalysts
- EPA Tier 3 Permeation Limits:The US regulation mandates sub-0.5 gram per day hydrocarbon leakage thresholds, compelling OEMs to specify higher-grade activated carbon media and multi-bed canister designs.
- Hybrid Powertrain Expansion:Extended engine-off operation in gasoline-electric vehicles reduces purge opportunities, requiring enlarged canister volumes and intelligent purge valve sequencing.
- China's GB 18352.6 Phase-In:The national standard's evaporative emission test protocols are tightening alignment with Euro 6d, stimulating domestic carbon media production capacity expansion.
Market Restraints
- Petroleum-Based Carbon Feedstock Volatility:Bituminous coal and coconut shell prices fluctuate with energy markets, compressing margin stability for carbon manufacturers supplying canister assemblers.
- Captive Supply Concentration:Volkswagen Group and BMW operate in-house engineering centers for vapor management systems, limiting Tier 1 supplier access to design-in decisions.
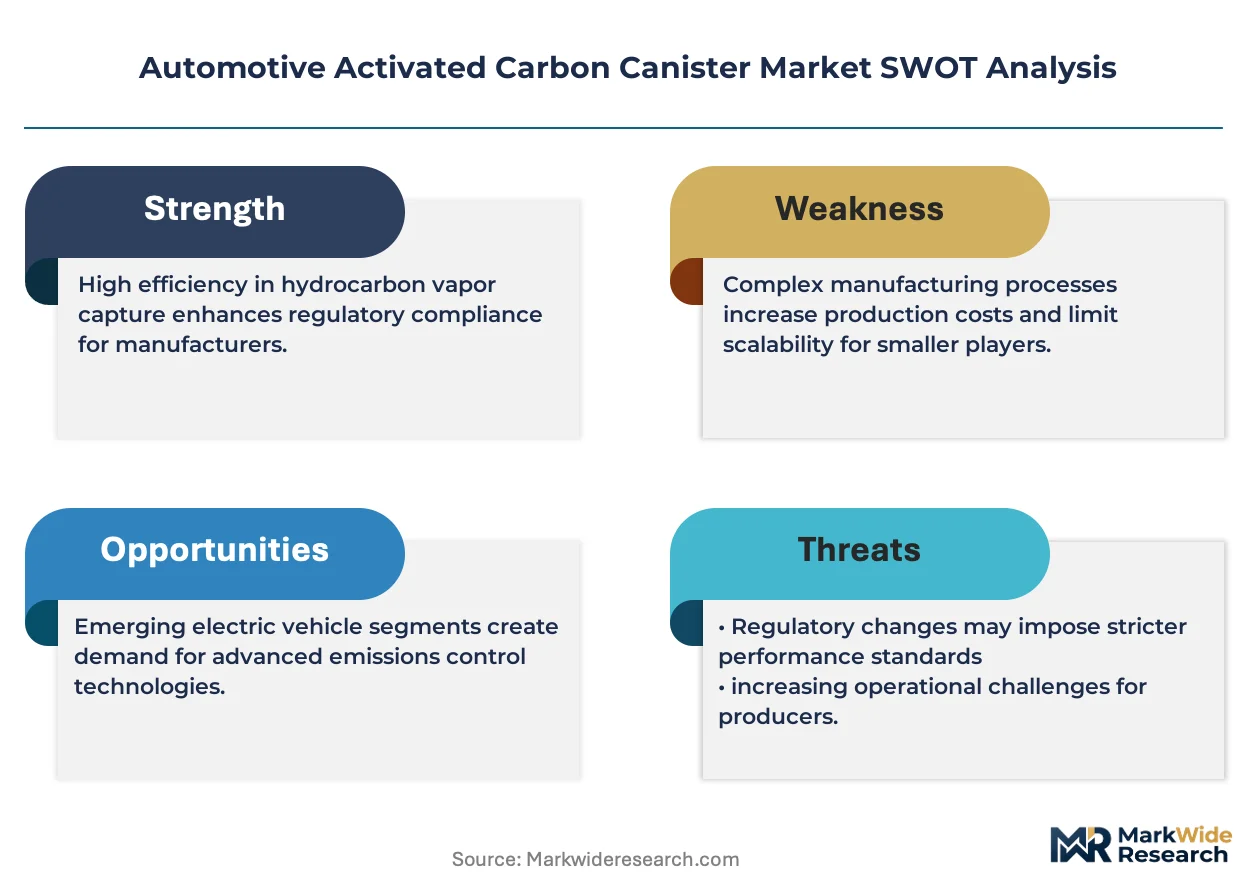
- Electric Vehicle Substitution:Battery-electric powertrains eliminate evaporative emission control hardware entirely, removing addressable volume in high-adoption metropolitan markets.
Strategic Opportunities
- India BS-VI Stage II Compliance:The country's tightened evaporative emission norms create first-mover advantage for suppliers establishing localized canister assembly operations ahead of full enforcement.
- Sensor-Integrated Smart Canisters:Convergence of pressure sensing, temperature monitoring, and predictive purge algorithms enables value capture through diagnostic-enabled fuel system modules.
- Refueling Vapor Recovery Mandates:California's enhanced ORVR requirements and pending EPA supplemental test procedures expand carbon bed sizing specifications for light-duty truck segments.
Industry Challenges
- Multi-Jurisdiction Validation Burden:Divergent EPA, Euro 6d, and Chinese test protocols force parallel engineering tracks, extending product development cycles and certification costs.
- Carbon Media Sourcing Reconfiguration:Geopolitical friction affecting coconut shell supply from Southeast Asian origins compels qualification of alternative lignocellulosic feedstocks with equivalent butane working capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Activated Carbon Canister Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OEM Canisters, Aftermarket Canisters, Integrated Systems, Standalone Solutions Application: Emission Control, Fuel Vapor Recovery, Odor Removal, Air Purification End User: Vehicle Manufacturers, Aftermarket Providers, Maintenance Facilities, Research Institutions Material: Activated Carbon, Composite Materials, Plastics, Metal |
| Companies Covered | Robert Bosch GmbH, UFI Filters S.p.A., MANN+HUMMEL, Denso, Stant Corporation, MAHLE, Continental AG, Hengst SE, Marelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Activated Carbon Canister Market Strategic Shifts
Material science advances and embedded intelligence are redefining canister performance benchmarks, with carbon formulation and system architecture evolving in lockstep with powertrain electrification timelines.
Engineered carbon composites with tailored pore size distributions are absorbing fuel vapors more efficiently than conventional granular media, enabling smaller packaging footprints without sacrificing working capacity. European OEMs are specifying these formulations for next-generation hybrid platforms where underhood space competes with battery thermal management hardware. The technology is absorbing engineering resources previously allocated to mechanical purge valve refinement, redirecting R&D toward adsorption kinetics optimization.
REACH-aligned material compliance through ECHA is restricting legacy seal polymers and housing compounds, forcing reformulation of canister enclosures to eliminate substances of very high concern. The regulation is accelerating migration to glass-filled polyamide and thermoplastic elastomer alternatives with validated permeation resistance. German KBA type-approval processes now require extended material aging documentation, extending validation timelines for suppliers serving BMW and Mercedes-Benz assembly networks.
Fleet procurement of integrated fuel system modules is consolidating vendor relationships, with vehicle manufacturers bundling canister, purge valve, and pressure sensor sourcing under single Tier 1 contracts. Traditional discrete component suppliers face exclusion from platform engineering discussions unless they demonstrate system-level calibration capabilities. This pattern is most pronounced in North American light-duty truck manufacturing, where Ford and General Motors have centralized evaporative emission control procurement under powertrain division authority.
Automotive Activated Carbon Canister Market Segmentation
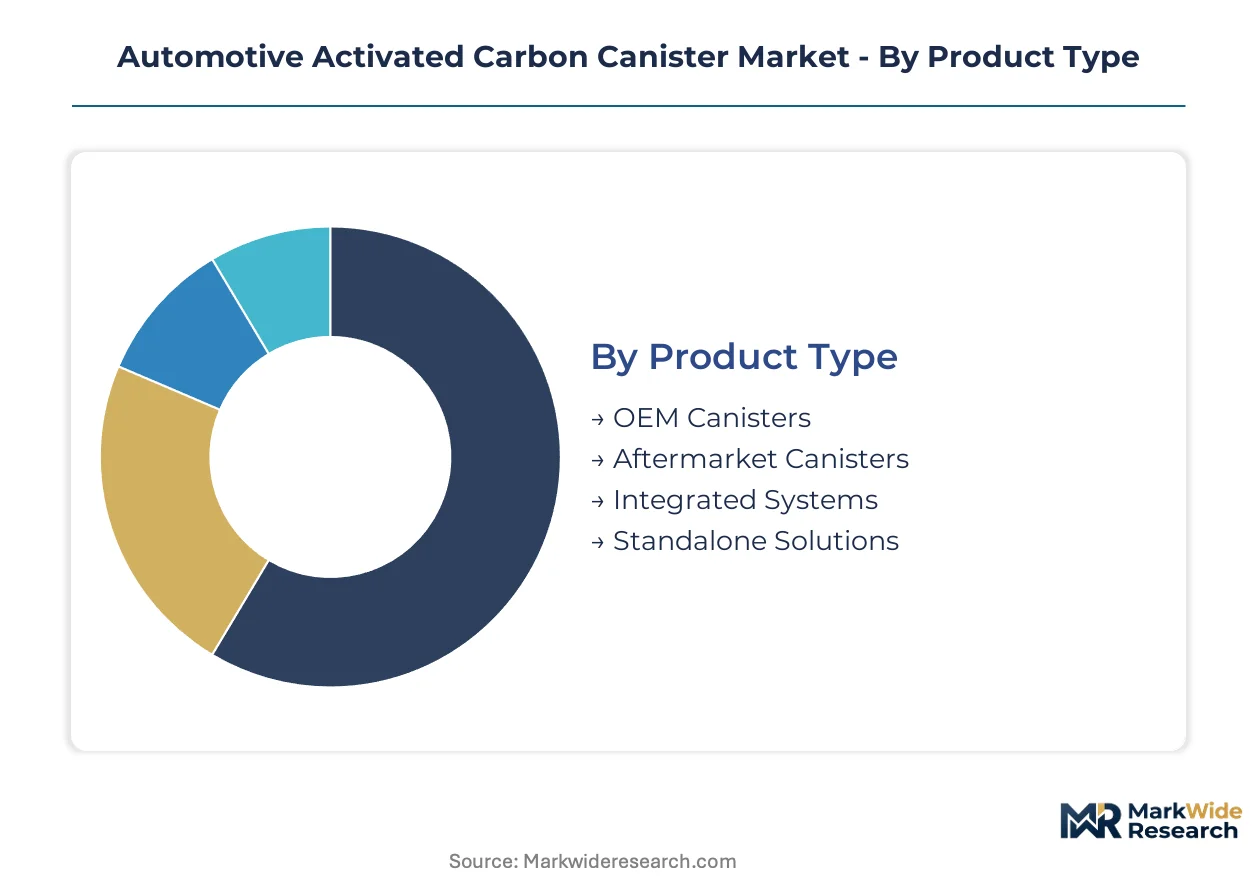
Segmentation in the automotive activated carbon canister market reveals how regulatory stringency and powertrain electrification are reshaping procurement priorities across product tiers and customer categories. Suppliers must align carbon loading specifications, housing materials, and system integration levels with divergent OEM and aftermarket economics.
Product Type:
Technical specification and design-in complexity separate segments with fundamentally different margin structures and customer retention profiles.
- OEM Canisters:These assemblies incorporate validated carbon bed configurations, purge valve interfaces, and pressure sensor mounting points calibrated to specific vehicle platforms. Volkswagen Group and BMW source these through captive engineering centers in Germany, locking in multi-year supply agreements with stringent KBA type-approval documentation requirements.
- Integrated Systems:Modules combining canister bodies with purge valves, pressure sensors, and predictive purge algorithms are capturing procurement consolidation in North American light-duty truck manufacturing. Ford and General Motors have centralized evaporative emission control sourcing under powertrain division authority, favoring suppliers with system-level calibration capabilities.
- Aftermarket Canisters:Commoditized plastic-housing replacements face margin compression from standardized fitment catalogs and price-transparent distribution channels.
- Standalone Solutions:Discrete canister units without integrated valving serve niche retrofit applications and legacy fleet maintenance.
OEM Canisters lead on scale; Integrated Systems lead on momentum.
Application:
Functional use cases map directly to regulatory test cycles and carbon working capacity requirements.
- Emission Control:EPA 40 CFR Part 86 test procedures mandate diurnal, hot soak, and running loss cycle performance, determining carbon bed sizing and purge strategy calibration. The US EPA Tier 3 sub-0.5 gram per day permeation thresholds compel multi-bed designs with higher-grade activated carbon media.
- Fuel Vapor Recovery:California's enhanced ORVR mandates and pending EPA supplemental test procedures expand carbon bed specifications for light-duty truck refueling events. This application absorbs engineering resources from mechanical purge valve refinement toward adsorption kinetics optimization.
- Odor Removal:Secondary cabin air applications in premium vehicle segments utilize smaller carbon volumes with faster saturation cycling.
- Air Purification:Non-automotive spillover applications in enclosed equipment cabins represent marginal volume with specialized media formulations.
Emission Control dominates absolute volume; Fuel Vapor Recovery shows the steepest expansion trajectory from regulatory tightening.
End User:
Customer type determines validation burden, pricing power, and relationship durability in supply contracts.
- Vehicle Manufacturers:Light-duty OEMs in North America and Europe specify carbon loading densities, housing polymers, and purge calibration complexity through platform engineering gates. These buyers concentrate procurement authority under powertrain divisions, consolidating vendor relationships.
- Aftermarket Providers:Distributors and retailers serving replacement demand compete on fitment coverage and logistics velocity rather than technical specification.
- Maintenance Facilities:Independent service networks source standardized canister replacements through wholesale channels with minimal technical differentiation.
- Research Institutions:Academic and regulatory testing laboratories procure specialized canister configurations for emission protocol development and carbon media qualification.
Vehicle Manufacturers command pricing power; Aftermarket Providers scale through distribution reach.
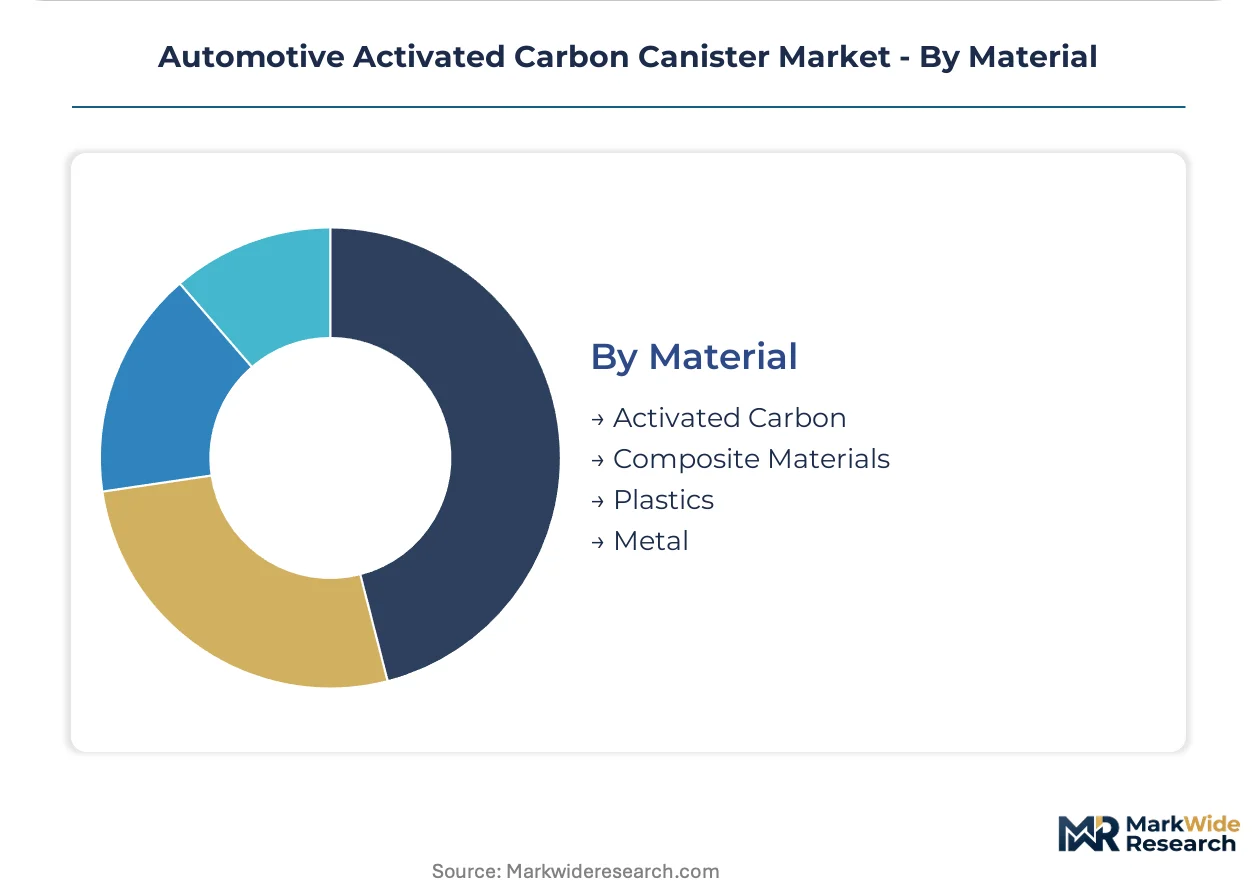
Material:
Feedstock selection and housing composition govern permeation resistance, thermal stability, and regulatory compliance.
- Activated Carbon:Engineered composites with tailored pore size distributions enable smaller packaging footprints without sacrificing butane working capacity. European OEMs specify these formulations for hybrid platforms where underhood space competes with battery thermal management hardware.
- Plastics:REACH-aligned material compliance through ECHA restricts legacy seal polymers, forcing migration to glass-filled polyamide and thermoplastic elastomer alternatives with validated permeation resistance.
- Composite Materials:Reinforced polymer blends offer weight reduction and corrosion immunity for severe-duty applications.
- Metal:Aluminum and steel housings persist in commercial vehicle segments requiring mechanical durability beyond polymer capabilities.
Activated Carbon anchors technical performance; Plastics face reformulation pressure from chemical compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands engineering-intensive canister development through captive OEM centers, while the United States drives volume procurement through consolidated powertrain division sourcing. China is scaling domestic carbon media production to serve localized vehicle manufacturing. India presents emerging compliance-driven demand as emission norms tighten.
United States
Light-duty truck manufacturers anchor procurement consolidation under powertrain division authority. The EPA Tier 3 sub-0.5 gram per day permeation thresholds mandate multi-bed canister designs with higher-grade activated carbon media. Detroit-based engineering centers calibrate purge strategies for Ford and General Motors assembly networks.
Germany
Volkswagen Group and BMW operate captive vapor management engineering centers that lock in multi-year supply agreements. The KBA type-approval process requires extended material aging documentation for REACH-aligned seal polymers. Stuttgart and Munich clusters concentrate carbon media qualification and housing polymer reformulation activities.
China
Domestic vehicle manufacturers are expanding evaporative emission control hardware procurement as GB 18352.6 standards tighten alignment with Euro 6d protocols. The MIIT oversees national standard implementation through dual carbon policy frameworks. Yangtze River Delta automotive clusters are scaling activated carbon media production capacity to serve localized supply chains.
Japan
Toyota and Honda assembly lines source standardized canister architectures through Southeast Asian manufacturing networks. The METI coordinates industrial policy alignment with emission reduction targets across automotive supply chains. Nagoya-based engineering groups optimize carbon bed configurations for hybrid powertrain purge sequencing.
India
BS-VI Stage II compliance deadlines are stimulating first-mover investment in localized canister assembly operations. The BIS enforces national emission standards that progressively align with European test protocols. Tamil Nadu and Maharashtra automotive corridors attract Tier 1 suppliers establishing regional manufacturing footprints.
Automotive Activated Carbon Canister Market Competitive Environment
German producers anchor the premium engineering tier; Japanese and Italian specialists hold scale-driven manufacturing positions. The vendor base separates into consolidated system integrators, filtration-centric component houses, and diversified automotive suppliers. Three archetypes dominate: captive OEM engineering centers, integrated powertrain bundlers, and carbon media specialists. Competitive moves concentrate on system-level calibration capabilities and geographic proximity to assembly networks.
Within the integrated systems tier, Robert Bosch GmbH exemplifies the powertrain bundling archetype, while MANN+HUMMEL occupies a filtration-centric position. Denso represents the scale-driven Asia-Pacific manufacturing model. These three anchors illustrate how competitive positioning fragments across engineering intensity, manufacturing scale, and regional supply chain proximity rather than converging on a single dominant structure.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| UFI Filters S.p.A. |
| MANN+HUMMEL |
| Denso |
| Stant Corporation |
| MAHLE |
| Continental AG |
| Hengst SE |
| Marelli |
| Others |
Value Chain & Pricing Dynamics
Bituminous coal and coconut shell price indices cascade through activated carbon canister supply chains, compressing margin stability for carbon manufacturers and forcing tiered pricing adjustments across OEM, integrated system, and aftermarket product tiers. Price stratification reflects feedstock volatility exposure, with premium formulations bearing higher pass-through sensitivity than commoditized plastic-housing replacements.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade activated carbon media, intensifying cost competition in the aftermarket tier. Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated canisters with KBA type-approval documentation from unbranded replacements. Price differentiation hinges on certification grade and volume scale, with vehicle manufacturers leveraging consolidated procurement authority to extract concessions. Cost compression in the aftermarket segment is intensifying because of price-transparent distribution channels and standardized fitment catalogs.
Supply Chain Analysis
Freight cost escalation from Southeast Asian coconut shell origins to European and North American assembly plants is accelerating regionalization of carbon media sourcing. Supply concentrates in Germany, China, and Japan, with activated carbon production drawing from bituminous coal deposits, coconut shell processing facilities, and emerging lignocellulosic feedstock qualification. Raw material dependencies span petroleum-based carbon precursors, glass-filled polyamide housing compounds, and thermoplastic elastomer seal materials. Single-source vulnerability from geopolitical friction affecting Southeast Asian coconut shell supply compels alternative feedstock validation. Distribution runs through captive OEM engineering centers, Tier 1 system integrators, and aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA Tier 3 and Euro 6d permeation thresholds mandating continuous carbon loading density upgrades and purge calibration complexity investments.
For Market Incumbents: Anticipate margin compression from electrification-driven volume erosion in metropolitan markets and defend through backward integration into activated carbon media production and captive purge valve manufacturing. Consolidate system-level calibration capabilities to maintain access to Ford and General Motors powertrain division procurement gates. Prioritize REACH-aligned material reformulation ahead of ECHA restriction timeline acceleration. For New Entrants and Emerging Players: Begin with localized canister assembly operations in India ahead of BS-VI Stage II full enforcement, targeting Tamil Nadu and Maharashtra automotive corridors with modular production footprints. Penetrate the sensor-integrated smart canister segment through diagnostic-enabled fuel system modules with predictive purge algorithms. Pursue joint development agreements with domestic vehicle manufacturers in China seeking GB 18352.6 compliance qualification. For Investors and Strategic Acquirers: Asymmetric upside sits with filtration-centric component houses possessing vapor-phase hydrocarbon capture R&D pipelines and established KBA type-approval track records. Long-term viability rests on regulatory divergence management capabilities across EPA, Euro 6d, and Chinese test protocol fragmentation. Monitor pending EPA supplemental federal test procedure rulemakings as inflection indicators for carbon bed sizing specification expansion in light-duty truck segments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Ford and General Motors consolidate evaporative emission control sourcing under powertrain division authority. |
| Backward Integration | Robert Bosch GmbH bundles canister modules with fuel injection systems through integrated powertrain division operations. |
| Geographic Manufacturing Footprint | Denso leverages Southeast Asian plant network scale to supply Toyota and Honda assembly lines. |
| Regulatory Compliance Investment | MANN+HUMMEL extends filtration-centric R&D pipelines into vapor-phase hydrocarbon capture for Euro 6d alignment. |
| Sensor Integration Partnership | Integrated systems combining canisters with pressure sensors and purge valves capture fastest-expanding product configuration demand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation from vehicle production databases, IHS Markit registration data, EPA 40 CFR Part 86 filings, and KBA type-approval documentation. Bottom-up carbon media demand modeling and top-down OEM procurement value chain analysis provided triangulation anchors.
Segment-weighting approaches distributed value and volume across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions throughout the forecast period. CAGRs derived from regression analysis against regulatory milestone timing and powertrain electrification adoption curves incorporated carbon loading density specifications, purge valve integration rates, and aftermarket replacement cycle assumptions.
Several conditions sit outside the modeled scope, including unannounced EPA supplemental federal test procedure modifications, accelerated battery-electric vehicle substitution beyond baseline electrification scenarios, and geopolitical disruptions to Southeast Asian coconut shell supply chains. Forecasts reflect assumptions about regulatory enforcement consistency and material qualification timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Roof Rack Market