
 Automotive Retail Market | 2026-2036
Automotive Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Retail Market Analysis
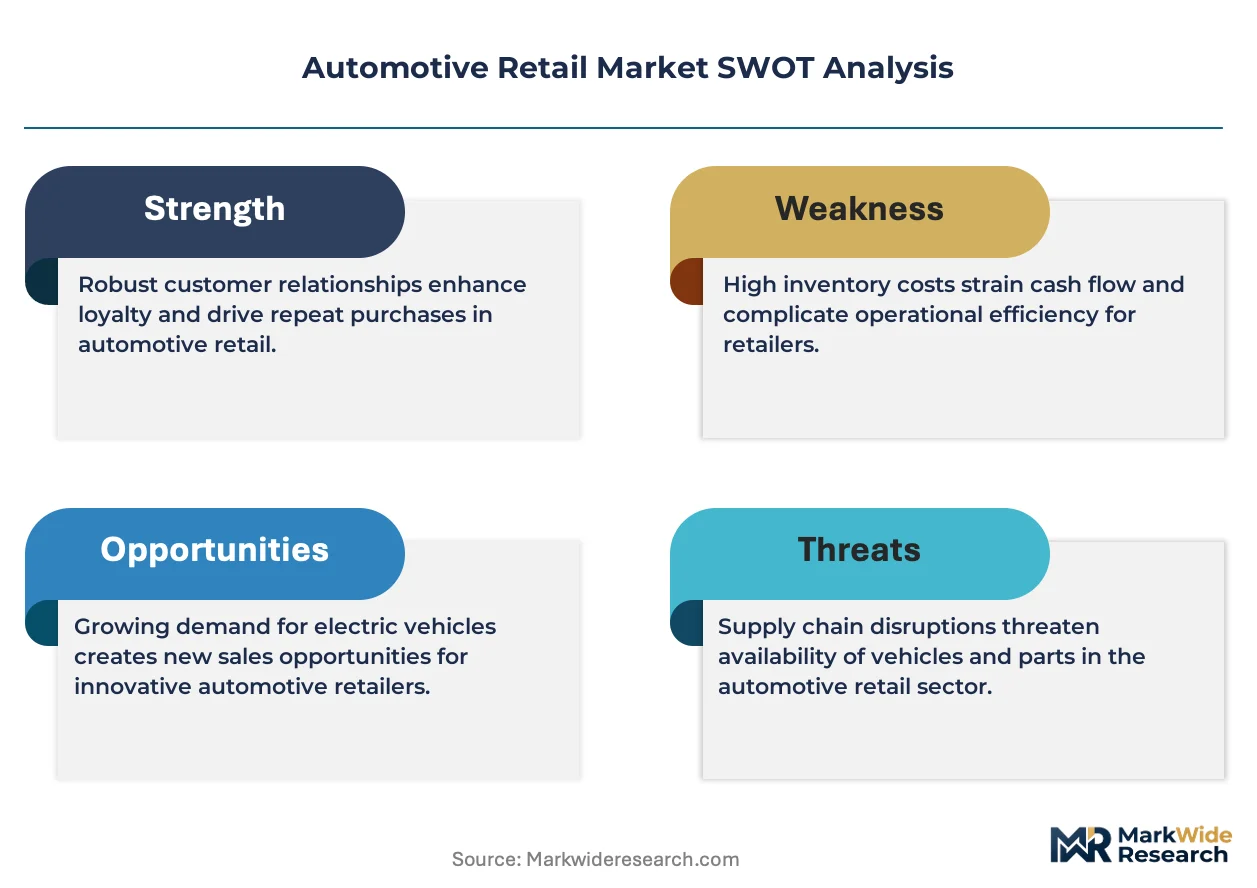
Subscription-based vehicle access and software-defined feature unlocks are realigning what automotive retail actually monetizes. Lithia Motors extends its Driveway digital platform to bundle maintenance and insurance into monthly payments. AutoNation dominates service-lane revenue by integrating predictive maintenance alerts with its dealership management system.
Automotive retail encompasses the distribution, sale, and post-sale servicing of motor vehicles through physical and digital channels, with inventory turnover cycles typically measured in 45-90 day windows and gross margins varying dramatically between new vehicle sales and fixed operations. New vehicles and used vehicles remain the core revenue pillars, though margin pools have migrated toward financing services and maintenance packages as front-end grosses compress. Online platforms represent the fastest-growing sales channel, yet dealerships sustain the bulk of fulfillment and regulatory compliance burdens.
The EPA tailpipe standards, EU Green Deal vehicle CO2 mandates, and NHTSA safety recall protocols collectively dictate inventory mix, certification requirements, and liability exposure for retail operators. The EU AI Act and emerging state-level data privacy frameworks in California and Virginia further constrain how customer driving data gets monetized through connected-car services. Stakeholders must decide whether to build captive subscription infrastructure or partner with fintech platforms before regulatory fragmentation hardens competitive moats.
Market Dynamics
Fleet electrification mandates and direct-to-consumer platform proliferation are compressing traditional dealership revenue models while redirecting capital toward battery electric inventory and integrated digital retail infrastructure.
Growth Catalysts
- EPA Tailpipe Standards:The EPA's progressively tightening vehicle emissions standards are forcing OEM allocation shifts toward zero-emission models, creating forced demand pull through regulatory compliance timelines rather than consumer preference alone.
- Integrated Digital Platforms:Direct-to-consumer showroom networks in China demonstrate how embedded financing and over-the-air feature activation can capture lifetime customer value previously fragmented across independent service providers.
- Total Cost of Ownership Models:Fleet procurement departments now weight electricity pricing stability and maintenance interval reduction against diesel volatility, accelerating commercial electrification decisions independent of retail consumer adoption curves.
Market Restraints
- Lithium Supply Concentration:Battery cell production concentrates in China and South Korea, exposing retail inventory financing to geopolitical disruption and raw material price volatility that compresses dealer margin predictability.
- Charging Infrastructure Gaps:Rural and secondary urban markets lack sufficient DC fast-charging density, constraining battery electric vehicle addressable market expansion regardless of model availability or pricing competitiveness.
- EU AI Act Data Constraints:The EU AI Act's algorithmic transparency requirements limit how connected-vehicle data streams can be monetized through predictive maintenance subscriptions or usage-based insurance products.
Strategic Opportunities
- Software-Defined Feature Unlocks:Over-the-air activation of heated seats, acceleration boost, and autonomous driving capabilities creates recurring revenue streams that decouple retail profitability from unit sales volume.
- Subscription-Based Vehicle Access:Bundled monthly payments covering vehicle, insurance, maintenance, and charging address younger demographics exhibiting asset-light consumption preferences and credit-constrained purchasing power.
- EU Green Deal Fleet Mandates:Corporate fleet CO2 targets are accelerating business-to-business procurement channels where dealers can secure multi-year volume commitments with lower customer acquisition costs than retail.
Industry Challenges
- Technician Reskilling Requirements:High-voltage battery diagnostics and electric powertrain repair demand certification programs that outpace existing vocational training pipeline capacity, constraining service lane throughput.
- Legacy DMS Integration:Dealership management system architectures designed for internal combustion engine parts hierarchies and service intervals struggle to accommodate battery health monitoring and remote diagnostic workflows.
- Inventory Reconfiguration Capital:Floorplan financing, charging infrastructure installation, and showroom redesign require substantial capital redeployment while front-end grosses compress during the transition period.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Retail Market |
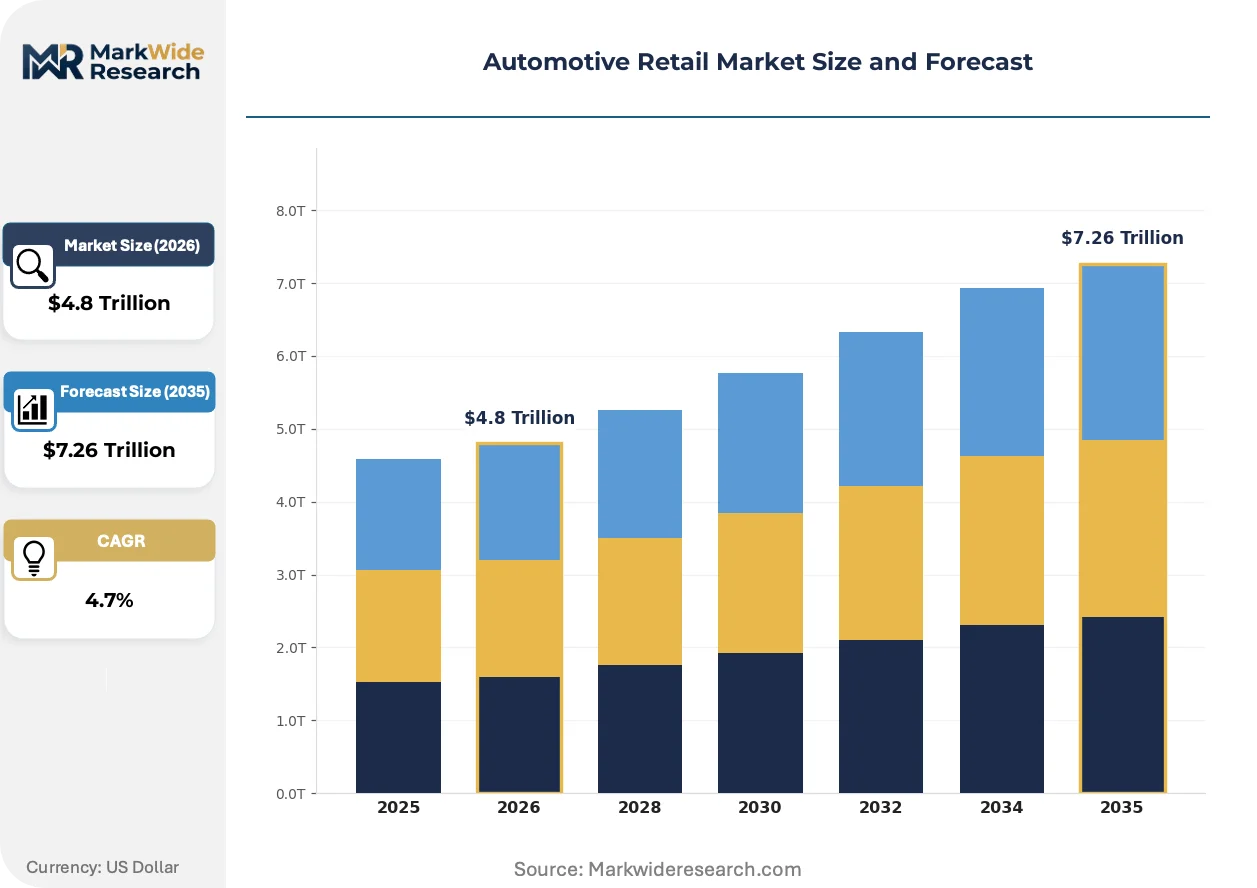
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $7.26 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: New Vehicles, Used Vehicles, Automotive Accessories, Financing Options Sales Channel: Dealerships, Online Platforms, Auctions, Private Sales Customer Type: Individual Consumers, Fleet Management Companies, Corporate Buyers, Government Agencies Service Type: Trade-ins, Financing Services, Insurance Products, Maintenance Packages |
| Companies Covered | Group 1 Automotive, Asbury Automotive, Lithia Motors, Hendrick Automotive Group, Sonic Automotive, AutoNation, Penske Automotive Group, Carvana, CarMax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Retail Market Emerging Trajectories
Digital retail infrastructure is absorbing functions previously executed through physical showrooms, while regulatory emissions frameworks and shifting ownership preferences simultaneously reshape vehicle monetization mechanics.
Artificial intelligence-driven pricing engines are absorbing real-time inventory, incentive, and competitor data to dynamically adjust vehicle quotations. Large dealer groups deploy these systems to optimize turn velocity and gross profit per unit. This technology is absorbing the traditional sales manager negotiation role, compressing transaction times and standardizing margin capture across distributed retail networks.
The EU Green Deal's vehicle CO2 mandates are hardening into binding fleet-average requirements with escalating penalty structures. OEMs respond by restricting internal combustion engine model availability and redirecting production capacity toward battery electric platforms. European dealers face compressed powertrain mix flexibility and accelerated used vehicle depreciation for non-compliant inventory categories.
Fleet procurement departments now weight total cost of ownership metrics against upfront capital expenditure, favoring electric commercial vehicles where operating cost advantages offset higher acquisition prices. This behavioral shift concentrates demand among leasing companies and logistics operators with centralized charging infrastructure. Germany and the Netherlands demonstrate the strongest fleet electrification velocity due to favorable tax depreciation treatments and urban low-emission zone enforcement.
Automotive Retail Market Segmentation
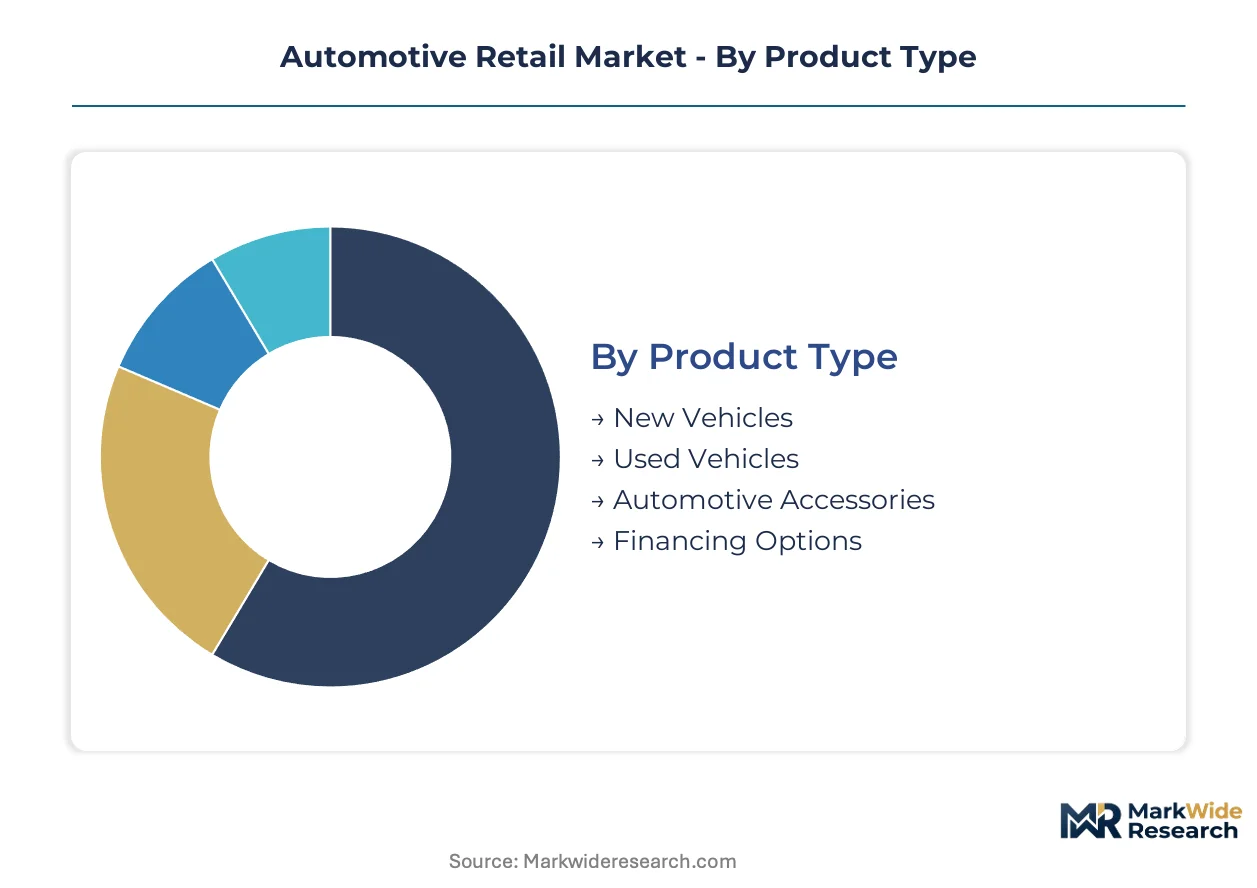
Automotive retail segmentation reveals how capital deployment, customer acquisition costs, and margin structures vary dramatically across transaction types and fulfillment channels. Understanding these divides helps operators prioritize inventory financing, digital infrastructure, and service lane investments.
Product Type:
New vehicle procurement demands the heaviest capital commitment through floorplan financing and manufacturer allocation deposits, while used inventory offers faster turns but compressed gross margins.
- New Vehicles:Factory-allocated units carry 60-90 day inventory cycles and require substantial showroom facilities for display and delivery. OEM electrification mandates in Germany and California are redirecting dealer capital toward battery electric SKUs with higher acquisition costs and slower initial turn rates.
- Used Vehicles:Sourcing through trade-ins, auctions, and off-lease returns enables 30-45 day inventory velocity. Digital pricing engines at CarMax and AutoNation optimize acquisition discipline, though wholesale price volatility compresses margin predictability.
- Automotive Accessories:Parts and add-on sales attach to new vehicle deliveries, generating incremental gross without additional floorplan burden.
- Financing Options:Captive finance subsidiaries and third-party lenders monetize credit spread across prime and subprime borrower segments.
New vehicles absorb the bulk of installed capital; used vehicles are expanding most quickly as supply chain normalization rebuilds wholesale availability.
Sales Channel:
Channel selection determines regulatory compliance burden, customer acquisition cost, and post-sale service attachment rates.
- Dealerships:Physical showrooms handle vehicle delivery, warranty administration, and recall compliance under franchise agreements. NHTSA safety protocols and state lemon laws impose liability exposure that independent platforms avoid.
- Online Platforms:Digital-first retailers like Carvana and Vroom absorb search marketing costs to capture demand upstream, though fulfillment still requires physical infrastructure for inspection and delivery.
- Auctions:Manheim and ADESA channel off-lease and fleet de-fleeted units into dealer wholesale networks, concentrating price discovery and liquidity.
- Private Sales:Peer-to-peer transactions bypass dealer gross margins entirely, though title transfer complexity and financing access constraints limit addressable market scope.
Dealerships retain the dominant share of transaction volume; online platforms are climbing the fastest as digital-native demographics enter prime vehicle acquisition age.
Customer Type:
Customer segmentation separates high-volume, low-acquisition-cost fleet relationships from fragmented individual retail demand.
- Individual Consumers:Retail buyers exhibit high touch requirements, extended decision cycles, and sensitivity to monthly payment packaging. Credit availability and employment stability directly correlate with transaction closure rates.
- Fleet Management Companies:Enterprise leasing and rental operators procure through centralized procurement functions with multi-year volume commitments. EU Green Deal CO2 mandates and EPA tailpipe standards are accelerating electrification timelines for commercial fleets in the Netherlands and California.
- Corporate Buyers:Executive vehicle programs and company car allocations favor premium segments with bundled maintenance and replacement scheduling.
- Government Agencies:Municipal and federal procurement operates through sealed bid processes with domestic content requirements and electrification mandates under federal fleet executive orders.
Individual consumers represent the largest revenue pool; fleet management companies are gaining share fastest as total cost of ownership models favor electrification at scale.
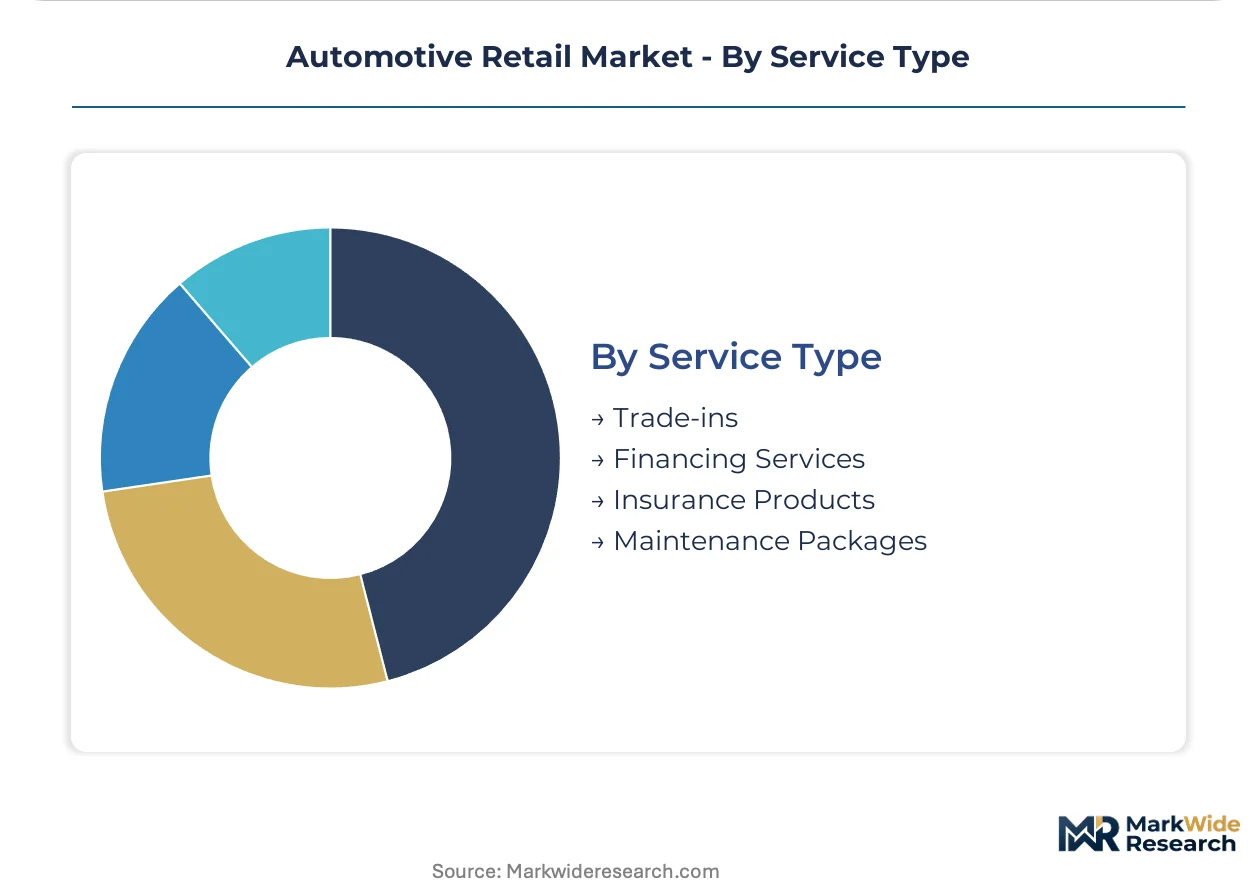
Service Type:
Service segmentation captures margin migration from front-end vehicle gross to recurring revenue streams.
- Trade-ins:Vehicle exchange transactions generate used inventory supply and finance reserve opportunities. Appraisal accuracy directly impacts gross profit capture and customer retention.
- Financing Services:Interest rate spreads, reserve participation, and aftermarket product penetration (GAP, extended service contracts) now exceed new vehicle front-end gross at many franchise operations.
- Insurance Products:Agency referrals and captive insurance offerings monetize customer lifetime value through recurring premium relationships.
- Maintenance Packages:Prepaid service plans and subscription-based vehicle access bundles lock in service lane revenue and reduce customer defection to independent repair facilities.
Financing services command the deepest margin contribution; maintenance packages are expanding most quickly as software-defined vehicles enable predictive service scheduling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of battery electric vehicles yet consumes them through direct-to-consumer platforms that bypass traditional retail infrastructure. Germany and the United States maintain substantial retail networks anchored by franchise dealer laws. Japan and South Korea concentrate hybrid and electric vehicle distribution through manufacturer-captive channels.
United States
Franchise dealer networks dominate new vehicle distribution under state-level protections that block direct manufacturer sales. The EPA's progressively tightening tailpipe standards redirect OEM allocation toward battery electric models. Texas and Florida sustain the highest transaction volumes, though California leads electrification velocity through ZEV mandates and incentive stacking.
Germany
The EU Green Deal's binding fleet CO2 targets force rapid powertrain transition across premium and volume segments. KBA certification requirements and type-approval protocols govern vehicle homologation and market entry. Bavaria and Baden-Württemberg concentrate manufacturer headquarters and flagship retail facilities, while Hamburg and Berlin accelerate urban low-emission zone enforcement.
China
Domestic brands capture share through integrated digital retail platforms and direct-to-consumer showroom networks. MIIT production quotas and NEV credit mandates compress internal combustion engine availability. The Yangtze River Delta and Pearl River Delta host the densest charging infrastructure and highest battery electric vehicle penetration rates.
Japan
Manufacturer-captive dealer networks maintain tight control over distribution and service relationships. METI carbon neutrality roadmaps and subsidy extensions support hybrid and battery electric model introductions. The Kanto region around Tokyo concentrates transaction volume, while Osaka-Kobe anchors western Japan retail density.
South Korea
Chaebol-affiliated retail networks integrate vehicle sales with captive finance and charging infrastructure. Government EV subsidy programs and corporate fleet electrification mandates accelerate battery electric adoption. The Seoul Capital Area absorbs over half of national transaction volume, with Busan-Ulsan serving as the secondary commercial hub.
Automotive Retail Market Vendor Landscape
Top-tier vendors anchor consolidated metro markets, while regional specialists defend secondary geographies through acquisition and service lane density. National dealer groups deploy capital across multiple states to capture scale economies in inventory financing and digital infrastructure. Two strategic archetypes dominate: integrated digital-retail platforms bundling subscription services, and service-lane-centric operators maximizing fixed operations yield. Competitive moves concentrate on multi-brand portfolio expansion and predictive maintenance technology deployment.
Within the publicly traded dealer group tier, AutoNation, Lithia Motors, and CarMax exemplify divergent capital allocation strategies. AutoNation occupies a position emphasizing service lane integration and manufacturer alignment. Lithia Motors represents the digital platform expansion archetype through its Driveway infrastructure. CarMax anchors the used-vehicle specialization vector with centralized reconditioning and pricing engine capabilities.
| Leading Market Players |
|---|
| Group 1 Automotive |
| Asbury Automotive |
| Lithia Motors |
| Hendrick Automotive Group |
| Sonic Automotive |
| AutoNation |
| Penske Automotive Group |
| Carvana |
| CarMax |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up dealer groups anchor inventory financing discipline across fragmented metro markets, linking floorplan leverage to pricing power compression as front-end grosses tighten and capital redeployment demands accelerate.
Pricing Analysis
Margin tightening in battery electric vehicle tiers reflects higher acquisition costs and slower initial turn rates as OEM electrification mandates redirect allocation. Three-tier pricing structure across premium, standard, and economy levels separates certified pre-owned programs from auction-sourced inventory and new vehicle MSRP anchoring. Pricing pressure stems from lithium supply volatility and compressed wholesale predictability. Fleet management companies exhibit lowest price sensitivity through volume commitments, while subprime retail borrowers face tightened credit spreads.
Supply Chain Analysis
Regional distribution centers in Germany, China, and South Korea concentrate battery cell and powertrain module warehousing before hub-and-spoke dealer allocation. Raw material dependencies draw from Chilean lithium, Indonesian nickel, and Australian cobalt processing. Single-source vulnerability in Chinese cathode production exposes inventory financing to geopolitical disruption. Distribution runs through manufacturer-captive allocation systems into franchise dealer floorplan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive retail consolidation accelerates as electrification capital requirements and technician reskilling costs force undercapitalized operators toward exit.
For Market Incumbents: Acquire high-voltage certification capacity and predictive maintenance technology stacks before technician pipeline constraints harden. Defensive consolidation targets fixed operations density in secondary metro markets where service lane throughput advantages compound. Lithia Motors' Driveway platform and AutoNation's DMS integration demonstrate how digital infrastructure investments preempt customer defection to independent repair networks. For New Entrants and Emerging Players: The price-point gap between subscription-based vehicle access and traditional ownership financing creates white-space entry at the asset-light demographic tier. Target fleet management procurement channels where EU Green Deal CO2 mandates and EPA tailpipe standards accelerate electrification timelines with lower customer acquisition costs. Deploy embedded insurance bundling and charging infrastructure partnerships as differentiated go-to-market anchors. For Investors and Strategic Acquirers: Distressed-cycle entries favor service-lane-centric operators in Texas and Florida where transaction volume concentration sustains fixed operations yield through volume downturns. Long-term viability hinges on predictive maintenance technology deployment and software-defined vehicle revenue capture. Watch battery electric vehicle inventory turn velocity as the inflection signal distinguishing viable platforms from capital-trapped operations.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium cell allocation from Chinese and South Korean producers amid raw material volatility. |
| Software-Defined Vehicle Investment | Enables over-the-air feature unlocks and subscription revenue streams beyond unit sales. |
| Charging Infrastructure Partnership | Addresses DC fast-charging gaps constraining battery electric vehicle addressable market expansion. |
| Geographic Manufacturing Footprint | Positions inventory near Yangtze River Delta and Pearl River Delta charging density clusters. |
| Platform Standardization | Reduces legacy DMS integration costs and accelerates predictive maintenance alert deployment. |
Methodological Framework
Multi-period observation of inventory turn velocity, floorplan financing spreads, and service lane revenue mix anchored the trend analysis, supplemented by interviews with dealership operations directors, OEM platform engineers, Tier 1 supplier procurement leads, and aftermarket distributors. Secondary validation drew from EPA tailpipe standard filings, EU Green Deal regulatory texts, NHTSA safety recall databases, and vehicle registration data. Bottom-up dealer financial statement analysis and top-down OEM allocation modeling were triangulated against fleet procurement survey data.
Segment-weighting across vehicle class, propulsion architecture, and regional production clusters structured the analytical framework. CAGRs were derived from production allocation trajectories and electrification mandate compliance timelines. Battery electric vehicle SKU expansion rates and technician certification pipeline capacity served as industry-specific forecast inputs throughout the projection horizon.
Inputs from OEM allocation disclosures and fleet procurement surveys were available through the study window; gaps in real-time lithium pricing and wholesale auction transaction data introduce uncertainty bands around margin compression assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Subscription Services Market
Automotive Services
Parking Services Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
GCC Car Wash Market
Automotive Services
Global Car Wash Market
Automotive Services
North America MRO Distribution Market
Automotive Services
North America Car Wash Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Vehicle Subscription Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Cab Services Market