
 Automotive Acoustic Engineering Services Market | 2026-2036
Automotive Acoustic Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Acoustic Engineering Services Market Intelligence
Asset-light engineering partnerships and simulation-as-a-service leasing are narrowing the capital barrier for mid-tier suppliers seeking acoustic testing capabilities. Brüel & Kjær leverages its transducer manufacturing heritage to sustain premium positioning in precision measurement hardware. Continental AG anchors large-scale contracts through integrated tire-vehicle acoustic programs that span multiple OEM platforms. AVL List GmbH differentiates by combining powertrain NVH with full-vehicle acoustic engineering under single program management.
Automotive acoustic engineering services encompass the measurement, simulation, and mitigation of noise, vibration, and harshness across vehicle systems using tools such as beamforming arrays, modal analysis, and statistical energy analysis at frequencies from 20 Hz to 20 kHz. These services enable OEMs to meet regulatory pass-by noise limits while optimizing occupant comfort and brand-specific sound signatures. Passenger vehicle applications lead service revenue due to volume scale, though electrics represent the fastest-expanding segment as powertrain silence exposes wind and road noise. Active noise cancellation technology commands the highest engineering margins, while sound insulation remains the most mature and price-competitive service category.
The EPA enforces noise emission limits for vehicles sold in the United States, while ECE R51 governs exterior noise across European type approvals, and China's MIIT implements GB standards for passenger car noise that tighten with each regulatory cycle. These frameworks compel OEMs to front-load acoustic simulation into vehicle development, shifting engineering spend earlier in product timelines. Stakeholders must monitor how battery-electric platform proliferation redirects NVH budgets from powertrain isolation toward aerodynamic and tire-road noise management.
Market Dynamics
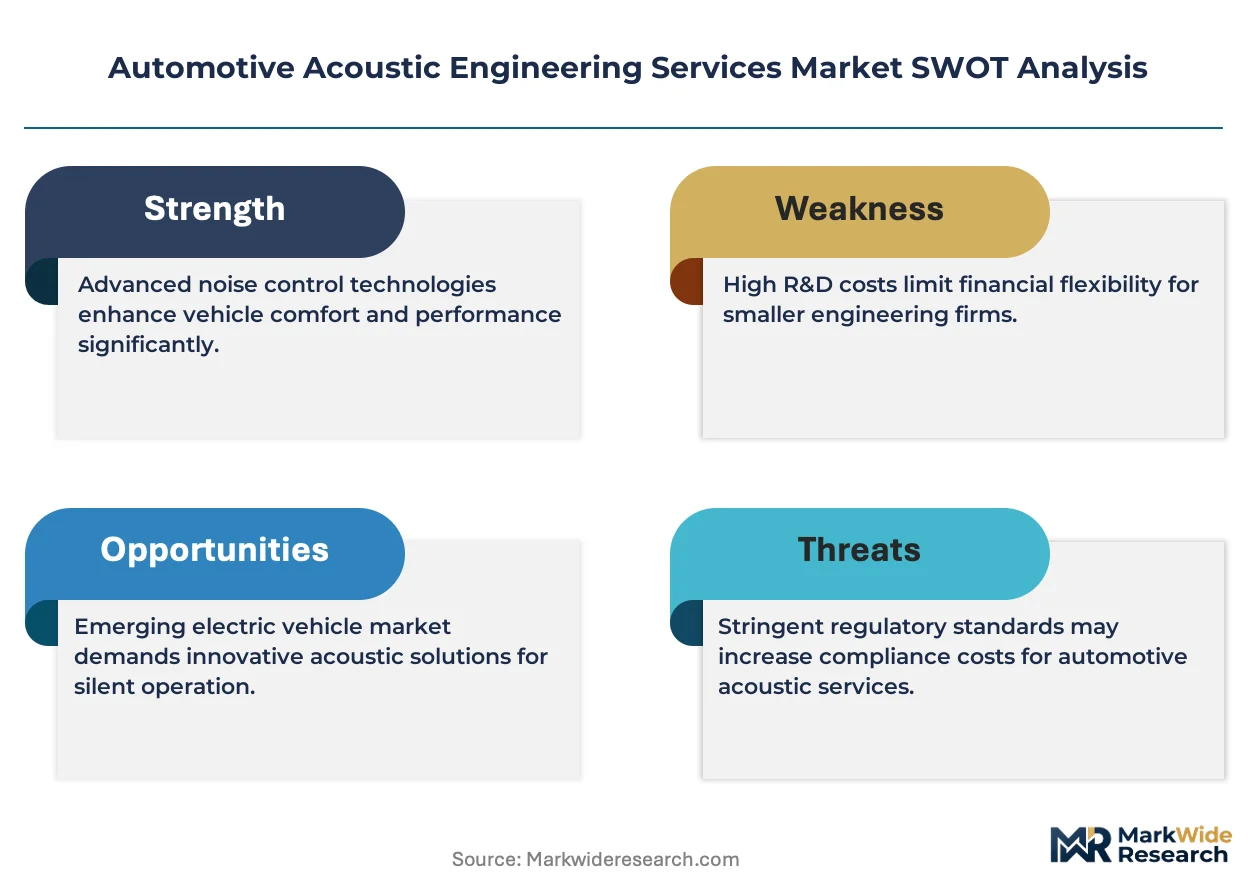
Electric vehicle powertrain silence is fundamentally rebalancing NVH engineering budgets toward aerodynamic and tire-road noise management, forcing service providers to retool capabilities and pricing models around wind tunnel correlation and road surface interaction simulation.
Growth Catalysts
- ECE R51 noise emission standards:Europe's tightening pass-by noise limits compel OEMs to front-load acoustic simulation earlier in vehicle development cycles, expanding engineering service procurement volumes.
- Active noise cancellation technology:Premium electric vehicle cabins demand sophisticated ANC system integration, creating high-margin engineering engagements that span hardware tuning and psychoacoustic calibration.
- Germany-China-US corridor:Engineering procurement concentrates in these three markets where OEM headquarters proximity enables embedded acoustic engineering partnerships and faster design iteration loops.
Market Restraints
- Beamforming microphone array hardware costs:Capital intensity for precision acoustic measurement equipment limits mid-tier suppliers from building in-house testing capabilities, reinforcing dependence on leased service models.
- Simulation software licensing concentration:Dominant CAE platform providers extract recurring fees that compress margins for independent engineering consultancies competing on simulation-based deliverables.
- ISO 362 pass-by noise testing:Harmonized international standards create compliance rigidity that constrains service differentiation and locks engineering approaches toward standardized methodologies.
Strategic Opportunities
- India's emerging EV manufacturing base:Domestic OEMs and joint ventures lack mature acoustic engineering infrastructure, creating first-mover advantage for service providers establishing localized testing facilities.
- EU Green Deal vehicle weight mandates:Material optimization requirements for lightweighting accelerate demand for statistical energy analysis services that predict noise transmission through novel composite structures.
- Simulation-as-a-service leasing:Cloud-based acoustic CAE platforms enable smaller suppliers to access enterprise-grade simulation tools without capital expenditure, expanding the addressable client base.
Industry Challenges
- Psychoacoustic calibration expertise:The specialized skill set combining physics-based NVH knowledge with human hearing perception science remains scarce, constraining service capacity for brand-specific sound signature development.
- Multi-physics simulation integration:Coupling aerodynamic CFD with acoustic radiation models requires computational infrastructure and cross-domain expertise that stretches project timelines and budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Acoustic Engineering Services Market |
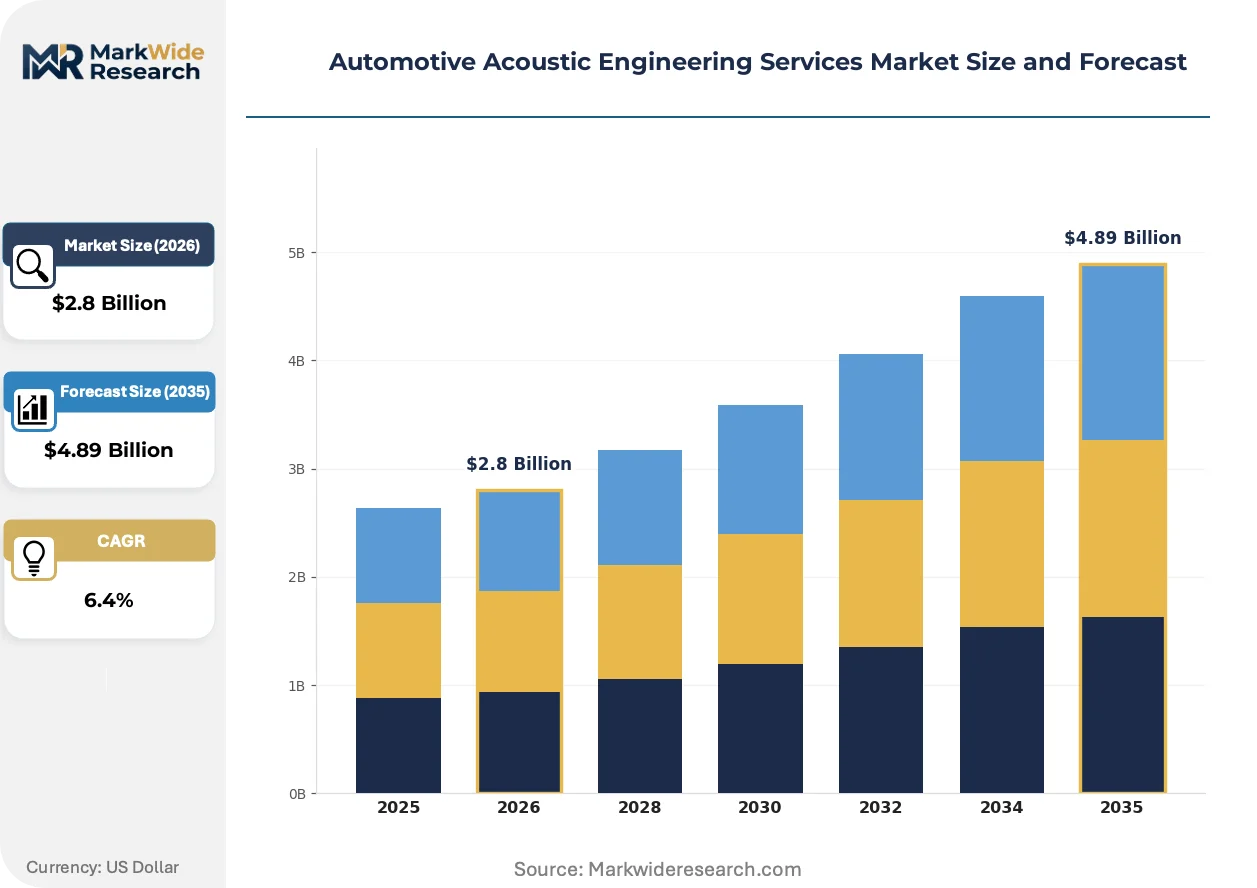
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Noise Control, Vibration Testing, Sound Absorption, Boundary Layer Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Active Noise Cancellation, Sound Insulation, Acoustic Analysis, Material Optimization Application: Passenger Vehicles, Commercial Vehicles, High-Performance Cars, Electrics |
| Companies Covered | Siemens Digital Industries Software, Brüel & Kjær, AVL List GmbH, HEAD acoustics GmbH, Continental AG, Bertrandt AG, FEV Group, EDAG Engineering GmbH, Autoneum Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Acoustic Engineering Services Market Strategic Shifts & Innovations
Digital twin methodologies are compressing physical prototype requirements while regulatory pressure on exterior noise intensifies simulation fidelity demands across development programs.
Digital acoustic twin platforms is digitizing vehicle noise prediction by integrating real-time powertrain, tire, and aerodynamic source models into unified simulation environments. Tier-1 suppliers and OEM engineering centers are deploying these tools at scale for electric platform development. The technology is digitizing traditional hardware-heavy validation workflows, reducing wind tunnel hours and accelerating design freeze decisions.
EPA noise emission enforcement under the Noise Control Act is tightening commercial vehicle compliance windows, extending passenger car acoustic standards into light truck and van segments. OEMs must now engineer for dual regulatory regimes spanning federal limits and state-level enforcement variations. Heavy-duty electric truck programs face the steepest adaptation requirements as powertrain silence exposes chassis and cargo bay resonance issues.
Asset-light engineering partnerships are displacing captive acoustic testing departments as OEMs prioritize variable cost structures over fixed facility investments. Tier-2 suppliers in Germany and the US Midwest are accessing premium measurement capabilities through embedded service contracts rather than capital programs. China-based EV startups represent the most aggressive adopters of this model, outsourcing entire NVH development streams to specialized engineering houses.
Automotive Acoustic Engineering Services Market Segmentation
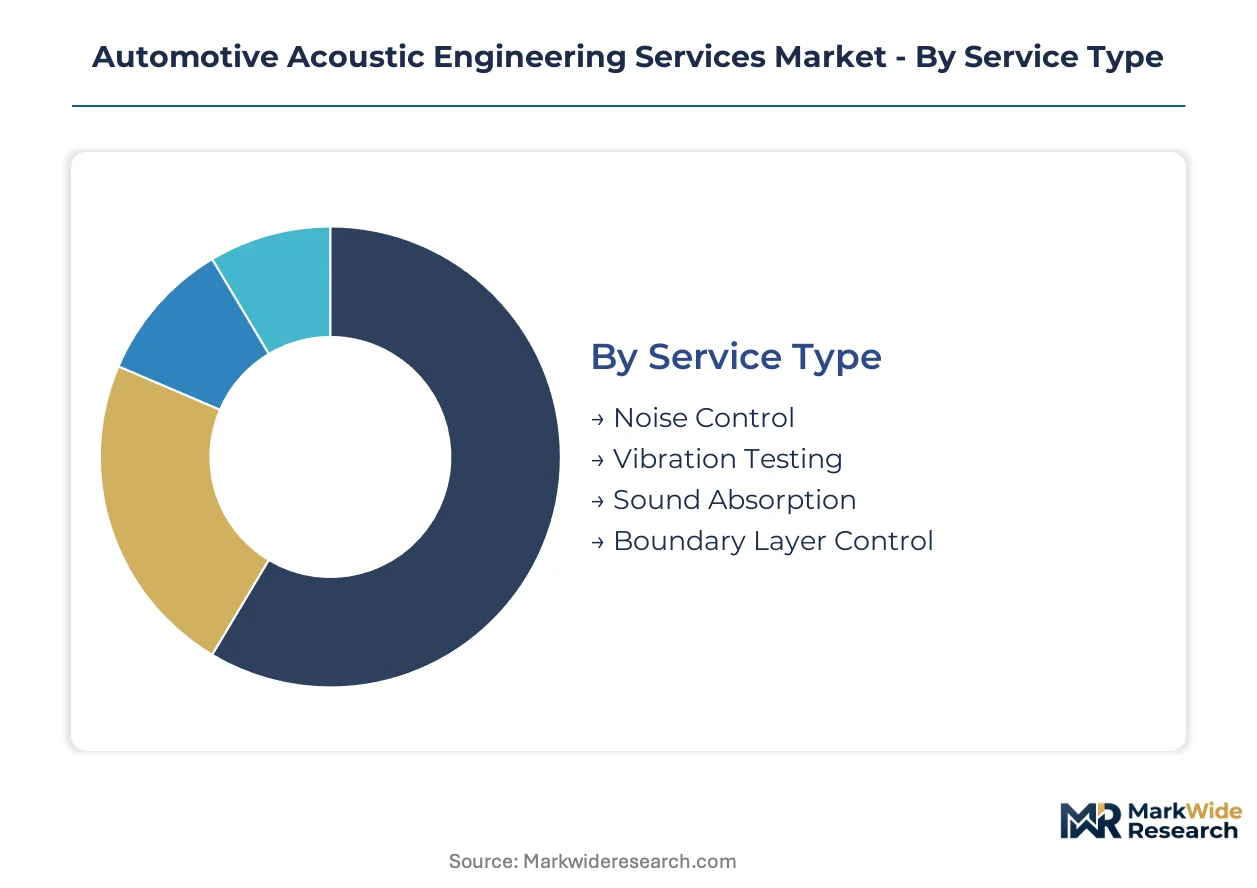
Automotive acoustic engineering services fragment across four intersecting dimensions that determine procurement patterns and margin structures. Service type and technology choices dictate capital intensity, while end-user category and application segment govern contract scale and development timeline compression.
Service Type:
After-sales service intensity varies sharply across engineering service categories, with some requiring continuous recalibration throughout vehicle lifecycle and others delivering finite validation milestones.
- Noise Control:Systematic mitigation of unwanted sound sources through source-path-receiver analysis and countermeasure implementation. OEMs in Germany and China concentrate procurement here as electric platforms expose aerodynamic and tire noise requiring iterative tuning across multiple model years.
- Vibration Testing:Modal analysis and operational deflection shape measurement to identify structural resonance frequencies and damping requirements. High-performance vehicle programs generate premium-margin engagements where frequency resolution below 0.5 Hz distinguishes competitive positioning.
- Sound Absorption:Material selection and cavity treatment design to reduce reverberant field energy in passenger compartments. Tier-1 suppliers integrate these services into interior module supply contracts.
- Boundary Layer Control:Aerodynamic surface optimization to manage flow separation and turbulent noise generation. Wind tunnel correlation programs for electric SUVs drive specialized demand.
By volume, Noise Control leads. By growth pace, Boundary Layer Control is climbing the fastest.
End User:
Cost tier stratification separates capital-intensive captive programs from variable-cost outsourced engagements, with procurement authority residing at different organizational levels across each category.
- OEMs:Full-vehicle NVH program ownership with embedded engineering teams and direct supplier management. Volkswagen Group, BYD, and Ford Motor Company anchor the largest contract values through platform-spanning acoustic development.
- Tier-1 Suppliers:Subsystem-level acoustic integration for powertrain, chassis, and interior modules. Continental AG and similar suppliers bundle testing services with component supply to capture lifecycle revenue.
- Aftermarket Providers:Retrofit sound treatment and diagnostic services for vehicle modification and repair channels. Fragmented demand across independent shops constrains contract scale.
- Vehicle Assemblers:Contract manufacturing operations lacking native R&D capabilities that outsource complete acoustic validation to engineering houses.
OEMs command the largest individual contracts. Tier-1 Suppliers are expanding their share fastest through integrated supply-service bundling.
Technology:
Application maturity spans decades-old material science through emerging signal processing domains, with margin compression inverse to technical novelty.
- Active Noise Cancellation:Real-time acoustic cancellation through microphone-speaker feedback loops and psychoacoustic calibration algorithms. Premium electric vehicle cabins in the United States and Scandinavia generate highest-margin engagements requiring hardware-software co-development.
- Sound Insulation:Mass-spring-mass barrier design and porous absorber specification using conventional material libraries. Mature pricing pressure from Asian suppliers compresses engineering margins toward commoditization.
- Acoustic Analysis:Simulation-based prediction using statistical energy analysis and boundary element methods. Cloud platform leasing is expanding access for mid-tier consultancies.
- Material Optimization:Composite and lightweight structure acoustic characterization for EU Green Deal compliance. Statistical energy analysis predicts noise transmission through novel substrates.
Sound Insulation dominates current procurement volume. Active Noise Cancellation shows the steepest expansion trajectory as electric vehicle silence exposes cabin refinement demands.
Application:
Volume concentration and technology adoption velocity diverge across vehicle categories, with electrification timing and regulatory exposure determining service mix.
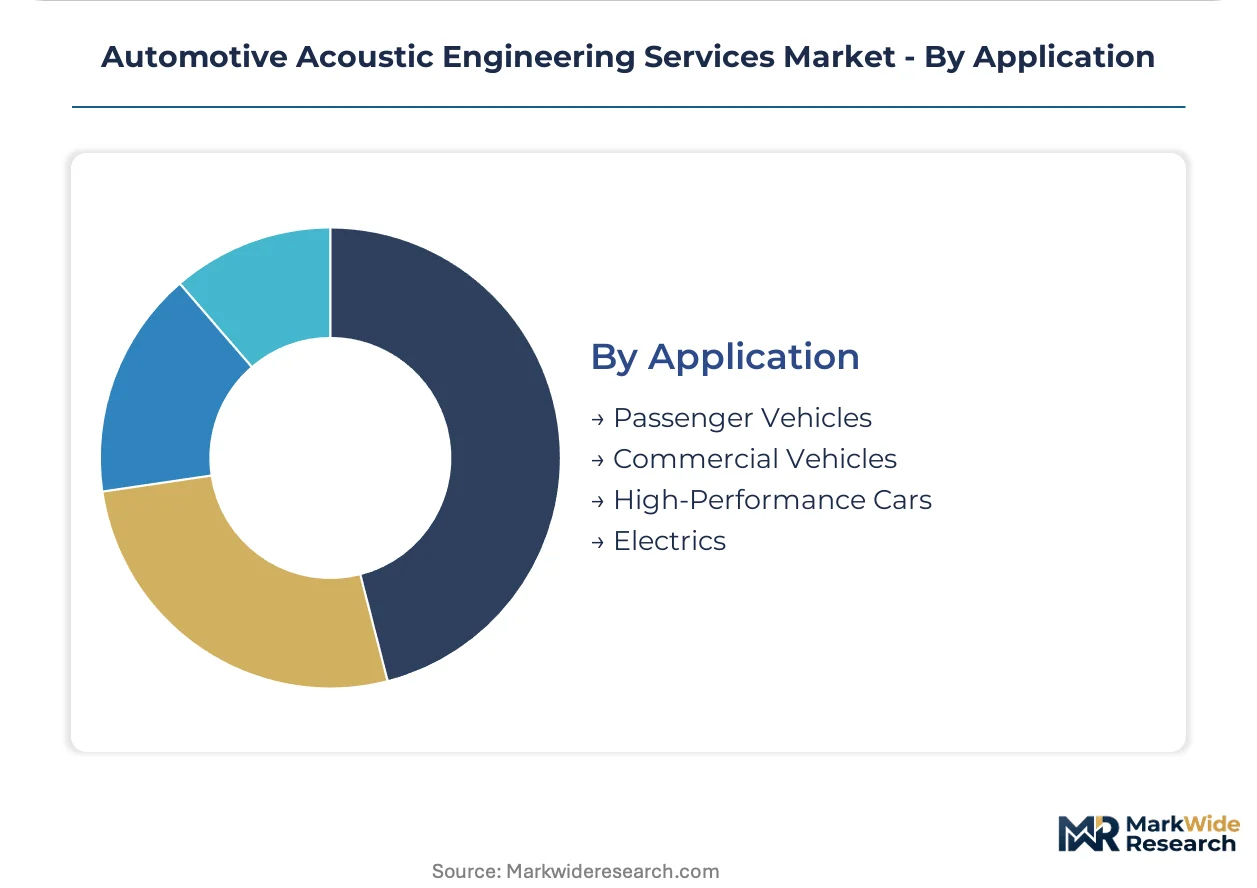
- Passenger Vehicles:High-volume compact and mid-size segments where acoustic engineering spreads across platform derivatives. Chinese domestic brands and joint ventures generate the largest absolute service procurement.
- Commercial Vehicles:Heavy-duty trucks and vans facing EPA Noise Control Act enforcement extension. Electric truck programs expose chassis and cargo bay resonance requiring specialized treatment.
- High-Performance Cars:Low-volume premium segments where brand-specific sound signature development commands engineering premiums. Porsche and Ferrari anchor exclusive calibration programs.
- Electrics:Battery-electric platforms across all vehicle classes where powertrain silence rebalances NVH budgets toward aerodynamic and tire-road noise. Startups in China outsource entire development streams.
Passenger Vehicles lead by contract volume. Electrics are gaining share fastest as platform proliferation accelerates engineering procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering procurement concentrates among OEM headquarters clusters in Germany, China, and the United States, where embedded partnerships enable faster design iteration and platform-spanning acoustic programs.
Germany
Volkswagen Group and BMW anchor platform-spanning NVH contracts that span multiple electric vehicle architectures. The KBA enforces ECE R51 pass-by noise standards through type approval processes that mandate front-loaded simulation. Stuttgart and Munich engineering corridors host captive acoustic testing facilities serving both OEMs and Tier-1 suppliers.
China
BYD and domestic EV startups outsource entire NVH development streams to specialized engineering houses lacking in-house infrastructure. MIIT implements GB standards for passenger car noise that tighten with each regulatory cycle. Shanghai and Shenzhen clusters concentrate both OEM headquarters and acoustic service provider regional offices.
United States
Ford Motor Company and General Motors anchor large-scale contracts through integrated platform development spanning light trucks and electric vehicles. The EPA enforces noise emission limits under the Noise Control Act with compliance windows tightening for commercial vehicle segments. Detroit and California engineering centers split between legacy powertrain NVH and emerging electric vehicle cabin refinement programs.
Japan
Toyota and Honda maintain hybrid platform acoustic engineering that bridges powertrain silence with aerodynamic noise management. METI coordinates national noise reduction targets that influence automotive supplier R&D priorities. Nagoya and Tokyo metropolitan areas concentrate both OEM engineering centers and precision measurement equipment manufacturers.
India
Domestic OEMs and joint ventures lack mature acoustic engineering infrastructure as EV manufacturing scales. The Ministry of Heavy Industries administers PLI scheme incentives that accelerate local component and testing capability development. Tamil Nadu and Maharashtra automotive corridors attract first-mover service providers establishing localized wind tunnel and road simulation facilities.
Automotive Acoustic Engineering Services Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven integrators and precision measurement heritage firms occupy distinct margin bands. The market organizes around three archetypes: transducer manufacturers leveraging hardware heritage, full-vehicle engineering houses bundling NVH with powertrain development, and simulation platform vendors extracting recurring software fees. Dominant competitive moves include asset-light partnership structures that displace captive testing departments and cloud-based simulation leasing that expands mid-tier supplier access.
Within the precision measurement tier, Brüel & Kjær and HEAD acoustics GmbH represent heritage transducer manufacturers sustaining premium positioning through hardware calibration expertise. AVL List GmbH and Continental AG exemplify full-vehicle integrators combining powertrain NVH with acoustic engineering under unified program management. Siemens Digital Industries Software occupies the simulation platform vector with CAE tools that independent consultancies license for statistical energy analysis deliverables.
| Leading Market Players |
|---|
| Siemens Digital Industries Software |
| Brüel & Kjær |
| AVL List GmbH |
| HEAD acoustics GmbH |
| Continental AG |
| Bertrandt AG |
| FEV Group |
| EDAG Engineering GmbH |
| Autoneum Holding AG |
| Others |
Cost & Logistics Intelligence
Beamforming microphone array import restrictions from precision equipment manufacturers in Denmark and Germany determine both the premium spread for measurement hardware tiers and the geographic clustering of acoustic testing facilities near transducer supply sources. OEMs and Tier-1 suppliers face divergent cost structures as captive calibration capabilities versus leased service models reshape procurement economics.
Pricing Analysis
Cost-plus contracts with steel and rare-earth magnet indexation dominate long-term equipment supply agreements for microphone arrays and shaker systems. Three-tier pricing structure across premium, standard, and economy levels separates Brüel & Kjær precision hardware from mid-tier Asian suppliers and refurbished equipment channels. Pricing pressure stems from cloud-based simulation-as-a-service leasing that compresses margins on perpetual software licenses. Aftermarket providers and vehicle assemblers exhibit highest price sensitivity due to fragmented contract scales, while OEM embedded engineering partnerships absorb premium rates for faster iteration cycles.
Supply Chain Analysis
Export-control regimes limiting high-precision transducer technology flows from Denmark and Germany constrain independent engineering consultancies in India and Southeast Asia from building captive testing capabilities. Hardware supply concentrates in Denmark, Germany, and Japan for precision microphones, modal shakers, and signal conditioning equipment. Raw material dependencies span neodymium for magnetic assemblies, specialized ceramics for piezoelectric sensors, and high-purity copper for cabling infrastructure. Single-source vulnerability runs through Danish transducer manufacturers holding decades of calibration heritage. Distribution runs through direct OEM partnerships for large platforms and regional service leasing networks for mid-tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native acoustic simulation platforms threaten incumbent engineering houses with disintermediation, forcing established providers to defend their position through embedded hardware-software integration.
For Market Incumbents: Insulate platform-spanning contracts by deepening backward integration into transducer manufacturing and calibration IP, countering the threat from simulation-only entrants. AVL List GmbH and Continental AG anchor defensible positions through unified powertrain-acoustic program management that cloud platforms cannot replicate without physical testing heritage.
For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra automotive corridors offer the most penetrable white-space for localized wind tunnel and road simulation facilities serving domestic OEMs lacking acoustic infrastructure. Target joint-venture EV programs through asset-light partnership structures that displace capital-intensive facility builds, leveraging MIIT regulatory tightening as the consultative entry wedge.
For Investors and Strategic Acquirers: ECE R51 pass-by noise standard revisions reshape the acquisition landscape toward engineering houses with front-loaded simulation capabilities and regulatory submission expertise. Long-term viability centers on providers bridging physical testing heritage with digital twin methodologies. The signal to monitor is OEM procurement shifting from perpetual hardware purchases toward subscription-based engineering service contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces wind tunnel hours across electric SUV architectures, compressing development timelines for Volkswagen Group and BYD programs. |
| Simulation-as-a-Service Leasing | Expands mid-tier supplier access to enterprise-grade acoustic CAE without capital expenditure, reshaping procurement patterns. |
| Backward Integration into Transducer Manufacturing | Secures calibration IP and hardware margin capture for precision measurement heritage firms against cloud-native entrants. |
| Geographic Manufacturing Footprint Expansion | Localizes testing capabilities in India's PLI scheme corridors to capture first-mover advantage in emerging EV manufacturing. |
| Software-Defined Vehicle Investment | Integrates active noise cancellation algorithms with cabin electronics architectures, creating high-margin engineering engagements. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, acoustic testing facility operators, and aftermarket diagnostic specialists, and refined through secondary validation against vehicle production databases, IHS Markit registration data, EPA noise enforcement records, and ECE R51 type approval filings. Bottom-up triangulation across service type procurement volumes and top-down reconciliation against OEM R&D expenditure disclosures anchored market sizing.
Demand-supply balance framing structured the analytical approach across the analysis window, modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segment-level engineering spend intensity curves and platform proliferation timelines. Forecast inputs incorporated battery-electric platform share trajectories and regulatory pass-by noise limit tightening schedules without year-specific calibration.
Practitioners should monitor battery-electric platform rollout delays, tariff escalations on precision measurement equipment, and MIIT regulatory cycle accelerations for early signals of forecast deviation. Material shifts in OEM outsourcing propensity toward asset-light engineering partnerships would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Motorsports Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
GCC Car Wash Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Cab Services Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Car Washing Service Market
Automotive Services
Online Car-Hailing Service Market
Automotive Services
Automotive MRO Market