
 Singapore Car Rental Market | 2026-2036
Singapore Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Car Rental Market Analytics
Electric vehicle adoption is expanding across Singapore's rental fleets as battery technology improves total cost of ownership calculations for operators. Avis Budget Group anchors its position through airport-centric infrastructure at Changi, while Hertz Corporation differentiates via EV partnerships and charging network integration. Europcar Mobility Group leverages corporate account density in the CBD to sustain recurring revenue streams against seasonal tourism fluctuations.
Singapore car rental encompasses short-term vehicle access services spanning economy sedans to luxury automobiles, typically governed by commercial insurance frameworks and LTA roadworthiness certification. Operators maintain fleets with mandatory six-month inspection cycles under the Vehicle Inspection Scheme to ensure safety compliance for hirer protection. Economy vehicles and short-term rentals dominate transaction volume, yet luxury cars and long-term corporate leases capture disproportionate margin pools due to lower churn and bundled maintenance structures. Corporate clients represent the most stable demand segment, while airport delivery modes command premium positioning through convenience value capture.
The Land Transport Authority administers vehicle supply through Certificate of Entitlement auctions, directly inflating fleet acquisition costs and compressing independent operator margins. Singapore's Building and Construction Authority parking regulations and Urban Redevelopment Authority land-use zoning further constrain depot placement and vehicle storage economics in dense districts. Stakeholders must monitor LTA electrification timelines and COE price trajectories to calibrate fleet composition decisions against policy-driven cost shifts.
Market Dynamics
The Certificate of Entitlement auction mechanism administered by Singapore's Land Transport Authority compresses fleet acquisition economics and redirects demand toward rental substitutes as private ownership costs escalate beyond median household absorption capacity.
Growth Catalysts
- Corporate Fleet Outsourcing:Financial services and logistics firms are divesting owned vehicle assets to rental operators, converting fixed costs to variable structures under operational lease frameworks.
- Changi Airport Corridor Demand:Inbound tourism recovery and business travel concentration at Singapore's primary aviation hub sustain premium pricing for airport delivery services.
- Vehicle Quota System:The Land Transport Authority's bi-monthly COE auctions constrain private vehicle supply and channel displacement demand into short-term rental alternatives.
Market Restraints
- Certificate of Entitlement Price Volatility:Fleet acquisition costs fluctuate with auction outcomes, compressing operator margins and complicating multi-year lease pricing commitments.
- Depot Placement Constraints:Urban Redevelopment Authority land-use zoning and Building and Construction Authority parking regulations restrict vehicle storage economics in dense districts like the Central Business District.
- Public Transit Substitution:Mass Rapid Transit network expansion and ride-hailing platform density cap rental demand elasticity among price-sensitive consumer segments.
Strategic Opportunities
- Electric Vehicle Fleet Conversion:Land Transport Authority electrification timelines and charging infrastructure subsidies create first-mover positioning for operators aligning fleet composition with policy trajectories.
- Long-Term Corporate Leasing:Bundled maintenance structures and lower churn characteristics of multi-year contracts offer margin stability against seasonal tourism fluctuations.
- CBD Premium Positioning:Corporate account density in the Central Business District enables recurring revenue capture through convenience-focused service tiers.
Industry Challenges
- Six-Month Inspection Cycles:The Vehicle Inspection Scheme mandates impose operational coordination burdens and vehicle downtime costs across distributed fleet networks.
- COE Auction Timing Risk:Fleet replacement decisions require calibration against certificate price trajectories that resist short-term forecasting reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Car Rental Market |
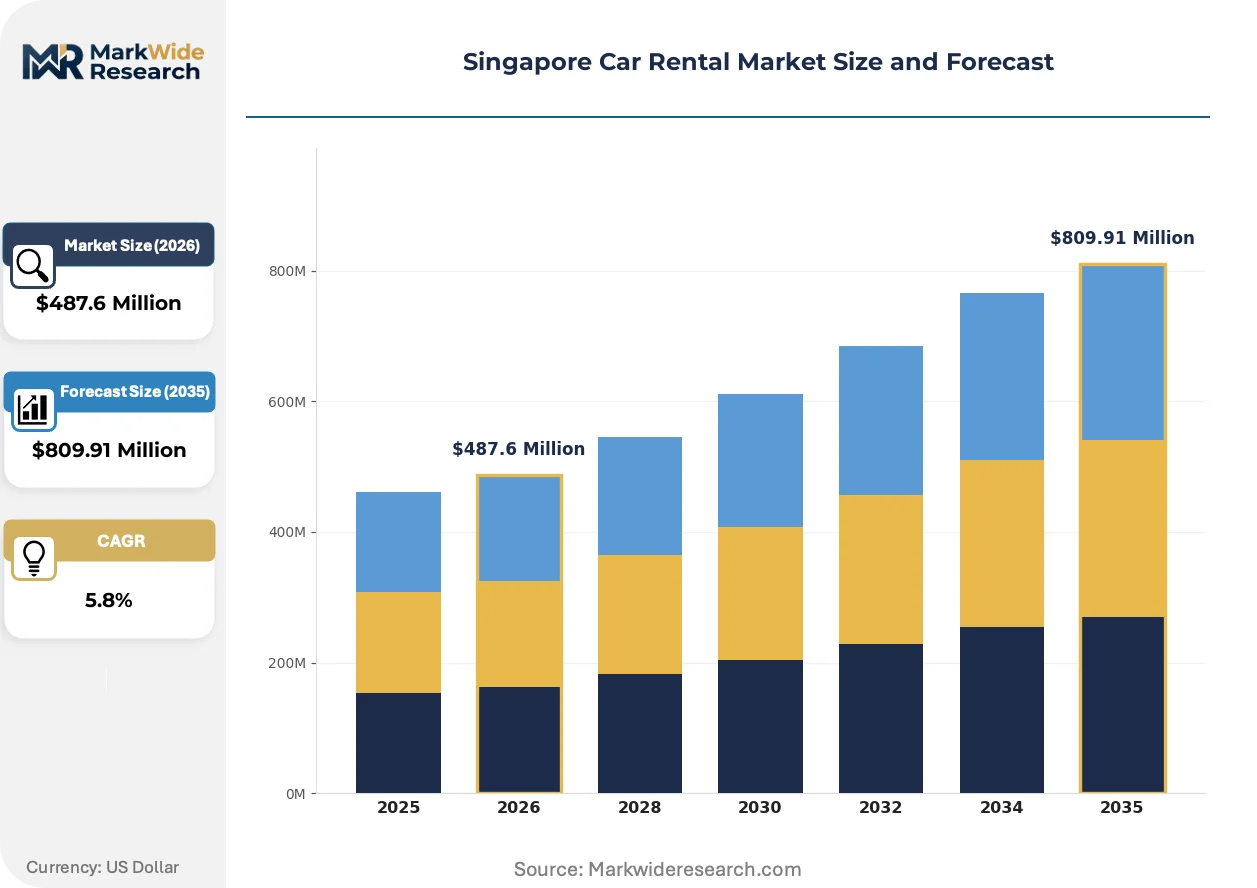
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Cars, SUV Rentals, Economy Vehicles, Vans Customer Type: Corporate Clients, Tourists, Local Residents, Event Organizers Duration: Short-Term Rentals, Long-Term Rentals, Weekly Packages, Daily Usage Delivery Mode: Pick-Up Stations, Home Delivery, Airport Delivery, Online Booking |
| Companies Covered | Europcar Mobility Group, Motorist Pte Ltd, Avis Budget Group, Ride Now, AKA Car Rental, Hertz Corporation, Drive SG Pte Ltd, TribeCar, Sixt SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Car Rental Market Evolving Landscape
Battery technology improvements and regulatory electrification mandates are rewriting fleet composition strategies across Singapore's rental sector, while procurement behaviors shift toward integrated mobility solutions.
Advanced battery chemistries are rewriting total cost of ownership calculations for electric vehicle fleet operators. Rental companies with Central Business District corporate accounts are accelerating EV adoption to capture sustainability procurement criteria. The technology is rewriting competitive positioning by enabling operators to differentiate through charging network integration rather than vehicle count alone.
The Land Transport Authority's electrification roadmap and COE category differentials for cleaner vehicles are compressing diesel fleet retention economics. Operators face accelerated depreciation exposure on internal combustion assets as certificate premiums for electric vehicle categories stabilize below conventional equivalents. Fleet managers are responding by front-loading EV procurement despite higher upfront capital requirements.
Subscription-based mobility packages are displacing transactional daily rentals among corporate procurement functions. Finance and logistics verticals are consolidating vendor relationships with operators offering integrated fleet management rather than vehicle-only provision. This pattern concentrates most visibly among multinational enterprises with Singapore regional headquarters demanding consolidated APAC mobility reporting.
Singapore Car Rental Market Segmentation
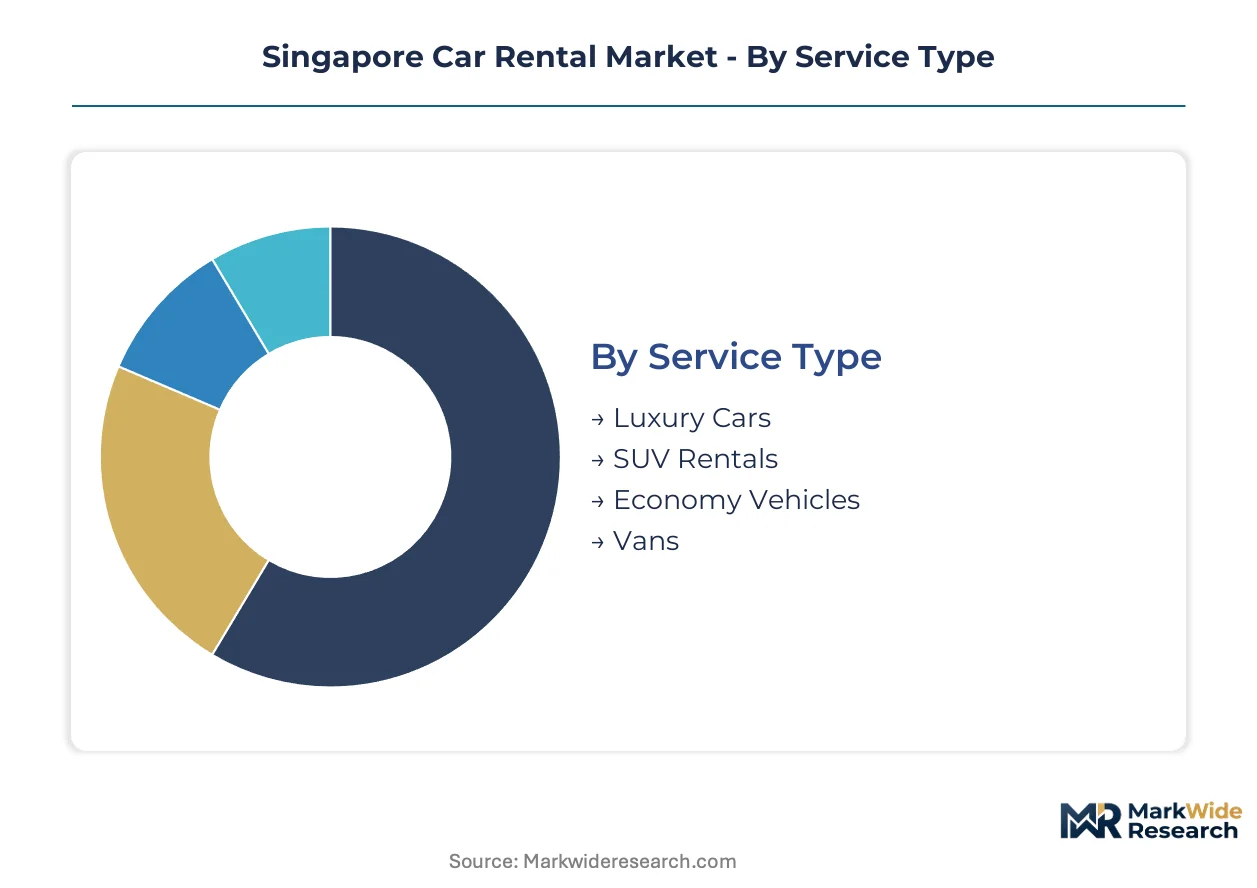
Singapore's car rental market fragments across service tiers, customer profiles, and delivery modalities that reflect the city-state's constrained vehicle ownership environment. Fleet composition and channel strategy must align with Certificate of Entitlement cost structures and Land Transport Authority electrification timelines.
Service Type:
Fleet supply concentrates disproportionately in economy and mid-market segments where volume absorption offsets COE acquisition premiums.
- Economy Vehicles:Compact sedans and hatchbacks dominate transaction frequency across Changi Airport corridors and suburban residential zones. Fleet operators deploy these units aggressively to capture displacement demand from private ownership aspirants priced out of COE auctions.
- Luxury Cars:Premium marques command extended booking windows from corporate entertainment budgets and high-net-worth transient residents. Marina Bay and Sentosa hospitality clusters sustain peak utilization during conference seasons and Formula 1 event periods.
- SUV Rentals:Multi-purpose vehicles address family mobility needs and commercial light-cargo requirements in warehouse districts. Operators position these units at fringe depots where parking economics permit larger fleet footprints.
- Vans:Commercial-grade vehicles serve logistics subcontracting and event logistics verticals with payload-focused specifications. Building and Construction Authority contractor licensing drives periodic demand spikes in construction corridors.
Today's leader: Economy Vehicles. Tomorrow's challenger: Luxury Cars.
Customer Type:
Margin stability varies sharply across customer acquisition channels, with recurring corporate relationships insulating operators from tourism volatility.
- Corporate Clients:Financial services and logistics firms convert fixed fleet assets to operational lease structures. These accounts deliver predictable utilization rates and bundled maintenance contracts that compress per-vehicle servicing overhead.
- Tourists:Inbound visitors from ASEAN and North Asian markets generate premium pricing at Changi Airport touchpoints. Seasonal concentration during school holiday periods creates capacity planning challenges for yield management systems.
- Local Residents:Households awaiting COE auction outcomes or managing temporary mobility gaps form the price-sensitive core of short-term demand. Mass Rapid Transit coverage expansion is eroding this segment's addressable base in central districts.
- Event Organizers:Conference producers and wedding planners generate episodic demand spikes with compressed lead times. Singapore Expo and Suntec City venue calendars drive predictable seasonal patterns for fleet pre-positioning.
Corporate Clients anchor current profitability. Tourists represent the steepest expansion trajectory as aviation capacity normalizes.
Duration:
Contract length directly determines maintenance bundling economics and vehicle turnover cadence across fleet planning horizons.
- Long-Term Rentals:Multi-month agreements spanning corporate relocations and expatriate housing transitions. These contracts amortize COE acquisition costs across extended utilization windows and minimize reconditioning frequency between hirers.
- Short-Term Rentals:Daily and weekend bookings dominate airport and hotel concierge channels. Yield management systems optimize pricing against real-time inventory and competitive positioning.
- Weekly Packages:Seven-day bundles target leisure travelers and temporary project staffing with modest duration discounts. Operators use these structures to improve utilization during mid-week troughs.
- Daily Usage:Single-day transactions concentrate in CBD corporate overflow and vehicle service substitution scenarios. Land Transport Authority's Vehicle Inspection Scheme downtime creates predictable demand spikes.
Long-Term Rentals secure margin stability. Short-Term Rentals scale revenue velocity.
Delivery Mode:
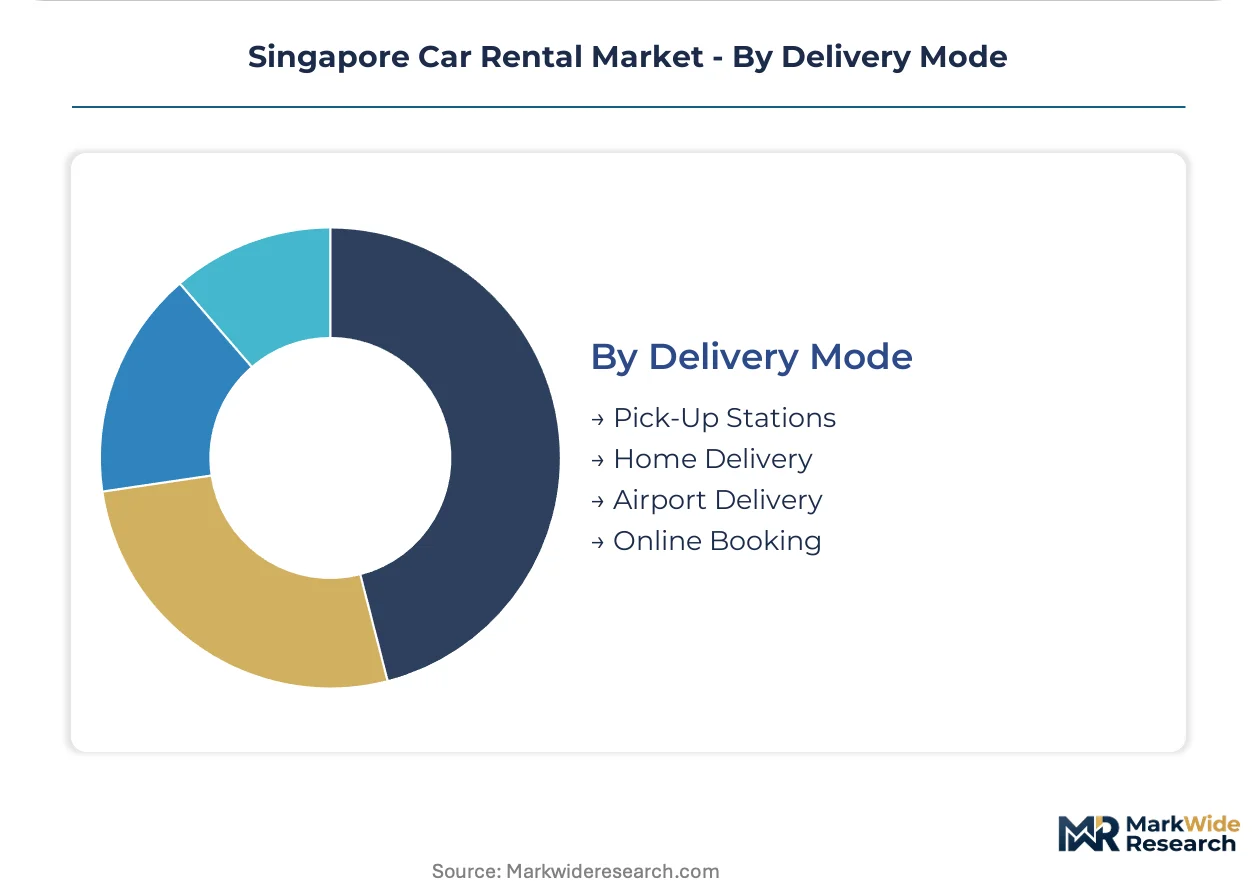
Channel configuration shapes customer acquisition costs and service differentiation in a market where physical depot placement faces zoning constraints.
- Airport Delivery:Changi Airport terminals one through four constitute the highest-value capture point for inbound business and leisure travelers. Premium positioning here commands convenience surcharges that offset parking and staffing costs.
- Pick-Up Stations:Central Business District and Orchard Road depots serve walk-in corporate and retail demand with limited vehicle storage. Urban Redevelopment Authority land-use restrictions compress feasible site footprints.
- Home Delivery:Concierge-style vehicle handoff at residential addresses addresses mobility-impaired and time-constrained segments. Last-mile logistics coordination imposes operational complexity on dispatch systems.
- Online Booking:Digital reservation platforms now dominate discovery and transaction completion across all customer types. Mobile application integration with Land Transport Authority's vehicle status databases is emerging as a competitive hygiene factor.
Airport Delivery commands current premium positioning. Online Booking is consolidating channel control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changi Airport anchors Singapore's car rental demand through its position as Southeast Asia's premier aviation hub, with the Central Business District forming a secondary concentration zone for corporate mobility services.
Central Business District
Financial services firms and multinational regional headquarters generate recurring corporate lease demand across Raffles Place and Marina Bay precincts. The Land Transport Authority's vehicle quota system through Certificate of Entitlement auctions constrains private ownership and channels displacement demand toward rental substitutes. Fleet operators position premium service tiers here to capture convenience-driven procurement from time-constrained executives.
Changi Airport Corridor
Inbound tourism recovery and business travel concentration sustain premium pricing for airport delivery services across terminals one through four. The Civil Aviation Authority of Singapore's aviation capacity expansion plans align with rental operator fleet positioning strategies. Ground transport service providers coordinate with airline loyalty programs to capture arriving passenger flows.
Orchard Road Retail Belt
Hotel concierge channels and shopping district visitors generate episodic short-term rental demand with compressed booking lead times. Urban Redevelopment Authority land-use zoning restricts depot placement economics in this dense commercial corridor. Operators deploy mobile delivery services to circumvent parking capacity constraints while maintaining service coverage.
Jurong Industrial Zone
Logistics subcontracting and manufacturing facility staffing drive commercial van and light truck rental requirements. The Building and Construction Authority's contractor licensing frameworks create periodic demand spikes across construction corridors. Fleet operators maintain fringe depot locations here where land economics permit larger vehicle storage footprints.
Sentosa Island Hospitality Cluster
Resort entertainment budgets and high-net-worth transient residents sustain luxury vehicle utilization during conference seasons and Formula 1 event periods. Sentosa Development Corporation's tourism promotion activities align with premium rental service positioning. Marina Bay hospitality precincts complement this demand through corporate entertainment vehicle procurement.
Singapore Car Rental Market Competitive Landscape
Global majors compete with regional champions across fleet scale and airport infrastructure access, producing a tiered market structure where international brands leverage brand recognition while local operators exploit regulatory familiarity and depot placement flexibility. The vendor base clusters around three strategic archetypes: airport-centric international networks, CBD-focused corporate lease specialists, and technology-enabled platform aggregators. Competitive dynamics center on fleet electrification timing and Certificate of Entitlement auction participation strategies rather than price-based rivalry alone.
Within the global network tier, Avis Budget Group and Hertz Corporation represent established international operators with Changi Airport infrastructure presence, while Europcar Mobility Group anchors the European-origin multinational segment. Among Singapore-based specialists, Motorist Pte Ltd and TribeCar exemplify platform-native competitors leveraging digital-first customer acquisition. These archetypes illustrate how market positioning diverges between asset-heavy fleet ownership models and technology-enabled marketplace intermediation.
| Leading Market Players |
|---|
| Europcar Mobility Group |
| Motorist Pte Ltd |
| Avis Budget Group |
| Ride Now |
| AKA Car Rental |
| Hertz Corporation |
| Drive SG Pte Ltd |
| TribeCar |
| Sixt SE |
| Others |
Value Network & Pricing Analysis
Family-owned depot operators with generational land holdings anchor Singapore's rental supply base, converting Certificate of Entitlement volatility into pricing power through fleet timing discipline and captive parking economics.
Pricing Analysis
Certificate of Entitlement auction premiums pass through directly to hirer rates with minimal lag, compressing operator margins during price spikes and enabling margin expansion when COE categories stabilize. Three-tier pricing structure across premium, standard, and economy levels segments by vehicle grade and delivery convenience, with airport delivery commanding the widest spreads. Pricing pressure stems from ride-hailing platform density and Mass Rapid Transit coverage expansion in central districts. Local residents awaiting COE outcomes exhibit the highest price sensitivity, while corporate procurement functions prioritize convenience over rate negotiation.
Supply Chain Analysis
Dual-sourcing requirements from multinational corporate accounts mandate fleet operators maintain relationships with at least two vehicle distributors to ensure model availability across COE auction cycles. Fleet acquisition draws from Japan, South Korea, and Germany for passenger vehicles, with commercial van supply concentrating on Japanese and European manufacturers. Battery supply for electric fleet conversion rests on South Korean and Chinese cell producers, exposing operators to logistics chokepoint risk through the Strait of Malacca. Distribution runs through Changi Airport terminals, CBD pick-up stations, and mobile concierge services to circumvent Urban Redevelopment Authority depot placement constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's car rental market functions as a stable compounder, with Land Transport Authority vehicle quota policy ensuring structural demand displacement from private ownership toward rental substitutes across economic cycles.
For Market Incumbents: Acquire fringe depot land parcels in Jurong and Tampines where Building and Construction Authority parking regulations permit larger fleet footprints. Consolidate charging infrastructure partnerships ahead of LTA electrification mandates to lock in first-mover positioning against platform-native entrants. Vertical integration into maintenance facilities compresses Vehicle Inspection Scheme downtime costs. For New Entrants and Emerging Players: Hotel concierge channels at Marina Bay and Sentosa hospitality clusters offer the most penetrable white-space for premium service tiers with compressed customer acquisition costs. Target event logistics verticals with episodic demand patterns that incumbent yield management systems underprice. Deploy subscription-based mobility packages to displace transactional daily rentals among finance sector procurement functions. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-heavy operators with aged fleet depreciation profiles and underutilized CBD depot licenses. Long-term viability hinges on electrification timing alignment with LTA policy trajectories and COE auction participation discipline. The signal to watch is Certificate of Entitlement category differentials for electric versus internal combustion vehicles as fleet replacement inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | Land Transport Authority subsidies and charging infrastructure grants reward early EV procurement against diesel depreciation exposure. |
| Corporate Lease Consolidation | Multinational regional headquarters demand integrated APAC mobility reporting from single-vendor relationships. |
| Airport Infrastructure Lock-in | Civil Aviation Authority of Singapore capacity expansion aligns fleet positioning with arriving passenger flow capture. |
| Subscription Mobility Packaging | Finance and logistics verticals convert fixed fleet assets to operational lease structures with bundled maintenance. |
| Depot Zoning Arbitrage | Urban Redevelopment Authority land-use restrictions create scarcity value for grandfathered parking licenses in dense districts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, corporate procurement managers at financial services firms, Land Transport Authority policy officers, and Changi Airport ground transport coordinators with secondary validation. Secondary sources included LTA vehicle registration databases, COE auction outcome records, Civil Aviation Authority passenger traffic statistics, and Urban Redevelopment Authority land-use zoning filings. Bottom-up fleet utilization modeling and top-down market sizing triangulated volume estimates.
Comparable-period anchoring calibrated the projection horizon against historical COE price trajectories, tourism recovery patterns, and corporate lease renewal cycles across the analysis window. Segmentation dimensions modeled encompass service tier, customer archetype, contract duration, and delivery channel alongside vehicle propulsion architecture as industry-specific forecast input. CAGRs derived from regression analysis of fleet expansion rates against displacement demand elasticity from private ownership constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Land Transport Authority electrification timeline adjustments and Certificate of Entitlement auction supply allocations. Deviation in COE premium trajectories or Mass Rapid Transit network completion schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Retail Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
US Car Wash Services Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Car Subscription Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Car Wash System Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Cab Services Market
Automotive Services
GCC Car Wash Market
Automotive Services
North America MRO Distribution Market
Automotive Services
United States Automotive Service Market