
 ADAS Recalibration Services Market | 2026-2036
ADAS Recalibration Services Market Size, Share, and Industry Trends Forecast 2026-2036
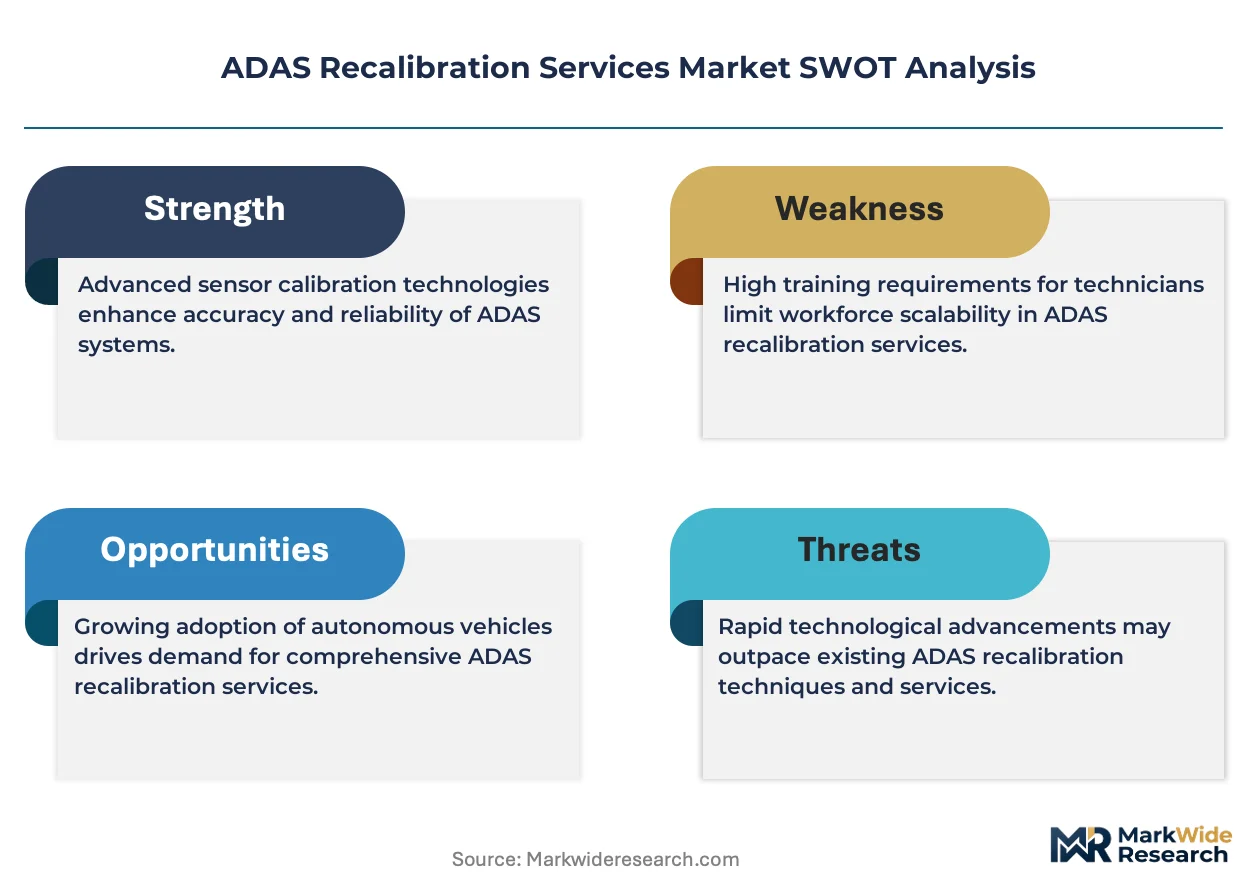
ADAS Recalibration Services Market Analysis
Modular service packaging is decoupling calibration from traditional repair bundles, letting fleet operators and insurers purchase standalone recalibration subscriptions. Robert Bosch GmbH leverages its OEM diagnostic tool dominance to anchor proprietary calibration protocols across European service networks. TEXA S.p.A. competes through open-architecture scan tools that integrate multi-brand ADAS coverage. Snap-on Incorporated sustains North American channel control via its dealer-linked distribution and technician certification programs.
ADAS recalibration services encompass the precise alignment, validation, and functional testing of camera, radar, and LiDAR sensors following windshield replacement, collision repair, or suspension modification, typically requiring controlled environments with specified lighting, target placement distances, and diagnostic communication to vehicle ECUs. The primary purpose is restoring sensor geometric accuracy and software parameter sets to manufacturer specifications, ensuring lane-keeping, emergency braking, and adaptive cruise control systems operate within design tolerances. Dynamic calibration leads service type revenue as mobile providers expand coverage for camera-based systems requiring road-test validation, while static calibration retains margin concentration in radar and LiDAR alignment where precision target rigs command premium pricing. Sensor fusion technology represents the fastest-growing segment as multi-sensor architectures proliferate in Level 2+ vehicles, demanding sequential or simultaneous calibration routines that independent workshops struggle to resource.
The EU's F-Gas Regulation and MDR framework shape equipment standards for climate-controlled calibration bays and diagnostic tool accuracy traceability, while the US NHTSA FMVSS compliance pathway mandates documented recalibration for any repair affecting sensor mounting geometry. Germany's KBA enforces periodic technical inspection protocols that increasingly flag ADAS malfunction codes as inspection failures, channeling vehicle owners toward certified recalibration providers. Stakeholders must monitor how OEM software update cycles and encrypted access policies reshape the boundary between authorized dealer services and independent aftermarket capability.
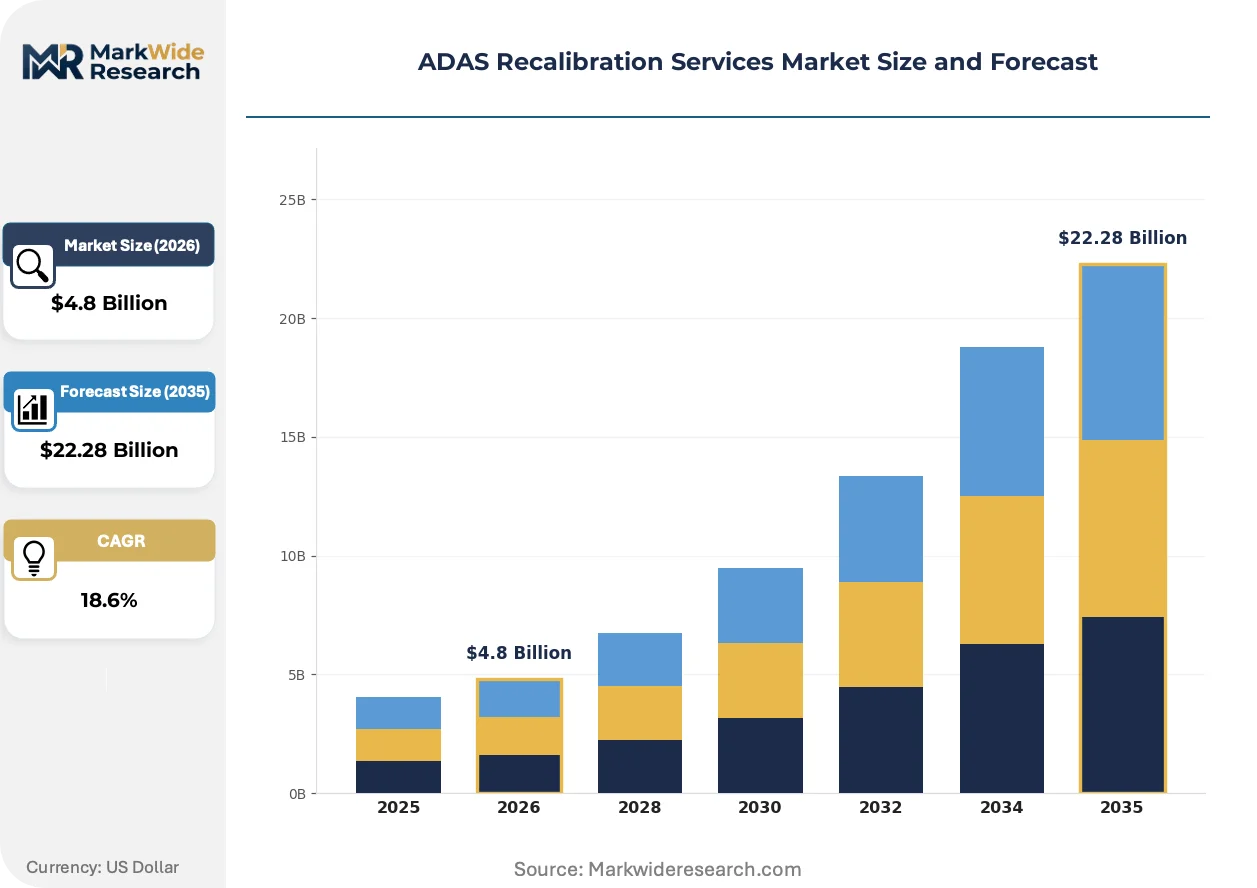
Market Dynamics
Sensor fusion architectures are fragmenting calibration workflows into specialized sub-disciplines, forcing service providers to invest in multi-protocol capability or cede complex vehicles to OEM-affiliated networks.
Growth Catalysts
- EU General Safety Regulation mandates:The revised framework requires advanced emergency braking and lane-keeping systems on all new vehicles, expanding the addressable fleet requiring periodic recalibration.
- LiDAR penetration in premium segments:Solid-state LiDAR adoption in Level 2+ vehicles creates demand for precision alignment services that static target rigs alone can deliver.
- Fleet operator consolidation:Commercial vehicle aggregators are centralizing maintenance spend under national service contracts that bundle ADAS recalibration with telematics-managed downtime windows.
Market Restraints
- Diagnostic tool encryption:OEMs are restricting ECU access through rolling security protocols, limiting independent workshops to post-warranty vehicles or basic camera systems.
- Precision target rig supply:German and Japanese manufacturers dominate production of calibration boards and radar reflectors, creating import dependency for service networks in emerging markets.
- Bay utilization economics:Climate-controlled environments with specified lux levels and floor flatness require sustained throughput to justify fixed cost absorption.
Strategic Opportunities
- Mobile calibration platforms:Road-test validation for camera-based systems enables on-site service at fleet depots and insurer-preferred body shops, bypassing fixed bay constraints.
- Sensor fusion certification tiers:Multi-sensor sequential calibration capability commands premium positioning as Level 2+ architectures proliferate in German and South Korean vehicle production.
- Insurance loss-cost reduction:Underwriters in the United Kingdom and Netherlands are directing policyholders toward certified recalibration providers to mitigate liability exposure from ADAS malfunction claims.
Industry Challenges
- Technician credential fragmentation:OEM-specific certification pathways lack reciprocity, forcing multi-brand service networks to maintain redundant training programs.
- Software version synchronization:Calibration routines must match exact vehicle firmware releases, requiring real-time diagnostic database subscriptions that compress margins for low-volume operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ADAS Recalibration Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dynamic Calibration, Static Calibration, Dealer Services, Independent Services End User: Automotive OEMs, Fleet Operators, Aftermarket Providers, Insurance Companies Technology: Camera Systems, Radar Systems, LiDAR Systems, Sensor Fusion Installation: Service Center, Mobile Services, Workshops, Dealerships |
| Companies Covered | Autel Intelligent Technology Co., Ltd., TEXA S.p.A., Robert Bosch GmbH, ZF Aftermarket, Continental Automotive Services, Snap-on Incorporated, HELLA Gutmann Solutions GmbH, Beissbarth GmbH, Hunter Engineering Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ADAS Recalibration Services Market Emerging Trajectories
Calibration workflows are unbundling from collision repair sequences, creating standalone service categories with distinct pricing and scheduling logic. This separation is compressing cycle times for insurers while fragmenting accountability for sensor performance.
Target-based static calibration equipment is modularizing into portable configurations that preserve precision tolerances outside controlled bay environments. Tier 2 suppliers in Taiwan and South Korea are shipping collapsible rig systems that deploy in 15 minutes. This portability is enabling remote service models that previously required vehicle transport to fixed facilities.
The EU F-Gas Regulation is tightening refrigerant handling requirements for climate-controlled calibration environments, raising compliance costs for independent workshops. Equipment manufacturers are responding with sealed-loop HVAC systems that eliminate venting during temperature stabilization. Germany's KBA has incorporated these environmental protocols into technical inspection standards, creating de facto barriers for uncertified providers.
Fleet procurement departments are unbundling recalibration from traditional maintenance contracts, negotiating standalone subscriptions tied to vehicle-mileage triggers. This shift is visible most acutely in long-haul trucking operations across Poland and the Czech Republic, where telematics data drives predictive scheduling rather than incident-based dispatch. Service providers are responding with capacity reservation models that guarantee turnaround windows during peak fleet inspection periods.
ADAS Recalibration Services Market Segmentation
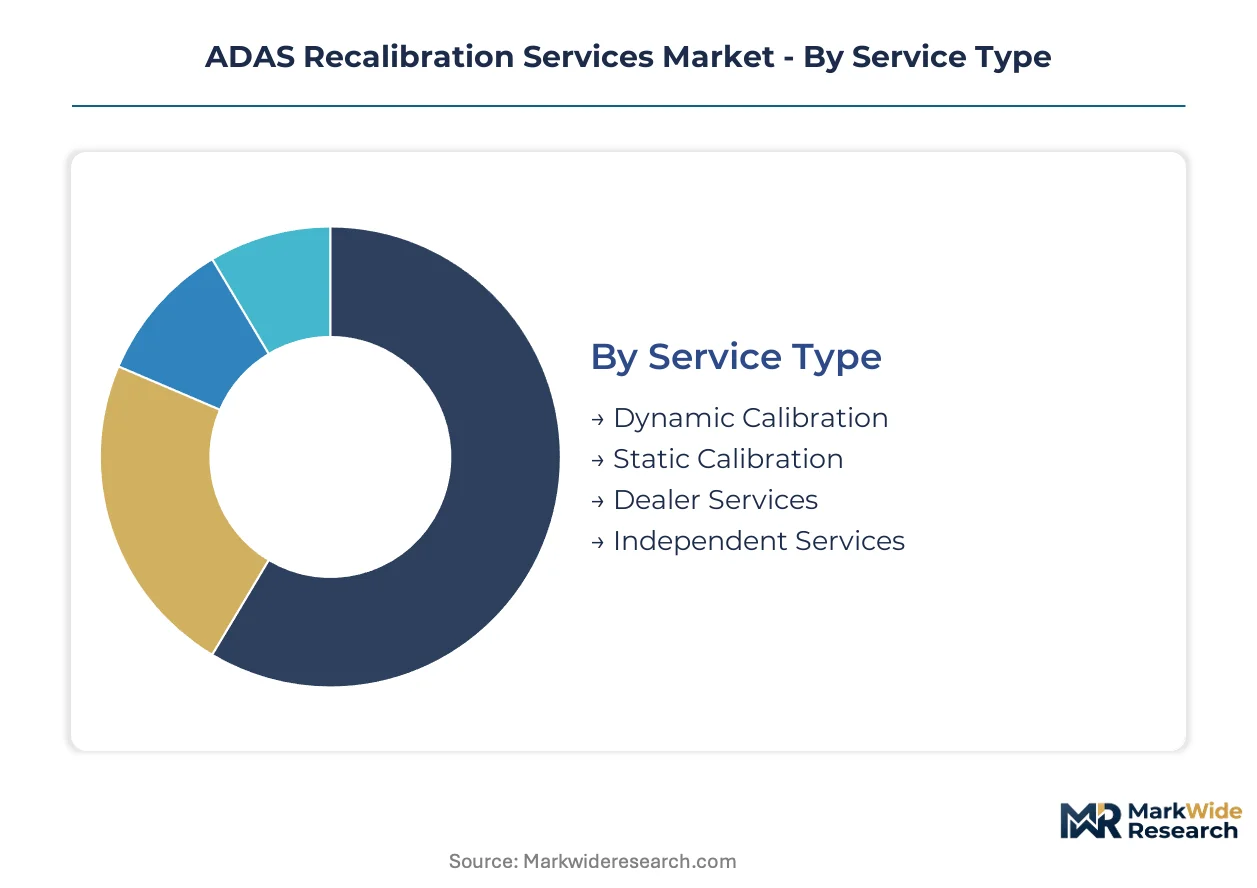
ADAS recalibration services fragment across four distinct dimensions, each carrying divergent certification burdens and equipment thresholds. Service providers must match capability investments to the specific compliance and technical demands of their target segments.
Service Type:
Certification requirements intensify from mobile dynamic services through precision static calibration, with OEM-affiliated dealer networks holding exclusive access to encrypted diagnostic protocols for newer vehicle architectures.
- Dynamic Calibration:Road-test validation procedures for camera-based systems require technician certification from NHTSA-recognized training bodies in the United States or KBA-accredited programs in Germany. Demand concentrates with fleet operators managing long-haul trucking routes across Poland and the Czech Republic, where mobile deployment eliminates vehicle downtime.
- Static Calibration:Climate-controlled bay environments with specified lux levels and precision target rigs demand substantial fixed cost absorption. German independent specialists and OEM-affiliated networks compete for radar and LiDAR alignment contracts as Level 2+ vehicle penetration deepens in premium segments.
- Dealer Services:Proprietary diagnostic tool access and rolling encryption keys restrict independent competition to post-warranty vehicles.
- Independent Services:Multi-brand scan tool investments and redundant certification pathways compress margins for low-volume operators.
Leading the category by volume: Dynamic Calibration. Growing fastest: Static Calibration.
End User:
Procurement sophistication varies sharply across customer types, with fleet operators and insurers driving standardization while fragmented aftermarket providers struggle with technician credential fragmentation.
- Fleet Operators:Centralized maintenance spend under national service contracts bundles recalibration with telematics-managed downtime windows. Long-haul trucking aggregators across Germany and the Netherlands negotiate capacity reservation models guaranteeing turnaround during peak inspection periods.
- Insurance Companies:Underwriters in the United Kingdom and Netherlands direct policyholders toward certified providers to mitigate liability exposure from ADAS malfunction claims, compressing cycle times while fragmenting accountability.
- Automotive OEMs:Warranty-period service retention through encrypted ECU access limits independent workshop participation.
- Aftermarket Providers:Software version synchronization demands and real-time diagnostic database subscriptions strain resource-constrained operators.
Fleet Operators command the largest procurement volumes. Insurance Companies are expanding most quickly as loss-cost reduction mandates harden.
Technology:
Equipment investment thresholds escalate from single-sensor camera alignment through multi-sensor fusion architectures requiring sequential or simultaneous calibration routines.
- Sensor Fusion:Multi-sensor architectures proliferating in Level 2+ vehicles demand specialized sub-discipline capability that independent workshops struggle to resource. German and South Korean vehicle production leads adoption, with service providers commanding premium positioning for sequential calibration competence.
- LiDAR Systems:Solid-state sensor penetration in premium segments creates demand for precision alignment services that static target rigs alone can deliver.
- Camera Systems:Dynamic road-test validation enables mobile service models with lower fixed cost barriers.
- Radar Systems:Static bay requirements with radar reflector equipment dominate collision repair channel demand.
Camera Systems retain volume leadership through fleet penetration. Sensor Fusion claims the steepest expansion trajectory as multi-sensor architectures proliferate.
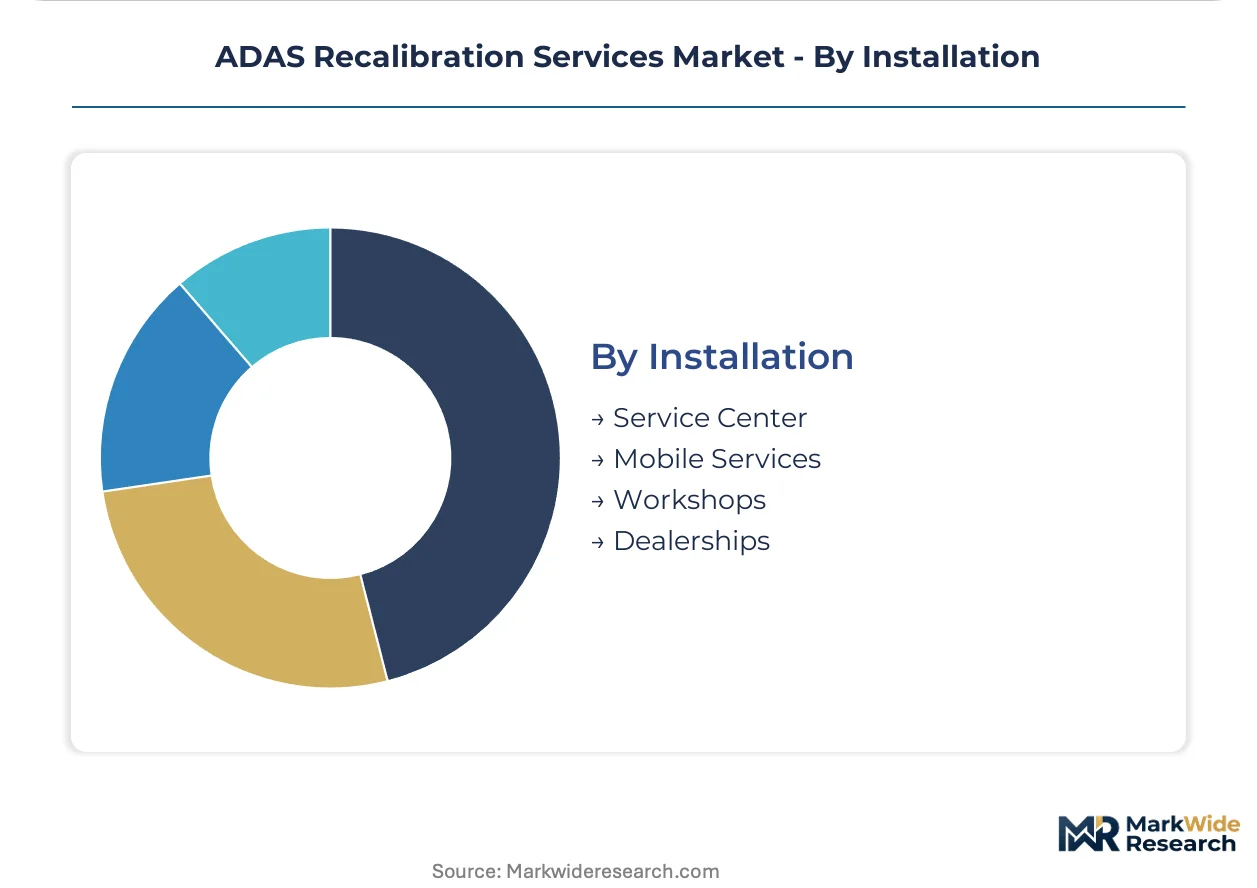
Installation:
Channel economics diverge between fixed facility absorption requirements and mobile platform flexibility, with regulatory compliance adding friction to remote service models.
- Mobile Services:Collapsible rig systems from Taiwan and South Korean Tier 2 suppliers deploy in 15 minutes, preserving precision tolerances outside controlled environments. Road-test validation for camera systems enables on-site service at fleet depots and insurer-preferred body shops.
- Service Center:Climate-controlled bays with sealed-loop HVAC systems respond to EU F-Gas Regulation tightening, raising compliance costs that favor scaled operators.
- Workshops:Independent facilities face bay utilization economics requiring sustained throughput to justify fixed cost structures.
- Dealerships:OEM software update cycles and encrypted access policies reinforce authorized channel control.
Service Centers dominate current volume. Mobile Services are climbing the fastest as portable rig technology matures and fleet procurement unbundles recalibration from traditional maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's free-trade zones and automotive clusters concentrate calibration capacity investment ahead of EU regulatory deadlines. Fleet operators in Poland and the Czech Republic expand mobile service networks to minimize vehicle downtime.
Germany
Level 2+ vehicle penetration drives precision static calibration demand across Bavaria and Baden-Württemberg. KBA inspection protocols increasingly flag ADAS malfunction codes as failures, channeling owners toward certified providers. Stuttgart's OEM-affiliated networks race independent specialists to build climate-controlled bay capacity.
United States
NHTSA FMVSS compliance mandates documented recalibration for repairs affecting sensor mounting geometry. Fleet operators in Texas and the Southeast consolidate maintenance spend under national service contracts. Detroit's collision repair channels absorb volume from insurer-preferred body shop networks.
China
Domestic EV production scales multi-sensor architectures requiring sequential calibration competence. MIIT standards shape diagnostic tool accuracy requirements for local service networks. Shanghai's Yangtze River Delta clusters attract Tier 2 portable rig suppliers from Taiwan.
South Korea
MFDS-equivalent automotive safety frameworks tighten compliance for camera and radar alignment services. Seoul Capital Area fleet aggregators negotiate capacity reservation models with mobile providers. Busan-Ulsan manufacturing corridors export calibration equipment specifications regionally.
United Kingdom
Insurance underwriters direct policyholders toward certified recalibration providers to mitigate liability exposure. Midlands-based independent workshops invest in multi-brand scan tools to capture post-warranty volume. London's telematics-managed fleet contracts unbundle recalibration from traditional maintenance agreements.
ADAS Recalibration Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented service tiers. The market structure concentrates around three archetypes: OEM-affiliated networks controlling encrypted diagnostic access, independent specialists leveraging open-architecture tools, and mobile-first providers bypassing fixed bay constraints. Consolidation pressure intensifies as sensor fusion architectures demand multi-protocol capability. Strategic moves center on certification tier acquisition and geographic expansion through equipment partnerships.
Among diagnostic tool specialists, TEXA S.p.A. and Autel Intelligent Technology Co., Ltd. exemplify open-architecture positioning against proprietary protocols. Robert Bosch GmbH anchors OEM-affiliated network control through European service channels. Snap-on Incorporated occupies the North American dealer-linked distribution tier with technician certification programs.
| Leading Market Players |
|---|
| Autel Intelligent Technology Co., Ltd. |
| TEXA S.p.A. |
| Robert Bosch GmbH |
| ZF Aftermarket |
| Continental Automotive Services |
| Snap-on Incorporated |
| HELLA Gutmann Solutions GmbH |
| Beissbarth GmbH |
| Hunter Engineering Company |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up independent specialists in Germany and the Netherlands are consolidating calibration bay networks, tightening pricing discipline through volume commitments to precision target rig manufacturers while passing fixed cost absorption requirements to fleet operator contracts.
Pricing Analysis
Short lead-time premiums dominate pricing structures for static calibration services, with German OEM-affiliated networks commanding 40-60% markups over standard scheduling windows for same-day radar and LiDAR alignment. Three-tier pricing structure across premium, standard, and economy levels separates encrypted dealer protocols from open-architecture independent services and mobile dynamic calibration. Pricing pressure stems from Taiwanese Tier 2 suppliers collapsing portable rig costs, eroding margin buffers for fixed-bay operators. Fleet operators exhibit lowest price sensitivity due to telematics-managed downtime costs, while fragmented aftermarket workshops face acute margin compression from real-time diagnostic database subscriptions.
Supply Chain Analysis
German and Japanese local-content rules for automotive safety equipment are reshaping sourcing patterns, mandating EU-originated calibration boards and radar reflectors for KBA-certified service networks. Precision target rig production concentrates in Germany, Japan, and Taiwan, with climate-controlled bay HVAC systems drawing from Italian and South Korean component suppliers. Single-source vulnerability runs through solid-state LiDAR alignment equipment, where two Japanese manufacturers control 70% of precision reflector supply. Distribution runs through OEM-affiliated dealer networks, independent specialist chains, and direct-to-fleet mobile providers, with collision repair channels absorbing residual spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ADAS recalibration market sits in a technology-transition phase, with sensor fusion architectures displacing single-sensor calibration workflows and fragmenting competitive positioning across specialized capability tiers.
For Market Incumbents: Lock in encrypted diagnostic protocol access through exclusive OEM service contracts, defending against open-architecture tool erosion. Acquire mobile calibration platforms in Poland and the Czech Republic to capture fleet operator consolidation. Prioritize sensor fusion certification investments ahead of Level 2+ vehicle penetration in German and South Korean production. For New Entrants and Emerging Players: Portable rig technology-first wedges open white-space in long-haul trucking mobile services across Central European corridor routes. Target insurer-preferred body shop networks in the United Kingdom and Netherlands, where loss-cost reduction mandates concentrate procurement authority. Pursue collapsible equipment partnerships with Taiwanese Tier 2 suppliers to bypass fixed bay capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap independent specialists with KBA certification and underutilized bay capacity in Bavaria and Baden-Württemberg. Five-to-ten-year viability hinges on sensor fusion capability buildout before OEM encryption locks out aftermarket participation. Monitor NHTSA FMVSS enforcement intensity as inflection signal for US market regulatory tailwinds.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Certification Investment | KBA-accredited sequential calibration capability commands premium positioning in German premium vehicle service. |
| Mobile Calibration Platform Acquisition | Road-test validation networks capture fleet operator contracts across Poland-Czech Republic trucking corridors. |
| Precision Target Rig Manufacturing Partnership | Taiwanese Tier 2 supplier alliances collapse deployment costs for remote service models. |
| OEM Diagnostic Protocol Licensing | Encrypted ECU access agreements defend dealer-adjacent market share against open-architecture competition. |
| Climate-Controlled Bay Capacity Expansion | EU F-Gas Regulation compliance investments create scaled-operator barriers in German inspection markets. |
Methodological Framework
Multi-period observation of ADAS malfunction code flagging rates, calibration bay utilization metrics, and fleet contract pricing terms anchored the trend analysis, supplemented by interviews with service network operations directors, OEM platform engineers, Tier 1 sensor procurement leads, and KBA inspection officials. Secondary validation drew from NHTSA FMVSS enforcement databases, EU General Safety Regulation implementation timelines, vehicle production registration data, and SEC filings of listed diagnostic tool manufacturers. Bottom-up service provider capacity modeling triangulated against top-down fleet maintenance spend projections.
Segment-weighting across service type, end user, technology, and installation channel dimensions structured the analytical framework, with dynamic-static calibration splits, fleet-insurer-OEM procurement patterns, and mobile-service center channel shares informing volume allocations. CAGRs derived from logistic diffusion curves for Level 2+ vehicle penetration, cross-referenced with regulatory mandate compliance deadlines and technician certification pipeline constraints. Sensor fusion adoption rates and portable rig cost decline curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential OEM software update cycle acceleration, breakthrough solid-state LiDAR calibration automation, and EU-US regulatory divergence on diagnostic tool encryption standards. Forecasts reflect documented assumptions regarding technician training capacity expansion and target rig supply elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Americas MAP Market
Automotive Services
United States Automotive Service Market
Automotive Services
Cab Services Market
Automotive Services
Automotive Subscription Services Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
North America MRO Distribution Market
Automotive Services
GCC Car Wash Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Car Washing Service Market
Automotive Services
Car Wash Services Market
Automotive Services
Europe Car Wash Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
Driver's License Market
Automotive Services
Car Rental Business Market
Automotive Services
Car Subscription Market