
 Automotive Digital Assistant Market | 2026-2036
Automotive Digital Assistant Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Assistant Market Outlook
Premium natural-language processing tiers is bifurcating the competitive landscape into cockpit experience leaders and commodity voice vendors. NVIDIA leverages its GPU-accelerated AI platforms to dominate training infrastructure for multimodal automotive assistants. Cerence sustains its position through deep specialization in proprietary speech recognition engines tuned for in-vehicle acoustic environments. Bosch competes via backward integration into sensor hardware that feeds contextual data streams into assistant logic layers.
An automotive digital assistant constitutes an embedded software system that processes voice commands, biometric inputs, and vehicle telemetry through natural-language understanding algorithms to execute navigation, climate, entertainment, and safety functions. These systems typically operate with sub-200-millisecond response latency and integrate with CAN bus architectures for real-time vehicle control. Voice recognition solutions anchor current revenue pools due to their maturity in OEM specification sheets, while sensor fusion technology represents the fastest-expanding segment as automakers merge cabin monitoring with predictive assistance. Fleet operators emerge as a concentrated demand node where operational efficiency metrics justify premium assistant licensing fees.
NHTSA guidelines in the United States and EU AI Act risk-classification rules in Europe compel assistant vendors to document decision transparency and fail-safe behaviors for driver-attention applications. Japan's METI has issued connected-vehicle data governance standards that shape how cloud-connected assistants handle cross-border telemetry. Stakeholders must decide whether to build compliant architectures for each regulatory jurisdiction or pursue modular certification frameworks that adapt to divergent safety and privacy mandates.
Market Dynamics
The automotive digital assistant sector is bifurcating around multimodal sensor fusion architectures, as premium OEMs race to integrate cabin monitoring with predictive assistance while legacy voice-only systems face commoditization pressure.
Growth Catalysts
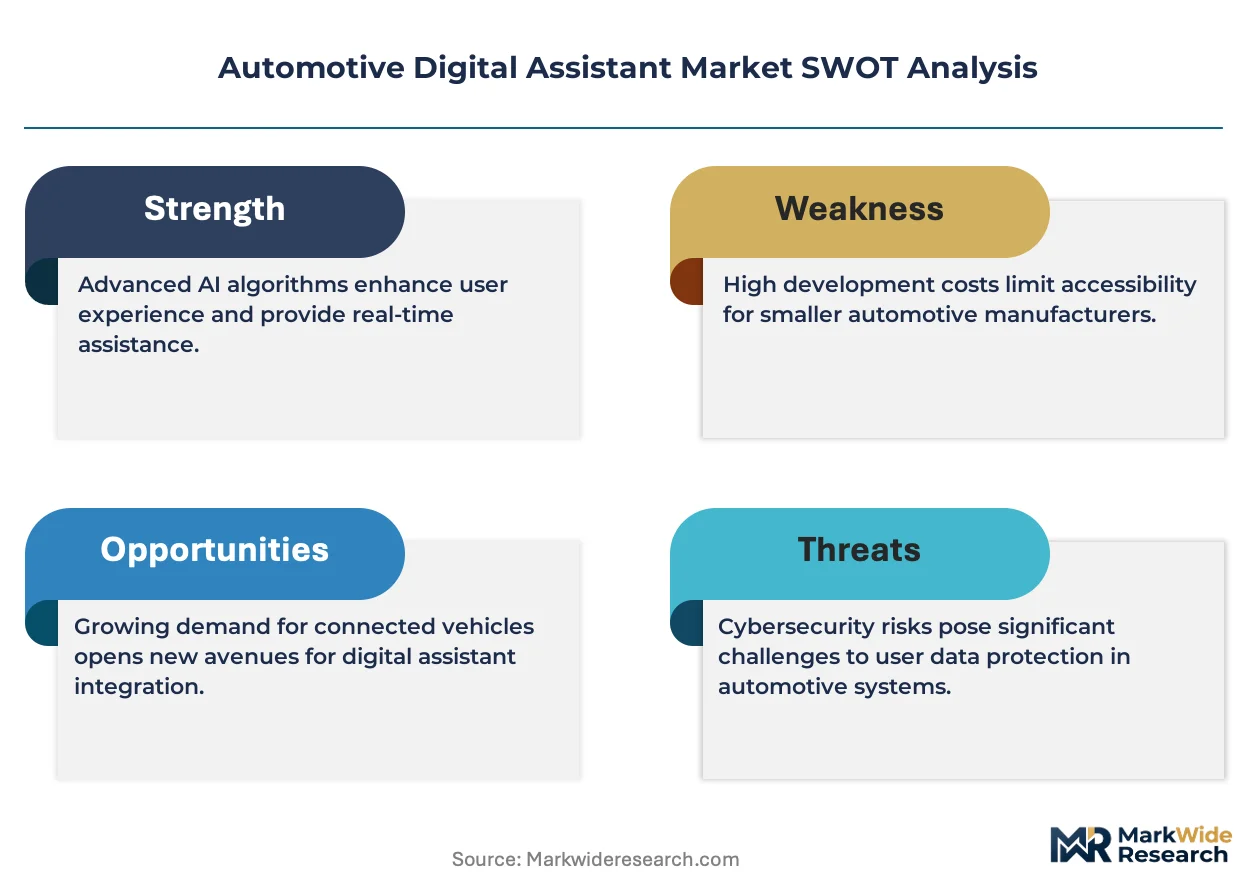
- EU AI Act compliance mandates:Risk-classification rules for driver-attention systems are forcing OEMs to upgrade assistant transparency and fail-safe documentation, accelerating replacement cycles for non-compliant legacy platforms.
- Fleet operator operational efficiency metrics:Commercial vehicle managers are licensing premium assistant tiers to reduce driver distraction incidents and optimize route coordination through voice-activated dispatch systems.
- Sub-200-millisecond latency benchmarks:Edge computing integration with CAN bus architectures is enabling real-time vehicle control responses that satisfy safety-critical application requirements.
Market Restraints
- GPU training infrastructure concentration:NVIDIA's dominance in automotive AI compute substrates creates supply bottleneck risks for assistant vendors without captive silicon access or alternative accelerator partnerships.
- Cross-border telemetry governance friction:Japan's METI connected-vehicle data standards impose architectural constraints on cloud-connected assistants handling transnational data flows, complicating single-platform deployment strategies.
- Acoustic environment specialization costs:Proprietary speech recognition tuning for in-cabin noise profiles requires sustained R&D expenditure that commodity voice vendors cannot amortize across thin-margin deployments.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Domestic manufacturing incentives are creating localized production hubs for assistant hardware modules serving South Asian OEM supply chains.
- Biometric input convergence:Integration of driver fatigue detection with voice command systems is opening new safety-assistance revenue streams in long-haul commercial segments.
- Subscription-based feature unlocking:OEMs are piloting post-sale assistant capability activation, transforming one-time licensing into recurring service revenue across vehicle lifecycles.
Industry Challenges
- NHTSA documentation timelines:Decision transparency requirements for driver-attention applications are extending certification cycles and compressing product launch windows.
- Multimodal sensor fusion integration complexity:Harmonizing camera, radar, and biometric data streams with legacy infotainment architectures demands specialized systems engineering talent that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Assistant Market |
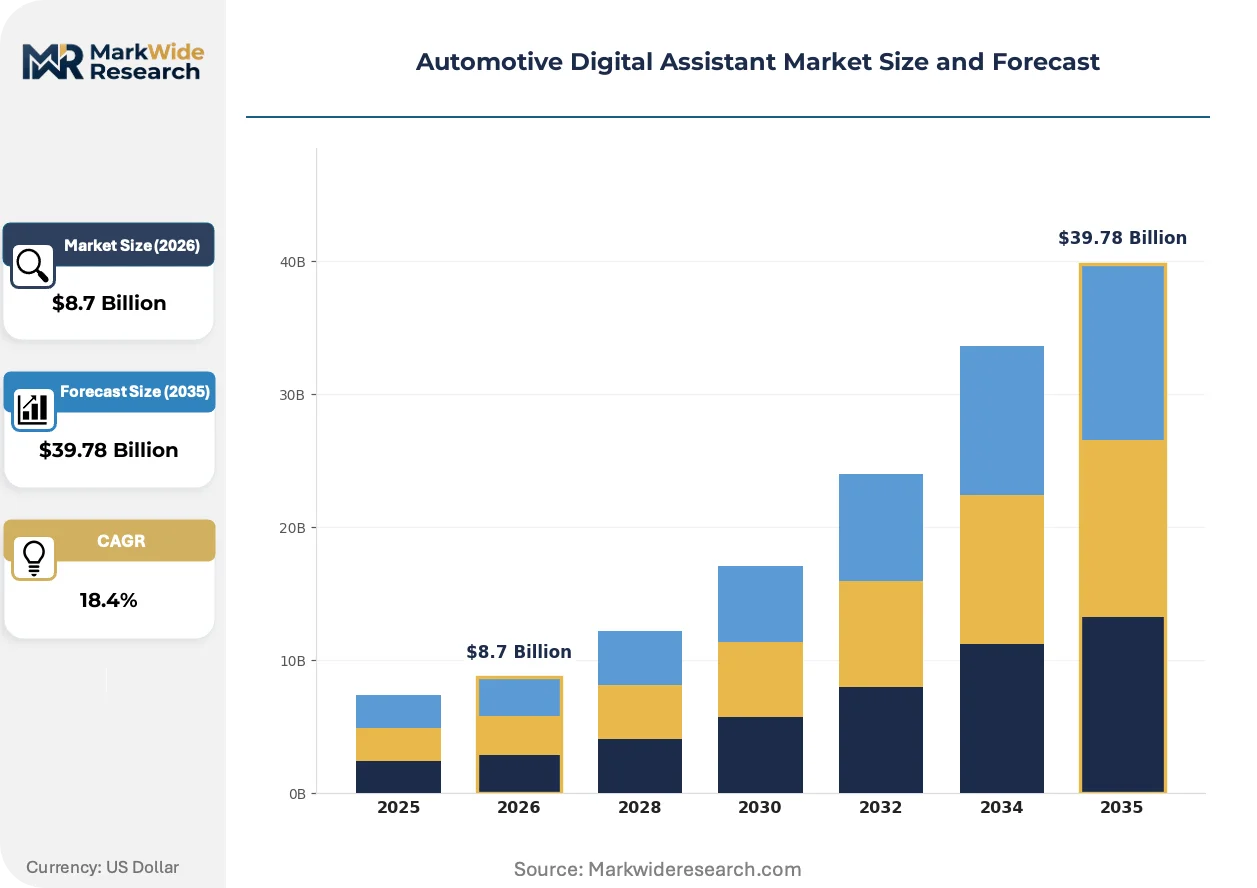
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Voice Recognition, Chatbot Interface, Navigation Assistance, Remote Control End User: OEMs, Aftermarket Providers, Fleet Operators, Automotive Tech Startups Application: In-Car Assistance, Driver Safety, Navigation, Entertainment Management Technology: AI Algorithms, Machine Learning, Cloud Connectivity, Sensor Fusion |
| Companies Covered | NVIDIA, Qualcomm Technologies, Continental, Bosch, Cerence, Harman International Industries, Aptiv, DENSO, Visteon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Assistant Market Strategic Shifts
Multimodal architectures are actively displacing voice-isolated systems as the defining competitive frontier, with regulatory transparency mandates and fleet procurement evolution accelerating the transition timeline.
Edge-based neural inference engines are supplanting cloud-dependent processing for latency-sensitive safety functions. Tier 1 suppliers are embedding TensorRT-optimized models directly into cockpit domain controllers to satisfy sub-200-millisecond response requirements for emergency interventions. This shift is compressing data sovereignty risks and reducing ongoing connectivity cost burdens for OEMs.
The EU AI Act's risk-classification framework is mandating algorithmic audit trails for driver-monitoring assistants. Vendors must now document decision pathways and fail-safe behaviors to obtain CE marking for high-risk applications. German premium OEMs are responding by segregating safety-critical assistant functions into independently certifiable software modules.
Fleet procurement patterns are pivoting from bundled infotainment packages toward standalone assistant licensing with operational KPI guarantees. Logistics operators in the United States are negotiating usage-based contracts tied to measurable driver distraction reduction. This unbundling is fragmenting traditional tiered pricing structures and elevating outcome verification capabilities as a vendor selection criterion.
Automotive Digital Assistant Market Segmentation
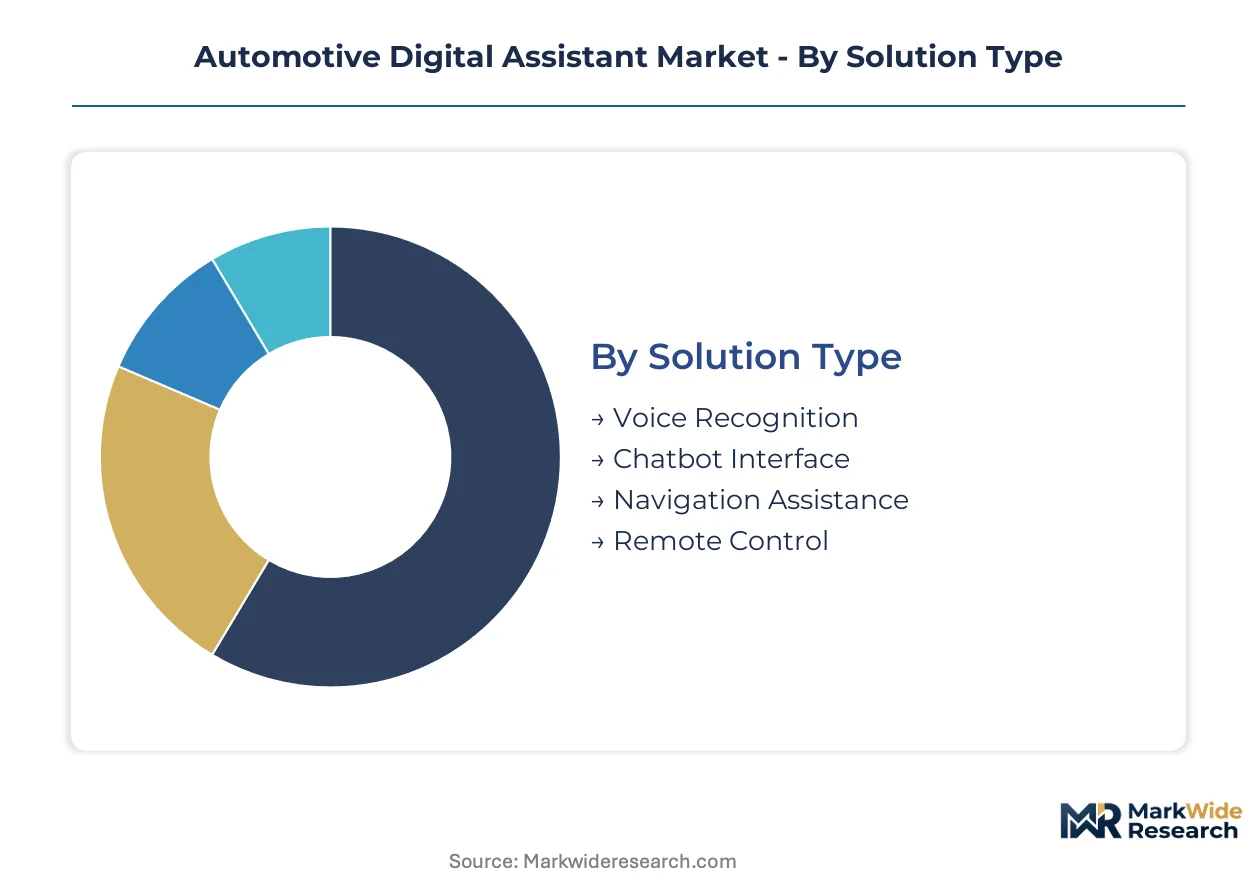
Automotive digital assistant segmentation reflects divergent certification burdens and deployment architectures across solution tiers. Regulatory risk-classification rules reshape how vendors position capabilities against compliance costs and performance benchmarks.
Solution Type:
EU AI Act risk tiers and NHTSA documentation requirements concentrate investment in latency-sensitive, safety-critical solution categories while commoditizing legacy voice-only offerings.
- Voice Recognition:Mature acoustic processing engines with proprietary noise-canceling algorithms tuned for cabin reverberation profiles. German premium OEMs specify sub-200-millisecond response benchmarks for navigation and climate commands, locking in specification dominance despite thin-margin pressure from cloud API alternatives.
- Navigation Assistance:Real-time route optimization fused with predictive traffic telemetry and voice-activated point-of-interest retrieval. Fleet operators in the United States negotiate outcome-based contracts tied to measurable fuel efficiency gains and driver distraction reduction metrics.
- Chatbot Interface:Conversational AI layers handling multi-turn dialogue for vehicle feature discovery and troubleshooting.
- Remote Control:Smartphone-integrated preconditioning and status monitoring via encrypted telemetry channels.
Established volume favors voice recognition; emerging adoption favors navigation assistance.
End User:
Procurement authority and integration complexity separate captive OEM programs from fragmented aftermarket channels.
- Fleet Operators:Concentrated demand nodes licensing premium assistant tiers with operational KPI guarantees. United States logistics managers negotiate usage-based contracts tied to driver safety incident reduction, unbundling assistants from bundled infotainment packages.
- OEMs:Vertical integration of assistant software into cockpit domain controllers with CAN bus architecture access. Japanese and German manufacturers embed multimodal sensor fusion as flagship differentiators, absorbing certification costs across high-volume vehicle lines.
- Aftermarket Providers:Retrofit voice modules for legacy vehicle parc without factory embedded connectivity.
- Automotive Tech Startups:Niche subscription-based feature unlocking pilots transforming one-time licensing into recurring revenue.
Procurement concentration favors fleet operators; margin expansion favors OEM captive programs.
Application:
Functional criticality determines edge computing allocation and regulatory scrutiny intensity.
- Driver Safety:Biometric fatigue detection merged with predictive intervention triggers. Edge-based neural inference engines process camera and radar streams locally to satisfy sub-200-millisecond emergency response requirements under EU AI Act high-risk classification rules.
- In-Car Assistance:Climate, lighting, and seat adjustment via natural-language commands. German OEMs segregate safety-critical functions into independently certifiable software modules to streamline CE marking pathways.
- Navigation:Route guidance with voice-activated destination entry and real-time traffic integration.
- Entertainment Management:Media selection and audio streaming control through conversational interfaces.
Regulatory tailwinds favor driver safety; volume scale favors in-car assistance.
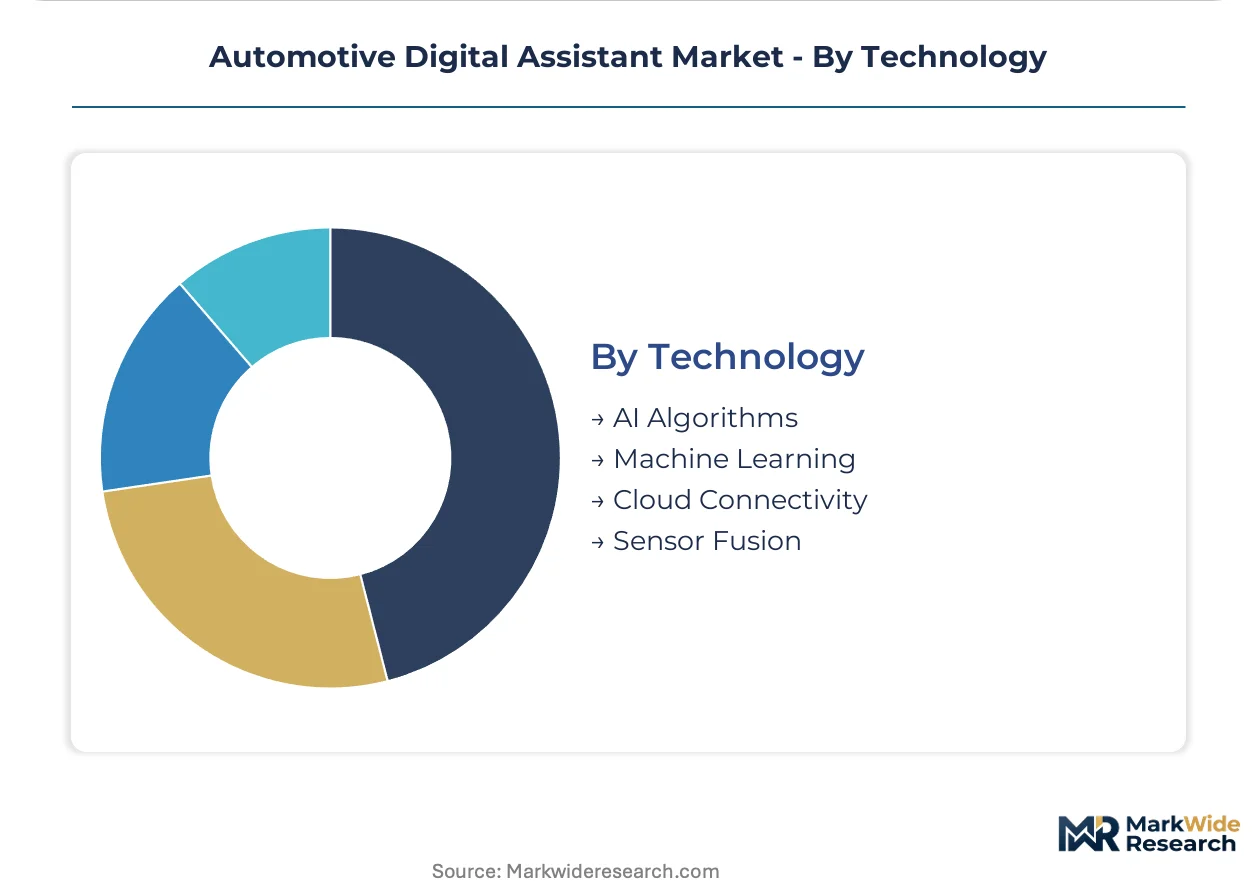
Technology:
Processing architecture choices determine latency profiles, data sovereignty exposure, and ongoing connectivity economics.
- Sensor Fusion:Harmonized camera, radar, and biometric data streams enabling predictive assistance. Tier 1 suppliers embed TensorRT-optimized models directly into cockpit domain controllers, climbing the fastest as premium OEMs race to integrate cabin monitoring with proactive safety interventions.
- AI Algorithms:Natural-language understanding and intent classification engines. NVIDIA GPU-accelerated platforms dominate training infrastructure, creating supply bottleneck risks for vendors without captive silicon access.
- Machine Learning:Continuous model refinement from fleet telemetry and driver interaction patterns.
- Cloud Connectivity:Over-the-air updates and voice processing offload for non-latency-sensitive functions.
Edge migration favors sensor fusion; infrastructure concentration constrains AI algorithm deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NVIDIA's GPU-accelerated training infrastructure concentrates supply-side leverage in the United States, while German premium OEMs and Japanese tier-1 suppliers anchor demand for multimodal cockpit systems. Regulatory divergence across jurisdictions is fragmenting deployment architectures.
United States
Fleet operators in Michigan and Texas negotiate outcome-based contracts tied to driver distraction reduction metrics. NHTSA guidelines extend certification cycles for driver-attention applications. Silicon Valley clusters host edge computing development for sub-200-millisecond latency benchmarks.
Germany
Premium OEMs in Stuttgart and Munich embed sensor fusion as flagship differentiators. EU AI Act risk-classification rules mandate algorithmic audit trails for high-risk driver-monitoring functions. Bavaria's automotive electronics corridor absorbs certification costs across high-volume vehicle lines.
Japan
Tier-1 suppliers in Nagoya integrate multimodal assistants into cockpit domain controllers. METI connected-vehicle data governance standards constrain cross-border telemetry flows. Kanto region clusters specialize in CAN bus architecture integration for real-time vehicle control.
China
Domestic OEMs in Shanghai and Shenzhen pilot subscription-based feature unlocking models. MIIT standards shape local processing requirements for voice and biometric data. Pearl River Delta manufacturing hubs produce assistant hardware modules for regional supply chains.
India
PLI scheme incentives attract automotive electronics manufacturing to Gujarat and Tamil Nadu. Domestic OEM supply chains source localized assistant hardware modules. Karnataka's tech corridor hosts software development centers for natural-language processing engines.
Automotive Digital Assistant Market Competitive Environment
Concentration sits with GPU-accelerated AI platform providers and proprietary speech recognition specialists. The vendor base stratifies across three tiers: silicon substrate owners, acoustic engine specialists, and sensor-integrated tier-1 suppliers. Dominant competitive moves include strategic partnerships for training infrastructure access and backward integration into sensor hardware for contextual data streams.
Among semiconductor-focused platform providers, NVIDIA and Qualcomm Technologies exemplify the silicon-owner archetype through control over automotive AI compute substrates. Cerence occupies a position within the acoustic specialization tier, representing vendors with sustained R&D expenditure in cabin-specific noise profile tuning. Continental and Bosch anchor the integrated tier-1 segment, exemplifying suppliers that merge sensor hardware production with assistant software layers.
| Leading Market Players |
|---|
| NVIDIA |
| Qualcomm Technologies |
| Continental |
| Bosch |
| Cerence |
| Harman International Industries |
| Aptiv |
| DENSO |
| Visteon |
| Others |
Value Chain & Pricing Dynamics
Ninety-day GPU allocation lead times concentrate pricing power with silicon substrate owners while forcing assistant vendors toward alternative accelerator partnerships or captive silicon strategies. This inventory dynamic tightens margins for acoustic engine specialists and tier-1 integrators lacking upstream compute access.
Pricing Analysis
The EU AI Act dictates the pricing tier structure by stratifying assistant capabilities across high-risk certification grades. Three-tier pricing structure across premium, standard, and economy levels separates safety-critical multimodal systems with algorithmic audit trails from commodity voice-only modules. Cost compression in the standard tier intensifies because cloud API alternatives erode proprietary speech recognition premiums. Fleet operators exhibit lowest price sensitivity due to operational KPI guarantees, while aftermarket providers face acute margin pressure from thin-margin retrofit deployments.
Supply Chain Analysis
Taiwan foundry capacity for automotive-grade GPUs constrains training infrastructure availability for multimodal assistant development. Supply concentrates in the United States for NVIDIA's AI compute platforms, Germany for Bosch's sensor hardware, and Japan for DENSO's cockpit domain controllers. Raw material dependencies span advanced node semiconductors, automotive-grade camera modules, and CAN bus interface chipsets. Single-source vulnerability runs through NVIDIA's GPU training infrastructure dominance. Distribution runs through tier-1 supplier direct OEM programs with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based feature unlocking layers expand faster than embedded hardware licensing, transforming one-time assistant sales into recurring service revenue streams across vehicle lifecycles. This service-attach dynamic elevates software monetization capabilities above pure hardware shipment metrics.
For Market Incumbents: Compound defensive moats through backward integration into sensor hardware and captive GPU allocation agreements that secure training infrastructure access. NVIDIA's silicon dominance threatens acoustic specialists with supply exclusion; Cerence must deepen proprietary noise-canceling R&D while Bosch leverages in-house radar production for contextual data streams. Certification investment in EU AI Act compliance modules creates switching costs that lock OEM relationships. For New Entrants and Emerging Players: Differentiate on edge-based neural inference latency benchmarks below 200 milliseconds for safety-critical applications. India's PLI scheme manufacturing incentives offer the most penetrable geography for localized hardware module production. Target fleet operator outcome-based contracts with driver distraction reduction guarantees as the go-to-market angle, unbundling from OEM captive programs. For Investors and Strategic Acquirers: Carve-out targets emerge from tier-1 supplier assistant software divisions lacking standalone recurring revenue infrastructure. Long-term viability hinges on subscription attach rates exceeding hardware replacement cycles. Watch for METI data governance standard harmonization with EU AI Act frameworks as the inflection signal for cross-platform scalability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Hardware Backward Integration | Bosch's radar production feeds contextual data streams directly into assistant logic layers. |
| Edge Computing Latency Optimization | TensorRT-optimized models embedded in cockpit domain controllers satisfy NHTSA emergency response benchmarks. |
| EU AI Act Compliance Modularization | German OEMs segregate safety-critical functions into independently certifiable software modules for CE marking. |
| Fleet Operator Outcome-Based Licensing | United States logistics managers negotiate usage contracts tied to measurable driver distraction reduction. |
| Subscription Feature Unlocking Pilots | Chinese OEMs in Shenzhen transform one-time licensing into recurring service revenue across vehicle lifecycles. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, tier-1 supplier procurement leads, fleet operations managers, and automotive electronics R&D directors; and secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from semiconductor suppliers, and EU AI Act implementation guidance documents. Bottom-up triangulation across assistant content per vehicle estimates and top-down market sizing from OEM specification sheets converged on segment-level projections.
Across the projection horizon, the analytical framework modeled segmentation dimensions including solution type, end-user procurement authority, application functional criticality, and processing architecture choices. CAGRs derived from OEM platform rollout timelines, fleet replacement cycles, and regulatory compliance phase-in schedules. Industry-specific forecast inputs incorporated GPU training infrastructure availability constraints and METI cross-border telemetry governance friction.
Forecasts assume regulatory continuity in EU AI Act risk-classification enforcement and NHTSA driver-attention documentation timelines; material policy shifts would require re-modeling certification burden impacts on replacement cycle acceleration. Practitioners should keep alternative scenarios live as edge computing cost curves and fleet electrification penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Singapore Car Rental Market
Automotive Services
Automotive Register Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Parking Services Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Automotive MRO Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Vehicle Subscription Market
Automotive Services
Europe Car Wash Market
Automotive Services
GCC Car Wash Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Electric Vehicle Repair Service Market