
 Powertrain Testing Market | 2026-2036
Powertrain Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Powertrain Testing Market Analysis
ISO 15118-20 vehicle-to-grid communication certification is collapsing the supplier base for high-voltage powertrain validation, forcing test houses to retool for bidirectional charging interoperability. AVL leverages its integrated toolchain spanning simulation to physical dynamometry, sustaining dominance across European OEM programs. Horiba anchors emission testing workflows in Japan and extends its footprint through exhaust measurement systems that comply with evolving pollutant protocols. Ricardo competes on specialized consulting-led test programs for motorsport-derived hybrid architectures.
Powertrain testing encompasses dynamometer-based validation, environmental simulation, and software-in-the-loop verification of propulsion systems spanning internal combustion, electric motor, and fuel cell architectures. Test cells subject hardware to thermal cycling, torque ripple characterization, and efficiency mapping across rotational speeds exceeding 20,000 rpm for electric drive units. Emission testing commands mature margin pools in Europe and North America as regulatory stringency sustains demand for particulate and NOx measurement, while electric powertrain testing represents the fastest-growing category as OEMs validate motor-inverter-battery integration. Durability testing retains structural importance for hybrid systems where mechanical and electrical stress cycles intersect.
EPA certification rules in the United States and Euro 7 standards advanced by the European Commission are reshaping test protocols, mandating real-driving emission monitoring and expanded particle number counting that force capital expenditure on new measurement hardware. China's MIIT enforces GB standards for new energy vehicle powertrains, creating a parallel compliance track for foreign suppliers accessing domestic OEM programs. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to maintain region-specific test assets or pursue unified platforms capable of multi-standard certification.
Market Dynamics
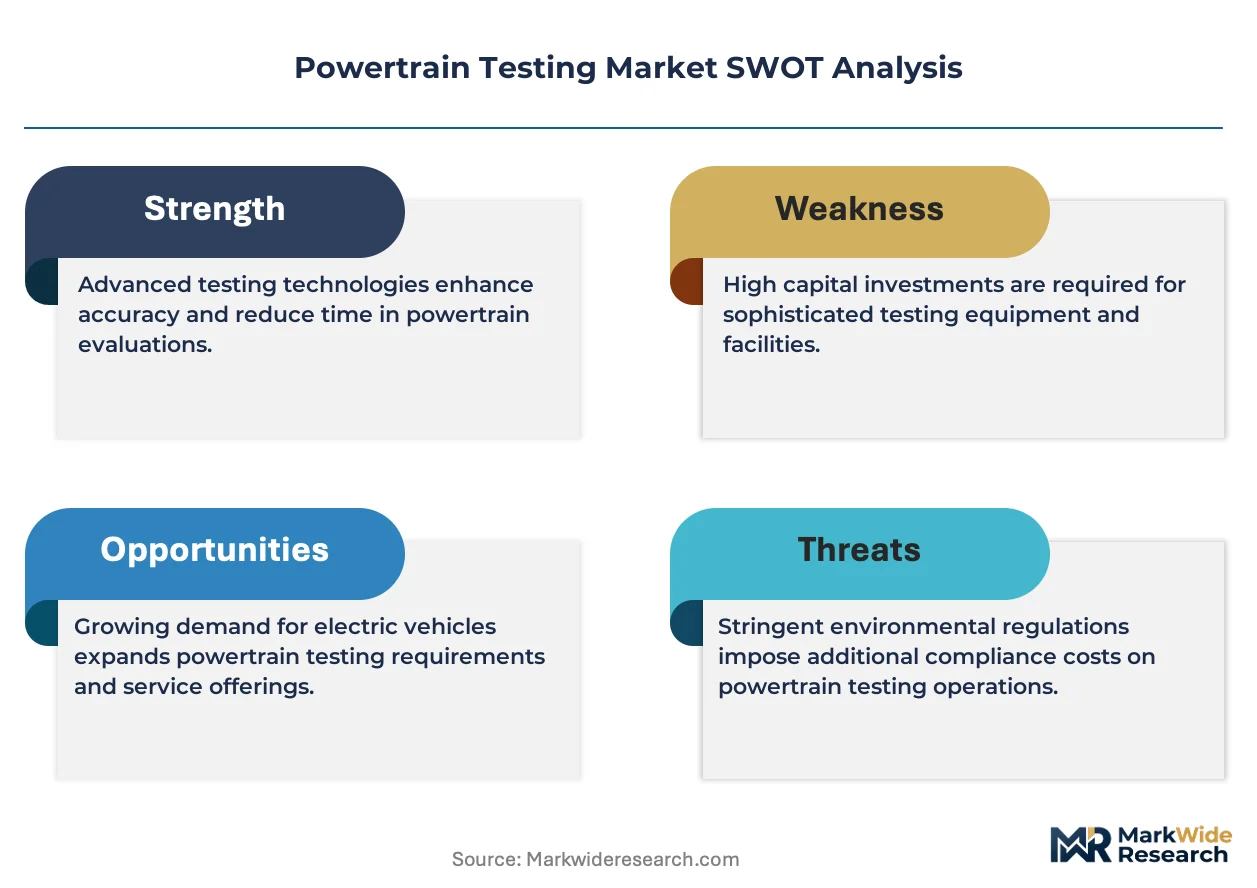
ISO 15118-20 certification for bidirectional charging is compressing the supplier base for high-voltage validation, forcing test houses to retool for vehicle-to-grid interoperability while maintaining legacy internal combustion programs.
Growth Catalysts
- Euro 7 emission standards:The European Commission's tightened particulate and NOx counting mandates sustained capital deployment toward exhaust measurement hardware across German and Italian test facilities.
- Electric motor-inverter-battery integration:OEM validation programs for 800V architectures expanded test cell throughput requirements for torque ripple characterization above 20,000 rpm.
- China's MIIT GB standards:Domestic new energy vehicle certification created parallel compliance tracks that pulled foreign test equipment suppliers into joint ventures with Shanghai and Beijing laboratories.
Market Restraints
- High-voltage safety infrastructure:Test cell retrofitting for 1500V battery packs demanded arc-flash containment and isolation transformers that doubled facility capital intensity.
- Specialized dynamometer supply:Precision torque measurement systems for electric drive units concentrated among Japanese and German component suppliers, creating procurement bottlenecks.
- Real-driving emission monitoring:Portable emission measurement systems imposed hardware costs and calibration complexity that strained mid-size test house margins.
Strategic Opportunities
- Fuel cell commercial vehicle programs:Heavy-duty hydrogen powertrain validation remained underdeveloped relative to battery-electric testing, opening white space for specialized environmental simulation.
- Software-in-the-loop verification:Virtual powertrain validation converged with physical dynamometry, enabling test houses to sell hybrid simulation-physical service bundles.
- EPA Tier 3 rule alignment:Unified test platforms capable of simultaneous Euro 7 and EPA certification reduced asset duplication for multinational OEM programs.
Industry Challenges
- High-voltage technician certification:Qualified engineers capable of 1000V+ system troubleshooting commanded wage premiums that compressed test house labor models.
- Multi-standard platform integration:Simultaneous compliance with China's MIIT protocols, EPA rules, and Euro 7 requirements forced software architecture complexity into test automation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powertrain Testing Market |
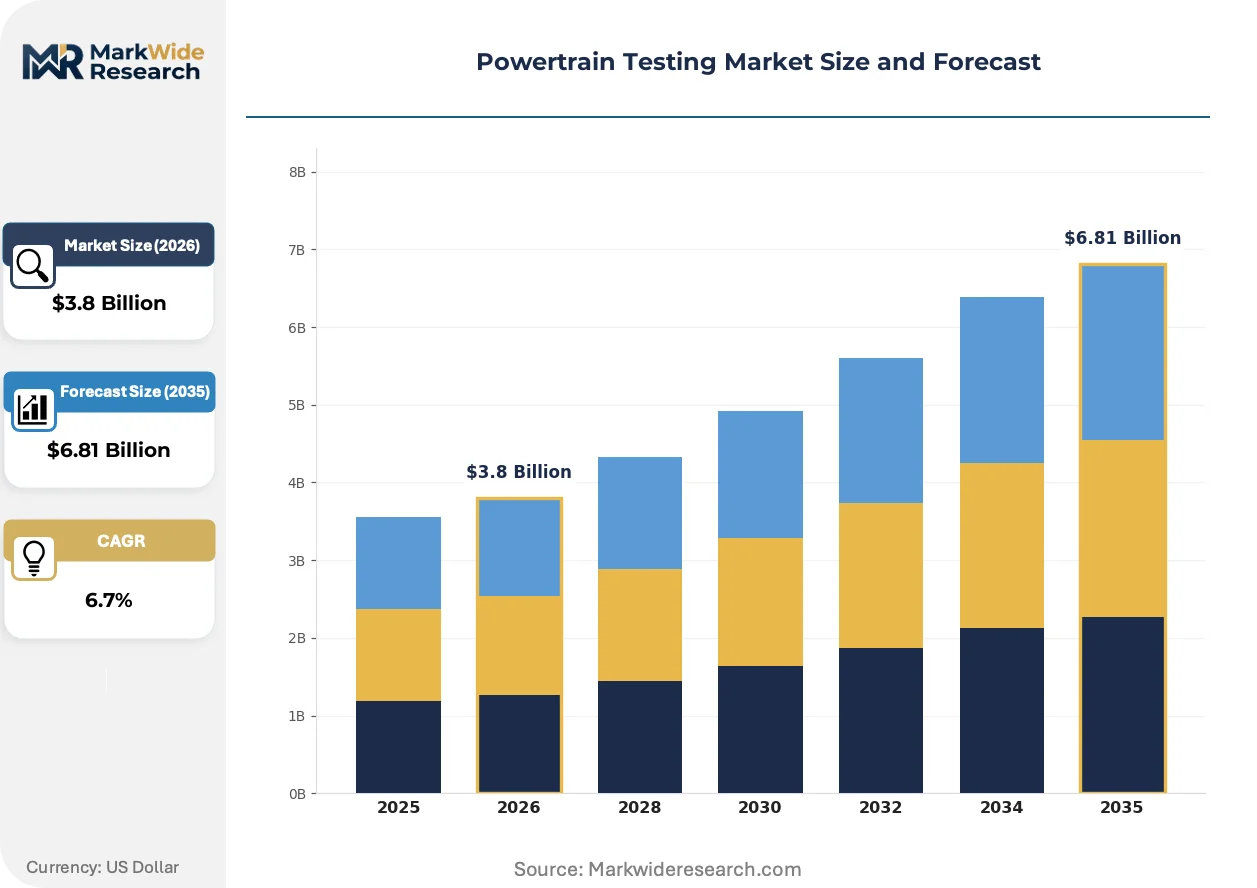
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: Durability Testing, Performance Testing, Emission Testing, Noise Testing Powertrain Type: Internal Combustion Engine, Electric Powertrain, Hybrid Powertrain, Fuel Cell Application: Automotive, Aerospace, Marine, Industrial End User: OEMs, Tier-1 Suppliers, Research Institutions, Aftermarket Providers |
| Companies Covered | AVL, FEV, Horiba, IAV, Atesteo, Applus, ThyssenKrupp, Ricardo, TÜV SÜD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powertrain Testing Market Emerging Trajectories
Powertrain testing is splitting into parallel tracks: physical hardware validation for certification and virtual verification for development speed, with the boundary between them actively contested.
Hardware-in-the-loop test benches is bifurcating the validation workflow. Battery-electric OEMs in Germany and California deploy these systems for inverter control algorithm verification before physical dynamometer commitment. The technology compresses development cycles by months while reducing energy consumption at test facilities.
EPA's expanded real-driving emission monitoring requirements forced test houses to deploy portable measurement hardware across on-road routes. The rule compresses laboratory-centric business models and privileges facilities with mobile certification capabilities. European test providers responded by acquiring telematics integration specialists.
After-sales service unbundling is fragmenting the traditional test house relationship. OEM procurement teams now separate validation program management from physical test execution, awarding simulation and analysis to engineering consultancies while reserving dynamometer time through spot-market platforms. This pattern concentrates in North American and German automotive R&D clusters.
Powertrain Testing Market Segmentation
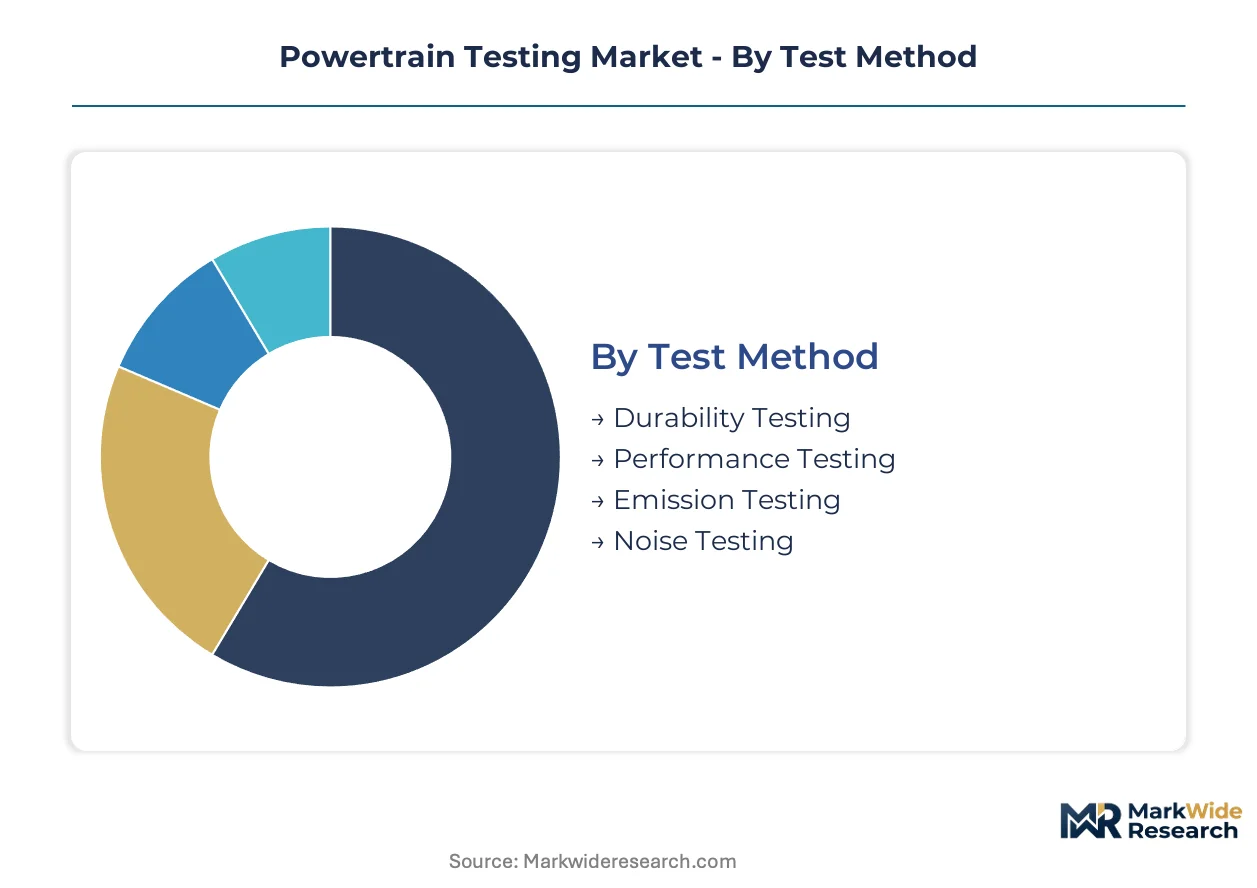
Powertrain testing vendors configure service portfolios around distinct technical workflows and customer procurement patterns. Segment boundaries determine capital allocation priorities across dynamometer capacity, emission measurement hardware, and software validation platforms.
Test Method:
Mature margin pools concentrate in emission certification workflows where regulatory stringency sustains equipment utilization rates.
- Durability Testing:Cyclic loading protocols subject powertrains to thermal-mechanical stress over thousands of hours. Hybrid architectures in Germany and Japan drive demand where mechanical and electrical duty cycles intersect.
- Performance Testing:Torque mapping, efficiency characterization, and transient response measurement across rotational speed ranges. Electric drive units above 20,000 rpm in California and Shanghai pull precision dynamometer investment.
- Emission Testing:Particulate number counting and NOx measurement for regulatory certification. Euro 7 and EPA Tier 3 rules sustain hardware utilization in European and North American laboratories.
- Noise Testing:Acoustic signature characterization for NVH compliance and brand differentiation. Premium automotive programs in Stuttgart and Munich maintain dedicated hemi-anechoic facilities.
Emission Testing holds installed capacity. Performance Testing is rotating up the share rankings.
Powertrain Type:
Capital deployment intensity varies sharply across propulsion architectures, with electric and hybrid systems demanding 40-60% higher test cell investment per unit of validation throughput.
- Internal Combustion Engine:Mature test protocols for spark-ignition and compression-ignition architectures. European and North American facilities maintain legacy capacity for commercial vehicle and performance applications.
- Electric Powertrain:Motor-inverter-battery integration validation at 400V and 800V architectures. Chinese and German OEM programs are expanding fastest, requiring high-voltage safety infrastructure and bidirectional charging certification.
- Hybrid Powertrain:Dual-mode operation testing across mechanical-electrical transition points. Japanese and Korean manufacturers concentrate development for series-parallel architectures.
- Fuel Cell:Hydrogen powertrain validation for heavy-duty mobility. Test infrastructure remains underdeveloped relative to battery-electric, creating white space in environmental simulation for stack durability.
Internal Combustion Engine dominates current installed base. Electric Powertrain is climbing the fastest.
Application:
Procurement concentration patterns split between high-volume automotive programs and specialized industrial validation with divergent pricing structures.
- Automotive:Passenger car and light truck powertrain validation at highest volume. German, Chinese, and United States OEMs concentrate R&D spending and regulatory certification demand.
- Aerospace:Turboshaft and turbofan engine testing for commercial and defense aviation. Certification requirements from FAA and EASA sustain specialized test cell utilization in Ohio and Toulouse clusters.
- Marine:Outboard, inboard, and auxiliary power systems for commercial shipping and leisure craft. IMO emission regulations in Rotterdam and Singapore drive compliance testing investment.
- Industrial:Stationary engines, gensets, and off-highway equipment validation. Construction and agricultural machinery OEMs in Illinois and Baden-Württemberg maintain seasonal test programs.
Automotive commands the deepest test cell networks. Aerospace maintains the highest per-hour validation pricing.
End User:
Customer type determines contract structure, with OEMs preferring multi-year framework agreements and Tier-1 suppliers purchasing spot capacity.
- OEMs:Integrated vehicle manufacturers operating captive test facilities and purchasing supplemental capacity. Volkswagen, Toyota, and Ford maintain the largest in-house validation footprints.
- Tier-1 Suppliers:Component and subsystem specialists including Bosch, Denso, and Continental. These firms outsource complete powertrain validation while retaining software-in-the-loop capabilities internally.
- Research Institutions:University laboratories and government research centers conducting fundamental propulsion research. Fraunhofer and Argonne National Laboratory anchor collaborative programs.
- Aftermarket Providers:Tuning, remanufacturing, and retrofit specialists requiring emission compliance verification. California CARB certification sustains regional demand concentration.
OEMs anchor long-term capacity commitments. Tier-1 Suppliers are gaining procurement leverage through platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive R&D rail corridors linking Stuttgart to Munich and Detroit to Chicago underpin Germany and the United States as validation hubs. China's high-speed freight network connects Shanghai test laboratories to Beijing certification centers, compressing development timelines for domestic OEMs.
United States
EPA Tier 3 emission rules sustain demand for portable measurement systems across Michigan and Ohio test corridors. The Inflation Reduction Act's clean vehicle tax credits accelerate battery-electric validation programs in California and Texas. Detroit anchors the densest concentration of captive OEM test facilities, with supplemental capacity procurement shifting toward spot-market platforms.
Germany
Euro 7 standards mandate real-driving emission monitoring that strains Baden-Württemberg laboratory infrastructure. KBA certification requirements force capital deployment toward particulate number counting hardware. The Stuttgart-Munich corridor concentrates AVL, FEV, and IAV operations, with independent test houses competing for framework agreements against OEM captive facilities.
China
MIIT GB standards for new energy vehicles create parallel compliance tracks distinct from EPA or Euro certification pathways. The dual carbon goals accelerate 800V architecture validation demand in Shanghai and Beijing laboratories. Joint ventures between foreign equipment suppliers and domestic test houses dominate the Yangtze River Delta cluster.
Japan
METI subsidies for hydrogen mobility sustain fuel cell test infrastructure development around Nagoya and Tokyo. JIS standards for electric powertrains diverge from ISO protocols, creating region-specific certification requirements. Horiba anchors emission measurement workflows across Chubu and Kanto industrial zones.
United Kingdom
Ricardo's motorsport-derived consulting programs concentrate around Silverstone and Warwickshire technical clusters. The UK's departure from EU regulatory alignment creates uncertainty for Euro 7 certification workflows serving continental OEMs. Oxfordshire and Northamptonshire host specialized hybrid architecture validation facilities.
Powertrain Testing Market Vendor Landscape
Listed leaders compete with private specialists across integrated toolchains versus consulting-led service models. The vendor base concentrates among European and Japanese equipment manufacturers with captive software ecosystems. Three archetypes dominate: full-stack platform providers spanning simulation to physical testing, emission measurement specialists with regulatory workflow integration, and consulting-engineering hybrids targeting motorsport and premium automotive programs. Capacity expansion and strategic partnerships constitute the primary competitive vectors as test houses retool for high-voltage architectures.
Within the integrated platform tier, AVL and FEV exemplify full-stack validation providers with simulation-to-dynamometer toolchains. Horiba occupies a position among emission measurement specialists with exhaust system hardware deployed across Japanese and European regulatory workflows. Ricardo sits within the consulting-engineering hybrid archetype, leveraging motorsport-derived expertise for premium hybrid programs. These three anchors illustrate divergent strategic positioning against the backdrop of electric powertrain transition and regulatory fragmentation.
| Leading Market Players |
|---|
| AVL |
| FEV |
| Horiba |
| IAV |
| Atesteo |
| Applus |
| ThyssenKrupp |
| Ricardo |
| TÜV SÜD |
| Others |
Supply Flow & Price Mechanics
Silicon carbide inverter modules replacing IGBT power electronics simultaneously shift procurement geography toward Japanese and German semiconductor fabs and compress validation pricing for 800V test programs as equipment amortization accelerates across high-volume electric powertrain platforms.
Pricing Analysis
Certification level creates the primary spread between ISO 15118-20 bidirectional charging validation and legacy emission testing workflows. Test houses deploy three-tier pricing structure across premium, standard, and economy levels based on regulatory stringency and turnaround urgency. Pricing pressure stems from spot-market platform proliferation in Michigan and Baden-Württemberg that fragments long-term framework agreements. Tier-1 suppliers exhibit highest price sensitivity due to procurement team consolidation, while motorsport-derived hybrid programs maintain lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of precision torque measurement systems dominates Japanese and German supplier relationships due to 18-24 month lead times for dynamometer components. Test equipment manufacturing concentrates in Germany, Japan, and the United States. High-voltage safety infrastructure draws from copper busbar suppliers in Chile and transformer specialists in South Korea. Single-source vulnerability persists around 1500V arc-flash containment systems. Distribution runs through direct OEM procurement channels and regional equipment integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain testing is approaching a platform-economics inflection where ISO 15118-20 certification ecosystems determine vendor lock-in, with bidirectional charging interoperability functioning as the interoperability layer that separates integrated toolchain providers from commodity test houses.
For Market Incumbents: Consolidate simulation-to-dynamometer toolchains through targeted acquisition of software-in-the-loop specialists in Stuttgart and Munich clusters. AVL and FEV should deepen backward integration into high-voltage measurement hardware to defend against emerging Chinese equipment suppliers capturing 800V validation share. Priority rests on securing KBA and EPA certification workflows before regulatory divergence accelerates capital duplication requirements. For New Entrants and Emerging Players: Lead with fuel cell commercial vehicle validation as the most penetrable white space, where environmental simulation infrastructure remains underdeveloped relative to battery-electric testing. Target hydrogen powertrain programs in Nagoya and California corridors where METI subsidies and Inflation Reduction Act credits concentrate development funding. Go-to-market angle should emphasize heavy-duty durability protocols that incumbent test houses have deprioritized. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-stack platform providers over emission measurement specialists facing margin compression from portable hardware proliferation. Long-term viability across the projection horizon hinges on software-defined validation capabilities that merge virtual and physical testing. Acquisition target archetype: consulting-engineering hybrids with motorsport-derived IP and embedded OEM relationships. Signal to watch is MIIT GB standard harmonization pressure that would favor unified platform investments over region-specific assets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | ISO 15118-20 unified certification reduces asset duplication for Euro 7 and EPA Tier 3 compliance. |
| Battery Supply Agreement | 1500V test cell partnerships with Korean cell manufacturers secure high-voltage validation capacity. |
| Software-Defined Vehicle Investment | Hardware-in-the-loop convergence with physical dynamometry compresses OEM development cycles. |
| Geographic Manufacturing Footprint | Yangtze River Delta joint ventures unlock MIIT GB standard access for foreign test equipment suppliers. |
| Charging Infrastructure Partnership | Bidirectional charging certification partnerships with grid operators anchor vehicle-to-grid validation workflows. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA certification databases, MIIT GB standard filings, and IHS Markit vehicle production data through structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, test house operations directors, and regulatory affairs specialists at KBA and CARB. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include propulsion architecture, test method workflow, voltage tier, and regional regulatory cluster throughout the forecast period. CAGRs derive from installed capacity utilization rates, OEM R&D spending patterns, and compliance deadline clustering. Industry-specific inputs incorporate dynamometer throughput constraints and high-voltage safety infrastructure deployment timelines.
The analysis sits within stated boundaries; outcomes outside sustained Euro 7 enforcement or abrupt MIIT standard divergence would require recalibration. Forecasts reflect assumptions around regulatory timeline adherence and electric powertrain adoption curves. Revision becomes warranted when 800V platform penetration crosses thresholds that obsolete legacy 400V test cell investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Global Automotive Damper Pulley Market
Powertrain
Torque Limiter Market
Powertrain
Global Automotive Engine Cover Market
Powertrain
Power Seat Adjustment Motor Market
Powertrain
Clutch Friction Plate Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Global Automotive Engine and Engine Mounts Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Fuel Pumps Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Transmission Fluids Market