
 Armored Transportation Services Market | 2026-2036
Armored Transportation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Transportation Services Market Insights
Subscription-style fleet monitoring is repositioning how armored transportation contracts are structured, shifting buyers from per-route fees toward integrated security-as-a-service agreements. Brink's Co leverages its global vault network to sustain multi-year contracts with multinational banks. Loomis AB anchors Nordic market share through specialized cash processing integration. GardaWorld Federal Services differentiates via cleared-personnel capabilities that dominate government and diplomatic segments.
Armored transportation services encompass the secure movement of currency, bullion, securities, and high-value assets using hardened vehicles operated by trained personnel, with vehicles typically rated to resist ballistic threats through steel plating, composite armor, and run-flat tire systems. The primary commercial purpose centers on eliminating theft exposure during transit between financial institutions, retail vaults, and central bank facilities. Cash-in-Transit commands the largest revenue pool among service types, reflecting persistent physical currency circulation despite digital payment growth. Bulletproof SUVs represent the fastest-expanding vehicle category, driven by executive protection demand from high-net-worth individuals and corporate security programs in volatile regions.
The US Department of Transportation's FMVSS armor standards and the European Union's ECE R29 commercial vehicle safety regulations shape vehicle procurement specifications and retrofit compliance costs across OECD markets. India's RBI cash logistics guidelines mandate GPS tracking and dual-crew protocols that directly determine vendor eligibility for ATM replenishment contracts. Stakeholders must weigh fleet electrification timelines against armor weight penalties that constrain battery range and charging infrastructure compatibility.
Market Dynamics
Financial institutions in emerging markets are extending cash logistics networks into rural territories, forcing armored fleet operators to reconfigure vehicle specifications and crew protocols for lower-density routes. This geographic expansion is compressing route economics while elevating compliance burdens.
Growth Catalysts
- RBI Cash Logistics Guidelines:India's central bank mandates GPS tracking and dual-crew protocols for ATM replenishment contracts, disqualifying non-compliant vendors and consolidating procurement among certified operators.
- ECE R29 Commercial Vehicle Safety Standards:European Union regulations mandate upgraded cab strength and rollover protection, accelerating fleet replacement cycles across Germany, France, and Italy.
- Bulletproof SUV Demand Surge:Executive protection programs for high-net-worth individuals and corporate security teams in volatile regions are expanding the addressable vehicle category beyond traditional cash-in-transit vans.
Market Restraints
- Armor Weight Penalties:Steel plating and composite armor add substantial mass that degrades fuel efficiency and constrains electric vehicle battery range, complicating fleet electrification timelines.
- FMVSS Compliance Costs:US Department of Transportation armor certification requires expensive third-party testing and documentation, elevating barriers for smaller regional operators.
- Digital Payment Substitution:Mobile wallet penetration and real-time payment rails in advanced economies are compressing physical currency circulation volumes in urban cores.
Strategic Opportunities
- Subscription Fleet Monitoring:Integrated security-as-a-service agreements are displacing per-route fee structures, locking in multi-year revenue visibility with multinational banking clients.
- Rural ATM Density Targets:India's unbanked population expansion under financial inclusion mandates is creating white-space demand for armored replenishment services in tier-3 and tier-4 cities.
- Run-Flat Tire System Convergence:Integration of self-sealing tire technology with telematics-enabled predictive maintenance is reducing roadside vulnerability windows and insurance premiums.
Industry Challenges
- Cleared-Personnel Recruitment Bottlenecks:Government and diplomatic contracts require security-cleared drivers and guards, creating talent scarcity that limits operator expansion into high-margin federal segments.
- Retrofit Certification Timelines:ECE R29 and FMVSS armor rating upgrades demand extended vehicle downtime for testing and documentation, disrupting fleet availability during compliance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Transportation Services Market |
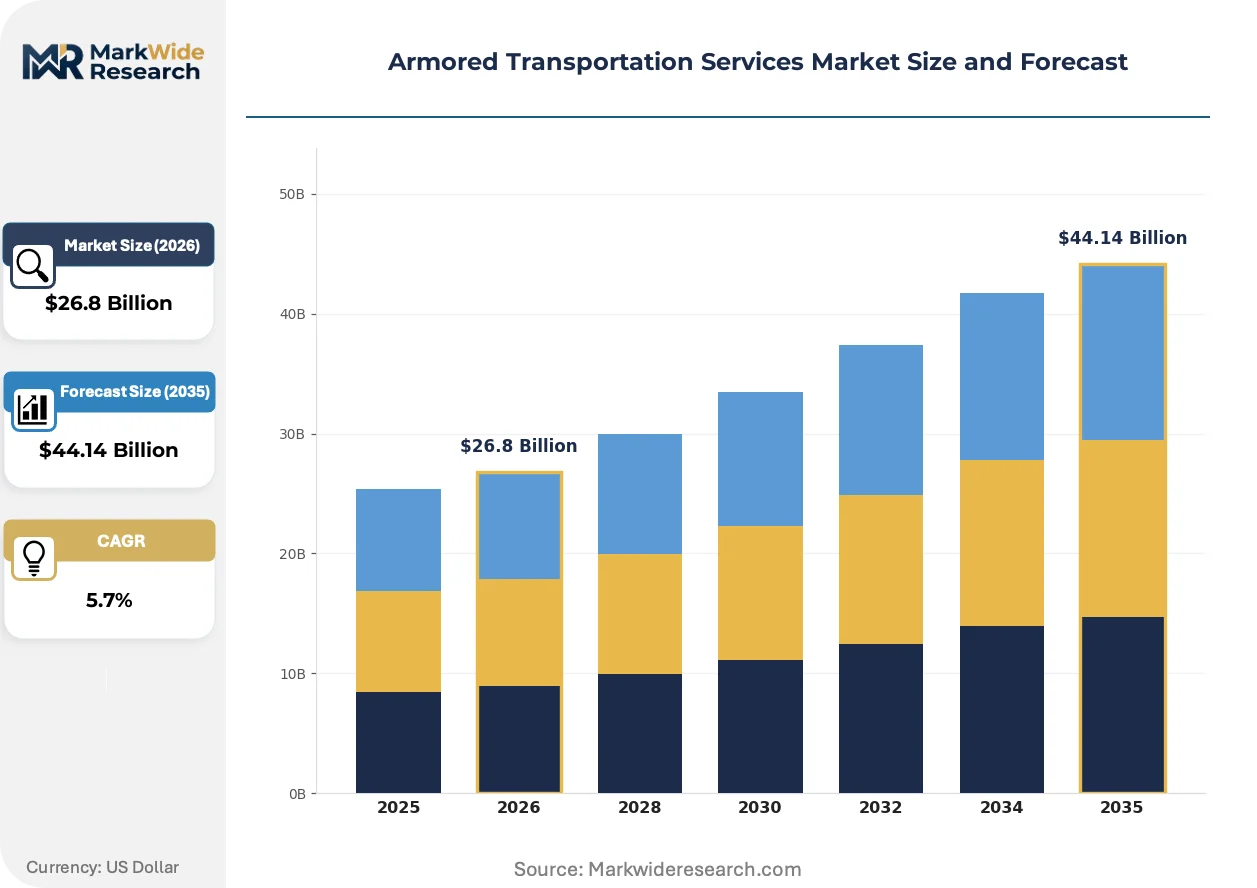
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $44.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cash-in-Transit, Valuable Goods Transfer, ATM Replenishment, Secure Courier, On-Demand Transport Vehicle Type: Light Armored Trucks, Heavy Armored Vans, Bulletproof SUVs, Armored Trailers, Tactical Vehicles End User: Financial Institutions, Jewelry Retailers, Government Agencies, Logistics Firms, High-Value Retailers Security Technology: GPS Tracking, Remote Monitoring, Panic Alarms, Biometric Access, Armed Escorts |
| Companies Covered | Dunbar Armored, Rochester Armored Car, Loomis AB, GardaWorld Federal Services, Pendum, Brink's Co, The Brinks Company, American Security, Garda World Security Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Transportation Services Market Trends and Innovations
Telematics integration and predictive analytics are redefining how armored fleet operators manage route risk and asset utilization. These capabilities are compressing the traditional boundaries between physical security and digital infrastructure.
Composite ceramic armor is absorbing ballistic protection duties from conventional steel plating in next-generation vehicle designs. High-net-worth individual protection services and corporate security programs are accelerating adoption of these lighter-weight systems. The technology is absorbing weight-reduction requirements that electric powertrain range targets impose on heavy-duty commercial vehicles.
EU Green Deal carbon intensity benchmarks are pressuring fleet operators to document emissions profiles across contracted routes. The regulation is triggering procurement specification changes that favor hybrid powertrains and alternative fuels in European markets. Cash-in-transit operators in Germany and France are responding with pilot programs for biofuel-compatible armored chassis.
Bank procurement departments are consolidating vendor relationships around integrated cash processing and transportation bundles. Regional operators with standalone logistics capabilities are losing share to competitors offering vault storage, counting, and reconciliation under single contracts. This concentration is most visible in Nordic markets where Loomis AB has anchored multi-service agreements with retail banking networks.
Armored Transportation Services Market Segmentation
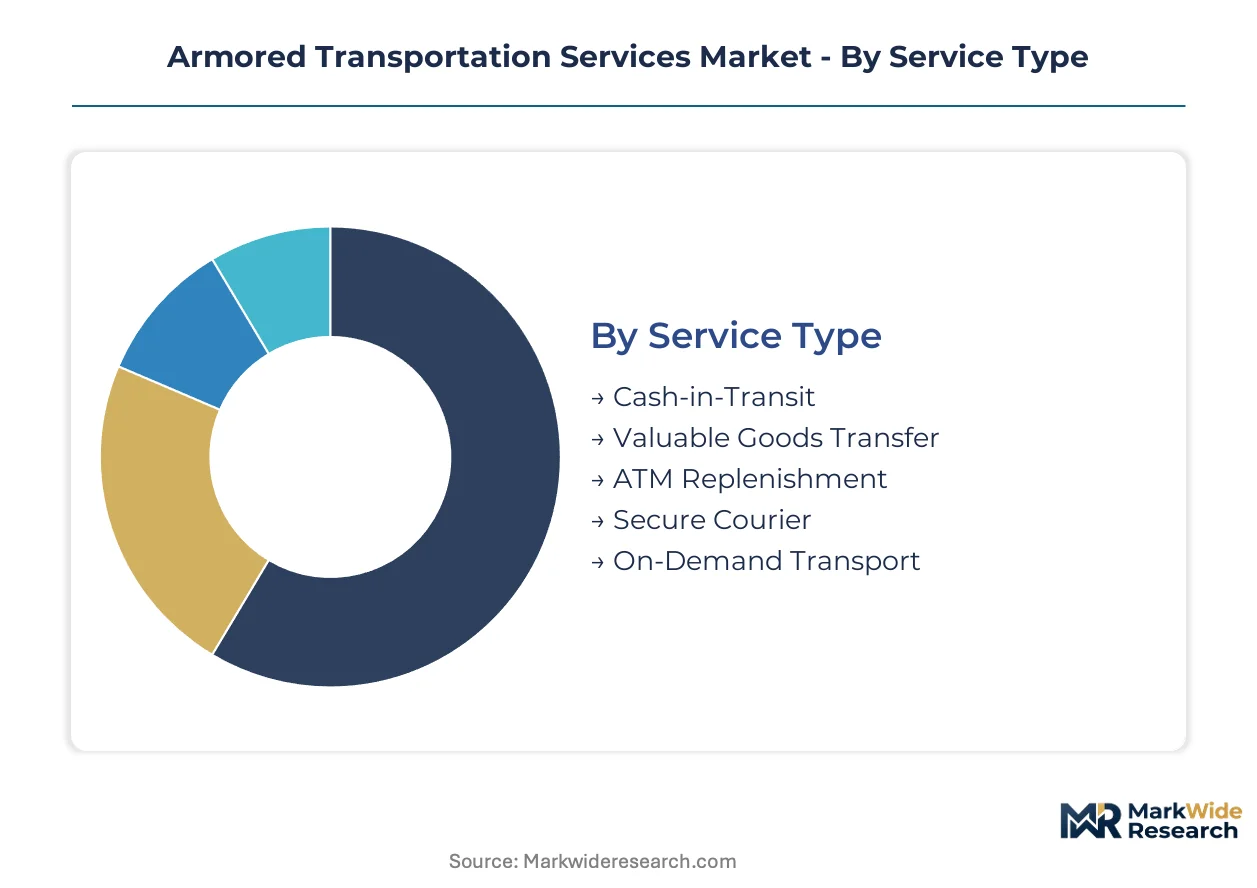
Armored transportation procurement varies sharply by operational context, with financial institutions prioritizing route density and jewelry retailers demanding discrete vehicle profiles. Fleet operators must align armor ratings, crew protocols, and technology stacks against distinct risk exposures across service categories.
Service Type:
Standalone cash movement contracts dominate vendor portfolios, while embedded security services bundle physical transit with vault storage and reconciliation.
- Cash-in-Transit:Bulk currency transport between central banks, retail vaults, and ATM networks using hardened vehicles with steel-plated cargo compartments and dual-crew protocols. Demand concentrates in India, where RBI-mandated GPS tracking and dual-crew requirements disqualify non-compliant operators from ATM replenishment contracts.
- ATM Replenishment:Scheduled cash loading and balancing services for automated teller machines, requiring synchronized logistics with bank cash forecasting systems. Demand concentrates in tier-3 and tier-4 Indian cities under financial inclusion mandates, compressing route economics while elevating compliance burdens.
- Valuable Goods Transfer:Secure movement of bullion, securities, and precious metals with chain-of-custody documentation.
- Secure Courier:Document and small-item transport for legal, medical, and corporate clients with tamper-evident sealing.
- On-Demand Transport:Emergency and ad-hoc movement services triggered by unexpected cash surpluses or security incidents.
Cash-in-Transit leads volumes today; ATM Replenishment is gaining share fastest.
Vehicle Type:
Cost tiers separate purpose-built commercial chassis from premium executive protection platforms, with armor certification levels driving procurement segmentation.
- Light Armored Trucks:Medium-duty commercial chassis with ballistic steel plating rated to ECE R29 and FMVSS standards, optimized for urban cash routes with frequent stops. Fleet operators in Germany and France face EU Green Deal pressure to pilot biofuel-compatible variants.
- Bulletproof SUVs:Luxury passenger vehicles with composite ceramic armor and run-flat tire systems, serving executive protection and high-net-worth individual transport. Demand from corporate security programs in volatile regions is expanding this category beyond traditional commercial applications.
- Heavy Armored Vans:High-capacity cargo vehicles for bulk currency and bullion movement with reinforced suspension systems.
- Armored Trailers:Detachable cargo units for flexible fleet deployment and temporary secure storage at event sites.
- Tactical Vehicles:Military-grade platforms for government and diplomatic contracts requiring cleared-personnel crews.
Light Armored Trucks anchor current fleet composition; Bulletproof SUVs show the steepest expansion trajectory.
End User:
Customer type determines contract structure, with financial institutions favoring multi-year integrated agreements and government agencies imposing security clearance requirements.
- Financial Institutions:Banks and credit unions requiring scheduled cash logistics, vault services, and ATM replenishment with regulatory-compliant documentation.
- Government Agencies:Central banks, mints, and tax authorities mandating cleared personnel and classified-route protocols.
- Jewelry Retailers:Discrete transport for high-value inventory with unmarked vehicles and variable routing.
- Logistics Firms:Subcontracted secure segments within broader supply chains for cross-border valuables.
- High-Value Retailers:Luxury goods merchants requiring timed deliveries and storefront cash collection.
Financial Institutions command the largest contract value; Government Agencies impose the strictest qualification barriers.
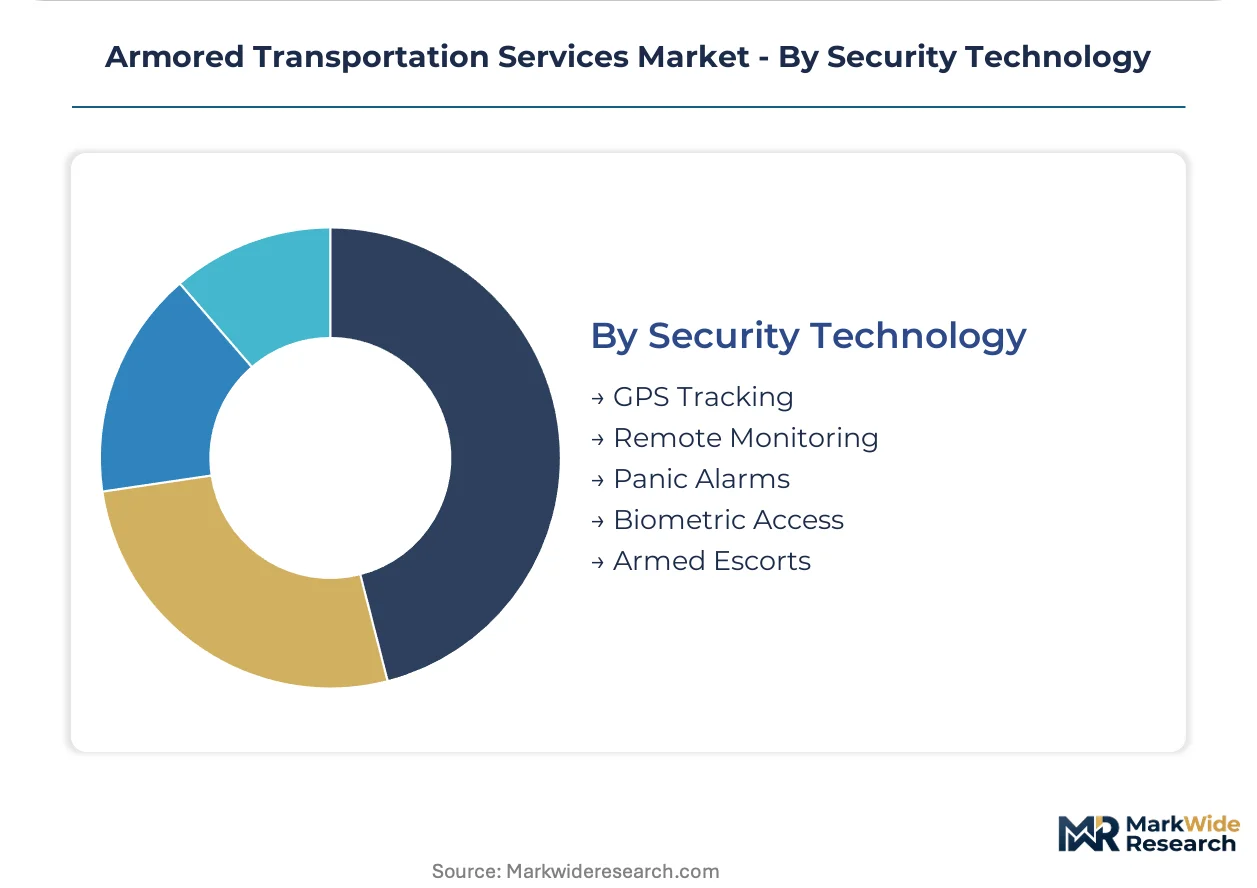
Security Technology:
Maturity levels separate established telematics from emerging biometric systems, with integration depth varying by client risk tolerance.
- GPS Tracking:Real-time location monitoring with geofencing alerts, now mandatory under India's RBI guidelines for ATM service eligibility.
- Remote Monitoring:Centralized surveillance of vehicle interiors and cargo status via cellular networks.
- Panic Alarms:Silent distress signaling to dispatch centers and law enforcement integration.
- Biometric Access:Fingerprint and facial recognition for driver authentication and cargo compartment entry.
- Armed Escorts:Trained security personnel in separate vehicles or onboard for high-threat routes.
GPS Tracking is universally deployed; Biometric Access is climbing the fastest as fleet operators differentiate on crew accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's armored fleet procurement outpaces Germany's replacement cycles by a factor of three, driven by divergent regulatory mandates and cash infrastructure maturity. Brazil's bulletproof SUV segment expands faster than Canada's cash-in-transit consolidation. The United Arab Emirates concentrates diplomatic and executive protection demand in ways that reshape regional competitive positioning.
United States
Financial institutions in Texas and Florida extend ATM networks into exurban corridors, forcing route reconfiguration for lower-density cash logistics. NHTSA's FMVSS armor certification requirements elevate compliance costs for regional fleet operators. The Southeast corridor from Atlanta to Miami anchors the largest concentration of executive protection services for high-net-worth individuals.
Germany
Commercial banks in Bavaria and North Rhine-Westphalia consolidate vendor relationships around integrated cash processing bundles. ECE R29 commercial vehicle safety standards accelerate fleet replacement cycles for light armored trucks. The Rhine-Ruhr industrial cluster hosts pilot programs for biofuel-compatible armored chassis under EU Green Deal pressure.
India
RBI-mandated GPS tracking and dual-crew protocols disqualify non-compliant operators from ATM replenishment contracts in tier-3 and tier-4 cities. Financial inclusion targets expand cash logistics networks into Maharashtra and Gujarat's rural territories. Mumbai and Delhi-NCR concentrate procurement decisions for multinational banking clients.
Brazil
Jewelry retailers in São Paulo and Rio de Janeiro demand discrete unmarked vehicles for high-value inventory transport. Central bank cash distribution mandates sustain bulk currency movement between mint facilities and commercial vaults. The São Paulo metropolitan corridor anchors the steepest bulletproof SUV adoption curve in Latin America.
United Arab Emirates
Diplomatic missions and sovereign wealth funds in Dubai and Abu Dhabi drive cleared-personnel requirements for armored transport contracts. Executive protection programs for regional corporate headquarters expand demand beyond traditional cash-in-transit applications. The Dubai International Financial Centre concentrates procurement specifications for multinational security standards.
Armored Transportation Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers commanding multi-year banking contracts while regional operators compete on route density. The vendor base organizes into three tiers: global vault-network operators, national cash logistics specialists, and niche executive protection providers. Consolidation pressure intensifies as procurement departments favor bundled cash processing and transportation agreements. Fleet electrification timelines and armor weight penalties drive partnership strategies between vehicle fabricators and battery technology suppliers.
Within the global integrated services tier, Brink's Co and Loomis AB exemplify archetypes that leverage vault infrastructure to lock in multinational banking relationships. GardaWorld Federal Services occupies a distinct position serving government and diplomatic segments where cleared-personnel requirements create qualification barriers. These three anchors demonstrate how regulatory compliance capabilities and personnel security clearances separate premium-tier competitors from regional cash logistics providers.
| Leading Market Players |
|---|
| Dunbar Armored |
| Rochester Armored Car |
| Loomis AB |
| GardaWorld Federal Services |
| Pendum |
| Brink's Co |
| The Brinks Company |
| American Security |
| Garda World Security Corp |
| Others |
Pricing and Supply Chain Analysis
Backward integration into armor fabrication and vehicle chassis production anchors pricing power for operators controlling in-house manufacturing capabilities. Fleet operators with captive steel-plating facilities in India and Germany command margin buffers that outsourced procurement models cannot replicate, particularly under ECE R29 and FMVSS compliance cost pressures.
Pricing Analysis
Capacity additions in India's tier-3 and tier-4 ATM replenishment corridors are reshaping price floors for cash-in-transit contracts. Three-tier pricing structure across premium, standard, and economy levels separates multinational banking clients from regional credit unions and retail aggregators. Price differentiation hinges on GPS tracking certification tier and dual-crew protocol compliance. Cost compression in the standard tier is intensifying because RBI-mandated fleet upgrades disqualify non-compliant vendors, consolidating procurement among certified operators. Regional credit unions exhibit the highest price sensitivity, while sovereign wealth funds and diplomatic missions show minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with ballistic steel suppliers concentrated in Germany, South Korea, and India. Composite ceramic armor feeds from specialized foundries in the United States and Japan. Run-flat tire systems draw from integrated rubber compounders in Thailand and Malaysia. Tariff exposure on alloy steel imports threatens cost stability for European fleet operators retrofitting under ECE R29 timelines. Distribution runs through authorized vehicle fabricators with direct OEM relationships, bypassing aftermarket channels for armor-rated chassis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
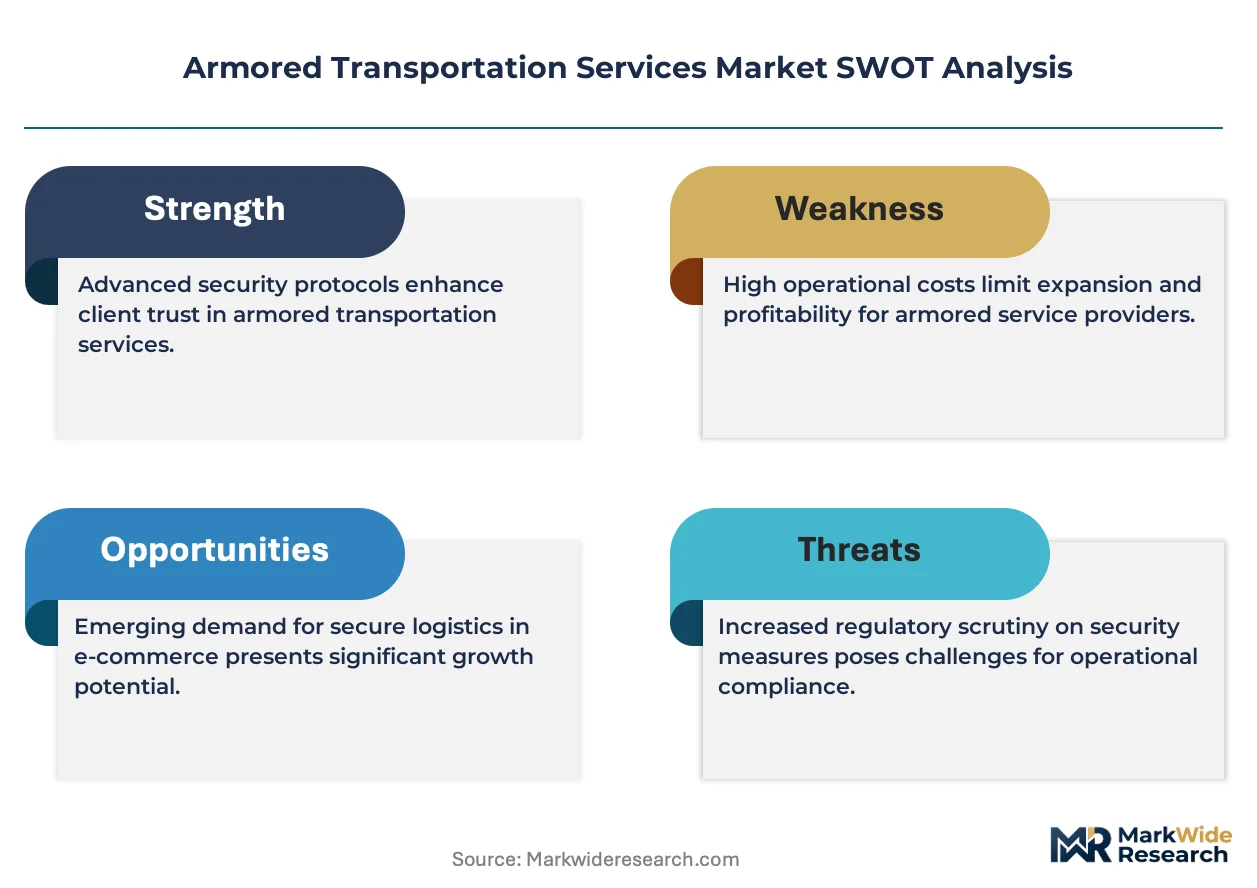
This market functions as a regulatory compounder where ECE R29 and FMVSS armor certification mandates perpetually refresh fleet replacement demand. Compliance investment creates sustainable competitive moats for operators with capital depth.
For Market Incumbents: Hedge against electric powertrain range penalties by piloting hybrid armored chassis in Germany and France under EU Green Deal benchmarks. Prioritize captive supply of composite ceramic armor to offset steel weight disadvantages. Consolidate regional operators in India's tier-3 cities before RBI compliance deadlines lock in vendor relationships.
For New Entrants and Emerging Players: Begin with cleared-personnel recruitment pipelines targeting government and diplomatic contracts where GardaWorld Federal Services has established qualification barriers. India's rural ATM density expansion under financial inclusion mandates offers the most penetrable white-space. Position around subscription-style fleet monitoring agreements that displace per-route fee structures.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale cash logistics operators because procurement consolidation among multinational banks favors integrated vault-and-transport bundles over standalone logistics. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than route density alone. Monitor RBI guideline enforcement intensity as the inflection indicator for Indian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Armor Integration | Reduces vehicle mass to preserve electric range under EU Green Deal pressure. |
| Cleared-Personnel Pipeline Development | Unlocks federal and diplomatic contracts requiring security clearance protocols. |
| Rural ATM Network Expansion | Captures RBI-mandated tier-3 and tier-4 replenishment demand in Maharashtra and Gujarat. |
| Subscription Service Repositioning | Locks multi-year revenue visibility with multinational banking clients. |
| Biofuel-Compatible Chassis Pilot | Positions German and French fleets for EU carbon intensity benchmarking. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included fleet operations directors at cash-in-transit providers, procurement managers at multinational banking clients, regulatory compliance officers, armor fabrication engineers, and insurance underwriters specializing in high-value transport. Secondary validation drew from NHTSA FMVSS documentation, EU ECE R29 technical standards, RBI circulars on cash logistics, SEC filings of publicly traded security services firms, and customs records for ballistic steel and composite armor imports. Bottom-up route density modeling and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the forecast window to pre-pandemic baseline utilization and post-regulatory implementation trajectory. Segmentation dimensions spanned service type, vehicle armor rating tier, end-user risk profile, and regional regulatory cluster. CAGRs derived from logistic curve fitting against fleet replacement cycle data and ATM density penetration curves. Industry-specific inputs included RBI-mandated dual-crew adoption timelines and ECE R29 retrofit completion rates across European operator fleets.
Several conditions sit outside the modeled scope, including geopolitical disruption to ballistic steel supply corridors, accelerated digital payment substitution beyond baseline assumptions, and breakthrough lightweight armor technologies that alter electrification economics. Forecasts reflect documented assumptions about regulatory enforcement consistency and fleet operator capital access. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Car Wash System Market
Automotive Services
Americas MAP Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
US Car Wash Services Market
Automotive Services
Automotive MRO Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Automotive Register Market
Automotive Services
Tow Truck Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Car Washing Service Market
Automotive Services
Car Wash Services Market
Automotive Services
Car Rental Business Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Global Street Sweeper Market