
 On-Demand Logistics Market | 2026-2036
On-Demand Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
On-Demand Logistics Market Analysis
The EU Green Deal is expanding compliance obligations for last-mile operators across European urban zones. DHL Group leverages its integrated ground-air network to sustain next-day coverage in high-density corridors. Amazon.com anchors North American same-day infrastructure through proprietary fulfillment centers positioned within metropolitan rings. FedEx Corporation competes on cross-border customs automation, differentiating its brokerage layer from pure-play domestic rivals.
On-demand logistics coordinates real-time demand matching with distributed inventory positioning, typically operating through cloud-based dispatch algorithms that optimize driver allocation against sub-two-hour delivery windows. Its primary commercial purpose is collapsing the temporal gap between order placement and physical receipt for time-sensitive goods. Last-mile delivery captures the dominant share of operational cost and customer touchpoint value, while route optimization software constitutes the fastest-improving margin lever as machine learning reduces empty miles. Drone delivery remains nascent in regulatory frameworks but attracts disproportionate R&D allocation from platforms seeking to bypass ground congestion.
The EPA tailpipe standards and FAA drone integration pathways jointly determine fleet technology roadmaps for US operators, with California's CARB waivers creating a de facto higher bar for vehicles serving Los Angeles and San Francisco basins. China's MIIT governs autonomous delivery vehicle testing permits in Shenzhen and Beijing, constraining robotaxi-to-logistics technology transfer. Stakeholders must monitor how municipal congestion pricing schemes in London, Singapore, and New York reshape the cost calculus of centralized versus micro-fulfillment inventory placement.
Market Dynamics
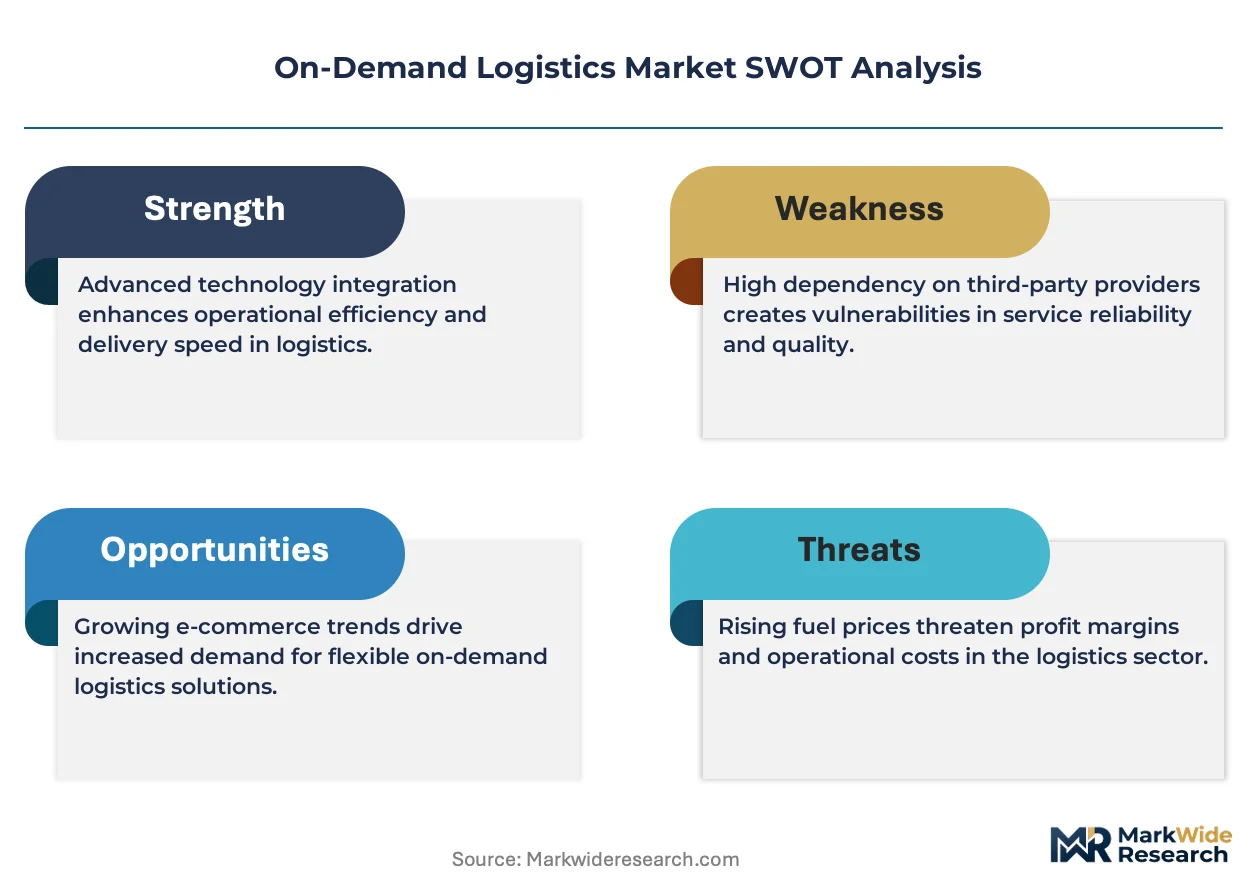
Cloud-based dispatch algorithms are compressing delivery windows below two hours while EPA tailpipe standards and EU Green Deal emissions mandates force fleet electrification across urban corridors.
Growth Catalysts
- Same-day shipping mandates:E-commerce fulfillment networks in tier-one Chinese cities and North American metropolitan rings are densifying inventory positioning to collapse order-to-delivery latency.
- EU Green Deal compliance:Emissions targets are reshaping last-mile fleet composition requirements, accelerating zero-emission vehicle deployment in London, Paris, and Amsterdam urban zones.
- Machine learning route optimization:Dispatch platforms are reducing empty miles through predictive demand clustering, improving margin structures for sub-two-hour delivery windows.
Market Restraints
- Lithium-ion supply concentration:Battery raw material processing bottlenecks in concentrated geographies constrain fleet electrification timelines for operators serving dense urban basins.
- FAA drone integration pathways:Regulatory uncertainty around beyond-visual-line-of-sight operations delays aerial last-mile deployment in US metropolitan airspace.
- Ground congestion pricing:Municipal schemes in Singapore, London, and New York inflate centralized fulfillment costs versus micro-fulfillment alternatives.
Strategic Opportunities
- Autonomous delivery vehicle permits:China's MIIT testing frameworks in Shenzhen and Beijing create regulatory pathways for robotaxi-to-logistics technology transfer.
- Cross-border customs automation:Brokerage layer differentiation through automated clearance systems offers margin expansion for international express operators.
- Micro-fulfillment inventory placement:Urban real estate repositioning near metropolitan rings enables sub-hour delivery without ground congestion exposure.
Industry Challenges
- Cloud-legacy system integration:Real-time dispatch algorithms face friction connecting with incumbent warehouse management systems at established fulfillment centers.
- Driver allocation volatility:Gig-economy labor pools create capacity mismatches against demand spikes during promotional windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Demand Logistics Market |
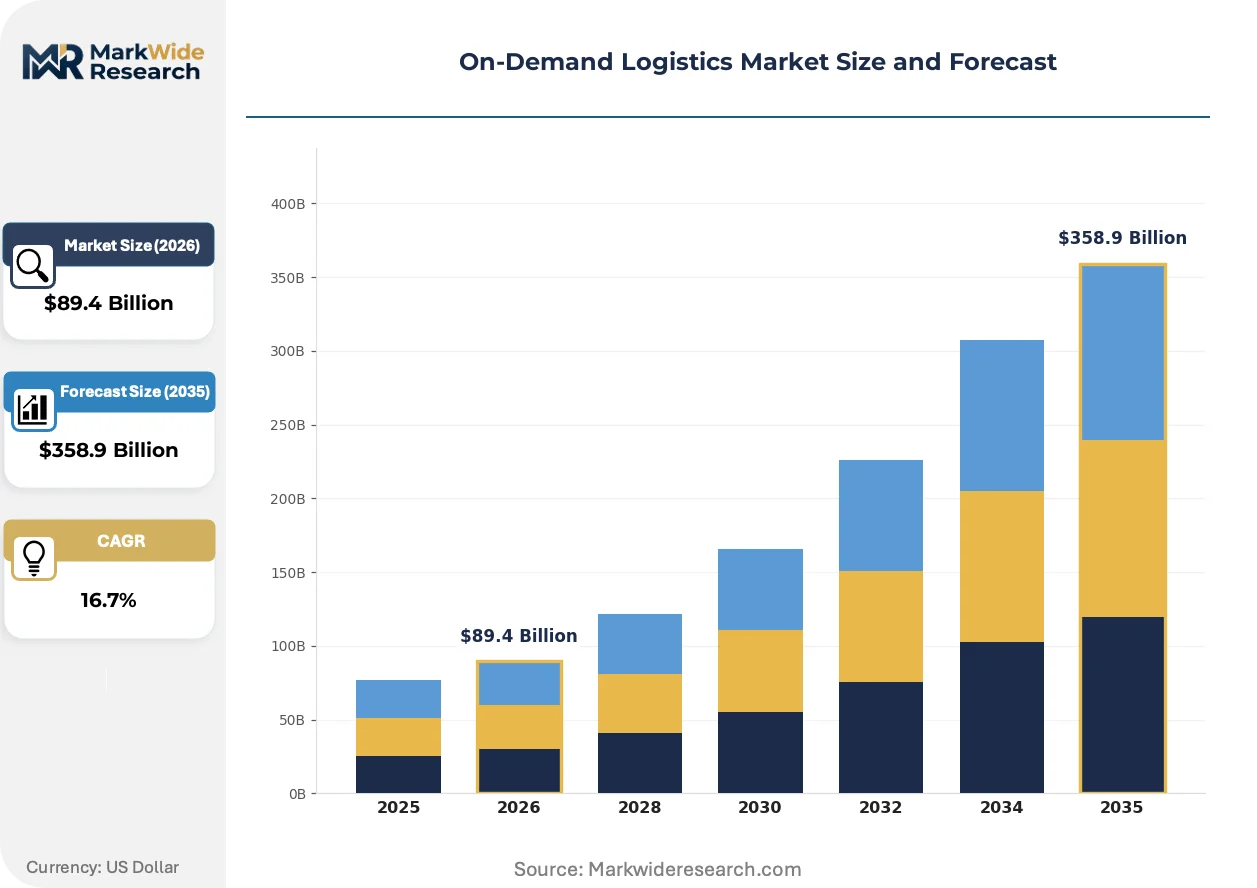
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $358.9 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last-Mile Delivery, Cross-Docking, Fulfillment Centers, Same-Day Shipping Technology: GPS Tracking, Route Optimization, Fleet Management Software, Mobile Apps End User: Retailers, E-Commerce Businesses, Manufacturers, Distributors Delivery Mode: Ground Transport, Air Freight, Maritime Shipping, Drone Delivery |
| Companies Covered | Uber Technologies, DHL Group, FedEx Corporation, DoorDash, Amazon.com, United Parcel Service of America, Delivery Hero SE, JD Logistics, Lalamove, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Demand Logistics Market Emerging Trajectories
Algorithmic orchestration is fragmenting fulfillment architecture while regulatory emissions frameworks and buyer delivery expectations compress operational timelines simultaneously.
Autonomous ground vehicles are modularizing last-mile infrastructure. These self-driving delivery pods separate cargo compartments from propulsion units, enabling operators in Beijing and Shenzhen to swap battery packs without unloading. Food and grocery platforms are piloting the format at scale. The technology is modularizing fleet utilization by decoupling vehicle range from driver shift limits.
EU Green Deal emissions targets are forcing zero-emission zone declarations across Amsterdam, Paris, and Berlin city centers. Commercial van operators face exclusion from dense urban cores without battery-electric or hydrogen fuel-cell replacement. Last-mile specialists serving European e-commerce are responding with depot electrification and charging infrastructure partnerships.
Buyer tolerance for delivery latency is collapsing toward immediate gratification thresholds. Subscription same-day services are displacing standard multi-day shipping as the default expectation in North American and Chinese urban households. Grocery and pharmaceutical verticals exhibit the most pronounced compression, with one-hour windows becoming table stakes in Los Angeles, New York, and Shanghai metropolitan zones.
On-Demand Logistics Market Segmentation
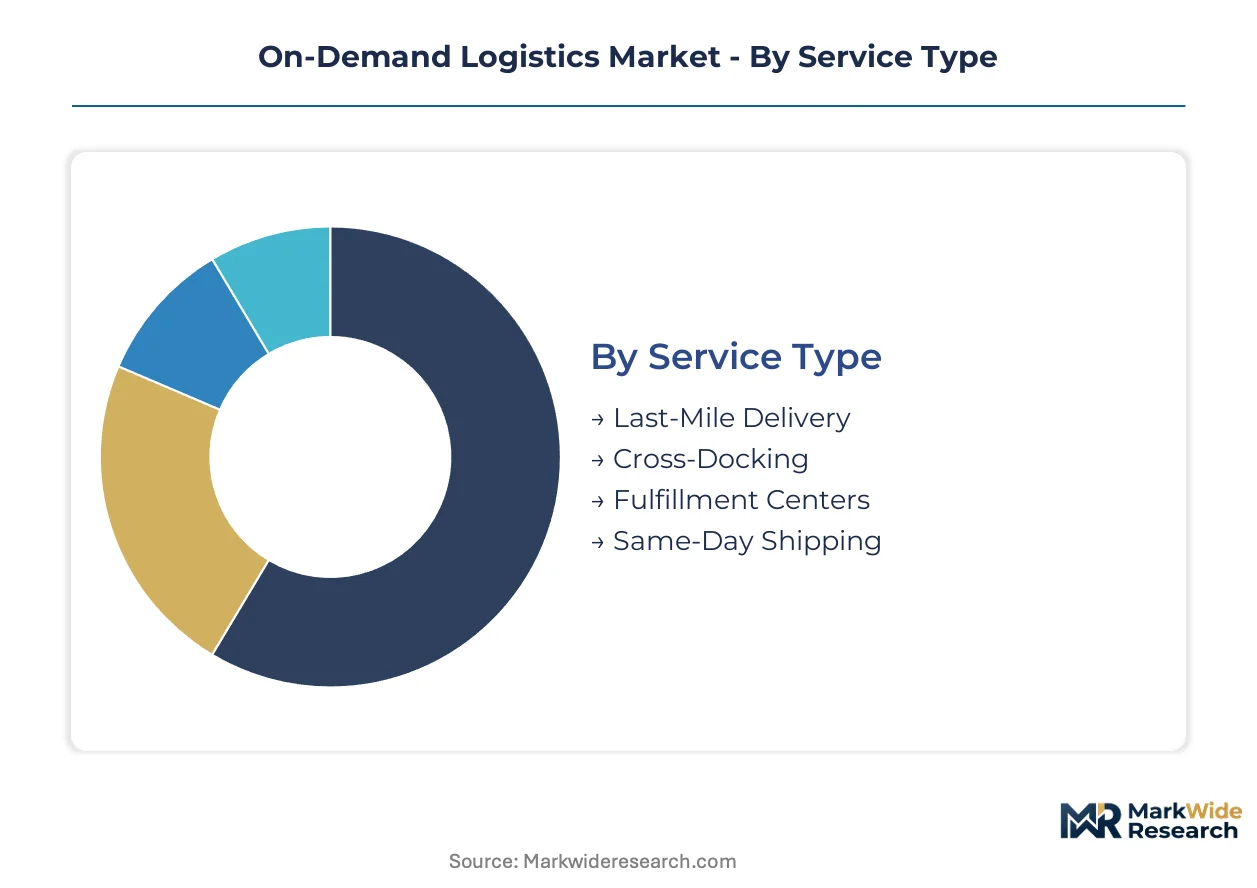
On-demand logistics operators configure service portfolios around delivery velocity tiers and technology stacks. Segment boundaries blur as platforms integrate fulfillment centers with last-mile assets and route optimization layers.
Service Type:
Supply concentrates in urban last-mile networks where inventory positioning density determines sub-two-hour feasibility.
- Last-Mile Delivery:Final-leg courier networks operate through gig-driver pools and micro-depots positioned within metropolitan rings. Demand clusters in Shanghai, Los Angeles, and London where e-commerce penetration has collapsed buyer tolerance for next-day windows. EPA tailpipe standards and EU Green Deal mandates force fleet electrification in these dense urban basins.
- Same-Day Shipping:Promise-bound fulfillment requires predictive inventory pre-positioning at forward nodes. JD Logistics and Amazon.com anchor proprietary networks in tier-one Chinese cities and North American metropolitan corridors. The operational model sacrifices margin for frequency, relying on machine learning demand clustering to improve route density.
- Fulfillment Centers:Urban micro-warehouses enable sub-hour retrieval without ground congestion exposure.
- Cross-Docking:Transload facilities consolidate parcel flows for line-haul injection into last-mile networks.
Today's leader: Last-Mile Delivery. Tomorrow's challenger: Same-Day Shipping.
Technology:
Cost tiers separate enterprise-grade fleet management suites from lightweight dispatch applications serving mid-market operators.
- Route Optimization:Cloud-based dispatch algorithms reduce empty miles through predictive demand clustering and dynamic driver allocation. Food and grocery platforms in Beijing and Shenzhen deploy these systems at scale. The margin improvement potential climbs fastest where delivery density already saturates urban cores.
- Fleet Management Software:Integrated telematics platforms track vehicle health, driver behavior, and regulatory compliance across dispersed assets. European operators leverage these tools to document EU Green Deal emissions performance for urban zone access permits. The category captures enterprise contract value through multi-year SaaS arrangements.
- GPS Tracking:Real-time shipment visibility layers provide buyer-facing delivery windows.
- Mobile Apps:Driver-facing interfaces coordinate gig-economy labor pools against demand spikes.
Route optimization platforms are gaining share fastest as machine learning compresses delivery windows below two hours.
End User:
Application requirements diverge sharply between inventory-heavy retail and asset-light digital commerce.
- E-Commerce Businesses:Pure-play digital retailers anchor same-day infrastructure investments, collapsing order-to-delivery latency to compete on immediacy. Amazon.com and Chinese marketplace operators densify fulfillment networks in metropolitan rings. Subscription same-day services displace standard multi-day shipping as the default expectation in urban households.
- Retailers:Brick-and-mortar operators repurpose store networks as forward fulfillment nodes, using existing real estate for buy-online-pickup-in-store and ship-from-store capabilities. Grocery and pharmaceutical verticals in Los Angeles, New York, and Shanghai metropolitan zones drive one-hour window adoption.
- Manufacturers:Industrial shippers prioritize cross-border customs automation and scheduled delivery certainty over velocity.
- Distributors:Wholesale intermediaries balance inventory carrying costs against fulfillment speed commitments.
E-Commerce Businesses currently dominate platform revenue. Retailers are climbing fastest as store networks convert to fulfillment assets.
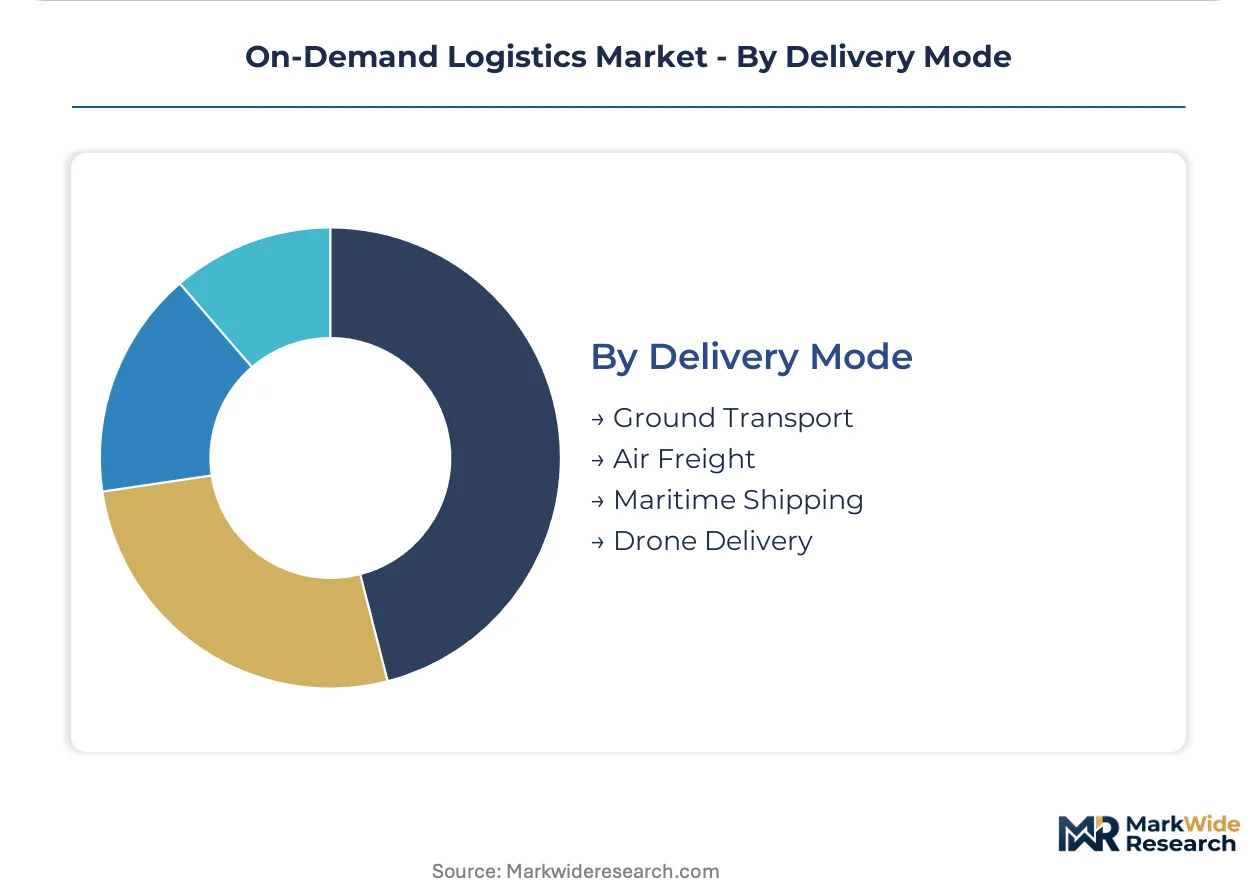
Delivery Mode:
Maturity gradients separate established ground transport from nascent aerial alternatives constrained by regulatory frameworks.
- Ground Transport:Van and bicycle courier networks handle the overwhelming volume of sub-two-hour delivery commitments. Operators in Amsterdam, Paris, and Berlin face EU Green Deal zero-emission zone exclusions without battery-electric replacement. California's CARB waivers create a de facto higher emissions bar for vehicles serving Los Angeles and San Francisco basins.
- Drone Delivery:Autonomous aerial platforms attract disproportionate R&D allocation despite FAA regulatory uncertainty around beyond-visual-line-of-sight operations. Pilot programs in Shenzhen operate under MIIT testing permits that constrain technology transfer to logistics from robotaxi development.
- Air Freight:DHL Group leverages integrated ground-air networks for next-day coverage in high-density corridors.
- Maritime Shipping:Coastal and riverine routes serve bulk cargo with limited on-demand applicability.
Ground Transport retains volume leadership. Drone Delivery presents the steepest expansion trajectory if regulatory pathways clarify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The on-demand logistics industry traces its modern scaling to the United States, where early platform economics fused gig labor with smartphone dispatch. From this foundation, operational models diffused to Europe and Asia-Pacific, adapting to local regulatory and urban density conditions.
United States
Amazon.com and FedEx Corporation anchor proprietary fulfillment networks across metropolitan rings, with same-day delivery compressing toward sub-hour windows in Los Angeles and New York. EPA tailpipe standards and California CARB waivers force fleet electrification timelines for vehicles serving dense urban basins. Seattle and San Francisco host dense clusters of route optimization software development.
China
JD Logistics and local platforms have built tier-one fulfillment density in Shanghai, Beijing, and Shenzhen, collapsing delivery latency for e-commerce households. MIIT governs autonomous delivery vehicle testing permits in Shenzhen and Beijing, constraining robotaxi-to-logistics technology transfer. The Yangtze River Delta and Pearl River Delta concentrate micro-fulfillment infrastructure investment.
Germany
DHL Group leverages integrated ground-air networks to sustain next-day coverage across high-density European corridors from its central European hub position. EU Green Deal emissions targets reshape last-mile fleet composition requirements, accelerating zero-emission vehicle deployment in Berlin and Munich urban zones. The Rhine-Ruhr and Bavarian industrial corridors anchor cross-border customs automation development.
United Kingdom
London's congestion pricing scheme inflates centralized fulfillment costs versus micro-fulfillment alternatives, reshaping inventory placement strategies for urban operators. EU Green Deal compliance obligations extend to UK urban zones post-Brexit through retained emissions frameworks. The Greater London metropolitan ring hosts dense last-mile courier network competition.
Singapore
Municipal congestion pricing and land scarcity drive micro-fulfillment innovation, with urban real estate repositioning enabling sub-hour delivery without ground exposure. The national regulator shapes autonomous vehicle testing frameworks for logistics applications. The city-state functions as a Southeast Asian hub for cross-border express consolidation.
On-Demand Logistics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across delivery velocity tiering, with sub-hour specialists commanding structural price premiums over next-day generalists. The vendor base fragments across three strategic tiers: integrated platform operators owning fulfillment-to-last-mile stacks, asset-light aggregators coordinating gig labor pools, and specialized same-day couriers serving vertical niches. Dominant competitive moves include geographic densification of micro-fulfillment nodes and machine learning route optimization licensing.
Within the integrated platform tier, Amazon.com and JD Logistics exemplify the fulfillment-center-to-last-mile ownership model, while DHL Group occupies a position bridging international express with domestic same-day capability. Uber Technologies and DoorDash represent the asset-light aggregator archetype, coordinating driver supply against demand spikes without fixed infrastructure ownership. FedEx Corporation anchors the legacy express carrier adaptation path, layering same-day services atop established ground-air networks.
| Leading Market Players |
|---|
| Uber Technologies |
| DHL Group |
| FedEx Corporation |
| DoorDash |
| Amazon.com |
| United Parcel Service of America |
| Delivery Hero SE |
| JD Logistics |
| Lalamove |
| Others |
Supply Flow & Price Mechanics
Vertical integration into fulfillment-center-to-last-mile stacks anchors pricing power for platform operators serving dense urban corridors. Amazon.com and JD Logistics leverage captive inventory positioning and proprietary driver networks to command premium rates for sub-hour delivery windows, while asset-light aggregators compete on thinner margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates same-day specialists from next-day generalists and multi-day commodity carriers. Price differentiation hinges on delivery velocity guarantees and urban zone density, with sub-hour windows commanding structural premiums over two-hour promises. Pricing pressure stems from gig-economy labor cost inflation and lithium-ion battery procurement expenses. E-commerce businesses exhibit lowest price sensitivity for expedited fulfillment, while manufacturers prioritize cost certainty over speed.
Supply Chain Analysis
Lithium-ion battery supply rests on concentrated processing capacity in China, South Korea, and Japan, constraining fleet electrification timelines for operators serving EPA-regulated and EU Green Deal urban zones. Electric van chassis, autonomous delivery sensors, and cloud-based dispatch software constitute critical input dependencies. Single-source vulnerability in cathode material refining exposes operators to commodity price volatility. Distribution runs through micro-fulfillment nodes positioned within metropolitan rings to bypass ground congestion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
On-demand logistics functions as a geographic-arbitrage play where EU Green Deal compliance costs in Amsterdam and Paris create margin advantages for operators with pre-electrified fleets serving comparable-density US corridors.
For Market Incumbents: Deepen machine learning route optimization capabilities to compress empty miles and defend margin position against asset-light aggregators. Expand micro-fulfillment real estate footprints in tier-one Chinese cities and North American metropolitan rings to sustain sub-hour delivery promises. Prioritize lithium-ion supply agreements with South Korean and Japanese producers to secure fleet electrification timelines. For New Entrants and Emerging Players: Autonomous ground vehicle technology offers a technology-first wedge into last-mile delivery verticals where labor cost inflation pressures incumbent unit economics. Target pharmaceutical and grocery segments in Los Angeles and New York where one-hour windows remain underpenetrated by specialized same-day couriers. Deploy pilot programs under China's MIIT testing frameworks to accelerate regulatory learning curves. For Investors and Strategic Acquirers: Roll-up economics work for regional same-day specialists because EU Green Deal compliance investments create scale advantages that fragment sub-scale competitors. Focus acquisition screening on operators with established zero-emission zone access permits and dense metropolitan real estate positions. Watch FAA beyond-visual-line-of-sight rulemaking as the inflection signal for aerial last-mile viability.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Densification | Urban real estate repositioning near Los Angeles and Shanghai metropolitan rings enables sub-hour delivery without congestion exposure. |
| Fleet Electrification Partnership | Battery supply agreements with South Korean producers secure EU Green Deal compliance timelines for Amsterdam and Berlin operators. |
| Route Optimization Platform Licensing | Machine learning dispatch algorithms reduce empty miles for food and grocery platforms in Beijing and Shenzhen. |
| Autonomous Vehicle Testing Permit | MIIT frameworks in Shenzhen create regulatory pathways for robotaxi-to-logistics technology transfer. |
| Cross-Border Customs Automation | Automated brokerage systems differentiate international express operators from pure-play domestic rivals. |
Methodological Framework
Direct dialogue with logistics platform executives, fleet operations directors, urban planning officials, and e-commerce fulfillment managers grounded qualitative insights. Secondary validation drew from EPA regulatory filings, EU Green Deal implementation documents, FAA drone integration notices, and China MIIT autonomous vehicle permit records. Bottom-up service tier sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Bottom-up modeling segmented the market by delivery velocity tier, technology stack, and end-user vertical across the analysis window. Service type splits included last-mile delivery, same-day shipping, fulfillment centers, and cross-docking operations. Technology segmentation captured route optimization, fleet management software, GPS tracking, and mobile applications. CAGRs derived from logistic curve adoption modeling applied to e-commerce penetration rates and urban household same-day service subscription patterns.
The model holds under stable regulatory frameworks for autonomous vehicle testing and emissions zone enforcement; deviation in FAA beyond-visual-line-of-sight rulemaking or lithium-ion supply disruption would shift fleet technology roadmaps and delivery window feasibility. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market